
 Maleic Acid Market | 2026-2036
Maleic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Maleic Acid Market Outlook
Modular packaging of maleic acid derivatives is expanding buyer flexibility across derivative supply chains. BASF SE leverages its integrated Ludwigshafen complex to sustain captive feedstock supply for downstream resin production. Lanxess AG anchors its competitive stance through specialized industrial grade formulations serving European automotive coatings demand. Ineos Group Holdings competes on manufacturing scale across multiple Atlantic basin production sites.
Maleic acid (cis-butenedioic acid, C4H4O4) functions as a dicarboxylic acid intermediate produced primarily via catalytic oxidation of benzene or n-butane, with purity grades ranging from 99% technical specification to higher-refinement food and pharmaceutical variants. Its primary commercial purpose centers on maleic anhydride conversion for unsaturated polyester resins, alkyd coatings, and agricultural chemical synthesis. Technical grade material dominates volume throughput across the analysis window, while pharmaceutical grade commands concentrated margin pools due to CDMO qualification requirements and tighter impurity specifications. Resins and coatings applications absorb the majority of industrial grade output, with agrochemicals representing the fastest-growing application segment as formulation houses seek acid-compatible intermediates.
REACH registration obligations in Europe and EPA TSCA Section 5 requirements in the United States govern new chemical introductions and derivative substance notifications, shaping product standard thresholds and market access timelines for non-compliant producers. China's GB standards under SAMR oversight impose additional purity and labeling specifications on food grade imports, while India's BIS certification mandates create procedural friction for unqualified foreign suppliers. Stakeholders must monitor evolving ECHA SVHC candidate list expansions and corresponding downstream notification obligations to anticipate reformulation costs and qualification timelines.
Market Dynamics
REACH registration obligations in Europe are forcing reformulation cycles across unsaturated polyester resin supply chains, compressing qualification timelines for non-compliant producers and redistributing volume toward integrated manufacturers with captive maleic anhydride capacity.
Growth Catalysts
- Agrochemical formulation demand:Agricultural chemical houses in India seek acid-compatible intermediates for pesticide synthesis, expanding technical grade consumption beyond traditional resin applications.
- MIIT dual carbon compliance:China's Ministry of Industry and Information Technology mandates cleaner production pathways for maleic anhydride derivatives, accelerating capital deployment into catalytic oxidation upgrades.
- Coatings sector expansion:Alkyd coating manufacturers in Germany leverage BIS-certified technical grade imports to serve automotive OEM specification requirements.
Market Restraints
- Benzene feedstock volatility:Aromatic hydrocarbon price swings transmit directly into maleic acid production economics, squeezing margin stability for non-integrated producers.
- Supply concentration in n-butane oxidation:Catalytic oxidation capacity clusters among Gulf Coast petrochemical complexes, creating geographic vulnerability to hurricane-related disruption.
- Fumaric acid substitution:The trans-isomer competes in food acidulant and beverage formulation applications where thermal stability requirements favor its crystalline structure.
Strategic Opportunities
- Pharmaceutical grade qualification:CDMO certification requirements for dicarboxylic acid intermediates create concentrated margin pools for producers meeting tighter impurity specifications.
- Modular packaging formats:Flexible intermediate bulk container configurations enable derivative supply chains to reduce working capital intensity and batch size minimums.
- EU Green Deal alignment:Bio-based feedstock pathways for maleic anhydride production qualify for green chemistry procurement preferences in European public sector tenders.
Industry Challenges
- SVHC notification complexity:ECHA candidate list expansions trigger downstream reformulation costs and extended qualification timelines for resin compounders serving regulated end-uses.
- Legacy asset retrofit requirements:Fixed-bed catalytic oxidation units face obsolescence risk as fluidized-bed technologies achieve superior selectivity and energy efficiency metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maleic Acid Market |
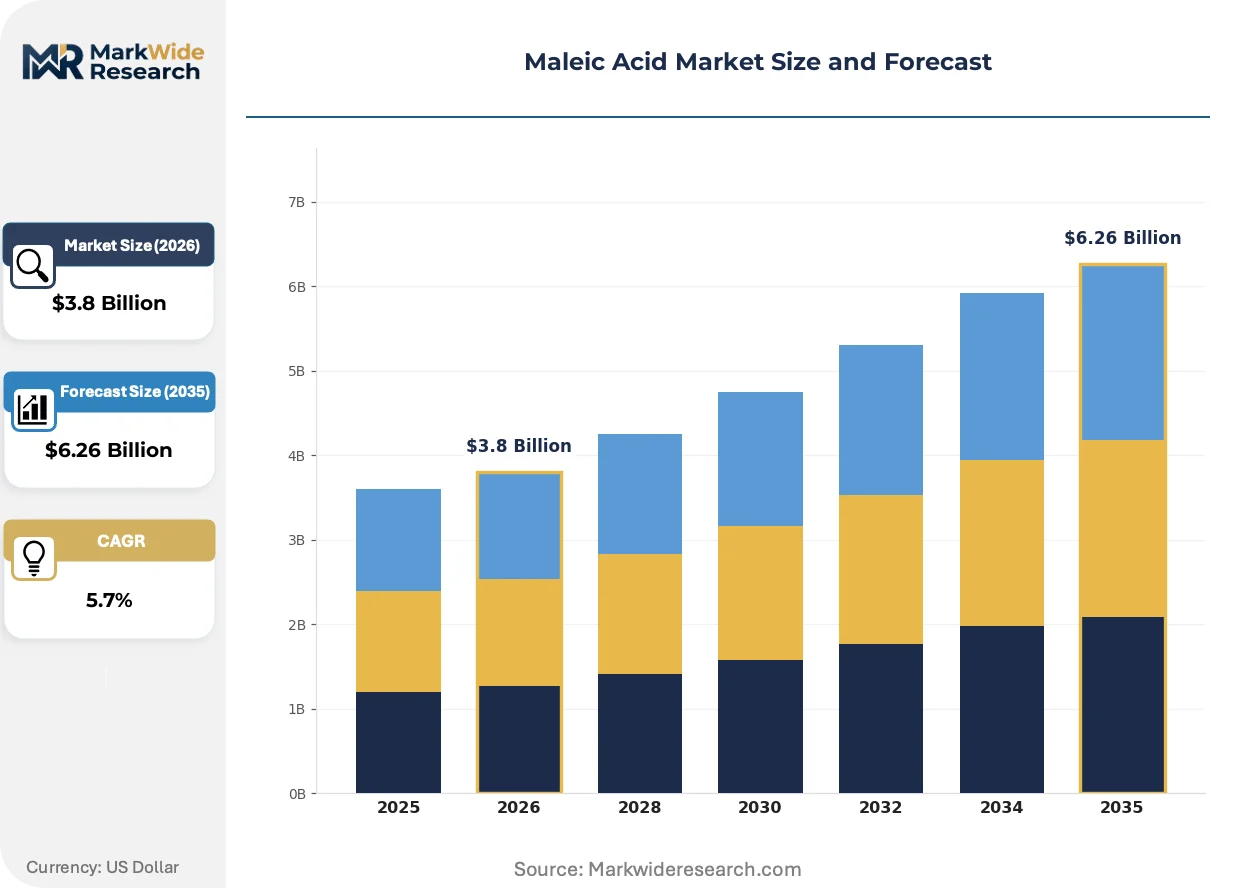
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Food Grade, Pharmaceutical Grade, Industrial Grade Application: Resins, Coatings, Plastics, Agrochemicals End User: Chemical Manufacturers, Agriculture, Food Processing, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | BASF SE, Lanxess AG, Ineos Group Holdings, Ashland Global Holdings, Anhui Beverly Chemicals, Fushun Xinye Chemical Company, Guangxi Guochem, Xi'an DongHai Chemical Group, Shandong Huajin Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maleic Acid Market Strategic Shifts
Digital process control systems and advanced catalytic materials are compressing yield variability in maleic anhydride production, while regulatory pressure on carbon intensity reshapes feedstock selection across integrated complexes.
Continuous flow reactor technology is automating oxidation step control in maleic anhydride plants, enabling real-time adjustment of oxygen-to-hydrocarbon ratios. European resin compounders adopt these systems fastest, driven by energy cost pressures and yield optimization targets. The technology is automating quality consistency that previously required batch-wise laboratory intervention, reducing specification drift and customer rejection rates.
EPA TSCA Section 5 premanufacture notification requirements are tightening scrutiny on novel maleic acid derivative substances entering US commerce. Chemical manufacturers face extended review timelines for modified ester formulations, particularly those intended for agricultural chemical intermediates. Agrochemical formulation houses are responding by concentrating new product development in existing substance inventories to avoid regulatory friction.
Specification-driven procurement is consolidating buyer power among large resin compounders, who now mandate certificate of analysis documentation for every lot rather than accepting periodic quality audits. This pattern displaces spot-market purchasing in favor of contracted supply arrangements with qualified producers. German automotive coating supply chains exhibit this shift most visibly, where OEM traceability requirements cascade downstream to raw material qualification protocols.
Maleic Acid Market Segmentation
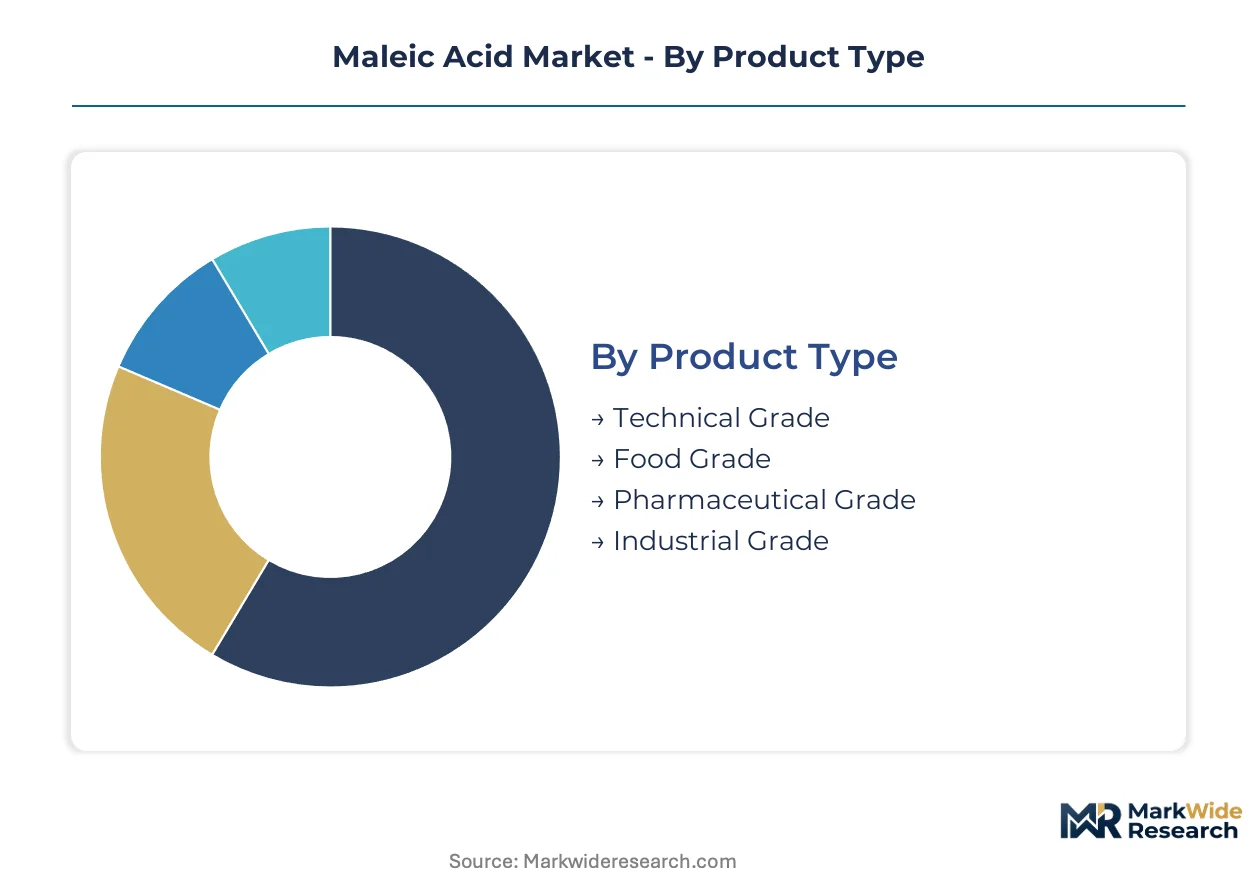
Segmentation in maleic acid markets reveals how certification burdens, feedstock integration, and end-use specifications fragment commercial pathways. Buyers align procurement strategies to grade-specific regulatory requirements rather than commodity pricing alone.
Product Type:
REACH registration and BIS certification obligations concentrate differently across purity tiers, with pharmaceutical grade demanding CDMO qualification and food grade requiring GB standard compliance under SAMR oversight.
- Technical Grade:99% purity specification serves resin compounders and alkyd coating manufacturers. Demand clusters in India where BIS-certified material feeds domestic plastics output and automotive OEM coating supply chains.
- Pharmaceutical Grade:Tighter impurity thresholds qualify dicarboxylic acid intermediates for CDMO synthesis contracts. European compounders pay concentrated margin premiums for EMA-aligned documentation packages that accelerate drug master file approvals.
- Food Grade:GB standards under SAMR impose labeling and purity specifications on imports into China. FSSAI parallel requirements in India create dual-qualification friction for cross-border suppliers.
- Industrial Grade:Captive consumption within integrated maleic anhydride complexes dominates volume flows. Gulf Coast petrochemical producers leverage n-butane oxidation integration to supply internal resin operations.
Leading the category by volume: Technical Grade. Growing fastest: Pharmaceutical Grade.
Application:
Application segments diverge by margin stability, with agrochemical intermediates offering volume expansion and resin markets providing baseline offtake certainty.
- Resins:Unsaturated polyester resin production absorbs the majority of technical grade maleic anhydride conversion. German automotive OEMs specify REACH-compliant material for composite body panel substrates.
- Agrochemicals:Acid-compatible intermediates for pesticide synthesis represent the steepest expansion trajectory. Indian formulation houses source technical grade material to bypass fumaric acid substitution in heat-sensitive synthesis steps.
- Coatings:Alkyd coating manufacturers in Germany leverage certificate-of-analysis documentation for every lot to satisfy OEM traceability mandates.
- Plastics:Plasticizer and modifier applications consume industrial grade output from integrated complexes. China's MIIT dual carbon goals are accelerating cleaner production pathway upgrades for derivative supply.
Resins anchor volume throughput. Agrochemicals climb the fastest.
End User:
End user concentration reflects downstream integration depth, with chemical manufacturers capturing economies of scale and pharmaceutical buyers extracting qualification premiums.
- Chemical Manufacturers:Integrated producers with captive maleic anhydride capacity dominate resin and coating supply chains. BASF SE's Ludwigshafen complex exemplifies feedstock-to-derivative control.
- Pharmaceuticals:CDMOs and API houses demand pharmaceutical grade with full impurity profiling. EMA master file alignment commands 40-60% price premiums over technical specification.
- Agriculture:Pesticide formulation houses in India and Brazil seek acid-compatible intermediates for organophosphate synthesis. ANVISA and CDSCO registration requirements shape import qualification timelines.
- Food Processing:Acidulant applications face fumaric acid substitution pressure where thermal stability favors the trans-isomer crystalline structure.
Chemical Manufacturers lead by volume. Pharmaceuticals expand most quickly.
Distribution Channel:
Channel selection tracks buyer scale and specification stringency, with large resin compounders consolidating power through direct contracting.
- Direct Sales:Contracted supply arrangements with qualified producers displace spot-market purchasing. German automotive coating supply chains mandate direct relationships for traceability compliance.
- Distributors:Regional chemical distributors serve mid-tier compounders lacking volume for producer-direct negotiations. Inventory pooling reduces working capital intensity for smaller resin houses.
- Online:Digital procurement platforms facilitate technical grade spot purchasing for non-critical applications. Certificate-of-analysis verification remains manual in most implementations.
- Retail:Limited to laboratory-scale quantities for research and development applications. Specialty chemical retailers stock pharmaceutical grade in select European and North American markets.
Direct Sales dominates volume. Distributors gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of maleic anhydride feedstock through n-butane oxidation, while Germany and India absorb disproportionate shares of derivative consumption for coatings and agrochemicals. This production-consumption divide shapes freight economics and qualification protocols across trade lanes.
China
MIIT dual carbon mandates accelerate catalytic oxidation upgrades in Shandong and Jiangsu provinces, where integrated petrochemical complexes supply domestic resin compounders. GB standards under SAMR impose strict purity documentation on food-grade exports, creating procedural friction for cross-border shipments. The Yangtze River Delta cluster houses fluidized-bed technology deployments that achieve superior selectivity versus legacy fixed-bed units.
Germany
REACH registration obligations compress qualification timelines for non-compliant resin producers, redistributing volume toward integrated manufacturers with captive maleic anhydride capacity. The Ludwigshafen chemical complex anchors European supply chains through backward integration into benzene and n-butane feedstocks. Automotive OEM coating specifications cascade downstream to mandate certificate-of-analysis documentation for every raw material lot.
United States
EPA TSCA Section 5 premanufacture notifications extend review timelines for novel maleic acid derivatives, particularly agricultural chemical intermediates. Gulf Coast petrochemical complexes concentrate catalytic oxidation capacity, creating geographic vulnerability to hurricane-related disruption. Texas and Louisiana producers leverage n-butane feedstock access to serve domestic unsaturated polyester resin compounders.
India
BIS certification mandates create procedural barriers for unqualified foreign suppliers of technical grade material. Pesticide formulation houses in Maharashtra and Gujarat source acid-compatible intermediates to bypass fumaric acid substitution in heat-sensitive synthesis steps. The domestic coatings sector absorbs certified imports for automotive OEM specification compliance.
Brazil
ANVISA registration requirements shape import qualification timelines for pharmaceutical grade dicarboxylic acid intermediates. Agrochemical formulation demand in São Paulo state expands technical grade consumption beyond traditional resin applications. Local compounders face working capital pressure from certificate-of-analysis mandates that displace spot-market purchasing.
Maleic Acid Market Competitive Environment
The competitive structure tilts toward integrated petrochemical conglomerates with captive feedstock supply. BASF SE, Lanxess AG, and Ineos Group Holdings anchor the top tier through Ludwigshafen-scale complexes and multi-site Atlantic basin manufacturing. Mid-tier specialists compete on pharmaceutical grade qualification and CDMO documentation packages. Dominant competitive moves include backward integration into n-butane oxidation capacity and strategic partnerships with resin compounders for long-term offtake agreements.
Within the integrated conglomerate tier, BASF SE and Lanxess AG represent archetypal European positioning through Ludwigshafen and Leverkusen chemical complexes. Ineos Group Holdings occupies a scale-driven position across multiple Atlantic basin production sites. Among Asia-Pacific-based producers, Anhui Beverly Chemicals and Fushun Xinye Chemical Company exemplify regional supply concentration serving domestic derivative demand. These named entities anchor commentary on geographic sourcing patterns rather than specific strategic actions.
| Leading Market Players |
|---|
| BASF SE |
| Lanxess AG |
| Ineos Group Holdings |
| Ashland Global Holdings |
| Anhui Beverly Chemicals |
| Fushun Xinye Chemical Company |
| Guangxi Guochem |
| Xi'an DongHai Chemical Group |
| Shandong Huajin Group |
| Others |
Value Chain & Pricing Dynamics
Catalytic oxidation specialists concentrated in Shandong province and the Texas Gulf Coast command wage premiums that compress margin spreads between technical and pharmaceutical grade tiers. Labor-cost differentials between fixed-bed legacy units and fluidized-bed modern plants translate directly into pricing-tier spreads, with German automotive coating buyers absorbing certificate-of-analysis premiums that Indian agrochemical formulators resist.
Pricing Analysis
Margin tightening in technical grade reflects benzene feedstock volatility transmitting directly into non-integrated producer economics. Three-tier pricing structure across pharmaceutical, technical, and industrial grades separates CDMO-qualified documentation packages from BIS-certified technical material and captive-consumed industrial output. Price differentiation hinges on impurity profiling depth and EMA master file alignment. Agrochemical formulation houses in India exhibit highest price sensitivity, while European pharmaceutical CDMOs accept concentrated premiums for accelerated qualification timelines.
Supply Chain Analysis
Freight cost differentials between Shandong province n-butane oxidation clusters and German automotive coating plants reshape procurement geography for derivative supply chains. Production capacity concentrates in China, the United States, and Germany, with raw material dependencies anchored in benzene and n-butane feedstock access. Supply chain risk centers on hurricane-related disruption vulnerability across Gulf Coast petrochemical complexes. Distribution runs through direct contracted supply arrangements that displace spot-market purchasing among large resin compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive maleic anhydride capacity determines supply security for downstream resin and coating operations. Players pursue backward integration into n-butane oxidation feedstock control as the decisive competitive lever.
For Market Incumbents: Lock in long-term offtake agreements with German automotive OEM coating supply chains before REACH registration obligations compress qualification timelines further. Defend margin position by accelerating fluidized-bed catalytic oxidation upgrades that achieve superior selectivity versus legacy fixed-bed units threatened by MIIT dual carbon compliance mandates. For New Entrants and Emerging Players: Mid-tier Indian pesticide formulation houses lacking volume for producer-direct negotiations represent the most penetrable buyer archetype. Target technical grade supply through regional chemical distributors serving Maharashtra and Gujarat agrochemical clusters. Pursue BIS certification investment as the essential market entry credential displacing unqualified foreign suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical grade specialists possessing CDMO documentation capabilities given EMA master file alignment commands sustained margin premiums. Acquisition focus should center on European compounders with captive catalytic oxidation capacity and established impurity profiling infrastructure. Watch ECHA SVHC candidate list expansion velocity as the signal indicating downstream reformulation cost intensity and qualification timeline extension.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into N-Butane Oxidation | Captive feedstock supply secures margin stability against benzene price volatility for resin compounders. |
| Pharmaceutical Grade CDMO Qualification | EMA-aligned documentation packages unlock 40-60% price premiums over technical specification material. |
| Fluidized-Bed Catalytic Upgrade | MIIT dual carbon mandates accelerate cleaner production pathway adoption in Shandong and Jiangsu provinces. |
| Long-Term Supply Agreement with Automotive OEMs | German coating supply chains mandate certificate-of-analysis documentation for every raw material lot. |
| BIS Certification Investment for India Entry | Certification mandates create procedural barriers that qualified suppliers exploit to displace unqualified imports. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs that plant managers at catalytic oxidation facilities, procurement leads at unsaturated polyester resin compounders, distribution channel partners in Indian agrochemical clusters, and technical R&D directors at European coating houses validated through structured primary interviews. Bottom-up volume modeling triangulated against top-down macroeconomic indicators ensured cross-verification of demand estimates across grade tiers and application segments.
Segmentation dimensions including purity grade, end-use industry, packaging format, and regional production hub were modeled at country-level granularity throughout the forecast period. CAGRs derived from regression analysis against historical trade flows and capacity utilization rates incorporated catalytic oxidation yield improvements and REACH registration timeline compressions as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA SVHC candidate list expansions, benzene feedstock price volatility, and fluidized-bed technology adoption rates. Forecasts reflect assumptions about regulatory compliance cost trajectories and carbon intensity reduction pathways. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Asia Pacific Waterproofing Chemicals Market
Chemicals
Aerosol Insecticides Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Uranyl Carbonate Market
Chemicals
Ferric Phosphate Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Ethyl Chloride Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
Lime Sulfur Market
Chemicals
Global Methyl Cellulose Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market