
 p-Coumaric Acid Market | 2026-2036
p-Coumaric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
p-Coumaric Acid Market Insights
Project finance for microbial fermentation facilities is rewriting competitive entry barriers in p-coumaric acid production. Conagen Biotech leverages its synthetic biology platform to sustain cost advantages in fermentation-derived supply. Hangzhou Viablife Biotech anchors its position through integrated strain engineering and downstream processing capabilities. Shandong Holly dominates powder and crystalline form production from established Shandong province infrastructure.
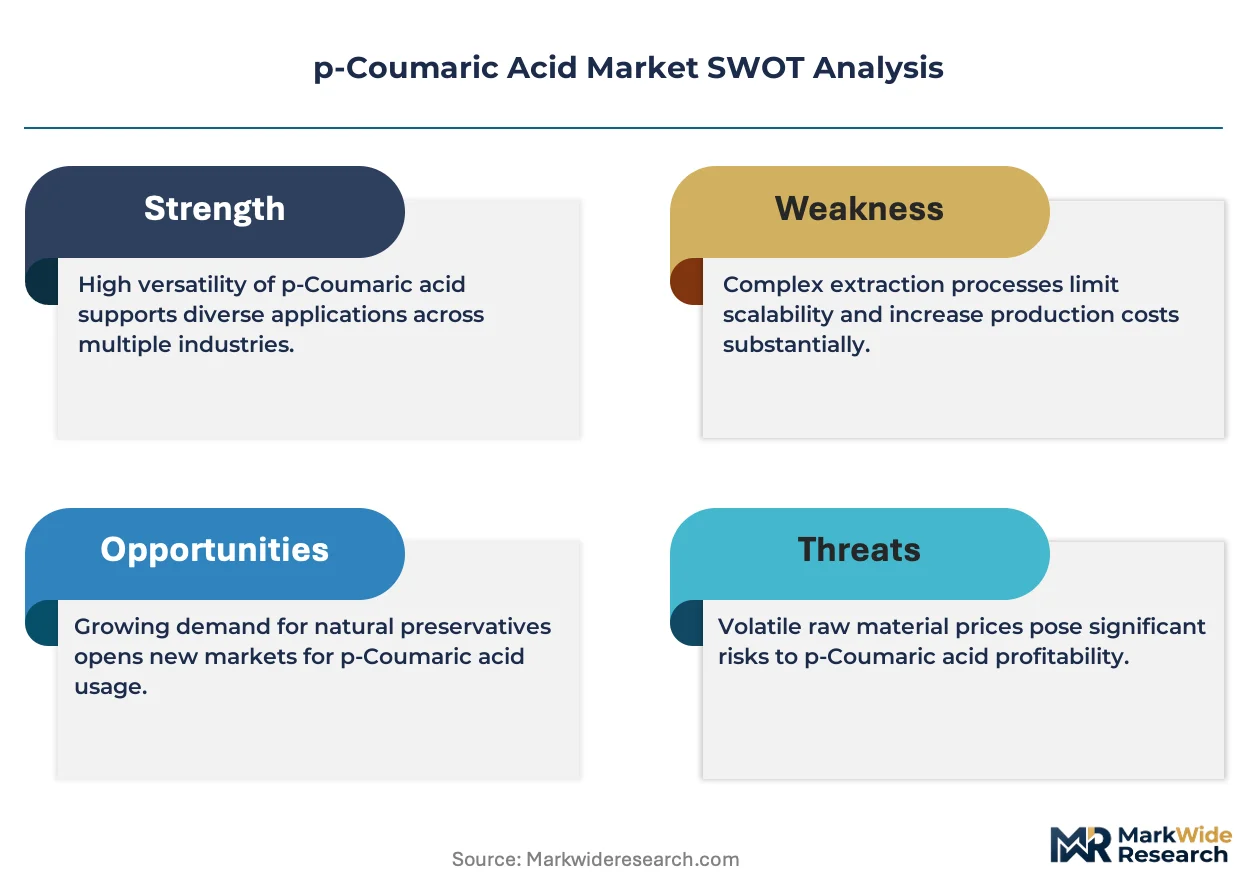
p-Coumaric acid is a hydroxycinnamic acid with the molecular formula C9H8O3, typically extracted from plant sources or produced via microbial fermentation, serving primarily as an antioxidant intermediate and preservative precursor across food, pharmaceutical, and cosmetic applications. Natural extraction supply carries premium positioning due to limited agricultural feedstock availability and batch-to-batch compositional variance. Synthetic production occupies cost-sensitive preservative applications where pharmaceutical-grade purity thresholds are not required. Fermentation-derived output is capturing margin pools as personal care brands reformulate under ECHA sustainability disclosure requirements.
REACH registration obligations and ECHA substance evaluation protocols shape import access for non-European suppliers into European pharmaceutical and cosmetic end uses. FDA food additive regulations and FSSAI preservative limits in India govern permissible application concentrations across food processing and drug manufacturing segments. Stakeholders must monitor evolving biomanufacturing incentives under China's dual carbon goals and the EU Green Deal to determine optimal capacity placement and feedstock sourcing strategies.
Market Dynamics
Fermentation-derived production methods are compressing cost structures and displacing solvent-based extraction as the dominant supply mode, driven by ECHA sustainability disclosure mandates and EU Green Deal carbon accounting requirements.
Growth Catalysts
- REACH registration compliance:European pharmaceutical and cosmetic formulators face mandatory substance evaluation protocols, pulling demand toward fermentation-derived supply with verified carbon footprints.
- Antioxidant intermediate demand:Food processors in India operate under FSSAI preservative limits that favor natural-origin compounds over synthetic alternatives in clean-label positioning.
- Shandong-Jiangsu manufacturing clusters:China's dual carbon goals channel state incentives toward biomanufacturing capacity expansion, concentrating technical expertise and feedstock access.
Market Restraints
- Agricultural feedstock volatility:Natural extraction supply faces raw material cost swings from wheat bran and rice hull availability, compressing margin stability for plant-derived producers.
- Pharmaceutical-grade purity thresholds:Synthetic production routes face technical ceilings in impurity profiles, limiting access to drug-active ingredient specifications governed by FDA and EMA standards.
- Substitution by ferulic acid:Cosmetic formulators in personal care applications pivot toward structurally similar hydroxycinnamic acids with equivalent antioxidant performance and simpler supply chains.
Strategic Opportunities
- Brazil ANVISA pharmaceutical pathways:Underpenetrated generic drug manufacturing base offers first-mover positioning for fermentation-derived active ingredient suppliers meeting bioequivalence documentation requirements.
- Synthetic biology platform convergence:CRISPR strain engineering combined with continuous fermentation processing enables step-change yield improvements and capital efficiency in microbial production.
- EU Green Deal biomanufacturing incentives:Carbon border adjustment mechanisms and sustainable chemistry taxonomies redirect European procurement toward verified low-carbon supply sources.
Industry Challenges
- Downstream processing expertise gap:Fermentation facilities face acute shortages in chromatographic purification specialists and crystallization process engineers, extending commissioning timelines.
- ISO 17025 certification complexity:Analytical method validation for pharmaceutical-grade specifications requires 18-24 month qualification periods, delaying market entry for new production assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | p-Coumaric Acid Market |
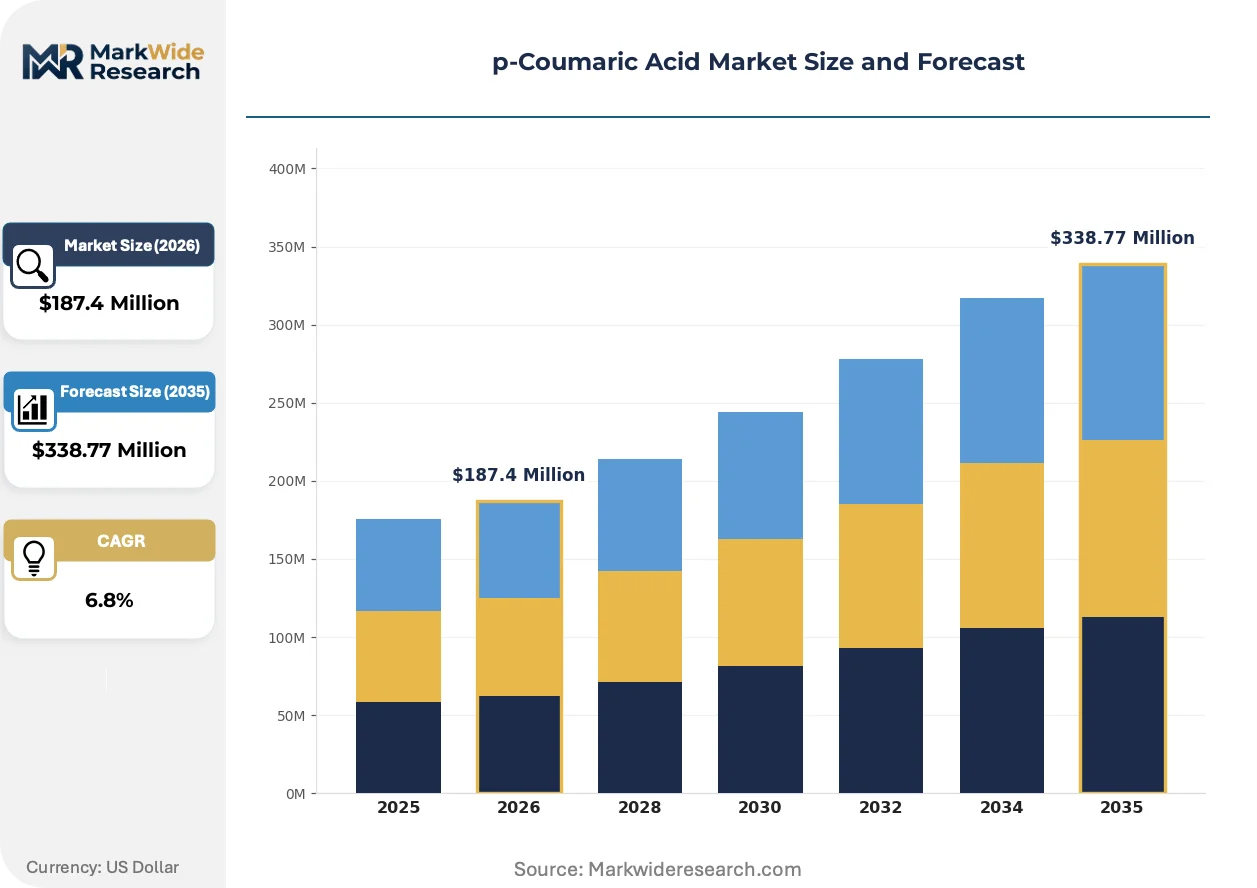
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extraction, Synthetic, Fermentation Derived, High-Purity Grade Application: Food Preservation, Pharmaceutical Formulations, Cosmetic Additives, Agricultural Biocontrol End Use Industry: Food Processing, Drug Manufacturing, Personal Care, Crop Protection Form: Powder, Crystalline, Liquid Concentrate, Granular |
| Companies Covered | Conagen Biotech, Hangzhou Viablife Biotech, Shandong Holly, Cixiang Medicine, Zhuhai Jiayi, Shandong YangCheng, Cayman Chemical, TCI Chemicals, HiMedia Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
p-Coumaric Acid Market Trends and Innovations
Bioprocess intensification and regulatory carbon accounting are forcing simultaneous reinvention of production economics and supply chain verification protocols across the value chain.
Continuous fermentation technology with integrated membrane separation is hybridizing batch and perfusion modes to achieve pharmaceutical-grade titers. Personal care ingredient buyers in Western Europe are adopting this platform at pilot scale ahead of commercial volume commitments. The technology is hybridizing capital deployment patterns by enabling modular capacity expansion without full-scale greenfield construction.
EU CSRD sustainability reporting mandates now require Scope 3 upstream emissions disclosure for cosmetic and pharmaceutical finished goods. This regulatory pressure forces ingredient suppliers to deploy blockchain-tracked carbon accounting from fermentation feedstock through final crystallization. German and French formulators are most advanced in supplier qualification against these standards, with audit timelines compressing from annual to quarterly verification cycles.
Direct procurement contracts between personal care brands and fermentation specialists are displacing traditional distributor intermediaries in high-volume antioxidant intermediate sourcing. Specialty chemical distributors in North America face margin compression as Unilever and L'Oréal procurement teams establish captive supply relationships with Conagen Biotech and Hangzhou Viablife. This channel restructuring is most visible in skin care applications where ECHA disclosure requirements demand supply chain transparency incompatible with multi-tier distribution opacity.
p-Coumaric Acid Market Segmentation
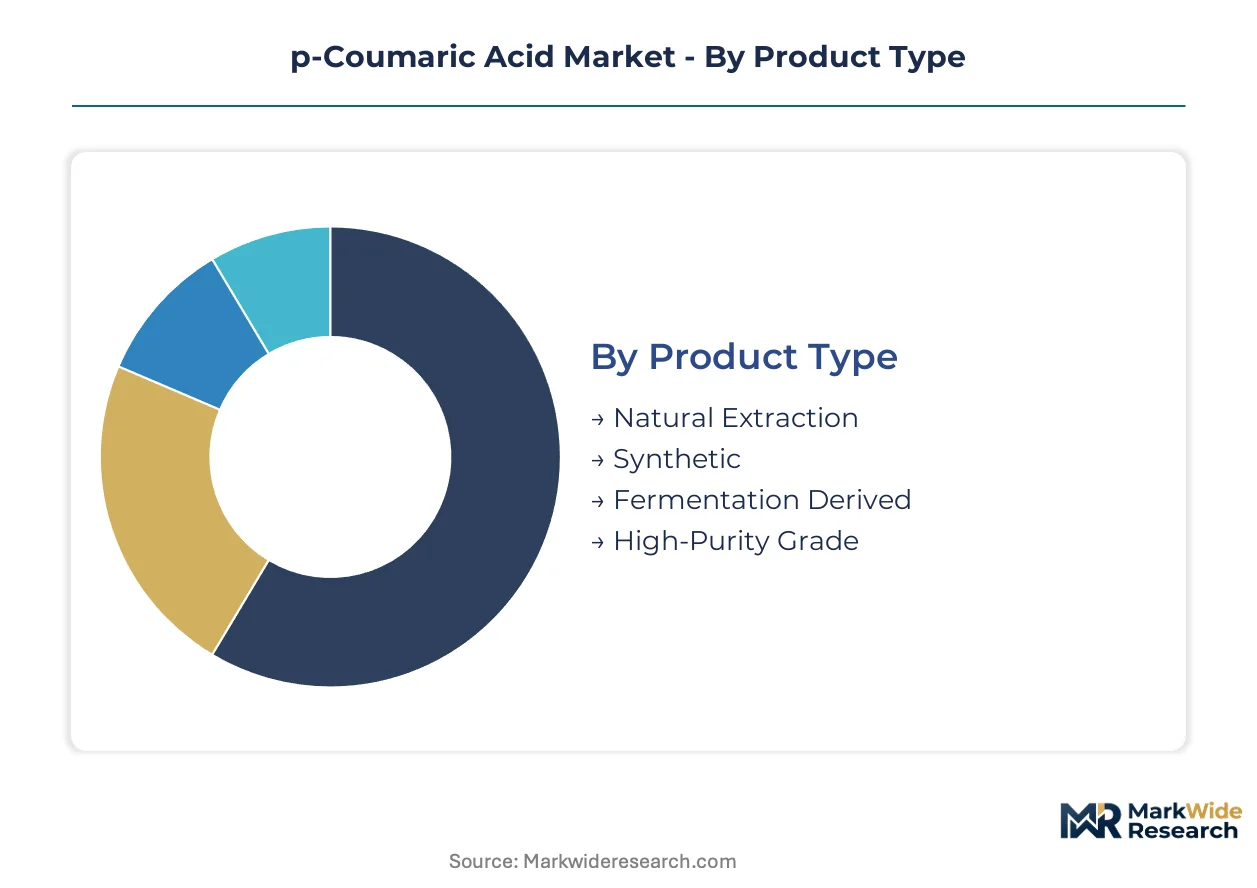
p-Coumaric acid supply fragments across production methodologies with divergent cost structures and regulatory compliance profiles. End-use specifications from pharmaceutical-grade purity to food-grade antioxidant functionality create distinct margin pools that reshape competitive positioning across the value chain.
Product Type:
Cost tier differentiation separates premium-positioned natural extraction from volume-oriented synthetic and fermentation alternatives.
- Natural Extraction:Agricultural feedstock sourcing from wheat bran and rice hulls yields batch-variable composition. European cosmetic formulators under ECHA disclosure mandates absorb price premiums for verified botanical origin.
- Fermentation Derived:Engineered yeast and bacterial strains convert sugar feedstocks into consistent titers. CRISPR strain optimization at Hangzhou Viablife and Conagen Biotech compresses unit economics below solvent extraction benchmarks.
- Synthetic:Chemical synthesis from hydroxybenzaldehyde precursors occupies cost-sensitive preservative applications. FDA food additive regulations permit synthetic routes where pharmaceutical-grade impurity thresholds are not required.
- High-Purity Grade:Chromatographic purification and recrystallization protocols achieve drug-active ingredient specifications. CDSCO and EMA documentation requirements extend qualification timelines.
Natural extraction commands the established base. The steepest expansion runs through fermentation-derived supply.
Application:
Application concentration varies by regulatory jurisdiction and end-use performance requirements.
- Pharmaceutical Formulations:Active ingredient development for anti-inflammatory and antimicrobial compounds demands chiral purity above 99.5%. Brazilian ANVISA bioequivalence pathways attract first-mover fermentation suppliers.
- Cosmetic Additives:Antioxidant stabilization in skin care formulations responds to EU CSRD Scope 3 disclosure requirements. L'Oréal and Unilever procurement teams establish direct supplier relationships bypassing distributor intermediaries.
- Food Preservation:FSSAI preservative limits in India favor natural-origin compounds in clean-label positioning. Synthetic alternatives face concentration caps in processed food applications.
- Agricultural Biocontrol:Plant defense elicitor applications in crop protection remain underpenetrated. Formulation stability challenges limit commercial deployment against established synthetic fungicides.
Pharmaceutical formulations anchor revenue concentration. Cosmetic additives are gaining share fastest.
End Use Industry:
Customer type determines specification stringency and contract structure across the value chain.
- Drug Manufacturing:GMP compliance and API master file documentation govern supplier qualification. ISO 17025 analytical method validation requires 18-24 month commissioning periods.
- Personal Care:Brand-owned sustainability scorecards under EU Green Deal taxonomies prioritize verified low-carbon supply chains. Quarterly audit cycles replace annual verification.
- Food Processing:Clean-label positioning in North American and European retail channels pulls demand toward natural-extraction supply despite cost premiums.
- Crop Protection:Agrochemical formulators evaluate p-coumaric acid as a biochemical pesticide precursor under EPA and PMRA registration pathways.
Drug manufacturing holds the premium tier. Personal care represents the steepest expansion trajectory.
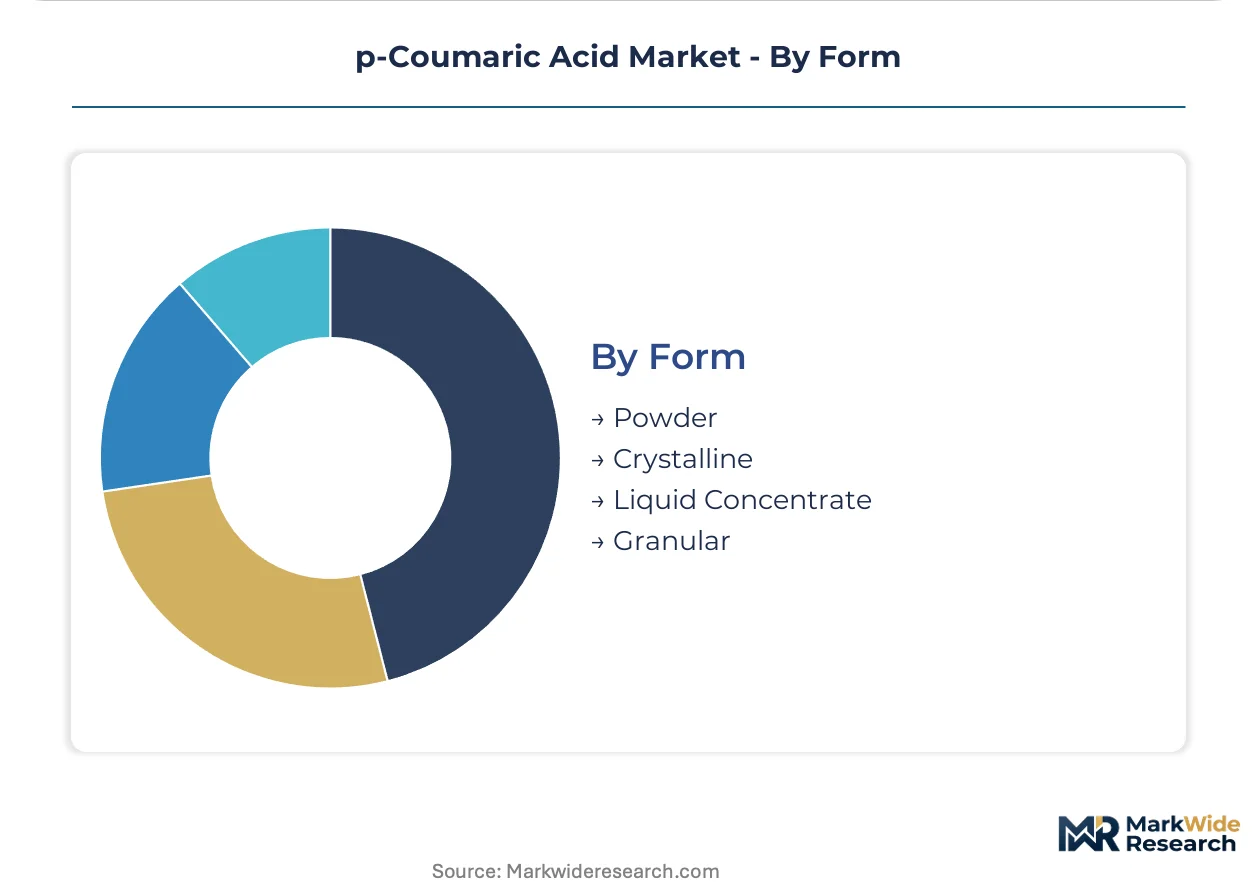
Form:
Physical form selection aligns with downstream processing integration and handling economics.
- Crystalline:Defined melting point and dissolution kinetics suit pharmaceutical tablet compression and precise dosing requirements.
- Powder:Shandong Holly production clusters dominate bulk antioxidant intermediate supply to food processors.
- Liquid Concentrate:Ready-to-dilute formats reduce handling costs in high-volume cosmetic manufacturing.
- Granular:Flowability optimization addresses caking challenges in humid storage environments.
Crystalline forms command specification premiums. Powder output scales most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon accounting requirements and China's dual carbon goals are redirecting fermentation capacity investments toward jurisdictions with verified low-carbon infrastructure. National regulators in pharmaceutical and cosmetic hubs are tightening substance evaluation protocols that favor traceable biomanufacturing supply chains.
China
Shandong and Jiangsu province manufacturing clusters concentrate technical expertise and feedstock access for fermentation-derived output. NMPA registration pathways for pharmaceutical-grade supply are streamlining under national biomanufacturing incentives. Hangzhou Viablife Biotech anchors strain engineering capabilities in the Yangtze River Delta.
Germany
Cosmetic formulators in North Rhine-Westphalia and Bavaria are adopting quarterly audit cycles for supplier carbon verification under EU CSRD mandates. ECHA REACH registration obligations pull procurement toward fermentation-derived sources with blockchain-tracked emissions documentation. BASF and Evonik procurement teams are establishing direct supplier relationships bypassing distributor intermediaries.
United States
FDA food additive regulations and pharmaceutical-grade purity thresholds govern active ingredient development for anti-inflammatory compounds. Greater Boston and San Francisco Bay Area biotech clusters are piloting continuous fermentation technology with integrated membrane separation. EPA biochemical pesticide registration pathways are opening for agricultural biocontrol applications.
India
FSSAI preservative limits favor natural-origin compounds in clean-label positioning for processed food applications. Maharashtra and Gujarat pharmaceutical manufacturing zones are expanding API master file documentation for fermentation-derived inputs. CDSCO bioequivalence requirements are attracting first-mover suppliers from microbial production platforms.
Brazil
ANVISA pharmaceutical pathways offer underpenetrated positioning for generic drug manufacturers seeking fermentation-derived active ingredients. São Paulo state chemical parks are developing downstream processing capabilities for chromatographic purification. The national regulator's bioequivalence documentation requirements are compressing qualification timelines for qualified suppliers.
p-Coumaric Acid Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply configurations. Fermentation-derived output is displacing solvent-based extraction as the dominant supply mode, concentrating margin pools among synthetic biology platforms with integrated downstream processing. Three archetypes define competitive positioning: strain-engineering specialists, crystalline-form commodity producers, and analytical-grade purity suppliers. Capacity expansion and direct procurement contracting represent the dominant competitive moves as personal care brands bypass distributor intermediaries.
Within the synthetic biology tier, Conagen Biotech and Hangzhou Viablife Biotech exemplify platform-based competitive positioning. Shandong Holly occupies a position among crystalline-form commodity producers serving bulk antioxidant intermediate demand. These three anchors represent divergent strategic vectors: microbial engineering capabilities, integrated strain-to-crystal processing, and established province-level manufacturing infrastructure.
| Leading Market Players |
|---|
| Conagen Biotech |
| Hangzhou Viablife Biotech |
| Shandong Holly |
| Cixiang Medicine |
| Zhuhai Jiayi |
| Shandong YangCheng |
| Cayman Chemical |
| TCI Chemicals |
| HiMedia Laboratories |
| Others |
Pricing and Supply Chain Analysis
Shandong province manufacturing clusters concentrate fermentation-derived capacity, granting domestic producers leverage over export pricing to European pharmaceutical and cosmetic formulators facing ECHA carbon disclosure mandates. This geographic concentration compresses margin pools for solvent-extraction competitors while elevating premiums for blockchain-tracked, low-carbon supply.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and food-grade supply, with ISO 17025 analytical validation and API master file documentation commanding substantial premiums over FSSAI-limited preservative applications. Contract-based long-term offtake dominates high-purity procurement, while spot transactional pricing governs bulk antioxidant intermediate sales to food processors. Cost compression in synthetic routes is intensifying because fermentation platforms at Conagen Biotech and Hangzhou Viablife achieve yield improvements through CRISPR strain engineering. Food processing buyers exhibit highest price sensitivity due to clean-label positioning constraints, whereas drug manufacturers absorb premiums for chiral purity above 99.5%.
Supply Chain Analysis
Extended payment terms from European personal care brands are forcing fermentation specialists to deploy supply-chain finance facilities, tightening working capital cycles for strain-engineering platforms. Manufacturing gravity centers on China, India, and Germany, with raw material dependencies on agricultural feedstocks (wheat bran, rice hulls) and sugar-based fermentation media. Single-source vulnerability runs through Shandong-Jiangsu corridor infrastructure concentration. Distribution runs through direct procurement contracts between personal care brands and fermentation specialists, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where analytical method validation and quarterly carbon audit cycles expand faster than base ingredient supply, embedding recurring revenue layers into pharmaceutical-grade relationships.
For Market Incumbents: Insulate fermentation-derived margin pools by deepening captive supply relationships with L'Oréal and Unilever procurement teams ahead of EU CSRD Scope 3 disclosure deadlines. Prioritize ISO 17025 certification investment to extend qualification timelines for synthetic competitors. Backward integration into sugar feedstock sourcing secures cost stability against agricultural commodity volatility. For New Entrants and Emerging Players: Establish a beachhead in Brazilian ANVISA pharmaceutical pathways where generic drug manufacturers seek fermentation-derived active ingredients with compressed bioequivalence documentation timelines. Target agricultural biocontrol applications under EPA biochemical pesticide registration as an underpenetrated white space with limited incumbent specialization. Deploy synthetic biology platform licensing as the go-to-market angle to bypass capital-intensive greenfield construction. For Investors and Strategic Acquirers: Long-term, this sits as a carbon-accounting infrastructure play because EU Green Deal taxonomies and ECHA disclosure mandates institutionalize demand for verified low-carbon supply chains. Acquisition targets should center on strain-engineering specialists with integrated downstream processing capabilities. Watch for ANVISA qualification timeline compression as the inflection signal for first-mover fermentation suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Strain Optimization | Conagen Biotech and Hangzhou Viablife compress unit economics below solvent extraction benchmarks. |
| Blockchain Carbon Tracking | German and French formulators deploy quarterly audit cycles incompatible with multi-tier distribution opacity. |
| Direct Procurement Contracting | Unilever and L'Oréal bypass distributor intermediaries for supply chain transparency under ECHA mandates. |
| Continuous Fermentation Scale-Up | Greater Boston and San Francisco Bay Area biotech clusters pilot integrated membrane separation technology. |
| ANVISA Pathway Entry | São Paulo state chemical parks develop chromatographic purification for generic drug manufacturing demand. |
Research Methodology
A spread of perspectives from fermentation platform engineers, pharmaceutical regulatory affairs leads, personal care procurement directors, and agricultural biocontrol formulators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against NMPA registration databases, ECHA REACH filings, FDA food additive regulations, and FSSAI preservative limit documentation. Customs trade data from Shandong and Jiangsu export corridors, CDSCO API master file records, and ANVISA bioequivalence submission timelines anchored bottom-up volume estimates against top-down market sizing.
Demand-supply balance modeling across the projection horizon segmented by production methodology, application concentration, and end-use industry specification stringency. Pharmaceutical-grade purity thresholds, cosmetic additive sustainability scorecards, and food preservation regulatory limits formed discrete demand nodes. CAGRs derived from trajectory analysis of fermentation capacity expansion, synthetic biology yield improvement curves, and regulatory compliance cost escalation.
Sensitivities concentrate around CRISPR strain engineering breakthroughs, EU carbon border adjustment mechanism implementation timelines, and Brazilian ANVISA pathway streamlining. Forecasts reflect documented assumptions on feedstock cost trajectories and certification timeline stability. Macroeconomic commodity volatility, regulatory disclosure requirement acceleration, or continuous fermentation technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Sodium Fluorosilicate Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Stimulation Materials Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Potassium Alum Market
Chemicals
Europe Textile Chemicals Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Formalin Market
Chemicals
Superplasticizer Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Global Butanediol Market
Chemicals
Latin America Construction Chemicals Market
Chemicals
Methoprene Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
Pyromellitic Dianhydride Market