
 Calcium Hydroxide Market | 2026-2036
Calcium Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Hydroxide Market Analysis
Multi-source procurement among lime producers is expanding as water treatment contractors diversify supply risk across regional quarries. Carmeuse sustains captive limestone reserves across Belgium and France that anchor its hydrated lime output. Lhoist Group dominates specialty slurry grades for North American flue gas desulfurization. Graymont Limited leverages vertical integration from quarry to bulk delivery to control logistics costs in the Pacific Northwest.
Calcium hydroxide, Ca(OH)₂, is an inorganic compound produced by slaking calcium oxide with water to yield a fine white powder or aqueous slurry with pH typically exceeding 12.4; it serves primarily as an alkaline reagent for pH correction, chemical precipitation, and masonry binding across industrial and environmental applications. The powder segment remains the volume leader in cement production and soil stabilization where bagged delivery suits remote job sites. Slurry formulations capture expanding margin pools in wastewater treatment as utilities automate chemical feed systems. Granule grades occupy a mature niche in agricultural liming where spreader compatibility limits format innovation.
EPA effluent guidelines under the Clean Water Act shape product purity specifications for mercury and heavy metals in drinking water applications. REACH registration requirements in Europe constrain import channels for non-EU producers seeking construction chemical markets. OSHA permissible exposure limits for respirable crystalline silica drive packaging innovation toward sealed bulk systems that reduce handler contact. Stakeholders must monitor regulatory divergence between EPA and ECHA hazard classifications that could fragment formulation standards across Atlantic supply chains.
Market Dynamics
EPA effluent guidelines and REACH registration requirements are forcing calcium hydroxide producers to reconfigure purification protocols and documentation systems, while water treatment utilities automate chemical feed infrastructure to meet tightening discharge standards.
Growth Catalysts
- Clean Water Act enforcement:EPA mercury and heavy metals limits for drinking water applications mandate high-purity calcium hydroxide grades, expanding specification-driven procurement among municipal utilities.
- Flue gas desulfurization retrofit cycles:Coal-fired power plants across the United States and Germany upgrade scrubber systems, consuming specialty slurry formulations for sulfur dioxide capture.
- Soil stabilization specifications:State departments of transportation in Texas, California, and Florida specify hydrated lime for subgrade modification in highway construction bids.
Market Restraints
- Limestone feedstock concentration:Captive quarry reserves in Belgium, France, and select Appalachian formations create supply vulnerability for non-integrated producers.
- Energy cost volatility:Natural gas and electricity inputs for kiln operations comprise substantial production costs, exposing margins to commodity price swings.
- Portland cement substitution:Fly ash and ground granulated blast-furnace slag displace calcium hydroxide in select masonry and stabilization applications.
Strategic Opportunities
- Indian water infrastructure:Central Pollution Control Board mandates for industrial effluent treatment create demand for automated slurry feed systems in Gujarat and Maharashtra chemical clusters.
- Carbon capture integration:Direct air capture facilities employ calcium hydroxide for carbon dioxide mineralization, opening chemical loop applications beyond traditional end-uses.
- Sealed bulk packaging:OSHA silica exposure limits drive adoption of closed-loop pneumatic delivery systems that eliminate handler contact and reduce liability exposure.
Industry Challenges
- Process automation expertise:Slurry production facilities require instrumentation specialists capable of maintaining pH control and solids concentration within tight tolerances, creating recruitment bottlenecks.
- REACH dossier maintenance:European producers face recurring compliance costs for substance registration updates and extended safety data sheet obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Hydroxide Market |
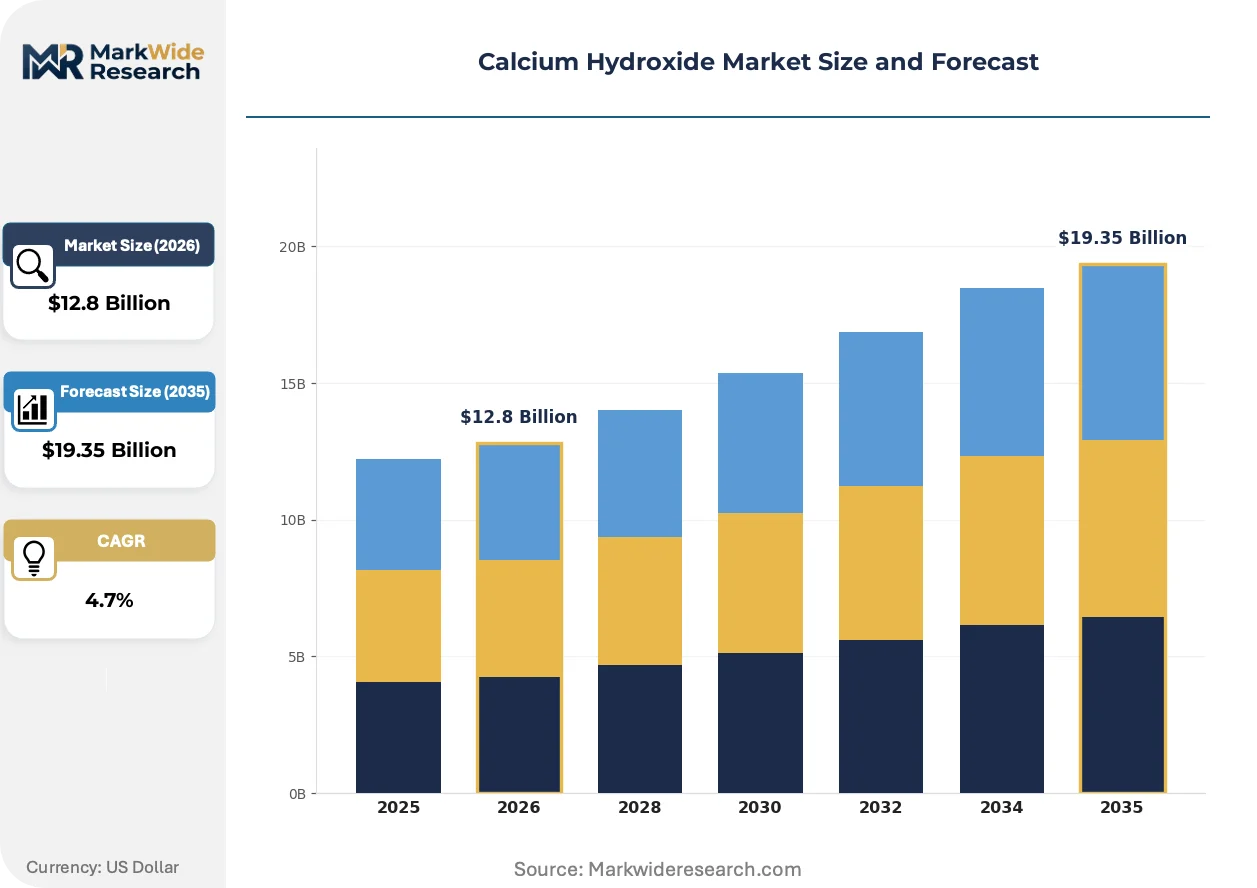
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Slurry, Solution End Use Industry: Construction, Agriculture, Water Treatment, Mining Application: Soil Stabilization, Wastewater Treatment, Cement Production, Paper Manufacturing Packaging Type: Bag, Bulk, Drum, Container |
| Companies Covered | Graymont Limited, Omya AG, Carmeuse, Sigma-Aldrich, Hydrite Chemical Co., Lhoist Group, United States Lime & Minerals, Nordkalk Corporation, Mississippi Lime Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Hydroxide Market Emerging Trajectories
Digital process control and closed-loop material handling are compressing operational variability while regulatory data requirements expand documentation burdens across the value chain.
Membrane filtration integration with hydrated lime slaking systems is unifying water treatment plant operations by combining chemical preparation and solids removal in single-unit processes. Municipal utilities in the Rhine-Ruhr industrial corridor adopt these skids to reduce footprint and labor intensity. The technology is unifying procurement decisions around packaged systems rather than commodity chemical supply.
REACH registration requirements for calcium hydroxide under Substance Evaluation constrain import channels for non-EU producers seeking construction chemical markets in Germany and France. Industrial downstream users now demand full supply chain disclosure for SVHC compliance. Specialty slurry grades for drinking water applications face the most stringent documentation requirements.
Specification-driven procurement now dominates water treatment chemical selection, with utilities prioritizing certified purity grades over volume discounts. Distributors in the Ohio River Valley respond by stocking multiple quality tiers and providing batch certification documentation. Municipal buyers in Pennsylvania and Ohio increasingly require third-party testing protocols that extend qualification timelines.
Calcium Hydroxide Market Segmentation
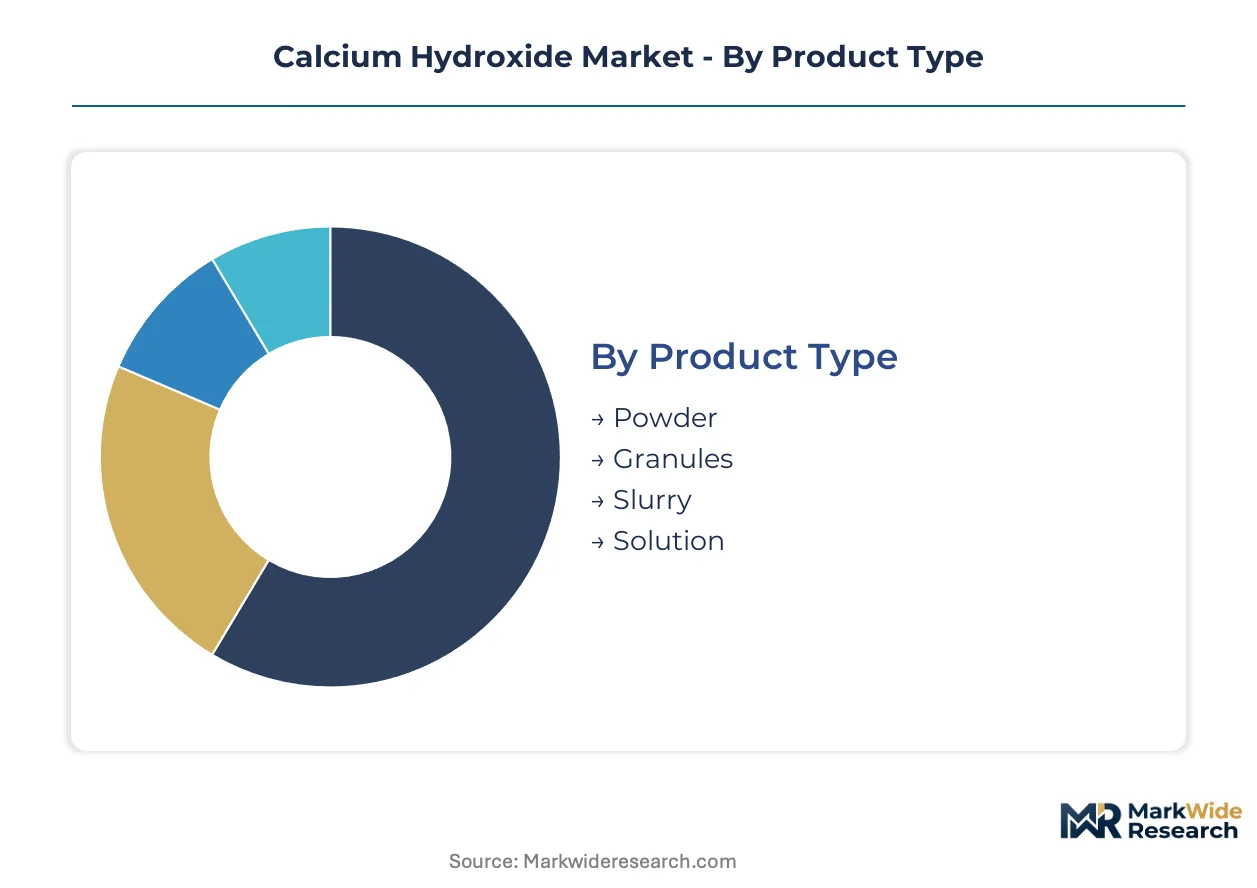
Calcium hydroxide procurement patterns diverge sharply across product formats and end-use specifications. Water treatment contractors prioritize slurry automation compatibility while construction buyers optimize for bagged logistics at remote sites.
Product Type:
Buyers in this category separate by automation infrastructure and handling cost tolerance rather than chemistry alone.
- Powder:Fine white particulate produced by controlled slaking of calcium oxide, typically 95%+ purity with bulk density around 0.5 g/cm³. Highway construction crews in Texas and California specify bagged powder for soil stabilization where pneumatic delivery is unavailable. Volume sits with powder; growth tilts toward slurry.
- Slurry:Aqueous suspension with solids content ranging 20-40% and pH exceeding 12.4, requiring continuous agitation to prevent settling. Municipal utilities in Germany's Rhine-Ruhr corridor deploy automated feed skids that integrate membrane filtration, unifying chemical preparation with solids removal. Slurry captures expanding margin pools as EPA discharge standards tighten.
- Granules:Pelletized form engineered for spreader compatibility in agricultural liming applications. Farm cooperatives in France's Limousin region favor this format for pasture pH correction.
- Solution:Dilute aqueous preparation for specialized chemical synthesis and laboratory applications. Pharmaceutical manufacturers in Switzerland source certified low-heavy-metal grades for process chemistry.
Slurry commands premium pricing where automation justifies total cost of ownership; powder retains volume leadership in cost-sensitive infrastructure.
End Use Industry:
Regulatory exposure and capital intensity distinguish buyers across these verticals.
- Water Treatment:Municipal utilities and industrial effluent facilities consuming high-purity grades for pH correction and heavy metals precipitation. EPA mercury limits under the Clean Water Act mandate certified purity documentation that extends procurement cycles in Pennsylvania and Ohio.
- Construction:State transportation departments and highway contractors deploying hydrated lime for subgrade modification and masonry mortar. Caltrans specifications for soil stabilization drive volume in California's Central Valley projects.
- Agriculture:Farm operations and agricultural cooperatives applying calcium hydroxide for soil pH management and livestock sanitation. Demand clusters in France's dairy regions and Germany's arable belt.
- Mining:Mineral processing facilities using alkaline reagents for pH control in flotation circuits and acid mine drainage neutralization. Base metal operations in Australia's Queensland specify bulk delivery for tailings treatment.
Water treatment leads specification complexity; construction anchors absolute tonnage.
Application:
Process integration requirements and regulatory scrutiny define buyer priorities here.
- Wastewater Treatment:Municipal and industrial facilities employing calcium hydroxide for phosphorus precipitation, heavy metals removal, and sludge conditioning. Utilities automate chemical feed to meet tightening EPA effluent guidelines.
- Soil Stabilization:Highway engineering applications modifying clay subgrades to improve bearing capacity and reduce plasticity. Florida DOT specifications require hydrated lime for projects across the Panhandle and peninsula.
- Cement Production:Portland cement manufacturers using calcium hydroxide as an additive and processing aid. Plants in Belgium integrate captive supply from adjacent quarry operations.
- Paper Manufacturing:Pulp and paper mills employing alkaline reagents in chemical recovery and bleaching sequences. Nordic producers in Sweden and Finland favor slurry delivery for integrated mill complexes.
Soil stabilization dominates construction-phase procurement; wastewater treatment exhibits the steepest specification escalation.
Packaging Type:
Handler exposure regulations and logistics infrastructure shape format selection.
- Bag:Multi-wall paper or woven polypropylene containers typically 25-50 kg for powder and granule grades. OSHA respirable crystalline silica limits drive sealed bag innovations that reduce handler contact at remote job sites.
- Bulk:Pneumatic tanker or hopper truck delivery for high-volume consumers with silo storage. Water treatment utilities in the Ohio River Valley specify bulk to minimize packaging waste and handling labor.
- Drum:Steel or fiber containers for specialty slurry grades and solution formulations. Laboratory and pharmaceutical buyers in Switzerland require drum packaging for certified low-contamination products.
- Container:Intermediate bulk containers and totes for mid-scale industrial users lacking permanent storage infrastructure. Chemical processors in Gujarat's industrial corridor favor this format for flexible inventory management.
Bulk delivery minimizes unit costs at scale; bagged formats retain necessity where infrastructure is absent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive limestone deposits in Belgium and France anchor European production capacity, while Appalachian formations and Western US reserves supply North American kiln operations. Water treatment infrastructure investments and flue gas desulfurization retrofits concentrate demand in industrial corridors across Germany, the United States, and India.
United States
EPA mercury limits under the Clean Water Act drive municipal utilities toward certified high-purity grades for drinking water applications. Coal-fired power plants in the Ohio River Valley upgrade scrubber systems, consuming specialty slurry formulations for sulfur dioxide capture. Pennsylvania and Ohio utilities now require third-party testing protocols that extend supplier qualification timelines.
Germany
Rhine-Ruhr industrial corridor municipalities deploy automated chemical feed skids integrating membrane filtration with hydrated lime slaking systems. REACH registration requirements under Substance Evaluation constrain import channels for non-EU producers seeking construction chemical markets. Carmeuse and Lhoist Group operate major production hubs serving regional water treatment and flue gas desulfurization demand.
India
Central Pollution Control Board mandates for industrial effluent treatment create demand for automated slurry feed systems in Gujarat and Maharashtra chemical clusters. State pollution control authorities enforce stricter discharge standards for textile and pharmaceutical processors. Bulk delivery infrastructure expands around Ahmedabad and Mumbai to serve mid-scale industrial users lacking permanent silo storage.
Belgium
Captive limestone reserves across Wallonia anchor integrated quarry-to-kiln operations for hydrated lime output. ECHA hazard classification requirements shape product purity specifications for cross-border construction chemical trade. Integrated cement plants near Antwerp source adjacent quarry operations for processing aid supply.
France
Farm cooperatives in the Limousin region favor granule grades for pasture pH correction and livestock sanitation applications. ANSM documentation requirements for pharmaceutical-grade calcium hydroxide constrain laboratory chemical supply channels. Construction chemical demand clusters around Lyon and Marseille infrastructure projects specifying hydrated lime for soil stabilization.
Calcium Hydroxide Market Vendor Landscape
Global majors compete with regional champions across quarry reserve access and slurry formulation expertise. The vendor base organizes around integrated limestone-to-lime operators, specialty chemical distributors, and construction material suppliers. Three archetypes dominate: captive reserve holders with kiln networks, toll processors serving regional water treatment contractors, and construction chemical blenders sourcing commodity hydrate. Capacity expansion and strategic partnerships represent the dominant competitive moves as EPA and ECHA regulations fragment formulation standards.
Among North American integrated producers, Graymont Limited exemplifies the captive reserve archetype through its Pacific Northwest quarry-to-delivery infrastructure. Mississippi Lime Company occupies a position within the specialty slurry tier serving municipal automation requirements. Carmeuse and Lhoist Group anchor the European integrated tier with multi-country limestone portfolios. United States Lime & Minerals represents the regional champion model focused on Southwestern construction and industrial markets.
| Leading Market Players |
|---|
| Graymont Limited |
| Omya AG |
| Carmeuse |
| Sigma-Aldrich |
| Hydrite Chemical Co. |
| Lhoist Group |
| United States Lime & Minerals |
| Nordkalk Corporation |
| Mississippi Lime Company |
| Others |
Supply Flow & Price Mechanics
Membrane filtration integration with slaking systems is compressing operational footprints while simultaneously concentrating procurement power among utilities that can justify packaged system investments. This technology shift rewards scaled producers with automated slurry capabilities and marginalizes commodity powder suppliers in municipal water treatment segments.
Pricing Analysis
Service bundling separates system integrators from commodity suppliers, with automated skid manufacturers including pH control calibration and membrane maintenance in long-term contracts while unbundled chemical-only vendors compete on spot powder pricing. Three-tier pricing structure across certified high-purity, standard industrial, and economy agricultural grades reflects EPA mercury documentation requirements and REACH dossier completeness. Cost compression in standard industrial tiers is intensifying because energy-intensive kiln operations face natural gas price volatility. Municipal utilities in Pennsylvania and Ohio exhibit lowest price sensitivity due to regulatory compliance mandates, while highway contractors in Texas prioritize volume discounts over certification tiers.
Supply Chain Analysis
Limestone feedstock quality rests on captive quarry reserves in Belgium, France, and select Appalachian formations that anchor integrated production economics. Quicklime sourcing, slaking equipment fabrication, and specialty chemical additives for pH stabilization constitute critical input dependencies. Single-source vulnerability concentrates in high-calcium limestone deposits controlled by Carmeuse and Lhoist Group across Wallonia and Lorraine. Distribution runs through regional toll processors serving water treatment contractors, construction material distributors, and agricultural cooperatives with divergent logistics requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated slurry feed systems are displacing manual powder handling in municipal water treatment, creating a technology-transition window where legacy kiln operators must adapt or cede share to integrated system providers.
For Market Incumbents: Cement captive limestone reserve positions through quarry acquisitions or long-term lease extensions in Belgium and France before REACH Substance Evaluation tightens import channels. Defend municipal utility relationships by embedding membrane filtration skids into chemical supply contracts, neutralizing toll processor competition. Prioritize backward integration into quicklime production to control energy cost exposure. For New Entrants and Emerging Players: Begin with carbon capture mineralization applications in direct air capture facilities, where chemical loop demand is nascent and specification standards remain unsettled. Target Indian industrial clusters in Gujarat and Maharashtra where Central Pollution Control Board mandates outpace local slurry production capacity. Lead with containerized intermediate bulk packaging to bypass silo infrastructure gaps among mid-scale textile and pharmaceutical processors. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty slurry toll processors with automated feed system expertise and established utility relationships. Long-term viability favors integrated operators controlling quarry-to-delivery infrastructure across multiple regulatory jurisdictions. Watch EPA effluent guideline enforcement consistency across Ohio River Valley states as inflection indicator for specification-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Carmeuse and Lhoist Group anchor production economics through captive Wallonia and Lorraine quarries. |
| Automated Slurry System Deployment | Rhine-Ruhr municipalities integrate membrane filtration skids that unify chemical preparation with solids removal. |
| Sealed Bulk Packaging Innovation | OSHA silica exposure limits drive closed-loop pneumatic delivery adoption among Pennsylvania and Ohio utilities. |
| Carbon Capture Chemical Loop Partnerships | Direct air capture facilities employ calcium hydroxide mineralization, opening demand beyond traditional end-uses. |
| REACH Dossier Maintenance Investment | ECHA Substance Evaluation compliance constrains non-EU import channels for construction chemical markets. |
Methodological Framework
Trade databases, SEC filings from lime and limestone operators, and ECHA registration documentation formed the secondary backbone, supplemented by customs records tracking calcium hydroxide and quicklime flows. Primary interviews with water treatment plant managers, municipal procurement officers, highway construction material specifiers, and chemical distribution channel partners validated demand patterns and pricing dynamics. Bottom-up and top-down triangulation reconciled quarry production capacities with end-use consumption estimates across product formats and regional markets.
Bottom-up modeling built from individual quarry capacities, kiln utilization rates, and slurry production line configurations, while top-down analysis cross-checked against construction spending and water treatment infrastructure investment flows. Segmentation dimensions included product format tier, end-use industry vertical, packaging logistics type, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to utility automation adoption rates and flue gas desulfurization retrofit cycles across the analysis window. Energy cost sensitivity and limestone reserve depletion timelines informed scenario-weighted projections.
Underlying measurement precision varies by segment; automated slurry system deployments and certified high-purity grades carry tighter precision than agricultural granule consumption. Forecasts reflect assumptions regarding EPA enforcement consistency, REACH implementation timelines, and natural gas price stability that could revise trajectories if regulatory or commodity conditions shift. A small set of named triggers—Central Pollution Control Board mandate acceleration, carbon capture subsidy structures, and silica exposure limit harmonization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Waterproofing Chemicals Market
Chemicals
Tributyl Phosphate Market
Chemicals
Acetic Ether Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Hydrogen Fluoride Pyridine Market
Chemicals
Tanning Agents Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
South America Construction Chemicals Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
Global Organobromine Market
Chemicals
Benzophenone (Oxybenzone) Market
Chemicals
Global Acetic Anhydride Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Global Fluorosilicic Acid Market