
 Anhydrides Market | 2026-2036
Anhydrides Market Size, Share, and Industry Trends Forecast 2026-2036
Anhydrides Market Analysis
China's expanding petrochemical corridor is reshaping supply availability for maleic anhydride derivatives. BASF SE leverages integrated naphtha-to-derivatives complexes in Ludwigshafen to sustain cost leadership across European pharmaceutical-grade supply. Huntsman International LLC anchors North American competitiveness through specialized alkyd resin precursor output. DuPont differentiates via high-purity succinic anhydride positions serving electronics and specialty polymer segments.
Anhydrides are cyclic acid derivatives formed by dehydration of dicarboxylic acids, typically exhibiting reactivity with alcohols and amines to form esters and imides at controlled temperature ranges. These compounds serve primarily as curing agents, plasticizers, and chemical intermediates in industrial synthesis pathways. Phthalic anhydride occupies mature volume leadership through entrenched plasticizer demand, while maleic anhydride captures faster expansion in unsaturated polyester resins for construction composites. Succinic anhydride concentrates margin pools where pharmaceutical and biodegradable polymer applications command specification premiums over commodity grades.
EPA emission standards and OSHA workplace exposure limits constrain US production economics for conventional phthalic routes, while REACH authorization requirements in Europe redirect investment toward bio-based succinic alternatives. China's MEE enforcement on volatile organic compound discharge accelerates closure of smaller coal-tar-based units, tightening regional maleic anhydride availability. Stakeholders must monitor regulatory divergence between jurisdictions to align capacity decisions with shifting compliance cost structures and emerging low-carbon feedstock pathways.
Market Dynamics
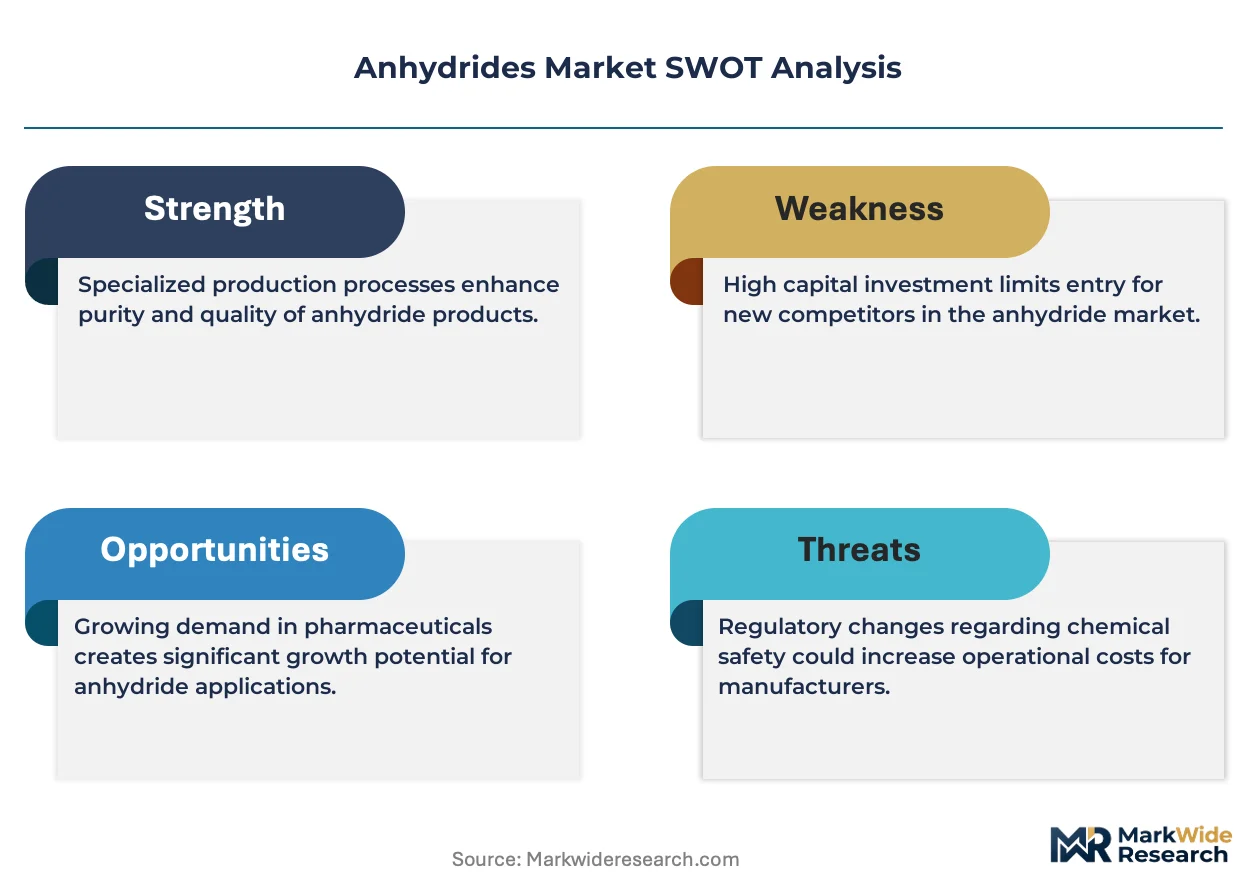
Feedstock volatility in benzene and n-butane markets is compressing margin structures for conventional phthalic anhydride producers, forcing capacity reallocation toward bio-based succinic routes that command specification premiums in pharmaceutical and biodegradable polymer segments.
Growth Catalysts
- Unsaturated Polyester Resin Demand:Construction composite manufacturers in India and Vietnam are accelerating maleic anhydride consumption for corrosion-resistant infrastructure applications. Infrastructure spending under India's National Infrastructure Pipeline redirects procurement toward domestic chemical intermediates.
- REACH Authorization Pressures:ECHA's sunset date extensions for certain phthalate plasticizers are redirecting European formulation demand toward non-phthalate anhydride alternatives. Specialty polymer compounders in Germany and the Netherlands are qualifying succinic derivatives for medical device applications.
- China's Dual Carbon Targets:MEE enforcement on coal-tar-based production routes is tightening regional maleic anhydride availability and elevating import dependency for coastal derivative manufacturers. Petrochemical corridor expansions in Zhejiang and Jiangsu provinces concentrate supply among integrated producers.
Market Restraints
- Benzene Price Volatility:Crude oil oscillations transmit directly to ortho-xylene and naphthalene feedstock costs, destabilizing phthalic anhydride production economics for non-integrated European and North American facilities.
- Supply Concentration in China:Maleic anhydride capacity clusters among three coastal provinces, creating geographic single-point vulnerability for Asian derivative supply chains and amplifying disruption risk from environmental enforcement actions.
- Substitution by Bio-Succinic Acid:Fermentation-derived succinic acid from agricultural feedstocks is capturing share in biodegradable polymer and personal care applications where carbon intensity metrics influence procurement decisions.
Strategic Opportunities
- Underpenetrated Indian Pharmaceutical Sector:CDSCO's accelerated approval pathways for active pharmaceutical ingredients are expanding domestic demand for high-purity succinic and maleic anhydrides in generic drug synthesis.
- EU Green Deal Chemistry Mandates:The Chemicals Strategy for Sustainability is creating preferential market access for bio-based anhydride producers who can demonstrate renewable carbon content through mass-balance certification.
- Digital Distribution Platforms:B2B chemical marketplaces are compressing procurement cycles for mid-volume buyers in specialty coatings and adhesive segments, enabling direct producer-to-formulator relationships that bypass traditional distributor markups.
Industry Challenges
- Process Safety Expertise Scarcity:Maleic anhydride production involves exothermic oxidation chemistry requiring specialized reactor engineering talent that chemical engineering programs in Western Europe and North America are producing at insufficient rates.
- Pharmaceutical-Grade Certification Timelines:ICH Q7 compliance and FDA DMf filing processes extend qualification periods to 18-24 months for new succinic anhydride supply sources, freezing out speculative capacity investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anhydrides Market |
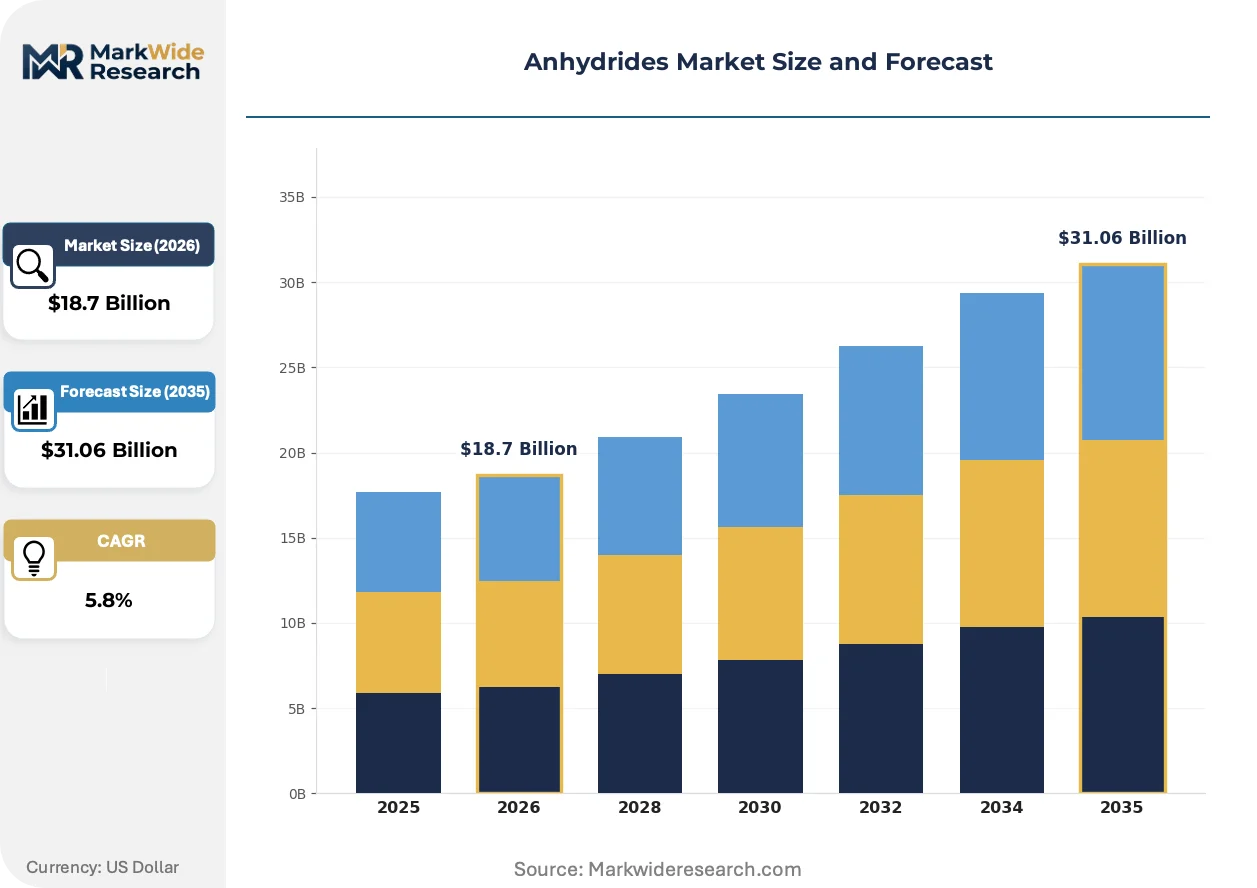
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phthalic Anhydride, Maleic Anhydride, Succinic Anhydride, Glutaric Anhydride End User: Plastics, Coatings, Adhesives, Pharmaceuticals Application: Polymer Production, Paint Formulation, Textile Finishing, Chemical Synthesis Packaging Type: Drums, Bags, Totes, Bulk Containers |
| Companies Covered | BASF SE, Huntsman International LLC, LANXESS, Celanese Corporation, Eastman Chemical Company, DuPont, Solvay, Akzo Nobel, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anhydrides Market Emerging Trajectories
Electrification of chemical process heating and catalytic efficiency improvements are restructuring production cost curves, while regulatory carbon accounting requirements are embedding emissions transparency into procurement specifications across European and North American buyer bases.
Catalytic partial oxidation technologies utilizing vanadium-phosphorus oxide catalysts with enhanced selectivity are rendering obsolete conventional fixed-bed benzene oxidation routes for maleic anhydride production. Unsaturated polyester resin manufacturers in Turkey and Mexico are qualifying these lower-carbon-intensity supply sources for export-oriented composite applications. The technology diffusion is compressing capital recovery periods for first-mover adopters while stranding legacy assets in high-regulatory-cost jurisdictions.
EU F-Gas Regulation phase-down schedules are tightening containment requirements for process refrigeration systems in anhydride derivative facilities. Chemical processors in Belgium and Italy are retrofitting ammonia-based cooling circuits to avoid hydrofluorocarbon quota limitations that constrain production scale-up. The regulatory friction is elevating compliance capital requirements for mid-scale European producers relative to integrated Gulf Coast competitors with newer infrastructure.
Specification-driven procurement is consolidating buyer power among top-tier coatings formulators who now require ISO 14001 certification and product carbon footprint disclosures from anhydride suppliers. Mid-scale distributors in the US Midwest and Northern Italy are losing share to direct sourcing arrangements as procurement functions centralize sustainability verification. The behavioral shift is most pronounced in automotive OEM supply chains where Scope 3 emissions reporting obligations cascade through tiered supplier networks.
Anhydrides Market Segmentation
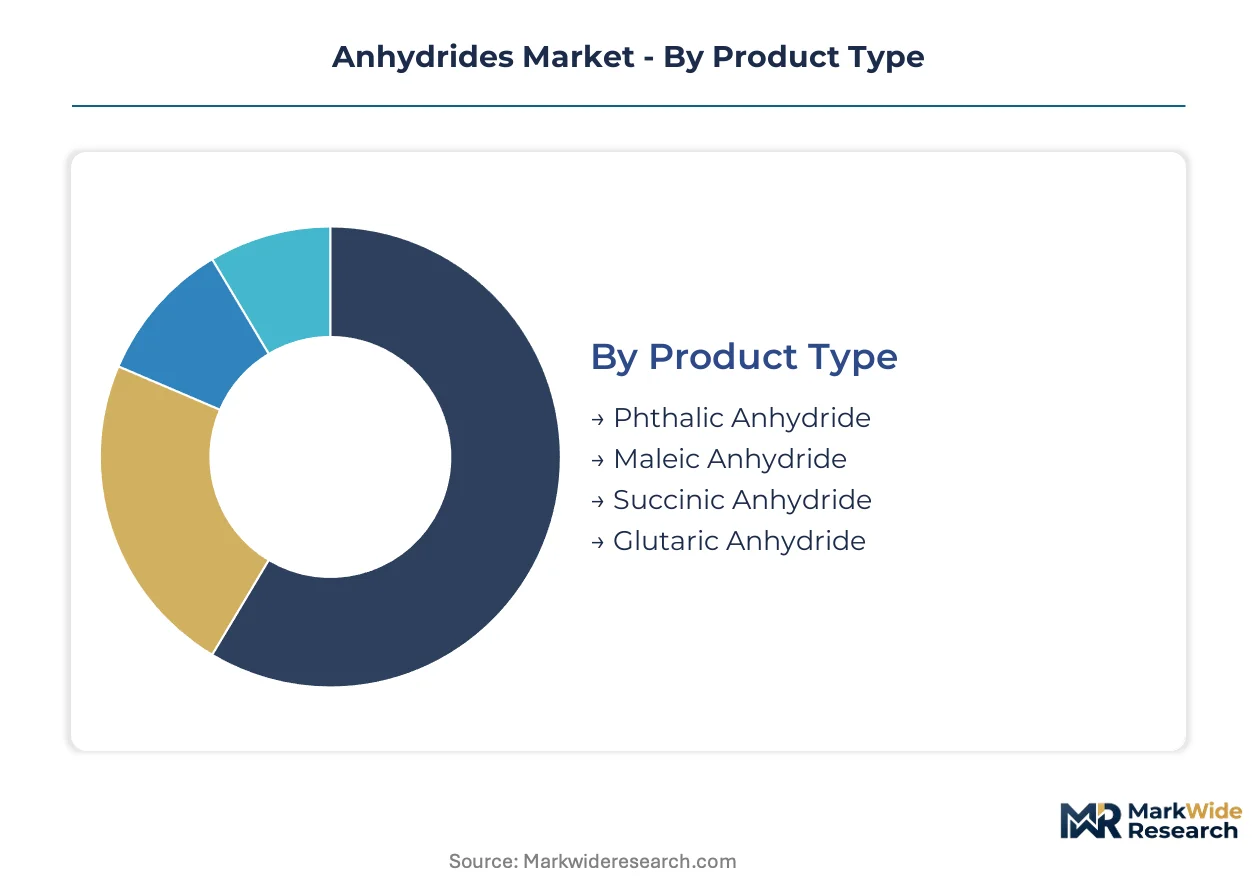
Segmentation in anhydrides reveals how specification requirements diverge across end-use applications. Technical purity thresholds, regulatory compliance burdens, and supply security needs create distinct purchasing behaviors that suppliers must address through differentiated service models.
Product Type:
After-sales service intensity varies sharply across product categories, with pharmaceutical-grade variants demanding batch traceability and technical support that commodity grades do not require.
- Phthalic Anhydride:Ortho-xylene-derived cyclic compound serving as the dominant plasticizer precursor for PVC applications. Demand concentrates in flexible film and cable jacket manufacturing across India and Vietnam, where infrastructure investment drives volume procurement. REACH authorization pressures on phthalate plasticizers in Europe are redirecting formulation demand toward non-phthalate alternatives, constraining growth in high-regulatory-cost jurisdictions.
- Maleic Anhydride:Butane-oxidized dicarboxylic anhydride exhibiting high reactivity in Diels-Alder chemistry and unsaturated polyester resin curing. Construction composite manufacturers in India and Vietnam are accelerating consumption for corrosion-resistant infrastructure under national infrastructure spending programs. China's MEE enforcement on coal-tar-based production routes is tightening regional availability and elevating import dependency for coastal derivative manufacturers.
- Succinic Anhydride:Five-membered ring anhydride commanding specification premiums in pharmaceutical intermediates and biodegradable polymer synthesis.
- Glutaric Anhydride:Seven-carbon cyclic anhydride serving niche applications in specialty polymer crosslinking and agricultural chemical synthesis.
Phthalic anhydride holds the largest share; momentum sits with maleic anhydride for composite applications.
End User:
Volume scale and margin structure diverge substantially across end-user categories, with pharmaceutical procurement exhibiting price inelasticity that plastics compounding does not match.
- Plastics:PVC plasticizer and polymer modifier applications representing the foundational demand base for phthalic anhydride derivatives. Flexible film processors in India and Southeast Asia drive procurement volume as packaging demand expands with consumer goods consumption.
- Coatings:Alkyd resin and unsaturated polyester formulations for protective and decorative surface applications. Automotive OEM supply chains in Germany and Japan now require ISO 14001 certification and product carbon footprint disclosures from anhydride suppliers, elevating compliance costs for mid-scale producers.
- Adhesives:Reactive hot-melt and structural bonding systems utilizing anhydride curing chemistry. Demand concentrates in electronics assembly and construction applications where bond durability specifications command technical service intensity.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and excipient applications requiring ICH Q7 compliance and FDA DMF filing. CDSCO's accelerated approval pathways in India are expanding domestic demand for high-purity succinic and maleic anhydrides in generic drug synthesis.
Plastics commands the volume base; pharmaceuticals generates the steepest margin expansion.
Application:
Process integration requirements separate polymer production from discrete chemical synthesis applications, with continuous operations demanding supply security that batch processes tolerate less.
- Polymer Production:Continuous manufacturing of polyesters, polyimides, and modified thermoplastics requiring consistent feedstock quality and volume assurance. Integrated petrochemical complexes in Zhejiang and Jiangsu provinces concentrate supply among producers with captive raw material positions.
- Paint Formulation:Alkyd resin and coating additive compounding where VOC content regulations constrain formulation flexibility. EPA emission standards and OSHA workplace exposure limits in the US constrain production economics for conventional phthalic routes.
- Textile Finishing:Dye carrier and fabric treatment applications utilizing anhydride reactivity for fiber modification. Regional textile clusters in India and Bangladesh drive procurement with sustainability certification requirements tightening supplier qualification.
- Chemical Synthesis:Intermediate production for agrochemicals, flavors, and specialty molecules where batch-scale flexibility outweighs volume pricing. Fermentation-derived bio-succinic acid is capturing share in biodegradable polymer and personal care applications where carbon intensity metrics influence procurement decisions.
Polymer production anchors volume demand; chemical synthesis offers the fastest route to premium pricing.
Packaging Type:
Logistics cost structures and handling safety requirements determine packaging selection, with bulk formats favored by integrated operations and drums serving distributed specialty demand.
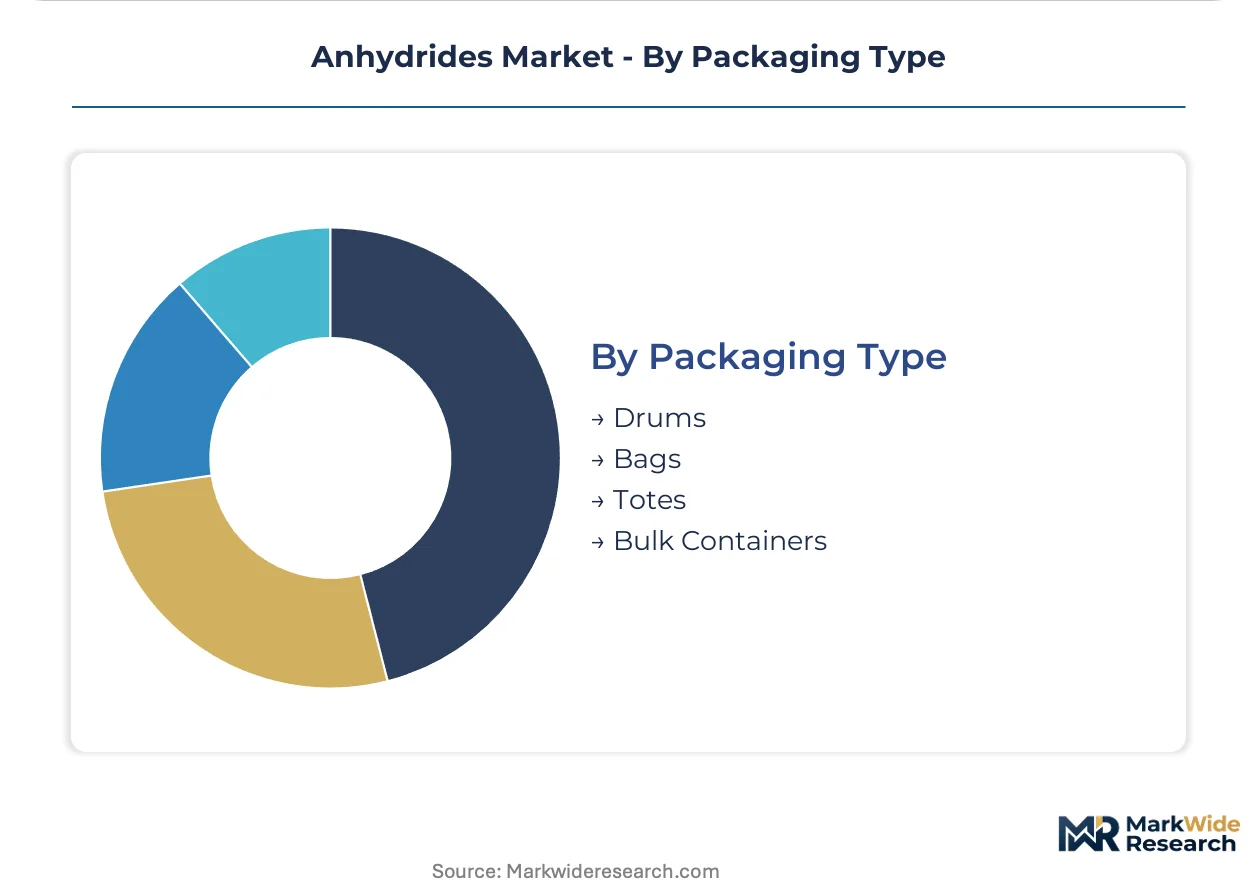
- Drums:Standard 200-liter steel containers for mid-volume shipments requiring material segregation and moisture protection. Specialty coatings formulators in Northern Italy and the US Midwest rely on drum packaging for just-in-time procurement from multiple suppliers.
- Bags:Multi-layer laminated sacks for powdered or flaked anhydride derivatives with anti-caking requirements. Regional distributors in India utilize bag packaging to serve fragmented plastics compounder demand across dispersed industrial zones.
- Totes:Intermediate bulk containers enabling pumpable transfer for liquid anhydride derivatives. Automotive coatings plants in Germany and Mexico specify tote delivery to minimize handling labor and contamination risk.
- Bulk Containers:Tank trucks and railcars for continuous supply to integrated polymer production facilities. Petrochemical corridor expansions in China's coastal provinces concentrate bulk logistics infrastructure among integrated producers with dedicated transport arrangements.
Bulk containers dominate tonnage movement; totes are gaining share among efficiency-focused formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE enforcement in China is redirecting maleic anhydride trade flows as domestic coal-tar capacity contracts. Regulatory divergence across major economies is fragmenting supply security calculations for derivative manufacturers.
China
Petrochemical corridor expansions in Zhejiang and Jiangsu provinces are concentrating supply among integrated producers with captive n-butane positions. MEE volatile organic compound discharge standards are accelerating closure of smaller coal-tar-based maleic anhydride units. Coastal derivative manufacturers in Ningbo and Shanghai are elevating import dependency as regional availability tightens.
Germany
Specialty polymer compounders in Ludwigshafen and Leverkusen are qualifying succinic derivatives for medical device applications under ECHA sunset date pressures. REACH authorization requirements are redirecting formulation demand toward non-phthalate anhydride alternatives. BASF SE's integrated naphtha-to-derivatives complex sustains cost leadership across pharmaceutical-grade supply.
United States
Alkyd resin precursor output from Gulf Coast producers anchors North American competitiveness in coatings applications. EPA emission standards and OSHA workplace exposure limits constrain production economics for conventional phthalic routes. Texas and Louisiana petrochemical infrastructure supports bulk logistics efficiency for integrated operations.
India
Construction composite manufacturers in Gujarat and Maharashtra are accelerating maleic anhydride consumption for corrosion-resistant infrastructure under the National Infrastructure Pipeline. CDSCO accelerated approval pathways for active pharmaceutical ingredients are expanding domestic demand for high-purity succinic and maleic anhydrides. Domestic plastics compounders across dispersed industrial zones are driving procurement volume for flexible film applications.
Japan
Automotive OEM supply chains in Toyota City and Yokohama now require ISO 14001 certification and product carbon footprint disclosures from anhydride suppliers. METI industrial standards are embedding emissions transparency into procurement specifications for tiered supplier networks. Specialty coatings formulators are consolidating procurement functions to centralize sustainability verification.
Anhydrides Market Vendor Landscape
Capability concentration sits with integrated petrochemical majors possessing captive feedstock positions; scale advantage sits with regional specialists serving derivative niches. The vendor base stratifies across three tiers: multinational chemical conglomerates with global distribution, mid-cap national champions with backward integration into key raw materials, and specialized pharmaceutical-grade producers with ICH Q7 certification. Dominant competitive moves include capacity reallocation toward bio-based succinic routes and geographic expansion into underpenetrated Indian pharmaceutical procurement.
Within the integrated multinational tier, BASF SE and DuPont exemplify divergent strategic positioning—BASF anchoring European pharmaceutical-grade supply through Ludwigshafen infrastructure, DuPont occupying high-purity succinic anhydride positions in electronics and specialty polymer segments. Huntsman International LLC represents the North American specialist archetype with concentrated alkyd resin precursor output. LANXESS and Celanese Corporation sit within the mid-cap tier where portfolio diversification into non-phthalate alternatives is redirecting R&D allocation.
| Leading Market Players |
|---|
| BASF SE |
| Huntsman International LLC |
| LANXESS |
| Celanese Corporation |
| Eastman Chemical Company |
| DuPont |
| Solvay |
| Akzo Nobel |
| SABIC |
| Others |
Supply Flow & Price Mechanics
Undercapacity in China's coastal maleic anhydride corridor is elevating spot premiums for derivative manufacturers in Ningbo and Shanghai, compressing procurement budgets while forcing buyers toward longer-term contract structures that sacrifice flexibility for supply security.
Pricing Analysis
Coastal China commands a substantial premium over inland European quotations for pharmaceutical-grade succinic anhydride, reflecting freight differentials and MEE-driven supply tightness. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and commodity-grade levels segments buyer pools by certification burden and batch traceability requirements. Cost compression in technical-grade phthalic anhydride is intensifying because benzene feedstock volatility transmits directly through ortho-xylene and naphthalene input costs. Plastics compounders in India exhibit the highest price sensitivity due to dispersed procurement across fragmented industrial zones, while pharmaceutical formulators in Germany accept substantial premiums for ICH Q7-compliant supply.
Supply Chain Analysis
Tariff exposure between China and downstream derivative markets in Southeast Asia dominates supply chain risk calculations for maleic anhydride procurement. Production gravity centers on Zhejiang and Jiangsu provinces in China, Ludwigshafen in Germany, and the Gulf Coast petrochemical corridor in the United States. Feedstock supply draws from captive n-butane positions, benzene derivatives from integrated naphtha cracking, and fermentation-derived agricultural feedstocks for bio-succinic routes. Single-source vulnerability concentrates among coastal Chinese producers serving pan-Asian unsaturated polyester resin demand. Distribution runs through bulk tanker and railcar arrangements for integrated polymer facilities, with drum and tote formats serving specialty coatings formulators in Northern Italy and the US Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized reactor engineering talent for maleic anhydride oxidation chemistry is exiting Western chemical engineering programs faster than replacement, constraining capacity expansion and process safety management across North American and European facilities.
For Market Incumbents: Harden process safety expertise retention through targeted compensation structures and knowledge-capture programs before specialized reactor engineering talent fully departs Western training pipelines. Deepen backward integration into captive n-butane or bio-based feedstock positions to insulate margin structures from benzene volatility and MEE enforcement cycles. Prioritize ICH Q7 certification maintenance for pharmaceutical-grade succinic anhydride supply to defend against emerging Indian producers qualifying under CDSCO accelerated pathways. For New Entrants and Emerging Players: Pharmaceutical-grade succinic anhydride supply to domestic Indian generic drug manufacturers represents the most penetrable entry point given CDSCO's streamlined API approval processes and concentrated demand growth in Gujarat and Maharashtra. Technical-grade maleic anhydride for construction composite applications in Vietnam offers secondary white-space access under national infrastructure spending programs. Establish direct B2B marketplace presence to bypass traditional distributor markups and compress procurement cycles for mid-volume coatings formulators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade anhydride producers with locked FDA DMF positions and multi-year supply agreements to generic drug manufacturers. Long-term viability over the coming decade rests on feedstock flexibility and regulatory compliance infrastructure rather than scale alone. Target acquisition archetypes include mid-cap specialists with ICH Q7 certification and demonstrated mass-balance accounting capabilities for EU Green Deal chemistry mandates. Monitor MEE enforcement intensity in China's coastal provinces as the critical inflection signal for regional supply availability and import dependency ratios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Feedstock | BASF's Ludwigshafen naphtha-to-derivatives complex demonstrates cost leadership through integrated supply control. |
| Green Manufacturing Transition | EU Chemicals Strategy for Sustainability creates preferential market access for bio-based anhydride producers with mass-balance certification. |
| Long-term Supply Agreement | Automotive OEMs in Toyota City and Yokohama now mandate ISO 14001 certification and carbon footprint disclosures from anhydride suppliers. |
| Capacity Expansion in India | National Infrastructure Pipeline spending redirects procurement toward domestic chemical intermediates for corrosion-resistant construction composites. |
| Joint Venture for Process Technology | Catalytic partial oxidation with vanadium-phosphorus oxide catalysts is rendering obsolete fixed-bed benzene oxidation routes for maleic anhydride production. |
Methodological Framework
A spread of perspectives from plant operations managers, downstream OEM procurement leads, distribution channel partners, and technical R&D directors converged on the working assumptions for capacity utilization and feedstock cost transmission. Primary field engagement combined structured interviews with secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE enforcement disclosure records. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated to constrain estimate variance.
Demand-supply-balance dynamics across the analysis window were modeled through segmentation by product grade tier, end-use industry concentration, packaging format preference, and regional production hub characteristics. CAGRs were derived from slope analysis of normalized historical trajectories and forward-looking capacity announcement pipelines. Forecast inputs incorporated benzene futures curve structures, MEE enforcement probability assessments, and CDSCO approval velocity indicators for pharmaceutical-grade supply.
Practitioners should monitor MEE enforcement intensity, REACH authorization timeline shifts, and bio-succinic acid cost-parity milestones for early signals of forecast revision necessity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Pinoxaden Market
Chemicals
Mercury (I) Sulphate Market
Chemicals
Calcium Carbide Market
Chemicals
Global Bleaching Agents Market
Chemicals
Sodium Tripolyphosphate (STPP) Market
Chemicals
Valeronitrile Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
Ferric Phosphate Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
Trichloroisocyanuric Acid Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Global Oxo Alcohols Market
Chemicals
China Inorganic Iodide Market
Chemicals
Aluminum Phosphide Market
Chemicals
Ruthenium Tetroxide Market