
 North America Rooftop Solar Market | 2026-2036
North America Rooftop Solar Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rooftop Solar Market Analytics
Aftermarket service revenue is narrowing as module prices fall and installation margins compress across the value chain. Tesla sustains vertical integration from cell production through retail software, controlling customer acquisition costs in key US metros. Sunrun anchors its position through lease and power-purchase-agreement financing, dominating residential third-party ownership. Hanwha Qcells leverages domestic manufacturing scale in Georgia, positioning against import tariff exposure.
North America rooftop solar encompasses photovoltaic systems mounted on building structures, typically employing silicon cells with conversion efficiencies between 19% and 22% for commercial modules, generating electricity for on-site consumption or grid export. Monocrystalline panels command the premium product tier due to higher efficiency density, while bifacial technology captures reflected irradiance and expands output per square meter in commercial applications. Residential installation type leads volume but commercial and industrial segments concentrate larger average project sizes and faster payback periods in high-rate utility territories.
The US Federal Energy Regulatory Commission and state public utility commissions shape interconnection rules and net metering compensation, directly influencing project economics across jurisdictions. Canada's provincial regulators and the US EPA renewable energy guidelines establish environmental compliance benchmarks for equipment sourcing and end-of-life recycling. Stakeholders must monitor evolving tariff structures and interconnection queue reforms as these policy levers determine regional deployment viability more than module cost curves alone.
Market Dynamics
The US Inflation Reduction Act's investment tax credit extension is compressing project payback periods and redrawing competitive economics across state markets. Module cost deflation has shifted margin pressure downstream to installation and soft costs.
Growth Catalysts
- California net metering reforms:The state's NEM 3.0 framework accelerates battery attachment rates as homeowners seek to maximize self-consumption economics.
- Texas ERCOT grid volatility:Sporadic pricing spikes in the deregulated wholesale market drive commercial and industrial buyers toward on-site generation with storage.
- Bifacial module adoption:Reflected irradiance capture boosts commercial rooftop output per square meter, improving project returns in high-albedo environments.
Market Restraints
- Polysilicon supply concentration:Chinese ingot and wafer capacity controls upstream pricing, exposing North American installers to input cost volatility and tariff uncertainty.
- Interconnection queue delays:FERC Order 2023 reforms face implementation friction at state utility commissions, stretching project timelines in high-growth territories.
- Roof structural limitations:Aging commercial building stock in the US Northeast requires costly reinforcement before panel installation, constraining addressable inventory.
Strategic Opportunities
- Florida utility rate escalation:Investor-owned utility rate cases are compressing solar payback periods below six years in the Sunshine State's residential segment.
- Virtual power plant aggregation:Behind-the-meter battery fleets are creating grid services revenue streams that decouple installer economics from net metering alone.
- Community solar carve-outs:State-level mandates in Illinois and New York are opening rooftop-adjacent subscription models for renters and shaded properties.
Industry Challenges
- Licensed electrician scarcity:Residential installation growth is outpacing certified workforce supply in California, Texas, and Florida, extending project backlogs.
- Permitting fragmentation:Municipal AHJ variance in fire code interpretations and setback requirements forces customization that erodes standardized installation margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rooftop Solar Market |
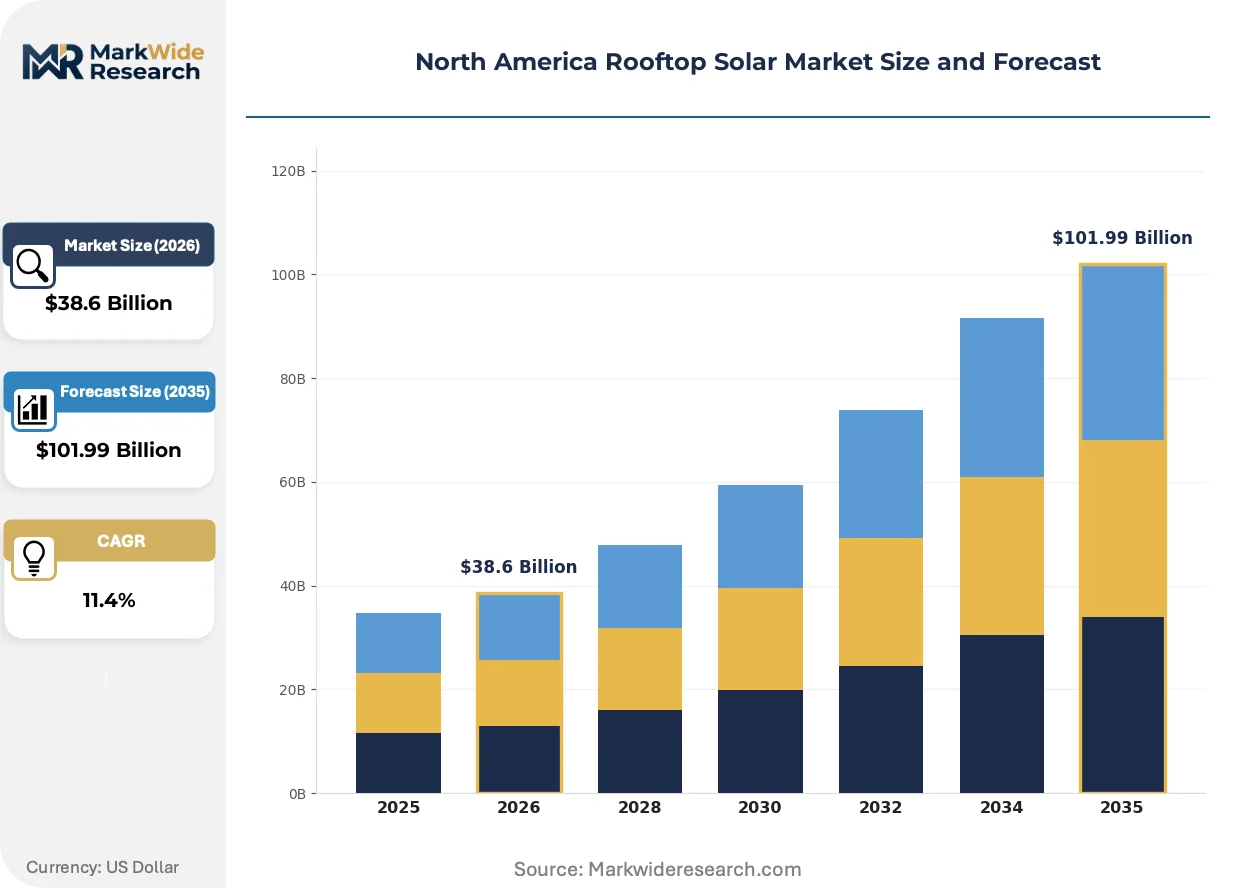
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin-Film Installation Type: Residential, Commercial, Industrial, Community Technology: Grid-Tied, Off-Grid, Hybrid, Integrated End User: Homeowners, Businesses, Non-Profits, Educational Institutions |
| Companies Covered | First Solar, Hanwha Qcells, Sunrun, Tesla, SunPower Corporation, Silfab Solar, Canadian Solar, GAF Energy, Mission Solar, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rooftop Solar Market Evolving Landscape
Module efficiency gains and software-defined energy management are converging to transform rooftop solar from a commodity hardware sale into a financed energy service. This shift is compressing traditional installer business models while elevating platform players.
N-type TOPCon cell architecture is rendering obsolete older p-type PERC modules in premium residential applications. High-income homeowners in California and Texas are specifying 22%-plus efficiency panels despite 15-20% cost premiums. The technology is rendering obsolete the historical trade-off between system size and roof area constraints, shrinking payback calculations.
The US EPA's renewable energy guidelines and state-level environmental justice screening are tightening equipment sourcing disclosure requirements. Domestic content bonus credits under the IRA are steering procurement toward Georgia and Ohio manufacturing. Commercial developers in Illinois and New York are restructuring supply contracts to capture the 10% adder.
Third-party ownership is ceding ground to cash and loan purchases as financing costs reset higher. Sunrun and regional installers are responding with loan product innovation rather than lease retention. The shift is most visible in Texas, where property-assessed clean energy financing faces political headwinds and buyers favor direct ownership.
North America Rooftop Solar Market Segmentation
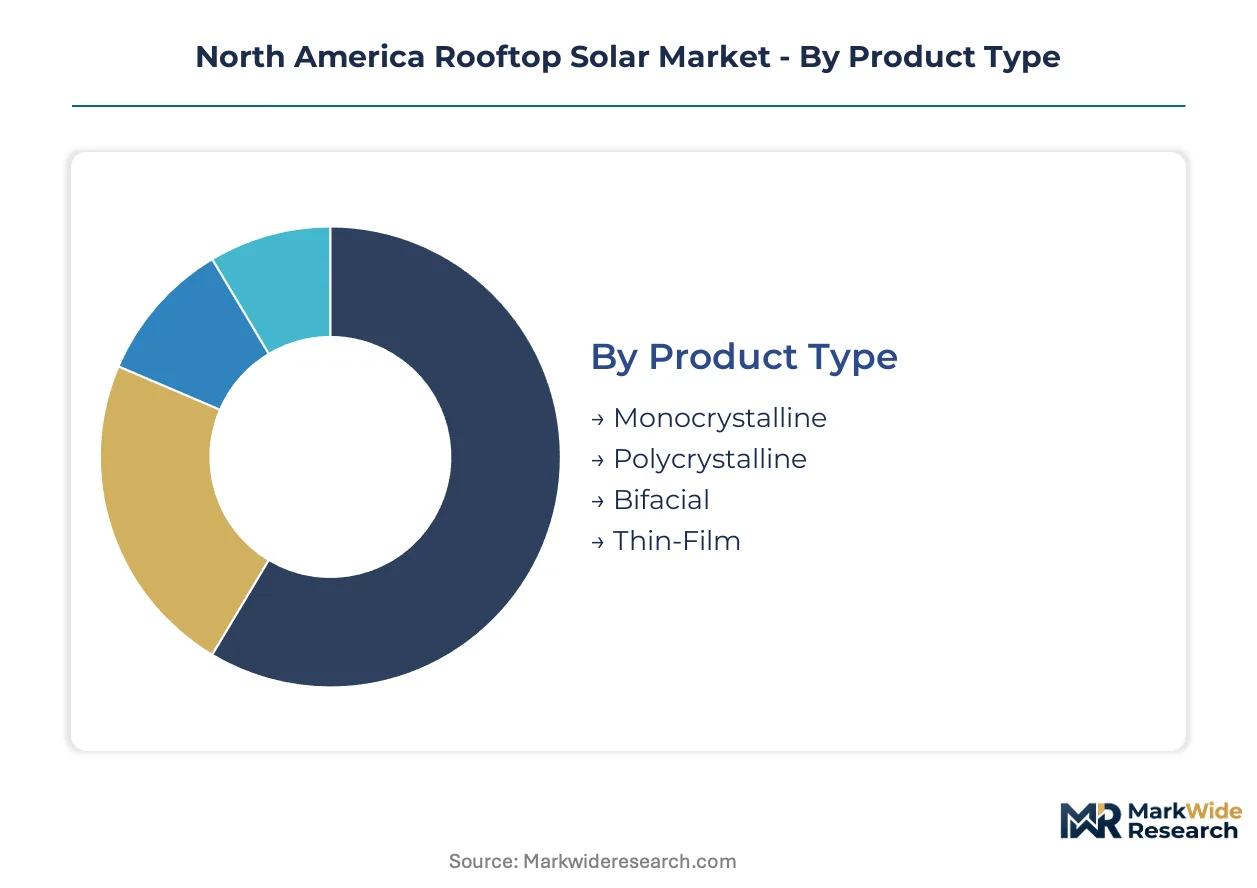
Segmentation in rooftop solar reveals distinct equipment, installation, and customer profiles that demand specialized service protocols and margin structures. Product efficiency tiers and ownership models create divergent aftermarket revenue streams across the value chain.
Product Type:
After-sales service intensity varies sharply across cell architectures, with premium segments requiring specialized diagnostics and warranty claim management.
- Monocrystalline:Single-crystal silicon construction delivers conversion efficiencies between 20% and 22% in commercial deployments. California and Texas homeowners with limited roof area specify these panels despite 15-20% cost premiums, compressing payback periods through higher output density.
- Bifacial:Dual-sided cell architecture captures reflected irradiance from rooftops and surrounding surfaces, boosting yield per square meter in high-albedo commercial environments. Texas ERCOT grid volatility accelerates adoption among industrial buyers seeking maximum generation per installed watt.
- Polycrystalline:Multi-crystal silicon offers lower manufacturing costs and acceptable efficiency for price-sensitive residential segments in Florida's utility-scale adjacent markets.
- Thin-Film:Cadmium telluride and CIGS technologies suit lightweight commercial retrofits where structural load limits constrain crystalline alternatives.
Monocrystalline holds the largest share; momentum sits with bifacial as commercial developers optimize land-constrained rooftops.
Installation Type:
Customer acquisition costs and project margins diverge substantially across ownership structures and scale thresholds.
- Residential:Single-family and small multi-family systems under 20 kW dominate unit volumes. Financing innovation through loan products and lease structures drives deployment in California, Texas, and Florida where utility rates and solar irradiance align favorably.
- Commercial:Office buildings, retail centers, and warehouses host 50 kW to 1 MW installations with faster payback periods in high-rate utility territories. Illinois and New York developers restructure supply contracts to capture IRA domestic content bonus credits.
- Industrial:Manufacturing facilities and distribution centers deploy megawatt-scale rooftop arrays with behind-the-meter storage to hedge ERCOT pricing spikes.
- Community:Shared subscription models open solar access to renters and shaded properties through state mandates in Illinois and New York.
Residential leads by unit count; commercial and industrial segments concentrate revenue and margin expansion.
Technology:
Grid interconnection architecture determines regulatory exposure and revenue stacking potential across jurisdictions.
- Grid-Tied:Systems export surplus generation to utility networks under net metering or feed-in tariffs. California's NEM 3.0 reforms are compressing export compensation rates and accelerating battery attachment for self-consumption optimization.
- Off-Grid:Standalone systems with storage serve remote properties and backup-critical facilities where interconnection queues stretch timelines.
- Hybrid:Grid-connected architecture with battery backup captures time-of-use arbitrage and resilience premiums in Texas's deregulated market.
- Integrated:Building-integrated photovoltaics replace conventional roofing materials, appealing to new construction and aesthetic-constrained historic districts.
Grid-tied dominates installed base; hybrid configurations are climbing the fastest as storage economics improve.
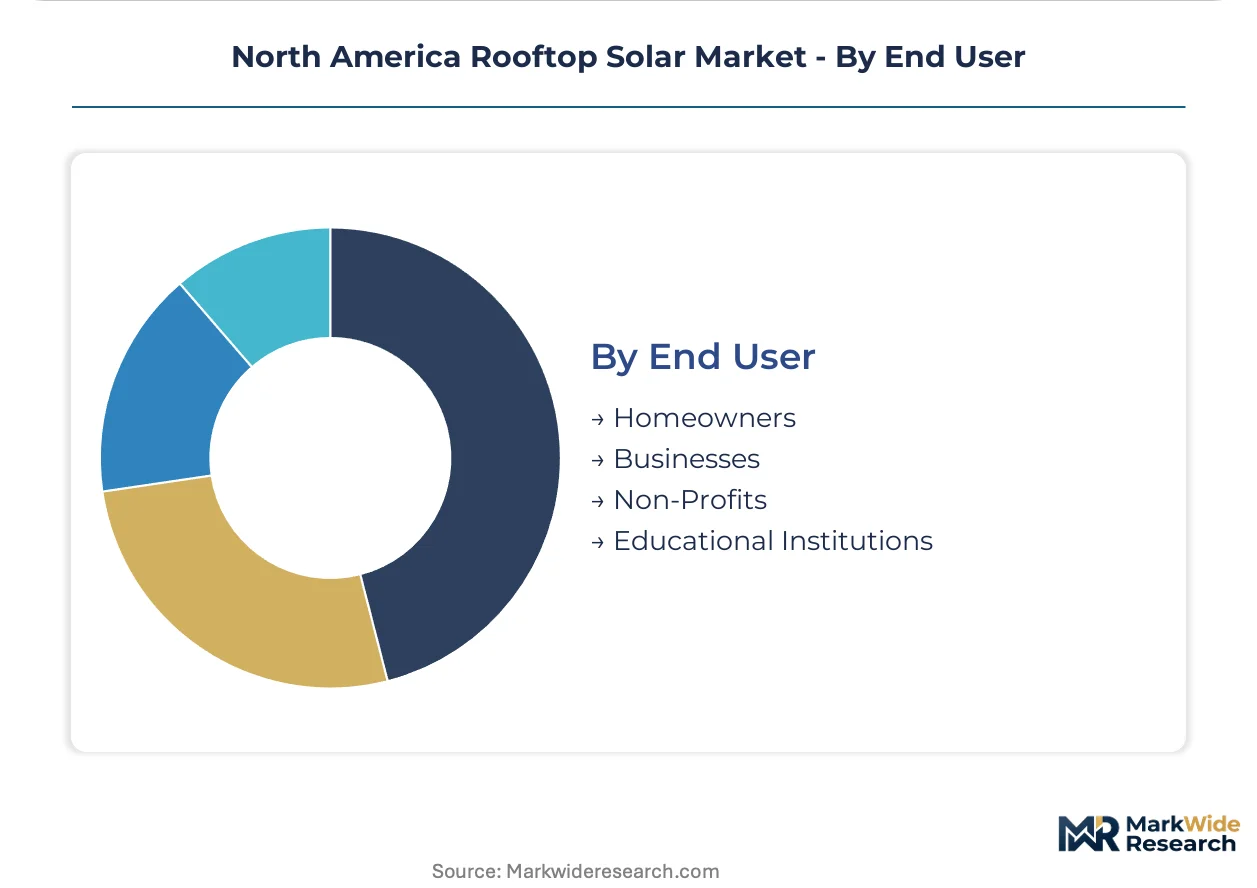
End User:
Procurement sophistication and financing access create distinct customer segments with divergent sales cycle lengths.
- Homeowners:Individual residential buyers drive volume through direct ownership, leases, and power purchase agreements. Third-party ownership is ceding ground to cash and loan purchases as financing costs reset higher.
- Businesses:Commercial enterprises prioritize payback certainty and brand alignment with sustainability commitments. Corporate procurement teams negotiate long-term contracts with performance guarantees.
- Non-Profits:Tax-exempt entities rely on third-party ownership structures or direct pay provisions under the IRA to monetize credits they cannot use directly.
- Educational Institutions:Schools and universities leverage roof portfolios across multiple buildings, aggregating procurement for scale and standardizing installation specifications.
Homeowners represent the steepest expansion trajectory; businesses anchor commercial segment value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers in California and Texas show the lowest price elasticity, absorbing 15-20% module premiums for high-efficiency systems, while Florida homeowners remain rate-sensitive and prioritize payback speed over technology tiers.
United States
California's NEM 3.0 export compensation cuts and Texas's ERCOT pricing volatility drive divergent storage attachment strategies. FERC Order 2023 interconnection reforms face state-level implementation friction. The Austin-San Antonio corridor hosts the fastest residential deployment velocity as municipal utilities streamline permitting.
Canada
Ontario's net metering cap restrictions and Alberta's deregulated retail market create contrasting project economics. Provincial regulators in British Columbia maintain feed-in tariff remnants for community solar. Toronto's commercial building stock drives bifacial adoption in high-albedo urban environments.
Mexico
Industrial buyers in Monterrey and Tijuana seek behind-the-meter generation to hedge CFE rate volatility. The country's national energy regulator has slowed distributed generation interconnection approvals. Baja California's high irradiance and manufacturing base concentrate commercial rooftop development.
California
Utility rate escalation above inflation and NEM 3.0 self-consumption optimization accelerate battery attachment rates. The California Public Utilities Commission structures time-of-use periods that favor west-facing panel configurations. Fresno and Bakersfield sub-markets lead Central Valley deployment among agricultural processing facilities.
Texas
ERCOT's scarcity pricing events drive commercial and industrial buyers toward hybrid systems with four-hour storage. The state's Public Utility Commission maintains retail choice frameworks that enable competitive solar-plus-storage offerings. Houston's petrochemical corridor and Dallas-Fort Worth logistics hubs concentrate megawatt-scale rooftop installations.
North America Rooftop Solar Market Competitive Landscape
Vertically integrated manufacturers and financing-platform installers split the market into divergent margin structures. The vendor base concentrates around three archetypes: domestic cell producers capturing IRA content credits, third-party ownership financiers monetizing tax equity, and integrated energy platforms bundling hardware with software. Capacity expansion in Georgia and Ohio manufacturing corridors and strategic partnerships for interconnection queue access define current competitive moves.
Within the domestic manufacturing tier, Hanwha Qcells and Silfab Solar occupy positions shaped by tariff exposure and content credit eligibility. Among financing-platform specialists, Sunrun exemplifies the lease and power-purchase-agreement model that dominated residential third-party ownership. Tesla sits within the integrated platform archetype, controlling customer acquisition through retail software and in-house cell production. These three anchors illustrate how IRA incentive structures are redrawing competitive boundaries between hardware producers and capital aggregators.
| Leading Market Players |
|---|
| First Solar |
| Hanwha Qcells |
| Sunrun |
| Tesla |
| SunPower Corporation |
| Silfab Solar |
| Canadian Solar |
| GAF Energy |
| Mission Solar |
| Others |
Value Network & Pricing Analysis
The Port of Los Angeles-Long Beach freight corridor anchors North American module distribution, with container cost volatility feeding directly into installer pricing power and downstream buyer segmentation across residential and commercial tiers.
Pricing Analysis
Aftermarket service contracts drive lifetime value capture as module prices compress installation margins. Three-tier pricing structure across premium monocrystalline, standard polycrystalline, and economy thin-film levels segments buyers by roof constraint severity and financing access. Cost compression in standard-tier hardware is intensifying because Chinese ingot oversupply feeds global spot markets. Florida homeowners exhibit highest price sensitivity, prioritizing payback speed over efficiency premiums, while California buyers absorb technology markups for space-constrained deployments.
Supply Chain Analysis
Contract manufacturing concentration sits with Hanwha Qcells' Georgia fabs and Silfab Solar's Washington operations, supplemented by Canadian Solar's Ontario assembly. Polysilicon sourcing draws from Chinese ingot capacity, Malaysian wafer processing, and domestic cell finishing. Single-source vulnerability concentrates in upstream metallurgical-grade silicon and silver paste for cell metallization. Distribution runs through regional EPC aggregators and direct-to-installer logistics networks, with FERC interconnection queue access emerging as a bottleneck arbitrage point.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America rooftop solar sits in early-cycle expansion as IRA incentive structures compress payback periods below seven years across high-utility-rate territories, accelerating penetration beyond early-adopter demographics.
For Market Incumbents: Harden domestic content qualification protocols to capture 10% IRA adders before bonus credit phase-down schedules take effect. Secure interconnection queue priority through strategic utility partnerships in ERCOT and CAISO territories. Deepen backward integration into Georgia and Ohio manufacturing corridors to offset tariff exposure on imported wafers.
For New Entrants and Emerging Players: Pursue virtual power plant aggregation software and battery fleet management as unclaimed white space, targeting Texas commercial-industrial buyers exposed to scarcity pricing. Illinois and New York community solar carve-outs offer the most penetrable entry segment. Lead with loan-product innovation rather than lease structures to match shifting ownership preferences.
For Investors and Strategic Acquirers: Regional EPC platforms with FERC interconnection expertise and certified electrician workforces represent the priority acquisition archetype. Long-term viability hinges on installer margin sustainability as hardware commoditization accelerates. Monitor NEM 3.0 adoption rates and battery attachment ratios as inflection indicators for platform valuation resets.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Scale-Up | Georgia and Ohio fabs capture IRA content credits and reduce tariff exposure. |
| Virtual Power Plant Aggregation | Behind-the-meter battery fleets create grid services revenue beyond net metering. |
| Interconnection Queue Partnership | FERC Order 2023 compliance positions developers for faster project timelines. |
| Loan Product Innovation | Direct ownership financing matches shifting residential buyer preferences. |
| Certified Workforce Development | Electrician training programs address California and Texas labor bottlenecks. |
Research Methodology
Cross-validation between EIA deployment databases and FERC interconnection filings anchors the qualitative findings from installer and utility interviews. Primary fieldwork engaged EPC contractors, utility planning officers, solar financing specialists, and state regulatory staff across California, Texas, and Florida. Secondary validation drew from EPA renewable energy guidelines, state public utility commission dockets, IRA implementation guidance, and project development tracking databases. Bottom-up capacity builds and top-down incentive absorption models were reconciled through iterative triangulation.
Calibration against historical deployment trajectories and policy implementation lags shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include cell architecture tier, installation type, ownership structure, grid interconnection architecture, and regional regulatory cluster. CAGRs were derived from slope-log regression on normalized deployment curves. Key inputs encompassed utility rate escalation schedules, NEM reform implementation timelines, and domestic content credit eligibility thresholds.
Sensitivities concentrate around interconnection queue reform velocity, tariff rate adjustments, and IRA credit phase-down triggers. Forecasts embed assumptions on financing cost normalization and battery cost curves that could shift materially. Quarterly review of FERC docket filings, state net metering rulemakings, and Georgia manufacturing capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Energy Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Global Solar Module for Electric Vehicle Market
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Rooftop Solar PV Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
United States Solar Energy Market
Solar Power Systems
Spain Rooftop Solar Market