
 Brazil Oil and Gas Upstream Market | 2026-2036
Brazil Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Oil and Gas Upstream Market Outlook
Offshore equipment procurement is fragmenting as pre-salt operators diversify supplier relationships beyond traditional integrated vendors. Petroleo Brasileiro SA anchors Brazil's upstream landscape through its dominant position in pre-salt block operations and floating production system deployments. Shell Plc competes aggressively in deepwater exploration, leveraging its global ultra-deepwater expertise to secure high-potential blocks in recent bidding rounds. Exxon Mobil Corporation differentiates through disciplined frontier exploration, targeting high-impact prospects in underexplored basins while sustaining a capital-light partnership model.
Brazil oil and gas upstream encompasses exploration, development, and production of crude oil and natural gas reservoirs, spanning water depths from shallow continental shelves to ultra-deepwater zones exceeding 2,000 meters where subsea tiebacks and FPSO vessels serve as primary production infrastructure. The sector's commercial purpose centers on supplying feedstock to domestic refineries, petrochemical complexes, and LNG export terminals while reducing Brazil's historical dependence on imported refined products. Deepwater technology leads capital allocation given the pre-salt carbonate reservoirs that yield high-flow-rate wells, though enhanced oil recovery methods gain traction as mature Campos Basin fields require pressure maintenance and gas injection to sustain output. Well services represent a concentrated margin pool as aging offshore infrastructure demands continuous intervention, workover, and subsea integrity management.
ANP, Brazil's national petroleum regulator, enforces local content requirements that mandate minimum percentages of Brazilian-sourced goods and services in exploration and production contracts, directly shaping supplier selection and domestic manufacturing demand. IBAMA, the federal environmental agency, imposes licensing conditions on offshore drilling campaigns and FPSO installations that extend project timelines and elevate compliance costs for operators. The Central Bank of Brazil monitors foreign exchange flows from petroleum exports and import obligations, influencing capital repatriation rules that affect international operators' financial planning. Stakeholders must monitor how evolving local content thresholds and environmental licensing backlogs reshape project economics and partnership structures.
Market Dynamics
ANP's escalating local content mandates are compressing procurement timelines for pre-salt operators while forcing rapid supplier base reconfiguration across the supply chain. This regulatory pressure is restructuring partnership models and capital deployment schedules throughout the upstream sector.
Growth Catalysts
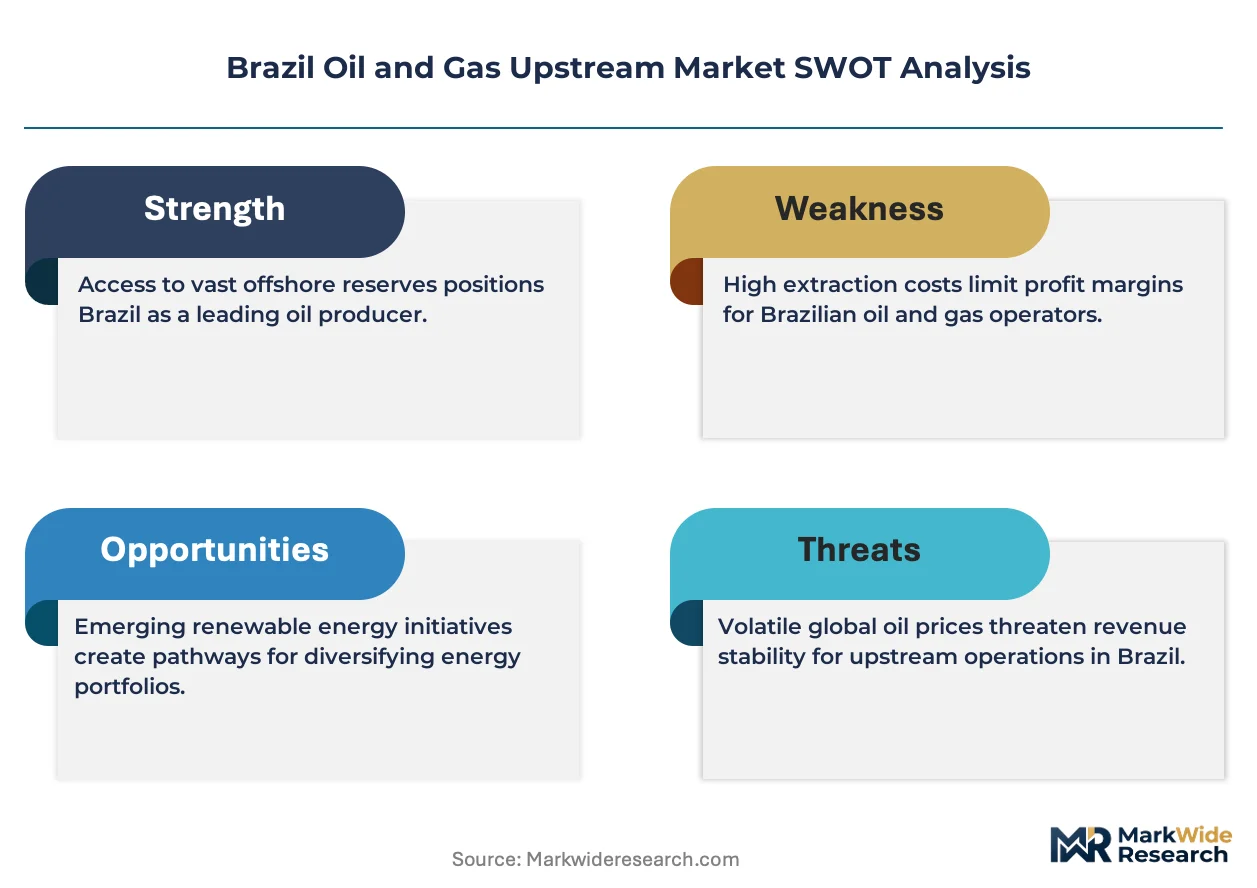
- Pre-salt carbonate reservoirs:High-flow-rate wells from these formations anchor production economics and sustain field development commitments. Operators prioritize these assets for capital allocation.
- Petrochemical feedstock demand:Southeast Brazil's integrated refining-petrochemical complexes require consistent domestic crude supply, locking in offtake agreements with upstream producers.
- ANP concession terms:Favorable fiscal frameworks for pre-salt bidding rounds accelerate investment decisions and project sanctioning timelines.
Market Restraints
- Deepwater rig supply concentration:Limited availability of sixth-generation drillships capable of 2,000-meter-plus operations creates queue bottlenecks and dayrate volatility.
- IBAMA environmental licensing backlogs:Extended approval timelines for FPSO installations and drilling campaigns stretch project schedules and elevate carrying costs.
- Steel and subsea component input costs:Specialized alloy requirements for sour service conditions expose operators to commodity price swings and long-lead procurement cycles.
Strategic Opportunities
- Campos Basin enhanced oil recovery:Mature fields requiring gas injection and pressure maintenance present service-intensive workover demand for specialized contractors.
- Subsea processing technology convergence:Integration of seabed separation with subsea compression unlocks stranded pre-salt reserves previously deemed uneconomic.
- Local manufacturing incentives:ANP's domestic content thresholds create captive demand for Brazilian-built FPSO hulls, turret systems, and subsea manifolds.
Industry Challenges
- Deepwater geoscience talent scarcity:Specialized expertise in pre-salt carbonate geology and ultra-deepwater geomechanics commands premium compensation and extends recruitment cycles.
- Legacy subsea infrastructure integrity:Aging flowlines and risers in the Campos Basin demand continuous inspection, repair, and replacement programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Oil and Gas Upstream Market |
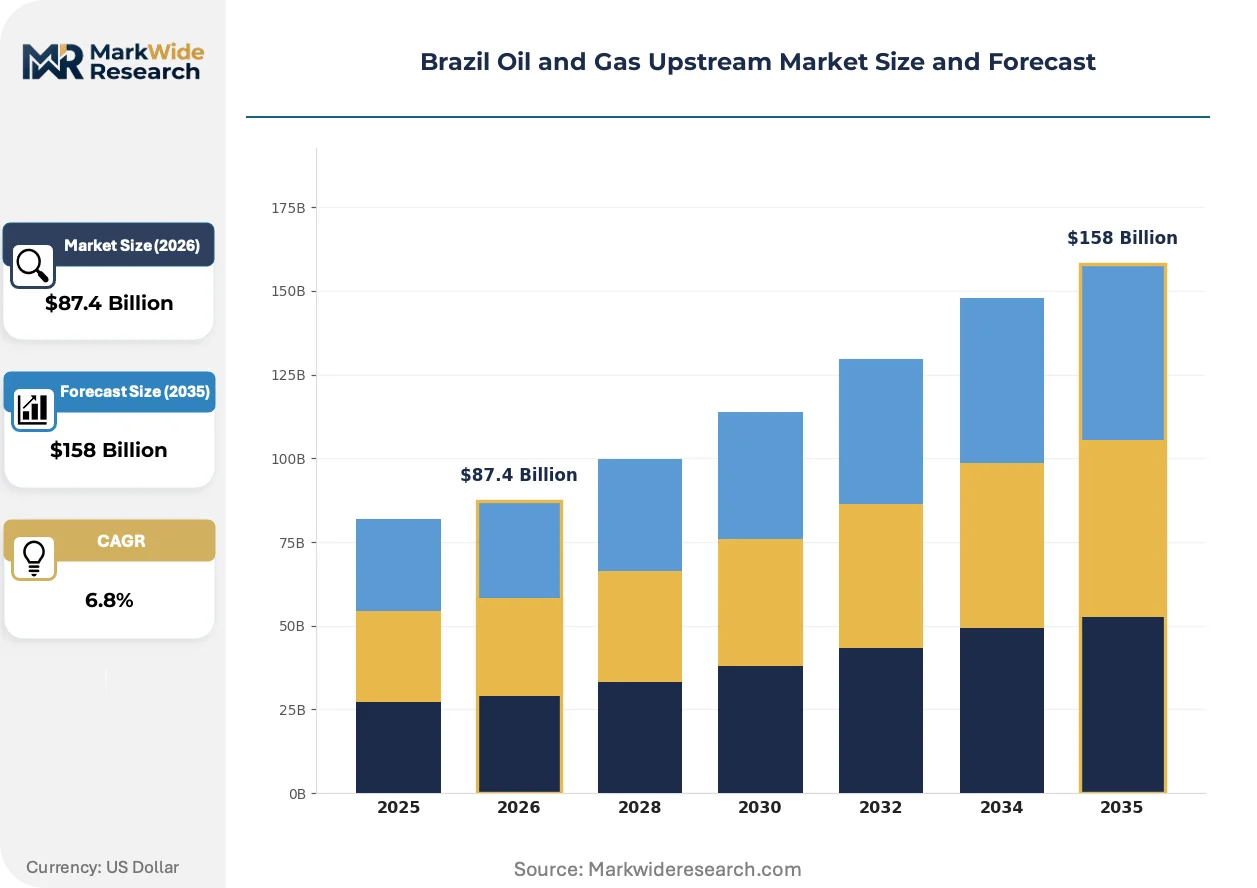
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling, Exploration, Production, Well Services Technology: Conventional, Unconventional, Enhanced Oil Recovery, Deepwater Production Method: Offshore, Onshore, Floating Production, Subsea Equipment Type: Rigs, Blowout Preventers, Pumps, Separators |
| Companies Covered | Petroleo Brasileiro SA, Exxon Mobil Corporation, Shell Plc, BP plc, TotalEnergies SE, Chevron Corporation, Equinor ASA, Enauta Participacoes SA, Murphy Oil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Oil and Gas Upstream Market Strategic Shifts
Digital reservoir characterization and modular production systems are compressing development cycles while enabling smaller operators to participate in pre-salt opportunities previously reserved for capital-heavy majors.
Electrified subsea processing is collapsing the surface facility footprint required for remote field developments. Independent operators and mid-tier players are adopting all-electric subsea trees and seabed boosting systems to reduce topside weight and eliminate hydraulic fluid complexity. This architecture is compressing capital intensity thresholds and opening marginal pre-salt accumulations to development.
ANP's revised local content calculation methodology tightens domestic sourcing requirements for exploration and production contracts. Operators must now document higher percentages of Brazilian-sourced goods and services, reshaping procurement strategies toward domestic fabricators and engineering firms. Pre-salt block concessionaires are responding by restructuring supplier relationships and accelerating local partnership negotiations.
Integrated service contracting is displacing discrete equipment procurement across deepwater developments. Operators now bundle drilling, completions, and subsea installation under single-source agreements with integrated service providers, consolidating vendor relationships and transferring execution risk. This pattern concentrates most visibly among independent operators lacking in-house project management capabilities.
Brazil Oil and Gas Upstream Market Segmentation
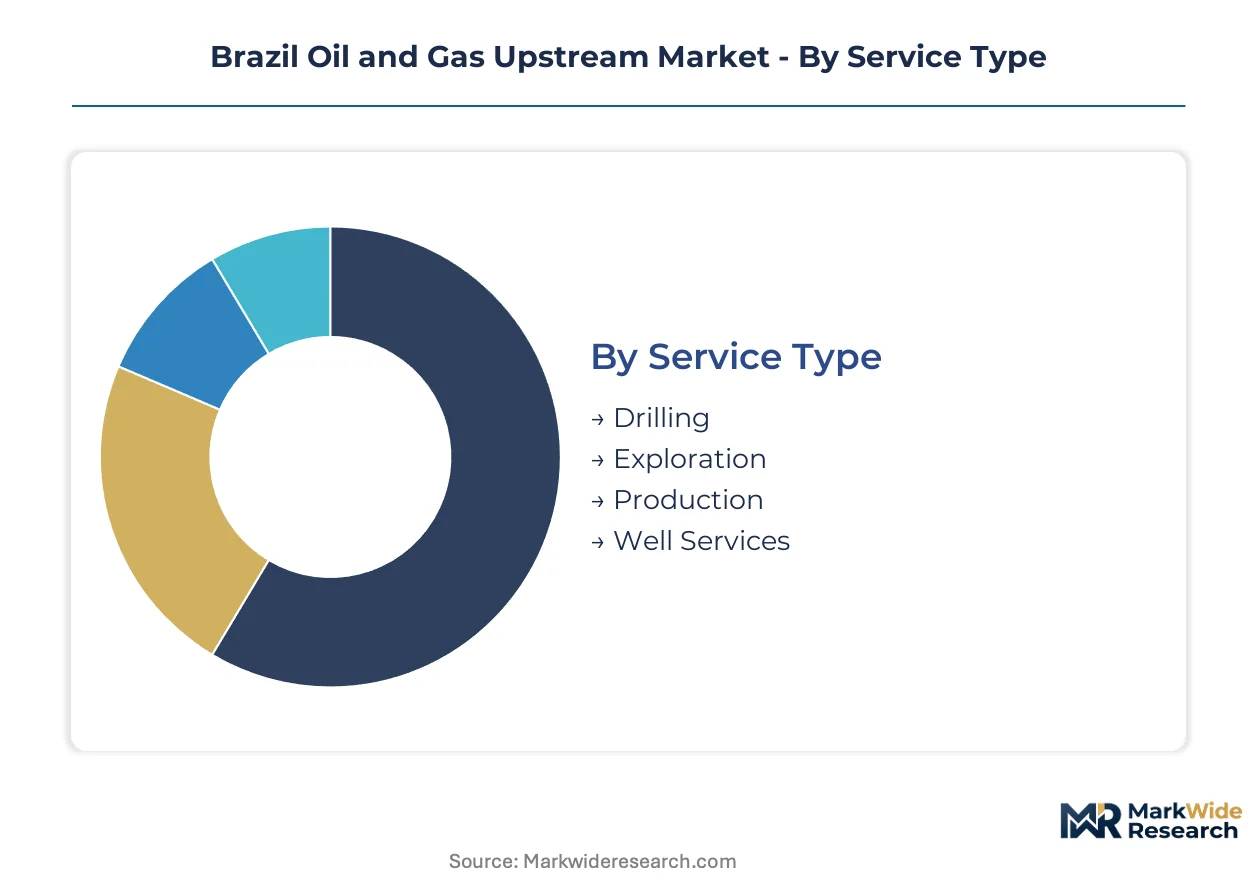
Segmentation in Brazil's upstream market reveals how capital allocation priorities diverge across technical capabilities, water depths, and reservoir characteristics. Each dimension carries distinct procurement patterns, regulatory exposure, and partnership structures that shape operator decision-making.
Service Type:
Mature production infrastructure dominates service demand while exploration activity accelerates in frontier basins.
- Drilling:Sixth-generation drillships capable of 2,000-meter-plus operations command premium dayrates as queue bottlenecks persist for pre-salt campaigns. Demand concentrates with international contractors serving ANP concession rounds in the Santos Basin where carbonate targets require specialized bit designs and managed pressure drilling systems.
- Production:Floating production system installation and topside hookup absorb the largest capital share as FPSO deployments multiply across pre-salt clusters. Southeast Brazil's integrated refining complexes anchor offtake agreements that sustain field development commitments through commodity cycles.
- Exploration:Seismic acquisition and wildcat drilling in underexplored equatorial margin basins.
- Well Services:Intervention, workover, and subsea integrity management for aging Campos Basin infrastructure.
Production retains volume leadership; drilling holds the steepest expansion curve.
Technology:
Cost tier separation distinguishes mature basin applications from frontier pre-salt developments requiring specialized engineering.
- Deepwater:Subsea tiebacks to FPSO vessels with seabed separation and boosting systems unlock stranded pre-salt reserves. Rio de Janeiro's offshore cluster concentrates deployment of all-electric subsea trees that eliminate hydraulic complexity and reduce topside weight.
- Enhanced Oil Recovery:Gas injection and pressure maintenance programs sustain output from mature Campos Basin fields. Thermal and chemical EOR methods gain traction where waterflooding efficiency declines in heavy oil reservoirs.
- Conventional:Standard platform drilling and fixed-leg production in shallow continental shelf areas.
- Unconventional:Tight sandstone and shale evaluation in onshore Paleozoic basins with limited commercial scale.
Deepwater commands the dominant investment share; enhanced oil recovery offers the most service-intensive expansion opportunity.
Production Method:
Application context separates offshore developments supplying domestic refineries from marginal onshore production.
- Offshore:Fixed platforms and compliant tower structures in Campos Basin water depths of 400-1,500 meters anchor legacy production. New developments favor FPSO-based solutions with disconnectable turret systems for hurricane-prone southeastern Atlantic conditions.
- Subsea:Seabed manifolds, flowlines, and risers connect satellite wells to centralized processing facilities. Local content mandates from ANP drive procurement toward Brazilian fabricators for subsea production system components.
- Floating Production:Spread-moored and turret-moored FPSO vessels with storage capacity exceeding 1.6 million barrels.
- Onshore:Mature fields in Reconcavo and Potiguar basins with declining output profiles.
Offshore retains volume leadership; subsea infrastructure holds the steepest expansion curve.
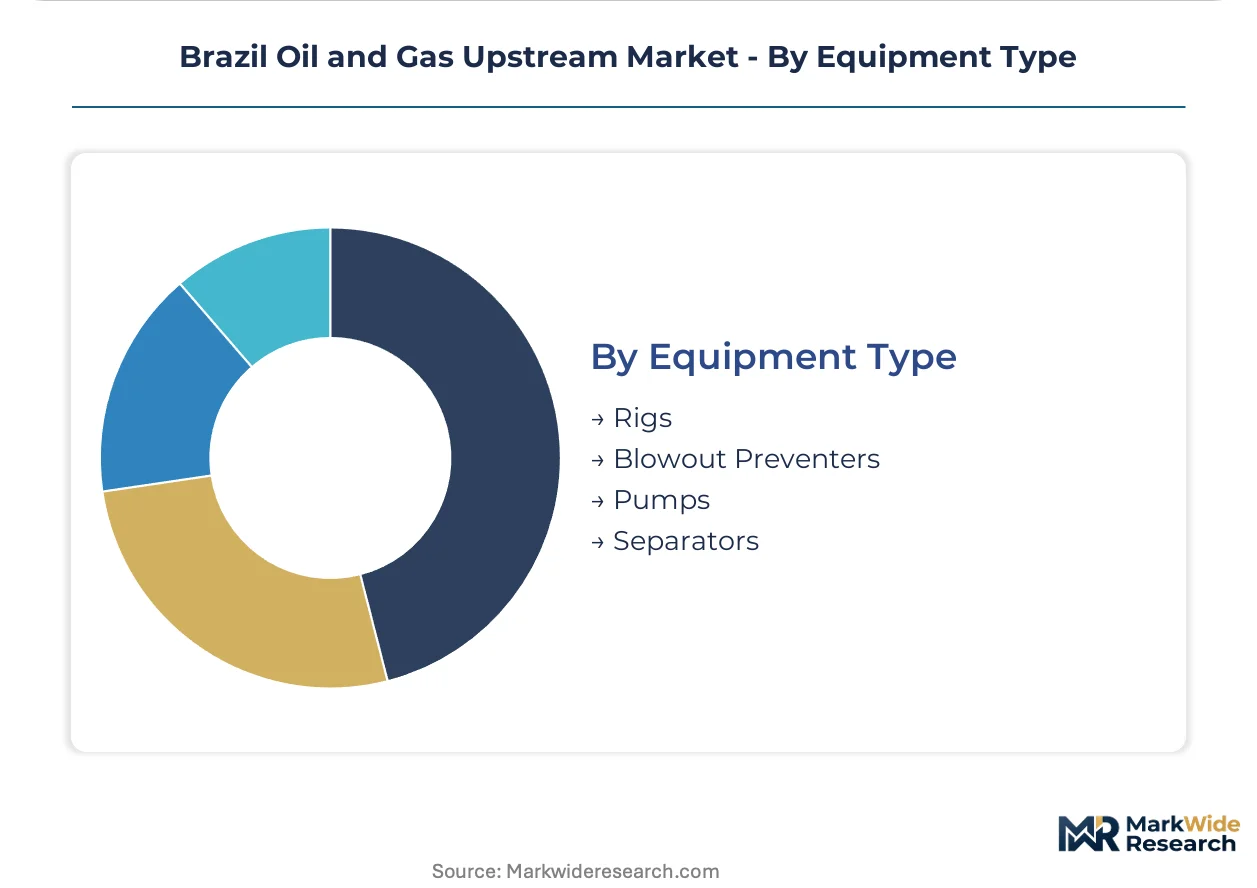
Equipment Type:
Supply concentration shapes procurement timelines and local content compliance strategies across hardware categories.
- Rigs:Ultra-deepwater drillships and semisubmersibles with dynamic positioning and dual-activity derricks. ANP's concession terms require rapid deployment commitments that strain available fleet capacity.
- Blowout Preventers:Subsea stack systems rated for 15,000 psi working pressure with shear ram capability for high-pressure pre-salt conditions. Specialized alloy requirements for sour service expose operators to extended manufacturing lead times.
- Pumps:Subsea multiphase and boosting systems for long-distance tieback developments.
- Separators:Slug catchers and production separators for FPSO topside processing modules.
Rigs retain volume leadership; blowout preventers face the steepest demand expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pre-salt production economics in Brazil's Santos Basin command premium valuations against mature North Sea assets, creating a regional arbitrage that attracts capital from European majors seeking reserve replacement. This pricing-power asymmetry reshapes portfolio allocation across Atlantic basin upstream strategies.
São Paulo
Petrochemical complexes in Cubatão and Guarulhos anchor feedstock demand for domestic crude, locking in offtake volumes from pre-salt clusters. ANP's local content mandates require operators to source subsea components from certified Brazilian fabricators, compressing procurement timelines. The Santos Basin pre-salt province, accessible from São Paulo-state logistics hubs, concentrates FPSO integration yards and subsea equipment staging facilities.
Rio de Janeiro
Deepwater production clusters off the Campos and Santos basins drive service demand for drilling, completion, and subsea installation. IBAMA environmental licensing conditions for offshore campaigns extend project timelines, elevating compliance costs for operators. The metropolitan area hosts engineering centers for integrated service contractors and the national petroleum regulator's headquarters, concentrating technical expertise and regulatory interface functions.
Minas Gerais
Onshore mature fields in the Reconcavo Basin require continuous well intervention and artificial lift services to sustain declining output. State-level industrial incentives support manufacturing of pumps, valves, and production equipment for upstream applications. Belo Horizonte's machinery sector supplies pressure control equipment and wellhead assemblies to offshore operators under ANP domestic content frameworks.
Rio Grande do Sul
Shallow-water production from the Pelotas Basin and onshore tight gas evaluation in Paleozoic formations attract niche exploration investment. Port facilities at Rio Grande support supply base operations for southern offshore concessions. Local engineering firms specialize in marginal field redevelopment and enhanced recovery methods for mature carbonate reservoirs.
Brazil Oil and Gas Upstream Market Competitive Environment
National champions and international majors split the market between reserve access and technology transfer priorities. State-affiliated operators anchor pre-salt development through carried interests and operator roles in strategic blocks. International integrated oil companies compete for non-operated partnerships and exploration acreage in frontier basins. Dominant competitive moves include portfolio high-grading toward pre-salt barrels and accelerated local partnership formation to satisfy ANP domestic content thresholds.
Within the national champion tier, Petroleo Brasileiro SA anchors Brazil's upstream landscape through its dominant position in pre-salt block operations. Shell Plc and Exxon Mobil Corporation represent competing international archetypes: the former leverages global ultra-deepwater expertise for high-potential block positions, while the latter pursues disciplined frontier exploration through capital-light partnership structures. These three entities exemplify the strategic divergence between state-reserve stewardship and international portfolio optimization that defines competitive positioning in Brazilian waters.
| Leading Market Players |
|---|
| Petroleo Brasileiro SA |
| Exxon Mobil Corporation |
| Shell Plc |
| BP plc |
| TotalEnergies SE |
| Chevron Corporation |
| Equinor ASA |
| Enauta Participacoes SA |
| Murphy Oil Corporation |
| Others |
Value Chain & Pricing Dynamics
Santos Basin port corridors from São Paulo to Rio de Janeiro concentrate logistics costs that amplify supply concentration effects and downstream price differentiation across deepwater equipment tiers.
Pricing Analysis
Configured-to-order subsea trees and FPSO hulls command substantial premiums over standardized shallow-water jackup packages. Project-based long-term offtake contracts dominate, with price differentiation resting on ANP certification tier and customization depth for sour service conditions. Cost compression in standard drilling packages is intensifying because of sixth-generation drillship queue bottlenecks. National oil companies show lowest price sensitivity; independent operators exhibit highest.
Supply Chain Analysis
Subsea equipment contract manufacturing concentrates with Singaporean and South Korean yards for hull integration, while Brazilian fabricators capture turret and manifold assembly under local content mandates. Specialized alloy forgings draw from German and Japanese foundries; hydraulic control systems feed from Norwegian engineering centers. Single-source vulnerability runs through high-pressure blowout preventer stack suppliers. Distribution runs through ANP-certified procurement channels to pre-salt block operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's upstream market requires substitution defense against renewable hydrogen and biofuel feedstocks that threaten long-term crude offtake commitments from Southeast petrochemical complexes.
For Market Incumbents: Build regulatory compliance moats through accelerated ANP local content certification and captive Brazilian fabrication partnerships. Deepen backward integration into subsea component manufacturing to offset steel alloy price volatility. Lock in decade-long FPSO charter agreements before independent operators capture marginal pre-salt accumulations. For New Entrants and Emerging Players: Mid-tier Campos Basin enhanced oil recovery service contracts represent the most penetrable entry point for specialized intervention contractors lacking pre-salt track records. Target gas injection and pressure maintenance programs where majors outsource workover demand. Pursue integrated service bundling as the go-to-market angle to displace discrete equipment vendors. For Investors and Strategic Acquirers: Subsea technology specialists with electrified tree capabilities and ANP certification history present the highest-conviction acquisition archetype. Long-term viability hinges on pre-salt reserve replacement rates and electrification capex cycles across the Santos Basin. Monitor IBAMA environmental licensing approval velocity as the inflection signal for project sanctioning momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Local Content Certification Acceleration | ANP compliance thresholds reshape procurement toward Brazilian fabricators and engineering partnerships. |
| Electrified Subsea Technology Deployment | All-electric trees eliminate hydraulic complexity and reduce FPSO topside weight for marginal fields. |
| Integrated Service Contracting Expansion | Single-source agreements transfer execution risk from independent operators lacking project management depth. |
| Campos Basin EOR Service Buildout | Gas injection and workover demand sustains contractor margins as mature fields require pressure maintenance. |
| Pre-salt Partnership Restructuring | Non-operated equity positions allow capital-light exposure to high-flow-rate carbonate reservoirs. |
Study Parameters
A standing panel of drilling contractors, FPSO leasing executives, ANP regulatory affairs specialists, and subsea equipment procurement managers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with engineering directors at integrated service companies and validation against ANP concession databases, IBAMA licensing records, and Central Bank petroleum export flow data. Bottom-up field development cost modeling triangulated against top-down macroeconomic scenarios.
Scenario-bracketing around oil price bands and local content threshold variations anchored the analytical framework across the projection horizon. Segmentation dimensions included water depth tier, reservoir type, production method, and operator scale category. CAGRs derived from unit economics modeling of pre-salt well productivity and FPSO deployment schedules. Forecast inputs incorporated rig dayrate trajectories and steel alloy price indices.
Practitioners should monitor ANP local content calculation revisions and IBAMA licensing backlog durations for early signals of project timeline compression. Forecasts reflect assumptions about concession term stability and environmental approval cadence. Quarterly review of pre-salt block relinquishment rates and international operator capital allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Norway Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
South America Offshore Seismic Survey Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
South Sudan Oil and Gas Upstream Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market