
 PV Solar Data Logger Market | 2026-2036
PV Solar Data Logger Market Size, Share, and Industry Trends Forecast 2026-2036
PV Solar Data Logger Market Insights
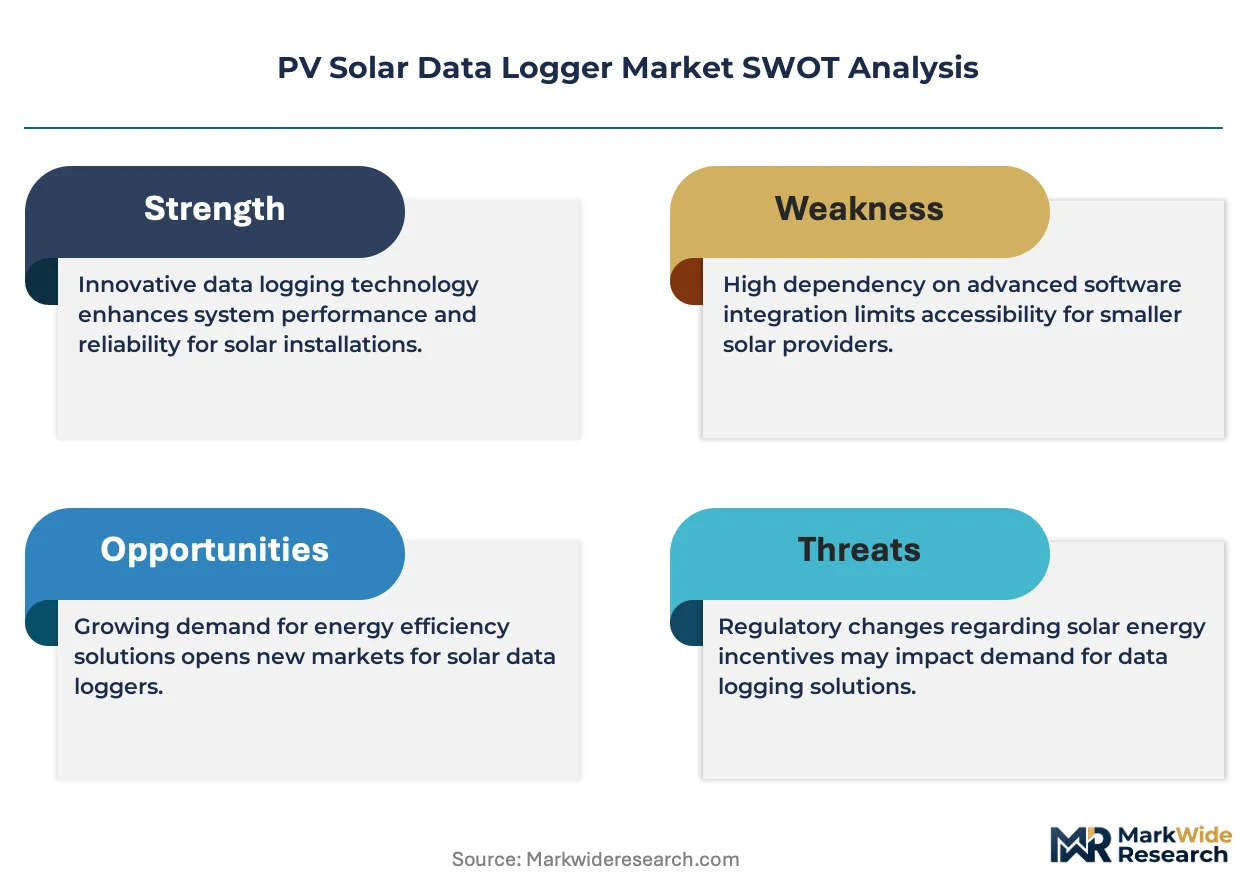
Asset-light leasing models for solar monitoring infrastructure are narrowing the capital barrier for mid-tier competitors. SMA Solar Technology leverages its European manufacturing footprint to sustain premium positioning in integrated logger-inverter systems. Huawei Technologies anchors its competitive stance through in-house silicon design and cloud platform integration. Growatt competes aggressively on cost-optimized standalone units for distributed residential markets.
A PV solar data logger is an electronic device that records irradiance, module temperature, DC voltage, and AC power output at intervals ranging from one second to fifteen minutes, enabling performance ratio analysis and fault detection in photovoltaic installations. Its primary commercial purpose is to maximize energy yield, validate warranty claims, and satisfy financing conditions for solar asset portfolios. Wireless product types are capturing disproportionate growth as retrofit demand surges across aging European and North American installations. Cloud-based technology segments concentrate margin pools through recurring software subscriptions layered over hardware sales. The utilities end-user category dominates volume while residential applications generate the fastest installation growth curves.
IEC 61724 standards, the EU Green Deal framework, and China's GB/T 19964 grid integration rules collectively mandate higher-resolution data logging and remote telemetry compliance for grid-connected solar assets. These requirements force hardware upgrades and create certification bottlenecks that favor established suppliers with testing laboratory relationships. Stakeholders must weigh interoperability investments against proprietary ecosystem lock-in as distributed energy resource management platforms consolidate vendor selection criteria.
Market Dynamics
Utility-scale solar operators now mandate sub-string level monitoring, forcing logger architectures toward higher channel density and edge computing capability as IEC 61724-1 Class A compliance becomes a financing prerequisite.
Growth Catalysts
- Grid Integration Mandates:China's GB/T 19964 rules require real-time telemetry for assets above 10 MW, compelling hardware refresh cycles across provincial solar fleets.
- Performance Warranty Enforcement:Module manufacturers now embed logger verification clauses, creating captive demand for independent monitoring hardware in utility portfolios.
- Edge AI Silicon:On-device inference chips are compressing fault detection latency from minutes to milliseconds, enabling predictive maintenance contracts.
Market Restraints
- Flash Memory Supply Concentration:Industrial-grade NAND sourcing clusters in South Korean and Taiwanese foundries, exposing logger OEMs to allocation volatility.
- IEC 61724-1 Certification Bottlenecks:Only three accredited laboratories worldwide can validate Class A accuracy, extending product launch timelines by 8-14 months.
- Cellular Module Cost Structure:LTE-M and NB-IoT radio units represent 18-22% of bill-of-materials, squeezing margin on sub-$200 hardware SKUs.
Strategic Opportunities
- India's DISCOM Reform Trajectory:State-level solar parks under KUSUM and green hydrogen mandates lack monitoring infrastructure, creating first-mover terrain for compliant hardware.
- Virtual Power Plant Convergence:Aggregation platforms need logger API standardization, rewarding vendors with open protocol stacks.
- EU Green Deal CSRD Alignment:Scope 3 emissions disclosure rules are forcing corporate offtakers to demand granular asset-level data, expanding enterprise rooftop demand.
Industry Challenges
- Firmware Security Certification:IEC 62443-3-3 industrial cybersecurity compliance requires dedicated engineering teams most mid-tier vendors lack.
- Legacy SCADA Integration:15-20 year-old control systems in European solar fleets use proprietary Modbus dialects, complicating retrofit deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PV Solar Data Logger Market |
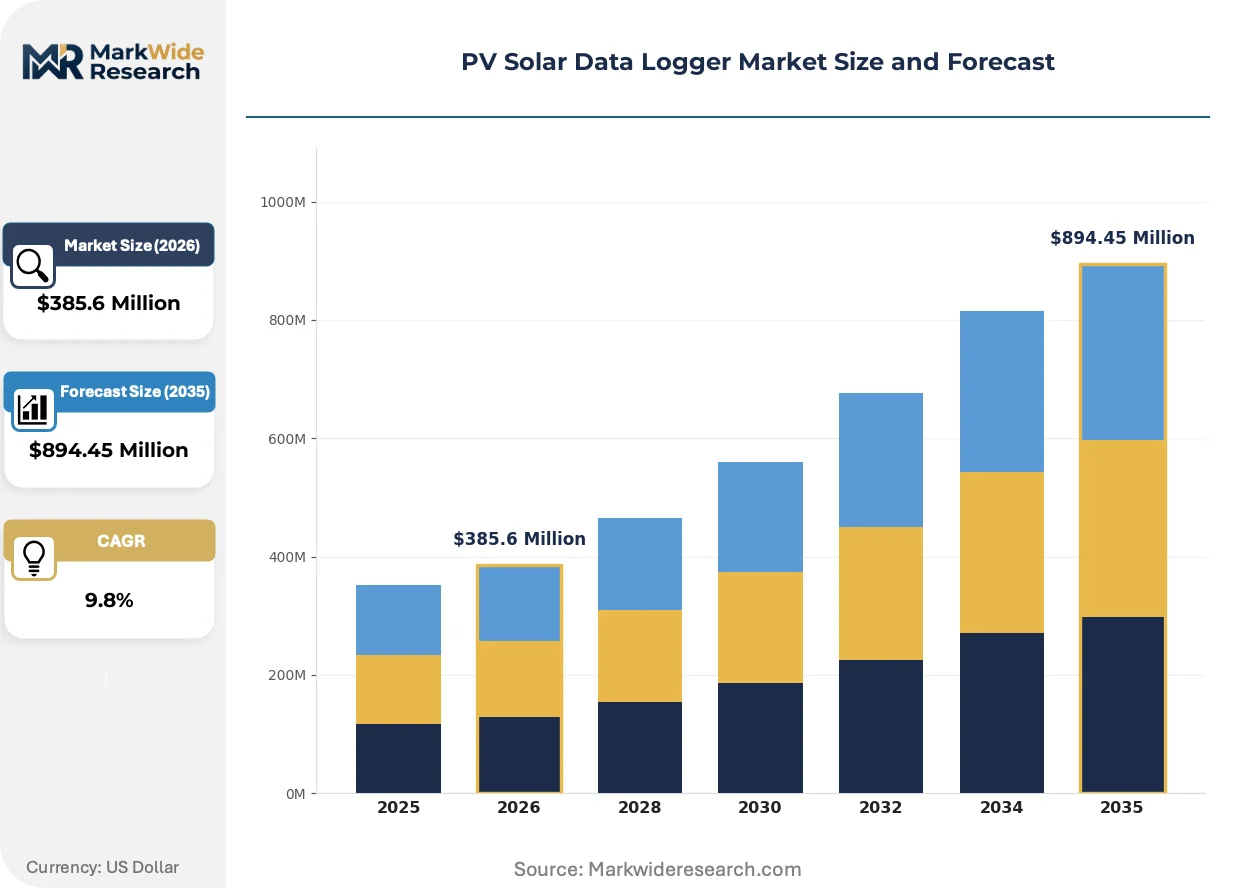
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $894.45 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated, Remote Monitoring, Wireless Technology: Analog, Digital, IoT, Cloud-Based End User: Residential, Commercial, Industrial, Utilities Installation: On-Site, Off-Grid, Roof-Mounted, Ground-Mounted |
| Companies Covered | SMA Solar Technology, SolarEdge Technologies, Huawei Technologies, Fronius, NRG Systems, Solar-Log, meteocontrol, Growatt, Sungrow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PV Solar Data Logger Market Trends and Innovations
Logger hardware is converging with inverter electronics and cloud analytics platforms, collapsing the traditional three-tier supply structure into integrated performance stacks. This integration is compressing standalone hardware margins while elevating software-recurring revenue pools.
Time-synchronized phasor measurement units adapted from grid transmission applications are digitizing fault location precision in utility-scale solar farms. Developers in Texas and California are deploying these units to isolate string-level degradation within seconds rather than hours. The technology is digitizing how asset operators negotiate warranty claims and schedule corrective maintenance.
The EU Green Deal's CSRD disclosure framework is mandating machine-readable sustainability data from solar asset owners. This regulatory pressure is forcing logger vendors to embed XBRL and ESG reporting APIs directly into firmware. European institutional investors now screen monitoring capability as a due diligence checkpoint before portfolio acquisition.
Asset operators are unbundling hardware procurement from software subscriptions, reversing the bundled sales model that dominated the 2015-2022 period. Large IPPs in Spain and Australia now issue separate RFPs for logger hardware, data platform licenses, and O&M analytics. This bifurcation is exposing standalone hardware vendors to pure-play software competitors and compressing equipment pricing transparency.
PV Solar Data Logger Market Segmentation
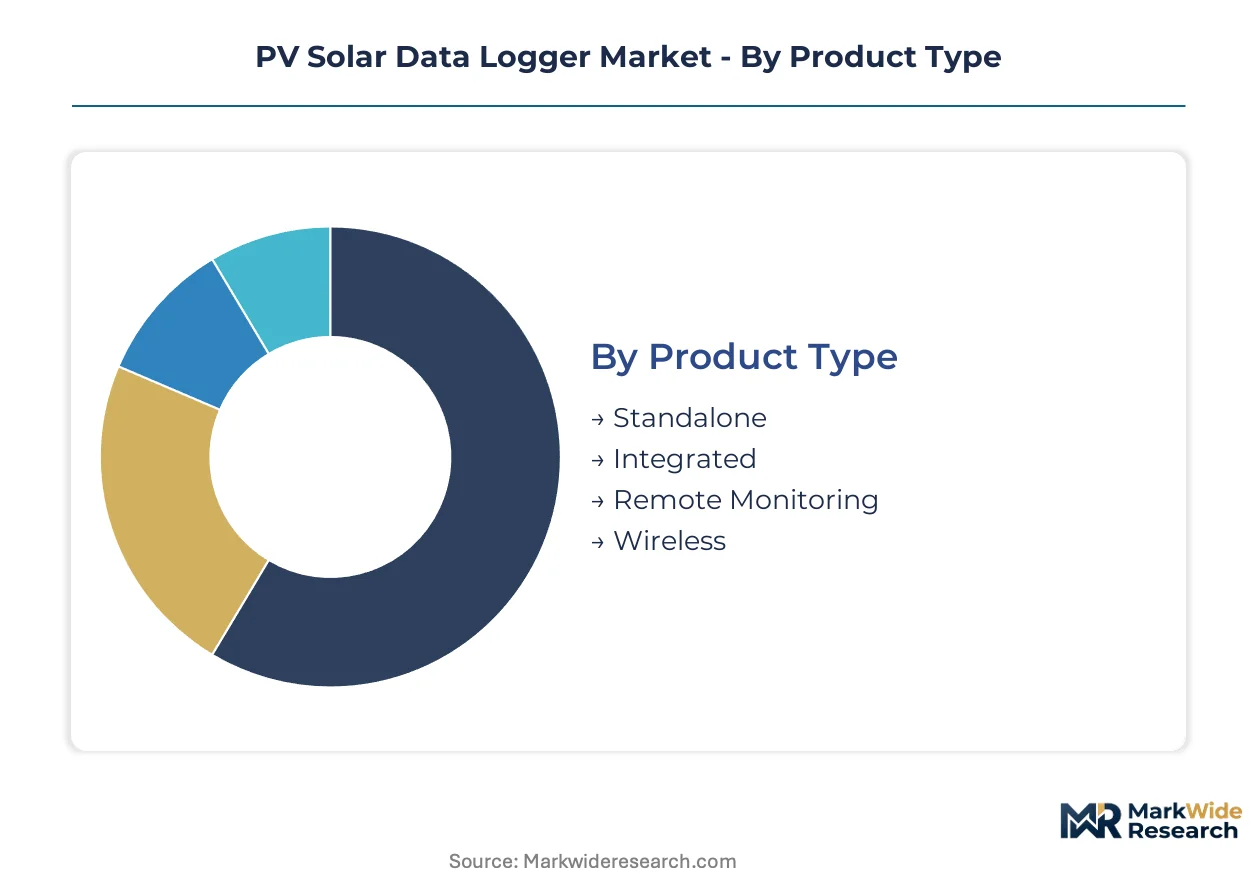
Segmentation in the PV solar data logger market reveals distinct service intensity profiles across hardware tiers. Wireless and cloud-based segments demand continuous firmware updates and subscription renewals, while standalone analog units require minimal post-sale engagement.
Product Type:
After-sales-service intensity varies sharply across product architectures, with integrated and wireless systems locking customers into multi-year platform commitments.
- Wireless:Radio-enabled loggers transmit irradiance, temperature, and power metrics via LTE-M or NB-IoT protocols without physical site visits. European retrofit markets in Germany and Spain concentrate demand as aging installations seek telemetry upgrades without rewiring. Recurring connectivity fees and cloud API access generate 40-60% lifetime revenue after initial hardware sale.
- Integrated:Logger electronics embedded within inverter housings share power supplies and cooling systems, reducing installation labor. Utility-scale developers in Texas and California favor these units for streamlined procurement and single-vendor warranty accountability. Firmware updates cascade automatically through inverter communication buses, lowering truck-roll costs.
- Standalone:Discrete hardware units with dedicated enclosures suit distributed residential deployments where inverter replacement cycles lag logger upgrade timelines.
- Remote Monitoring:Satellite or cellular backhaul variants serve off-grid installations beyond terrestrial network coverage.
By volume, Integrated leads. By growth pace, Wireless is ahead.
Technology:
Cost tier stratification separates premium cloud architectures from commoditized analog legacy stock.
- Cloud-Based:Edge-to-cloud pipelines stream sub-second data into machine learning platforms for predictive degradation modeling. Industrial and utility operators in China's Jiangsu and Zhejiang provinces mandate these systems under GB/T 19964 telemetry rules. Subscription pricing models capture recurring revenue but require dedicated customer success teams for dashboard onboarding.
- IoT:Low-power wide-area network chips enable battery-operated loggers in agricultural and remote industrial settings where grid power is unreliable. Indian solar pump installations under KUSUM scheme specifications drive volume, with hardware optimized for dusty environments and seasonal monsoon humidity.
- Digital:Microcontroller-based architectures with local SD card storage serve cost-sensitive commercial rooftops in Brazil and Mexico.
- Analog:Voltage-output sensor interfaces persist in 15-20 year-old European fleets awaiting full replacement cycles.
By margin contribution, Cloud-Based dominates. By installation base expansion, IoT is expanding most quickly.
End User:
Customer type determines procurement complexity, with utilities running centralized RFPs and residential buyers transacting through installer channels.
- Utilities:Central procurement teams specify IEC 61724-1 Class A accuracy and API interoperability for virtual power plant aggregation. State-backed solar parks in China's Qinghai and Gansu provinces represent concentrated volume, with single tenders exceeding 500 MW of monitored capacity. Long-term service agreements span 10-15 years, embedding logger vendors within asset ownership structures.
- Residential:Homeowner associations and net-metering participants in Australia's Queensland and Victoria states generate fastest installation growth. Installer-led sales favor plug-and-play wireless units with smartphone app visibility over technical specification depth.
- Commercial:Corporate offtakers under EU Green Deal CSRD disclosure rules demand granular asset-level data for Scope 3 emissions reporting.
- Industrial:Factory rooftop and carport installations prioritize Modbus TCP integration with existing building management systems.
By revenue concentration, Utilities leads. By growth pace, Residential is gaining share fastest.
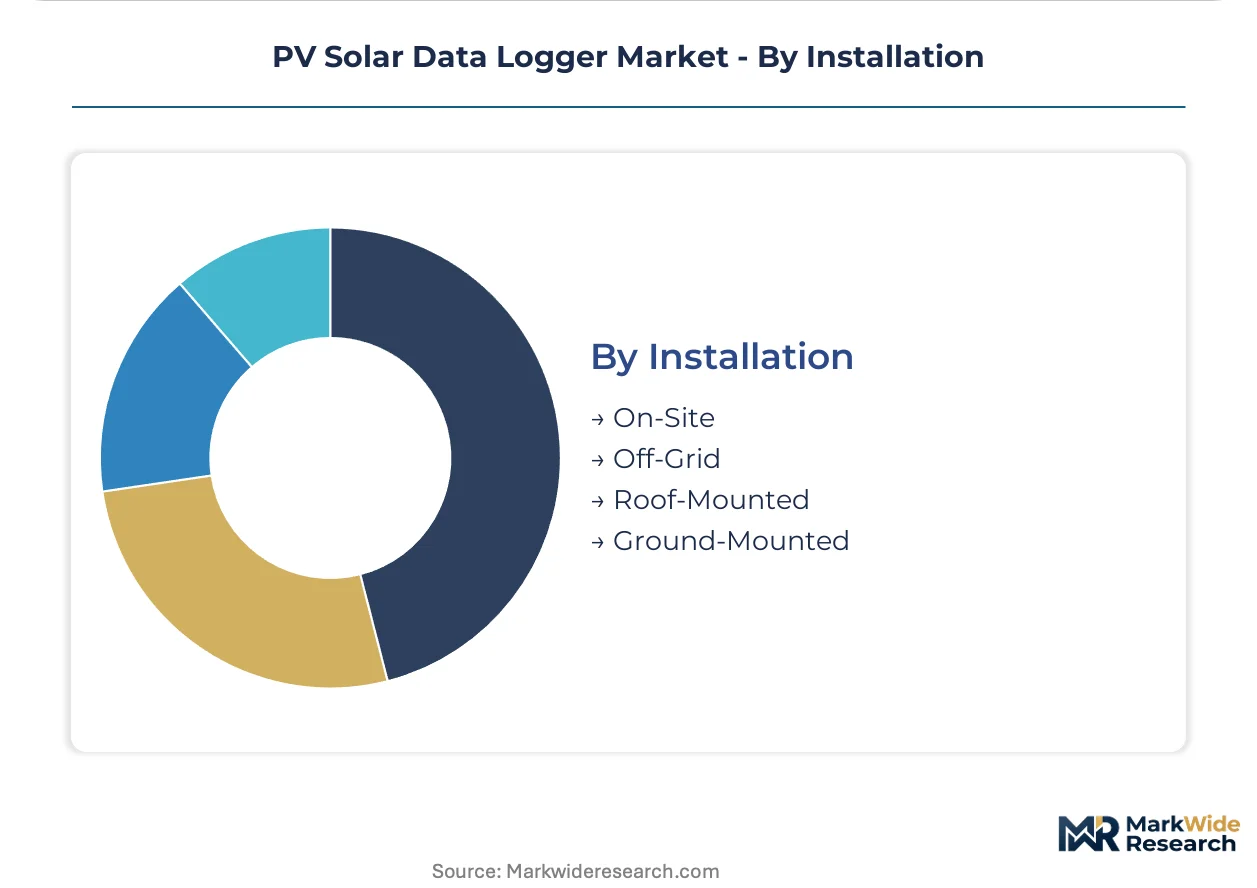
Installation:
Site configuration dictates environmental hardening requirements and communication infrastructure choices.
- Ground-Mounted:Large-scale trackers and fixed-tilt arrays in California's Mojave Desert and Nevada's Clark County expose loggers to extreme thermal cycling and dust ingress. IP67 enclosures and conformal-coated PCBs withstand 20-year operational lifespans. Trenching for fiber or power cabling is cost-effective at scale, favoring wired Ethernet backhaul over cellular.
- Roof-Mounted:Commercial and residential rooftops in Japan's Kanto region and South Korea's Gyeonggi-do province constrain hardware footprint and weight. Wireless transmission eliminates penetration risks, while rapid shutdown compliance adds electrical isolation complexity.
- On-Site:Grid-connected installations with permanent monitoring infrastructure dominate hardware revenue.
- Off-Grid:Battery-coupled systems in sub-Saharan Africa and Southeast Asian islands prioritize ultra-low power draw and satellite backhaul.
By deployment scale, Ground-Mounted leads. By retrofit opportunity, Roof-Mounted shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB/T 19964 grid integration rules and the EU Green Deal's CSRD disclosure framework are accelerating logger deployment across utility-scale solar fleets. National renewable targets in India and state-level mandates in the United States are creating parallel demand corridors for IEC 61724-compliant monitoring infrastructure.
China
Provincial solar parks in Qinghai and Gansu provinces drive concentrated procurement volumes, with single tenders exceeding 500 MW of monitored capacity. GB/T 19964 mandates real-time telemetry for assets above 10 MW, compelling hardware refresh cycles across state-backed renewable fleets. Jiangsu and Zhejiang industrial clusters host domestic manufacturing ecosystems serving both domestic deployment and export markets.
United States
Utility-scale developers in Texas and California deploy time-synchronized phasor measurement units to isolate string-level degradation within seconds. FERC interconnection standards and state renewable portfolio requirements in California and New York mandate granular performance visibility for grid-connected solar assets. Mojave Desert and Clark County installations expose loggers to extreme thermal cycling, driving demand for IP67-hardened enclosures.
Germany
Aging European installations in Bavaria and Baden-Württemberg generate retrofit demand for wireless telemetry upgrades without rewiring. EU Green Deal CSRD alignment forces corporate offtakers to demand granular asset-level data for Scope 3 emissions disclosure. SMA Solar Technology leverages its European manufacturing footprint to sustain premium positioning in integrated logger-inverter systems.
India
State-level solar parks under KUSUM and green hydrogen mandates lack monitoring infrastructure, creating first-mover terrain for compliant hardware. CEA grid integration rules and state DISCOM reform trajectories are tightening data logging requirements for assets above 5 MW. Agricultural solar pump installations in Gujarat and Rajasthan drive volume for battery-operated, dust-hardened IoT loggers.
Australia
Homeowner associations and net-metering participants in Queensland and Victoria generate the fastest installation growth curves for residential wireless units. Installer-led sales favor plug-and-play systems with smartphone app visibility over technical specification depth. Virtual power plant aggregation platforms are standardizing logger API requirements, rewarding vendors with open protocol stacks.
PV Solar Data Logger Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. European and Chinese manufacturers anchor the premium tier through integrated hardware-software stacks, while cost-optimized specialists capture distributed residential volumes. The vendor base clusters around inverter-integrated architectures, standalone wireless units, and cloud-native platform plays. Strategic moves concentrate on firmware security certification and interoperability investments against proprietary ecosystem lock-in.
Within the integrated systems tier, SMA Solar Technology and Huawei Technologies exemplify divergent geographic anchoring strategies. SMA leverages its European manufacturing footprint for premium positioning in utility-scale procurement channels. Huawei anchors competitive stance through in-house silicon design capabilities. Growatt occupies a position among cost-optimized standalone specialists targeting distributed residential markets through aggressive hardware pricing.
| Leading Market Players |
|---|
| SMA Solar Technology |
| SolarEdge Technologies |
| Huawei Technologies |
| Fronius |
| NRG Systems |
| Solar-Log |
| meteocontrol |
| Growatt |
| Sungrow |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure between Chinese silicon foundries and European assembly plants determines both pricing tier spreads and supply chain shape in the PV solar data logger market. Industrial-grade NAND flash sourcing clusters in South Korean and Taiwanese facilities, exposing logger OEMs to allocation volatility that compresses margins on sub-$200 hardware SKUs while elevating premium positioning for vertically integrated suppliers.
Pricing Analysis
IEC 61724-1 Class A certification creates the primary spread between premium integrated systems and cost-optimized standalone units. Three-tier pricing structure across premium, standard, and economy levels reflects accuracy grade, after-sales bundling, and geographic delivery cost. Cost compression in the standalone tier intensifies because cellular module costs represent 18-22% of bill-of-materials. Residential installers exhibit highest price sensitivity, while utility procurement teams prioritize certification depth over unit economics.
Supply Chain Analysis
Single-source vulnerability for industrial-grade NAND flash dominates supply chain risk assessment. Manufacturing concentrates in China, South Korea, and Taiwan, with assembly drawing from European and North American facilities. Raw material dependencies include silicon wafers, LTE-M cellular modules, and conformal coating chemistries. Distribution runs through EPC contractors and inverter OEMs for utility-scale volumes, while residential channels favor distributor networks and installer-direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PV solar data logger market is experiencing high-growth disruption as IEC 61724-1 Class A compliance becomes a financing prerequisite for utility-scale solar assets. Edge AI silicon integration and virtual power plant aggregation platforms are reshaping competitive positioning.
For Market Incumbents: Entrench firmware security certification capabilities ahead of IEC 62443-3-3 mandates. Deepen in-house silicon design to offset cellular module cost pressure. Prioritize API standardization investments to defend against pure-play software competitors unbundling hardware from analytics platforms. For New Entrants and Emerging Players: Build out open protocol stack offerings for Australia's virtual power plant aggregation platforms. Target India's DISCOM reform corridor where KUSUM scheme specifications lack compliant monitoring infrastructure. Pursue installer-channel partnerships in Queensland and Victoria residential markets. For Investors and Strategic Acquirers: EU Green Deal CSRD alignment reshapes the acquisition landscape by forcing corporate offtakers to demand granular asset-level data. Long-term viability favors vendors with cloud-native platform architecture and recurring subscription revenue pools. Watch for logger-inverter integration convergence as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Silicon Integration | On-device inference chips compress fault detection latency from minutes to milliseconds for predictive maintenance contracts. |
| IEC 61724-1 Class A Certification | Only three accredited laboratories worldwide validate accuracy, creating certification bottlenecks that favor established suppliers. |
| Cloud Platform Integration | Recurring software subscriptions layered over hardware sales concentrate margin pools in vendor ecosystems. |
| API Standardization Investment | Open protocol stacks reward vendors as virtual power plant aggregation platforms consolidate vendor selection criteria. |
| Wireless Telemetry Retrofit | LTE-M and NB-IoT protocols enable European and North American aging installation upgrades without rewiring. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings. Utility planning officers, IPP project developers, EPC contractors, and inverter OEM product managers provided operational data. Secondary sources include IEC standards documentation, FERC interconnection filings, EIA project databases, and CEA grid integration notifications. Bottom-up installation tracking and top-down renewable capacity forecasts were triangulated against vendor shipment disclosures.
Calibration against historical deployment patterns and technology substitution curves shaped the analytical framework. Segmentation dimensions span product architecture, technology tier, end-user category, and installation configuration. CAGRs were derived from fitted growth curves applied to country-level renewable targets and grid integration mandates. Forecast inputs incorporate NAND flash supply allocation cycles and cellular module cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native software entrants would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
Europe Solar Charging Station Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
Global Solar PV Balance of System Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Solar EVA Market