
 Global Industrial Lead Acid Battery Market | 2026-2036
Global Industrial Lead Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Lead Acid Battery Market Outlook
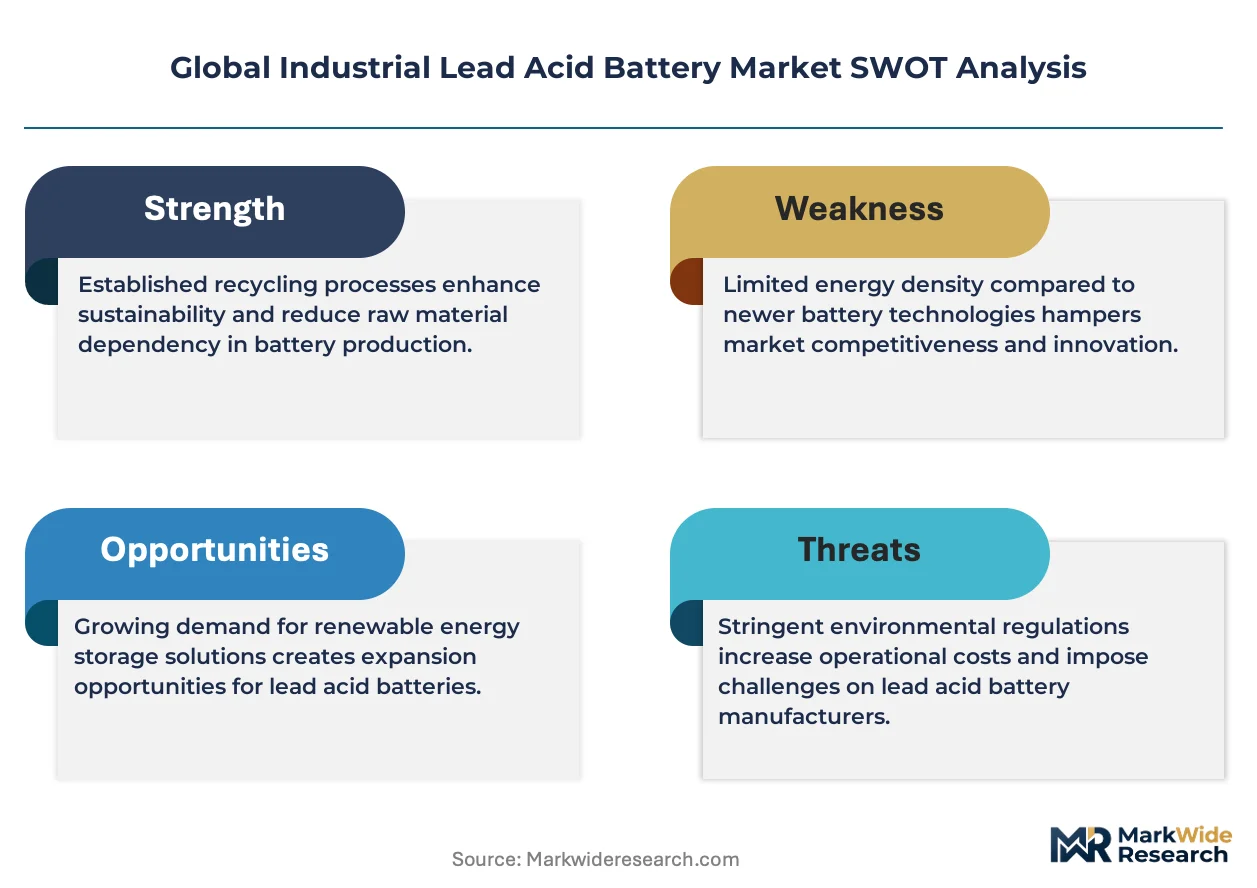
The EU Green Deal is restructuring procurement criteria across European industrial battery buyers, favoring suppliers with verified recycling chains. Exide Industries leverages its integrated smelter network to meet these traceability requirements. EnerSys competes through North American service infrastructure density. GS Yuasa anchors Asian supply relationships with forklift OEMs and submarine battery programs.
Industrial lead acid batteries are electrochemical storage devices using lead dioxide positive plates, sponge lead negative plates, and sulfuric acid electrolyte, engineered for deep-cycle durability and high-current discharge in temperatures from minus twenty to plus fifty degrees Celsius. Their primary purpose is to deliver reliable backup power and motive energy where grid stability is critical or electrified transport requires cost-effective traction. Flooded lead acid occupies the mature bulk segment in forklift and mining vehicle applications where maintenance access is routine. AGM lead acid captures margin pools in telecommunications and data center UPS installations where valve-regulated designs reduce ventilation infrastructure. Gel lead acid extends into renewable energy storage in off-grid solar configurations where temperature cycling tolerance justifies premium positioning.
The EPA enforces lead emissions standards at U.S. recycling facilities, shaping domestic smelter economics and secondary lead pricing. REACH and the EU Battery Regulation mandate carbon footprint disclosure and recycled content quotas, raising compliance costs for European market access. India's BIS certification and China's GB standards enforce divergent testing protocols that fragment product platform standardization. Stakeholders must monitor how divergent recycling mandates across the U.S., European Union, and China reshape cost structures and supplier qualification timelines.
Market Dynamics
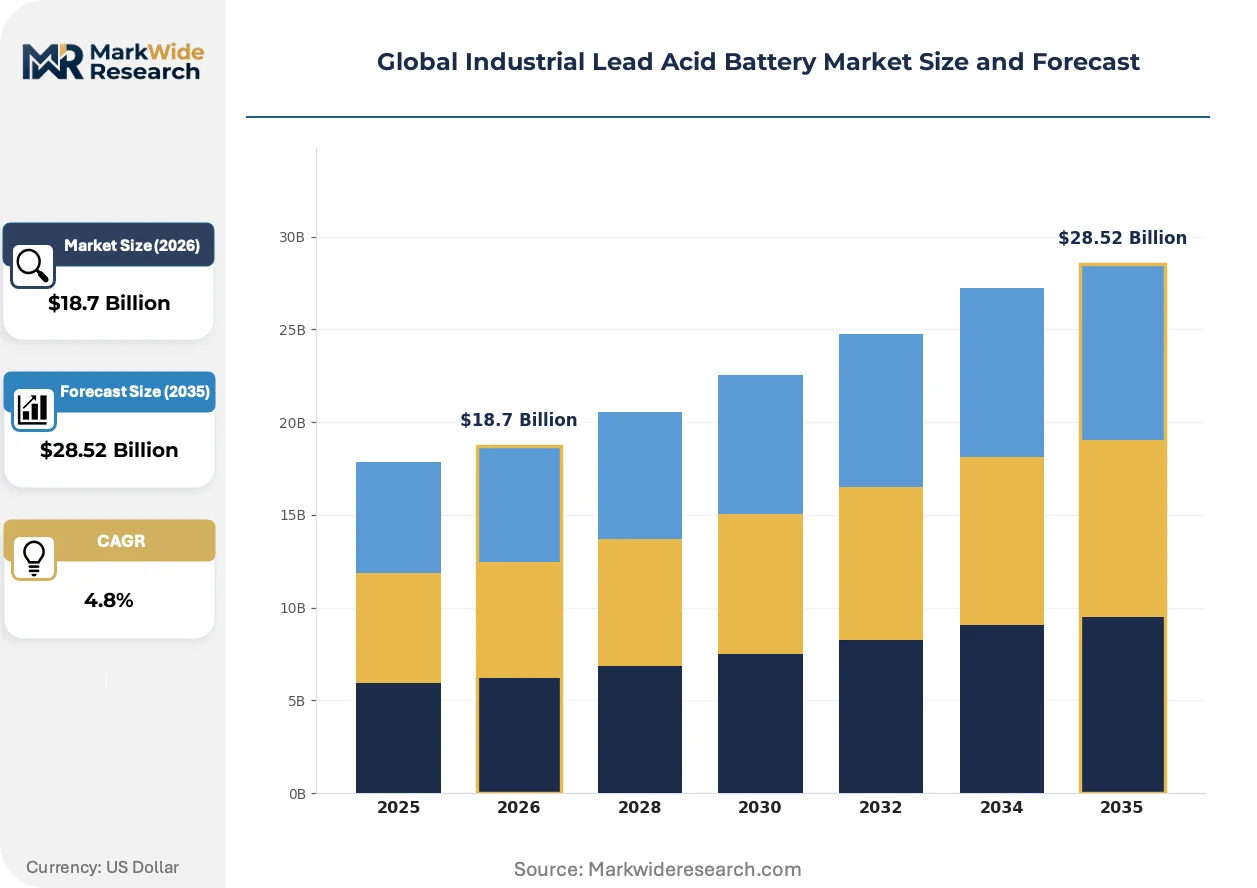
The industrial lead acid battery sector faces a structural pivot as EU Battery Regulation mandates and China's dual carbon goals simultaneously compress demand for legacy flooded systems while elevating valve-regulated designs. This regulatory divergence is fragmenting product platforms and forcing manufacturers to maintain parallel certification tracks across jurisdictions.
Growth Catalysts
- Data center UPS expansion:Hyperscale operators in India and Southeast Asia are standardizing on AGM configurations to reduce ventilation infrastructure. India's PLI scheme for advanced chemistry cells is indirectly validating battery-based backup architecture.
- EU F-Gas Regulation:Industrial cooling systems across Germany and France are accelerating battery substitution for compressor-based backup. This regulatory pressure is opening margin pools in gel-type systems for temperature-cycling applications.
- Telecom infrastructure hardening:Tower operators in Brazil and South Africa are deploying deep-cycle lead acid for off-grid and weak-grid sites. The technology's cost position in heavy-duty cycling preserves its relevance against lithium-ion in capital-constrained deployments.
Market Restraints
- Lead price volatility:Secondary lead smelter economics in the U.S. are exposed to EPA emissions compliance costs. Domestic recycler margins compress when LME lead spikes coincide with environmental remediation outlays.
- Substitution acceleration:Lithium iron phosphate is capturing forklift motive power in temperature-controlled European warehouses. Cold-chain logistics operators are amortizing higher upfront costs against energy density advantages.
- REACH carbon footprint disclosure:European market access now requires documented recycled content quotas. Asian exporters without EU-verified recycling partnerships face extended qualification timelines and compliance cost premiums.
Strategic Opportunities
- India domestic manufacturing:The PLI scheme's advanced chemistry cell incentives are creating co-location opportunities for lead acid recyclers. Integrated smelter-battery complexes can capture circular economy certification premiums.
- Marine and submarine programs:Naval procurement in Japan and South Korea favors gel lead acid for underwater propulsion. These programs offer decade-long contract visibility absent in commercial forklift markets.
- Renewable energy storage hybridization:Off-grid solar installations in sub-Saharan Africa are pairing lead acid with lithium-ion in cost-optimized configurations. Distribution partners with local assembly capability are capturing installation and maintenance revenue streams.
Industry Challenges
- Smelter technician scarcity:Lead battery recycling requires specialized metallurgical expertise that vocational programs in the U.S. and Europe have deprioritized. Facilities face recruitment bottlenecks as veteran operators retire.
- Dual certification complexity:India's BIS testing protocols diverge from China's GB standards on cycle life validation. Manufacturers serving both markets must maintain separate product variants and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Lead Acid Battery Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealed Lead Acid, Flooded Lead Acid, Gel Lead Acid, AGM Lead Acid End User: Telecommunications, Automotive, Renewable Energy, UPS Application: Backup Power, Starting Power, Electric Vehicles, Energy Storage Distribution Channel: Direct Sales, Distributors, Online Retail, Retail Outlets |
| Companies Covered | Exide Industries, GS Yuasa, EnerSys, Clarios, East Penn Manufacturing, Amara Raja Batteries, C&D Technologies, Narada, Coslight Technology International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Lead Acid Battery Market Strategic Shifts
Carbon footprint traceability is emerging as a decisive procurement filter across European industrial buyers. Battery purchasers are now requiring supplier documentation that extends from raw material sourcing through end-of-life recycling, reshaping competitive qualification criteria.
Carbon black additives in negative active material are rewriting cycle life expectations in partial state-of-charge applications. Forklift fleet operators in Germany and the Netherlands are adopting these enhanced formulations to extend watering intervals and reduce maintenance labor. The technology is compressing total cost of ownership differentials against lithium-ion in high-utilization three-shift operations.
REACH and the EU Battery Regulation are mandating recycled lead content thresholds and supply chain due diligence disclosures. Battery assemblers without captive recycling or long-term secondary lead offtake agreements face margin erosion from spot market exposure. The regulatory burden falls most heavily on small and mid-tier suppliers lacking integrated smelter networks.
After-sales service unbundling is disrupting traditional distributor relationships in North American motive power markets. End-users are separating battery procurement from maintenance contracts, favoring specialized service providers with telemetry-enabled fleet management platforms. This pattern is most visible in warehouse consolidation networks where capital and operating budgets sit in separate procurement functions.
Global Industrial Lead Acid Battery Market Segmentation
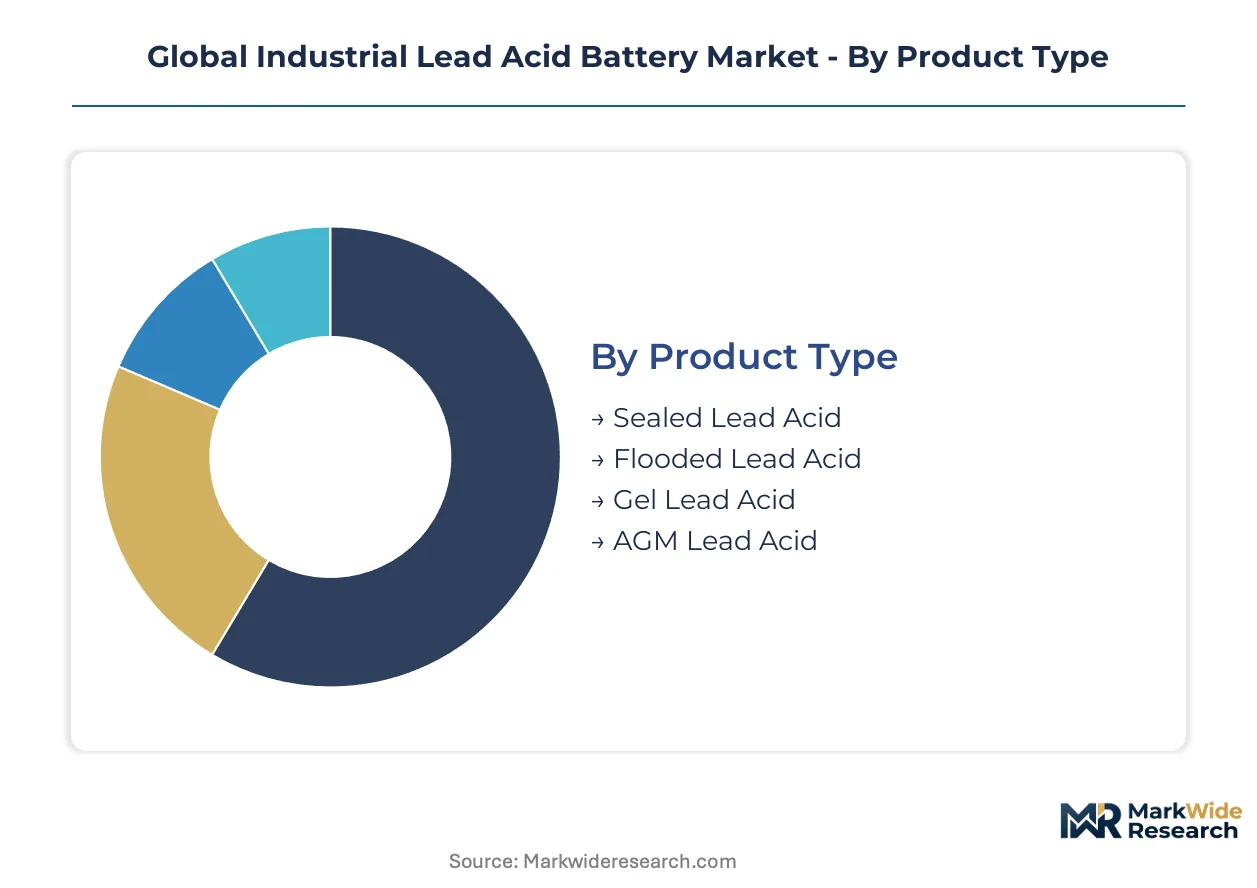
Segmentation in industrial lead acid batteries reveals how regulatory pressure and application economics split demand across chemistry types and procurement channels. Understanding these divides exposes where margin pools concentrate and where substitution threats loom.
Product Type:
Flooded systems dominate volume shipments while valve-regulated designs command premium positioning in regulated environments.
- Sealed Lead Acid:Maintenance-free construction with immobilized electrolyte eliminates watering requirements. Demand concentrates in small-format backup applications across Brazilian telecom towers where technician access is limited and total cost of ownership drives procurement.
- Flooded Lead Acid:Liquid electrolyte design with removable caps for specific gravity testing and water replenishment. Mining vehicle fleets in South Africa and Australian extraction sites specify these systems for their field-serviceability and tolerance to deep discharge cycling in harsh operating conditions.
- Gel Lead Acid:Silica-thickened electrolyte prevents stratification and extends cycle life in partial state-of-charge operation. German solar off-grid installations favor gel formulations for temperature stability across seasonal cycling patterns.
- AGM Lead Acid:Absorptive glass mat separators enable high-rate discharge and valve-regulated gas recombination. Data center operators in India standardize on AGM for reduced ventilation infrastructure and compatibility with fire suppression systems.
Today's leader: Flooded Lead Acid. Tomorrow's challenger: AGM Lead Acid.
End User:
Application requirements for cycle depth and discharge rate create divergent procurement specifications across customer verticals.
- Telecommunications:Remote tower installations require batteries capable of sustaining float service with occasional deep cycling during grid outages. Tower operators in Indonesia and Nigeria prioritize capital efficiency over energy density.
- Automotive:Commercial vehicle starting and auxiliary power applications specify thin-plate pure lead constructions for cold-cranking performance. Aftermarket replacement cycles in Mexico and Thailand sustain steady demand.
- Renewable Energy:Daily deep-cycling duty in off-grid solar and wind installations demands thick-plate tubular designs. Rural electrification programs in Kenya and Bangladesh specify lead acid for cost containment against lithium-ion alternatives.
- UPS:Uninterruptible power supply installations prioritize high-rate discharge capability and minimal maintenance. Japanese and South Korean manufacturing facilities specify valve-regulated designs for cleanroom compatibility.
Telecommunications anchors current volume. Renewable Energy is climbing the fastest as rural electrification accelerates.
Application:
Duty cycle intensity and discharge profile determine plate chemistry and separator specifications across use cases.
- Backup Power:Float-service optimized designs with calcium-alloy grids minimize water loss during standby periods. Hospital and critical infrastructure installations in Italy and Spain require multi-hour autonomy under EU resilience directives.
- Starting Power:High-surface-area plates deliver burst current for engine cranking applications. Commercial trucking fleets across the US Midwest specify dual-purpose constructions combining starting and light cycling duty.
- Electric Vehicles:Deep-cycle traction batteries with reinforced plates withstand repeated discharge to depth of discharge levels above 50 percent. Forklift fleets in Dutch and Belgian logistics hubs evaluate carbon-enhanced negative active material formulations.
- Energy Storage:Grid-connected and off-grid stationary applications balance cycle life against capital cost. Australian household solar installations pair lead acid with lithium-ion in hybrid configurations.
Backup Power maintains installed base dominance. Energy Storage offers the steepest expansion trajectory as grid stabilization needs multiply.
Distribution Channel:
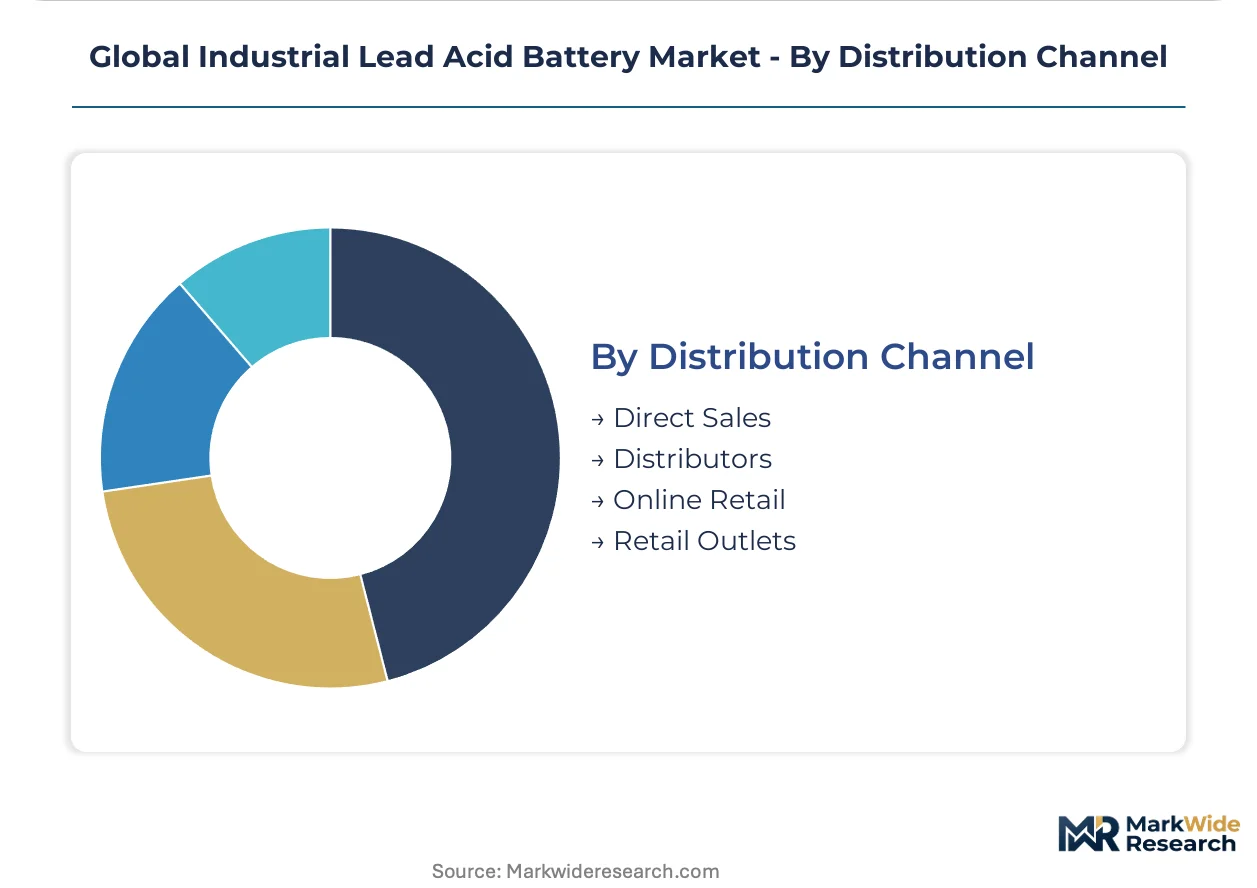
Channel selection reflects purchase scale, technical support requirements, and geographic density of end-user operations.
- Direct Sales:Manufacturer-to-end-user relationships for large fleet operators and OEM supply agreements. Multi-site warehouse operators in Germany negotiate enterprise pricing with telemetry-enabled fleet management integration.
- Distributors:Regional stockholding intermediaries providing local inventory and field service capabilities. Independent distributors across the US Southeast capture motive power replacement demand from manufacturing plants.
- Online Retail:E-commerce platforms serving small-scale buyers and remote locations with standardized product configurations. Replacement battery procurement for residential solar in rural India shifts toward digital channels.
- Retail Outlets:Physical storefronts for immediate replacement needs and walk-in commercial customers. Automotive aftermarket channels in Brazil and Argentina maintain counter presence for commercial vehicle servicing.
Distributors control current volume flows. Direct Sales is gaining share fastest as large fleet operators unbundle procurement from maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial lead acid battery manufacturing traces its modern scale to German electrochemical engineering and American mass-production techniques developed through the twentieth century. Today's demand geography reflects this dual heritage while incorporating new production centers in Asia.
United States
Forklift fleet operators and data center developers drive procurement across the Midwest and Southeast. EPA emissions standards at secondary lead smelters elevate compliance costs for domestic recyclers. The Ohio-Pennsylvania industrial corridor hosts concentrated battery assembly and recycling operations serving North American motive power demand.
Germany
Automotive suppliers and renewable energy installers specify valve-regulated designs for cold-chain logistics and solar storage applications. REACH carbon footprint disclosure and the EU Battery Regulation mandate recycled content quotas. The Baden-Württemberg industrial cluster integrates battery production with precision engineering supply chains.
China
Telecom infrastructure expansion and electric vehicle auxiliary power sustain volume demand despite lithium-ion substitution in traction applications. GB standards enforcement and dual carbon goals compress margins for legacy flooded production. The Pearl River Delta and Yangtze River Delta concentrate both manufacturing and secondary lead refining capacity.
India
Tower operators and rural electrification programs anchor demand for cost-optimized deep-cycle systems. The PLI scheme for advanced chemistry cells creates co-location incentives for integrated lead acid recyclers. Gujarat and Maharashtra industrial zones attract smelter-battery complex investments targeting circular economy certification.
Japan
Submarine propulsion programs and industrial UPS installations favor gel-type formulations for reliability-critical applications. METI procurement guidelines emphasize domestic supply chain security for defense-adjacent manufacturing. The Kansai region maintains specialized production lines for naval battery systems with decade-long contract visibility.
Global Industrial Lead Acid Battery Market Competitive Environment
Premium-margin players sit above commodity-margin players across recycling integration and service infrastructure density. The vendor base stratifies into three tiers: integrated smelter operators with captive lead supply, regional assemblers dependent on spot secondary markets, and specialized service providers unbundling maintenance from procurement. Two dominant competitive moves are reshaping positioning: backward integration into secondary lead refining and geographic co-location with hyperscale data center developments.
Within the integrated recycling tier, Exide Industries and Clarios exemplify archetypes of circular economy positioning. EnerSys anchors the North American service infrastructure vector. These three names represent distinct strategic postures—Indian smelter network leverage, multi-regional scale aggregation, and dense field service capability—rather than interchangeable market presence.
| Leading Market Players |
|---|
| Exide Industries |
| GS Yuasa |
| EnerSys |
| Clarios |
| East Penn Manufacturing |
| Amara Raja Batteries |
| C&D Technologies |
| Narada |
| Coslight Technology International Group |
| Others |
Value Chain & Pricing Dynamics
Secondary lead pricing volatility cascades through three distinct procurement tiers as Indian and Chinese smelter economics diverge under divergent environmental compliance regimes. Spot market exposure at non-integrated assemblers compresses margins when LME lead spikes coincide with EPA remediation outlays in U.S. recycling facilities.
Pricing Analysis
Contract-based long-term offtake agreements dominate volume procurement between integrated manufacturers and hyperscale data center operators, while spot transactions serve fragmented forklift fleet replacement demand. Price differentiation separates AGM configurations with EU Battery Regulation carbon disclosure from economy flooded systems lacking traceability documentation. Cost compression in standard-tier flooded batteries is intensifying because lithium iron phosphate substitution in European cold-chain logistics erodes volume leverage. Tower operators in capital-constrained emerging markets exhibit highest price sensitivity, whereas submarine program procurement in Japan shows lowest sensitivity due to decade-long contract visibility and reliability premiums.
Supply Chain Analysis
Smelter technician scarcity in U.S. and European vocational programs constrains secondary lead refining capacity expansion despite rising battery collection volumes. Manufacturing concentrates in China, India, and the United States, with the Pearl River Delta and Gujarat industrial zones anchoring integrated smelter-battery complex investments. Raw material dependencies center on mined lead concentrates, recycled secondary lead, and sulfuric acid electrolyte. Single-source vulnerability in Chinese GB-standard certification testing creates qualification bottlenecks for exporters serving multiple jurisdictions. Distribution runs through regional stockholding distributors with field service capabilities, though direct sales channels gain share as large fleet operators unbundle procurement from maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where procurement criteria are shifting toward verified recycling chains and carbon footprint documentation under EU Battery Regulation mandates.
For Market Incumbents: Deepen backward integration into captive secondary lead refining to insulate margin structures from spot market volatility. Invest in EU-verified recycling partnerships to compress qualification timelines for European market access. Lithium iron phosphate substitution in temperature-controlled warehouse applications threatens volume leverage in motive power segments. For New Entrants and Emerging Players: Begin with co-location opportunities in India's Gujarat and Maharashtra industrial zones where PLI scheme incentives for advanced chemistry cells create circular economy certification premiums. Target rural electrification programs in sub-Saharan Africa and Southeast Asian telecom infrastructure hardening as penetrable segments. Pursue distribution partnerships with local assembly capability to capture installation and maintenance revenue streams in off-grid solar hybrid configurations. For Investors and Strategic Acquirers: Roll-up economics work for regional assemblers with established BIS or GB certification track records because regulatory fragmentation across India and China extends supplier qualification timelines and creates acquisition currency for compliant assets. Long-term viability hinges on positioning for premium valve-regulated demand growth against commoditized flooded system contraction. Monitor lithium iron phosphate cost curves in forklift motive power as inflection indicator for substitution acceleration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Lead Refining | Captive smelter capacity insulates margins from LME volatility and EPA compliance cost spikes. |
| EU Battery Regulation Certification Investment | Carbon footprint disclosure capabilities unlock premium pricing in German and French industrial procurement. |
| Geographic Co-location with Hyperscale Data Centers | Proximity to Indian and Southeast Asian cloud infrastructure reduces logistics costs and service response times. |
| Telemetry-Enabled Fleet Management Platform Development | Unbundled service contracts capture recurring revenue as North American motive power procurement separates capital and operating budgets. |
| Marine and Submarine Program Qualification | Naval procurement in Japan and South Korea offers decade-long contract visibility absent in commercial forklift markets. |
Study Parameters
Direct dialogue with battery plant managers, OEM procurement leads at forklift manufacturers, telecom tower operators, secondary lead smelter technical directors, and renewable energy EPC contractors grounded qualitative assessment. Secondary validation drew from EPA emissions filings, EU Battery Regulation implementation guidance, BIS certification protocols, customs trade data on lead concentrate imports, and hyperscaler data center capex disclosures. Bottom-up demand modeling across end-use segments triangulated against top-down macroeconomic indicators to produce volume and value estimates.
Segment-level projections across product type, end user, application, and distribution channel dimensions informed the analytical framework throughout the forecast period. CAGRs were derived from regression analysis against industrial production indices, data center construction pipelines, and telecom infrastructure investment cycles. Key inputs included lead price volatility assumptions, lithium-ion substitution elasticity estimates, and regulatory compliance cost trajectories under REACH and EU Battery Regulation mandates.
Several conditions sit outside the modeled scope, including unforeseen breakthroughs in solid-state battery commercialization, abrupt shifts in Chinese dual carbon policy enforcement intensity, and trade barrier escalations affecting lead concentrate flows. Forecasts reflect assumptions about continued cost competitiveness in heavy-duty cycling applications and stable secondary lead recycling economics. Material deviation in lithium iron phosphate cost reduction trajectories or EU carbon border adjustment implementation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Primary Lithium Battery Market
Batteries
Medical Batteries Market
Batteries
Liquid Metal Battery Market
Batteries
Breathing Battery Market
Batteries
Thin Film and Printed Battery Market
Batteries
Forklift Battery Market
Batteries
India Micro Batteries Market
Batteries
Europe SLI Battery Market
Batteries
Proton Battery Market
Batteries
Middle-East Battery Market
Batteries
Battery Maintainer Market
Batteries
Seawater Battery Market
Batteries
Battery Plate Market
Batteries
GCC Rechargeable Battery Market
Batteries
South America Micro Battery Market
Batteries
Power Tool Batteries Market