
 Europe Solar Blanket Market | 2026-2036
Europe Solar Blanket Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Solar Blanket Market Insights
The Europe solar blanket market is restructuring around a widening gap between premium fluoropolymer-backed products and commodity PET-based alternatives. Dupont leverages its fluoro-chemistry heritage to command high-performance segments, while Krempel anchors Central European manufacturing with cost-optimized backsheet solutions. Targray competes aggressively on material sourcing scale across the Iberian and Italian solar corridors.
Solar blankets are multi-layer protective laminates—typically comprising a fluorinated top sheet, PET core, and adhesive EVA interface—engineered to shield photovoltaic cells from moisture ingress, thermal cycling, and UV degradation over 25-year service lives. Flexible product types are capturing disproportionate growth as building-integrated photovoltaics expand across European commercial rooftops, while rigid formats retain dominance in utility-scale Spanish and Italian ground-mount installations where mechanical durability requirements are most severe. Photovoltaic technology applications generate the deepest margin pools due to blanket-to-cell interface complexity, whereas solar thermal deployments occupy a mature, price-compressed niche concentrated in Mediterranean residential water heating.
REACH compliance and the EU Green Deal's embodied carbon reporting requirements are reshaping material selection across the value chain, with ECHA substance restrictions now forcing reformulation of conventional adhesive chemistries. CE marking under the Construction Products Regulation governs fire performance and weathering standards for building-attached deployments. Stakeholders must monitor how the EU AI Act's emerging conformity frameworks intersect with automated manufacturing quality systems before committing capital to new European blanket production lines.
Market Dynamics
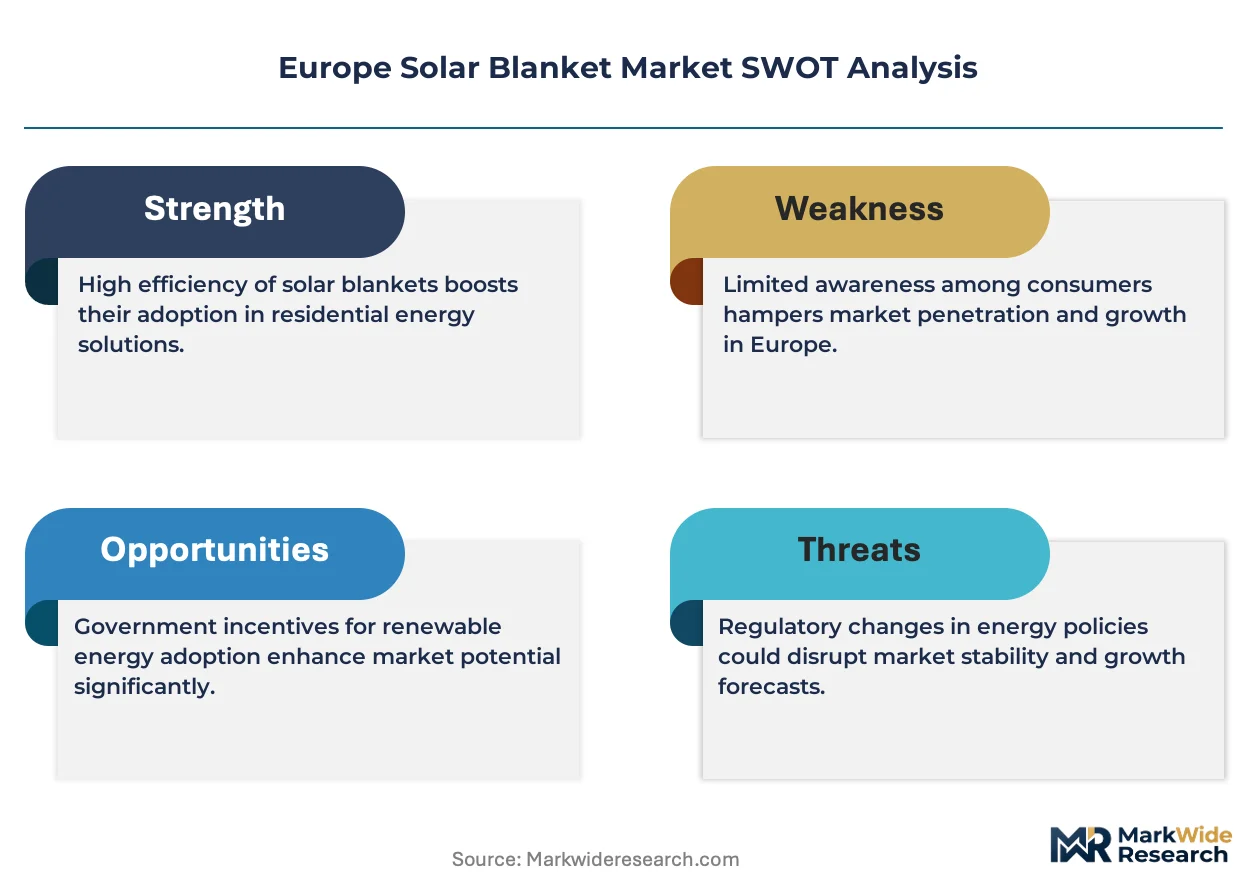
EU Green Deal mandates are compressing installation timelines for building-integrated photovoltaics, forcing solar blanket manufacturers to reformulate backsheet chemistries for faster curing and lower embodied carbon. REACH substance restrictions are simultaneously eliminating legacy adhesive systems.
Growth Catalysts
- Building-integrated photovoltaics:Commercial rooftop deployments across Germany and Spain are accelerating demand for flexible laminates that conform to curved architectural surfaces. Architects specify these systems for LEED-equivalent certifications.
- REPowerEU targets:The European Commission's 2025 renewable capacity mandates are tightening national building codes in Italy and Poland, requiring solar-ready construction for new commercial developments.
- Perovskite tandem integration:Next-generation cell architectures demand modified backsheet thermal expansion coefficients, creating specification upgrades across premium installation segments.
Market Restraints
- Fluoropolymer supply concentration:PVDF and ETFE resin production clusters in Belgium and Germany, exposing buyers to single-source risk during force majeure events.
- Silver metallization cost volatility:Cell manufacturers face margin compression from precious metal price swings, indirectly constraining backsheet upgrade budgets.
- ECHA substance restrictions:REACH Annex XVII limitations on PFAS chemistries are forcing adhesive reformulations that extend qualification timelines by 12-18 months.
Strategic Opportunities
- Polish distributed solar:The country's lagging rooftop penetration versus Germany offers first-mover positioning for flexible blanket suppliers targeting residential installers.
- Agrivoltaic dual-use installations:French and Italian agricultural solar projects require permeable, lightweight backsheet designs that preserve soil moisture and enable mechanized farming.
- EU AI Act compliance services:Automated quality inspection systems for blanket lamination lines create adjacent revenue streams for verification and algorithm auditing.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for fluoropolymer-PET adhesion interfaces concentrates at aging technical institutes in Germany and Switzerland.
- CE marking timeline compression:Construction Products Regulation fire testing for building-attached deployments now requires concurrent weathering validation, extending certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Solar Blanket Market |
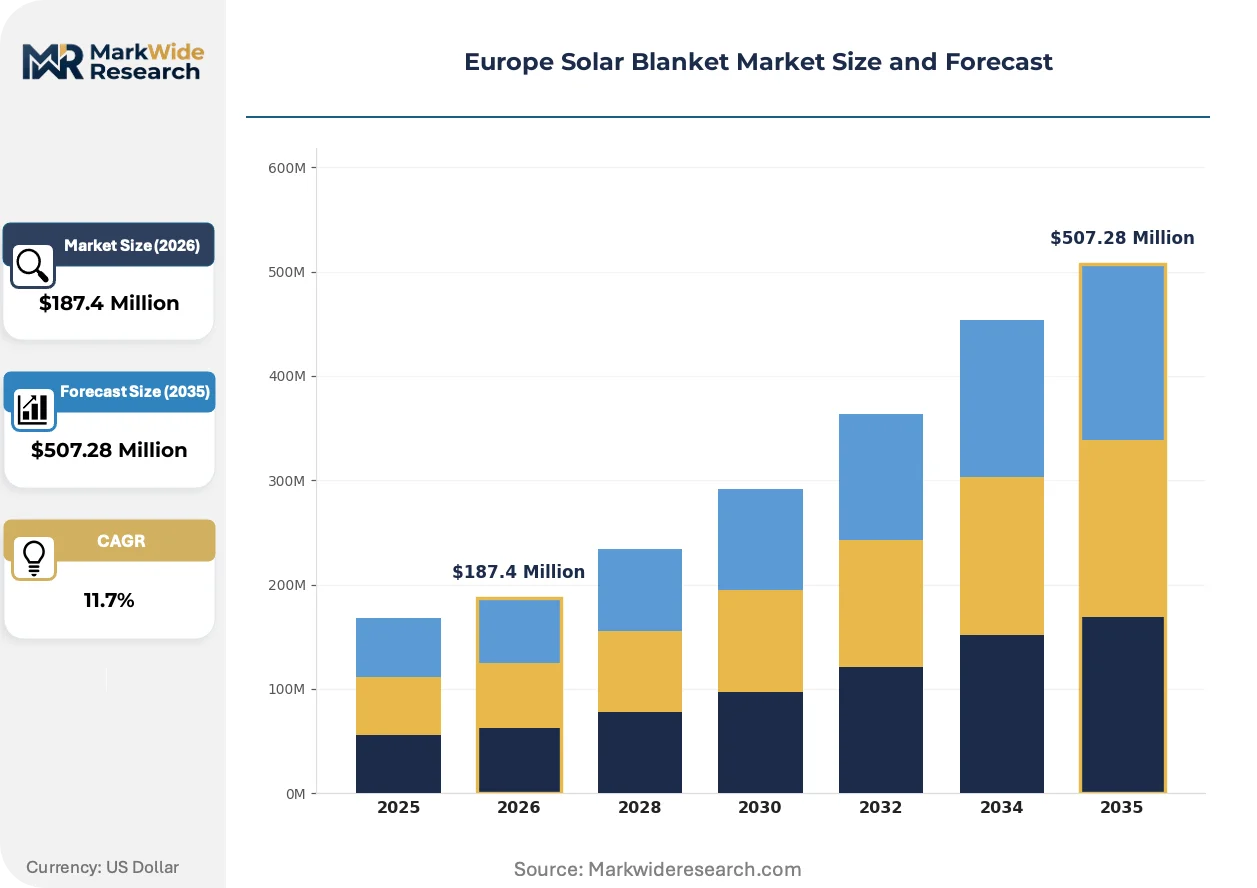
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Film, Flexible, Rigid, Integrated End User: Residential, Commercial, Industrial, Utility Technology: Photovoltaic, Solar Thermal, Concentrated, Hybrid Application: Heating, Electricity Generation, Water Heating, Off-Grid |
| Companies Covered | Dupont, ZTT International, Mitsubishi Chemical America Inc., Targray, Krempel, Hangzhou First, Jolywood Solar Technology Ltd, Honeywell, 3M, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Solar Blanket Market Trends and Innovations
Material science breakthroughs are collapsing the performance gap between fluoropolymer and non-fluorinated backsheet alternatives, while digital manufacturing tools are redefining quality assurance protocols across European production lines.
Co-extruded polyolefin barrier films are electrifying the commodity segment of the solar blanket market. These multi-layer structures replace fluorinated top sheets in utility-scale Spanish and Italian ground-mount projects. EPC contractors are specifying them for 20-year warranted installations where capital cost minimization dominates procurement criteria.
REACH Annex XVII PFAS restrictions are eliminating legacy adhesive chemistries from European supply chains. Formulators are pivoting to silicone and acrylate alternatives that sacrifice some moisture barrier performance for regulatory compliance. Building-integrated photovoltaic manufacturers in Germany face the steepest reformulation costs due to their reliance on high-bond-strength fluoropolymer interfaces.
Long-term power purchase agreements are reshaping buyer risk allocation for solar blanket performance guarantees. Utility offtakers in France and Spain now require 30-year material warranties backed by third-party insurance instruments. This contractual evolution favors suppliers with captive resin production and documented 25-year field aging databases over import-dependent trading houses.
Europe Solar Blanket Market Segmentation
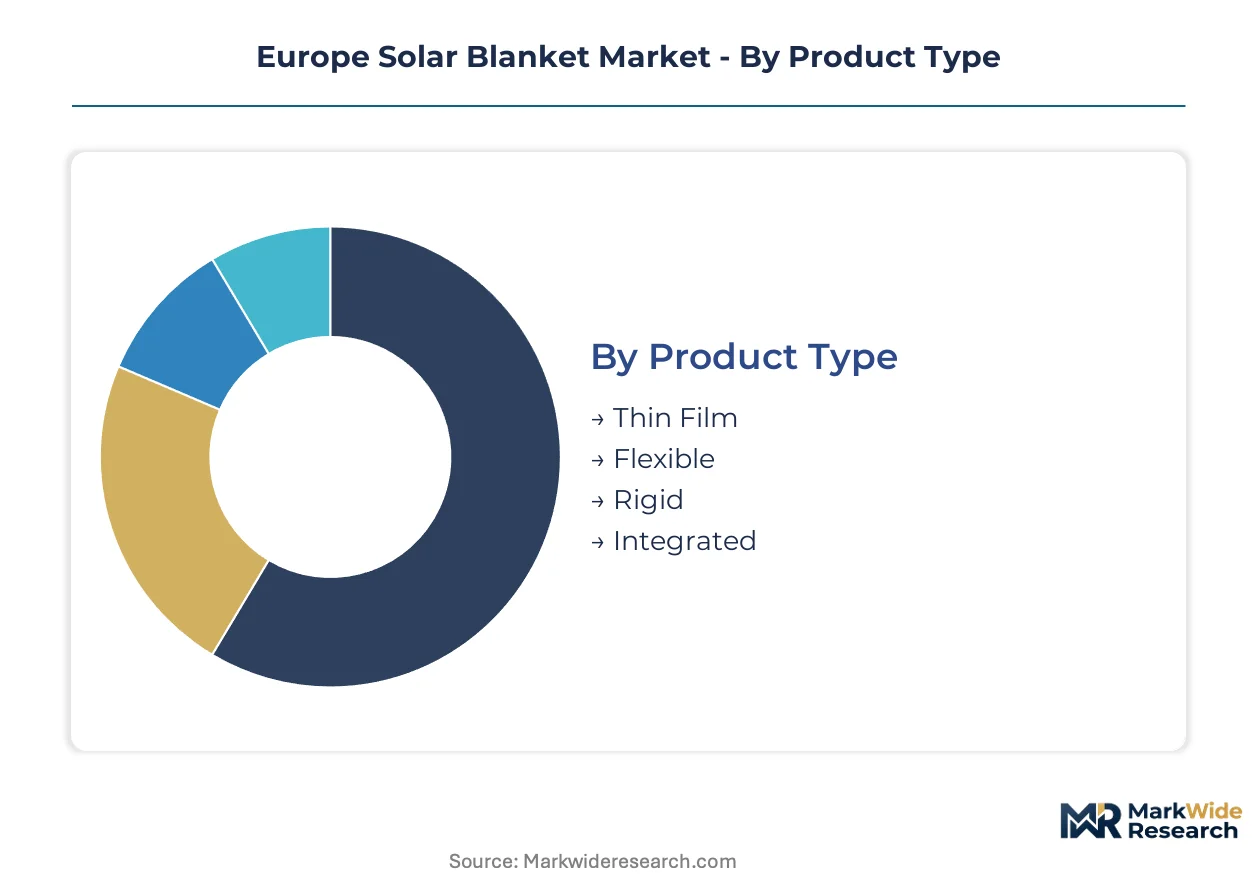
Solar blanket segmentation in Europe reflects divergent performance requirements across building-integrated and utility-scale deployments. Material specifications, thermal expansion properties, and fire resistance ratings vary sharply by installation context and regulatory exposure.
Product Type:
Customization intensity spans from architect-specified flexible laminates to standardized rigid panels for ground-mount arrays.
- Flexible:Multi-layer fluoropolymer-PET laminates conform to curved commercial rooftops across Germany and Spain. German building codes for BIPV now mandate these formats for heritage structure retrofits where load-bearing limits prohibit glass-glass modules.
- Rigid:Glass-encapsulated backsheet assemblies dominate Italian and Spanish utility-scale installations. EPC contractors specify these for 30-year performance guarantees under long-term power purchase agreements with French and Spanish offtakers.
- Thin Film:Lightweight amorphous silicon blankets serve portable and mobile applications.
- Integrated:Structural building elements combining insulation and photovoltaic layers target Nordic passive house standards.
Leading the category by volume: Rigid. Growing fastest: Flexible.
End User:
Procurement sophistication escalates from residential installer networks to utility engineering departments with captive technical specification teams.
- Commercial:Rooftop installations across German logistics parks and Spanish retail chains drive specification of fire-rated backsheet assemblies. REPowerEU building code amendments now require solar-ready construction for new commercial developments in Italy and Poland.
- Utility:Ground-mount solar farms in Spain and Italy procure backsheet materials through multi-year framework agreements. These buyers demand 30-year material warranties backed by third-party insurance instruments and documented field aging databases.
- Residential:Distributed rooftop systems concentrate in German and Polish suburban markets.
- Industrial:On-site generation for manufacturing facilities with 24-hour load profiles.
Commercial deployments generate the deepest specification complexity. Utility procurement commands the largest individual contract values.
Technology:
Cell architecture selection dictates backsheet thermal expansion coefficients and moisture barrier requirements.
- Photovoltaic:Crystalline silicon and perovskite-tandem cells require modified backsheet formulations. Next-generation tandem architectures in German pilot production demand tighter coefficient matching between cell and laminate layers.
- Solar Thermal:Flat-plate and evacuated tube collectors use simplified backsheet designs. Mediterranean residential water heating markets in Italy and Spain concentrate demand for these mature, price-compressed products.
- Concentrated:High-temperature applications require specialized thermal management layers.
- Hybrid:Combined photovoltaic-thermal systems emerging in French agrivoltaic pilots.
Photovoltaic applications command premium pricing for interface complexity. Solar thermal occupies a commoditized niche with thinner margins.
Application:
Functional use case determines exposure severity and warranty duration requirements.
- Electricity Generation:Grid-connected and off-grid power production drives the majority of backsheet demand. Spanish and Italian ground-mount installations specify 30-year warranted laminates under long-term offtake contracts.
- Water Heating:Residential solar thermal systems concentrate in Mediterranean markets. Italian and Spanish installers favor standardized PET-based backsheets for these cost-sensitive applications.
- Heating:Space heating integration with heat pump systems in Nordic climates.
- Off-Grid:Remote installations requiring enhanced durability for maintenance access constraints.
Electricity generation commands the broadest specification range. Water heating remains the most price-sensitive application segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European solar blanket manufacturing, with Belgian fluoropolymer resin production feeding lamination facilities across the Low Countries and western Germany.
Germany
Building-integrated photovoltaic retrofits on heritage structures in Berlin and Munich drive flexible laminate demand. The EU Green Deal's REPowerEU targets tighten federal building codes for solar-ready commercial construction. Bavarian industrial parks host pilot production lines for perovskite-tandem compatible backsheet formulations.
Spain
Utility-scale ground-mount installations in Andalusia and Extremadura procure rigid glass-encapsulated backsheets through long-term power purchase agreements. The country's national energy regulator enforces 30-year material warranty requirements for grid-connected solar farms. Valencia's port logistics cluster handles bulk resin imports for Iberian lamination plants.
Italy
Agrivoltaic dual-use projects in Emilia-Romagna and Lazio specify permeable, lightweight blanket designs for mechanized farming compatibility. REPowerEU building code amendments mandate solar-ready construction for new commercial developments. Lombardy's manufacturing belt concentrates backsheet adhesive formulators adapting to REACH Annex XVII PFAS restrictions.
Poland
Lagging rooftop penetration versus German benchmarks creates first-mover opportunities for flexible blanket suppliers targeting residential installers in Warsaw and Krakow. National building code harmonization with EU renewable energy directives accelerates distributed solar deployment. Silesian industrial zones attract lamination line investments serving Central European markets.
France
Agricultural solar pilots in Provence-Alpes-Côte d'Azur require specialized backsheet permeability for soil moisture preservation. The EU AI Act's emerging conformity frameworks intersect with automated quality inspection systems for blanket manufacturing. Île-de-France engineering consultancies specify fire-rated assemblies for commercial rooftop deployments.
Europe Solar Blanket Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure. Integrated resin-to-laminate manufacturers with captive fluoropolymer supply anchor premium segments, while trading houses and toll converters occupy price-sensitive utility procurement channels. Three archetypes dominate: chemical conglomerates leveraging fluoro-chemistry heritage, regional manufacturing specialists with optimized backsheet solutions, and material sourcing scale operators across solar corridors. Competitive moves concentrate on adhesive chemistry reformulation for REACH compliance and 30-year warranty underwriting capacity.
Among chemistry-heritage conglomerates, Dupont exemplifies premium-tier positioning through fluoropolymer expertise. Targray and Krempel occupy complementary positions across the sourcing-scale and manufacturing-specialist archetypes respectively. These three anchors illustrate how regulatory compliance capability and field aging databases increasingly determine competitive viability as long-term power purchase agreements reshape risk allocation.
| Leading Market Players |
|---|
| Dupont |
| ZTT International |
| Mitsubishi Chemical America Inc. |
| Targray |
| Krempel |
| Hangzhou First |
| Jolywood Solar Technology Ltd |
| Honeywell |
| 3M |
| Others |
Pricing and Supply Chain Analysis
Fluoropolymer-versus-PET performance bifurcation separates premium laminates from commodity alternatives across European procurement channels, with Dupont's chemistry heritage commanding value-based premiums while Krempel's cost-optimized formats anchor utility-scale tenders in Spain and Italy. This tier divergence manifests in divergent supply chain configurations: high-performance segments draw from captive Belgian resin production, while commodity tiers source through trading houses with floating inventory positions.
Pricing Analysis
Performance-guarantee pricing anchors European solar blanket valuation, with 30-year warranted laminates commanding substantial premiums over 20-year alternatives in French and Spanish utility offtake contracts. Three-tier pricing structure across fluoropolymer-premium, co-extruded polyolefin-standard, and PET-economy levels reflects certification grade and field-aging database depth. Cost compression in the commodity tier is intensifying because EPC contractors in Iberian ground-mount projects prioritize capital minimization over longevity. Utility procurement teams demonstrate lowest price sensitivity due to long-term power purchase agreement risk allocation, while Polish residential installers exhibit highest sensitivity as distributed solar penetration accelerates.
Supply Chain Analysis
Freight cost differentials between Belgian fluoropolymer resin clusters and Iberian lamination plants disadvantage non-integrated suppliers serving Spanish utility-scale projects. Raw material dependencies center on PVDF and ETFE resins from Belgium and Germany, PET film substrates from regional converters, and silicone-acrylate adhesives reformulating for REACH Annex XVII compliance. Single-source vulnerability concentrates in Belgian fluoropolymer production, where force majeure events would disrupt premium laminate availability across German BIPV channels. Distribution runs through EPC contractor framework agreements for utility segments and installer network distributors for commercial and residential deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European solar blanket competition is becoming a vertical-integration race, with players pursuing captive fluoropolymer resin supply to secure margin pools and warranty underwriting capacity as long-term offtake contracts reshape risk allocation.
For Market Incumbents: Hedge against REACH Annex XVII adhesive reformulation delays by qualifying multiple silicone and acrylate chemistries in parallel, preserving shipment continuity as ECHA substance restrictions eliminate legacy systems. Secure backward integration into PET film extrusion or fluoropolymer resin production to defend margin position against import-dependent trading houses as 30-year warranty requirements harden. For New Entrants and Emerging Players: REPowerEU building code amendments in Poland open a window for flexible blanket suppliers targeting residential installer networks in Warsaw and Krakow, where rooftop penetration lags German benchmarks substantially. Prioritize agrivoltaic dual-use specifications for French and Italian agricultural solar pilots, where permeable lightweight designs command specification premiums and mechanized farming compatibility creates defensible positioning. For Investors and Strategic Acquirers: Re-rating potential sits with integrated resin-to-laminate manufacturers given EU Green Deal embodied carbon reporting requirements and field-aging database scarcity. Monitor ECHA PFAS restriction implementation timelines as inflection indicators: accelerated enforcement would compress qualification timelines and favor incumbents with captive formulation expertise over import-dependent entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Chemistry Reformulation | REACH Annex XVII compliance preserves market access for European laminate suppliers serving German BIPV channels. |
| Captive Fluoropolymer Resin Production | Belgian PVDF supply integration secures margin pools and 30-year warranty underwriting capacity for premium segments. |
| Agrivoltaic-Compatible Design Development | Permeable lightweight formats capture French and Italian agricultural solar specifications requiring mechanized farming compatibility. |
| Automated Quality Inspection Deployment | EU AI Act conformity frameworks create adjacent revenue streams for algorithm auditing in blanket lamination lines. |
| Polish Distribution Network Establishment | First-mover positioning in lagging rooftop penetration markets captures REPowerEU building code acceleration benefits. |
Research Methodology
Independent corroboration across EPC contractor procurement leads, adhesive formulator technical directors, and building-integrated photovoltaic system architects underwrites the qualitative findings in this study. Primary fieldwork encompassed plant managers at Belgian and German resin facilities, distribution channel partners across Iberian solar corridors, and regulatory affairs specialists navigating REACH compliance timelines. Secondary validation drew from ECHA substance restriction databases, EU Construction Products Regulation fire testing protocols, and SEC filings of listed materials conglomerates. Bottom-up segmentation modeling and top-down macroeconomic anchoring ensured cross-verification across the analysis window.
Rate-of-change decomposition across product type, end-user procurement sophistication, cell technology architecture, and national regulatory framework intensity shaped the analytical framework. CAGRs were derived from installed capacity trajectories, backsheet intensity per watt assumptions, and pricing evolution by tier. Forecast inputs incorporated perovskite-tandem cell thermal expansion requirements, REPowerEU mandate implementation schedules, and PFAS restriction enforcement probability distributions.
The model assumes a particular technology adoption path; alternative pathways for perovskite-tandem integration or accelerated PFAS phase-out would alter the outlook for premium laminate demand and adhesive reformulation timelines. Forecasts reflect documented assumptions regarding regulatory enforcement, building code harmonization, and resin supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Chile Solar Energy Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
Solar PV Mounting Systems Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Smart Solar Solutions Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Australia Rooftop Solar Market