
 Hybrid Operating Room Market | 2026-2036
Hybrid Operating Room Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Operating Room Market Intelligence
The replacement of traditional metallic components with radiolucent carbon fiber tabletops is recalibrating the economics of intraoperative imaging. Siemens Healthineers leverages its deep expertise in advanced imaging systems to dominate this integrated space. Stryker Corporation competes by focusing on orthopedic and neurological surgical equipment integration within the hybrid suite. Getinge AB specializes in the architectural and workflow components, including modular room systems and surgical lights.
A hybrid operating room combines a conventional surgical theater with advanced medical imaging systems, such as fixed C-arms or intraoperative MRI scanners. This integration allows for simultaneous diagnostic and surgical procedures, enabling minimally invasive interventions with real-time visualization. Cardiovascular procedures represent the largest application segment due to the high volume of complex interventions. Among technologies, CT imaging and fluoroscopy are foundational, while fixed hybrid ORs dominate new installations in general hospitals over mobile solutions.
Product approval pathways are governed by bodies like the US FDA for 510(k) clearance and the EU's Medical Device Regulation (MDR) for CE marking. These frameworks mandate stringent validation for imaging equipment safety and software interoperability, influencing design and development costs. The critical decision for hospital administrators remains balancing the high initial capital investment against the long-term clinical and operational benefits.
Market Dynamics
The convergence of advanced imaging modalities with surgical instrumentation is the central force defining the hybrid operating room market. This integration is driven by the clinical demand for real-time visualization during complex, minimally invasive procedures, fundamentally altering hospital capital expenditure priorities.
Growth Catalysts
- Demographic Pressures:Aging populations in developed nations like Germany and Japan are elevating the incidence of complex cardiovascular and neurovascular diseases, increasing the procedural volume that necessitates hybrid OR capabilities for improved patient outcomes.
- Radiolucent Materials:The adoption of carbon fiber composites for surgical tables and patient positioning systems enhances intraoperative imaging quality by minimizing artifacts, which is a critical factor for procedures guided by fluoroscopy and CT scans.
- Reimbursement Frameworks:Favorable reimbursement policies from bodies like the Centers for Medicare & Medicaid Services (CMS) in the United States incentivize hospitals to invest in advanced surgical environments that support minimally invasive techniques.
Market Restraints
- High Capital Investment:The substantial upfront cost of constructing and equipping a hybrid OR, including fixed imaging systems and architectural modifications, remains a significant barrier for community hospitals and facilities in emerging economies.
- Interoperability Hurdles:A lack of universal communication standards between imaging equipment, surgical navigation systems, and patient monitoring devices from different vendors creates persistent integration challenges and reliance on single-supplier solutions.
- Substitution from Mobile Systems:High-performance mobile C-arms offer a lower-cost, flexible alternative for less complex procedures, posing a substitution threat and potentially delaying investment in fixed hybrid room installations for budget-constrained institutions.
Strategic Opportunities
- Emerging Market Build-Outs:Significant white space exists in Latin American and Southeast Asian countries, where governments are actively funding healthcare infrastructure modernization, creating opportunities for turnkey hybrid OR solution providers.
- Oncology and Trauma Applications:Expanding the use of hybrid ORs beyond cardiology into complex tumor resections and polytrauma cases represents a major growth avenue, leveraging intraoperative imaging for precision and immediate assessment.
- AI-Driven Surgical Planning:The integration of artificial intelligence and machine learning algorithms for pre-operative planning, automated image fusion, and predictive analytics offers a new frontier for enhancing surgical precision and efficiency.
Industry Challenges
- Specialized Talent Shortage:A critical gap persists in the availability of surgeons, nurses, and technologists trained to operate sophisticated imaging equipment and manage the complex workflow of a hybrid surgical environment.
- Radiation Safety Management:Ensuring the safety of both patients and clinical staff from increased radiation exposure during lengthy, image-guided procedures requires stringent protocols, specialized training, and investment in shielding technologies.
- Data Integration and Security:Integrating the vast amounts of imaging and procedural data generated in a hybrid OR with hospital-wide electronic health record (EHR) systems presents significant IT and cybersecurity challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Operating Room Market |
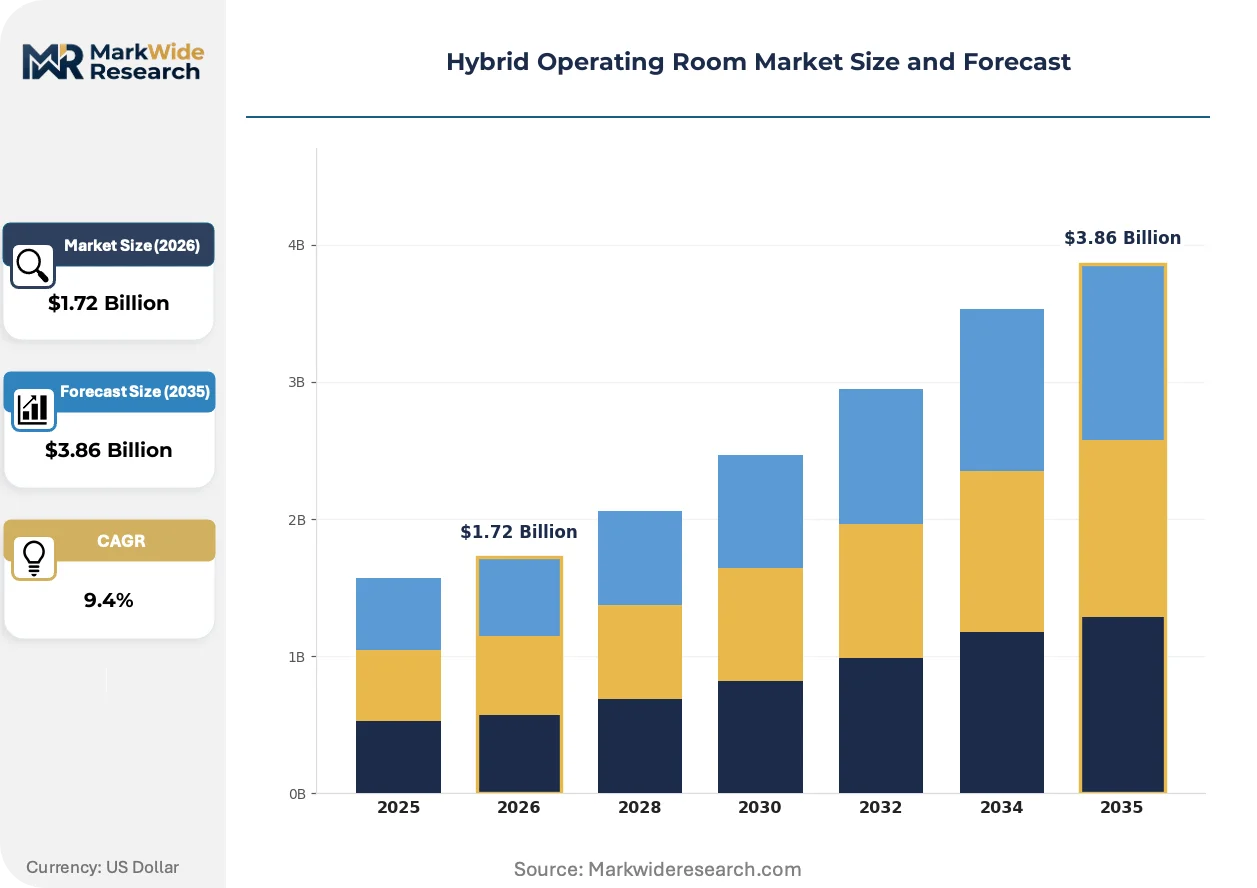
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.86 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Hybrid OR, Mobile Hybrid OR, Portable Hybrid OR, Modular Hybrid OR Technology: CT Imaging, MRI Imaging, Fluoroscopy, Ultrasound, Digital Subtraction Angiography Application: Cardiovascular Procedures, Neurological Interventions, Orthopedic Surgeries, Thoracic Operations, Vascular Treatments End User: General Hospitals, Specialty Treatment Centers, Trauma Centers, Ambulatory Surgery Facilities |
| Companies Covered | Koninklijke Philips N.V., Siemens Healthineers, General Electric Company, Stryker Corporation, Steris PLC, Toshiba Corporation, Getinge AB, Trumpf Medical, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Operating Room Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of robotics, advanced software, and new service models. These elements are transforming the hybrid OR from a static room into an intelligent, data-rich surgical ecosystem that prioritizes efficiency and clinical outcomes.
Robotic-assisted C-arms provide automated, pre-programmable movements for intraoperative imaging. Major academic medical centers are the primary adopters for complex vascular and spinal surgeries where precise, repeatable views are critical. This automation is electrifying the surgical workflow by reducing the need for manual repositioning, shortening procedure times, and minimizing staff exposure to the radiation field.
Implementation of the European Union's Medical Device Regulation (MDR) has elevated the compliance burden for all system components. The regulation mandates more extensive clinical evidence and rigorous post-market surveillance, directly impacting development timelines and costs for manufacturers. Imaging systems and interconnected software are particularly affected, requiring enhanced validation for cybersecurity and interoperability to gain or maintain CE marking.
A notable shift in hospital acquisition strategy involves moving from piecemeal capital purchases to comprehensive, long-term managed equipment service agreements. This trend disrupts the traditional sales model by bundling hardware, software, maintenance, and technology upgrades into a single operational contract. This procurement approach is gaining traction within large hospital networks in the United States and public health systems like the UK's NHS.
Hybrid Operating Room Market Segmentation
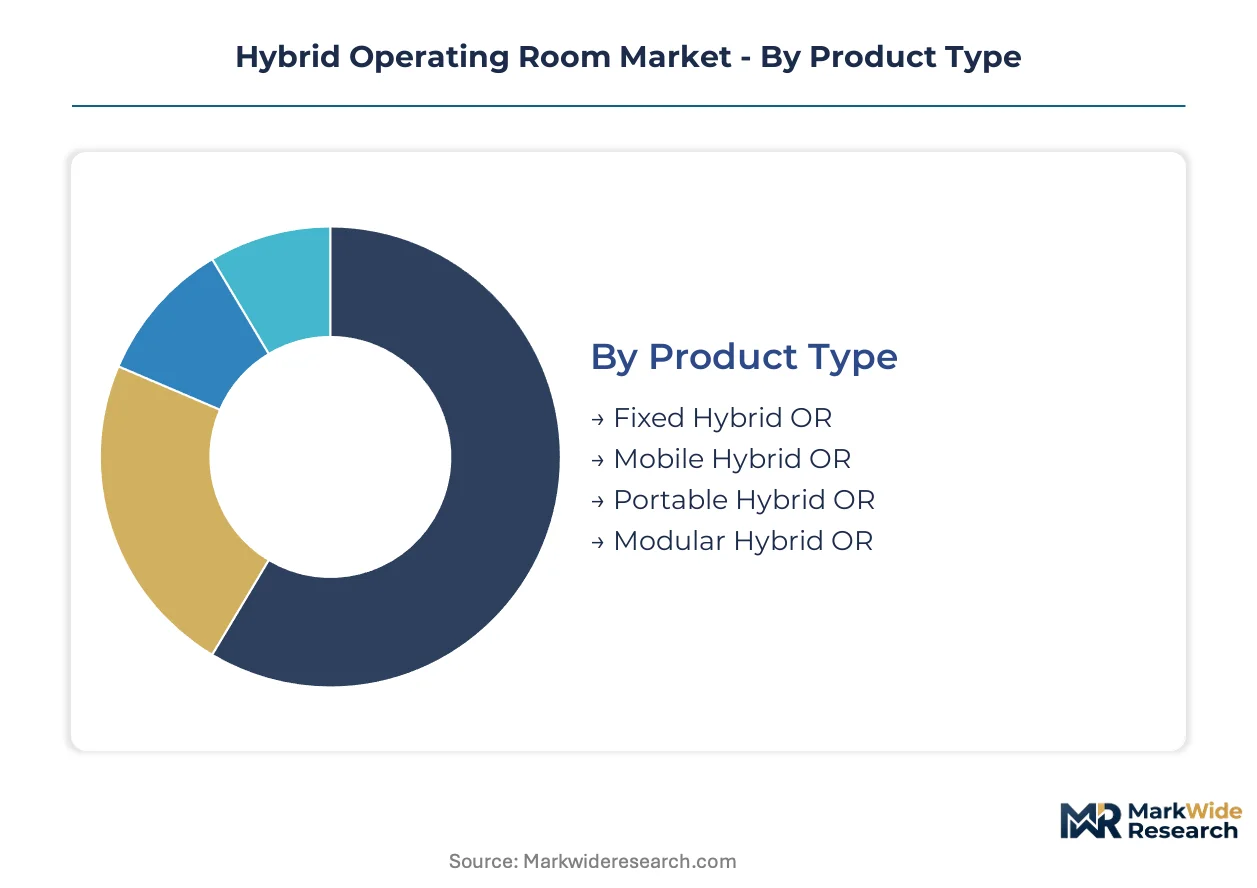
The hybrid operating room market's segmentation reflects the diverse technological advancements and clinical demands driving facility modernization. Understanding these distinct categories provides clarity on investment priorities and the evolving operational landscape for healthcare providers.
Product Type:
The upgrade cycle for surgical infrastructure heavily influences the adoption patterns across different hybrid OR product types, with hospitals evaluating long-term integration capabilities against immediate cost benefits.
- Fixed Hybrid OR:These integrated surgical suites combine a traditional operating room with permanently installed advanced imaging systems, such as C-arms or intraoperative MRI. General hospitals in developed economies like Germany prioritize these installations for complex, high-volume procedures, driven by the need for consistent, real-time visualization.
- Modular Hybrid OR:Pre-engineered, customizable room systems offer accelerated construction timelines and design flexibility, allowing hospitals to adapt existing spaces or build new facilities with specific clinical requirements. This approach gains traction in regions like the United States where rapid expansion of specialty treatment centers is observed.
- Mobile Hybrid OR:These units integrate imaging equipment onto mobile platforms, providing flexibility to move between different operating rooms or facilities. Budget-constrained institutions or those requiring temporary solutions often utilize mobile systems.
- Portable Hybrid OR:Compact imaging solutions that can be easily transported and deployed within various surgical settings. These offer a cost-effective alternative for less complex procedures or in environments with space limitations.
Volume placements concentrate in Fixed Hybrid OR; the faster expansion belongs to Modular Hybrid OR.
Technology:
The functionality and precision required for specific surgical interventions dictate the selection of imaging technologies within hybrid operating rooms, directly impacting procedural success rates.
- CT Imaging:Computed tomography provides detailed cross-sectional images, crucial for precise anatomical assessment and navigation during complex procedures, particularly in neurosurgery and trauma. Facilities in Japan frequently integrate advanced CT systems for their diagnostic capabilities.
- Fluoroscopy:This real-time X-ray imaging technique offers dynamic visualization of anatomical structures and instrument placement during minimally invasive procedures, essential for cardiovascular and orthopedic interventions. Its widespread use makes it foundational across all hybrid OR types.
- MRI Imaging:Magnetic resonance imaging delivers superior soft tissue contrast without radiation exposure, making it invaluable for neurosurgical and oncology applications where precise tumor delineation is critical. Major academic medical centers are the primary adopters.
- Ultrasound:High-frequency sound waves generate real-time images, offering a radiation-free option for soft tissue visualization and guidance in various procedures. This technology supports vascular access and organ biopsies.
- Digital Subtraction Angiography:This technique enhances the visualization of blood vessels by subtracting background images, providing clear views for vascular interventions. It is a specialized tool within cardiovascular hybrid suites.
CT Imaging holds the largest share; Digital Subtraction Angiography demonstrates the steepest expansion trajectory.
Application:
The increasing complexity of patient cases and the drive for improved outcomes are shaping the primary applications of hybrid operating rooms, with certain specialties demanding advanced imaging integration more acutely.
- Cardiovascular Procedures:This segment represents the largest application due to the high volume of complex interventions like transcatheter aortic valve replacement (TAVR) and endovascular aneurysm repair (EVAR). Hospitals in the United States heavily invest in hybrid ORs for these life-saving procedures, requiring real-time imaging for precision.
- Neurological Interventions:Hybrid ORs facilitate highly precise brain and spine surgeries, offering intraoperative imaging for tumor resection, aneurysm clipping, and spinal stabilization. Specialty treatment centers prioritize these capabilities to enhance surgical accuracy and patient safety.
- Orthopedic Surgeries:Image-guided orthopedic procedures, particularly for complex trauma and spinal fusions, benefit from real-time visualization in a hybrid setting. This reduces revision rates and improves implant placement.
- Thoracic Operations:Minimally invasive lung and esophageal surgeries leverage hybrid OR capabilities for precise navigation and immediate assessment of resections. This reduces patient morbidity.
- Vascular Treatments:Procedures involving peripheral artery disease and venous interventions utilize hybrid ORs for detailed vessel mapping and stent placement. This application underpins the demand in specialized vascular centers.
Cardiovascular Procedures commands the largest procedural volume; Neurological Interventions are gaining share fastest.
End User:
The investment capacity and patient demographic served by different healthcare facilities are key determinants in their adoption of hybrid operating room technology.
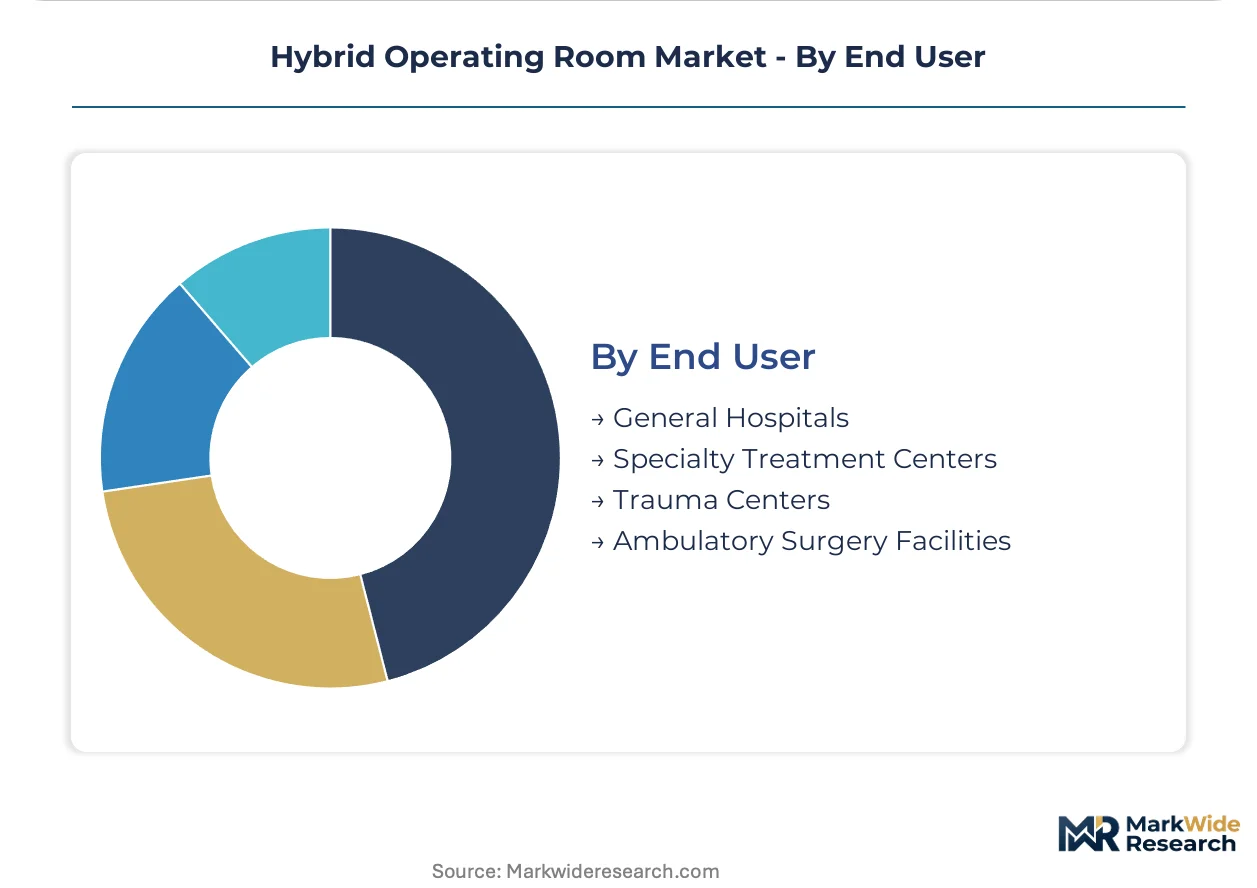
- General Hospitals:These facilities represent a significant end-user segment, driven by the need to upgrade existing infrastructure and offer a broad range of advanced surgical services. Modernization efforts in Europe often involve general hospitals implementing hybrid ORs to meet increasing demand for minimally invasive procedures.
- Specialty Treatment Centers:Focused on specific disease areas like cardiology or oncology, these centers often lead in adopting cutting-edge hybrid OR technology to deliver highly specialized and complex care. Their concentrated patient populations justify the high capital investment.
- Trauma Centers:Equipped to handle critical injuries, trauma centers use hybrid ORs for immediate diagnostic imaging and surgical intervention in polytrauma cases. This integration significantly improves patient outcomes in emergency situations.
- Ambulatory Surgery Facilities:These outpatient centers perform less complex procedures, and their adoption of hybrid ORs is typically limited to smaller, mobile imaging solutions. Cost efficiency remains a primary concern for these facilities.
General Hospitals constitute the largest end-user group; Specialty Treatment Centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for hybrid operating rooms is pronounced in developed economies grappling with aging populations and a high incidence of chronic diseases. These regions prioritize advanced surgical capabilities to enhance patient outcomes and manage complex procedural volumes. Significant investment in facility modernization reflects this clinical imperative.
Germany
Aging demographics in Germany elevate the incidence of complex cardiovascular and neurovascular diseases, driving demand for hybrid ORs. The EU's Medical Device Regulation (MDR) influences facility upgrades, mandating stringent compliance for imaging equipment. Academic medical centers in Berlin and Munich are actively investing in advanced hybrid operating room installations.
United States
The United States sees substantial demand for hybrid ORs, particularly for high-volume cardiovascular procedures like TAVR and EVAR. Favorable reimbursement policies from the Centers for Medicare & Medicaid Services (CMS) incentivize hospitals to adopt advanced surgical environments. Major hospital networks across New York and California are rapidly expanding their hybrid OR capabilities.
Japan
Japan's aging population contributes to an increasing need for precise anatomical assessment during neurovascular and orthopedic interventions. The Ministry of Health, Labour and Welfare (MHLW) provides guidelines for the adoption of advanced medical technologies. Leading medical institutions in Tokyo and Osaka are integrating sophisticated CT imaging systems within their hybrid suites.
China
China is undergoing significant healthcare infrastructure modernization, increasing demand for minimally invasive surgical techniques. The National Medical Products Administration (NMPA) governs the approval pathways for medical devices, impacting market entry. Major cities like Shanghai and Beijing are experiencing substantial investment in new hybrid OR installations to meet growing patient needs.
France
French healthcare providers require enhanced precision for oncology and trauma applications, driving hybrid OR adoption for improved patient outcomes. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) oversees medical device safety and performance. University hospitals in Paris and Lyon are adopting advanced imaging-guided surgical suites for complex procedures.
Hybrid Operating Room Market Key Industry Players
Technology integration dominates the current landscape, as market players seek to offer comprehensive solutions for advanced surgical environments. The market exhibits a tiered structure, with established medical technology giants alongside specialized providers focusing on specific components. Strategic partnerships and portfolio diversification are primary competitive moves.
Specialists in advanced imaging systems, such as Siemens Healthineers, represent a core segment, leveraging deep expertise in real-time visualization. Stryker Corporation exemplifies companies focusing on integrating orthopedic and neurological surgical equipment within the hybrid suite. Getinge AB occupies a position among providers specializing in the architectural and workflow components, including modular room systems and surgical lights.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| General Electric Company |
| Stryker Corporation |
| Steris PLC |
| Toshiba Corporation |
| Getinge AB |
| Trumpf Medical |
| Johnson & Johnson Services, Inc. |
| Others |
Cost & Logistics Intelligence
Hospital administrators' need for long-term managed equipment service agreements reshapes vendor go-to-market strategies. This demand drives suppliers to offer bundled operational contracts, directly impacting pricing structures.
Pricing Analysis
Volume-based pricing structures often apply to standard components, while complex hybrid OR installations utilize project-based models. Price differentiation stems from the high customization level required for integrated systems and comprehensive after-sales service packages. Pricing softness emerges from budget-constrained institutions evaluating mobile solutions as alternatives to fixed installations. Ambulatory Surgery Facilities exhibit high price sensitivity, whereas major academic medical centers prioritize advanced features over cost.
Supply Chain Analysis
China's increasing domestic content mandates are reshaping sourcing strategies for medical device components. Geographic supply concentrates in Germany for advanced imaging systems and the United States for specialized surgical equipment, while key electronic components often source from East Asia. The supply chain relies heavily on carbon fiber composites and advanced semiconductors, creating single-source vulnerability for critical imaging components. Distribution runs through direct sales channels to large hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hybrid operating room market is becoming a vertical-integration race as companies seek to control the entire surgical workflow. Players are pursuing software companion development to enhance system interoperability and data analytics capabilities.
For Market Incumbents:
Anchor market share by deepening strategic partnerships with IT providers for seamless data integration and cybersecurity. Investing in specialized talent training programs mitigates the critical talent shortage and reinforces customer loyalty. Incumbents must counter the threat of substitution from lower-cost mobile systems by highlighting long-term clinical benefits. Prioritize R&D in AI-driven surgical planning to maintain a technological edge.
For New Entrants and Emerging Players:
A price-point gap exists between premium fixed installations and basic mobile systems, creating entry opportunities. New entrants should target emerging markets in Latin America and Southeast Asia, where healthcare infrastructure build-outs are active. Focus on oncology and trauma applications, which represent expanding use cases beyond cardiology. Offer flexible, modular hybrid OR solutions to budget-constrained institutions, emphasizing faster deployment and scalability.
For Investors and Strategic Acquirers:
Re-rating potential sits with specialized software and AI firms given the increasing demand for integrated, data-rich surgical ecosystems. Long-term viability is strong due to sustained demand for minimally invasive procedures and improved patient outcomes. Investors should target niche imaging technology firms or companies with strong interoperability solutions. The signal to watch is the pace of regulatory approvals for AI-driven surgical planning tools, indicating market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Enhances interoperability between imaging systems and surgical navigation, improving workflow efficiency for Siemens Healthineers. |
| CE Marking Pathway | Ensures compliance with EU MDR, facilitating market access for advanced imaging equipment from General Electric Company. |
| Hospital System Partnership | Secures long-term contracts and integrates solutions within large networks, benefiting Getinge AB. |
| Geographic Expansion | Penetrates under-served regions like Latin America, expanding the customer base for Stryker Corporation. |
| Reimbursement Strategy | Aligns product offerings with favorable payment policies, driving adoption in the United States for Koninklijke Philips N.V. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, validated through primary interviews. Clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers provided direct insights. Secondary sources included hospital procurement databases, GPO contracts, EU MDR guidelines, and US FDA 510(k) clearances. This approach ensured robust bottom-up and top-down triangulation.
Market volume and value were modeled at granular levels for product type, technology, application, end user, and regional adoption patterns. The analytical framework projected growth across the analysis window, with CAGRs derived from historical trends and anticipated market dynamics. Healthcare capital expenditure budgets and procedural volume forecasts served as key inputs.
Inputs from regulatory bodies and industry associations were available through the study window; gaps in real-time hospital capital expenditure data introduce uncertainty bands. Forecasts reflect assumptions regarding economic stability and healthcare policy. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
Medical CO2 Carboxytherapy Machine Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Photorejuvenation Equipment Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
Refurbished Medical Equipment Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Global Medical Equipment Calibration Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market