
 Medical Oxygen Cylinders Market | 2026-2036
Medical Oxygen Cylinders Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Oxygen Cylinders Market Intelligence
Refill and maintenance subscription programs is expanding how oxygen cylinder vendors monetize patient relationships beyond one-time equipment sales. Linde plc leverages its global logistics network to control cylinder exchange infrastructure across multiple continents. Air Liquide sustains competitive positioning through backward integration into industrial gas production. Invacare Corporation specializes in portable cylinder formats for ambulatory home care patients.
Medical oxygen cylinders are pressure vessels constructed from aluminum alloy or seamless steel, designed to store and dispense compressed or liquid oxygen for therapeutic respiratory support at flow rates typically ranging from 0.5 to 15 liters per minute. Portable cylinders dominate unit volume in home care settings where patient mobility determines product selection, while stationary cylinders anchor hospital bulk installations with higher capacity and centralized manifold connections. Emergency services applications are growing fastest due to pre-hospital care expansion and ambulance fleet modernization programs.
FDA enforces 21 CFR Part 820 quality system regulations for medical gas container manufacturing, while ISO 7866 and ISO 9809 govern cylinder design, testing, and material certification for international market access. The EU Medical Device Regulation requires notified body intervention for oxygen delivery systems sold in European member states. Stakeholders must monitor evolving cylinder material standards as composite and lightweight aluminum designs challenge traditional steel construction economics.
Market Dynamics
Home care oxygen delivery is restructuring around refill subscription economics, compressing capital equipment margins while extending patient lifetime value through recurring consumable revenue streams.
Growth Catalysts
- Pre-hospital care expansion:Ambulance fleet modernization programs across India, Germany, and the United States are driving emergency services cylinder procurement. Mobile integrated healthcare initiatives mandate oxygen readiness for community paramedicine.
- ISO 13485 certification harmonization:Quality management standardization is accelerating cross-border trade in aluminum alloy cylinders. Manufacturers achieving dual FDA-ISO compliance capture hospital system contracts requiring documented traceability.
- Chronic respiratory patient mobility demand:Portable cylinder formats are displacing stationary concentrators for COPD patients requiring ambulatory oxygen. Lightweight aluminum construction enables 4-6 hour away-from-home therapy sessions.
Market Restraints
- Seamless steel raw material volatility:Alloy steel price fluctuations compress margin predictability for traditional cylinder manufacturers. Steel-dependent producers face working capital pressure during commodity spikes.
- EU Medical Device Regulation compliance costs:Notified body intervention requirements for oxygen delivery systems impose documentation and testing burdens. Small manufacturers exit European markets rather than absorb MDR transition expenses.
- Liquid oxygen bulk system substitution:Hospital centralized cryogenic installations are displacing high-capacity stationary cylinders in new construction. Bulk liquid infrastructure offers lower per-liter oxygen costs for high-volume clinical settings.
Strategic Opportunities
- Rural India home care penetration:Underserved districts lack oxygen access infrastructure for chronic respiratory patients. Portable cylinder distribution partnerships with primary health centers address last-mile delivery gaps.
- Composite cylinder material convergence:Carbon fiber-wrapped aluminum designs are emerging from aerospace pressure vessel technology. Weight reductions of 40-50% versus steel enable new ambulatory patient segments.
- PLI scheme manufacturing incentives:India's production-linked incentive program for medical devices subsidizes domestic cylinder fabrication. Localized production reduces import dependency for critical care infrastructure.
Industry Challenges
- Pressure vessel welder certification scarcity:Qualified technicians for seamless steel cylinder fabrication are concentrated in legacy industrial regions. Training pipeline gaps constrain capacity expansion timelines.
- Valve integration complexity:Regulator-cylinder compatibility testing across multiple flow rate specifications delays product launches. Integration failures in emergency field conditions damage brand reliability perceptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Oxygen Cylinders Market |
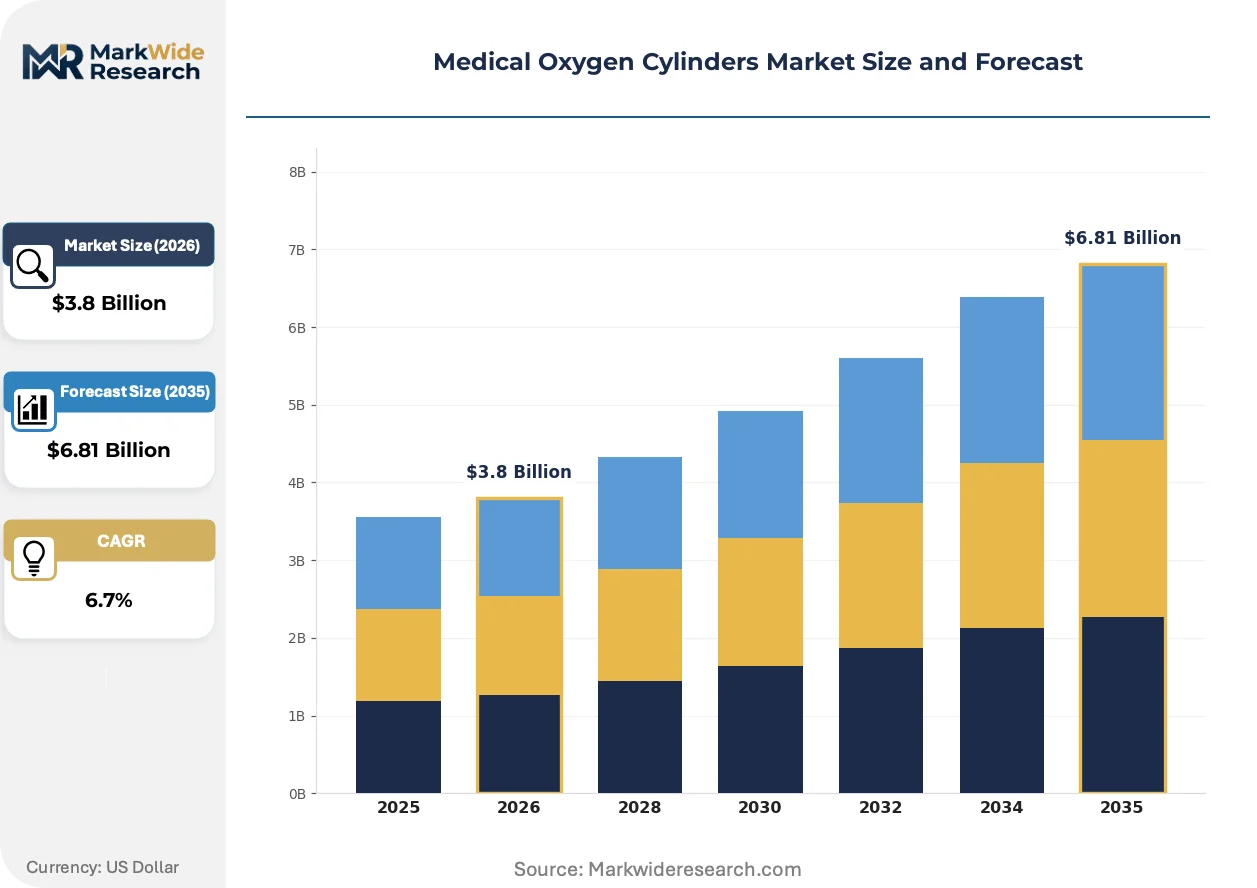
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Cylinders, Stationary Cylinders, Liquid Oxygen Systems, Oxygen Concentrators Application: Home Care, Hospitals, Emergency Services, Rehabilitation Centers End User: Patients, Healthcare Providers, Emergency Responders, Retail Pharmacies Distribution Channel: Direct Sales, Medical Supply Stores, Online Retail, Healthcare Institutions |
| Companies Covered | Linde plc, Air Liquide, Philips Healthcare, Drive DeVilbiss Healthcare, Invacare Corporation, Luxfer Gas Cylinders, Catalina Cylinders, Worthington Industries, Faber Industrie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Oxygen Cylinders Market Strategic Shifts & Innovations
Material science advances and regulatory harmonization are compressing product development cycles while fragmenting competitive advantage sources across manufacturing, logistics, and patient monitoring integration.
Composite pressure vessel technology is converging with medical oxygen containment requirements. Carbon fiber-reinforced polymer wrapping around aluminum liners achieves DOT certification for portable cylinders at sub-5-kilogram weights. Emergency medical services in Germany and the United States are piloting these formats for extended-duration field operations.
REACH substance restrictions are reshaping cylinder coating and valve seal material selection. Chromate conversion coatings face sunset dates, forcing manufacturers to validate alternative corrosion protection for aluminum alloy surfaces. European notified bodies are prioritizing biocompatibility documentation for new surface treatment chemistries.
Remote patient monitoring integration is altering home care oxygen service economics. Connected regulators transmitting flow rate and cylinder pressure data enable predictive refill scheduling. United States durable medical equipment suppliers are bundling telemetry-enabled cylinders with respiratory therapist telehealth consultations.
Medical Oxygen Cylinders Market Segmentation
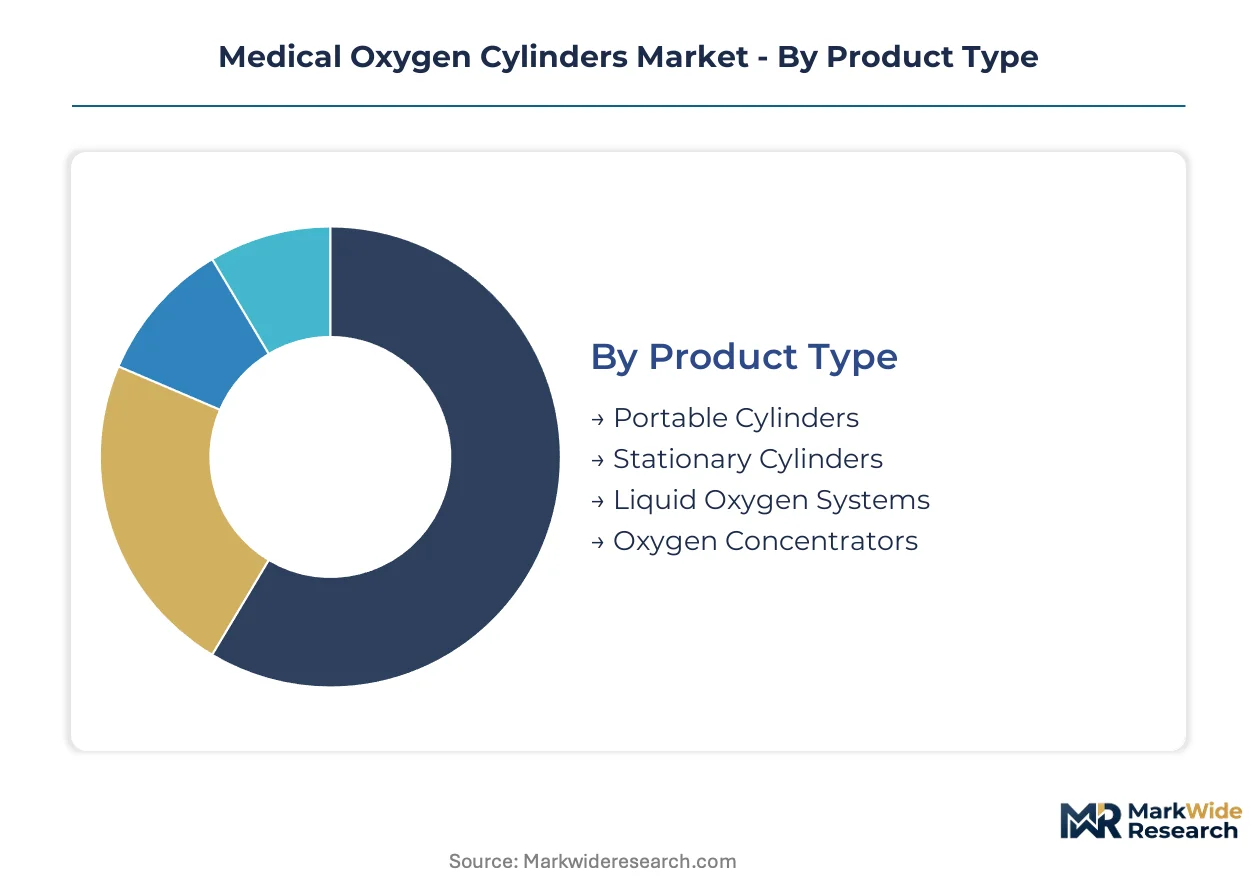
Product configuration determines reimbursement pathways and logistics infrastructure for oxygen cylinder vendors. Segmentation reveals how portability requirements, clinical setting specifications, and procurement channel economics fragment addressable markets across patient mobility and care delivery models.
Product Type:
Customization intensity spans from standardized hospital bulk systems to patient-specific portable formats with individualized flow regulators.
- Portable Cylinders:Aluminum alloy construction dominates at 2-5 liter capacities with pin-index valve systems. Demand concentrates among COPD patients in Germany and the United States pursuing ambulatory therapy outside clinical settings. Lightweight designs enabling 4-6 hour mobility sessions drive replacement cycles.
- Stationary Cylinders:Seamless steel pressure vessels with manifold connections serve hospital bulk installations at 20-50 liter capacities. Procurement clusters in India and the United States where centralized oxygen delivery infrastructure supports ICU and surgical suite requirements. Liquid oxygen bulk system substitution constrains new stationary cylinder placements in high-volume tertiary facilities.
- Liquid Oxygen Systems:Cryogenic storage with vaporization units supports high-consumption clinical environments through refillable base reservoirs.
- Oxygen Concentrators:Pressure swing adsorption technology generates oxygen from ambient air for stationary home care deployment.
Most installed capacity flows through Stationary Cylinders. Expansion is steepest in Portable Cylinders.
Application:
Revenue concentration shifts toward outpatient settings as hospital length-of-stay compression accelerates home care oxygen prescription.
- Home Care:Chronic respiratory patients manage long-term oxygen therapy through cylinder exchange programs or concentrator rental. Medicare durable medical equipment reimbursement in the United States and Germany's statutory health insurance fund coverage determine patient access economics. Refill subscription models are restructuring vendor monetization from capital equipment to recurring consumable revenue.
- Emergency Services:Pre-hospital care expansion across ambulance fleets and community paramedicine initiatives drives cylinder procurement. Mobile integrated healthcare mandates in India and the United States require oxygen readiness for field stabilization. Carbon fiber-wrapped portable formats are piloting for extended-duration operations.
- Hospitals:Centralized oxygen delivery through pipeline systems or bulk liquid storage dominates acute care settings.
- Rehabilitation Centers:Post-acute respiratory therapy programs utilize portable cylinders for patient mobility during pulmonary rehabilitation sessions.
Procurement volume concentrates in Home Care. Steepest expansion trajectory belongs to Emergency Services.
End User:
Decision-making authority fragments between prescribing clinicians, procurement departments, and direct patient choice depending on reimbursement structure.
- Healthcare Providers:Hospital systems and physician practices specify cylinder formats based on clinical workflow integration and FDA 21 CFR Part 820 quality documentation requirements. Group purchasing organizations in the United States aggregate demand for aluminum alloy cylinders with ISO 13485 certification.
- Patients:Direct purchasing concentrates in retail pharmacy channels for supplemental oxygen where insurance coverage gaps exist. Portability and weight specifications override brand loyalty in home care selection.
- Emergency Responders:Fire departments and ambulance services prioritize valve reliability and rapid cylinder exchange logistics over unit cost.
- Retail Pharmacies:Community pharmacy networks stock portable cylinders for cash-pay patients and travel oxygen needs.
Healthcare Providers command the largest procurement volume. Patient-directed purchasing is climbing the fastest as high-deductible health plans expand.
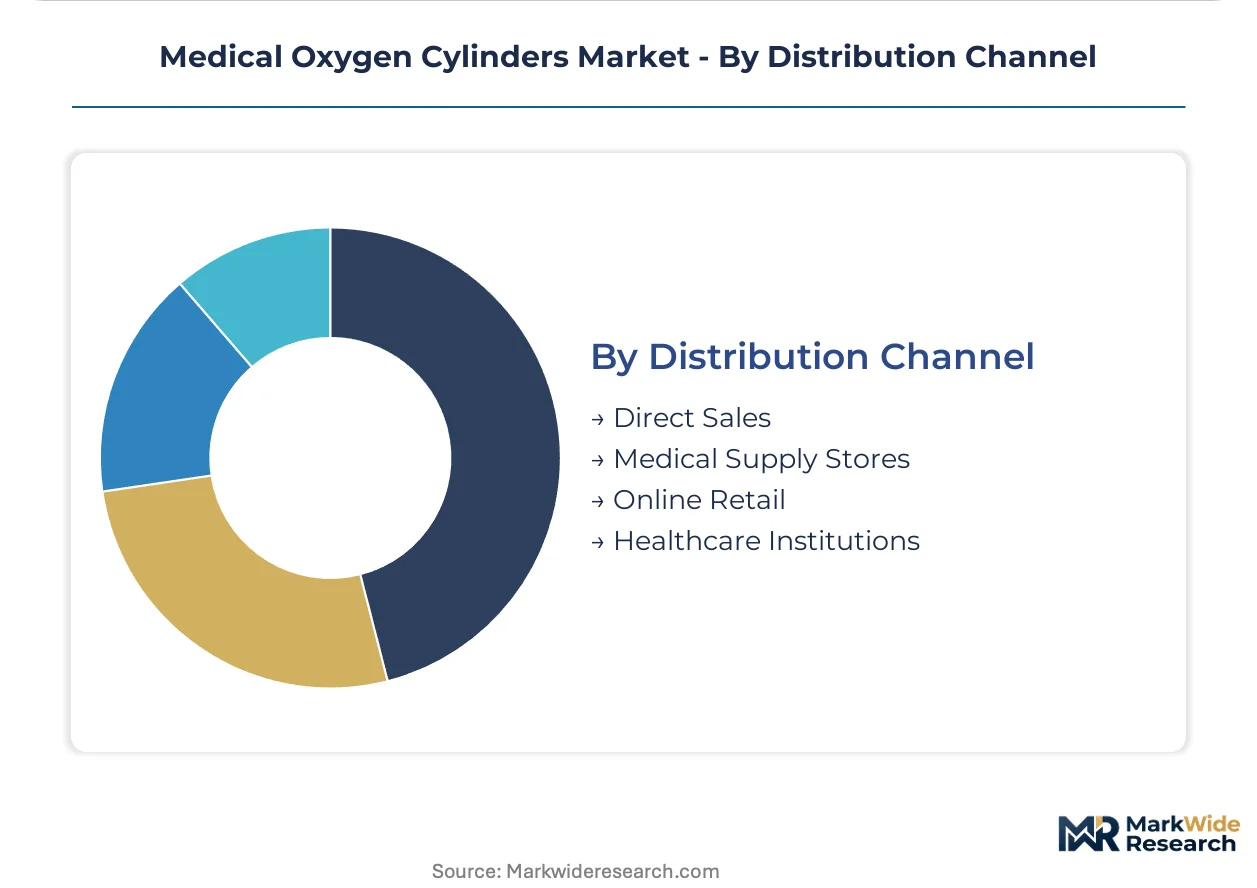
Distribution Channel:
Channel economics reflect working capital intensity and technical service requirements that favor specialized medical supply intermediaries.
- Direct Sales:Manufacturers like Linde plc and Air Liquide deploy field service engineers for hospital system contracts requiring cylinder exchange logistics and manifold maintenance. Long-term agreements with documented traceability compliance lock out distributor competition.
- Medical Supply Stores:Regional durable medical equipment suppliers bundle portable cylinders with respiratory therapist training and insurance documentation support. Medicare accreditation requirements filter store participation in funded patient segments.
- Online Retail:E-commerce penetration concentrates in travel oxygen accessories and cylinder carrying cases rather than pressurized vessels subject to hazardous shipping regulations.
- Healthcare Institutions:Integrated delivery networks negotiate direct cylinder supply with backward-integrated industrial gas producers.
Medical Supply Stores handle the greatest transaction volume. Direct Sales is gaining share fastest as hospital consolidation concentrates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance reimbursement structure generates more predictable home care cylinder demand than India's fragmented out-of-pocket payment landscape. The United States concentrates emergency services procurement through consolidated hospital networks. India's production-linked incentive schemes are accelerating domestic manufacturing capacity.
United States
Medicare durable medical equipment reimbursement drives portable cylinder adoption among COPD patients in Florida and Arizona retirement corridors. FDA 21 CFR Part 820 quality system enforcement shapes hospital procurement documentation requirements. Houston and Dallas medical supply clusters coordinate cylinder exchange logistics for ambulatory home care networks.
Germany
Stationary cylinder installations anchor hospital bulk oxygen systems in Bavaria and North Rhine-Westphalia industrial medical corridors. EU Medical Device Regulation notified body intervention mandates compliance documentation for valve-integrated delivery systems. Berlin-based respiratory equipment distributors manage refill subscription economics for statutory health insurance-covered patients.
India
PLI scheme manufacturing incentives subsidize domestic aluminum alloy cylinder fabrication in Gujarat and Maharashtra industrial zones. CDSCO medical device quality standards tighten pressure vessel certification requirements for hospital system suppliers. Bangalore and Hyderabad medical device clusters are expanding portable cylinder production for rural primary health center distribution partnerships.
China
NMPA medical device registration requirements govern oxygen cylinder import and domestic production licensing across Yangtze River Delta manufacturing hubs. GB standards for pressure vessel construction specify seamless steel and aluminum alloy testing protocols. Shanghai and Suzhou industrial gas equipment clusters supply centralized hospital manifold systems for tertiary care expansion.
Medical Oxygen Cylinders Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with backward-integrated industrial gas producers controlling hospital bulk installations while regional fabricators serve portable cylinder replacement demand. The vendor base concentrates around three strategic archetypes: global gas majors with captive cylinder production, dedicated pressure vessel manufacturers, and diversified medical equipment suppliers extending into respiratory therapy. Competitive positioning hardens through M&A consolidation of regional refill networks and capacity expansion into composite-wrapped lightweight formats.
Among global gas majors, Linde plc and Air Liquide exemplify the backward-integrated archetype through captive cylinder exchange infrastructure spanning multiple continents. Invacare Corporation occupies a position within the medical equipment specialist tier, representing portable format expertise for ambulatory patient segments. These three anchors illustrate how competitive advantage fragments across manufacturing scale, logistics density, and clinical workflow integration rather than concentrating in any single capability layer.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Philips Healthcare |
| Drive DeVilbiss Healthcare |
| Invacare Corporation |
| Luxfer Gas Cylinders |
| Catalina Cylinders |
| Worthington Industries |
| Faber Industrie |
| Others |
Cost & Logistics Intelligence
Hospital system consolidation in the United States is compressing procurement negotiation timelines and forcing cylinder manufacturers to absorb certification documentation costs that were previously passed through, eroding margin buffers in aluminum alloy portable formats.
Pricing Analysis
Capacity additions in India under the PLI scheme are reshaping price floors for aluminum alloy cylinders globally. Three-tier pricing structure across premium composite-wrapped, standard aluminum, and economy steel formats dominates the market, with ISO 13485 certification and FDA 21 CFR Part 820 compliance serving as the primary price differentiation drivers. Cost compression in economy steel cylinders is intensifying because alloy steel spot volatility transfers directly to fabricator working capital. Home care patients in Germany exhibit the highest price sensitivity due to statutory insurance reimbursement caps, while emergency services buyers in the United States prioritize valve reliability over unit economics.
Supply Chain Analysis
Pressure vessel welder certification scarcity in Gujarat and Maharashtra industrial zones constrains seamless steel cylinder expansion timelines. Manufacturing concentrates in India, China, and Germany, with raw material sourcing drawing from aluminum alloy smelters in the Yangtze River Delta and specialty steel mills in North Rhine-Westphalia. Single-source vulnerability in carbon fiber composite wrapping imports from aerospace suppliers poses structural risk for lightweight portable production. Distribution runs through hospital system direct contracts for bulk stationary formats and regional medical supply stores for ambulatory patient segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost arbitrage between India's PLI-subsidized domestic production and Europe's MDR documentation burdens creates geographic repositioning incentives for cylinder fabricators seeking margin preservation.
For Market Incumbents: Anticipate liquid oxygen bulk system substitution in tertiary hospital new construction by accelerating composite-wrapped portable development for emergency services field operations. Backward integration into aluminum alloy smelting in Gujarat secures input cost control against commodity volatility. Lock hospital system contracts through bundled telemetry-enabled regulator offerings that embed predictive refill scheduling and respiratory therapist telehealth consultations. For New Entrants and Emerging Players: E-commerce direct-to-patient channels bypass Medicare-accredited durable medical equipment intermediaries for travel oxygen accessories and cylinder carrying cases, avoiding hazardous shipping regulatory complexity for pressurized vessels. Rural India primary health center distribution partnerships represent the most penetrable white-space target, with portable cylinder refill subscription models enabling recurring revenue capture in districts lacking oxygen infrastructure. Position around lightweight aluminum construction for 4-6 hour ambulatory therapy sessions outside clinical settings. For Investors and Strategic Acquirers: Asymmetric upside sits with regional pressure vessel fabricators achieving dual FDA-ISO compliance that qualifies for United States hospital group purchasing organization contracts. The five-to-ten year viability window favors manufacturers with captive cylinder exchange logistics density across multiple continents. Monitor CDSCO medical device quality standard enforcement tightening as the inflection signal for Indian domestic production consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Cylinder Material Certification | DOT certification for carbon fiber-wrapped aluminum designs unlocks sub-5-kilogram emergency services procurement in Germany and the United States. |
| Refill Subscription Program Expansion | Recurring consumable revenue restructuring extends patient lifetime value beyond one-time portable cylinder equipment sales. |
| Rural Distribution Partnership Buildout | Primary health center alliances in underserved Indian districts address last-mile oxygen access gaps for chronic respiratory patients. |
| Telemetry-Enabled Regulator Integration | Connected flow rate and pressure data transmission enables predictive refill scheduling bundled with respiratory therapist telehealth consultations. |
| Backward Integration into Alloy Production | Captive aluminum smelting in Gujarat PLI-subsidized zones insulates margin predictability against commodity price spikes. |
Research Approach
Bottom-up home care and emergency services demand modeling reconciled against top-down cylinder fabrication capacity tracking forms the analytical core of this study. Primary interviews with hospital procurement committee members, biomedical engineers, GPO contracts managers, and respiratory equipment distributors combined with secondary validation against FDA 21 CFR Part 820 filings, CDSCO medical device registrations, and hospital procurement database extracts. Trade data from aluminum alloy and seamless steel customs records provided input cost trend verification.
Historical trendline analysis across portable, stationary, and liquid oxygen system shipment volumes established baseline growth patterns over the projection horizon. Segmentation modeling captured product type, application setting, end user decision authority, and distribution channel economics. CAGRs derived from fitted trend extrapolation adjusted for regulatory compliance cost inflections and material substitution dynamics. Forecast inputs incorporated ambulance fleet modernization program announcements and chronic respiratory patient mobility demand surveys.
The model assumes a particular technology adoption path; alternative pathways for composite pressure vessel convergence would alter the outlook. Forecasts reflect documented assumptions regarding PLI scheme continuation, MDR enforcement intensity, and alloy steel price volatility persistence. Material deviation in Medicare durable medical equipment reimbursement rates or EU notified body intervention timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Animal Operating Table Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Nuclear Medicine Equipment Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Medical Oxygen Systems Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
Europe Medical Device Reprocessing Market
Medical Equipment
Global Medical Equipment Calibration Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Global Blood Viscometer Market