
 Medical CO2 Carboxytherapy Machine Market | 2026-2036
Medical CO2 Carboxytherapy Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Medical CO2 Carboxytherapy Machine Market Insights
Trained aesthetic technicians is rotating toward shortage in several European markets, constraining clinic expansion and machine utilization rates. DTA Medical leverages in-house production of precision gas-flow modules to sustain margin control across its installed base. Maya Beauty Engineering anchors its position through geographic dominance in Southern European aesthetic chains. Axt Medical Systems differentiates via R&D intensity in digital dosing algorithms for pain-management protocols.
A medical CO2 carboxytherapy machine is a precision gas-delivery apparatus engineered to administer controlled subcutaneous or intradermal carbon dioxide at flow rates typically calibrated between 20 and 100 mL per minute and pressures below 1.5 bar, designed to stimulate localized vasodilation, collagen remodeling, and adipose-tissue metabolism for therapeutic and cosmetic outcomes. Portable devices command expanding share among mobile aesthetic practitioners seeking flexible deployment across multiple clinic sites. Stationary machines retain the dominant margin pool in hospital dermatology departments where throughput volume justifies capital investment. Automated administration technology is displacing manual systems in high-volume aesthetic centers seeking reproducible treatment parameters and reduced operator variability.
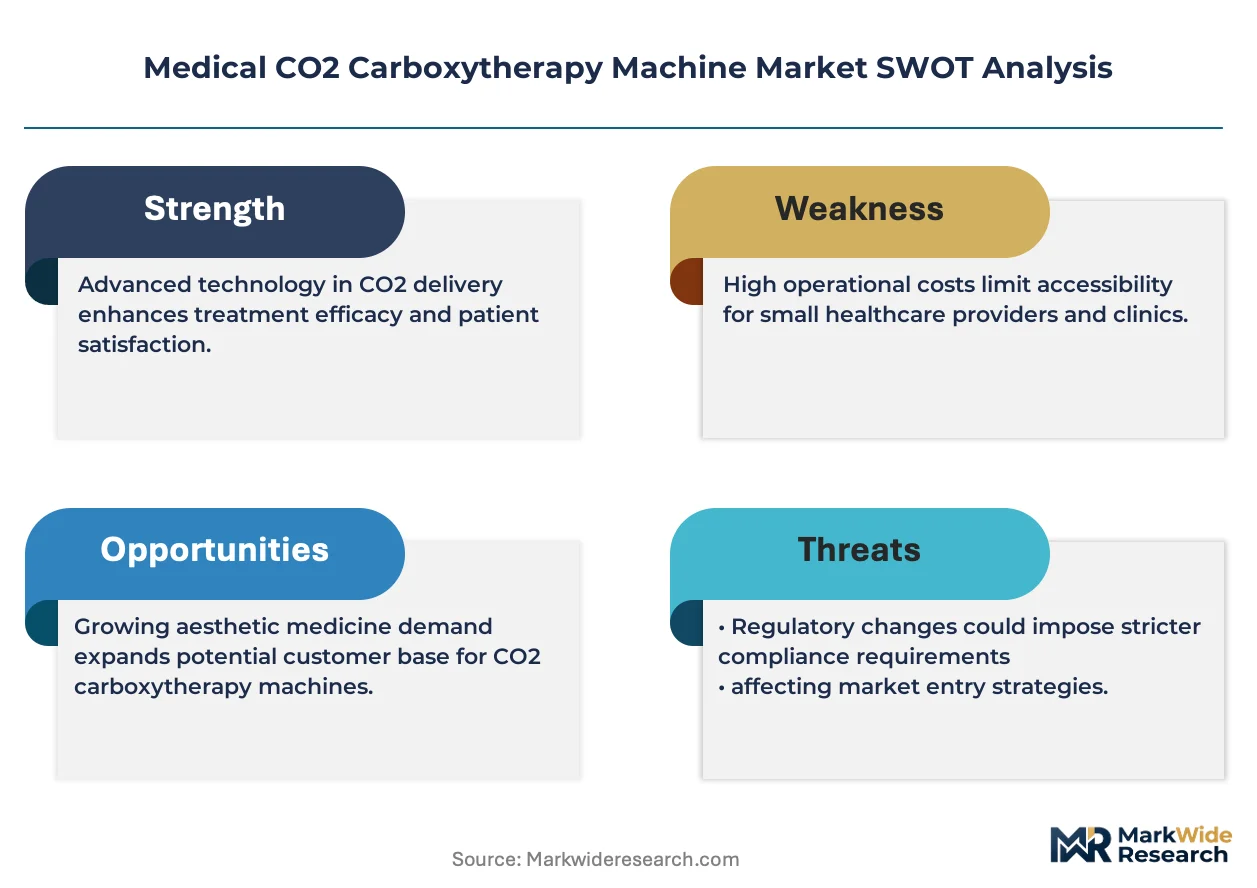
The EU Medical Device Regulation and CE marking framework govern market access, with notified bodies intensifying scrutiny of gas-pathway biocompatibility and electrical safety for Class IIa equipment. Germany's BfArM and France's ANSM coordinate post-market surveillance for adverse event reporting, shaping product liability exposure and design control documentation burdens for manufacturers. ISO 13485 quality management certification functions as a de facto prerequisite for supply contracts with institutional purchasers across the continent. Stakeholders must monitor evolving MDR transitional deadlines and notified body capacity constraints as these will determine competitive entry timelines and portfolio rationalization decisions.
Market Dynamics
The EU Medical Device Regulation's intensified scrutiny of Class IIa gas-administration equipment is compressing manufacturer certification timelines while simultaneously elevating documentation burdens, forcing portfolio rationalization across European supply chains.
Growth Catalysts
- MDR Compliance Thresholds:Tighter CE marking requirements for gas-pathway biocompatibility are filtering subscale competitors, concentrating procurement authority with ISO 13485-certified suppliers in institutional channels.
- Automated Dosing Algorithms:Digital flow-control modules enabling reproducible treatment parameters are accelerating adoption in high-volume aesthetic centers seeking reduced operator variability.
- Western European Clinic Density:Dermatology and aesthetic chains across Germany, France, and Italy are expanding carboxytherapy protocols for cellulite and stretch mark indications, sustaining equipment refresh cycles.
Market Restraints
- Notified Body Capacity Bottlenecks:MDR transitional deadlines have created queue congestion for Class IIa conformity assessments, extending time-to-market for new gas-delivery system submissions.
- Medical-Grade CO2 Supply Concentration:Regional dependence on specialized industrial gas distributors creates input cost volatility and purity-grade procurement friction for machine manufacturers.
- Manual System Substitution:Lower-cost pneumatic injection alternatives retain share in price-sensitive outpatient settings, constraining premium automated system penetration in certain clinic tiers.
Strategic Opportunities
- Portable Device Mobility:Compact, battery-capable units enabling multi-site deployment by independent aesthetic practitioners represent underpenetrated demand in mobile service segments.
- Pain Management Protocol Expansion:Subcutaneous CO2 administration for vasodilation in chronic pain applications offers regulatory pathway diversification beyond cosmetic indications.
- Southern European Chain Consolidation:Geographic dominance strategies targeting Spain, Portugal, and Italy's aesthetic network consolidation create white-space acquisition opportunities for equipment vendors.
Industry Challenges
- Trained Technician Scarcity:Certified aesthetic operator shortages across several European markets constrain clinic expansion velocity and machine utilization rates in newly equipped facilities.
- Legacy System Integration:Retrofitting automated dosing interfaces with existing clinic management software creates implementation friction and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical CO2 Carboxytherapy Machine Market |
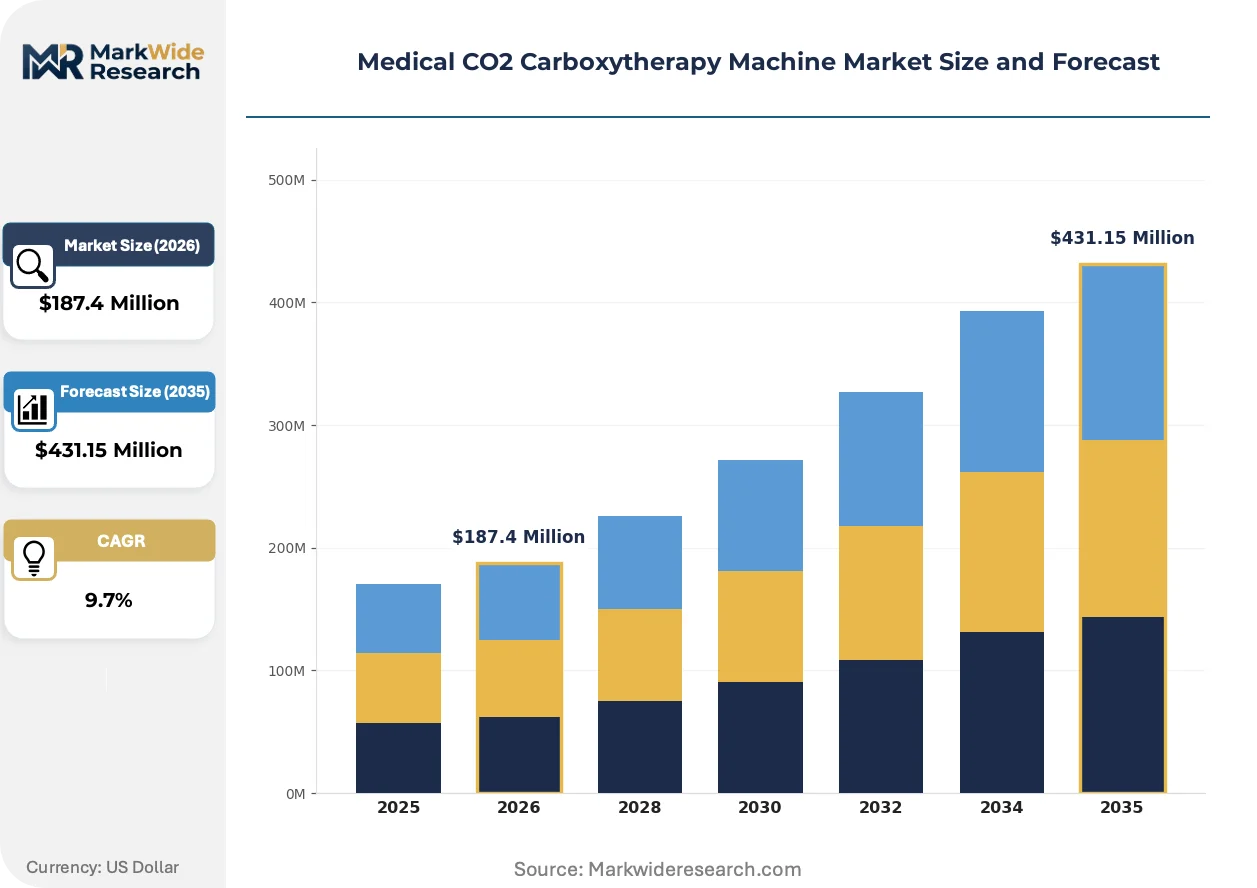
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Stationary Machines, Combination Units, Accessories Application: Aesthetic Treatments, Pain Management, Dermatology, Physiotherapy End User: Clinics, Hospitals, Aesthetic Centers, Rehabilitation Facilities Technology: Digital Controls, Manual Systems, Automated Administration, Hybrid Solutions |
| Companies Covered | DTA Medical, Maya Beauty Engineering, Axt Medical Systems, Wavemed, JonteLaser, BodyHT, DermoEquipos SRL, Mcure, MEZO Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical CO2 Carboxytherapy Machine Market Trends and Innovations
Digital dosing architectures and portable form factors are actively redrawing competitive boundaries, while regulatory documentation automation and service unbundling reshape vendor-client economics across the aesthetic equipment value chain.
Precision digital gas-flow control with real-time pressure feedback is fragmenting the traditional dichotomy between manual and fully automated systems. Mid-tier aesthetic centers in France and Germany are adopting semi-automated configurations that retain operator override capabilities while standardizing core parameters. This hybrid category is fragmenting procurement patterns, compressing pure manual system margins while delaying full automation adoption in budget-constrained settings.
The EU Medical Device Regulation's post-market surveillance requirements are tightening adverse event reporting obligations for gas-administration equipment. Germany's BfArM and France's ANSM coordinate cross-border vigilance data, elevating product liability exposure and design control documentation intensity. Stationary hospital dermatology departments face the steepest compliance adaptation costs as they maintain the largest installed bases requiring traceability retrofit.
After-sales service unbundling is accelerating as clinic procurement teams separate hardware acquisition from maintenance contracts and consumable supply agreements. Independent aesthetic practitioners in Italy and Spain increasingly source CO2 cartridges through third-party industrial gas distributors rather than captive vendor programs. This disintermediation compresses recurring revenue streams for original equipment manufacturers while expanding margin capture for specialized gas logistics providers.
Medical CO2 Carboxytherapy Machine Market Segmentation
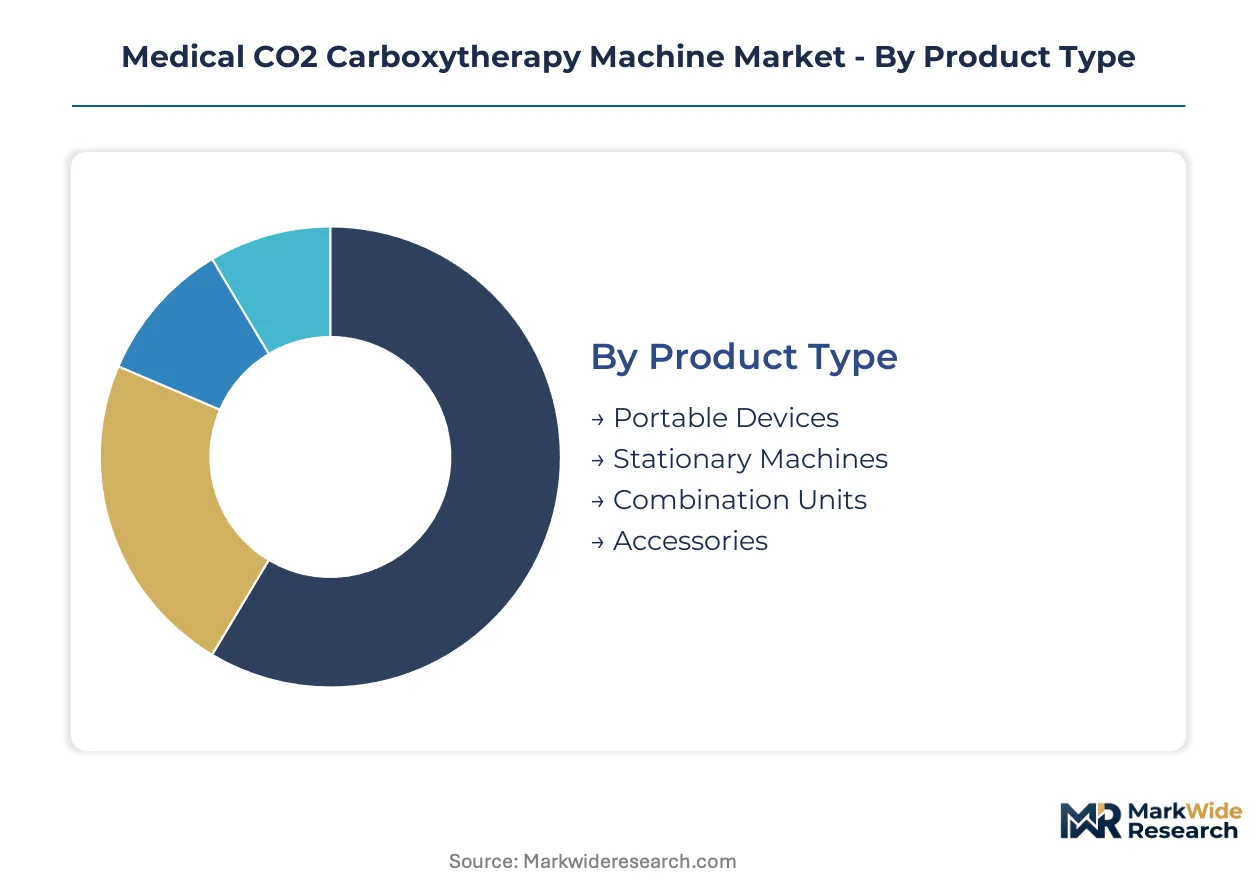
Carboxytherapy equipment segments distribute unevenly across procurement channels, with institutional purchasers favoring capital-intensive configurations while independent practitioners drive compact system demand. Understanding these flow patterns enables vendors to align certification investments and service architectures with actual buyer economics.
Product Type:
Portable devices flow primarily through distributor networks serving mobile aesthetic practitioners, while stationary machines concentrate in direct sales channels targeting hospital procurement departments.
- Portable Devices:Battery-capable units weighing under 8 kg enable multi-site deployment by independent practitioners across Germany, France, and Italy. Demand clusters in mobile service segments where clinic rental costs and flexible scheduling outweigh throughput requirements.
- Stationary Machines:High-throughput floor-standing systems with integrated gas cylinder housing and clinical-grade filtration dominate hospital dermatology departments in Western Europe. Capital investment justification depends on patient volume thresholds that amortize acquisition costs across treatment protocols.
- Combination Units:Modular platforms supporting both portable and fixed configurations serve mid-tier aesthetic chains seeking fleet standardization.
- Accessories:Disposable cannulas, gas filters, and calibration kits generate recurring revenue through captive supply agreements.
Stationary machines dominate installed base. Portable devices are where expansion concentrates.
Application:
Margin profiles diverge sharply across indication types, with aesthetic protocols commanding premium pricing and pain management applications requiring reimbursement navigation.
- Aesthetic Treatments:Cellulite reduction and stretch mark protocols in French and Italian aesthetic centers generate the highest per-procedure equipment utilization rates. Patient self-pay economics insulate demand from reimbursement volatility.
- Pain Management:Subcutaneous CO2 administration for vasodilation in chronic pain syndromes is gaining clinical validation in German rehabilitation networks. Regulatory pathway complexity and heterogeneous reimbursement coverage constrain penetration velocity.
- Dermatology:Hospital-based departments in Germany apply carboxytherapy for wound healing and microcirculation disorders within established clinical workflows.
- Physiotherapy:Sports medicine clinics in Spain and Portugal are piloting protocols for muscle recovery and localized inflammation management.
Aesthetic treatments command premium positioning. Pain management offers the steepest expansion trajectory.
End User:
Procurement authority and decision criteria vary substantially across facility types, shaping vendor sales cycle length and contract structure requirements.
- Clinics:Independent dermatology and aesthetic practices in France and Italy prioritize equipment financing flexibility and rapid technician training programs. Budget constraints favor semi-automated systems over full automation.
- Hospitals:German university hospitals and regional medical centers demand ISO 13485-certified suppliers with established MDR technical documentation. Procurement committees extend evaluation timelines but generate multi-unit orders.
- Aesthetic Centers:Corporate chains across Southern Europe standardize on specific brands to enable staff mobility and centralized service contracts.
- Rehabilitation Facilities:Post-acute care providers in Germany evaluate carboxytherapy for adjunctive pain management within bundled payment frameworks.
Hospitals anchor revenue stability. Aesthetic centers are climbing the fastest.
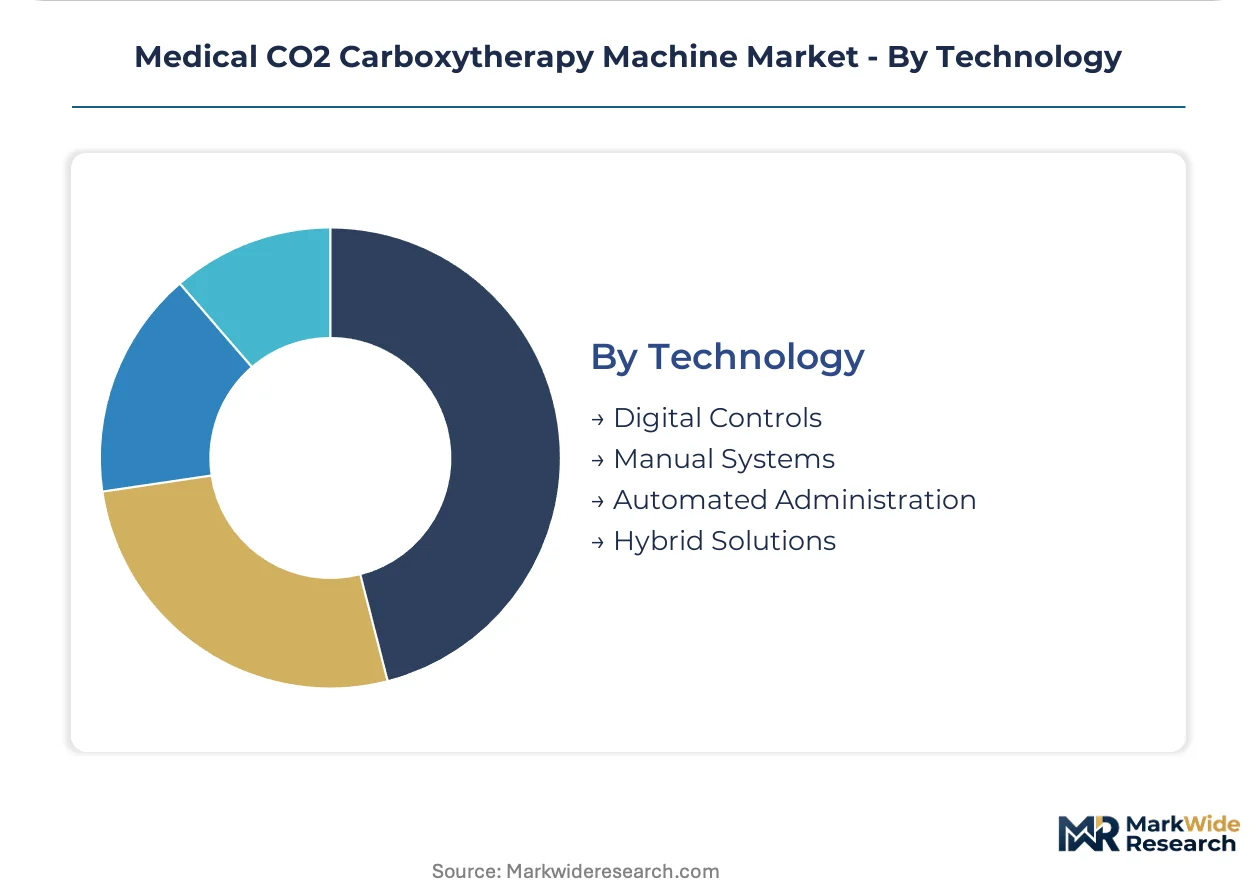
Technology:
Control architecture selection determines regulatory classification burden and aftermarket service intensity across the installed base.
- Digital Controls:Microprocessor-based flow regulation with touchscreen interfaces enables parameter logging for MDR traceability requirements. German clinics lead adoption of connectivity-enabled units supporting remote diagnostics.
- Manual Systems:Pneumatic mechanical regulators retain share in price-sensitive Southern European outpatient settings where operator training costs exceed automation premiums.
- Automated Administration:Closed-loop pressure feedback systems with programmable treatment protocols are displacing manual alternatives in high-volume French aesthetic chains seeking reproducible outcomes.
- Hybrid Solutions:Semi-automated configurations preserving operator override capabilities capture mid-tier budgets across Italian clinic networks.
Digital controls anchor technology roadmaps. Hybrid solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MDR transitional deadlines are compressing certification timelines across European markets while aesthetic clinic expansion in Germany, France, and Italy sustains equipment procurement velocity.
Germany
BfArM coordinates post-market surveillance for Class IIa gas-administration equipment alongside ANSM in France. The country's rehabilitation networks are piloting subcutaneous CO2 protocols for chronic pain management within bundled payment frameworks. Munich and Berlin host the densest concentrations of hospital dermatology departments refreshing stationary machine fleets.
France
ANSM intensifies scrutiny of gas-pathway biocompatility documentation for CE marking renewals. Parisian aesthetic chains are standardizing on semi-automated configurations that preserve operator override capabilities. The Île-de-France corridor generates the highest per-procedure utilization rates for cellulite and stretch mark protocols.
Italy
Southern European clinic consolidation is accelerating procurement centralization across Milan, Rome, and Naples aesthetic networks. Independent practitioners increasingly source CO2 cartridges through third-party industrial gas distributors rather than captive vendor programs. Rome-based chains are driving demand for modular platforms supporting fleet standardization.
Spain
Sports medicine clinics in Barcelona and Madrid are piloting carboxytherapy protocols for muscle recovery and localized inflammation management. The country's national pharmaceutical regulator maintains vigilance coordination with EMA for adverse event reporting. Andalusian aesthetic centers favor portable devices enabling multi-site deployment by mobile practitioners.
United Kingdom
MHRA operates under retained EU law for medical device oversight while adapting to independent market surveillance frameworks. London dermatology departments prioritize ISO 13485-certified suppliers with established MDR technical documentation. The Southeast England corridor concentrates demand for high-throughput floor-standing systems in hospital procurement channels.
Medical CO2 Carboxytherapy Machine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former controlling precision gas-flow module production and the latter competing on regional service density. The vendor base stratifies across three archetypes: in-house manufacturers of dosing hardware, geographic aggregators serving aesthetic chains, and algorithm-focused developers targeting pain-management protocols. Competitive moves center on backward integration into gas-pathway components and geographic tuck-in acquisitions serving Southern European consolidation.
Within the integrated manufacturing tier, DTA Medical exemplifies captive production of precision gas-flow modules for margin control across installed bases. Maya Beauty Engineering occupies a position as a geographic aggregator anchored in Southern European aesthetic chain consolidation. Axt Medical Systems represents the R&D-intensive archetype, with its nomenclature suggesting specialization in algorithmic dosing systems for therapeutic applications.
| Leading Market Players |
|---|
| DTA Medical |
| Maya Beauty Engineering |
| Axt Medical Systems |
| Wavemed |
| JonteLaser |
| BodyHT |
| DermoEquipos SRL |
| Mcure |
| MEZO Pharma |
| Others |
Pricing and Supply Chain Analysis
Long-term service bundling contracts lock in CO2 cartridge supply visibility for German hospital procurement committees while capping annual price escalation for precision gas-flow modules. These arrangements tether equipment vendors to specialized industrial gas distributors across Western Europe, embedding purity-grade certification costs into multi-year agreements.
Pricing Analysis
Price spreads between Northern and Southern European markets reflect divergent certification burdens under MDR transitional deadlines. Three-tier pricing structure across premium automated, semi-automated, and manual pneumatic systems separates ISO 13485-certified hospital installations from budget-conscious Italian outpatient clinics. Cost compression in manual system tiers is intensifying as third-party gas distributors disintermediate captive vendor programs. Independent aesthetic practitioners in Spain exhibit the highest price sensitivity, while German university hospitals prioritize technical documentation over unit economics.
Supply Chain Analysis
Germany and Italy anchor precision gas-flow module production for the European installed base, with Czech Republic emerging as a secondary machining hub for pressure-regulator components. Manufacturing draws from medical-grade aluminum alloys, specialized polymer seals, and microprocessor control boards. Single-source vulnerability concentrates in notified body capacity for Class IIa conformity assessments. Distribution runs through direct sales channels for hospital procurement and distributor networks serving mobile practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment refresh cycles across Western European aesthetic chains signal cyclical recovery momentum, with MDR compliance deadlines compressing replacement timelines for legacy manual systems.
For Market Incumbents: Fortify margin control through captive production of gas-pathway biocompatibility components, insulating against industrial gas distributor pricing power. Accelerate ISO 13485 certification investments ahead of notified body queue congestion. Prioritize backward integration into precision flow-module manufacturing to offset disintermediation risk from third-party cartridge suppliers. For New Entrants and Emerging Players: MDR fast-track pathways for Class IIa automated dosing systems unlock procurement access in French aesthetic chains seeking reduced operator variability. Target portable device segments in Spanish mobile practitioner networks where clinic rental economics favor flexible deployment. Pursue white-space acquisition in Southern European chain consolidation through algorithm-focused positioning for pain-management protocols. For Investors and Strategic Acquirers: Algorithm-specialist developers with validated dosing architectures for therapeutic applications present asymmetric upside within a five-to-ten-year regulatory diversification window. Monitor notified body capacity expansion as the inflection signal for competitive entry velocity and portfolio rationalization decisions.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance for Class IIa gas-administration equipment unlocks institutional procurement channels in Germany and France. |
| Hospital System Partnership | Multi-unit fleet standardization agreements with Berlin and Munich dermatology departments anchor recurring revenue stability. |
| Software Companion Development | Digital dosing algorithms with remote diagnostic connectivity address BfArM post-market surveillance requirements. |
| Backward Integration | In-house production of precision gas-flow modules defends margin compression from specialized industrial gas distributors. |
| Reimbursement Strategy | Clinical validation for chronic pain protocols in German rehabilitation networks diversifies beyond aesthetic self-pay economics. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committee members, aesthetic clinic operators, and industrial gas distribution specialists converged on the working assumptions for installed base sizing and replacement velocity. Primary fieldwork across Germany, France, Italy, and Spain was cross-referenced with secondary validation from EMA vigilance databases, notified body capacity registers, hospital procurement contract disclosures, and ISO 13485 certification records. Bottom-up equipment unit estimates were triangulated against top-down aesthetic clinic expansion metrics.
Segmentation dimensions modeled span product type, application indication, end-user facility category, and control technology architecture across the projection horizon. CAGRs were derived from treatment protocol adoption curves and equipment refresh cycle analysis. Forecast inputs incorporated MDR transitional deadline impacts on competitive entry timelines and regional clinic density projections for cellulite and stretch mark service expansion.
Underlying assumptions cover notified body capacity recovery, medical-grade CO2 supply continuity, and aesthetic technician training program scaling, with deviation risk concentrated in regulatory deadline extensions or gas distributor consolidation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Automated Dialysis Concentrated Production Systems Market
Medical Equipment
Global Microtome Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
Europe Medical Carts Market
Medical Equipment
Nuclear Medicine Equipment Market
Medical Equipment
Blood Bank Refrigerators Market
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
Refurbished Medical Equipment Market