
 Australia Computed Tomography Market | 2026-2036
Australia Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Computed Tomography Market Outlook
The capability gap between high-end spectral imaging platforms and conventional scanner portfolios is collapsing as vendors race to commercialize photon-counting detectors. Siemens Healthineers anchors its position through deep R&D investment in dual-source architectures, while GE Healthcare leverages its established service infrastructure across Australian hospital networks. Canon Medical Systems competes by specializing in compact, high-throughput systems tailored to outpatient clinic workflows.
Computed tomography is a diagnostic imaging modality that reconstructs cross-sectional anatomical views from multiple X-ray projections, with modern systems achieving sub-millimeter spatial resolution and temporal resolutions under one rotation second. Its primary purpose is to enable non-invasive visualization of soft tissue, vasculature, and bone for clinical diagnosis and treatment planning. Stationary CT systems occupy the mature core of hospital radiology departments where replacement cycles drive predictable revenue, while photon-counting CT represents the fastest-expanding technology dimension as clinicians pursue reduced radiation dose with enhanced spectral discrimination. Mobile CT units are gaining structural importance in regional Australia where fixed infrastructure gaps limit patient access to stroke and trauma protocols.
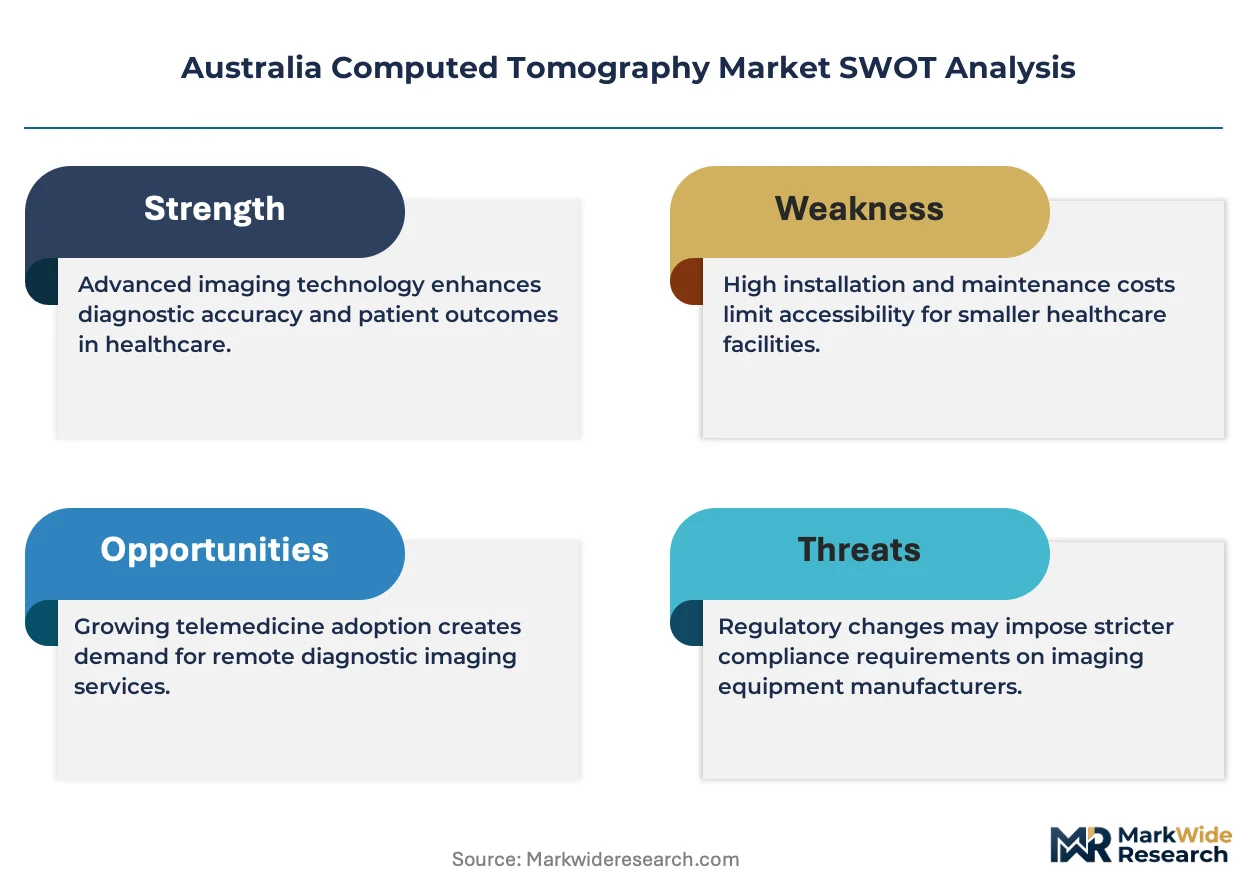
TGA medical device conformity requirements and the Australian Radiation Protection and Nuclear Safety Agency standards govern CT system approval, installation shielding, and operator certification, creating compliance barriers that favor established suppliers with local regulatory expertise. The Medical Technology Association of Australia engages actively with reimbursement frameworks to secure favorable prostheses list coverage for advanced CT applications. Stakeholders must monitor how Medicare Benefits Schedule revisions for diagnostic imaging services reshape hospital capital allocation priorities between scanner replacement and modality expansion.
Market Dynamics
Photon-counting detector maturation is compressing the performance premium once commanded by spectral CT platforms, forcing incumbent vendors to defend installed base revenue through service contract restructuring and modular detector upgrades rather than greenfield scanner placements.
Growth Catalysts
- Cardiac imaging protocol expansion:Tertiary centers across New South Wales and Victoria are adding cardiac CT angiography suites to capture coronary artery disease referrals previously directed to invasive catheterization labs.
- TGA streamlined registration:The Therapeutic Goods Administration's priority review pathway for breakthrough medical devices accelerates market entry for photon-counting CT systems, reducing pre-market approval timelines for advanced modalities.
- Regional stroke network mandates:State health departments in Queensland and Western Australia are mandating 24-hour CT availability for thrombectomy-eligible stroke patients, creating procurement pressure on regional hospitals.
Market Restraints
- Helium supply concentration:Superconducting magnet cooling depends on helium sourced from limited global refining capacity, exposing Australian operators to price volatility and allocation disruptions.
- Shielding construction bottlenecks:Lead and concrete radiation shielding installation faces qualified contractor shortages in Perth and Adelaide, extending project timelines for new CT suite deployments.
- Interventional radiology substitution:MRI and ultrasound-guided biopsy systems are capturing certain tissue characterization applications previously referred to contrast-enhanced CT protocols.
Strategic Opportunities
- Mobile stroke unit deployment:Regional Victoria and Tasmania present underpenetrated geographies where truck-mounted CT scanners can compress time-to-imaging for rural stroke patients.
- AI-integrated workflow automation:Convergence of deep learning reconstruction algorithms with photon-counting raw data streams enables automated organ segmentation and dose optimization without radiologist intervention.
- Outpatient imaging center expansion:Private equity-backed day hospitals in Sydney's outer suburbs are creating new channel demand for compact, high-throughput systems with minimal facility modification requirements.
Industry Challenges
- Medical physicist certification scarcity:Australian Radiation Protection and Nuclear Safety Agency accreditation requirements for CT quality assurance testing outpace university training program output, creating service backlogs.
- Legacy PACS integration complexity:Photon-counting CT spectral datasets exceed storage and transmission specifications of decade-old picture archiving systems deployed across public hospital networks, forcing costly middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Computed Tomography Market |
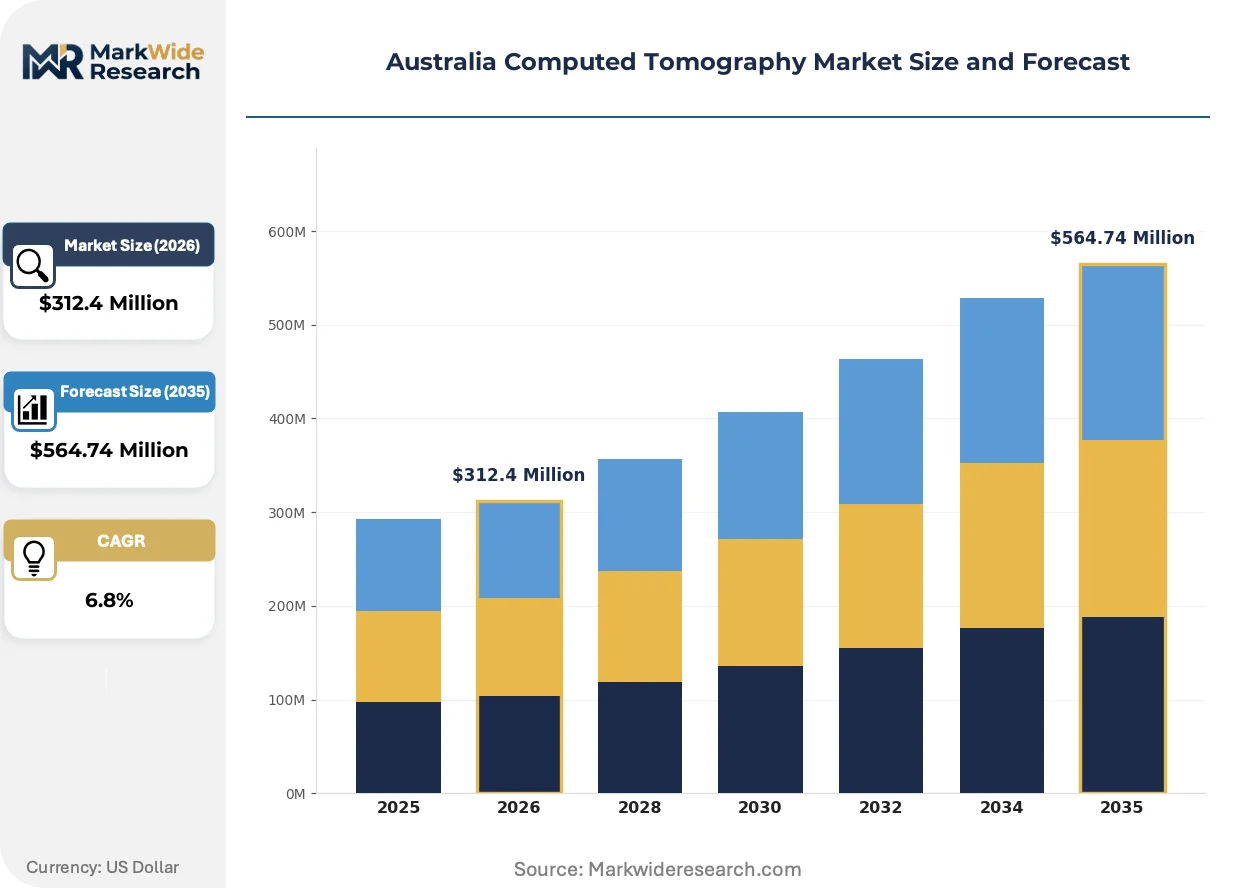
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile CT, Cone Beam CT, Stationary CT, Helical CT End User: Hospitals, Diagnostic Imaging Centers, Outpatient Clinics, Research Institutions Technology: X-ray CT, MRI-CT Integration, Dual-Energy CT, Photon-Counting CT Application: Oncology, Neurology, Cardiology, Musculoskeletal |
| Companies Covered | Siemens Healthineers AG, Koning Corporation, GE Healthcare, United Imaging, Samsung Electronics Co., Ltd., Koninklijke Philips NV, Planmeca Group, Canon Medical Systems Corporation, Carestream Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Computed Tomography Market Strategic Shifts
Detector technology advancement is fragmenting the traditional scanner tier structure, while reimbursement recalibration and procurement centralization are compressing vendor pricing power across Australian health systems.
Photon-counting CT is bifurcating the premium scanner segment from conventional energy-integrating platforms. Metropolitan teaching hospitals in Melbourne and Sydney are adopting the technology for dual-energy cardiac and oncology protocols. The capability gap between high-end and mid-range systems is collapsing as vendors commercialize cost-reduced photon-counting detector arrays.
TGA's alignment with International Medical Device Regulators Forum technical documentation standards is reducing redundant conformity assessment burdens for manufacturers with existing FDA or CE markings. This regulatory convergence accelerates product lifecycle synchronization between Australian and northern hemisphere markets. Multinational vendors are prioritizing TGA submissions for flagship systems simultaneously with US and EU launches.
Hospital procurement departments are consolidating CT acquisition decisions into centralized capital equipment committees, displacing radiology department autonomy in vendor selection. New South Wales Health's shared services model aggregates statewide purchasing volume, compressing unit pricing and standardizing service contract terms. Private hospital groups are replicating this centralization, favoring vendors with national service infrastructure over regional specialists.
Australia Computed Tomography Market Segmentation
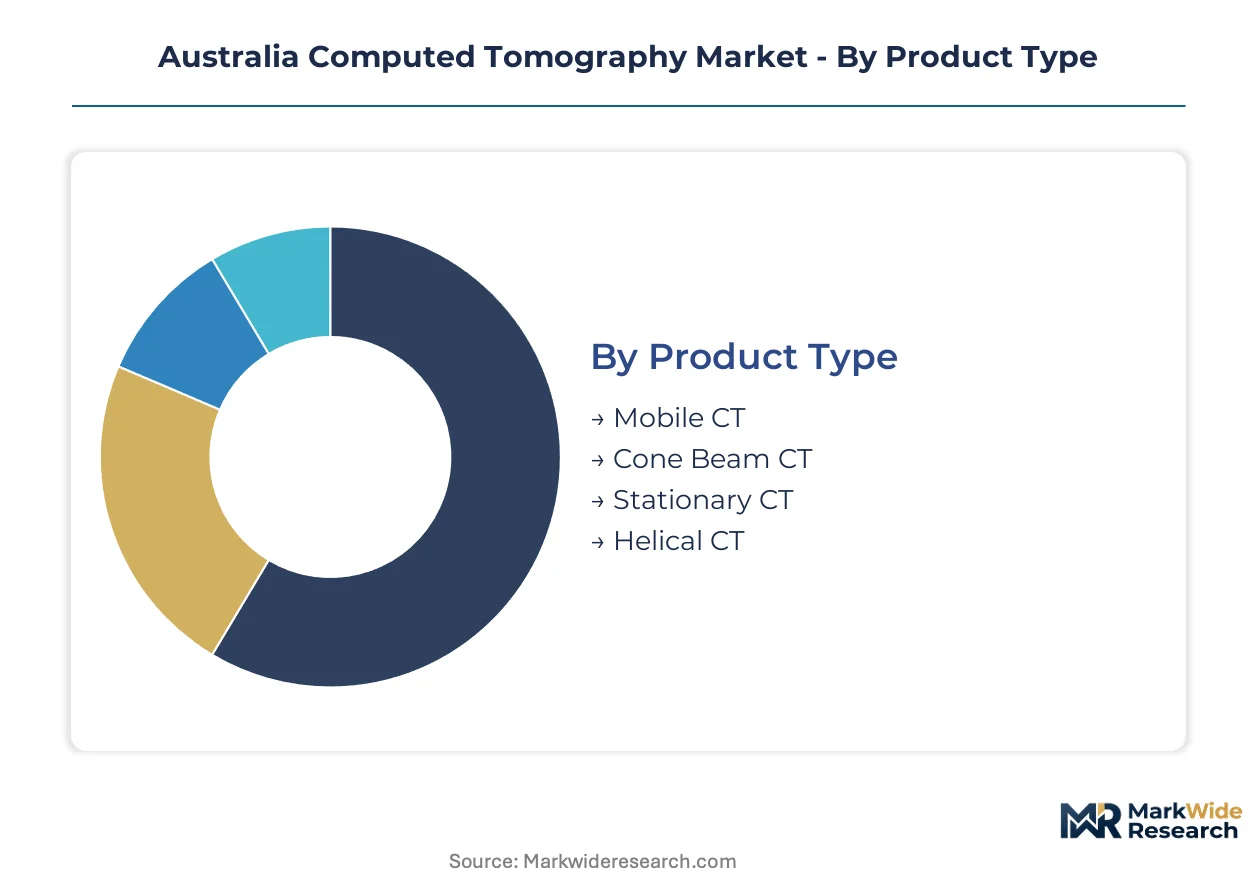
CT procurement patterns across Australian healthcare facilities diverge sharply between metropolitan tertiary centers and regional networks, with technology selection, end-user requirements, and clinical applications each following distinct geographic logics that vendors must navigate.
Product Type:
Mobile CT systems dominate procurement in rural Queensland and Western Australia where fixed infrastructure gaps persist, while stationary platforms concentrate in Sydney and Melbourne hospital replacement cycles.
- Stationary CT:Fixed-installation systems with gantry-mounted rotating X-ray tubes and detector arrays achieve sub-millimeter spatial resolution for complex cardiac and oncologic protocols. New South Wales and Victorian public hospitals are expanding fleet replacement programs to address diagnostic backlogs, with tertiary centers prioritizing dual-source architectures for high-throughput emergency departments.
- Mobile CT:Truck-mounted or trailer-based systems with self-contained power and climate control enable point-of-care imaging in regional stroke networks. Queensland Health mandates 24-hour CT availability for thrombectomy-eligible patients across rural catchments, driving procurement of deployable units that bypass shielding construction bottlenecks.
- Cone Beam CT:Compact systems with flat-panel detectors optimized for high-resolution dental and maxillofacial imaging occupy outpatient clinic niches.
- Helical CT:Continuous patient translation during rotation enables rapid whole-body trauma assessment in busy metropolitan emergency departments.
Stationary CT holds the largest share; momentum sits with Mobile CT as regional network mandates expand.
End User:
Cost tier differentiation separates capital-intensive hospital procurement from lean outpatient clinic requirements, with diagnostic imaging centers occupying the mid-market where throughput optimization drives technology selection.
- Hospitals:Public tertiary centers in Sydney, Melbourne, and Brisbane operate the highest scanner densities, with cardiac CT angiography suites capturing coronary artery disease referrals from invasive catheterization labs. New South Wales Health's shared services model aggregates statewide purchasing volume, compressing unit pricing for premium photon-counting systems.
- Diagnostic Imaging Centers:Private equity-backed day hospitals in Sydney's outer suburbs are creating new channel demand for compact, high-throughput systems with minimal facility modification requirements.
- Outpatient Clinics:Specialist practices prioritize compact footprint systems with rapid installation timelines.
- Research Institutions:University-affiliated medical schools in Melbourne and Sydney drive early adoption of spectral imaging protocols for quantitative biomarker development.
Hospitals command the dominant revenue position; diagnostic imaging centers are climbing the fastest as private outpatient infrastructure expands.
Technology:
Application intensity varies across clinical domains, with cardiac and oncology protocols demanding spectral discrimination capabilities that conventional energy-integrating detectors cannot deliver.
- Photon-Counting CT:Direct X-ray photon detection with energy discrimination enables material decomposition and reduced radiation dose. TGA's priority review pathway for breakthrough medical devices accelerates market entry, with metropolitan teaching hospitals in Melbourne and Sydney adopting the technology for dual-energy cardiac and oncology protocols.
- Dual-Energy CT:Rapid kVp switching or dual-source acquisition generates material-specific images for gout characterization and urinary stone composition analysis.
- X-ray CT:Conventional energy-integrating detectors remain the workhorse technology for routine diagnostic protocols in regional hospitals.
- MRI-CT Integration:Hybrid imaging systems for radiation therapy planning occupy niche applications in comprehensive cancer centers.
X-ray CT maintains installed base dominance; photon-counting CT shows the steepest expansion trajectory as TGA pathways streamline premium system adoption.
Application:
Customer type segmentation reveals divergent procurement authority structures, with radiology department autonomy giving way to centralized capital equipment committees that standardize vendor selection criteria.
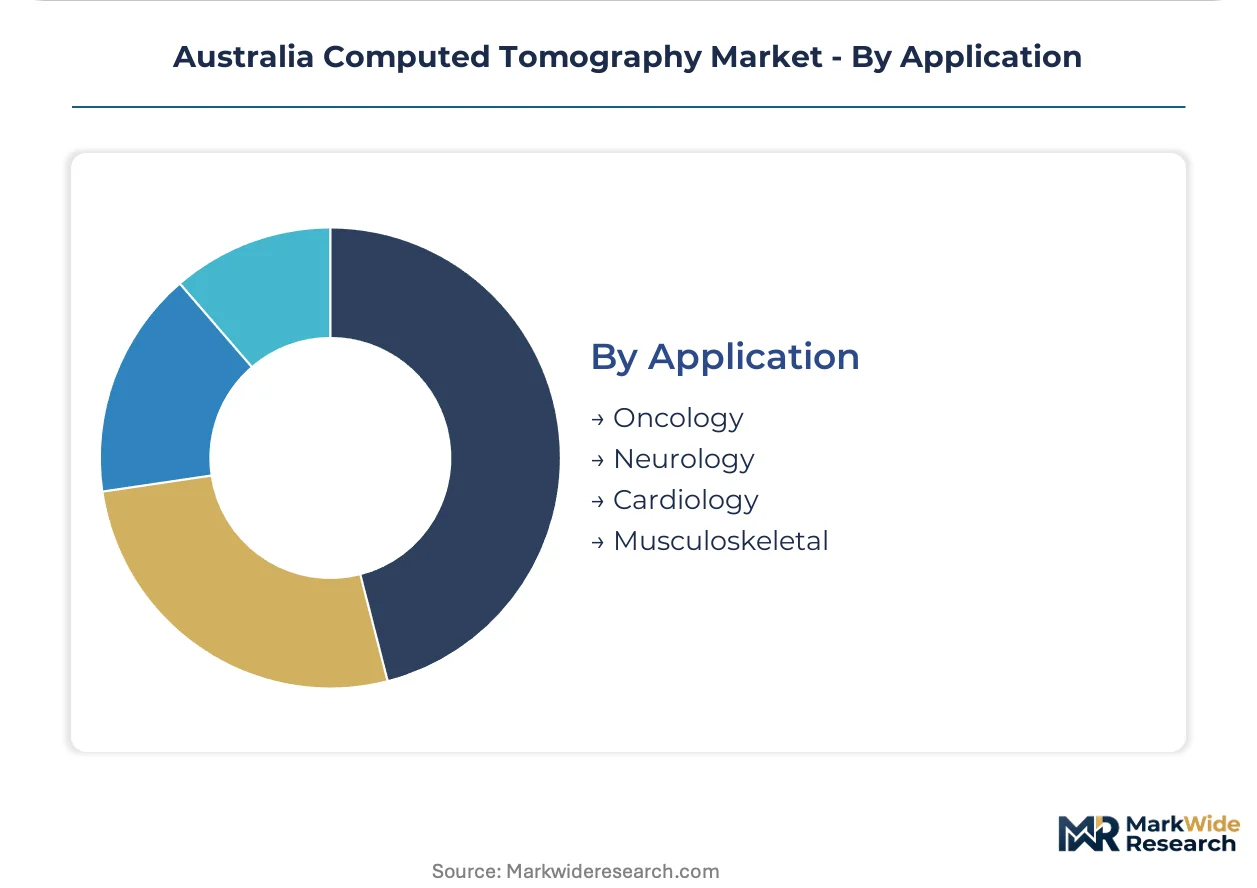
- Oncology:Staging and treatment response assessment drives demand for spectral discrimination and quantitative perfusion imaging. Comprehensive cancer centers in Sydney and Melbourne prioritize photon-counting detectors for dual-energy iodine mapping and virtual non-contrast imaging protocols.
- Cardiology:Coronary CT angiography expansion captures referrals from invasive catheterization labs, with tertiary centers across New South Wales and Victoria adding dedicated cardiac suites.
- Neurology:Stroke protocol compliance mandates 24-hour CT availability across Queensland and Western Australia regional networks.
- Musculoskeletal:Trauma and orthopedic planning applications favor high-resolution volumetric imaging in metropolitan emergency departments.
Oncology holds the largest share; cardiology is gaining share fastest as non-invasive coronary assessment protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan tertiary centers in New South Wales and Victoria command premium pricing power for photon-counting CT systems, while regional hospitals in Queensland and Western Australia face cost compression from mobile unit procurement mandates.
New South Wales
Tertiary centers across Sydney and Newcastle are expanding cardiac CT angiography suites to capture coronary referrals from invasive catheterization labs. TGA streamlined registration pathways accelerate premium system adoption. The Sydney metropolitan cluster concentrates the highest scanner density, with public hospital shared services aggregating statewide purchasing volume.
Victoria
Melbourne teaching hospitals drive early adoption of spectral imaging protocols for quantitative biomarker development. Victorian Department of Health procurement centralization compresses unit pricing through standardized service contracts. The Melbourne metropolitan area anchors diagnostic imaging infrastructure, with regional stroke network mandates extending mobile CT deployment to Ballarat and Bendigo.
Queensland
State health department mandates for 24-hour CT availability across rural catchments drive mobile unit procurement. Queensland Health bypasses shielding construction bottlenecks through deployable truck-mounted systems. The Brisbane-Gold Coast corridor maintains fixed-installation concentration, while regional networks prioritize thrombectomy-eligible stroke protocol compliance.
Western Australia
Perth faces qualified contractor shortages for lead and concrete radiation shielding installation, extending new CT suite deployment timelines. Western Australia Country Health Service mandates compress time-to-imaging for rural stroke patients through mobile unit networks. The Perth metropolitan area concentrates tertiary diagnostic capacity, with regional procurement focused on bypassing infrastructure gaps.
South Australia
Adelaide hospitals contend with similar shielding construction bottlenecks that delay stationary system installations. South Australian Health's procurement patterns favor compact, high-throughput systems requiring minimal facility modification. The Adelaide metropolitan cluster serves as the diagnostic hub, with regional outreach dependent on mobile unit availability.
Australia Computed Tomography Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with consolidated multinational presence across Australian hospital networks. Siemens Healthineers anchors premium positioning through deep R&D investment in dual-source architectures, while GE Healthcare leverages established service infrastructure. Canon Medical Systems competes on compact, high-throughput systems tailored to outpatient workflows. Strategic moves concentrate on service contract restructuring and modular detector upgrades rather than greenfield placements.
Among German-based multinationals, Siemens Healthineers AG exemplifies the technology-leadership archetype through photon-counting detector commercialization. GE Healthcare represents the service-infrastructure anchor, leveraging nationwide coverage for maintenance and upgrade pathways. United Imaging occupies a position as the emerging cost-competitive alternative, challenging premium pricing through aggressive market entry positioning.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Koning Corporation |
| GE Healthcare |
| United Imaging |
| Samsung Electronics Co., Ltd. |
| Koninklijke Philips NV |
| Planmeca Group |
| Canon Medical Systems Corporation |
| Carestream Health |
| Others |
Value Chain & Pricing Dynamics
TGA medical device conformity requirements gate both vendor qualification and price differentiation simultaneously, compressing margins for non-compliant suppliers while enabling certified incumbents to command service contract premiums across Australian hospital networks.
Pricing Analysis
Configured-to-order pricing spreads 15-25% above standard system configurations across Australian procurement channels. Three-tier pricing structure across premium, standard, and economy levels segments by detector technology class and after-sales bundling intensity. Cost compression in mid-range systems is intensifying because photon-counting detector commercialization collapses capability premiums previously reserved for spectral platforms. Public hospital shared services exhibit highest price sensitivity through aggregated volume tenders, while private day hospitals show lowest sensitivity for rapid-installation compact systems.
Supply Chain Analysis
Just-in-time inventory strategies dominate detector array and X-ray tube sourcing, though helium stockpiling for superconducting magnet cooling has shifted toward strategic reserves after 2022 allocation disruptions. Manufacturing concentrates in Germany, Japan, and the United States for precision gantry components and detector substrates. Australian operators draw from limited global helium refining capacity concentrated in Qatar and the United States, creating single-source vulnerability for magnet cooling. Distribution runs through manufacturer-direct service organizations with localized spare parts depots in Sydney and Melbourne.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates switching costs that lock hospital procurement committees into established service infrastructures.
For Market Incumbents: Shield installed base revenue through modular detector upgrade pathways rather than greenfield replacement cycles. Deepen backward integration into photon-counting detector manufacturing to capture margin compression from emerging cost-competitive entrants. Prioritize TGA priority review pathway pre-submission for next-generation spectral systems to maintain technology leadership positioning against United Imaging's market entry. For New Entrants and Emerging Players: Lead with mobile stroke unit deployment in regional Victoria and Tasmania where fixed infrastructure gaps persist and incumbent service coverage thins. Target diagnostic imaging centers in Sydney's outer suburbs where private equity-backed day hospitals prioritize compact footprint systems with minimal facility modification requirements. Pursue channel partnerships with regional equipment financiers to bypass capital committee approval bottlenecks. For Investors and Strategic Acquirers: TGA alignment with International Medical Device Regulators Forum standards reshapes the acquisition landscape by accelerating product lifecycle synchronization and reducing regulatory due diligence burdens for northern hemisphere targets. Long-term viability centers on service infrastructure density rather than manufacturing scale, favoring acquisition of firms with established biomedical engineer training programs and spare parts logistics. Watch for Medicare Benefits Schedule diagnostic imaging reimbursement revisions as the signal indicating capital allocation priority shifts between replacement and expansion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Priority Review Submission | Accelerates market entry for photon-counting systems by 6-12 months against standard pathways. |
| Mobile Stroke Unit Deployment | Captures Queensland and Western Australia regional mandates bypassing shielding construction bottlenecks. |
| Service Contract Restructuring | Locks hospital procurement committees into multi-year maintenance agreements with modular upgrade clauses. |
| AI-Integrated Workflow Development | Automates organ segmentation for Melbourne and Sydney teaching hospitals pursuing quantitative biomarker protocols. |
| Regional Service Infrastructure Expansion | Addresses medical physicist certification scarcity limiting quality assurance testing throughput. |
Study Parameters
Operator-level perspectives from hospital procurement managers, biomedical engineers, GPO contracts specialists, and radiology department heads anchored the qualitative base. Primary interviews combined with secondary validation from TGA device registration databases, Medicare Benefits Schedule diagnostic imaging item listings, and state health department capital equipment tender records. Bottom-up scanner placement projections and top-down healthcare expenditure analysis triangulated market sizing across metropolitan and regional network segments.
Sensitivity analysis tested forecast robustness against helium supply disruption scenarios and reimbursement rate revision pathways. Segmentation modeling spanned product type, end-user facility class, detector technology tier, and clinical application intensity throughout the forecast period. CAGRs derived from replacement cycle analysis, technology adoption S-curve positioning, and state health infrastructure budget trajectories. Industry-specific inputs incorporated TGA registration pipeline velocity and ARPANSA shielding compliance timelines.
Forecasts assume regulatory continuity in TGA medical device frameworks and ARPANSA radiation safety standards; material policy shifts would require re-modeling. Revision becomes warranted when photon-counting detector cost curves collapse premium-standard pricing spreads below service contract bundling thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Argentina Digital X-Ray Market
Medical Imaging
Specialty PACS Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
Optical Coherence Tomography Market
Medical Imaging
UK Imaging Services Market
Medical Imaging
AI Fetal Ultrasound View Detection Software Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Brazil Digital X-Ray Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
Portable Ultrasound Bladder Scanner Market
Medical Imaging
UK Digital Radiology Market
Medical Imaging
Cranial Doppler Market
Medical Imaging
Spain Diagnostic Imaging Equipment Market
Medical Imaging
South Korea Digital X-Ray Market
Medical Imaging
Mexico Digital X-Ray Devices Market