
 Blood Banking Equipment Market | 2026-2036
Blood Banking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Banking Equipment Market Outlook
Buyer concentration across hospital networks is broadening as integrated delivery systems expand their in-house blood banking capabilities. Fresenius Kabi AG anchors its position through specialized infusion and transfusion technologies that serve these consolidating buyers. Haemonetics Corporation differentiates through automated collection systems that reduce manual processing labor. Terumo BCT, Inc. competes on geographic reach across North American and European hospital contracts.
Blood banking equipment comprises the refrigerated, automated, and cryogenic systems used to collect, process, store, and distribute blood components for therapeutic transfusion, with core specifications including temperature stability within one degree Celsius and sterile closed-system processing. Blood storage refrigerators and plasma freezers represent the most mature product category, where replacement cycles and energy efficiency upgrades now drive purchasing decisions. Automated blood processing systems capture expanding capital budgets as labor costs rise and throughput demands intensify at high-volume transfusion centers.
The FDA enforces current Good Manufacturing Practice requirements for blood bank equipment validation, while the EU Medical Device Regulation mandates stricter clinical evidence standards for automated collection devices entering European markets. These frameworks elevate compliance costs for manufacturers but create barriers that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor how evolving WHO blood safety guidelines reshape procurement specifications in emerging health systems.
Market Dynamics
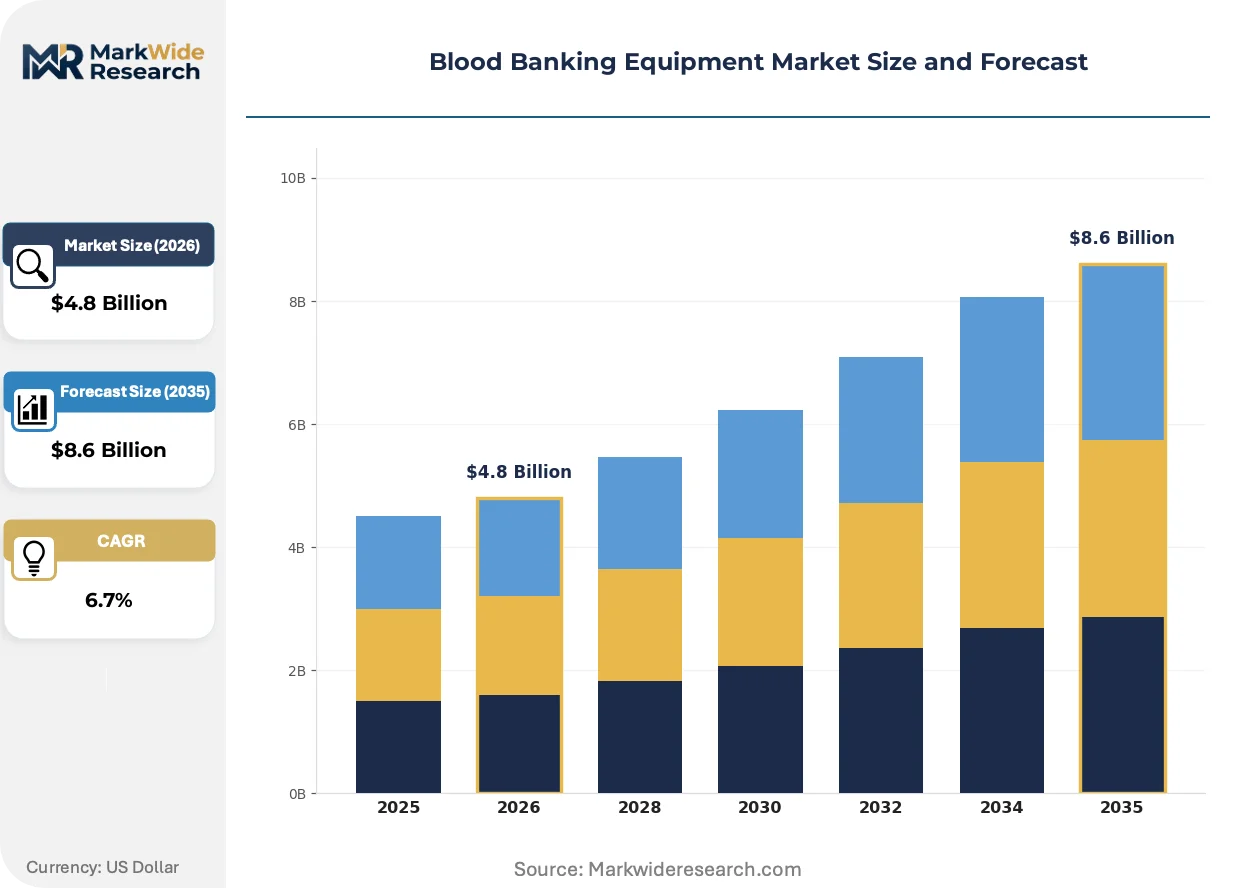
Hospital network consolidation and automated processing mandates are compressing equipment replacement cycles while elevating compliance burdens for temperature validation systems across transfusion centers.
Growth Catalysts
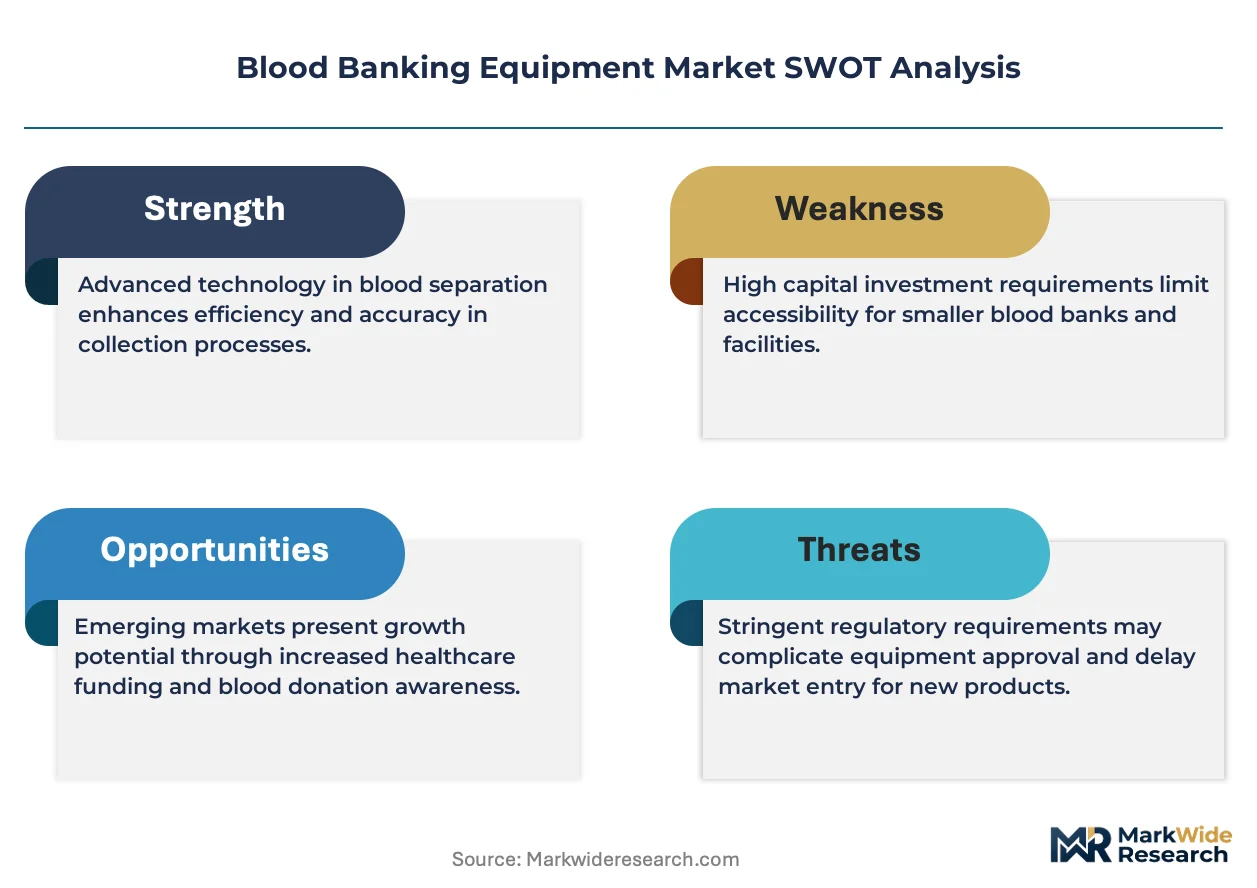
- FDA Blood Storage Guidance:Updated temperature monitoring requirements are forcing equipment upgrades at US hospital blood banks, creating replacement demand for validated refrigeration systems.
- Automated Processing:Labor cost pressures at high-volume transfusion centers are accelerating capital deployment toward closed-system collection and component separation technologies.
- Integrated Delivery Systems:Consolidating US health networks are centralizing in-house blood banking capabilities, expanding capital budgets for enterprise-scale processing infrastructure.
Market Restraints
- Stainless Steel and Compressor Input Volatility:Refrigeration equipment manufacturing faces raw material cost swings that compress margin predictability for storage system producers.
- EU MDR Clinical Evidence Requirements:Stricter documentation mandates for automated collection devices entering European markets extend approval timelines and elevate regulatory affairs overhead.
- Manual Processing Persistence:Smaller rural hospitals and emerging market facilities continue relying on labor-intensive methods, limiting addressable market expansion for premium automation.
Strategic Opportunities
- India Blood Safety Modernization:CDSCO and state health procurement bodies are expanding cold chain infrastructure for blood component storage, opening equipment tender opportunities.
- Cryogenic Automation Convergence:Integration of robotic sample handling with liquid nitrogen storage systems is creating premium positioning for plasma and stem cell banking applications.
- Outcome-Based Service Contracts:Equipment vendors are unbundling maintenance from capital sales, capturing recurring revenue through uptime guarantees and remote monitoring subscriptions.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Specialized technicians capable of servicing automated collection systems and validated refrigeration are concentrated at major academic medical centers, limiting field service expansion.
- Legacy System Integration Friction:Hospital IT departments face complexity connecting new automated processing equipment to existing laboratory information management systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Banking Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Collection Bags, Blood Processing Systems, Blood Storage Refrigerators, Plasma Freezers Application: Transfusion Centers, Hospitals, Blood Donation Camps, Research Laboratories Technology: Manual, Automated, Refrigerated, Cryogenic End User: Healthcare Facilities, Non-Profit Organizations, Blood Banks, Academic Institutions |
| Companies Covered | Haemonetics Corporation, Terumo BCT, Inc., Fresenius Kabi AG, Beckman Coulter, Inc., Grifols S.A., BD, Immucor, Inc., Macopharma, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Banking Equipment Market Strategic Shifts
Closed-system automation and real-time cold chain monitoring are displacing manual handling protocols while regulatory digitization is compressing validation documentation workflows across transfusion medicine.
Integrated blood processing platforms are unifying collection, separation, and component storage into single-vendor workflows. Major US academic medical centers and consolidated hospital networks are adopting these systems to reduce cross-contamination risk and labor handoffs. This consolidation is unifying procurement decisions around full-stack suppliers rather than point-solution vendors.
REACH and EU MDR are mandating stricter material traceability and clinical performance documentation for blood contact devices and automated collection systems. European manufacturers are restructuring quality management systems to capture device-history records across component suppliers. Automated collection device categories face the heaviest documentation burden, with several firms withdrawing legacy products rather than completing MDR conformity assessments.
Consolidated procurement at US integrated delivery networks is compressing vendor evaluation cycles and elevating total-cost-of-ownership criteria over upfront capital cost. Group purchasing organizations are centralizing blood banking equipment selection for member hospitals, displacing individual facility purchasing autonomy. This concentration is most visible in the Southeast and Midwest hospital network expansions, where standardization across dozens of facilities creates volume leverage.
Blood Banking Equipment Market Segmentation
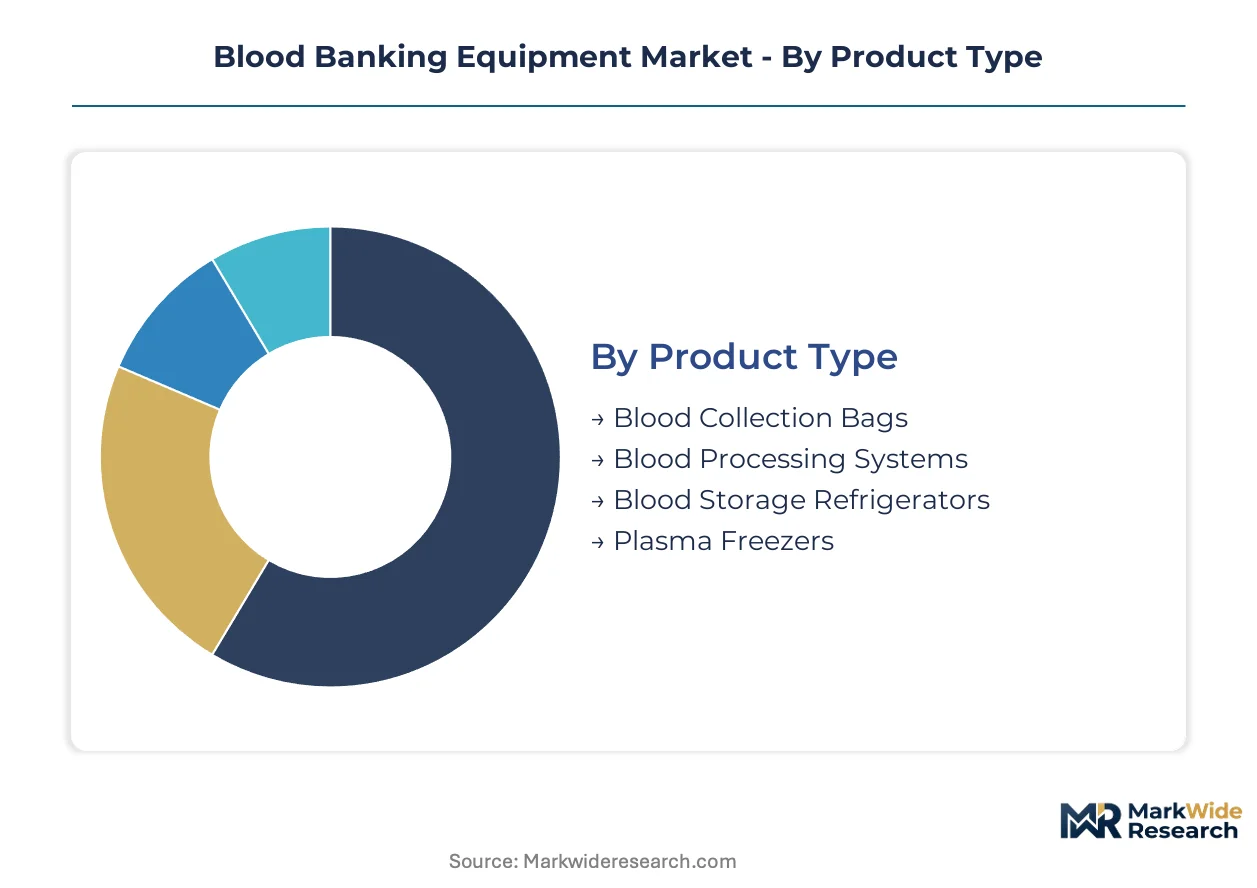
Segmentation in blood banking equipment reveals how procurement decisions split between replacement-driven categories and automation-led capital investments. Understanding these divisions helps vendors align product development with the divergent priorities of high-volume transfusion centers versus smaller facility budgets.
Product Type:
Specifications across product categories range from sterile polymer containment to precision thermal control systems with validated temperature logging.
- Blood Collection Bags:Single-use sterile containers manufactured from PVC or alternative plasticized polymers with anticoagulant solutions pre-filled. Demand clusters at high-frequency donation camps in India and Southeast Asia where disposable economics dominate procurement.
- Blood Processing Systems:Automated centrifugation and component separation platforms that integrate closed-system collection with leukoreduction. US hospital networks and European transfusion centers are deploying these systems to reduce manual labor and contamination risk.
- Blood Storage Refrigerators:Validated refrigeration units maintaining 2-6°C with continuous temperature monitoring and alarm systems. Replacement cycles accelerate under FDA guidance updates.
- Plasma Freezers:Ultra-low temperature units preserving plasma components at -30°C or below. Energy efficiency upgrades drive purchasing in European markets facing F-Gas Regulation compliance costs.
Mature deployment sits with Blood Storage Refrigerators. Newer deployment is concentrated in Blood Processing Systems.
Application:
End-use environments impose distinct throughput, compliance, and infrastructure requirements that reshape equipment specifications.
- Transfusion Centers:High-volume facilities processing thousands of units annually with automated workflows and enterprise-scale cold chain infrastructure. US integrated delivery networks are centralizing transfusion capabilities at these dedicated sites.
- Hospitals:Inpatient facilities maintaining emergency blood reserves with smaller-scale refrigeration and occasional component processing. Rural hospitals persist with manual methods due to capital constraints.
- Blood Donation Camps:Mobile or temporary collection sites requiring portable collection bags and basic refrigeration. Indian state health programs are expanding camp infrastructure under blood safety modernization initiatives.
- Research Laboratories:Academic and pharmaceutical facilities using blood components for therapeutic development and cell therapy research. Cryogenic storage demand is climbing fastest here.
Volume concentration rests with Transfusion Centers. Capability expansion is accelerating fastest in Research Laboratories.
Technology:
Technology tiers separate labor-dependent methods from capital-intensive automation with compliance documentation requirements.
- Automated:Closed-system platforms integrating collection, separation, and component handling with minimal operator intervention. EU MDR clinical evidence requirements are elevating barriers for new automated device entrants.
- Manual:Operator-dependent processing using open systems with higher contamination risk and labor intensity. Smaller rural hospitals and emerging market facilities continue reliance due to lower capital thresholds.
- Refrigerated:Temperature-controlled storage systems with validated monitoring for whole blood and red cell components. FDA storage guidance is forcing upgrades at US hospital blood banks.
- Cryogenic:Liquid nitrogen or mechanical freezer systems preserving plasma, stem cells, and rare blood types at ultra-low temperatures. Robotic sample handling integration is creating premium positioning opportunities.
Installed base dominance belongs to Refrigerated systems. Investment momentum is shifting toward Automated platforms.
End User:
Procurement authority and budget structures vary sharply across institutional categories with divergent funding sources.
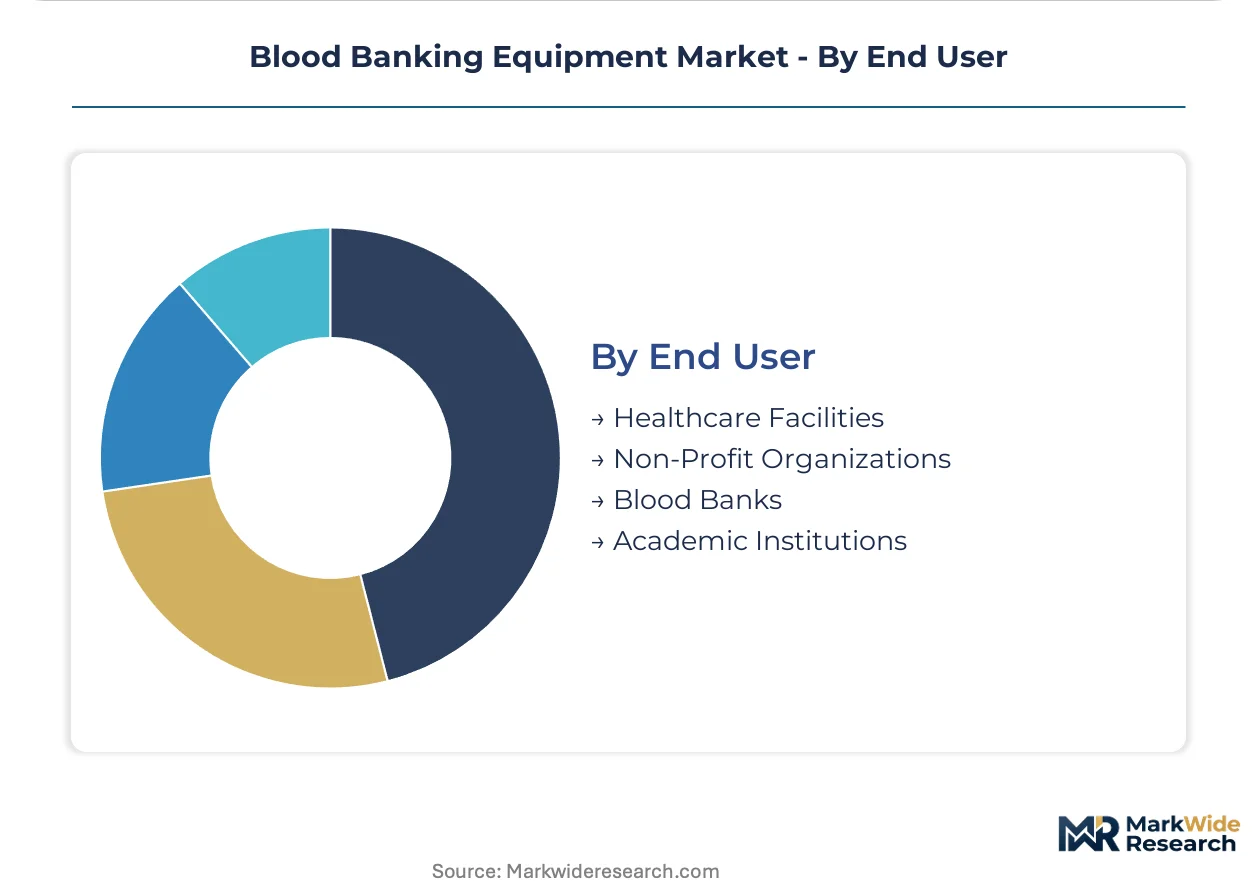
- Healthcare Facilities:Hospital networks and clinics with capital equipment budgets tied to patient revenue. Group purchasing organizations are consolidating selection authority across US member hospitals.
- Blood Banks:Dedicated collection and processing organizations with mission-critical infrastructure requirements. These facilities are expanding cryogenic capacity for plasma and stem cell banking.
- Non-Profit Organizations:Red Cross affiliates and community blood centers operating on donation-funded budgets with cost-sensitive procurement. Maintenance service contracts are displacing capital purchases.
- Academic Institutions:University medical centers and research hospitals with dual clinical and research missions. These buyers prioritize integration with laboratory information management systems.
Procurement volume concentrates at Healthcare Facilities. Specification complexity is expanding fastest at Academic Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital network consolidation in the United States concentrates transfusion infrastructure investment, while European regulatory tightening and Asian blood safety modernization programs are redistributing equipment demand across distinct compliance environments.
United States
Integrated delivery systems in the Southeast and Midwest are centralizing blood banking capabilities across dozens of facilities, elevating capital budgets for enterprise-scale processing infrastructure. FDA updated guidance on blood storage temperature monitoring is forcing equipment upgrades at hospital blood banks, creating replacement demand for validated refrigeration systems. Major academic medical centers in Boston and the Research Triangle are adopting integrated blood processing platforms to reduce cross-contamination risk.
Germany
European transfusion centers are deploying automated processing systems to reduce manual labor and contamination risk amid rising healthcare labor costs. EU Medical Device Regulation mandates stricter clinical evidence standards for automated collection devices entering European markets, extending approval timelines for manufacturers. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host refrigeration equipment producers restructuring quality management systems for MDR conformity.
India
High-frequency donation camps in Maharashtra and Tamil Nadu are driving demand for single-use blood collection bags where disposable economics dominate procurement. CDSCO and state health procurement bodies are expanding cold chain infrastructure for blood component storage under blood safety modernization initiatives. Delhi-NCR and Karnataka health systems are tendering for automated processing capacity at central transfusion facilities.
Japan
Aging demographics are intensifying demand for plasma-derived therapies, expanding cryogenic storage requirements at blood banks and academic medical centers. PMDA maintains rigorous device approval standards that favor established manufacturers with dedicated regulatory affairs infrastructure. The Kanto region around Tokyo concentrates transfusion medicine research facilities adopting robotic sample handling integration with liquid nitrogen storage systems.
Australia
TGA oversight of blood banking equipment aligns with international standards while maintaining distinct documentation requirements for automated collection devices. Research laboratories in New South Wales and Victoria are climbing fastest in cryogenic storage demand for cell therapy development. Blood service infrastructure modernization is concentrating procurement authority at the national level, favoring vendors with comprehensive service contract capabilities.
Blood Banking Equipment Market Competitive Environment
United States producers anchor one tier; German and Japanese specialists hold differentiated positions in precision refrigeration and automated processing. The vendor base concentrates around established players with dedicated regulatory affairs infrastructure capable of navigating FDA and EU MDR compliance burdens. Three strategic archetypes dominate: full-stack integrated platform suppliers, point-solution refrigeration specialists, and automated collection technology developers. Competitive moves center on outcome-based service contract unbundling and cryogenic automation convergence for premium positioning.
Within the full-stack integrated platform tier, Fresenius Kabi AG and Haemonetics Corporation exemplify vendors capturing consolidated procurement decisions at US hospital networks. Terumo BCT, Inc. occupies a position among automated collection specialists competing on geographic reach across North American and European hospital contracts. These three companies represent the archetype of established manufacturers leveraging regulatory compliance infrastructure as a competitive barrier against new market entrants.
| Leading Market Players |
|---|
| Haemonetics Corporation |
| Terumo BCT, Inc. |
| Fresenius Kabi AG |
| Beckman Coulter, Inc. |
| Grifols S.A. |
| BD |
| Immucor, Inc. |
| Macopharma |
| Bio-Rad Laboratories, Inc. |
| Others |
Value Chain & Pricing Dynamics
Stainless steel and compressor component costs cascade through three distinct pricing tiers for blood banking equipment, with validated refrigeration systems commanding premium positioning against standard storage units and economy-grade manual processing alternatives. Raw material volatility at German and Japanese industrial clusters feeds downstream margin compression that manufacturers offset through service contract unbundling and remote monitoring subscriptions.
Pricing Analysis
Volume concentration in blood storage refrigerators and plasma freezers compresses margins for mature product categories, while automated processing systems sustain premium positioning through FDA validation requirements and EU MDR clinical evidence barriers. Price differentiation hinges on temperature stability certification grade and after-sales service bundling, with integrated delivery networks leveraging group purchasing organization scale for total-cost-of-ownership concessions. Cost compression in standard refrigeration tiers intensifies as energy efficiency mandates force component upgrades. Non-profit blood centers and rural hospitals exhibit highest price sensitivity, whereas academic medical centers prioritize LIMS integration and uptime guarantees over capital cost.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and recertification of validated refrigeration equipment extend asset lifecycles at US hospital networks, compressing replacement demand for original equipment manufacturers. Manufacturing concentrates in Germany, Japan, and the United States, with precision compressor production anchored at Baden-Württemberg industrial clusters and control system fabrication centered in Kanto region facilities. Supply chains draw from specialized stainless steel grades, medical-grade polymers, and cryogenic coolant inputs. Single-source vulnerability sits with precision temperature sensor suppliers serving automated collection device producers. Distribution runs through group purchasing organization contracts and direct hospital network procurement at integrated delivery systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomedical engineering talent scarcity at field service operations props pricing for maintenance contracts and remote monitoring subscriptions, constraining rapid vendor expansion despite capital demand acceleration.
For Market Incumbents: Cement regulatory compliance infrastructure as a sustainable barrier by deepening MDR documentation capabilities and FDA validation expertise against emerging Asian competitors. Prioritize backward integration into precision temperature sensor supply to reduce single-source exposure. Expand cryogenic automation service contracts at academic medical centers to capture recurring revenue displacement of capital sales. For New Entrants and Emerging Players: Begin with India's state health procurement tenders for cold chain infrastructure under CDSCO blood safety modernization, where disposable collection bag economics dominate and automation penetration remains nascent. Target blood donation camp logistics providers with portable refrigeration solutions. Pursue outcome-based service contracts rather than capital equipment sales to bypass incumbent GPO lock-in. For Investors and Strategic Acquirers: FDA guidance updates on blood storage temperature monitoring are the leading indicator that replacement cycle compression will sustain equipment demand regardless of macroeconomic softness. Position for five-to-ten-year viability through platforms with installed base density enabling service contract transitions. Monitor EU MDR conformity assessment withdrawals as consolidation signals for automated collection device categories.| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Service Contract Unbundling | Captures recurring revenue through uptime guarantees at US hospital networks displacing capital purchases. |
| Cryogenic Automation Convergence | Integrates robotic sample handling with liquid nitrogen storage at Japanese academic medical centers. |
| MDR Conformity Assessment Completion | Preserves European market access for automated collection devices facing documentation withdrawal waves. |
| Hospital System Partnership Expansion | Secures preferred vendor status at Southeast and Midwest integrated delivery network standardization programs. |
| Remote Monitoring Platform Development | Enables predictive maintenance subscriptions addressing biomedical engineering talent scarcity in field service. |
Study Parameters
Independent corroboration across blood bank operations directors, biomedical engineering managers, and group purchasing organization contract specialists underwrites the qualitative findings, validated against FDA guidance documents, EU MDR technical file databases, and hospital procurement records. Secondary sources include CDSCO tender announcements, Japanese PMDA device approvals, and blood safety modernization program disclosures. Bottom-up equipment shipment analysis triangulates with top-down health infrastructure spending assessments.
Comparable-period anchoring to historical replacement cycles and regulatory compliance milestones structured the projection horizon, with segmentation modeling across product type, application environment, technology tier, and end-user procurement authority. CAGRs derive from installed base evolution, upgrade elasticity to guidance changes, and automation penetration curves at high-volume transfusion centers. Forecast inputs incorporate labor cost trajectories, energy efficiency mandate compliance costs, and cold chain infrastructure investment flows.
Underlying measurement precision varies by segment; automated processing systems and cryogenic platforms carry tighter precision than mature refrigeration categories given disclosure concentration at public manufacturers. Forecasts reflect assumptions on regulatory timeline adherence, hospital network consolidation velocity, and biomedical engineering workforce expansion. Practitioners should monitor FDA inspection observation trends, EU MDR designation withdrawals, and Indian state health budget allocations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Lifting Slings Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Tanning Units Market
Medical Equipment
Cryochambers Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Home Medical Equipment Market