
 Global Medical Equipment Calibration Market | 2026-2036
Global Medical Equipment Calibration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Equipment Calibration Market Foresight
EU MDR is realigning the cost-of-entry calculus for calibration service providers serving European device manufacturers. Siemens Healthineers leverages its captive metrology infrastructure to control turnaround times for imaging system recertification. Transcat anchors its competitive position through a distributed North American service network with A2LA-accredited laboratories. Fluke Corporation dominates handheld electrical safety analyzer calibration, a segment where hospital biomedical engineering departments require annual traceability.
Medical equipment calibration encompasses the measurement and adjustment of diagnostic and therapeutic devices against traceable reference standards to ensure clinical accuracy within manufacturer-specified tolerances, typically requiring temperature-controlled environments within ±0.5°C and humidity below 60% RH to preserve measurement integrity. The process verifies that patient monitoring devices, imaging modalities, and surgical instruments deliver quantitatively reliable outputs for clinical decision-making. Imaging equipment calibration commands the largest share of current service revenue given the complexity of CT dose index verification and MRI field uniformity mapping. Software-based calibration is displacing manual protocols in radiology and cardiology applications where automated drift correction reduces equipment downtime. Diagnostic instruments remain the most mature segment with established ISO 17025 procedures, while remote calibration services represent the fastest-expanding technology category as cloud-connected analytics enable predictive maintenance scheduling.
FDA quality system regulations, EU MDR technical documentation requirements, and ISO 13485 medical device quality management standards collectively mandate documented traceability chains for all calibration activities affecting patient safety. These frameworks compel hospitals and diagnostic centers to maintain accredited calibration partnerships or build in-house metrology capabilities with qualified personnel. Stakeholders must monitor evolving cybersecurity requirements for networked calibration systems as software-based and remote service models expand their footprint in clinical environments.
Market Dynamics
Software-based calibration protocols are compressing turnaround times for imaging recertification while tightening traceability requirements force hospital biomedical departments to rebuild vendor qualification frameworks around automated audit trails.
Growth Catalysts
- FDA Quality System Regulation Updates:The FDA's enhanced documentation mandates for medical device manufacturers are compelling service providers to deploy automated calibration management systems that maintain continuous traceability chains from reference standards to field instruments.
- EU MDR Technical Documentation Requirements:European device manufacturers must now demonstrate metrological traceability across the full device lifecycle, driving calibration partnerships with ISO 17025-accredited laboratories for conformity assessment procedures.
- Cloud-Connected Predictive Maintenance:Remote calibration analytics platforms are integrating with hospital asset management systems to schedule interventions before drift exceeds clinical tolerance thresholds, reducing unplanned downtime for patient monitoring fleets.
Market Restraints
- Reference Standard Supply Concentration:Primary metrology-grade reference artifacts for ionizing radiation and magnetic field calibration concentrate among three national measurement institutes in the United States, Germany, and Japan, creating bottleneck risk for traceability chain validation.
- Specialized Personnel Scarcity:Qualified metrologists with combined competencies in biomedical engineering and ISO 17025 quality management command compensation premiums that inflate service delivery costs for distributed calibration networks.
- Temperature-Controlled Infrastructure Requirements:Maintaining laboratory environments within ±0.5°C and below 60% relative humidity demands capital-intensive HVAC investments that constrain entry for regional service providers.
Strategic Opportunities
- India Diagnostic Laboratory Expansion:The country's central drugs regulator is tightening accuracy requirements for pathology analyzers and imaging equipment in tier-2 and tier-3 cities, opening demand for accredited calibration partnerships outside established metropolitan clusters.
- Cybersecurity-Certified Calibration Systems:FDA draft guidance on networked medical device security is creating first-mover advantage for service providers integrating hardware security modules and encrypted data transmission into remote calibration platforms.
- Point-of-Care Device Convergence:The proliferation of portable ultrasound and handheld diagnostic instruments is fragmenting calibration demand toward field-deployable reference standards that eliminate transport logistics for clinic-based equipment.
Industry Challenges
- Multi-Standard Accreditation Complexity:Service providers seeking to serve both FDA-registered device manufacturers and EU MDR-notified body clients must maintain parallel quality system documentation that strains audit resource allocation.
- Legacy Imaging System Integration:Hospital biomedical engineering departments face protocol fragmentation when connecting automated calibration platforms to installed imaging modalities with proprietary data interfaces and non-standard communication buses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Equipment Calibration Market |
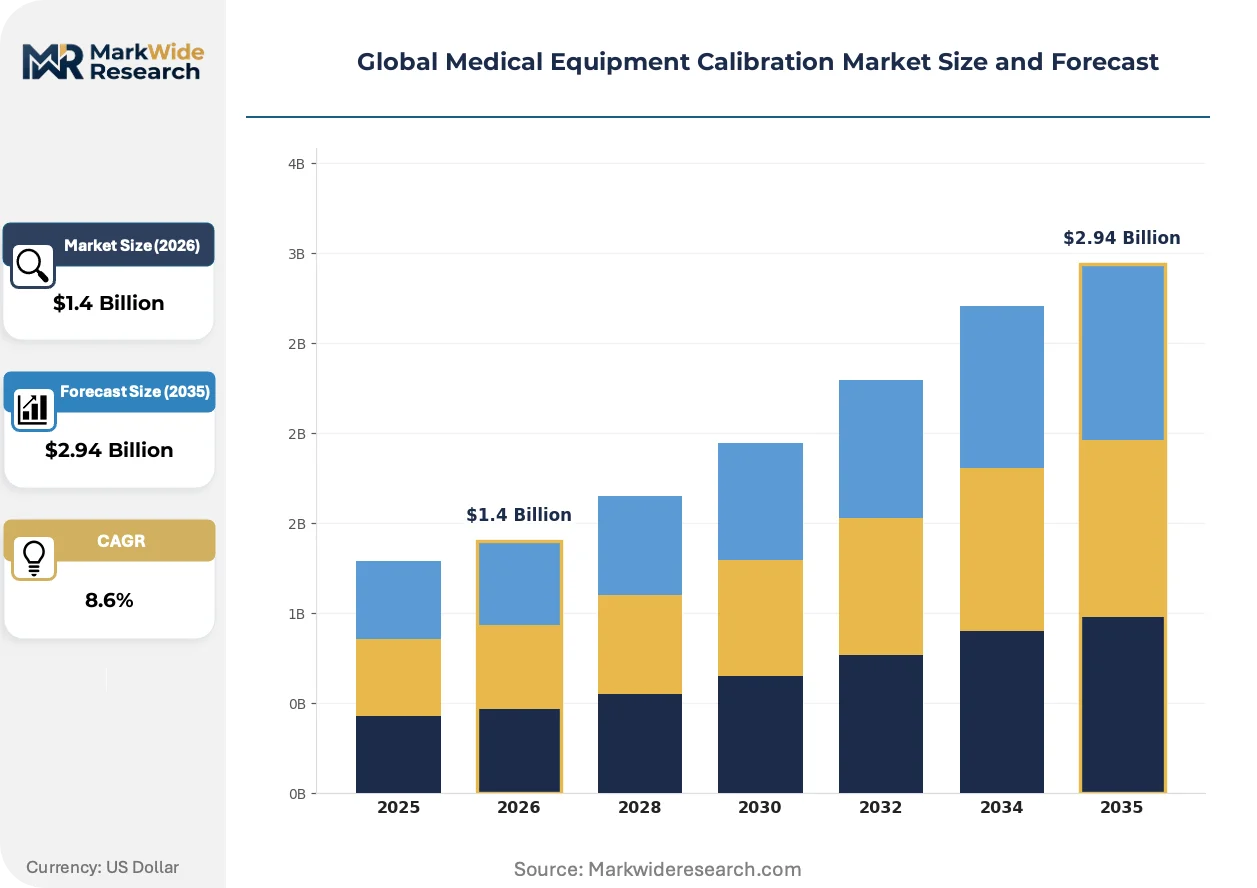
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Equipment, Diagnostic Instruments, Patient Monitoring Devices, Surgical Equipment, Laboratory Instruments Technology: Automated Calibration, Manual Calibration, Software-Based Calibration, Remote Calibration Services, Sensor Calibration Application: Cardiology, Neurology, Radiology, Oncology, Pathology, Critical Care End User: Hospitals, Diagnostic Centers, Research Laboratories, Surgical Centers, Outpatient Facilities |
| Companies Covered | Siemens Healthineers, Transcat, Fortive, Fluke Corporation, Tektronix, Trescal, Koninklijke Philips, JM Test Systems, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Equipment Calibration Market Shifts & Advancements
Artificial intelligence-enabled drift prediction and blockchain-anchored traceability records are redefining how calibration integrity is demonstrated to regulators and payers across interconnected healthcare delivery networks.
Automated calibration algorithms for CT dose index verification and MRI field uniformity mapping are integrating machine learning models that self-correct for environmental perturbations during measurement acquisition. Major academic medical centers in the United States and Germany are deploying these systems to compress recertification cycles from quarterly to monthly intervals without expanding metrology staffing. The technology is integrating predictive analytics that flag reference standard degradation before tolerance excursions compromise patient safety.
The EU MDR's technical documentation requirements for post-market surveillance are mandating calibration record retention periods that exceed fifteen years, forcing service providers to migrate from paper-based certificates to cryptographically signed digital records. Device manufacturers serving European markets must now demonstrate continuous metrological traceability through notified body audits, with particular scrutiny applied to software-upgradable diagnostic instruments. Imaging equipment vendors with captive calibration capabilities are restructuring service offerings to externalize documentation compliance for independent healthcare providers.
Hospital procurement departments are unbundling calibration services from original equipment manufacturer maintenance contracts, creating direct purchasing relationships with accredited third-party laboratories. This pattern is most pronounced in the United States, where group purchasing organizations for non-profit health systems are aggregating demand across multi-hospital networks to secure volume pricing for annual traceability programs. Independent service organizations with A2LA or UKAS accreditation are capturing share from manufacturer-captive service arms by guaranteeing faster turnaround times for patient monitoring device recertification.
Global Medical Equipment Calibration Market Segmentation
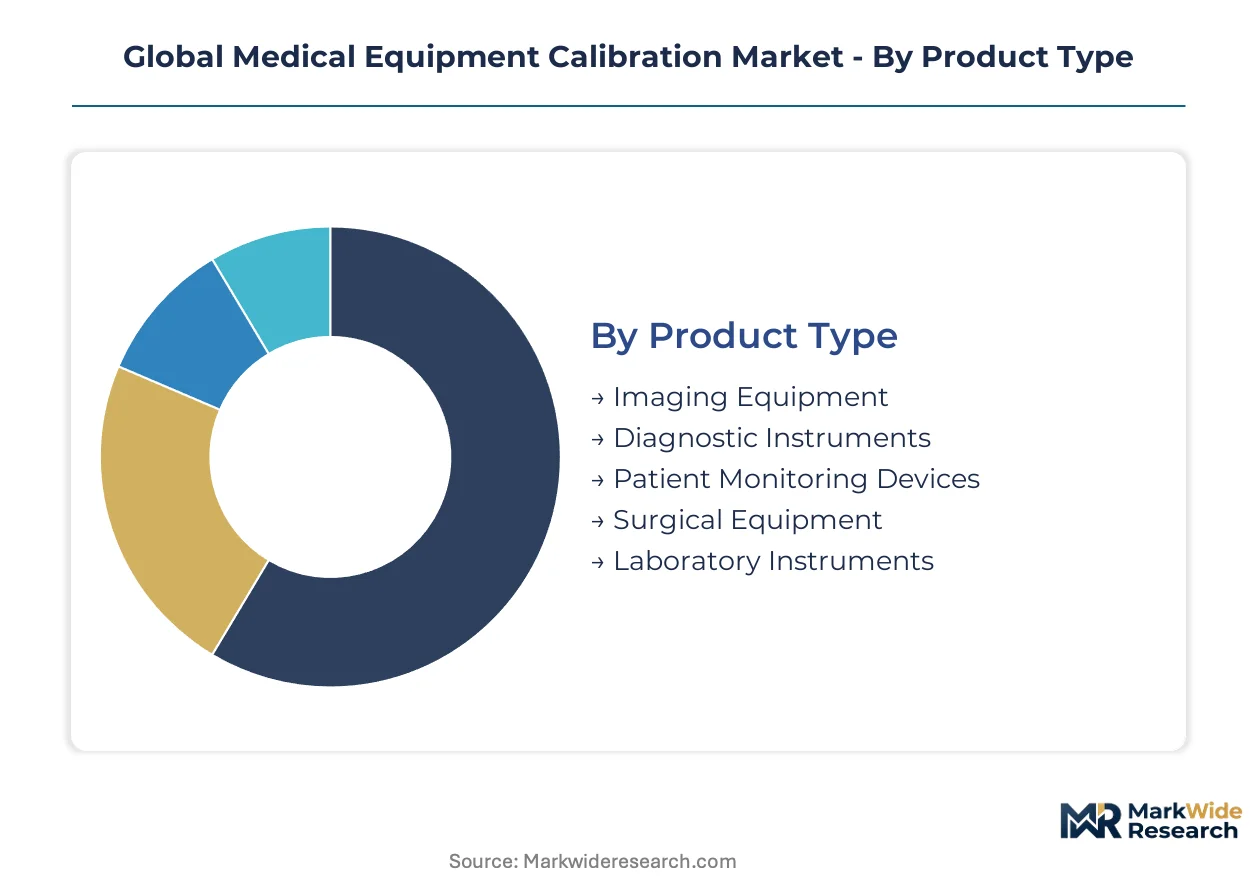
Medical equipment calibration markets fragment across equipment sophistication, protocol automation, clinical application, and facility scale. Each segmentation axis carries distinct margin profiles, accreditation requirements, and vendor qualification barriers that reshape competitive positioning across service tiers.
Product Type:
Supply concentration for reference-grade artifacts varies sharply by equipment category, with ionizing radiation and magnetic field standards bottlenecking through national metrology institutes in the United States, Germany, and Japan.
- Imaging Equipment:CT dose index verification and MRI field uniformity mapping demand temperature-controlled laboratory environments within ±0.5°C. Demand concentrates in academic medical centers across the United States and Germany where quarterly recertification compresses to monthly cycles under EU MDR post-market surveillance mandates.
- Diagnostic Instruments:Pathology analyzers and hematology systems constitute the most mature calibration segment with established ISO 17025 procedures. Hospital biomedical engineering departments in Japan prioritize automated traceability systems for these instruments following PMDA quality system updates.
- Patient Monitoring Devices:ECG, pulse oximetry, and blood pressure calibration protocols serve distributed hospital fleets requiring annual traceability documentation.
- Surgical Equipment:Electrosurgical generators and laser systems demand electrical safety analyzer verification with specialized personnel competencies.
- Laboratory Instruments:Centrifuges, incubators, and pipettes require less stringent environmental controls but broader geographic service coverage.
Today's leader: Imaging Equipment. Tomorrow's challenger: Patient Monitoring Devices.
Technology:
Cost tier stratification separates capital-intensive automated platforms from labor-dependent manual protocols, with software-based systems capturing mid-market positioning through reduced downtime value propositions.
- Automated Calibration:Robotic artifact handling and continuous environmental monitoring compress turnaround times for high-volume imaging recertification. Siemens Healthineers deploys captive automated infrastructure across German and United States manufacturing sites to control service delivery costs.
- Software-Based Calibration:Machine learning-enabled drift correction integrates with hospital asset management systems for predictive intervention scheduling. Cloud-connected analytics platforms in the United States are gaining share fastest among non-profit health systems unbundling from OEM maintenance contracts.
- Manual Calibration:Technician-dependent protocols persist for legacy equipment with proprietary data interfaces.
- Remote Calibration Services:Networked reference standards enable field-deployable verification without transport logistics.
- Sensor Calibration:Component-level adjustment supports point-of-care device manufacturers with distributed production footprints.
Automated systems command premium pricing. Software-based platforms are climbing the fastest through procurement unbundling.
Application:
Volume concentration tracks regulatory intensity, with cardiology and radiology applications facing the most stringent accuracy mandates from FDA quality system regulations and EU MDR technical documentation requirements.
- Radiology:CT, MRI, and X-ray calibration generates the highest service revenue per device given complexity of dose verification and field mapping. Academic medical centers in Germany and the United States deploy monthly recertification cycles using AI-enabled drift prediction.
- Cardiology:ECG and echocardiography calibration demand combines with software-upgradable diagnostic instruments under EU MDR scrutiny for continuous traceability demonstration.
- Oncology:Linear accelerator and brachytherapy calibration requires ionizing radiation reference standards with limited supplier base.
- Neurology:EEG and evoked potential systems demand specialized low-noise measurement environments.
- Pathology:Histology and cytology instrument calibration serves expanding diagnostic laboratory networks in India.
- Critical Care:Multi-parameter monitor fleets require rapid turnaround to minimize bedside downtime.
Radiology anchors current revenue. Cardiology is expanding most quickly through software-based protocol displacement.
End User:
Customer type determines procurement sophistication, with hospitals demanding integrated audit trails while outpatient facilities prioritize speed and geographic accessibility.
- Hospitals:Integrated delivery networks in the United States aggregate calibration demand across multi-hospital systems to secure volume pricing from A2LA-accredited laboratories. Biomedical engineering departments rebuild vendor qualification frameworks around automated traceability documentation.
- Diagnostic Centers:Independent imaging and pathology facilities unbundle from OEM service contracts to secure faster turnaround times, particularly for patient monitoring device recertification.
- Research Laboratories:Academic and pharmaceutical R&D facilities demand extended calibration record retention exceeding fifteen years under EU MDR post-market surveillance requirements.
- Surgical Centers:Ambulatory facilities require field-deployable reference standards to eliminate transport logistics for specialized equipment.
- Outpatient Facilities:Clinic-based portable ultrasound and handheld diagnostic instruments fragment demand toward point-of-care calibration solutions.
Hospitals dominate procurement volume. Diagnostic Centers are gaining share fastest through direct purchasing relationship formation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified metrologists with combined biomedical engineering and ISO 17025 competencies concentrate in the United States, Germany, and Japan, creating talent gravity that shapes regional service capabilities and accreditation density.
United States
Hospital integrated delivery networks aggregate calibration demand across multi-hospital systems to secure volume pricing from A2LA-accredited laboratories. FDA quality system regulation updates compel biomedical engineering departments to rebuild vendor qualification frameworks around automated traceability documentation. Academic medical centers in Boston and Stanford deploy monthly recertification cycles using AI-enabled drift prediction for imaging modalities.
Germany
EU MDR technical documentation requirements drive calibration partnerships with ISO 17025-accredited laboratories for conformity assessment procedures. Siemens Healthineers leverages captive metrology infrastructure across manufacturing sites in Erlangen and Forchheim to control turnaround times. The country's national measurement institute anchors traceability chains for ionizing radiation reference standards serving European device manufacturers.
Japan
PMDA quality system updates pressure hospital biomedical departments to invest in automated traceability systems for patient monitoring device fleets. Tokyo and Osaka metropolitan clusters host the densest concentration of ISO 17025-accredited calibration laboratories in Asia-Pacific. Domestic imaging equipment manufacturers maintain captive calibration capabilities to service installed base recertification requirements.
India
The central drugs regulator tightens accuracy requirements for pathology analyzers and imaging equipment in tier-2 and tier-3 cities outside established metropolitan clusters. CDSCO enforcement actions against non-compliant diagnostic laboratories accelerate demand for accredited calibration partnerships. Hyderabad and Bengaluru emerge as service hubs for field-deployable reference standards serving clinic-based portable ultrasound systems.
United Kingdom
UKAS-accredited laboratories capture share from manufacturer-captive service arms by guaranteeing faster turnaround times for patient monitoring device recertification. EU MDR alignment pressures device manufacturers serving European markets to demonstrate continuous metrological traceability through notified body audits. London and Cambridge academic medical centers pioneer blockchain-anchored calibration record retention exceeding fifteen years.
Global Medical Equipment Calibration Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across service tiers defined by accreditation breadth and geographic coverage density. The market structure fragments between captive metrology arms of imaging equipment manufacturers and independent service organizations with distributed laboratory networks. Three archetypes dominate: integrated healthcare technology conglomerates with in-house calibration infrastructure; independent accredited laboratories with regional service footprints; and precision measurement instrument manufacturers extending into service revenue streams. Consolidation pressures intensify as hospital procurement departments unbundle calibration from OEM maintenance contracts, while technology licensing agreements proliferate for software-based drift prediction platforms.
Among diversified healthcare technology conglomerates, Siemens Healthineers and GE Healthcare exemplify the captive infrastructure archetype, leveraging manufacturing-integrated metrology capabilities to control service delivery economics. Transcat occupies a position within the independent accredited laboratory tier, anchoring competitive positioning through distributed North American service networks. Fluke Corporation represents the precision instrument manufacturer extension model, dominating handheld electrical safety analyzer calibration where hospital biomedical engineering departments require annual traceability documentation.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Transcat |
| Fortive |
| Fluke Corporation |
| Tektronix |
| Trescal |
| Koninklijke Philips |
| JM Test Systems |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Hospital integrated delivery networks in the United States concentrate procurement volume for calibration services, driving a contract-based pricing model where multi-year agreements secure preferential rates for annual traceability programs across patient monitoring fleets.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture in medical equipment calibration. OEM maintenance contracts historically bundled calibration with repair services at premium rates; hospital procurement departments now unbundle these functions to secure direct relationships with A2LA-accredited laboratories. Price differentiation hinges on ISO 17025 certification tier and geographic service density, with metropolitan clusters commanding lower per-unit costs than distributed rural coverage. Pricing pressure stems from group purchasing organization aggregation of multi-hospital demand. Diagnostic centers exhibit highest price sensitivity due to thinner operating margins, while academic medical centers prioritize turnaround speed over unit cost.
Supply Chain Analysis
Direct-to-hospital channels serve integrated delivery networks with dedicated account management, while distributor-mediated pathways handle fragmented outpatient facility demand. Primary metrology-grade reference artifacts for ionizing radiation and magnetic field calibration concentrate among national measurement institutes in the United States, Germany, and Japan. The supply chain draws from specialized HVAC equipment for temperature-controlled laboratory environments, precision measurement instrumentation, and qualified metrologist labor pools. Single-source vulnerability pervades reference standard procurement, where three national institutes anchor global traceability chains. Distribution runs through accredited laboratory networks with regional service footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical equipment calibration functions as a stable compounder, with regulatory mandates for documented traceability creating non-discretionary demand that renews on annual cycles regardless of macroeconomic conditions.
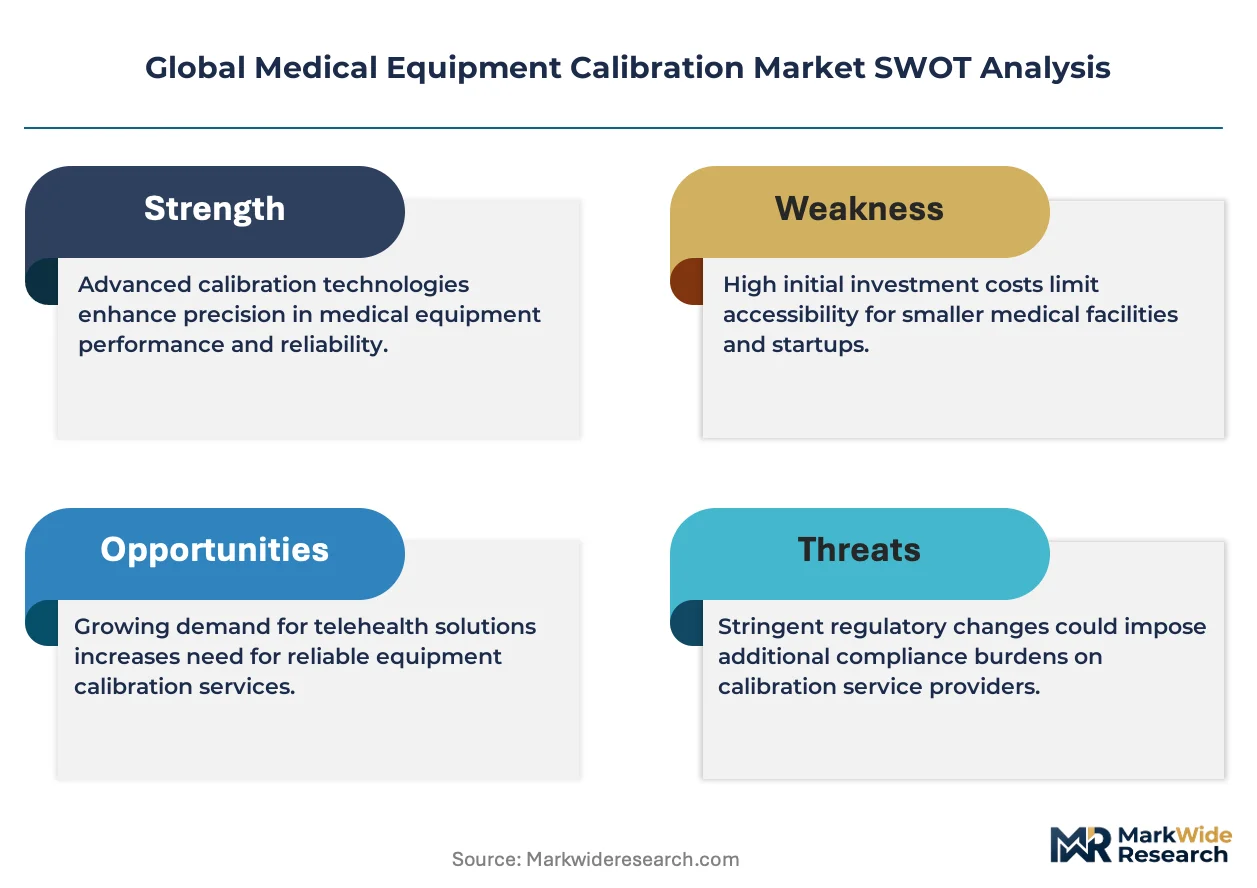
For Market Incumbents: Acquire field-deployable reference standard capabilities to defend against point-of-care device fragmentation. Siemens Healthineers and GE Healthcare should deepen backward integration into automated calibration software platforms, neutralizing the threat of independent service organizations capturing share through faster turnaround guarantees. ISO 17025 accreditation breadth remains the critical defensive lever. For New Entrants and Emerging Players: Enter via cybersecurity-certified remote calibration platforms targeting non-profit health systems unbundling from OEM contracts. India diagnostic laboratory expansion in tier-2 and tier-3 cities offers the most penetrable geography, with CDSCO enforcement actions accelerating demand for accredited partnerships. A software-first go-to-market angle bypasses capital-intensive laboratory infrastructure requirements. For Investors and Strategic Acquirers: Precision measurement instrument manufacturers are the most active acquirer in this space, extending hardware franchises into recurring service revenue streams. The five-to-ten year viability window favors platforms with cloud-connected predictive maintenance capabilities. Acquisition targets should demonstrate A2LA or UKAS accreditation with established hospital system relationships. The signal to watch is FDA draft guidance finalization on networked medical device security requirements, which will reshape vendor qualification frameworks and favor early movers with hardware security module integration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Expansion | EU MDR technical documentation requirements mandate accredited laboratory partnerships for European market access. |
| Automated Traceability System Deployment | FDA quality system regulation updates compel continuous documentation chains from reference standards to field instruments. |
| Remote Calibration Platform Development | Cloud-connected analytics enable predictive maintenance scheduling that reduces unplanned downtime for patient monitoring fleets. |
| Cybersecurity Certification Investment | FDA draft guidance on networked medical device security creates first-mover advantage for encrypted data transmission protocols. |
| Point-of-Care Reference Standard Miniaturization | Portable ultrasound and handheld diagnostic proliferation fragments demand toward field-deployable verification without transport logistics. |
Research Methodology
Direct dialogue with biomedical engineering directors, hospital procurement managers, GPO contracts specialists, and calibration service operations heads grounded qualitative assessment. Secondary validation drew from FDA quality system regulation filings, EU MDR technical documentation guidance, ISO 17025 accreditation databases, and hospital procurement contract disclosures. Bottom-up and top-down triangulation cross-checked service provider capacity estimates against end-user demand aggregation.
Bottom-up modeling calibrated individual laboratory throughput against hospital system contract volumes, while top-down analysis anchored aggregate market sizing to regulatory mandate expansion trajectories. Segmentation dimensions spanned equipment type, protocol automation level, clinical application, and facility scale. CAGR derivation incorporated accreditation requirement phase-in schedules and predictive maintenance adoption curves. Forecast inputs included PMDA quality system update implementation timelines and CDSCO enforcement action intensities.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in tier-2 and tier-3 Indian diagnostic laboratory compliance data introduce uncertainty bands around emerging market penetration assumptions. Forecasts reflect documented base assumptions regarding EU MDR post-market surveillance mandate adherence rates and FDA automated traceability system adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Spinal Surgery Tables Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Global Bone Densitometer Market
Medical Equipment
Global Microtome Market
Medical Equipment
Dialyzer Reprocessing Machines and Concentrates Market
Medical Equipment
Europe Medical Automation Market
Medical Equipment
China Radiotherapy Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
North America Durable Medical Equipment Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Contact Lens Inspection Equipment Market
Medical Equipment
Marijuana Drying and Curing Equipment Market