
 Peripheral Neuritis Treatment Market | 2026-2036
Peripheral Neuritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Neuritis Treatment Market Analytics
Project finance for late-stage neurology pipelines is fragmenting competitive entry barriers across the peripheral neuritis landscape. GSK plc leverages its established pain franchise to sustain manufacturing scale in topical and oral neuropathic pain categories. Pfizer Inc. anchors its position through R&D intensity in anticonvulsant formulations, while Eli Lilly and Company differentiates via channel control across hospital and rehabilitation center networks.
Peripheral neuritis treatment encompasses pharmacological and non-pharmacological interventions targeting inflammation, demyelination, or metabolic injury of peripheral nerves, with therapeutic efficacy measured by pain scores, nerve conduction velocity, and functional recovery metrics. The primary purpose centers on interrupting pathological signaling, restoring nerve integrity, and preventing progression to chronic neuropathic syndromes. Anticonvulsants and antidepressants together occupy the largest product-type margin pools, reflecting their first-line status in evidence-based guidelines. Injectable delivery modes represent the fastest-growing structural category, driven by clinic-administered biologics and long-acting depot formulations that reduce home-care compliance burdens.
FDA breakthrough therapy designation and EMA adaptive pathways now shape development priorities for novel peripheral neuritis candidates, compressing phase transitions and expanding label opportunities. The WHO Essential Medicines List inclusion criteria for neuropathic pain agents further standardize procurement patterns across public health systems. Stakeholders must monitor evolving CMS national coverage determinations for invasive neuromodulation procedures, as these reimbursement decisions will redistribute volume across medication, physical therapy, and surgical intervention segments.
Market Dynamics
Hospital-based pain management programs now drive volume concentration, compressing reimbursement timelines and forcing manufacturers to demonstrate nerve conduction velocity improvements within shorter clinical observation windows.
Growth Catalysts
- Medicare reimbursement expansion:CMS national coverage determinations for chronic pain services broaden patient access to advanced neuritis interventions across United States hospital networks.
- FDA breakthrough therapy designation:The accelerated approval pathway compresses phase transitions for novel analgesic entities, expanding label opportunities for peripheral neuropathy candidates.
- Injectable biologics:Long-acting depot formulations reduce home-care compliance burdens, shifting administration from patient-managed oral regimens to clinic-administered protocols.
Market Restraints
- Specialized neurology talent scarcity:Certified pain management specialists and electrodiagnostic technicians concentrate in major metropolitan academic medical centers, limiting rural and community hospital program expansion.
- EMA adaptive pathway uncertainty:Conditional marketing authorizations based on surrogate endpoints create post-approval evidence generation obligations that strain smaller developer balance sheets.
- Generic anticonvulsant price erosion:First-line gabapentin and pregabalin commoditization compresses margin pools for oral neuropathic pain categories, forcing portfolio diversification into injectable and device-based alternatives.
Strategic Opportunities
- Rehabilitation center channel penetration:Post-acute care facilities represent underdeveloped distribution nodes for combination pharmacological-physical therapy protocols targeting functional recovery metrics.
- WHO Essential Medicines List alignment:Procurement standardization across public health systems in India and Brazil creates volume aggregation opportunities for manufacturers meeting inclusion criteria.
- Digital therapeutics convergence:Remote nerve conduction monitoring paired with algorithmic dosing adjustment enables outcome-based contracting with United States accountable care organizations.
Industry Challenges
- Biomarker validation timelines:FDA qualification of peripheral nerve regeneration surrogate endpoints requires multi-year longitudinal studies, delaying label expansion for novel mechanisms.
- Legacy EMR integration:Pain score standardization across Cerner, Epic, and Meditech systems fragments real-world evidence collection for payor contract negotiations.
- Cross-border licensing complexity:Patent thickets covering sodium channel modulators create freedom-to-operate uncertainty for developers targeting diabetic peripheral neuropathy indications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Neuritis Treatment Market |
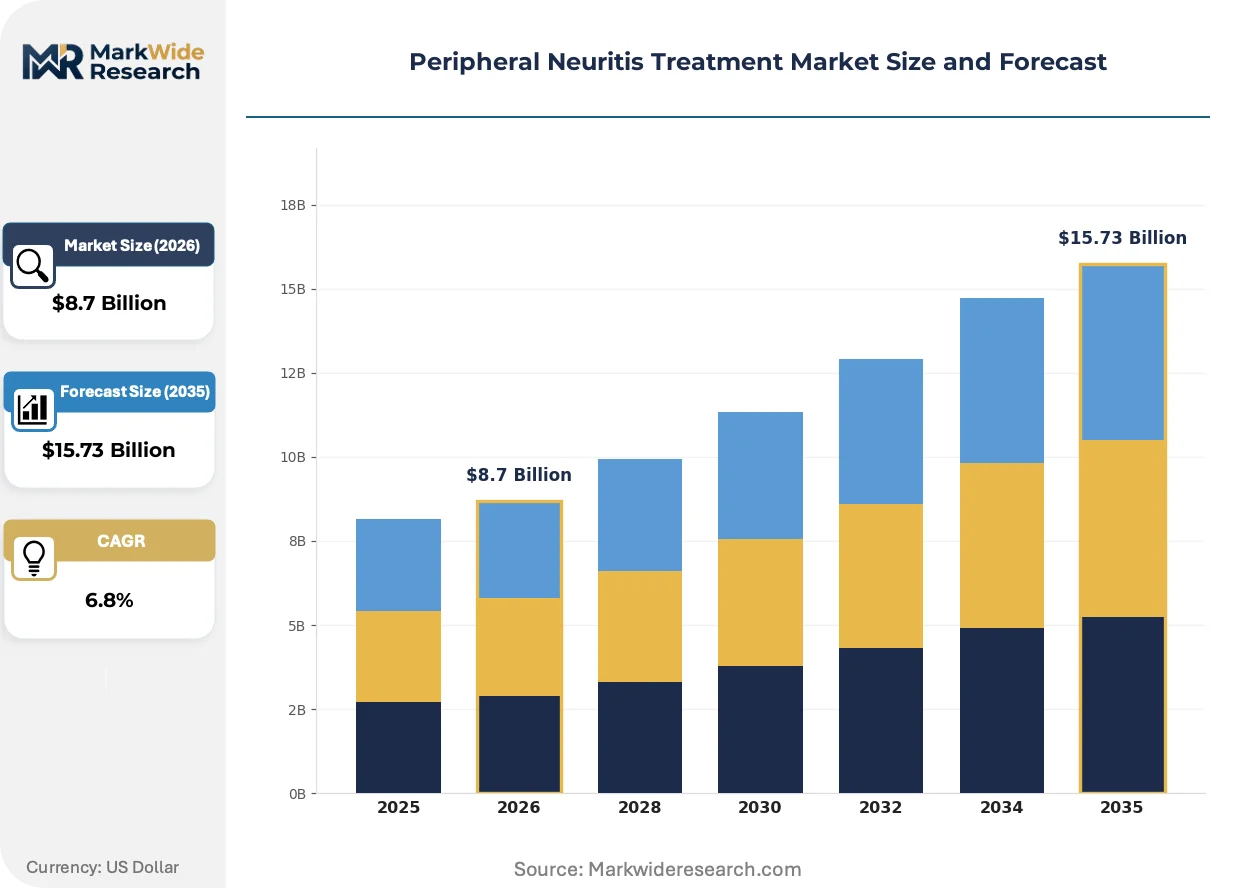
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Anticonvulsants, Topical Treatments, Opioids Treatment Approach: Medication, Physical Therapy, Alternative Therapies, Surgical Interventions Delivery Mode: Oral, Injectable, Transdermal, Intravenous End User: Hospitals, Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | GSK plc, AstraZeneca Plc, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Abbott Laboratories, Johnson & Johnson, Eli Lilly and Company, Boehringer Ingelheim, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Neuritis Treatment Market Evolving Landscape
Neuromodulation device miniaturization and biologics manufacturing scale-up are collapsing traditional boundaries between pharmacological and interventional pain management categories.
Gene therapy vectors targeting nerve growth factor signaling are collapsing the historical separation between disease-modifying and symptomatic treatment paradigms. Academic medical centers in the United States and Germany are establishing dedicated peripheral neuropathy gene therapy infusion suites. This compression is forcing pharmaceutical manufacturers to reposition small-molecule assets alongside viral vector platforms in integrated pipeline portfolios.
EMA's adaptive pathways framework now permits conditional marketing authorization based on phase 2 biomarker data, with post-authorization efficacy studies required for full approval. This regulatory innovation accelerates European patient access to novel sodium channel inhibitors while imposing evidence generation obligations that reshape clinical trial design strategies. Developers targeting diabetic peripheral neuropathy indications prioritize European launch sequencing to leverage this accelerated entry mechanism.
Hospital procurement committees now bundle neuromodulation devices with dedicated nursing support services, displacing standalone capital equipment purchasing. United States health systems consolidate vendor relationships through multi-year sole-source agreements that wrap device placement, programming, and outcome monitoring into per-procedure fees. This contractual evolution concentrates purchasing power among integrated delivery networks and marginalizes smaller device manufacturers lacking service infrastructure scale.
Peripheral Neuritis Treatment Market Segmentation
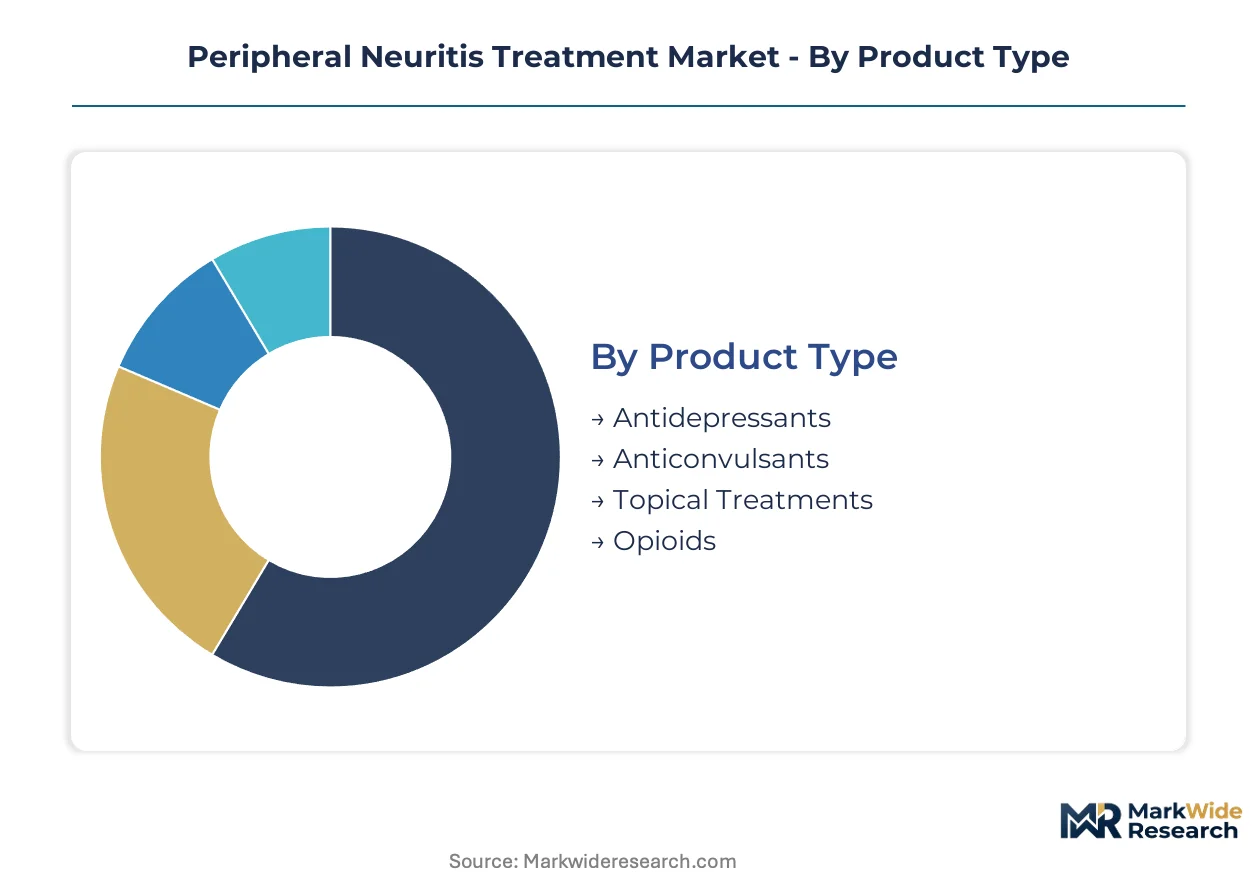
Peripheral neuritis treatment segments fragment across pharmacological mechanisms, care delivery settings, and administration technologies. Manufacturers configure service intensity and clinical support models differently for each segment cluster.
Product Type:
After-sales service intensity varies sharply across drug classes, with biologics and specialty formulations demanding dedicated nursing support and adverse event monitoring infrastructure that commoditized oral agents do not require.
- Anticonvulsants:Gabapentinoids modulate voltage-gated calcium channels to dampen ectopic neuronal firing. United States hospital formularies prioritize these agents for first-line neuropathic pain protocols, though generic pregabalin erosion has compressed manufacturer margins and forced portfolio restructuring toward extended-release formulations.
- Antidepressants:Serotonin-norepinephrine reuptake inhibitors and tricyclic compounds interrupt descending pain facilitation pathways. German rehabilitation centers favor duloxetine for diabetic peripheral neuropathy given EMA reimbursement alignment with functional outcome metrics rather than pain scores alone.
- Topical Treatments:Local anesthetic patches and capsaicin formulations target peripheral nerve terminals with minimal systemic exposure.
- Opioids:Tramadol and tapentadol occupy restricted-use niches given FDA boxed warnings and CMS audit scrutiny.
By volume, anticonvulsants lead. By growth pace, topical treatments are expanding most quickly.
Treatment Approach:
Cost tier stratification separates acute intervention protocols from chronic management programs, with surgical and device-based approaches commanding premium pricing against pharmacological maintenance regimens.
- Medication:Systemic drug therapy encompasses oral, injectable, and transdermal administration routes targeting molecular pain mechanisms. United States Medicare Part D formularies increasingly require step therapy through generic anticonvulsants before approving branded alternatives.
- Physical Therapy:Neuromuscular re-education and desensitization protocols restore functional capacity through graded exercise and manual techniques. Japanese METI reimbursement codes for peripheral neuropathy rehabilitation favor clinic-based over home-based delivery.
- Alternative Therapies:Acupuncture and transcutaneous electrical nerve stimulation occupy adjunctive care roles.
- Surgical Interventions:Nerve decompression and neuroma excision address structural etiologies.
By patient volume, medication dominates. By value concentration, surgical interventions generate the steepest expansion trajectory.
Delivery Mode:
Volume distribution across administration routes reflects compliance burden trade-offs between patient convenience and clinical oversight requirements.
- Injectable:Long-acting depot formulations and biologics require clinic administration with cold-chain logistics. United States hospital outpatient departments capture disproportionate volume given CMS reimbursement differentials favoring facility-based over physician-office administration.
- Oral:Immediate-release and extended-release tablets dominate prescription volume through pharmacy distribution.
- Transdermal:Patch systems bypass hepatic first-pass metabolism for patients with polypharmacy.
- Intravenous:Hospital infusion suites manage acute exacerbations and loading-dose protocols.
By prescription count, oral formulations lead. By revenue growth, injectable biologics are gaining share fastest.
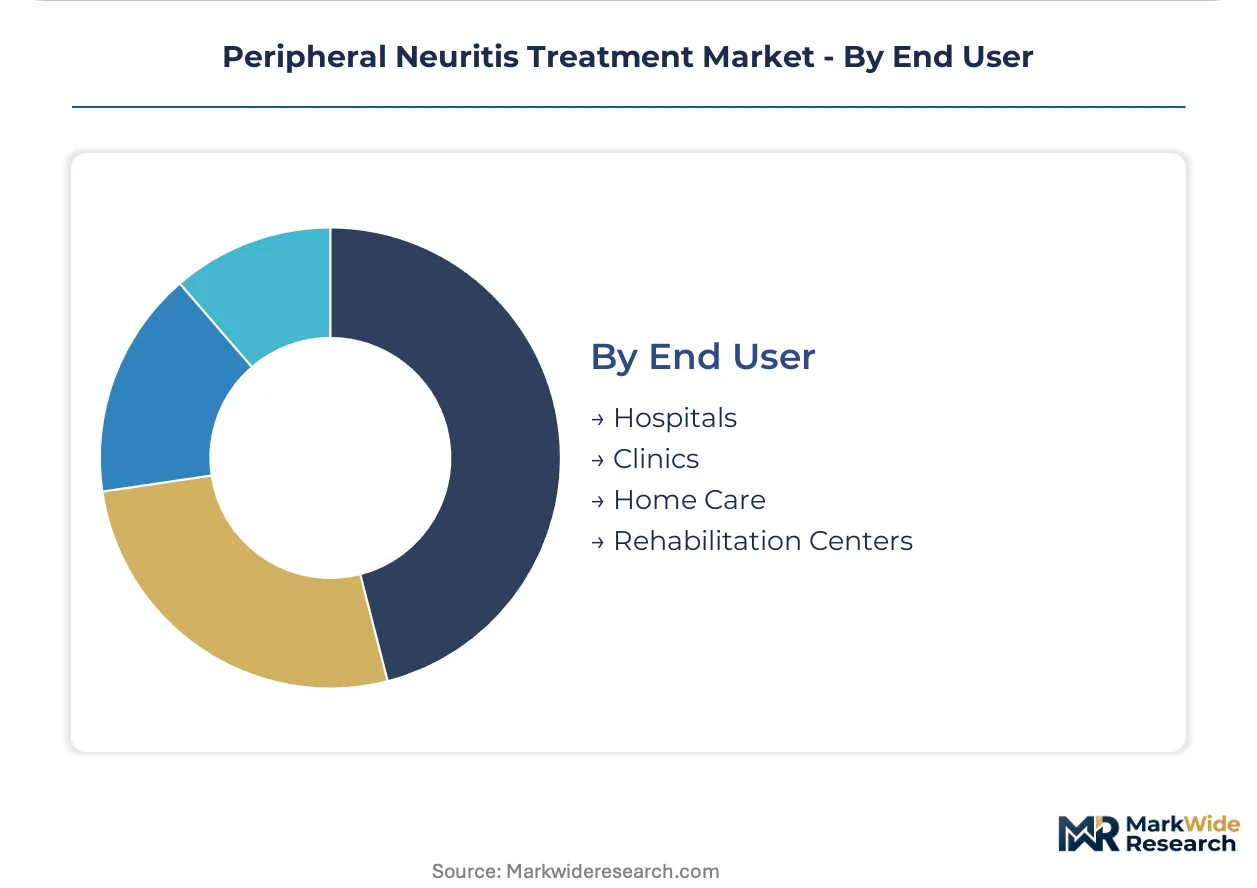
End User:
Customer type determines procurement authority structure, with integrated delivery networks consolidating purchasing decisions across hospital and post-acute settings.
- Hospitals:Academic medical centers and community hospitals operate pain management programs with electrodiagnostic capability. United States health systems increasingly bundle device placement with dedicated nursing support through multi-year vendor agreements.
- Rehabilitation Centers:Post-acute facilities target functional recovery metrics for chronic neuropathy patients. German rehabilitation clinics leverage Diagnosis-Related Group reimbursement incentives to shorten length-of-stay while maintaining outcome standards.
- Clinics:Physician offices and ambulatory surgery centers handle stable patients and routine procedures.
- Home Care:Home health agencies manage oral medication adherence and wound care.
By procedure volume, hospitals lead. By expansion rate, rehabilitation centers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement expansion for chronic pain services is reshaping hospital procurement patterns in the United States. FDA breakthrough therapy designations accelerate novel analgesic entry timelines across North American markets. EMA adaptive pathways in Europe compress phase transitions for sodium channel inhibitors targeting diabetic peripheral neuropathy.
United States
Hospital-based pain management programs drive volume concentration as CMS national coverage determinations broaden patient access to advanced neuritis interventions. The FDA's accelerated approval pathways compress development timelines for novel analgesic entities. Academic medical centers in Boston and the Mayo Clinic cluster in Minnesota establish dedicated peripheral neuropathy gene therapy infusion suites.
Germany
Rehabilitation centers leverage Diagnosis-Related Group reimbursement incentives to shorten length-of-stay while maintaining functional outcome standards. EMA adaptive pathways permit conditional marketing authorization based on phase 2 biomarker data for novel sodium channel inhibitors. The Heidelberg and Berlin university hospital networks anchor electrodiagnostic capability concentration for complex neuropathy cases.
Japan
METI reimbursement codes for peripheral neuropathy rehabilitation favor clinic-based over home-based delivery models. PMDA consultation programs accelerate regulatory dialogue for gene therapy vectors targeting nerve growth factor signaling. The Kanto region around Tokyo hosts the highest density of certified pain management specialists and electrodiagnostic technicians.
India
WHO Essential Medicines List inclusion criteria standardize procurement patterns across public health systems in Maharashtra and Gujarat. CDSCO streamlined approval processes for biologics manufacturing scale-up attract contract development investments. The Delhi-NCR corridor concentrates rehabilitation center expansion for post-acute neuropathy care protocols.
Brazil
ANVISA regulatory harmonization with FDA standards accelerates market entry for long-acting depot formulations. Public health system procurement aggregation in São Paulo and Minas Gerais creates volume opportunities for manufacturers meeting essential medicines criteria. The São Paulo metropolitan area anchors the largest concentration of hospital-based pain management programs in Latin America.
Peripheral Neuritis Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hospital, rehabilitation center, and clinic delivery settings. The market structure consolidates around diversified pharmaceutical conglomerates with established pain franchises and emerging biologics specialists with manufacturing scale in injectable categories. Three archetypes dominate: legacy analgesic portfolio holders, gene therapy platform developers, and neuromodulation device manufacturers with service-wrapped offerings. Competitive moves center on portfolio diversification into injectable biologics and strategic partnerships for digital therapeutics convergence.
Among diversified pharmaceutical conglomerates, GSK plc exemplifies the legacy pain franchise archetype with manufacturing scale in topical and oral neuropathic pain categories. Pfizer Inc. occupies a position within the anticonvulsant formulation specialist tier, while Eli Lilly and Company anchors the channel control archetype across hospital and rehabilitation center networks. These three entities represent distinct competitive positioning vectors within the peripheral neuritis treatment landscape.
| Leading Market Players |
|---|
| GSK plc |
| AstraZeneca Plc |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Abbott Laboratories |
| Johnson & Johnson |
| Eli Lilly and Company |
| Boehringer Ingelheim |
| Novartis AG |
| Others |
Value Network & Pricing Analysis
Active pharmaceutical ingredient manufacturing for gabapentinoids and sodium channel modulators concentrates in India and China, anchoring margin distribution toward finished-dose formulators in the United States and Germany who control FDA and EMA certification gates. This upstream concentration grants certified manufacturers pricing power over generic entrants lacking bioequivalence study infrastructure.
Pricing Analysis
Certification level creates the primary spread between premium branded formulations and commodity generics. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough therapy designation status, EMA adaptive pathway conditional approval, and WHO Essential Medicines List inclusion. Cost compression in oral anticonvulsant categories intensifies because pregabalin and gabapentin generic erosion eliminates brand premiums. Hospital procurement committees exhibit lowest price sensitivity given bundled device-service contracts, while retail pharmacy channels face highest sensitivity due to Medicare Part D step therapy requirements.
Supply Chain Analysis
Upstream feedstock for neuropathic pain APIs draws from specialty chemical precursors manufactured in Gujarat and Zhejiang provinces, with intermediate purification stages anchored in Hyderabad and Shanghai pharmaceutical clusters. Cold-chain biologics manufacturing for injectable depot formulations rests on temperature-controlled logistics infrastructure concentrated in the United States, Germany, and Japan. Single-source vulnerability pervades gene therapy vector production, where academic medical center infusion suites depend on limited qualified viral vector suppliers. Distribution runs through integrated delivery networks consolidating hospital and rehabilitation center procurement under multi-year sole-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy vectors targeting nerve growth factor signaling represent a high-growth disruption, with FDA breakthrough therapy designation compressing traditional development timelines and collapsing historical boundaries between disease-modifying and symptomatic treatment paradigms.
For Market Incumbents: Harden manufacturing scale advantages in injectable biologics through captive supply of cold-chain logistics infrastructure, insulating against gene therapy platform developers encroaching on clinic-administered protocols. Deepen backward integration into API precursors for sodium channel modulators to defend margin pools against Indian and Chinese contract manufacturers advancing up the value chain.
For New Entrants and Emerging Players: Rehabilitation centers in Germany and Japan represent the most penetrable entry point, given Diagnosis-Related Group reimbursement incentives and METI facility-based delivery codes that concentrate purchasing authority in underdeveloped distribution nodes. Digital therapeutics convergence enabling remote nerve conduction monitoring offers a software-enabled go-to-market angle bypassing capital-intensive biologics manufacturing.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed neuromodulation device manufacturers lacking service infrastructure scale to compete for hospital sole-source agreements. Five-to-ten year viability hinges on portfolio diversification into gene therapy platform capabilities or digital therapeutics adjacencies. The signal to watch is CMS national coverage determination expansion for invasive neuromodulation procedures, which would redistribute capital toward device-service bundled models and away from pure-play pharmaceutical assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Cold-chain biologics capacity expansion secures hospital outpatient department volume under CMS reimbursement differentials. |
| Regulatory Approval Pathway | EMA adaptive pathway submission accelerates European patient access for novel sodium channel inhibitors ahead of FDA timelines. |
| Hospital System Partnership | Multi-year sole-source agreements with integrated delivery networks bundle device placement with dedicated nursing support. |
| Pipeline Diversification | Gene therapy vector platforms reposition small-molecule assets alongside viral vectors in academic medical center infusion suites. |
| Reimbursement Strategy | WHO Essential Medicines List alignment standardizes procurement across public health systems in India and Brazil. |
Research Methodology
The analysis maps anticonvulsant formulations, injectable biologics, neuromodulation devices, and gene therapy vectors, each validated through pain management specialists, hospital procurement managers, formulary directors, and regulatory affairs leads. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare data establish baseline metrics. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation reconcile segment estimates.
Assumptions held fixed include current FDA breakthrough therapy designation criteria, EMA adaptive pathway conditional approval standards, and WHO Essential Medicines List inclusion thresholds, while Medicare reimbursement expansion rates and gene therapy manufacturing scale-up timelines varied across sensitivity scenarios. Segmentation dimensions modeled encompass product mechanism, delivery mode, end-user setting, and regional regulatory cluster. CAGRs derived from longitudinal prescription audit data and hospital procurement database trends, with nerve conduction velocity surrogate endpoint validation timelines and biologics cold-chain logistics capacity serving as industry-specific forecast inputs.
Practitioners should monitor biomarker qualification delays, generic anticonvulsant price erosion acceleration, and gene therapy manufacturing batch failure rates for early signals requiring forecast revision. Cross-checking against CMS national coverage determination tracking databases and EMA post-authorization study completion rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Hepatic Encephalopathy Market
Neurology
Arachnoiditis Market
Neurology
Spasticity Treatment Market
Neurology
Chile Neurology Devices Market
Neurology
Sweden Neurology Devices Market
Neurology
White Matter Injury Treatment Market
Neurology
Pediatric Neurology Device Market
Neurology
Germany Neurology Devices Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
Diabetic Neuropathy Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Movement Disorder Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Italy Neurology Devices Market
Neurology
Intracranial Aneurysm Market