
 Refurbished Medical Equipment Market | 2026-2036
Refurbished Medical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Refurbished Medical Equipment Market Intelligence
Software-defined imaging upgrades is decoupling hardware ownership from diagnostic capability in the refurbished medical equipment sector. GE Healthcare leverages remote monitoring overlays to extend functional lifespan on refurbished CT and MRI platforms. Siemens Healthineers anchors European refurbishment networks with proprietary parts logistics. Koninklijke Philips competes through predictive maintenance contracts that reduce total cost of ownership for mid-tier hospital buyers.
Refurbished medical equipment comprises previously deployed diagnostic, therapeutic, and monitoring devices restored to original manufacturer specifications through component replacement, calibration, and safety testing, typically achieving 70-85% of new-equipment performance at 30-50% of acquisition cost. The primary commercial purpose is capital-efficient healthcare delivery for budget-constrained providers. Imaging Systems dominate transaction volumes due to high replacement rates for CT, MRI, and ultrasound modalities, while Patient Monitors represent the fastest-turning segment with shorter refurbishment cycles and lower regulatory barriers. Diagnostic Centers now drive disproportionate demand growth as independent imaging chains expand fleet capacity without new-equipment capex burdens.
FDA 510(k) premarket notification requirements govern refurbished device legality in the United States, while EU MDR and CE marking obligations tighten traceability for remanufactured products entering European clinical settings. ISO 13485 quality management standards further constrain supplier qualification, filtering informal refurbishers from institutional procurement channels. Stakeholders must monitor evolving MDR technical documentation requirements and FDA guidance on remanufacturing versus servicing distinctions to preserve market access across jurisdictions.
Market Dynamics
Software-defined imaging upgrades are decoupling hardware ownership from diagnostic capability, forcing OEMs to pivot from equipment sales to lifecycle service contracts. This structural shift compresses replacement cycles for refurbished platforms while expanding addressable demand among capital-constrained providers.
Growth Catalysts
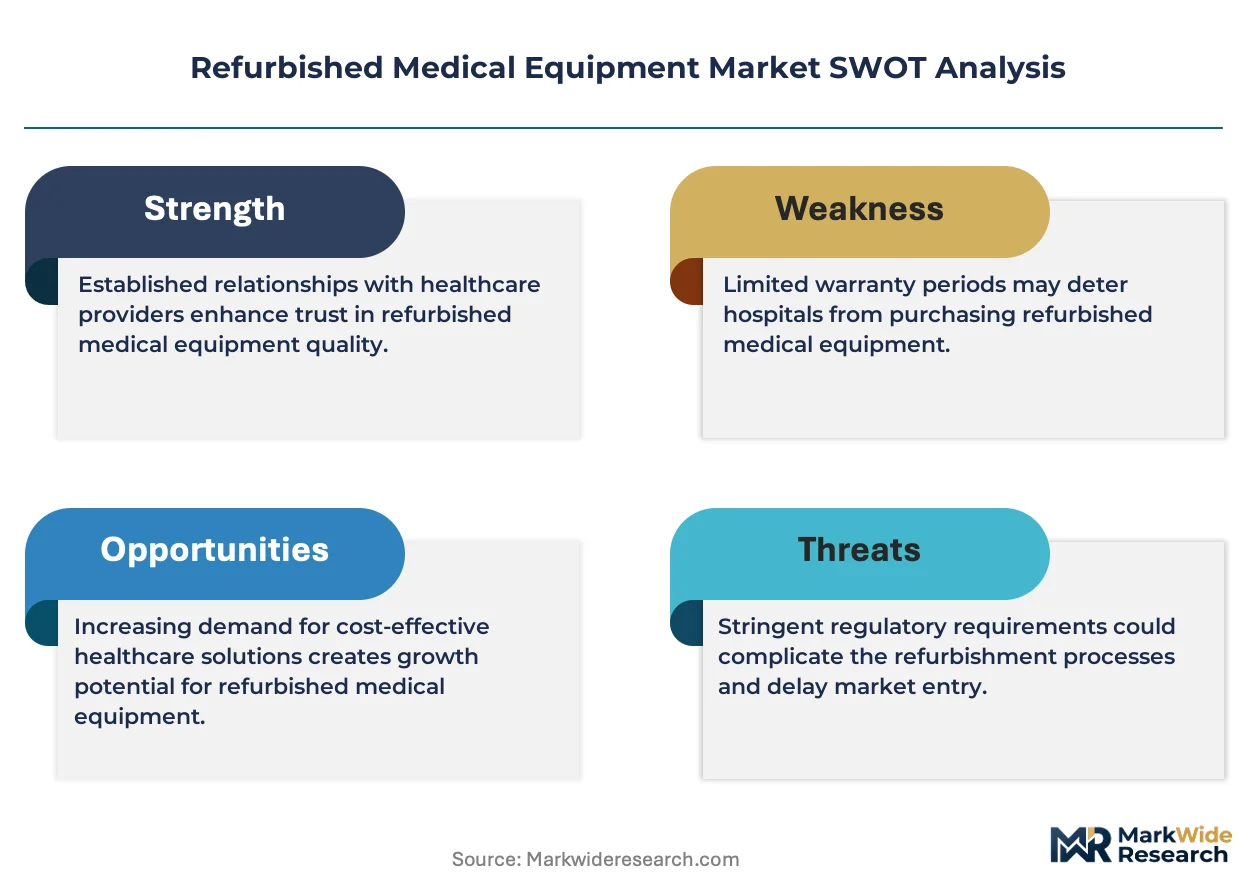
- FDA 510(k) Pathway Clarity:The United States regulator's refined guidance on remanufacturing versus servicing distinctions reduces compliance ambiguity for refurbished device vendors, accelerating institutional procurement approvals.
- Rural Diagnostic Center Expansion:India's public hospital networks and private imaging chains are scaling secondary equipment purchases to bridge healthcare access gaps in tier-2 and tier-3 cities.
- EU MDR Technical Documentation Harmonization:Standardized traceability requirements for remanufactured devices enable cross-border refurbishment network consolidation, lowering per-unit compliance costs for European vendors.
Market Restraints
- ISO 13485 Supplier Qualification Barriers:Quality management certification requirements filter informal refurbishers from institutional procurement channels, concentrating supply among capital-intensive operators.
- Component Obsolescence Risk:Proprietary parts logistics for legacy CT and MRI platforms face discontinuation pressure as OEMs sunset support for older modalities.
- CE Marking Timeline Compression:EU MDR's tightened clinical evidence requirements extend remanufacturing certification cycles, delaying inventory turnover for European-focused refurbishers.
Strategic Opportunities
- Predictive Maintenance Contract Penetration:Remote monitoring overlays on refurbished imaging systems create recurring revenue streams and deepen customer lock-in for mid-tier hospital buyers.
- Patient Monitor Segment Acceleration:Shorter refurbishment cycles and lower regulatory barriers in monitoring devices enable faster inventory turns compared to imaging modalities.
- India PLI Scheme Alignment:Production-linked incentive frameworks for medical device manufacturing create localized refurbishment hub potential for diagnostic equipment serving South Asian markets.
Industry Challenges
- Remanufacturing Technician Scarcity:Specialized calibration and safety testing expertise for restored diagnostic equipment outpaces vocational training program output, constraining refurbishment throughput.
- Legacy System Integration Complexity:Refurbished imaging platforms must interface with hospital IT infrastructure spanning multiple vendor generations, requiring costly custom interoperability solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refurbished Medical Equipment Market |
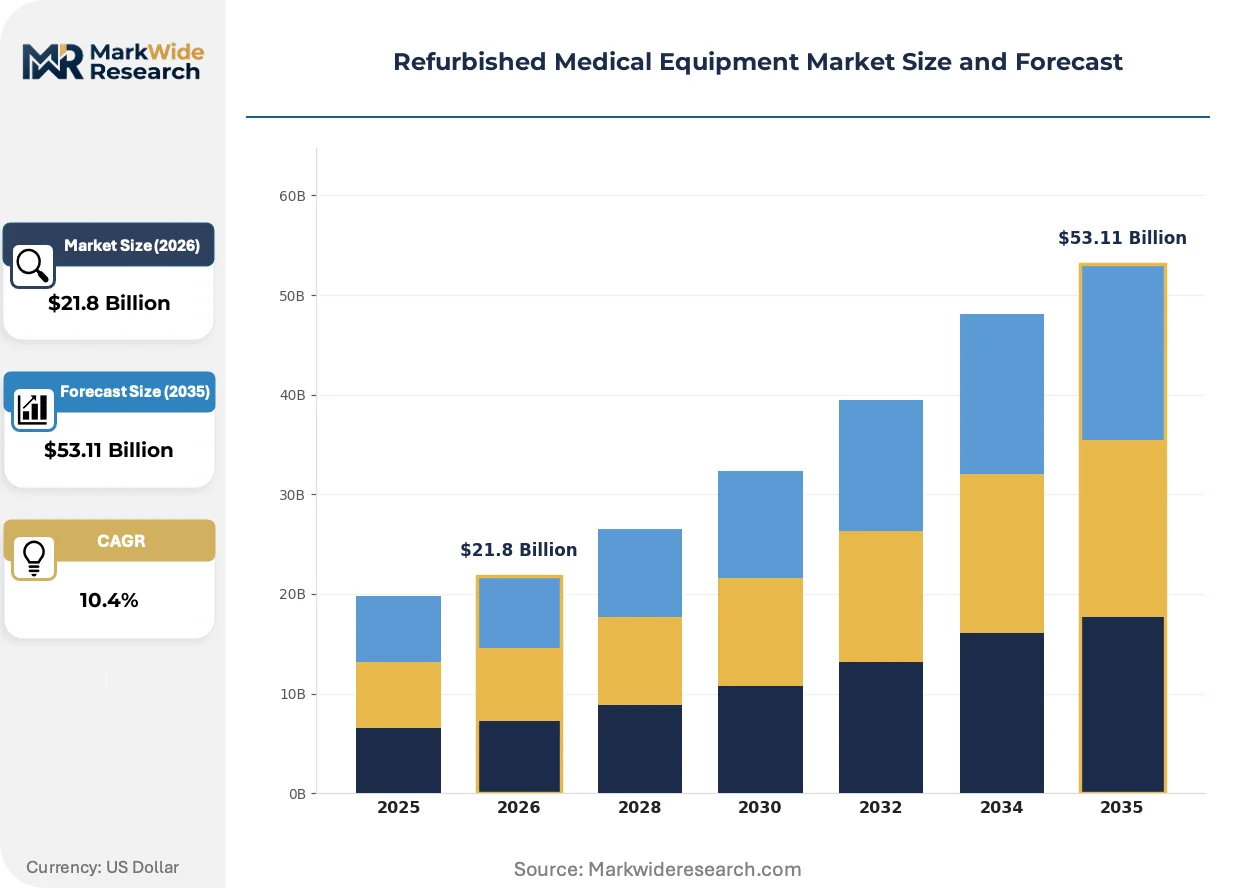
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $53.11 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Surgical Instruments, Patient Monitors, Respiratory Equipment End User: Hospitals, Clinics, Diagnostic Centers, Rehabilitation Facilities Technology: Digital, Analog, Hybrid, Telehealth Service Type: Repair Services, Maintenance, Leasing, Warranty Services |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Soma Technology, Block Imaging International, Canon Medical Systems, Avante Health Solutions, Mindray Medical, Integrity Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refurbished Medical Equipment Market Strategic Shifts & Innovations
Artificial intelligence overlays and remote diagnostics are redefining value capture in refurbished medical equipment, shifting competitive advantage from hardware restoration to software-enabled performance guarantees.
Edge computing architectures for real-time image processing are converging with refurbished CT and MRI platforms to restore diagnostic throughput comparable to new equipment. Diagnostic centers in budget-constrained markets are adopting these retrofitted systems at accelerating pace. The technology is converging with predictive maintenance protocols to compress total cost of ownership calculations for hospital procurement committees.
EU MDR's expanded technical documentation requirements for remanufactured devices are forcing refurbishment vendors to invest in traceability infrastructure. The regulation's clinical evidence standards disproportionately burden smaller operators lacking dedicated regulatory affairs functions. European diagnostic chains are responding by consolidating supplier relationships toward ISO 13485-certified refurbishers with established notified body partnerships.
Independent imaging chains are unbundling equipment acquisition from service contracts, negotiating direct refurbishment relationships that bypass traditional distributor markups. This channel disintermediation concentrates purchasing power among large diagnostic center networks capable of volume commitments. The pattern is most visible across India's private healthcare sector, where capital efficiency mandates drive aggressive secondary equipment sourcing strategies.
Refurbished Medical Equipment Market Segmentation
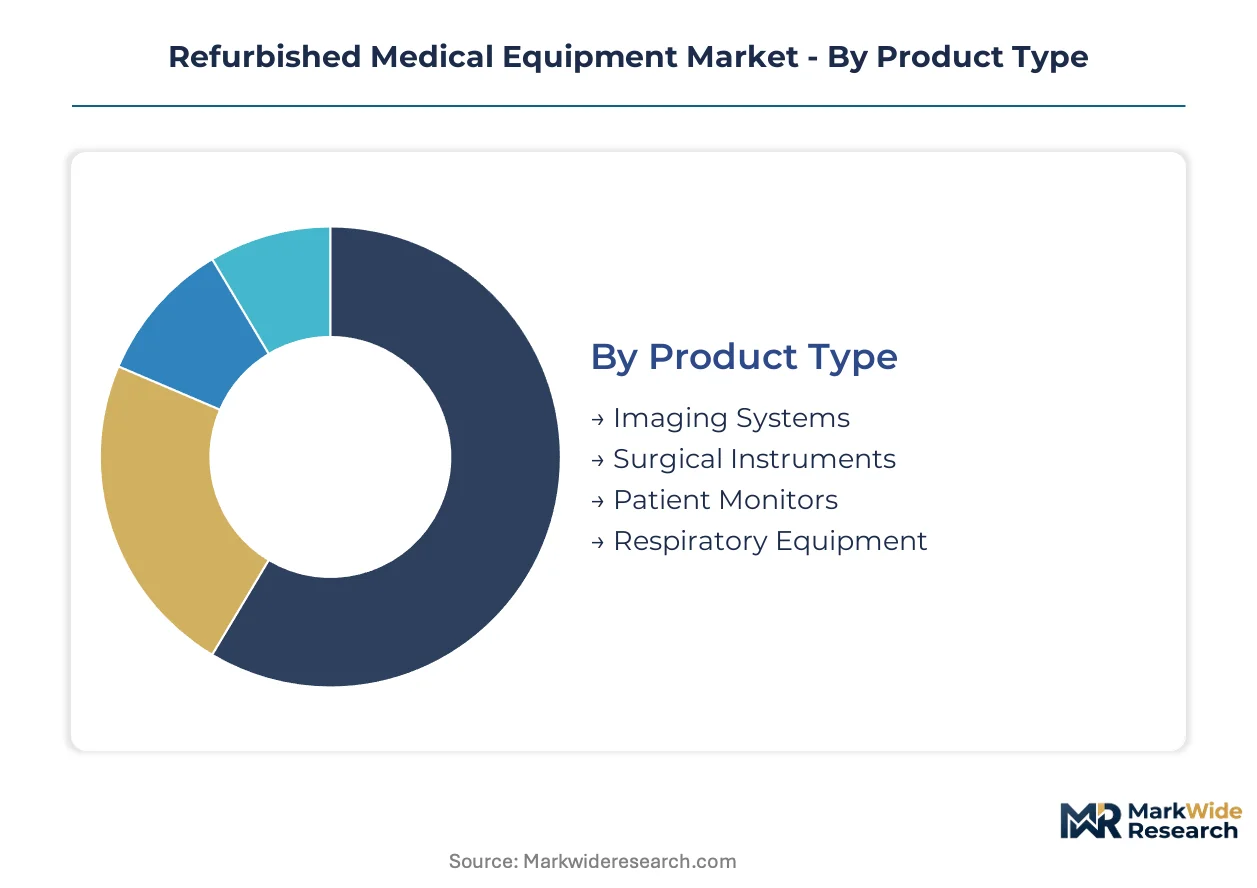
Segmentation in refurbished medical equipment reveals divergent capital efficiency strategies across provider types. Equipment lifecycle economics vary dramatically between high-throughput imaging platforms and rapid-turn monitoring devices, shaping procurement patterns for budget-constrained healthcare systems.
Product Type:
Volume concentration sits with imaging platforms commanding extended refurbishment cycles, while premium pricing attaches to surgical instruments with specialized calibration requirements.
- Imaging Systems:CT, MRI, and ultrasound modalities undergo component replacement, recalibration, and software validation to restore 70-85% of original diagnostic throughput. Demand concentrates across India's private diagnostic chains and public hospital networks bridging rural access gaps, driven by capital expenditure constraints on new-equipment procurement.
- Patient Monitors:Shorter refurbishment cycles and lower regulatory barriers enable faster inventory turns compared to imaging modalities. Diagnostic centers in developing economies deploy these at accelerating pace to expand fleet capacity without new-equipment capex burdens.
- Surgical Instruments:Precision restoration to original manufacturer specifications through metallurgical testing and sterilization validation ensures compliance with FDA 510(k) and EU MDR traceability mandates.
- Respiratory Equipment:Ventilator and oxygen concentrator refurbishment addresses supply continuity needs through component replacement and safety testing protocols.
Mature deployment sits with Imaging Systems. Newer deployment is concentrated in Patient Monitors.
End User:
Procurement authority separates institutional buyers with dedicated biomedical engineering staff from distributed providers relying on third-party refurbishment partnerships.
- Diagnostic Centers:Independent imaging chains unbundle equipment acquisition from service contracts, negotiating direct refurbishment relationships that bypass traditional distributor markups. India's private healthcare sector drives aggressive secondary equipment sourcing strategies to meet capital efficiency mandates.
- Hospitals:Mid-tier hospital buyers leverage predictive maintenance contracts on refurbished imaging systems to reduce total cost of ownership, with procurement committees prioritizing remote monitoring overlays.
- Clinics:Smaller-scale providers source refurbished patient monitors and respiratory equipment through ISO 13485-certified refurbishers to meet quality management standards.
- Rehabilitation Facilities:Secondary-market therapeutic devices address equipment needs for physical therapy and long-term care settings.
Procurement sophistication peaks with Diagnostic Centers. Price sensitivity concentrates in Clinics.
Technology:
Digital architectures command refurbishment premiums over analog legacy systems facing component obsolescence pressures.
- Digital:Software-defined imaging upgrades decouple hardware ownership from diagnostic capability, enabling remote monitoring overlays that extend functional lifespan on refurbished CT and MRI platforms.
- Hybrid:Mixed analog-digital systems bridge legacy infrastructure with modern connectivity requirements, requiring custom interoperability solutions for hospital IT integration.
- Telehealth:Refurbished monitoring devices with embedded connectivity support distributed care models expanding across rural healthcare networks.
- Analog:Legacy platforms face discontinuation pressure as OEMs sunset support for older modalities, constraining parts availability.
Technology migration favors Digital systems. Analog retention persists in cost-constrained settings.
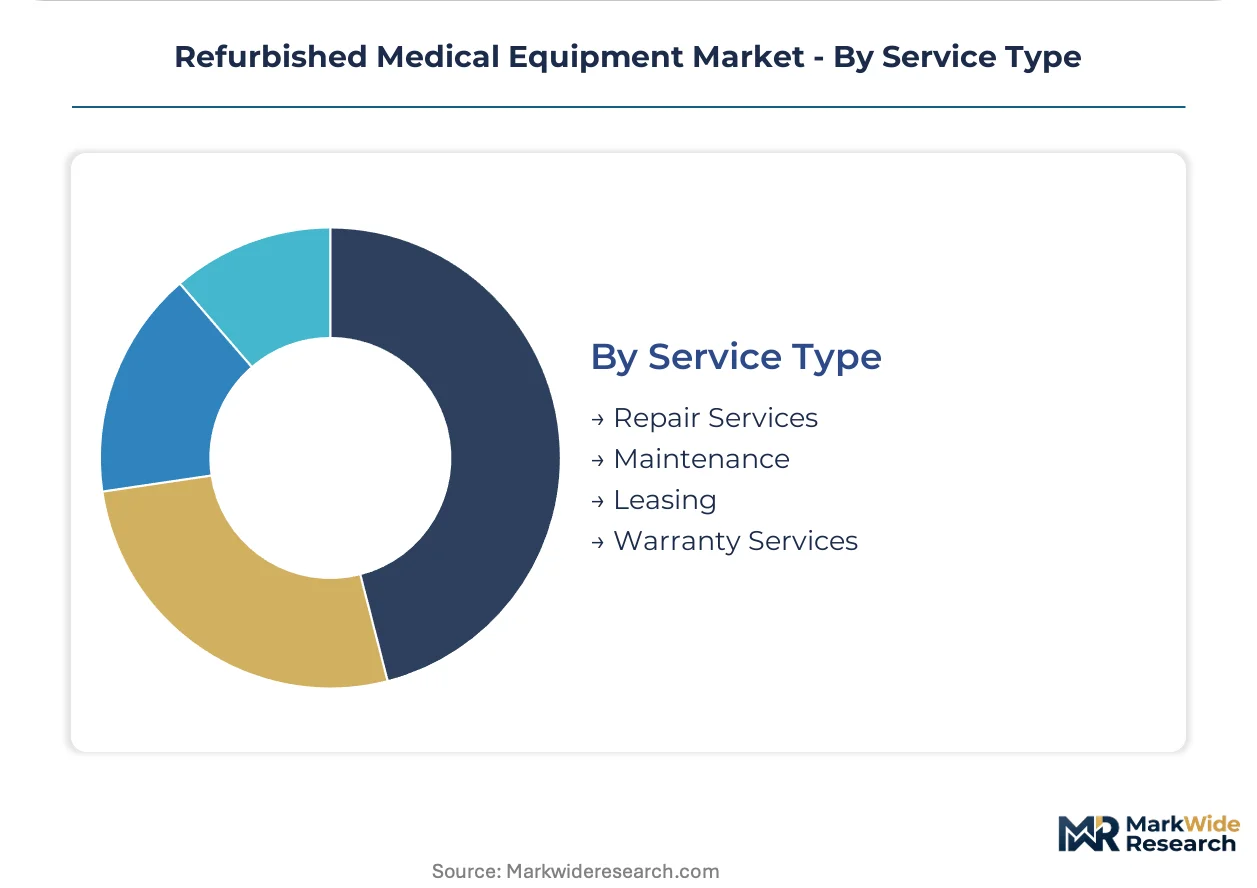
Service Type:
Revenue stability separates recurring service contracts from transactional equipment sales in vendor business models.
- Leasing:Operating lease structures eliminate upfront capital requirements for diagnostic centers expanding fleet capacity, with vendors retaining ownership and refurbishment responsibility.
- Maintenance:Predictive maintenance contracts create recurring revenue streams and deepen customer lock-in through remote monitoring overlays on refurbished imaging systems.
- Repair Services:Component-level restoration addresses equipment failures outside warranty periods, with ISO 13485 certification filtering informal providers from institutional channels.
- Warranty Services:Extended coverage offerings differentiate certified refurbishers from gray-market operators in procurement evaluations.
Contract penetration is deepest in Maintenance. Transactional volume concentrates in Repair Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refurbished medical equipment production concentrates in established manufacturing hubs, while consumption patterns diverge sharply between capital-constrained emerging markets and cost-optimization-focused developed economies.
United States
Diagnostic center chains and mid-tier hospital networks drive secondary equipment procurement to manage capital expenditure pressures. FDA 510(k) clearance pathways provide regulatory clarity for refurbished device vendors, accelerating institutional procurement approvals. The Greater Boston and Minneapolis-St. Paul medical device clusters host established refurbishment operations serving domestic healthcare networks.
Germany
EU MDR technical documentation requirements reshape compliance obligations for remanufactured medical devices entering European clinical settings. ISO 13485 quality management certification filters informal refurbishers from institutional procurement channels. The Baden-Württemberg region anchors continental refurbishment networks with specialized parts logistics infrastructure.
India
Public hospital networks and private diagnostic chains scale secondary equipment purchases to bridge rural healthcare access gaps in tier-2 and tier-3 cities. CDSCO regulatory frameworks and Production-Linked Incentive schemes for medical device manufacturing create localized refurbishment hub potential. Maharashtra and Karnataka host expanding refurbishment operations serving South Asian markets.
China
NMPA oversight of remanufactured medical devices tightens quality assurance requirements for secondary-market equipment distribution. Domestic diagnostic chains deploy refurbished imaging systems to extend fleet capacity without new-equipment capital burdens. The Yangtze River Delta region concentrates refurbishment operations serving provincial hospital networks.
Japan
PMDA regulatory standards for restored medical equipment ensure alignment with domestic quality expectations for secondary-market devices. METI industrial policy supports lifecycle extension initiatives for high-value diagnostic platforms. The Kansai region maintains specialized refurbishment capabilities for domestic healthcare providers.
Refurbished Medical Equipment Market Key Industry Players
Top-tier vendors anchor the premium refurbishment segment with proprietary parts logistics and predictive maintenance capabilities, while mid-tier operators compete on price and regional accessibility. The vendor base stratifies across OEM-affiliated refurbishment networks, independent certified refurbishers, and informal secondary-market operators. Strategic archetypes include lifecycle service integrators, regional refurbishment specialists, and technology-overlay providers. Competitive moves concentrate on predictive maintenance contract penetration and direct-to-diagnostic-center channel disintermediation.
Within the OEM-affiliated tier, GE Healthcare, Siemens Healthineers, and Koninklijke Philips exemplify integrated lifecycle service models. These entities leverage established parts logistics and remote monitoring infrastructure to extend functional lifespan on refurbished imaging platforms. Their positioning reflects a structural shift from equipment sales toward recurring revenue service contracts, with predictive maintenance overlays creating customer lock-in among mid-tier hospital buyers.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Soma Technology |
| Block Imaging International |
| Canon Medical Systems |
| Avante Health Solutions |
| Mindray Medical |
| Integrity Medical Systems |
| Others |
Cost & Logistics Intelligence
Software-defined imaging upgrades are compressing refurbishment economics by decoupling hardware performance from physical asset age, simultaneously concentrating supply power among OEM-affiliated networks with proprietary parts logistics while fragmenting price-setting authority across independent operators lacking remote monitoring infrastructure. This technological shift forces mid-tier refurbishers into cost-down spirals as diagnostic centers demand bundled service contracts that certified incumbents can deliver but price-competitive independents cannot match.
Pricing Analysis
Margin tightening in the standard-tier segment reflects ISO 13485 certification costs filtering informal operators from institutional procurement channels. Three-tier pricing structure across premium OEM-certified, standard independent-refurbished, and economy gray-market levels separates buyers by risk tolerance and warranty coverage depth. Cost compression accelerates in patient monitors as shorter refurbishment cycles and lower regulatory barriers attract price-competitive entrants. Diagnostic centers in India's tier-2 cities exhibit highest price sensitivity, while mid-tier U.S. hospital networks prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Regional distribution centers in Germany's Baden-Württemberg region, the U.S. Greater Boston cluster, and India's Maharashtra state anchor hub-and-spoke refurbishment networks serving continental markets. Proprietary parts logistics for legacy CT and MRI platforms draw from OEM captive supply chains, specialized component brokers, and reverse-engineered aftermarket alternatives. Single-source vulnerability concentrates in rare earth magnet supply for MRI refurbishment, with Chinese processing dominance creating tariff exposure for European and North American operators. Distribution runs through direct-to-diagnostic-center channels disintermediating traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technician scarcity for specialized calibration and safety testing constrains refurbishment throughput, propping pricing power for certified operators with established training pipelines and OEM technical partnerships.
For Market Incumbents: Anticipate channel disintermediation by diagnostic center networks negotiating direct refurbishment relationships, reinforcing position through predictive maintenance contract penetration and proprietary remote monitoring overlay development. Vertical integration into legacy parts logistics secures supply continuity as OEMs sunset support for older modalities. ISO 13485 certification investment filters price-competitive informal operators from institutional procurement channels. For New Entrants and Emerging Players: India's private diagnostic chains in tier-2 and tier-3 cities represent an underserved buyer archetype with aggressive capital efficiency mandates and limited OEM-direct access. Patient monitor refurbishment offers fastest inventory turns with lower regulatory barriers compared to imaging modalities. Leasing-based operating models eliminate upfront capital requirements for budget-constrained providers while establishing recurring revenue foundations. For Investors and Strategic Acquirers: Re-rating potential sits with ISO 13485-certified regional refurbishers with established notified body partnerships given EU MDR technical documentation harmonization compressing compliance costs for compliant operators. Long-term viability hinges on software-enabled service contract penetration displacing transactional equipment sales. Watch FDA guidance evolution on remanufacturing versus servicing distinctions as inflection indicator for U.S. market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Penetration | Remote monitoring overlays on refurbished CT and MRI platforms create recurring revenue streams and deepen customer lock-in. |
| ISO 13485 Certification Investment | Quality management certification filters informal refurbishers from institutional procurement channels across EU and U.S. markets. |
| Direct-to-Diagnostic-Center Channel Development | Bypassing traditional distributor markups concentrates purchasing power among large imaging chain networks in India's private healthcare sector. |
| Legacy Parts Logistics Integration | Proprietary component sourcing secures supply continuity as OEMs discontinue support for older CT and MRI modalities. |
| Software Companion Development | AI-enabled image processing upgrades restore diagnostic throughput comparable to new equipment on refurbished hardware platforms. |
Research Approach
Document review covered FDA 510(k) premarket notification databases, EU MDR technical documentation guidance, and ISO 13485 certification registries, complemented by interviews with hospital biomedical engineers, diagnostic center procurement directors, GPO contracts managers, and refurbishment operations executives. Secondary validation drew from CDSCO regulatory filings, NMPA oversight announcements, and hospital procurement database trends. Bottom-up equipment transaction modeling and top-down healthcare capital expenditure analysis provided triangulation across volume and value estimates.
Segment-level outputs across the projection horizon reflect equipment type, end-user category, technology architecture, and service model dimensions. Modeled variables included replacement cycle compression from software-defined upgrades, regulatory certification timeline variations, and geographic adoption pattern divergence between developed and emerging markets. CAGRs derive from installed base aging curves, capital constraint intensity by provider tier, and compliance cost trajectory assumptions.
Revisions become necessary when EU MDR enforcement intensity shifts, FDA remanufacturing guidance evolves, or OEM parts discontinuation accelerates beyond modeled timelines. Forecasts reflect documented assumptions regarding technician training pipeline expansion and diagnostic center network consolidation rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Water Bath Market
Medical Equipment
Auditory Brainstem Response Analyzers Market
Medical Equipment
North America Durable Medical Equipment Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Global Blood Purification Equipment Market
Medical Equipment
Medical Tubing Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Medical X-Ray Generators Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Global Mortuary Equipment Market
Medical Equipment
Cryopreservation Systems Market