
 HVAC Relay Market | 2026-2036
HVAC Relay Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Relay Market Intelligence
China is tilting the supply-demand balance through expanded electromechanical component manufacturing clusters in Jiangsu and Guangdong provinces. Siemens AG leverages its automation portfolio to anchor European demand for industrial-grade switching solutions. TE Connectivity Ltd. specializes in miniaturized relay architectures that serve data center cooling density requirements. Eaton Corporation plc extends its electrical distribution footprint through channel partnerships with North American facility operators.
An HVAC relay is an electrically operated switch designed to handle 24V to 480V control signals, using either electromagnetic coils with silver-alloy contacts or semiconductor-based switching to regulate compressor, fan, and damper operations in climate control systems. Electromechanical relays retain dominant share in residential HVAC replacement cycles due to cost parity and installer familiarity, while solid-state relays capture margin pools in data center cooling where zero-cross switching and million-cycle longevity reduce downtime exposure. Hybrid relays are gaining traction in commercial cooling applications that demand both electromechanical isolation and solid-state speed.
The US Department of Energy enforces minimum efficiency standards under 10 CFR Part 431 that compel relay manufacturers to reduce coil holding power and contact resistance. The EU F-Gas Regulation and Ecodesign Directive constrain refrigerant choices and system architectures, indirectly shaping relay specifications for compatibility with lower-GWP compressor technologies. Stakeholders must monitor how IEC 60730 automatic electrical controls standards evolve to address smart relay cybersecurity and predictive maintenance integration.
Market Dynamics
The HVAC relay market is experiencing structural compression as solid-state architectures displace electromechanical designs across data center cooling installations, driven by hyperscale operators demanding million-cycle reliability and zero-cross switching precision for thermal management uptime.
Growth Catalysts
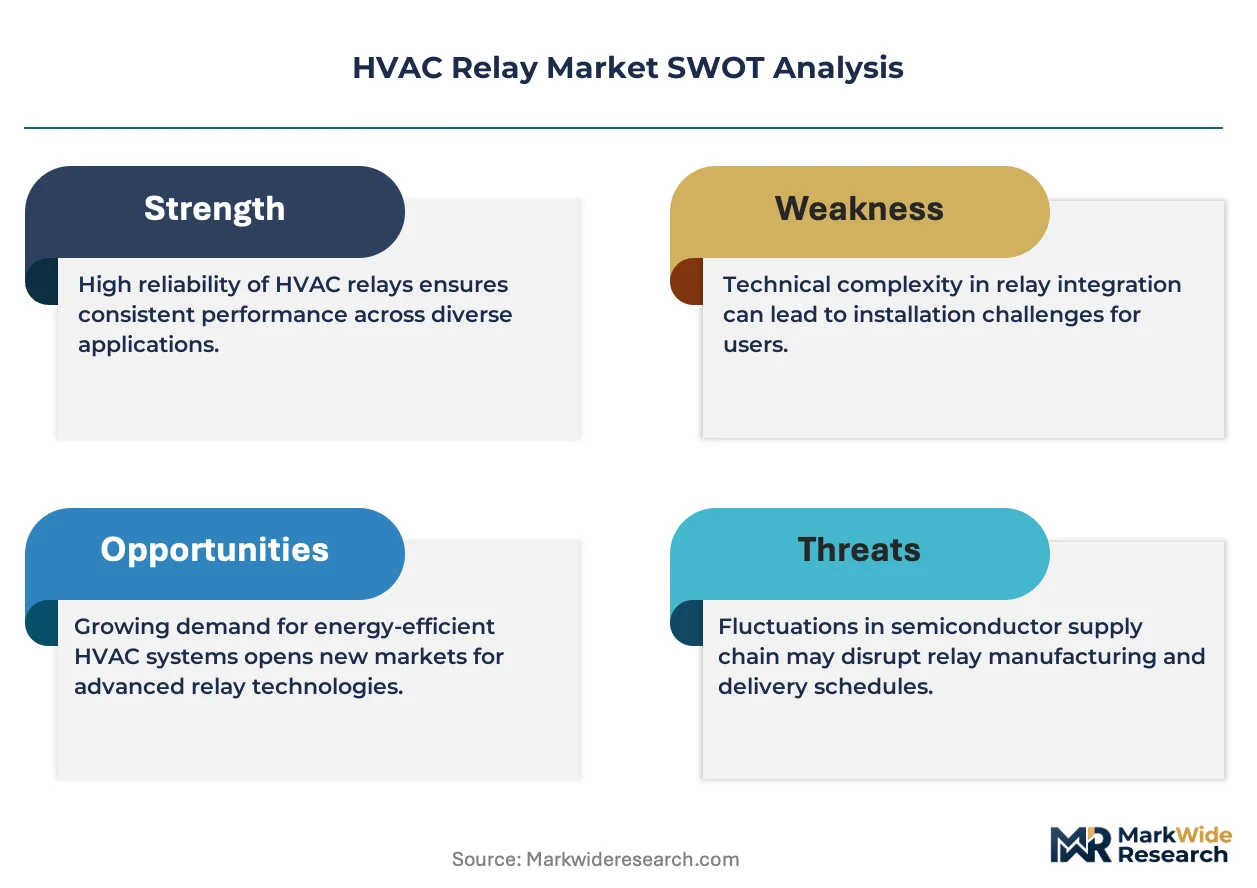
- 10 CFR Part 431 Efficiency Mandates:The US Department of Energy's appliance efficiency standards compel relay manufacturers to reduce coil holding power and contact resistance, accelerating R&D investment in low-consumption switching topologies.
- Hyperscale Data Center Cooling:Cloud infrastructure operators in Northern Virginia, Frankfurt, and Singapore are specifying solid-state relays for chiller and CRAH unit control, creating premium demand pools for semiconductor-based switching.
- Jiangsu-Guangdong Manufacturing Clusters:China's concentrated electromechanical component production bases are expanding relay output capacity to serve domestic HVAC OEMs and smart building retrofit programs.
Market Restraints
- Silver-Alloy Contact Cost Volatility:Electromechanical relay production depends on precious metal contact materials whose price swings compress margin predictability for manufacturers serving residential replacement cycles.
- Electromechanical-SSR Technical Gap:Solid-state relays cannot match electromechanical isolation ratings in certain legacy HVAC control architectures, forcing dual-inventory strategies that inflate working capital requirements.
- EU F-Gas Regulatory Friction:The F-Gas Regulation's phasedown of high-GWP refrigerants is retarding compressor relay specification cycles as OEMs redesign systems for lower-GWP alternatives.
Strategic Opportunities
- Hybrid Relay Architectures:Convergence of electromechanical isolation with solid-state switching speed is opening commercial cooling segments previously locked into single-technology procurement.
- Smart Building Retrofit Channels:Facility management platforms and energy service companies are emerging as direct relay procurement channels, bypassing traditional HVAC distributor networks.
- India PLI Scheme for HVAC Components:The Production Linked Incentive scheme is attracting relay manufacturing investment to serve domestic cooling appliance demand and export markets.
Industry Challenges
- IEC 60730 Cybersecurity Integration:Automatic electrical controls standards are evolving to address smart relay vulnerability management, forcing firmware development investments that strain mid-tier engineering budgets.
- Predictive Maintenance Skill Shortages:Field service organizations lack technicians trained to diagnose relay degradation patterns through IoT-enabled condition monitoring systems.
- Legacy Control System Interoperability:Building automation retrofits require relay form factors and voltage ranges compatible with decades-old pneumatic and analog control infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Relay Market |
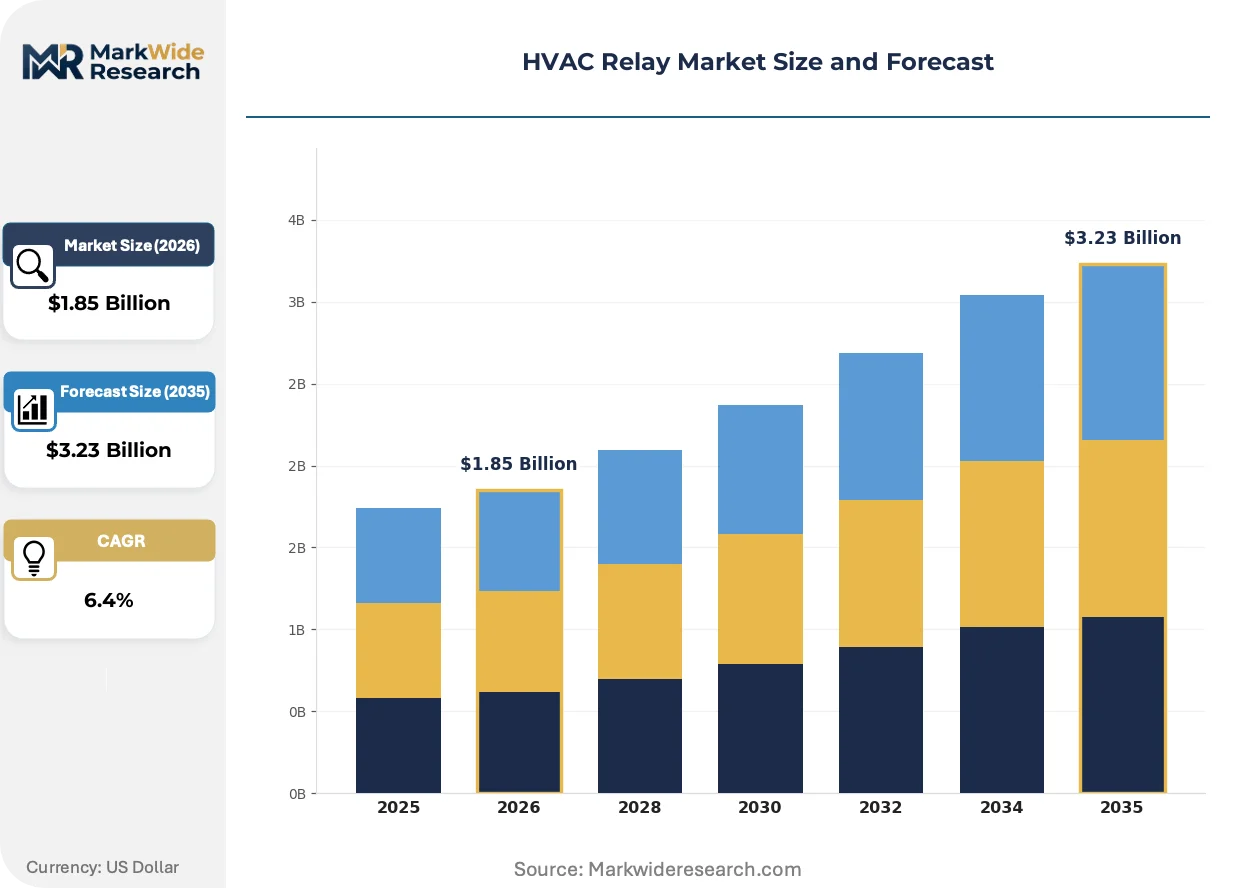
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical Relay, Solid State Relay, Hybrid Relay, Reed Relay, Thermal Relay Application: Residential HVAC, Commercial Cooling, Industrial Ventilation, Data Center Cooling, Agricultural Environment Control End User: Property Management Firms, Commercial Facility Operators, Manufacturing Plants, Tech Company Headquarters, Farming Operations Installation Type: Panel Mount, Surface Mount, DIN Rail Mount, Socket Mount |
| Companies Covered | TE Connectivity Ltd., Schneider Electric, Siemens AG, ABB Ltd., Eaton Corporation plc, Mitsubishi Electric Corporation, Toshiba Corporation, General Electric, Rockwell Automation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Relay Market Strategic Shifts & Innovations
Digital integration is penetrating HVAC relay architectures at the component level, enabling predictive maintenance and remote diagnostics that alter procurement criteria and supplier value propositions.
Intelligent relay modules with embedded microcontrollers and IoT connectivity are digitizing thermal management control loops. Data center operators in Ashburn, Dublin, and Tokyo are specifying these units for real-time chiller load balancing. This digitization is compressing the traditional replacement cycle toward condition-based rather than time-based maintenance triggers.
The EU F-Gas Regulation and Ecodesign Directive are constraining refrigerant choices and system architectures, indirectly reshaping relay specifications for compatibility with lower-GWP compressor technologies. HVAC OEMs in Germany and Italy are redesigning control enclosures to accommodate relays rated for variable-speed drive interference. The commercial rooftop unit segment is responding fastest, with specification sheets now listing F-Gas compliance tiers alongside electrical ratings.
Facility operators are consolidating relay procurement through energy service companies and direct OEM agreements, disintermediating traditional HVAC wholesale distributors. This channel compression is most visible in North American and Western European commercial real estate portfolios with centralized sustainability mandates. Manufacturers are reconfiguring sales organizations to serve procurement teams rather than contractor networks, altering technical support and inventory commitment models.
HVAC Relay Market Segmentation
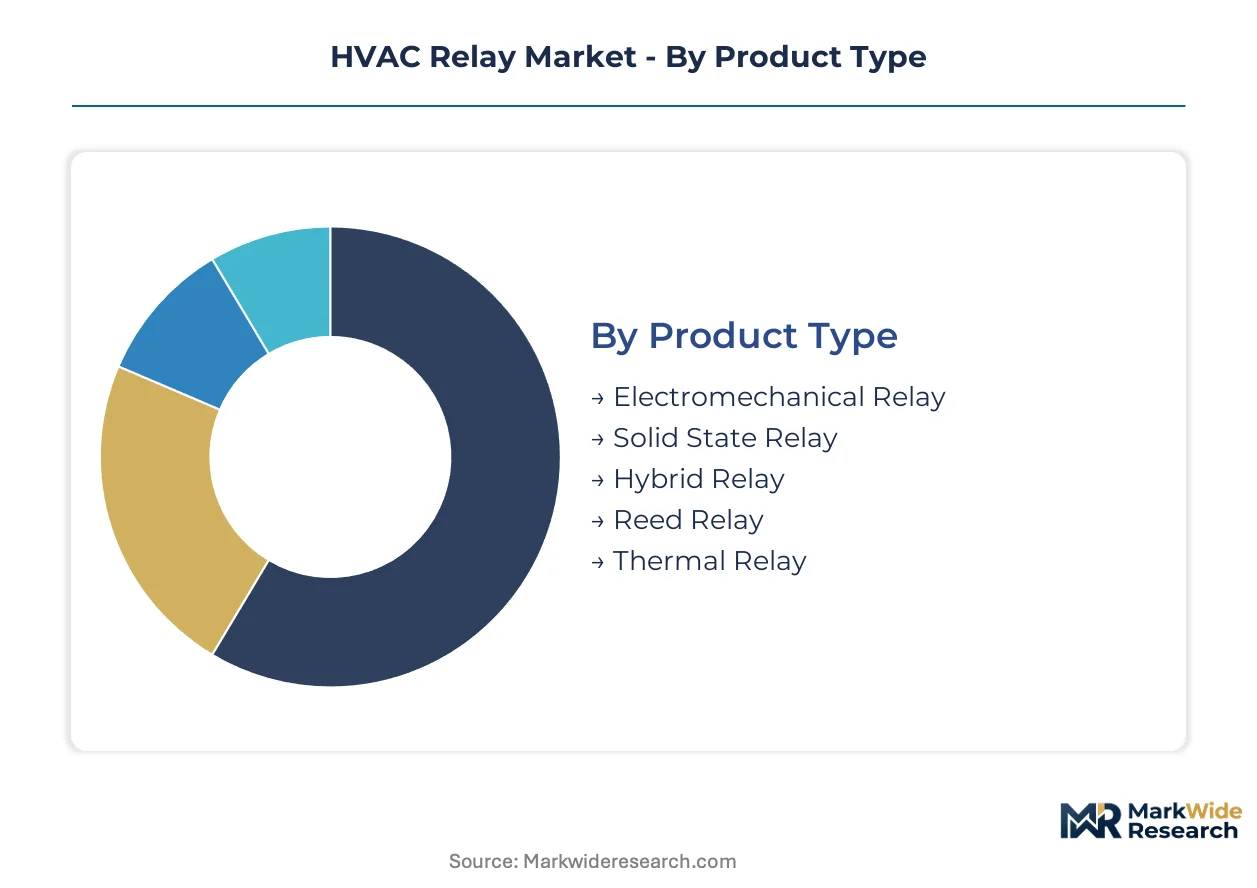
HVAC relay procurement patterns diverge sharply across switching technologies and deployment environments. Specification sheets now bundle thermal cycling ratings with IoT readiness tiers. Understanding segment boundaries clarifies where margin pools concentrate versus where volume commoditization dominates.
Product Type:
Cost tier differentiation separates commodity replacement cycles from premium uptime-critical installations.
- Electromechanical Relay:Silver-alloy contacts and copper coils handle 24V to 240V control signals with mechanical isolation rated for 100,000+ cycles. Residential HVAC contractors in the United States specify these units for furnace and heat pump retrofits where installer familiarity reduces callback risk.
- Solid State Relay:Semiconductor switching with zero-cross detection eliminates contact arcing and delivers million-cycle longevity. Hyperscale data centers in Northern Virginia and Frankfurt specify these for chiller and CRAH unit control where thermal management downtime costs exceed component price premiums by orders of magnitude.
- Hybrid Relay:Combines electromechanical isolation with solid-state switching speed for commercial rooftop units.
- Reed Relay:Hermetically sealed magnetic switches serve low-current signal routing in building automation panels.
- Thermal Relay:Bimetallic strip overload protection integrates with compressor motor starters.
Electromechanical Relay holds installed capacity. Solid State Relay is rotating up the share rankings.
Application:
Application context determines switching speed requirements and environmental sealing specifications.
- Residential HVAC:Split-system air conditioners and heat pumps demand 24V control relays with UL 508 listings. Replacement cycles in the United States concentrate around 10-15 year equipment lifespans.
- Data Center Cooling:Chiller plants and computer room air handlers require solid-state precision for load balancing. Operators in Singapore and Dublin specify relays with embedded diagnostics compatible with DCIM platforms.
- Commercial Cooling:Rooftop units and VRF systems need hybrid architectures for variable-speed compressor control.
- Industrial Ventilation:Dust-tight enclosures and high-vibration tolerance characterize relay specifications for manufacturing environments.
- Agricultural Environment Control:Humidity-resistant housings serve greenhouse and livestock facility climate systems.
Residential HVAC dominates shipment volumes. Data Center Cooling is climbing the fastest.
End User:
Customer type shapes procurement channel structure and technical support expectations.
- Property Management Firms:Multi-site portfolios with centralized sustainability mandates specify standardized relay SKUs across Class A office buildings. These buyers negotiate direct OEM agreements that disintermediate traditional HVAC distributors.
- Commercial Facility Operators:Hospital and university maintenance departments prioritize predictive maintenance integration over upfront component cost.
- Manufacturing Plants:Process cooling and cleanroom ventilation drive demand for industrial-grade switching.
- Tech Company Headquarters:Corporate campuses with on-premise data infrastructure specify intelligent relay modules.
- Farming Operations:Controlled environment agriculture facilities in the Netherlands and California deploy relays for precision climate management.
Property Management Firms concentrate procurement leverage. Tech Company Headquarters is expanding specifications fastest.
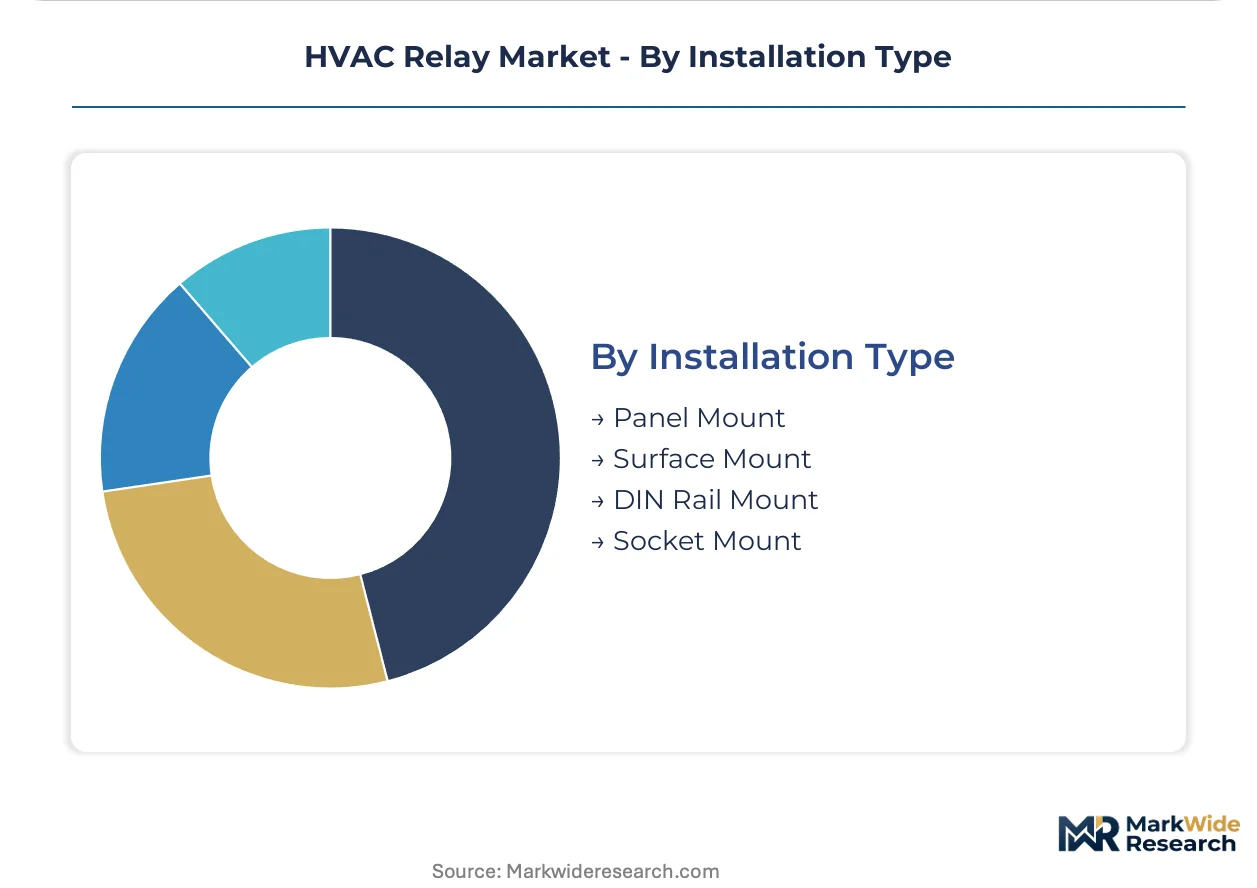
Installation Type:
Mounting configuration dictates enclosure design and field wiring labor economics.
- Panel Mount:Threaded studs or bracket fixtures secure relays inside custom control enclosures. OEMs in Jiangsu province specify these for factory-built air handling units.
- DIN Rail Mount:Standardized 35mm rail attachment enables rapid field installation and hot-swapping. European commercial retrofit contractors prefer this format for building automation upgrades.
- Surface Mount:Direct PCB soldering serves miniaturized control boards in ductless mini-split indoor units.
- Socket Mount:Plug-in bases with retaining clips facilitate relay replacement without rewiring terminal connections.
DIN Rail Mount anchors commercial infrastructure. Panel Mount is gaining share in OEM supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electromechanical component manufacturing clusters in Jiangsu and Guangdong provinces anchor relay supply capacity, while hyperscale data center construction in Northern Virginia, Frankfurt, and Singapore redirects demand toward solid-state architectures. National efficiency regulations and smart building retrofit programs are reshaping procurement patterns across major economies.
China
Domestic HVAC OEM production and smart building retrofit programs are expanding relay volumes across Jiangsu and Guangdong manufacturing clusters. MIIT efficiency guidelines and GB standards for appliance controls are accelerating domestic R&D in low-power switching topologies. Suzhou and Shenzhen production bases are scaling output to serve both domestic climate control demand and export markets.
United States
Hyperscale data center cooling installations in Northern Virginia and Dallas-Fort Worth are specifying solid-state relays for chiller and CRAH unit control. The Department of Energy enforces 10 CFR Part 431 efficiency mandates that compel manufacturers to reduce coil holding power. Midwest industrial zones and Southeast manufacturing corridors sustain electromechanical relay demand for replacement cycles in legacy HVAC infrastructure.
Germany
Commercial rooftop unit OEMs in Baden-Württemberg and Bavaria are redesigning control enclosures for relays compatible with variable-speed drive interference. The EU F-Gas Regulation and Ecodesign Directive constrain refrigerant choices and indirectly reshape relay specifications for lower-GWP compressor technologies. Stuttgart and Munich industrial clusters concentrate HVAC control system engineering expertise.
India
The Production Linked Incentive scheme for HVAC components is attracting relay manufacturing investment to serve domestic cooling appliance demand. Bureau of Indian Standards certification requirements and CEA electrical safety regulations are formalizing product compliance frameworks. Gujarat and Maharashtra industrial corridors are emerging as assembly locations for both residential and commercial climate control systems.
Japan
Data center operators in Tokyo and Osaka are specifying intelligent relay modules with embedded diagnostics compatible with DCIM platforms. METI energy efficiency standards and JIS certification requirements shape product development priorities for semiconductor-based switching. Nagoya manufacturing zones maintain precision electromechanical component production for hybrid relay architectures.
HVAC Relay Market Key Industry Players
Industrial conglomerates and specialized component manufacturers split the market between scale-driven supply contracts and technology-differentiated premium positions. The vendor base organizes around three strategic archetypes: diversified electrical equipment conglomerates with integrated automation portfolios, connectivity specialists focused on miniaturized switching architectures, and regional electromechanical component fabricators serving replacement cycles. Competitive dynamics center on M&A activity consolidating distribution channels and capacity expansion in Asian manufacturing clusters.
Among diversified electrical equipment conglomerates, Siemens AG and Eaton Corporation plc exemplify the integrated automation portfolio archetype, leveraging channel partnerships with facility operators to extend electrical distribution footprints. TE Connectivity Ltd. occupies a position within the connectivity specialist tier, anchoring demand for miniaturized relay architectures that serve data center cooling density requirements. These three companies represent the dominant competitive positioning vectors: scale-driven supply consolidation, technology-led miniaturization, and channel-integrated distribution reach.
| Leading Market Players |
|---|
| TE Connectivity Ltd. |
| Schneider Electric |
| Siemens AG |
| ABB Ltd. |
| Eaton Corporation plc |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| General Electric |
| Rockwell Automation Inc. |
| Others |
Cost & Logistics Intelligence
Jiangsu and Guangdong electromechanical manufacturing clusters concentrate silver-alloy contact and copper coil production, anchoring margin pools downstream with solid-state relay specialists capturing premium positions in data center procurement channels.
Pricing Analysis
10 CFR Part 431 dictates the pricing tier structure across the HVAC relay market, compelling manufacturers to absorb R&D costs for low-consumption switching topologies while segmenting offerings by certification grade and volume scale. Three-tier pricing structure across premium, standard, and economy levels separates solid-state units with million-cycle ratings from electromechanical replacements and commodity panel-mount options. Cost compression in the electromechanical tier is intensifying because silver-alloy contact volatility compresses margin predictability. Residential HVAC contractors exhibit the highest price sensitivity, while hyperscale data center operators prioritize uptime value over component cost.
Supply Chain Analysis
Flex, Jabil, and Benchmark Electronics hold contract manufacturing capacity for semiconductor-based relay modules serving data center cooling density requirements. Component fabrication concentrates in China, South Korea, and Japan, with final assembly drawing from Jiangsu province electromechanical clusters and Nagoya precision manufacturing zones. Raw material dependencies center on silver-alloy contact materials, copper magnet wire, and silicon carbide substrates. Single-source vulnerability in semiconductor substrate supply creates exposure for solid-state relay output expansion. Distribution runs through energy service companies and direct OEM agreements that disintermediate traditional HVAC wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service contracts and firmware update subscriptions are expanding faster than hardware shipments, transforming relay procurement into recurring-revenue relationships that alter supplier value propositions.
For Market Incumbents: Build switching technology IP moats through backward integration into semiconductor substrate supply and captive production of silver-alloy contact materials. Siemens AG and Eaton Corporation plc should expand channel control via direct agreements with property management firms bypassing distributor networks. Solid-state relay specialists threaten electromechanical incumbents in commercial rooftop segments; certification investment in IEC 60730 cybersecurity compliance defends institutional procurement access.
For New Entrants and Emerging Players: India's PLI scheme corridors in Gujarat and Maharashtra offer underpenetrated manufacturing capacity for both residential and commercial climate control relay assembly. Target data center cooling installations in secondary markets like Dublin and Tokyo where incumbent presence remains fragmented. Partner with facility management platforms as direct procurement channels rather than competing through traditional HVAC distributor relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward hybrid relay specialists combining electromechanical isolation with solid-state switching speed for commercial cooling segments. Long-term viability hinges on firmware development capabilities and DCIM platform integration rather than component cost alone. Watch for inflection signals in hyperscale data center capex disclosures and MIIT efficiency guideline revisions affecting low-power switching R&D subsidies.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Relay Architecture Development | Convergence technologies capture commercial cooling segments previously locked into single-technology procurement. |
| Direct OEM Agreement Expansion | Channel compression with property management firms disintermediates traditional HVAC wholesale networks. |
| IEC 60730 Cybersecurity Certification | Compliance investment secures institutional procurement access as automatic electrical controls standards evolve. |
| Silver-Alloy Contact Backward Integration | Upstream control over precious metal supply stabilizes margin predictability against commodity volatility. |
| DCIM Platform Integration Partnership | Embedded diagnostics compatibility with data center infrastructure management systems enables premium positioning. |
Research Approach
Initial hypotheses were tested against primary input from HVAC OEM procurement directors, facility management sustainability officers, data center operations engineers, and electromechanical component distributors and refined through secondary validation against SEC 10-K filings, MIIT efficiency guideline publications, EU F-Gas Regulation impact assessments, and hyperscaler capex disclosures. Bottom-up demand modeling across switching technology tiers triangulated with top-down market sizing from production capacity estimates in Jiangsu and Guangdong clusters.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling across electromechanical, solid-state, and hybrid product architectures; residential, commercial, and data center cooling applications; and DIN rail, panel, and socket mounting configurations. CAGRs were derived from production capacity expansion announcements, efficiency mandate compliance timelines, and infrastructure investment patterns. Forecast inputs included hyperscale data center construction pipelines and smart building retrofit program commitments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by semiconductor foundries into relay module assembly would shift outcomes beyond modeled ranges. Regulatory acceleration in F-Gas phasedown timelines or cybersecurity standard enforcement could compress specification cycles. Quarterly review of hyperscaler thermal management capex and MIIT low-power switching R&D subsidy announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Movable Scaffolding System Market
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Rigid Metal Electrical Conduit Market
Electro-Mech Systems
Elevator Door-Motor Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
Tubular Motors Market
Electro-Mech Systems
Wiring Duct Market
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
Automatic Slack Adjusters Market
Electro-Mech Systems
Rodless Cylinders Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market