

Rigid Metal Electrical Conduit Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Metal Electrical Conduit Market Insights
The gap between premium-grade stainless steel conduit and commodity galvanized steel products is broadening as data center operators specify enhanced corrosion resistance for mission-critical power distribution. Atkore leverages vertical integration across steel sourcing and conduit fabrication to sustain cost discipline in commodity segments. Zekelman Industries anchors its position through continuous weld manufacturing scale, while Schneider Electric differentiates via integrated electrical infrastructure systems that bundle conduit with power distribution equipment.
Rigid metal electrical conduit consists of thick-walled, threadable steel, aluminum, or stainless steel tubing manufactured to protect and route electrical conductors in commercial and industrial environments, typically meeting UL 6 or ANSI C80.1 wall thickness standards for physical damage resistance. Galvanized steel dominates volume across commercial buildings and manufacturing plants where cost efficiency governs specification, while aluminum gains share in data center and marine site installations where weight reduction and corrosion resistance justify premium positioning. Stainless steel occupies the highest margin tier in hazardous locations and oil and gas facilities exposed to chemical or salt-laden atmospheres.
The National Electrical Code in the United States, CSA C22.1 in Canada, and IEC 61386 standards in European markets collectively mandate metal raceway systems for specific voltage classes and environmental conditions, directly shaping material selection and product certification requirements. OSHA workplace safety regulations and NFPA 70E arc flash standards further reinforce demand for grounded metal conduit in industrial settings over non-metallic alternatives. Stakeholders must monitor evolving amendments to these codes as electrification of heating, cooling, and transportation infrastructure expands conduit duty cycles and environmental exposure profiles.
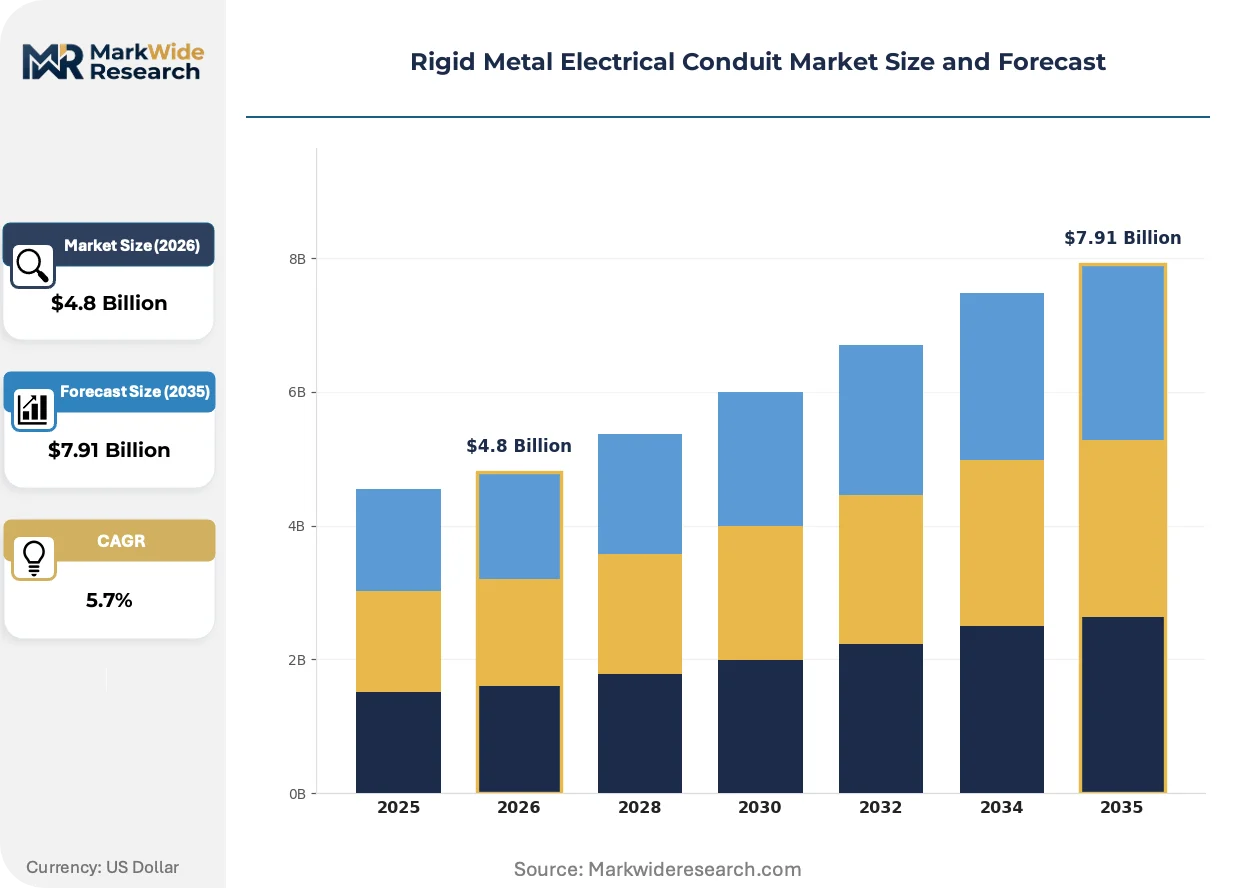
Market Dynamics
Data center electrification is compressing specification cycles for rigid metal conduit, forcing manufacturers to certify aluminum and stainless steel products against stricter corrosion resistance benchmarks before construction procurement windows close.
Growth Catalysts
- National Electrical Code mandates:The United States NEC now requires grounded metal raceway systems for critical power distribution above specific voltage thresholds, directly expanding specification volume for galvanized steel and aluminum conduit in commercial construction.
- Data center clustering:Hyperscale facility construction in Northern Virginia, Frankfurt, and Mumbai is accelerating procurement of corrosion-resistant aluminum conduit runs for mission-critical electrical infrastructure.
- OSHA workplace safety enforcement:NFPA 70E arc flash protection standards are reinforcing specification preference for grounded metal conduit over non-metallic alternatives in industrial manufacturing environments.
Market Restraints
- Steel input cost volatility:Hot-rolled coil pricing fluctuations at U.S. Midwest mills and Chinese export markets compress margin predictability for galvanized steel conduit fabricators serving commercial building segments.
- Supply concentration in continuous weld manufacturing:North American electric resistance welding capacity clusters among three integrated producers, creating procurement bottlenecks during construction season demand spikes.
- Non-metallic conduit substitution:PVC-coated flexible conduit and high-density polyethylene raceway systems are displacing rigid metal specifications in below-grade residential and light commercial applications where code permits.
Strategic Opportunities
- India data center buildout:The country's PLI scheme for electronics manufacturing is attracting hyperscale investments requiring certified aluminum conduit for 48-hour backup power distribution systems.
- Marine and offshore electrification:Salt-laden atmosphere exposure in coastal wind turbine installations and port electrification projects is opening specification pathways for 316L stainless steel conduit at premium price tiers.
- Integrated electrical infrastructure bundling:Conduit-plus-power-distribution equipment packages are capturing specification authority from standalone commodity procurement in German industrial automation projects.
Industry Challenges
- UL 6 certification timeline compression:Third-party testing laboratory backlogs are extending product qualification cycles from 12 to 20 weeks, misaligning with fast-track data center construction schedules.
- Welder skill scarcity:Certified pipefitter availability constraints in the American Sun Belt are forcing contractors toward pre-fabricated conduit assemblies, disrupting traditional field-threading installation economics.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Metal Electrical Conduit Market Trends and Innovations
Smart manufacturing investments and material science advances are compressing the gap between commodity galvanized steel and premium stainless steel performance, while procurement digitization is reshaping how electrical contractors source certified raceway systems.
Corrosion-resistant coating technologies are converging with nanoscale surface treatment processes to extend galvanized steel service life in humid industrial environments. Data center operators in Singapore and the Netherlands are specifying these enhanced products for 25-year infrastructure depreciation cycles. The technology is converging with predictive maintenance platforms that monitor conduit integrity through embedded sensor networks, creating subscription revenue opportunities for manufacturers.
REACH chemical substance restrictions in the European Union are phasing out hexavalent chromium conversion coatings traditionally applied to galvanized steel conduit for salt-spray resistance. German and French electrical distributors are transitioning inventory toward trivalent chromium and zinc-aluminum-magnesium alternatives ahead of 2026 enforcement deadlines. Marine and offshore segments are absorbing compliance costs through longer procurement lead times and premium pricing for certified low-carbon coating systems.
Electrical contractors are consolidating purchase authority through regional buying cooperatives that aggregate volume across multiple construction projects. Independent distributors in Texas and Florida are losing specification influence to these contractor-led procurement platforms that negotiate directly with conduit mills. The shift is most visible in commercial ground-up construction where standardized material takeoffs enable bulk forward contracting six months ahead of installation.
Rigid Metal Electrical Conduit Market Segmentation
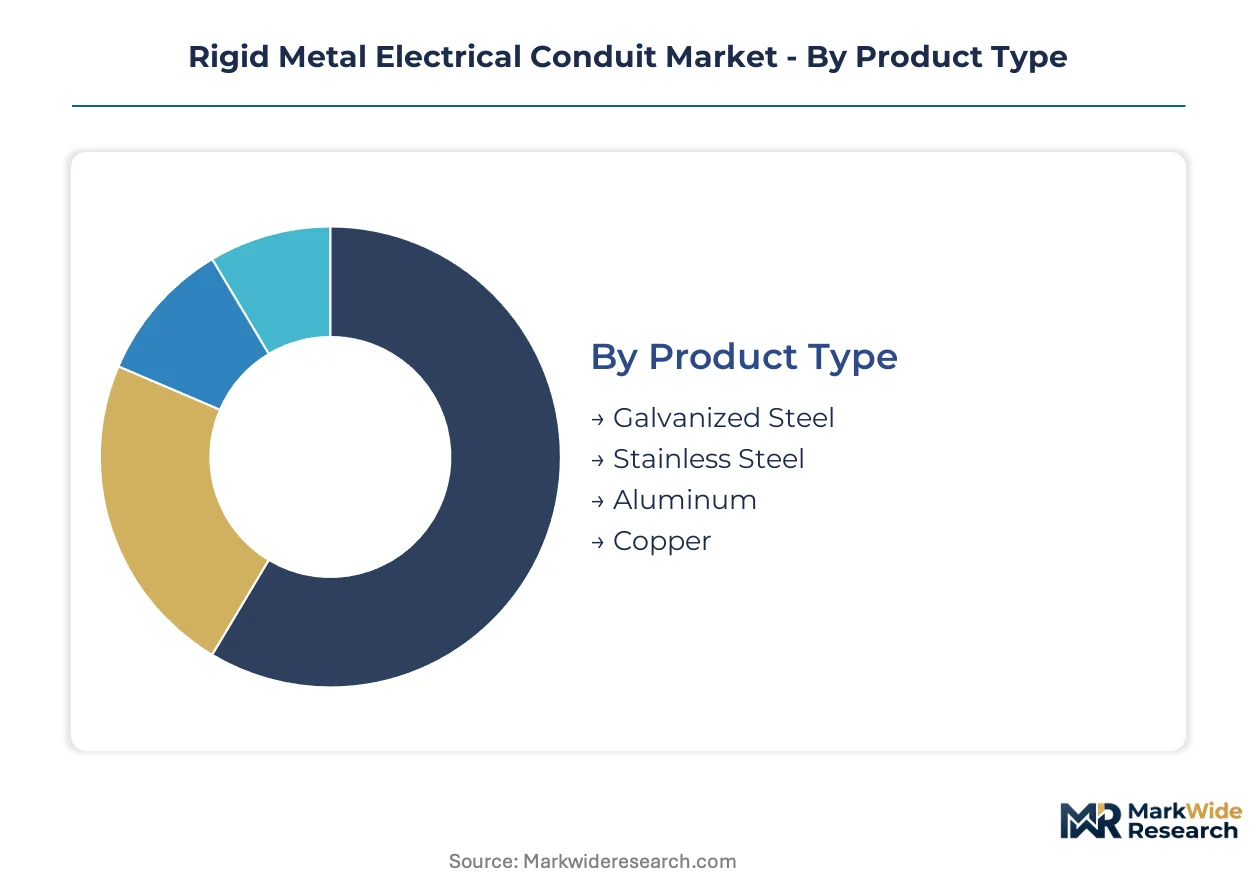
Specification cycles for rigid metal conduit compress as data center electrification and code amendments force material upgrades. Segmentation reveals how corrosion resistance, weight reduction, and installation environment reshape procurement across voltage classes and duty cycles.
Product Type:
Upgrade cycles vary dramatically by substrate, with aluminum and stainless steel displacing galvanized specifications in mission-critical infrastructure.
- Galvanized Steel:Zinc-coated carbon steel tubing meeting UL 6 wall thickness standards dominates commercial building volume where cost efficiency governs specification. Demand concentrates across the American Sun Belt as commercial permit expansion tightens procurement windows for standard utility infrastructure.
- Stainless Steel:304 and 316L grades deliver maximum corrosion resistance for chemical exposure and salt-laden atmospheres. Oil and gas facilities in the Gulf Coast and North Sea specify these alloys for hazardous location compliance despite premium positioning.
- Aluminum:Lightweight alloy conduit gains share in data center installations where weight reduction eases overhead routing complexity.
- Copper:Specialized applications in electromagnetic interference-sensitive environments require this non-ferrous alternative.
Galvanized steel sits at the top of the volume ranking, with aluminum climbing the fastest.
Application:
End-use concentration determines margin structure, with data center and oil and gas specifications commanding premium pricing over commodity commercial construction.
- Data Centers:Hyperscale facilities in Northern Virginia, Frankfurt, and Mumbai specify corrosion-resistant aluminum and stainless steel conduit for 48-hour backup power distribution. NEC voltage thresholds and NFPA 70E arc flash standards mandate grounded metal raceway systems for critical infrastructure.
- Commercial Buildings:Office, retail, and institutional construction consumes standardized galvanized steel products through regional buying cooperatives that aggregate volume across multiple projects.
- Infrastructure Projects:Transportation electrification and utility expansion drive specification for heavy-wall conduit in tunnel and bridge installations.
- Oil & Gas Facilities:Offshore platforms and refineries absorb premium stainless steel costs for salt-spray and chemical resistance compliance.
- Manufacturing Plants:OSHA workplace safety enforcement reinforces metal conduit preference over non-metallic alternatives in industrial environments.
Commercial buildings anchor absolute volume, though data centers expand most quickly.
Installation Environment:
Environmental exposure severity dictates material grade and coating specification, with marine and hazardous locations filtering procurement toward premium tiers.
- Outdoor:Direct exposure to precipitation and temperature cycling requires enhanced galvanized coatings or aluminum substrates for service life extension.
- Indoor:Climate-controlled environments permit standard galvanized steel specifications across commercial and institutional construction.
- Hazardous Locations:Class I Division 1 and Class II environments mandate stainless steel conduit for ignition source containment.
- Marine Sites:Coastal wind turbine installations and port electrification projects specify 316L stainless steel for salt-laden atmosphere survival.
Indoor specifications dominate unit volume, while marine sites gain share fastest.
End User:
Procurement authority consolidation reshapes distribution channels, with contractor-led platforms displacing traditional distributor influence.
- Electrical Contractors:Regional buying cooperatives in Texas and Florida aggregate material takeoffs across multiple ground-up construction projects, negotiating direct mill relationships six months ahead of installation.
- Construction Firms:General contractors managing design-build projects specify bundled electrical infrastructure packages that combine conduit with power distribution equipment.
- Facility Managers:Existing building retrofits and maintenance procurement favor standardized galvanized products through established distributor relationships.
- System Integrators:Industrial automation projects in Germany specify integrated raceway-plus-equipment solutions from electrical infrastructure specialists.
Electrical contractors command the largest procurement volume, with construction firms expanding their specification authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified pipefitter concentrations in the American Sun Belt, the Rhine-Ruhr industrial corridor, and India's western manufacturing belt anchor regional demand patterns for rigid metal electrical conduit installations.
United States
Data center construction in Northern Virginia and commercial building permits across Texas and Florida compress procurement timelines for galvanized steel and aluminum conduit. OSHA workplace safety enforcement through NFPA 70E arc flash standards mandates grounded metal raceway systems in industrial manufacturing environments. Electrical contractor buying cooperatives in Houston and Miami negotiate direct mill relationships six months ahead of installation schedules.
Germany
Industrial automation projects in Bavaria and Baden-Württemberg specify integrated electrical infrastructure bundling that combines conduit with power distribution equipment. REACH chemical substance restrictions phase out hexavalent chromium conversion coatings by 2026, forcing inventory transitions toward trivalent chromium and zinc-aluminum-magnesium alternatives. Frankfurt's hyperscale data center cluster accelerates corrosion-resistant aluminum conduit procurement for mission-critical backup power distribution.
India
The PLI scheme for electronics manufacturing attracts hyperscale data center investments requiring certified aluminum conduit for 48-hour backup power systems. Central Electricity Authority regulations mandate metal raceway compliance for critical voltage thresholds in commercial infrastructure. Mumbai's emerging data center corridor concentrates procurement windows as construction timelines compress to match global operator deployment schedules.
China
Hot-rolled coil pricing volatility at domestic mills shapes margin structures for galvanized steel conduit fabricators serving commercial building segments. GB standards and MIIT industrial policy direct material specifications for power distribution infrastructure in manufacturing zones. Yangtze River Delta construction activity tightens procurement for standard utility infrastructure as commercial permit expansion continues.
Netherlands
Data center operators in Amsterdam specify enhanced corrosion-resistant galvanized steel products with nanoscale surface treatments for 25-year infrastructure depreciation cycles. ECHA enforcement of REACH chemical restrictions accelerates coating technology transitions ahead of 2026 deadlines. Rotterdam port electrification projects open specification pathways for premium stainless steel conduit in salt-laden marine environments.
Rigid Metal Electrical Conduit Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the rigid metal electrical conduit market, with continuous weld manufacturing capacity clustering among integrated steel processors. The vendor base organizes into three strategic archetypes: vertically integrated steel-to-conduit fabricators, specialized electrical infrastructure bundlers, and regional tube mills serving contractor buying cooperatives. Dominant competitive moves include backward integration into hot-rolled coil sourcing and strategic partnerships with data center engineering firms to compress certification timelines.
Among North American integrated producers, Atkore and Zekelman Industries exemplify the scale-driven archetype through captive steel sourcing and continuous weld manufacturing capacity. Schneider Electric occupies a position within the electrical infrastructure bundler tier, representing the integrated systems approach that combines raceway with power distribution equipment. These three anchors illustrate how competitive positioning diverges between commodity volume leadership and premium solution bundling.
| Leading Market Players |
|---|
| Atkore |
| Zekelman Industries |
| American Conduit |
| Wheatland Tube |
| Nucor Tubular Products |
| Schneider Electric |
| Legrand |
| ABB |
| Eaton |
| Others |
Pricing and Supply Chain Analysis
Electrical contractor buying cooperatives in Texas and Florida anchor procurement volume, forcing manufacturers toward project-based contract pricing with six-month forward commitments rather than spot-market transactions. This buyer concentration compresses margin structures for galvanized steel products while creating pricing power for certified aluminum and stainless steel tiers.
Pricing Analysis
Bundled electrical infrastructure packages that combine conduit with power distribution equipment command premium positioning against standalone commodity procurement. Three-tier pricing structure across premium, standard, and economy levels separates 316L stainless steel for marine sites from aluminum for data centers from galvanized steel for commercial construction. Cost compression in commodity galvanized tiers is intensifying because hot-rolled coil volatility at U.S. Midwest mills feeds directly into fabricator margins. Commercial building contractors exhibit highest price sensitivity, while oil and gas facility operators absorb premium stainless steel costs without volume elasticity.
Supply Chain Analysis
Regional distribution centers in Houston, Frankfurt, and Mumbai operate hub-and-spoke patterns that position inventory within forty-eight hours of data center construction sites. Supply concentrates in the United States, China, and India, with continuous weld manufacturing capacity clustering among integrated steel processors. Raw material flows draw from hot-rolled coil at domestic mills, zinc for galvanizing baths, and aluminum alloy billet for lightweight conduit production. Single-source vulnerability in North American electric resistance welding capacity creates procurement bottlenecks during construction season demand spikes. Distribution runs through contractor-led procurement platforms that negotiate direct mill relationships, bypassing traditional electrical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through coating technology upgrades that extend galvanized steel service life, allowing premium positioning without full stainless steel cost structures.
For Market Incumbents: Cement specification authority by backward integration into hot-rolled coil sourcing and captive zinc-aluminum-magnesium coating capacity. Threats from PVC-coated flexible conduit substitution in below-grade residential applications demand defensive certification investment in UL 6 enhanced corrosion products. Channel control through pre-fabricated conduit assemblies addresses certified pipefitter scarcity in the American Sun Belt. For New Entrants and Emerging Players: Enter via India's PLI-driven data center corridor, where aluminum conduit demand outpaces domestic certification capacity. Marine and offshore electrification in Rotterdam and North Sea wind installations represents the most penetrable premium tier. Go-to-market leverage rests on 316L stainless steel specialization with trivalent chromium coating compliance ahead of REACH enforcement deadlines. For Investors and Strategic Acquirers: Electrical infrastructure bundlers are the most active acquirer in this space, consolidating regional tube mills to complete raceway-plus-equipment portfolios. Long-term viability hinges on coating technology transitions and data center construction cycle exposure. Watch for UL 6 certification timeline compression as an inflection indicator—backlogs extending beyond twenty weeks signal procurement authority shifts toward pre-qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hot-Rolled Coil Sourcing | Captive steel supply insulates margin from Midwest mill pricing volatility during construction spikes. |
| Coating Technology Transition | Trivalent chromium and zinc-aluminum-magnesium alternatives secure REACH compliance ahead of 2026 ECHA deadlines. |
| Pre-Fabricated Conduit Assembly Capacity | Pre-fab addresses certified pipefitter scarcity in Texas and Florida contractor markets. |
| Integrated Infrastructure Bundling | Raceway-plus-power-distribution packages capture specification authority in German industrial automation. |
| Data Center Engineering Partnerships | Direct relationships with hyperscale operators compress UL 6 certification timelines for fast-track procurement. |
Research Methodology
Direct dialogue with electrical contractor buying cooperative managers, conduit mill procurement directors, data center engineering firms, and UL certification laboratory staff grounded qualitative findings. Secondary validation drew from NEC code amendment filings, OSHA enforcement data, ECHA REACH substance restriction updates, and customs trade records for hot-rolled coil and zinc ingot flows. Bottom-up and top-down triangulation cross-checked volume estimates against construction permit databases and electrical distributor inventory turns.
Bottom-up modeling built from product-type, application, and installation environment segmentation across the analysis window. Top-down constraints applied national electrical code adoption rates and data center construction pipeline data. CAGRs derived from regression against commercial building permit indices, hyperscale facility investment announcements, and industrial manufacturing capacity utilization. Forecast inputs included welder skill availability projections and coating technology substitution curves.
The model holds under stable NEC adoption timelines and continued data center clustering in Northern Virginia, Frankfurt, and Mumbai; deviation in steel tariff regimes or REACH enforcement acceleration would shift material substitution patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.