
 Precast Concrete Manufacturing Market | 2026-2036
Precast Concrete Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Precast Concrete Manufacturing Market Analytics
India's western corridor is rewriting capacity maps for precast concrete manufacturing as state governments expand industrial park programs. CRH plc leverages captive aggregate reserves across multiple continents to sustain margin stability. HeidelbergCement AG anchors European supply through specialized infrastructure-focused batching operations. CEMEX competes on logistics density in urban megaprojects across the Americas.
Precast concrete manufacturing produces structural elements through controlled factory casting using Portland cement, graded aggregates, chemical admixtures, and steel reinforcement, then cures them under regulated temperature and humidity before transport to construction sites. Wet cast fabrication dominates architectural and structural applications requiring smooth surface finishes and complex geometries, while pre-stressing methods command premium positioning in long-span bridge and parking deck projects where load-bearing efficiency determines specification. Infrastructure application represents the deepest margin pool given project scale and specification rigor, though residential adoption accelerates fastest in markets confronting skilled labor scarcity.
OSHA mandates govern US plant safety and worker exposure limits during precast production, while the EU Green Deal's embodied carbon thresholds force mix-design reformulation and alternative binder testing across European facilities. India's BIS certification requirements for precast structural elements shape market access for domestic and imported suppliers. Stakeholders must monitor regulatory divergence between carbon accounting methodologies as compliance costs increasingly determine competitive viability across operating geographies.
Market Dynamics
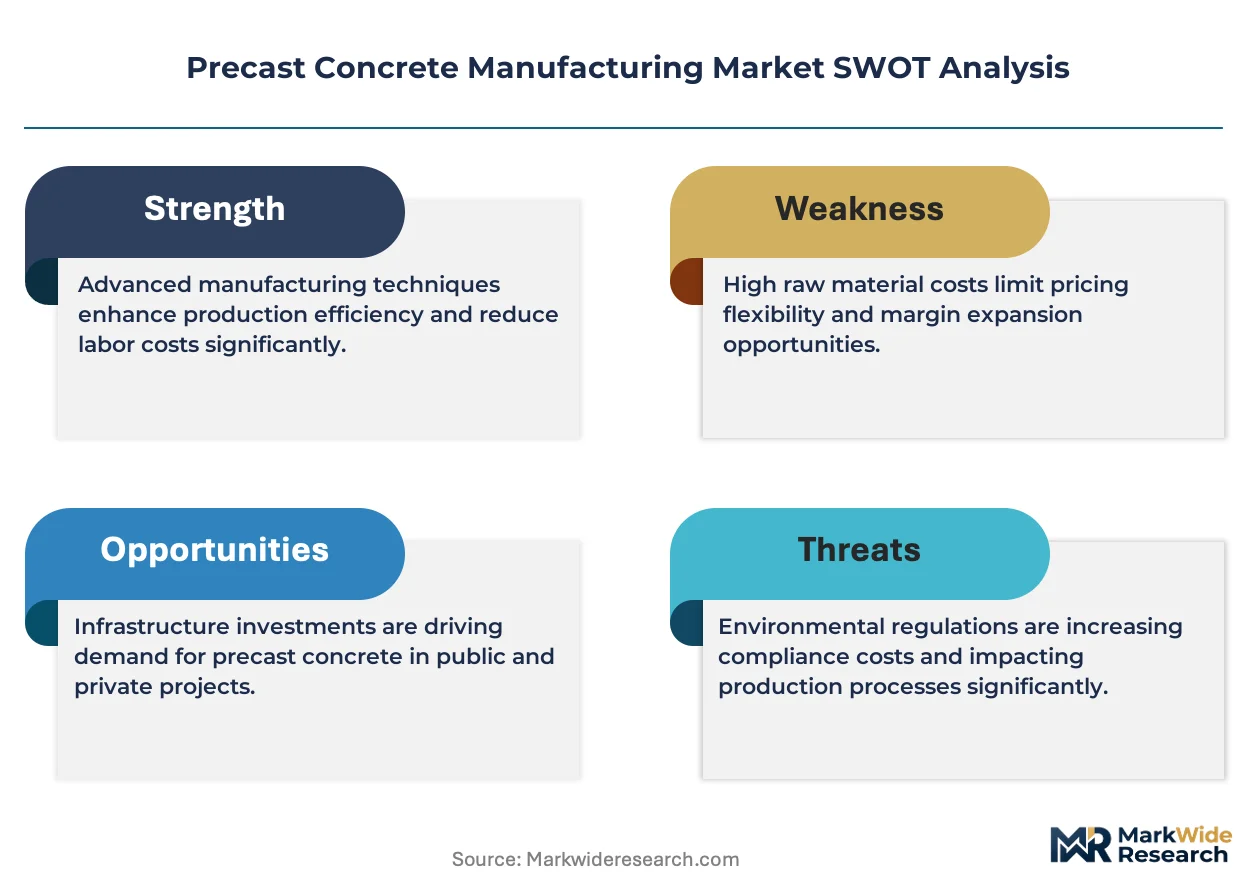
Factory automation is compressing labor-dependent production cycles while the EU Green Deal's embodied carbon thresholds force simultaneous capital reinvestment in low-carbon mix technologies, creating a dual-pressure environment for precast manufacturers.
Growth Catalysts
- EU Green Deal carbon benchmarks:Mandatory embodied carbon thresholds across member states are accelerating demand for geopolymer and calcined clay binders in structural precast applications.
- India's smart city corridors:State-led urban infrastructure programs in Maharashtra and Gujarat are generating concentrated procurement volumes for modular bridge decks and tunnel segments.
- Wet-cast automation:Robotic formwork cleaning and concrete placement systems are reducing cycle times by half in architectural cladding production.
Market Restraints
- Portland cement price volatility:Energy input costs and carbon border adjustments are compressing margins on standard-grade structural elements.
- Pre-stressing strand supply concentration:Chinese and Indian steel wire producers control over seventy percent of global capacity, creating procurement vulnerability.
- Dimensional tolerance limitations:Wet-cast methods struggle to achieve the precision required for high-rise modular connection systems without secondary machining.
Strategic Opportunities
- Vietnam's infrastructure buildout:North-South Expressway segments and metro systems in Hanoi and Ho Chi Minh City represent underpenetrated demand for pre-stressed bridge girders.
- Carbon capture curing:CO2 mineralization during accelerated curing is collapsing net embodied carbon in structural elements while qualifying for green procurement preferences.
- Direct-to-contractor digital platforms:B2B marketplaces are disintermediating traditional distributor networks in mid-size commercial construction.
Industry Challenges
- Pre-stressing tendon certification timelines:BIS approval cycles for imported strand grades delay project mobilization by four to six months in Indian infrastructure.
- Legacy ERP integration:Production scheduling software from the 2000s lacks API connectivity with modern IoT sensor networks for real-time curing monitoring.
- Specialized welding technician scarcity:Connection plate fabrication for modular high-rise systems faces bottlenecks from limited certified welder availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precast Concrete Manufacturing Market |
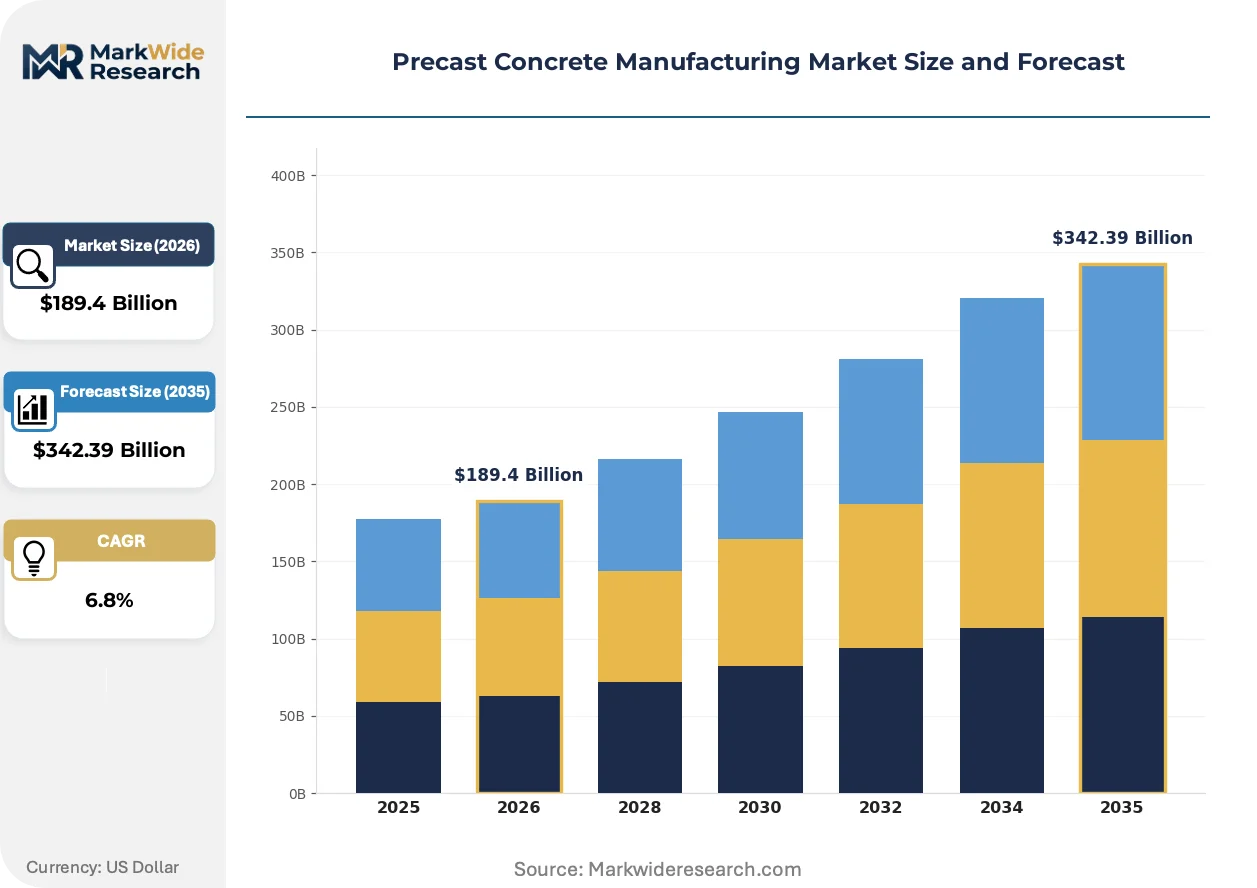
| Market Size in 2026 | $189.4 Billion |
| Market Size in 2035 | $342.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Panels, Flooring Systems, Beams, Columns Application: Residential, Commercial, Industrial, Infrastructure Material: Cement, Aggregate, Admixtures, Reinforcement Fabrication Method: Wet Cast, Dry Cast, Slipform, Pre-stressing |
| Companies Covered | CRH plc, Holcim Ltd, HeidelbergCement AG, CEMEX, Boral Limited, China National Building Material Co., Ltd, Oldcastle Infrastructure, Tindall Corporation, Forterra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precast Concrete Manufacturing Market Evolving Landscape
Digital fabrication and low-carbon material science are converging to redefine specification standards across structural and architectural precast segments.
Ultra-high-performance concrete (UHPC) is collapsing the boundary between structural and architectural functions by enabling thinner, load-bearing panels with exposed finishes. Infrastructure agencies in France and Japan specify UHPC for bridge deck link slabs and seismic retrofits. The technology is collapsing traditional trade distinctions between structural engineers and facade consultants on complex projects.
The EU Green Deal's embodied carbon disclosure requirements are mandating environmental product declarations for all public procurement above specified thresholds. German and Dutch precast producers are reformulating binders with calcined clay and ground glass pozzolan to meet Class A ratings. The policy is compressing competitive differentiation toward carbon transparency rather than price alone in European infrastructure tenders.
Design-build contractors are consolidating specification authority previously held by architect-led procurement offices. Major transportation departments in Texas and Florida now permit contractor-substituted precast alternatives during value engineering phases. This concentration is visible most acutely in US airport and parking structure programs where speed-to-occupancy overrides design fidelity.
Precast Concrete Manufacturing Market Segmentation
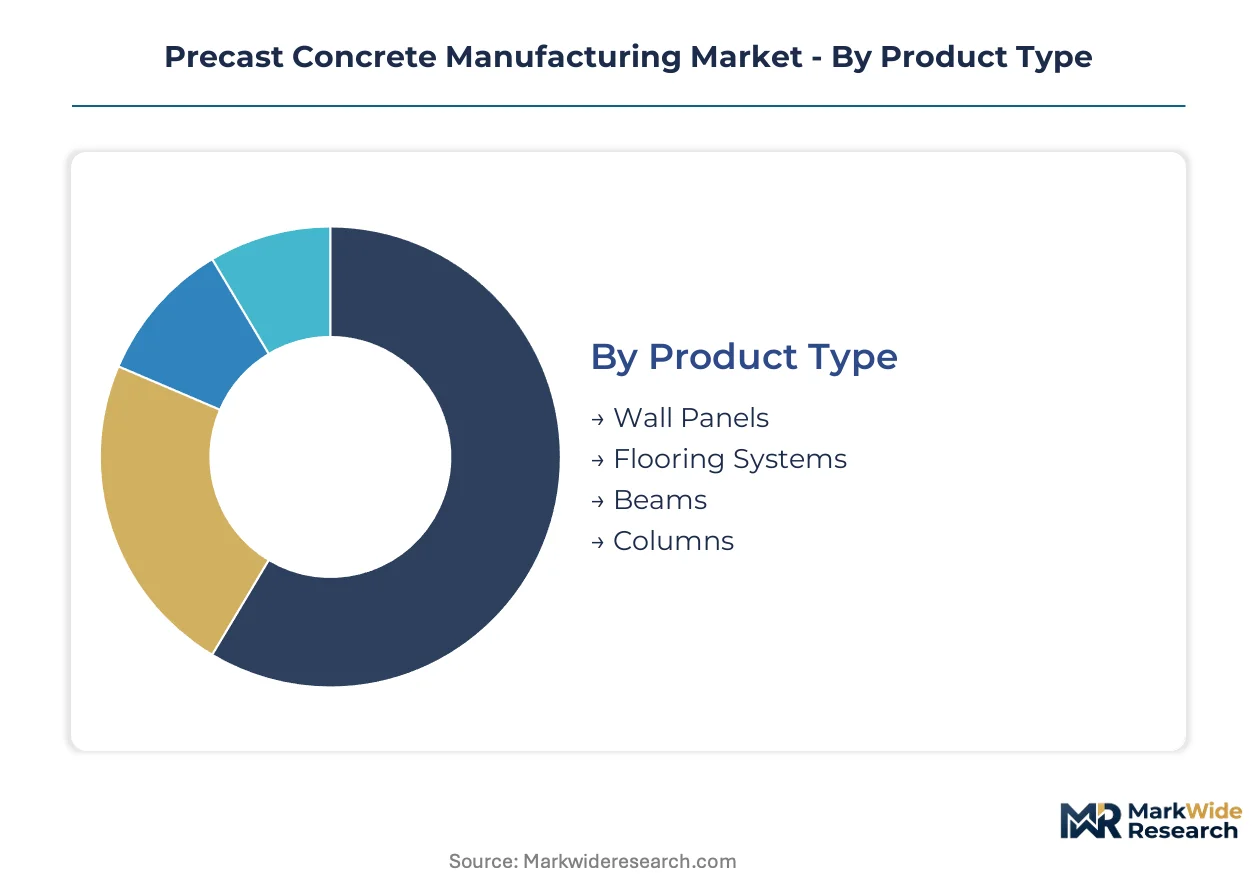
Precast concrete manufacturing segments along four distinct axes that shape procurement patterns and margin structures. Product type determines factory layout and mold capital intensity. Application segments diverge sharply in specification rigor and payment terms.
Product Type:
After-sales service intensity varies dramatically across product categories, with structural elements demanding field technical support while architectural components require finish warranty management.
- Wall Panels:Factory-cast vertical envelope elements integrate insulation layers and window openings in controlled conditions. India's smart city corridors in Maharashtra and Gujarat are absorbing high volumes of sandwich panels for affordable housing towers, driven by speed-to-completion mandates.
- Flooring Systems:Hollow-core slabs and double-tee units span intermediate structures with minimal propping. German and Dutch infrastructure agencies specify pre-stressed floor planks for parking structures and transit facilities under EU Green Deal embodied carbon thresholds.
- Beams:Linear flexural members carry distributed loads across open spans.
- Columns:Vertical compression elements anchor frame structures against lateral forces.
Wall panels hold the largest share; momentum sits with flooring systems.
Application:
Cost tier stratification separates specification-heavy infrastructure from price-sensitive residential procurement.
- Infrastructure:Bridge decks, tunnel segments, and transit structures command premium positioning through performance-grade certifications and extended design life requirements. Southeast Asian megaprojects in Vietnam's North-South Expressway and metro systems generate concentrated demand for pre-stressed girders with 100-year durability specifications.
- Residential:Mid-rise apartment construction and single-family housing deploy standardized panels and foundation elements. US Sun Belt markets facing skilled labor scarcity are accelerating adoption of modular wall systems for multifamily developments.
- Commercial:Office and retail structures balance span requirements with architectural expression.
- Industrial:Warehouse and manufacturing facilities prioritize clear spans and load-bearing capacity.
Infrastructure commands the deepest margins; residential is expanding most quickly.
Material:
Volume concentration in cement and aggregate creates procurement leverage for integrated producers.
- Cement:Portland and blended hydraulic binders constitute the primary matrix material. European producers are reformulating with calcined clay and ground glass pozzolan to meet EU Green Deal Class A carbon ratings in public tenders.
- Reinforcement:Steel bars, welded wire mesh, and pre-stressing strand provide tensile capacity. Indian BIS certification cycles for imported strand grades extend project mobilization timelines by four to six months in infrastructure applications.
- Aggregate:Graded crushed stone and sand comprise the bulk volume fraction.
- Admixtures:Chemical modifiers control workability, set time, and durability performance.
Cement represents the largest cost component; reinforcement faces the steepest supply concentration risk.
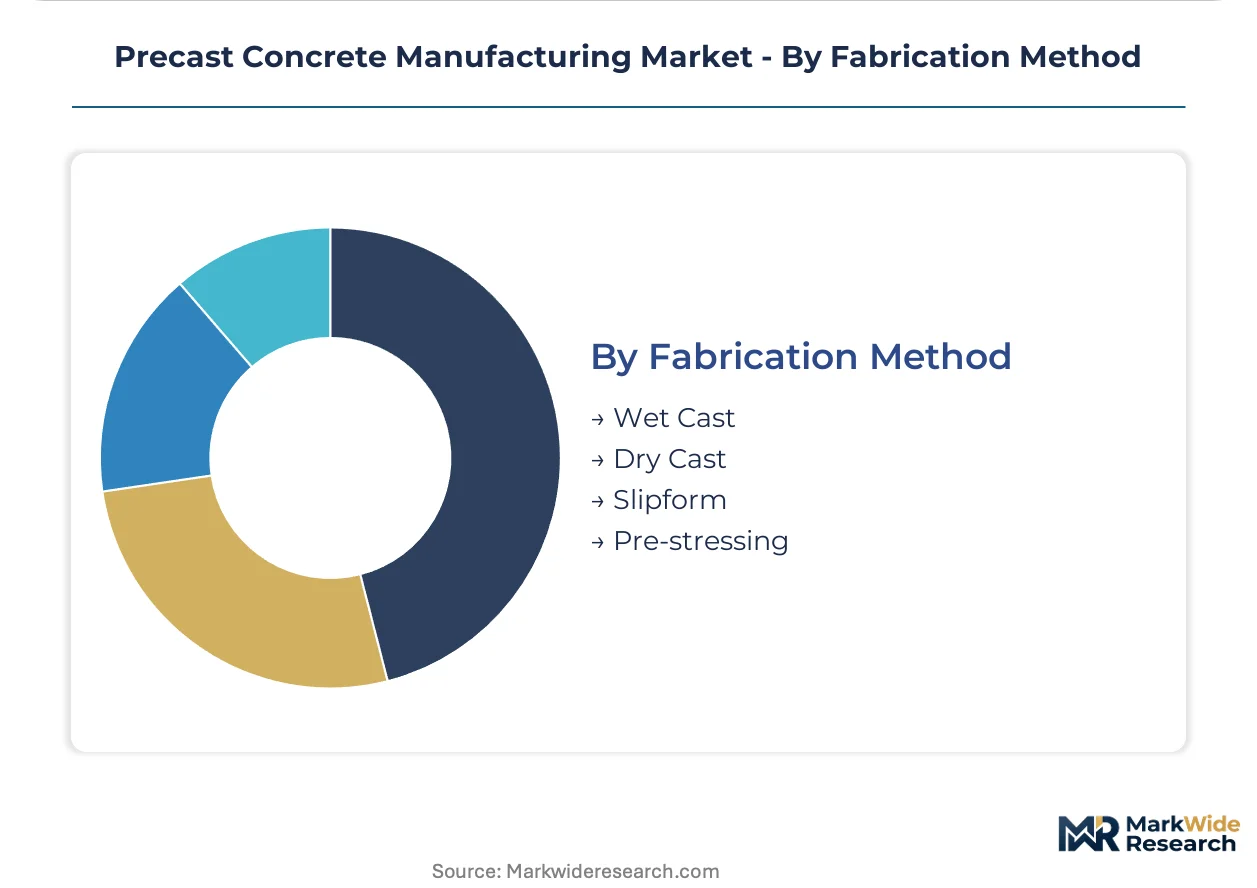
Fabrication Method:
Technology maturity separates established wet-cast processes from emerging carbon-curing innovations.
- Wet Cast:Flowable concrete fills precision molds for architectural and structural elements requiring smooth surface finishes. Robotic formwork cleaning and placement systems are compressing cycle times by half in cladding production for US commercial facades.
- Pre-stressing:Tensioned steel strand induces compressive pre-load for long-span bridge and parking deck applications. French and Japanese infrastructure agencies specify UHPC pre-stressed elements for seismic retrofits and deck link slabs.
- Dry Cast:Zero-slump concrete extrudes through forming machines for high-volume standardized sections.
- Slipform:Continuous casting produces uniform vertical elements without joint interruptions.
Wet cast dominates architectural specifications; pre-stressing carries the steepest expansion trajectory in infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated cement-precast conglomerates dominate capacity in Germany, the United States, India, China, and Vietnam, with each market responding to distinct regulatory pressures on embodied carbon and infrastructure procurement timelines.
Germany
Calcined clay binder reformulation accelerates across Rhineland batching operations as the EU Green Deal's Class A carbon ratings become mandatory for public tenders. ECHA compliance documentation now governs admixture selection in structural precast applications. The Düsseldorf-Cologne industrial corridor concentrates wet-cast automation investments for architectural cladding exports.
United States
Sun Belt multifamily developers deploy modular wall systems to offset skilled labor scarcity in Texas and Florida metro construction. OSHA exposure mandates govern plant safety protocols during pre-stressing tendon handling. The Dallas-Fort Worth metroplex anchors precast capacity expansion for airport and parking structure megaprojects.
India
Maharashtra and Gujarat smart city corridors generate concentrated procurement for modular bridge decks and tunnel segments under state-led urban infrastructure programs. BIS certification cycles for imported pre-stressing strand extend project mobilization timelines by four to six months. The Mumbai-Pune industrial belt concentrates factory-built component manufacturing for affordable housing towers.
China
Dual carbon goals under MEE oversight accelerate geopolymer binder testing in Yangtze River Delta precast facilities. GB standards revisions tighten dimensional tolerance requirements for high-rise modular connection systems. The Shanghai-Suzhou manufacturing cluster leads wet-cast automation adoption for commercial facade exports.
Vietnam
North-South Expressway segments and Hanoi-Ho Chi Minh City metro systems generate underpenetrated demand for pre-stressed bridge girders with 100-year durability specifications. National infrastructure procurement guidelines increasingly reference embodied carbon disclosure requirements. The Hai Phong-Quang Ninh industrial zone attracts precast joint ventures targeting export markets.
Precast Concrete Manufacturing Market Competitive Landscape
Vertically integrated building materials conglomerates and specialized precast fabricators split the market along capital intensity and geographic coverage vectors. Tier-one players leverage captive aggregate reserves and multi-continent batching networks to sustain margin stability against Portland cement price volatility. Mid-scale specialists concentrate on design-build contractor relationships and regional logistics density. Competitive dynamics center on low-carbon mix technology licensing and direct-to-contractor digital platform development.
Among Ireland-based building materials groups, CRH plc exemplifies the vertically integrated archetype through aggregate-to-precast supply chain control. Mexico-based CEMEX S.A.B. de C.V. occupies a position emphasizing urban megaproject logistics density across the Americas. Germany-based HeidelbergCement AG represents the European infrastructure-focused specialization model with dedicated batching operations for transportation agency specifications.
| Leading Market Players |
|---|
| CRH plc |
| Holcim Ltd |
| HeidelbergCement AG |
| CEMEX |
| Boral Limited |
| China National Building Material Co., Ltd |
| Oldcastle Infrastructure |
| Tindall Corporation |
| Forterra |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing cluster anchors global wet-cast capacity for architectural precast exports, and its automation density translates directly into pricing power over European buyers facing EU Green Deal compliance deadlines. Portland cement cost volatility and pre-stressing strand supply concentration feed downstream margin compression across standard-grade structural elements.
Pricing Analysis
The EU Green Deal's embodied carbon disclosure mandates dictate the pricing tier structure across European public procurement. Three-tier pricing structure across premium low-carbon certified, standard compliance-grade, and economy unverified tiers separates producers with calcined clay binder reformulation from legacy Portland-dependent competitors. Cost compression in standard-grade elements is intensifying because energy input spikes and carbon border adjustments erode margins on undifferentiated commodity precast. Infrastructure agencies exhibit the least price sensitivity due to 100-year durability specifications, while residential developers in India's affordable housing towers face acute budget constraints.
Supply Chain Analysis
CRH plc, HeidelbergCement AG, and CEMEX hold captive aggregate reserves and multi-continent batching networks that concentrate contract-manufacturing capacity. Geographic supply concentrates in Germany, the United States, and India, with emerging capacity buildout in Vietnam's Hai Phong-Quang Ninh industrial zone. Raw material dependencies rest on Portland cement, pre-stressing steel strand, and graded crushed stone aggregates. Single-source vulnerability in Chinese and Indian steel wire producers controlling over seventy percent of global pre-stressing strand capacity creates procurement risk. Distribution runs through design-build contractor networks and direct-to-contractor digital platforms disintermediating traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital fabrication platforms and low-carbon material science are converging to create interoperability standards that reshape competitive control points, positioning precast manufacturing at a platform-economics inflection where carbon transparency becomes the dominant procurement filter.
For Market Incumbents: Pre-empt margin erosion in standard-grade structural elements by accelerating calcined clay and geopolymer binder licensing to secure EU Green Deal Class A certification ahead of mandatory thresholds. Capture captive aggregate reserves in Vietnam and India to offset Portland cement price volatility and defend position against integrated cement-precast conglomerates expanding regional logistics density. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's North-South Expressway and metro infrastructure segments where pre-stressed bridge girder demand outpaces domestic supply capacity. Target carbon capture curing technology partnerships with European engineering firms to qualify for green procurement preferences in German and Dutch infrastructure tenders, bypassing legacy producer entrenchment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized precast fabricators with UHPC formulation expertise and direct-to-contractor digital platform capabilities over commodity structural element producers. Long-term viability hinges on low-carbon mix technology licensing revenue streams and design-build contractor relationship consolidation. Monitor BIS certification cycle acceleration for imported pre-stressing strand as the inflection signal for Indian infrastructure market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Calcined Clay Binder Reformulation | EU Green Deal Class A ratings secure premium positioning in German and Dutch public tenders. |
| Wet-Cast Automation Investment | Robotic formwork cleaning halves cycle times for US commercial facade production. |
| Carbon Capture Curing Deployment | CO2 mineralization during accelerated curing collapses net embodied carbon for green procurement qualification. |
| Direct-to-Contractor Platform Launch | B2B marketplaces disintermediate distributor networks in mid-size commercial construction segments. |
| Vietnam Joint Venture Formation | Hai Phong-Quang Ninh industrial zone access targets export markets and domestic infrastructure buildout. |
Research Methodology
The analysis maps wet-cast architectural, pre-stressed structural, dry-cast standardized, and slipform vertical element sub-sectors, each validated through plant operations managers, design-build contractor procurement leads, infrastructure agency specification engineers, and pre-stressing strand distribution channel heads. Primary interview intelligence triangulates against customs and trade flow databases, national standards body certification records, SEC 10-K filings from listed building materials groups, and EU EPD environmental product declaration registries. Bottom-up capacity and shipment estimates reconcile with top-down cement consumption and construction output indices.
Assumptions held fixed include EU Green Deal embodied carbon threshold implementation timelines and BIS certification cycle durations for imported reinforcement, while Portland cement price trajectories and infrastructure procurement budget allocations were varied across sensitivity bands. Segmentation dimensions modeled span product type, application vertical, material composition, and fabrication method, with regional regulatory cluster and project scale tier as cross-cutting variables. CAGRs derive from weighted average of historical volume trends and forward-looking capacity expansion announcements, incorporating pre-stressing strand supply concentration risk and wet-cast automation adoption curves as industry-specific forecast inputs.
Stress conditions across Portland cement energy input costs, carbon border adjustment implementation scope, and pre-stressing strand import certification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and acknowledge that regulatory divergence between carbon accounting methodologies or abrupt BIS procedural changes could materially revise trajectory. Quarterly review of EU EPD registration volumes, Indian infrastructure tender award flows, and Vietnamese expressway segment mobilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
Garage Doors Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
Japan Oriented Strand Board Market
Building & Construction Materials
SBS Waterproofing Membrane Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Sectional Door Market