
 Rodless Cylinders Market | 2026-2036
Rodless Cylinders Market Size, Share, and Industry Trends Forecast 2026-2036
Rodless Cylinders Market Analytics
Equipment leasing and performance-based contracting are narrowing the capital barrier for mid-sized manufacturers seeking automated linear motion systems. SMC Corporation leverages its captive pneumatic component ecosystem to sustain pricing power across Asian manufacturing hubs. Festo AG & Co. KG anchors its competitiveness in Europe through application engineering depth for cleanroom-compatible rodless designs. Parker Hannifin competes in North America by controlling distribution of integrated electric rodless systems for precision assembly.
A rodless cylinder transmits linear force through an external carriage coupled to an internal piston, eliminating the exposed piston rod to achieve stroke lengths up to ten meters within compact envelopes; manufacturers machine the extruded aluminum body to tight bore tolerances and seal the carriage against ingress for dust-heavy factory floors. Magnetically coupled types lead unit shipments where leak-free containment matters, while electric variants capture the fastest expansion as servo precision displaces pneumatics in electronics assembly. The automotive vertical concentrates margin pools around high-cycle magnetically coupled units for body-in-handling, whereas food processing buyers prioritize stainless pneumatic constructions that tolerate caustic washdown protocols.
ISO 4414 governs pneumatic machinery safety, OSHA enforces lockout-tagout for pressurized actuators in US plants, and the EU Machinery Directive mandates risk assessments for integrated linear motion modules—collectively elevating certified product demand over unbranded alternatives. Japan's METI promotes factory automation adoption through productivity incentives that indirectly expand rodless cylinder deployment in precision manufacturing clusters. Stakeholders must monitor how electric linear motor technology encroaches on traditional rodless cylinder positioning accuracy thresholds.
Market Dynamics
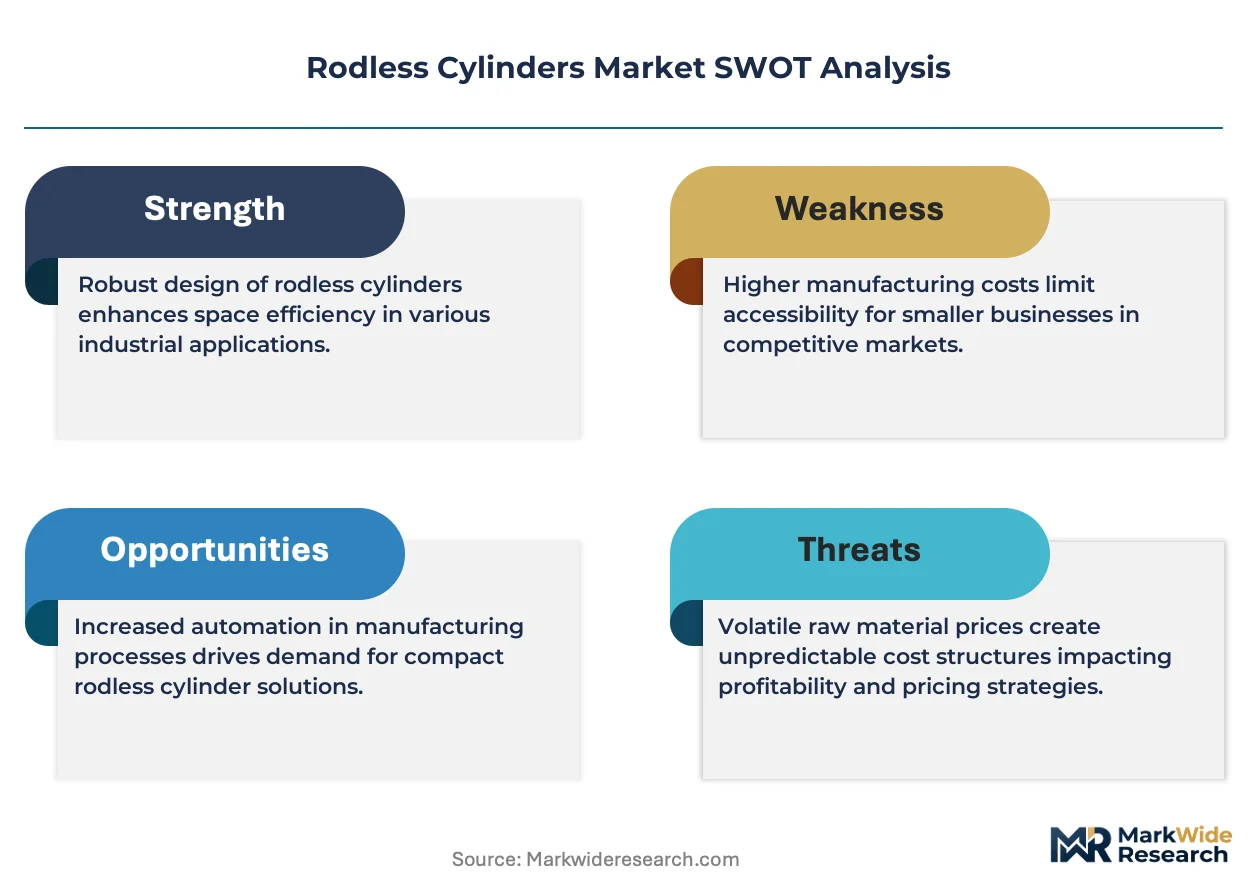
Electric linear motor technology is compressing the traditional performance advantage of pneumatic rodless cylinders in precision positioning applications, forcing incumbent suppliers to defend their installed base through integrated servo-pneumatic hybrid architectures.
Growth Catalysts
- EU Machinery Directive compliance mandates:The EU Machinery Directive and ISO 4414 pneumatic safety standards are tightening certification requirements for automated motion systems, elevating demand for certified rodless cylinder products over unbranded alternatives.
- Food processing washdown protocols:Packaging lines in food processing plants are expanding adoption of rodless actuators for sanitary washdown environments where stainless pneumatic constructions tolerate caustic cleaning cycles.
- Germany's industrial automation corridor:OEMs in Germany's industrial automation corridor are integrating rodless cylinders into compact handling modules, concentrating demand for magnetically coupled types in high-cycle body-in-white applications.
Market Restraints
- Electric linear motor substitution:Electric linear motor technology is encroaching on traditional rodless cylinder positioning accuracy thresholds in electronics assembly, compressing addressable market for pure pneumatic solutions.
- Aluminum extrusion input volatility:Tight bore tolerances require precision-machined extruded aluminum bodies, exposing manufacturers to raw material cost swings and energy-intensive processing margins.
- Asian supply concentration:Captive pneumatic component ecosystems concentrate component supply in Asian manufacturing hubs, creating geographic dependency risks for European and North American system integrators.
Strategic Opportunities
- Cleanroom-compatible design expansion:Application engineering depth for cleanroom-compatible rodless designs opens white space in semiconductor and pharmaceutical manufacturing where particulate containment is non-negotiable.
- Performance-based contracting models:Equipment leasing and performance-based contracting are narrowing the capital barrier for mid-sized manufacturers seeking automated linear motion systems without upfront ownership.
- Japan METI productivity incentives:Japan's METI promotes factory automation adoption through productivity incentives that indirectly expand rodless cylinder deployment in precision manufacturing clusters.
Industry Challenges
- Servo-pneumatic integration complexity:Hybrid electric-pneumatic system architectures demand cross-disciplinary engineering teams fluent in both fluid power and servo control, tightening talent pipelines.
- Multi-jurisdiction certification timelines:OSHA lockout-tagout enforcement for pressurized actuators in US plants, layered atop EU Machinery Directive risk assessments, extends product launch cycles for integrated linear motion modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rodless Cylinders Market |
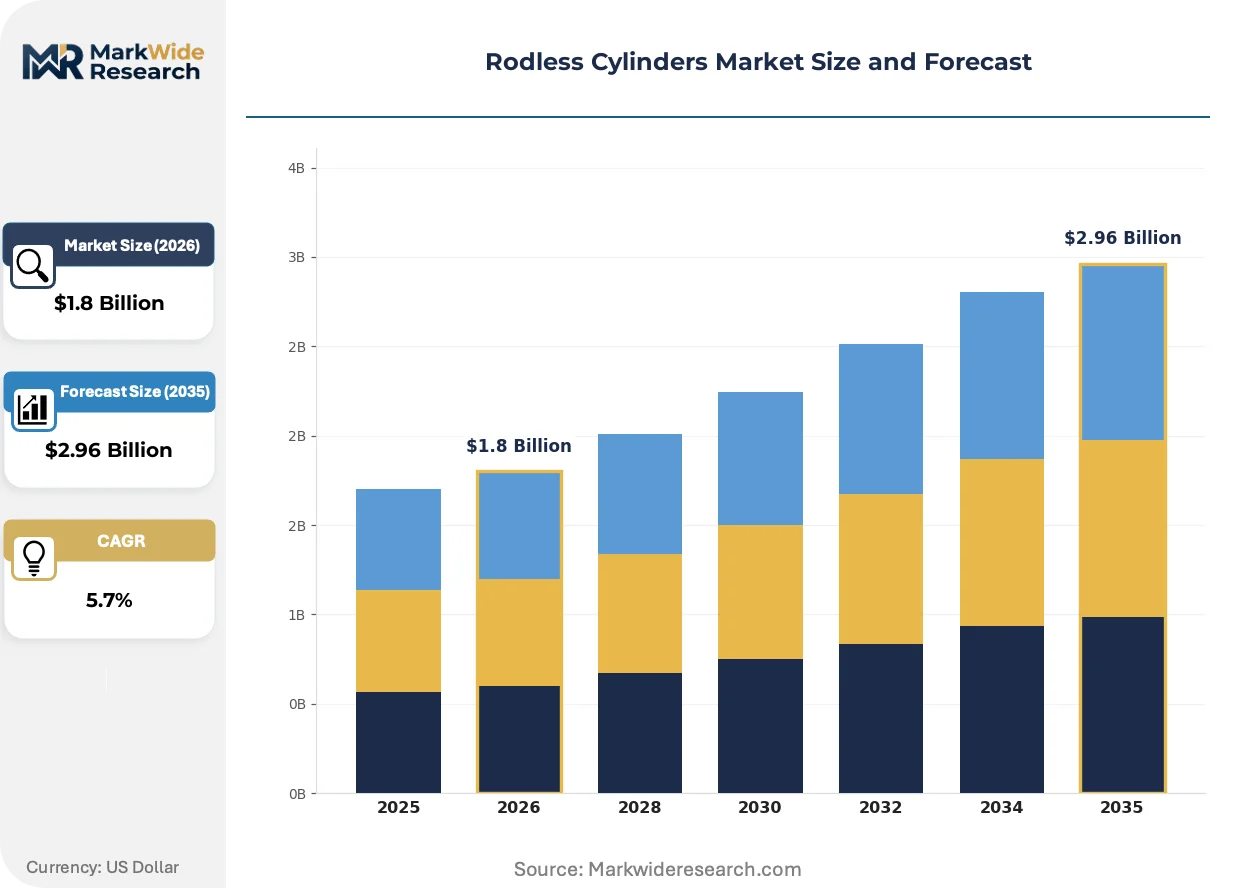
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Assembly Automation, Packaging, Material Handling, Machine Tool Type: Magnetically Coupled, Pneumatic, Electric, Hydraulic Industry Vertical: Automotive, Food Processing, Pharmaceuticals, Electronics Technology: Linear Motion, Control Systems, Robotics, Simulation |
| Companies Covered | SMC Corporation, Festo AG & Co. KG, Parker Hannifin, Tolomatic, Inc., CKD Corporation, GTek Automation, Airtac International Group, Camozzi Automation S.p.A., Emerson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rodless Cylinders Market Evolving Landscape
Linear motion technology is bifurcating between precision servo-electrics and ruggedized pneumatics, with hybrid architectures emerging as the contested middle ground where neither pure technology dominates.
Magnetically coupled rodless cylinder technology is migrating from traditional pneumatic-only architectures toward sealed, leak-free containment systems for dust-heavy factory floors. Automotive body-in-white handling lines are adopting these configurations at accelerating pace to eliminate rod seal wear points. The structural consequence is compressing maintenance intervals and extending mean time between failures in high-cycle environments.
ISO 4414 pneumatic machinery safety standards are tightening enforcement across European manufacturing jurisdictions. The regulation mandates validated risk assessments for integrated linear motion modules, forcing OEMs to document failure modes and mitigation strategies. Cleanroom-compatible rodless designs face the steepest compliance burden as they must simultaneously satisfy particulate containment and pressure safety protocols.
Buyer preference is rotating toward certified product alternatives over unbranded substitutes as liability exposure concentrates in automated production environments. System integrators in Germany's industrial corridor are consolidating supplier relationships around vendors with documented ISO 4414 compliance, displacing fragmented procurement of commodity pneumatic components. Food processing verticals exhibit the most pronounced certification-driven preference shift due to washdown protocol validation requirements.
Rodless Cylinders Market Segmentation
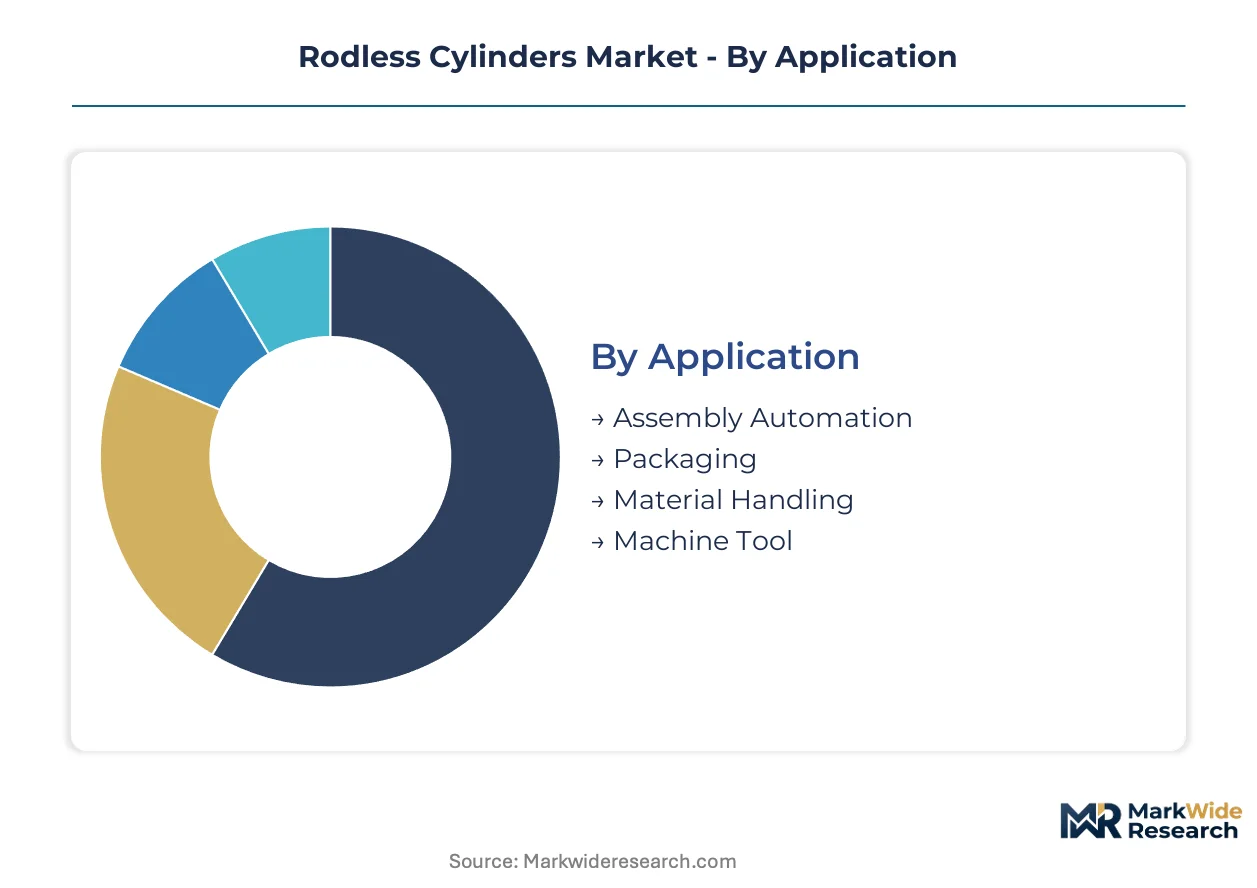
Rodless cylinder procurement patterns diverge sharply across application environments, with washdown tolerance requirements in food plants contrasting against precision positioning demands in electronics assembly. Technology selection determines total cost of ownership trajectories, forcing buyers to weigh pneumatic reliability against electric accuracy in long-cycle automation investments.
Application:
Cost tier differentiation separates high-velocity packaging lines from precision assembly cells, with capital intensity and cycle frequency driving technology selection.
- Assembly Automation:Magnetically coupled configurations dominate precision part placement where repeatability tolerances compress below 0.1 millimeter. Electronics manufacturers in precision manufacturing clusters specify these units for surface-mount technology lines where particulate exclusion and positioning accuracy converge.
- Packaging:Stainless pneumatic rodless cylinders tolerate caustic washdown protocols in food processing environments where caustic cleaning cycles degrade standard seal materials. Line speeds exceeding 200 cycles per minute concentrate demand for magnetically coupled variants that eliminate rod seal wear points.
- Material Handling:Long-stroke magnetically coupled units span transfer distances up to ten meters in automotive body-in-white handling.
- Machine Tool:Hydraulic rodless cylinders deliver force-dense actuation for metal cutting and forming operations.
Packaging commands the established base. The steepest expansion runs through assembly automation.
Type:
Technology maturity separates pneumatic dominance from electric encroachment, with hybrid architectures emerging in contested precision positioning applications.
- Magnetically Coupled:Sealed containment eliminates external leakage paths through an external carriage magnetically locked to an internal piston, achieving stroke lengths to ten meters without exposed rods. Automotive body-in-white handling lines specify these configurations for high-cycle environments where maintenance access is constrained.
- Electric:Servo motor-driven belt or screw mechanisms displace pneumatics in electronics assembly where positioning accuracy thresholds compress below pneumatic repeatability limits. ISO 4414 compliance burdens weigh less heavily on electric variants that eliminate pressurized containment requirements.
- Pneumatic:Compressed air systems retain cost advantages in dust-heavy factory floors where ingress tolerance exceeds precision demands.
- Hydraulic:Force-dense fluid power serves metal forming and heavy material handling where pneumatic force density proves insufficient.
Magnetically coupled variants anchor the installed base. Electric types are climbing the fastest as servo precision encroaches on traditional pneumatic positioning domains.
Industry Vertical:
Regulatory burden intensity stratifies demand, with washdown validation requirements in food and pharmaceutical plants elevating certified product specifications above commodity alternatives.
- Automotive:High-cycle magnetically coupled units concentrate in body-in-white handling lines where cycle frequencies exceed one million annually and downtime costs escalate rapidly. OEMs in Germany's industrial automation corridor integrate these into compact handling modules for paint shop and assembly transfer operations.
- Food Processing:Stainless pneumatic constructions with FDA-compliant seal materials satisfy caustic washdown protocols where sodium hypochlorite and peracetic acid cycles degrade standard elastomers. Certification-driven procurement displaces unbranded alternatives as liability exposure concentrates in automated production environments.
- Pharmaceuticals:Cleanroom-compatible rodless designs face steep compliance burdens for particulate containment concurrent with pressure safety protocols.
- Electronics:Electric linear motor technology encroaches on traditional rodless cylinder positioning accuracy thresholds in semiconductor and display manufacturing.
Automotive retains the volume concentration. Pharmaceuticals is gaining share fastest as cleanroom engineering depth opens white space in biologics manufacturing expansion.
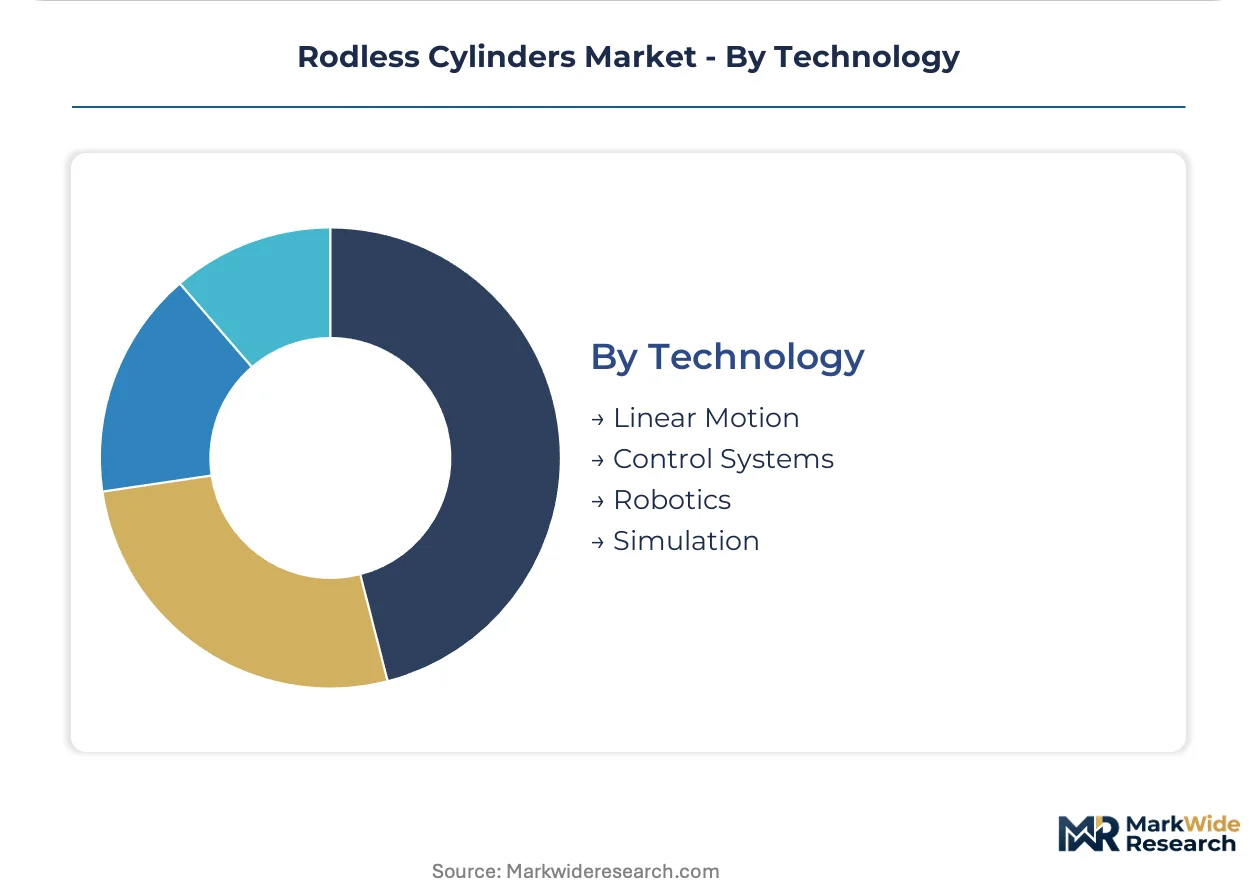
Technology:
Integration complexity separates standalone linear motion components from system-level architectures, with control sophistication determining supplier margin capture.
- Linear Motion:Extruded aluminum body construction with tight bore tolerances forms the mechanical foundation, with carriage sealing against ingress determining service life in dust-heavy factory floors. Magnetically coupled variants achieve leak-free containment for contaminated environments.
- Control Systems:Servo-pneumatic hybrid architectures defend pneumatic installed bases against pure electric substitution by integrating position feedback and proportional pressure regulation. Cross-disciplinary engineering teams fluent in both fluid power and servo control tighten talent pipelines for these configurations.
- Robotics:Rodless cylinders integrate as linear axes in Cartesian coordinate robotic systems for pick-and-place and palletizing operations.
- Simulation:Digital twin validation of motion profiles compresses commissioning timelines for complex multi-axis installations.
Linear motion commands the established base. Control systems are expanding most quickly as hybrid architectures bridge pneumatic reliability and electric precision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rodless cylinder trade flows tilt toward manufacturing economies with deep automation infrastructure, with Germany, Japan, and the United States posting consistent equipment surpluses while emerging industrial centers absorb imports to populate greenfield assembly lines.
Germany
OEMs in Germany's industrial automation corridor integrate magnetically coupled rodless cylinders into compact handling modules for automotive body-in-white operations. The EU Machinery Directive and ISO 4414 standards enforce validated risk assessments for integrated linear motion modules, elevating certified product specifications. Stuttgart and Munich anchor precision manufacturing clusters where Festo AG & Co. KG maintains application engineering depth for cleanroom-compatible designs.
Japan
Precision manufacturing clusters in Aichi and Kanagawa prefectures deploy rodless actuators for surface-mount technology lines where repeatability tolerances compress below 0.1 millimeter. METI productivity incentives indirectly expand factory automation adoption, accelerating rodless cylinder deployment in electronics assembly. Yokohama-based system integrators concentrate demand for servo-pneumatic hybrid architectures that bridge pneumatic reliability and electric precision.
United States
OSHA lockout-tagout enforcement for pressurized actuators shapes procurement patterns across automotive and food processing verticals. The Southeast manufacturing belt—spanning Georgia, Tennessee, and South Carolina—absorbs rodless cylinder volumes for packaging automation in poultry and beverage processing plants. Chicago and Detroit retain concentrations of metal forming operations specifying hydraulic rodless variants for force-dense applications.
China
MIIT industrial upgrade programs accelerate automation substitution in Yangtze River Delta and Pearl River Delta manufacturing zones. GB standards for pneumatic machinery safety tighten parallel to ISO harmonization, compressing demand for uncertified alternatives. Shenzhen and Suzhou electronics assemblers rotate procurement toward electric linear motor technology where positioning accuracy thresholds exceed pneumatic repeatability limits.
South Korea
Busan-Ulsan shipbuilding and automotive clusters specify long-stroke magnetically coupled units for transfer distances approaching ten meters in heavy material handling. MFDS-aligned sanitary equipment standards in Gyeonggi-do food processing plants prioritize stainless pneumatic constructions with FDA-compliant seal materials. Seoul Capital Area system integrators consolidate supplier relationships around vendors with documented multi-jurisdiction certification.
Rodless Cylinders Market Competitive Landscape
On the supply side, the industry is moderately consolidated around pneumatic component specialists with captive ecosystems and motion control conglomerates with distribution depth. Three strategic archetypes dominate: Asian pneumatic pure-plays with backward-integrated manufacturing, European application engineering specialists with cleanroom credentials, and North American diversified industrials with electric motion portfolios. Competitive moves concentrate on geographic expansion through distribution partnerships and portfolio diversification into servo-pneumatic hybrid architectures.
Within the pneumatic pure-play tier, SMC Corporation exemplifies the Asian manufacturing hub archetype with its captive component ecosystem, while Festo AG & Co. KG anchors European positioning through application engineering depth. Parker Hannifin occupies the diversified industrial position, competing through integrated electric rodless system distribution. These three represent distinct strategic postures: ecosystem control, technical specialization, and portfolio breadth.
| Leading Market Players |
|---|
| SMC Corporation |
| Festo AG & Co. KG |
| Parker Hannifin |
| Tolomatic, Inc. |
| CKD Corporation |
| GTek Automation |
| Airtac International Group |
| Camozzi Automation S.p.A. |
| Emerson |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's container rate volatility transmits directly into landed costs for European system integrators sourcing magnetically coupled rodless cylinders, compressing margins on standard-grade units while amplifying price premiums for ISO 4414-certified alternatives sourced through captive Asian manufacturing hubs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under ISO 4414 and customization depth for cleanroom compatibility separate price bands, with aftermarket service bundling adding further differentiation. Cost compression in economy tiers intensifies because electric linear motor substitution erodes pneumatic volume commitments. Small-to-mid-sized food processing plants exhibit the highest price sensitivity, whereas automotive OEMs in Germany's industrial corridor prioritize certified supply security over unit economics.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for aluminum extrusion inputs and precision-machined carriage assemblies. Manufacturing concentrates in China, Japan, and Germany, with extruded aluminum body production and magnet assembly operations drawing from these hubs. Single-source vulnerability persists in rare-earth magnet supply for magnetic coupling mechanisms. Distribution runs through authorized distributor networks with application engineering support, bypassing commodity wholesale channels for certified product categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as electric-pneumatic hybrid architectures create technology transition zones where neither pure-play pneumatic specialists nor electric motion incumbents hold definitive advantage, opening niches for cross-disciplinary engineering capabilities.
For Market Incumbents: Pre-empt electric linear motor encroachment by accelerating servo-pneumatic hybrid R&D investment and securing backward integration into rare-earth magnet supply chains. Certification depth under ISO 4414 and the EU Machinery Directive remains the priority defensive lever against unbranded Asian imports. Capacity addition in Eastern European manufacturing clusters reduces tariff exposure while maintaining proximity to German automotive OEM demand concentration. For New Entrants and Emerging Players: Build out cleanroom-compatible application engineering capabilities for pharmaceutical and semiconductor manufacturing verticals where Festo AG & Co. KG's established position leaves service gaps in mid-tier biologics production. The most penetrable segment is stainless pneumatic constructions for food processing washdown environments in the US Southeast manufacturing belt. A technical sales-led go-to-market angle emphasizing documented FDA-compliant seal validation displaces commodity procurement relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized pneumatic component divisions lacking electric motion portfolio breadth. Long-term viability hinges on hybrid architecture capabilities bridging fluid power reliability and servo precision. The specific signal to watch is accelerating deployment of servo-pneumatic systems in Japan's precision manufacturing clusters as an inflection indicator for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | ISO 4414 compliance documentation accelerates OEM approval cycles in Germany's automotive corridor. |
| Hybrid Architecture Development | Servo-pneumatic integration defends pneumatic installed base against pure electric substitution in electronics assembly. |
| Geographic Manufacturing Footprint | Eastern European production facilities reduce EU tariff exposure on Chinese-sourced aluminum extrusions. |
| Application Engineering Partnership | Cleanroom design collaboration with pharmaceutical OEMs opens biologics manufacturing expansion segments. |
| Aftermarket Service Expansion | Predictive maintenance contracts for magnetically coupled units extend customer lifetime value in high-cycle automotive handling. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and pneumatic system integrators; and secondary validation through customs trade records, SEC filings of motion control conglomerates, ISO certification registries, and METI industrial automation incentive disclosures. Bottom-up unit shipment estimates by application and technology type were triangulated against top-down value projections derived from distributor revenue disclosures.
Forecast inputs span technology substitution rates between pneumatic and electric linear motion, regulatory compliance cost trajectories under EU Machinery Directive enforcement, and aluminum input price sensitivity across the projection horizon. Segmentation dimensions modeled include actuator type, application environment, industry vertical, and regional manufacturing cluster. CAGRs were derived from fitted growth curves anchored to disclosed equipment replacement cycles and greenfield automation investment patterns.
Stress conditions across raw material cost bands, tariff rate scenarios, and electric motor cost decline curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology adoption S-curves and regulatory harmonization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Automatic Slack Adjusters Market
Electro-Mech Systems
Tubular Motors Market
Electro-Mech Systems
HVAC Relay Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market
Electro-Mech Systems
Movable Scaffolding System Market
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Wiring Duct Market
Electro-Mech Systems
Rigid Metal Electrical Conduit Market
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Elevator Door-Motor Market