
 Tubular Motors Market | 2026-2036
Tubular Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Tubular Motors Market Analytics
Brushless DC motor architecture is narrowing the performance gap between standard and premium tubular motor tiers. Somfy Group leverages integrated smart control ecosystems to sustain pricing power in European home automation channels. Ningbo Dooya Electromechanical anchors volume production through captive magnet supply and scale manufacturing in Zhejiang province. Elero GmbH differentiates via specialized low-noise gearing systems for healthcare and hospitality installations.
Tubular motors are cylindrical electromechanical drives encased within a hollow steel or aluminum tube, typically 25-60mm in diameter, converting electrical energy into rotational torque for roller-based mechanical systems. These devices deliver 10-300 Nm torque output through planetary or worm gear reductions, serving primary functions in automated shading, security closures, and material handling conveyance. Smart motors incorporating Wi-Fi and Zigbee connectivity command margin premiums over standard AC variants across residential and commercial channels. High torque motors dominate industrial roller shutter and warehouse door applications where load requirements exceed 150 Nm. Low noise motors capture hospitality and healthcare specification demand through sub-35 dB operational thresholds.
CE marking under the EU Machinery Directive and Ecodesign regulations govern minimum efficiency standards and safety interlocks for tubular motors deployed across European member states. China's GB standards and CCC certification administered by SAMR mandate electromagnetic compatibility and thermal protection for motors sold domestically. NMPA-equivalent technical regulations in China and REACH substance restrictions from ECHA collectively elevate compliance costs for manufacturers sourcing rare-earth magnet materials. Stakeholders must monitor evolving interoperability standards between motor control protocols and building management system architectures.
Market Dynamics
Brushless DC architecture is collapsing the historical performance gap between standard AC and premium smart motor tiers, forcing incumbents to recalibrate R&D roadmaps and pricing architectures across residential and commercial channels.
Growth Catalysts
- EU Ecodesign Directives:Minimum efficiency mandates under the Machinery Directive are phasing out single-speed AC induction motors from roller shutter and awning applications.
- Smart Building Retrofit Cycles:Germany's industrial automation corridor is accelerating replacement of legacy 230V AC motors with Zigbee-enabled variants in commercial real estate portfolios.
- Rare-Earth Magnet Supply Diversification:China's Zhejiang province is scaling NdFeB magnet production for brushless DC stator assemblies, reducing cost premiums for high-torque tubular drives.
Market Restraints
- Neodymium Price Volatility:Rare-earth magnet input costs fluctuate with Chinese export quota adjustments, compressing margins for brushless DC motor assemblers.
- Supply Concentration Risk:Planetary gearhead manufacturing concentrates in Baden-Württemberg and Ningbo, creating single-source vulnerability for precision-machined steel housings.
- AC Motor Substitution Inertia:Cost-sensitive residential installers in Southern Europe continue specifying brushed AC variants despite efficiency penalties, delaying technology transitions.
Strategic Opportunities
- Healthcare Noise Specifications:Sub-35 dB operational thresholds for patient room shading are creating specification pull for low-noise helical gearing systems in hospital construction.
- India Smart City Mandates:The CEA's building automation guidelines for commercial structures are opening specification channels for Wi-Fi-integrated tubular motors in Tier-1 metro developments.
- Photovoltaic Shading Convergence:Building-integrated PV awning systems are requiring high-torque motors with position feedback, merging solar and shading control electronics.
Industry Challenges
- Embedded Firmware Talent Scarcity:Motor control algorithm development for sensorless brushless DC commutation requires scarce power electronics specialists.
- Multi-Protocol Certification Burden:Thread, Matter, and proprietary smart home ecosystems demand redundant radio certification cycles, extending product launch timelines.
- Legacy Building Management Integration:BACnet and Modbus retrofit compatibility adds engineering overhead for specifying consultants in commercial automation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tubular Motors Market |
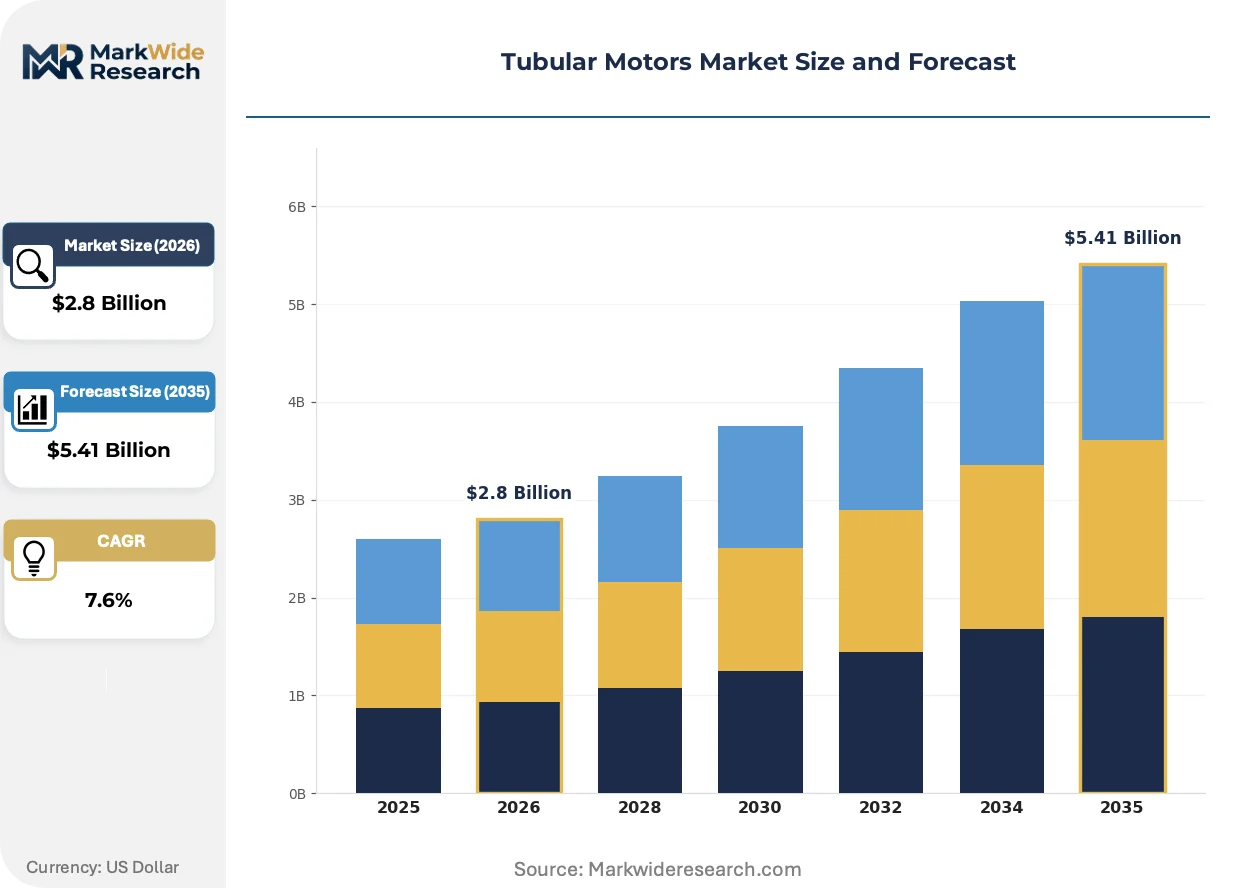
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Motors, High Torque Motors, Smart Motors, Low Noise Motors Installation Type: Internal Installation, External Installation, Integrated Installation, Modular Installation Application: Window Blinds, Roller Shutters, Industrial Applications, Home Automation Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Somfy Group, Nice S.p.A., Ningbo Dooya Electromechanical, Elero GmbH, Lutron Electronics, Hunter Douglas, Zhejiang Walter Mech Electrical, Jiecang Linear Motion, FAAC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tubular Motors Market Evolving Landscape
Electronics miniaturization and connectivity standardization are compressing the traditional three-tier motor architecture into two dominant configurations, eliminating mid-market positioning and forcing specialization at extremes.
Integrated motor-drive electronics is collapsing the distinction between standalone tubular motors and externally controlled systems. Residential smart home installers are specifying factory-integrated Wi-Fi modules at accelerating rates. This compression eliminates the historical upcharge for aftermarket control retrofits and forces motor OEMs to absorb RF engineering costs into base unit economics.
REACH substance restrictions from ECHA are tightening cadmium and lead content limits in motor housings and terminal blocks. Manufacturers serving European channels are accelerating aluminum housing adoption to preempt compliance deadlines. The industrial roller shutter segment is absorbing the highest cost impact due to structural load requirements that previously favored zinc-coated steel construction.
Specification consultants are consolidating vendor relationships around full-stack shading system providers rather than component motor suppliers. Commercial real estate developers in China's Yangtze River Delta are bundling motor, fabric, and control procurement into single-source contracts. This consolidation marginalizes standalone motor manufacturers without integrated channel partnerships or certified installer networks.
Tubular Motors Market Segmentation
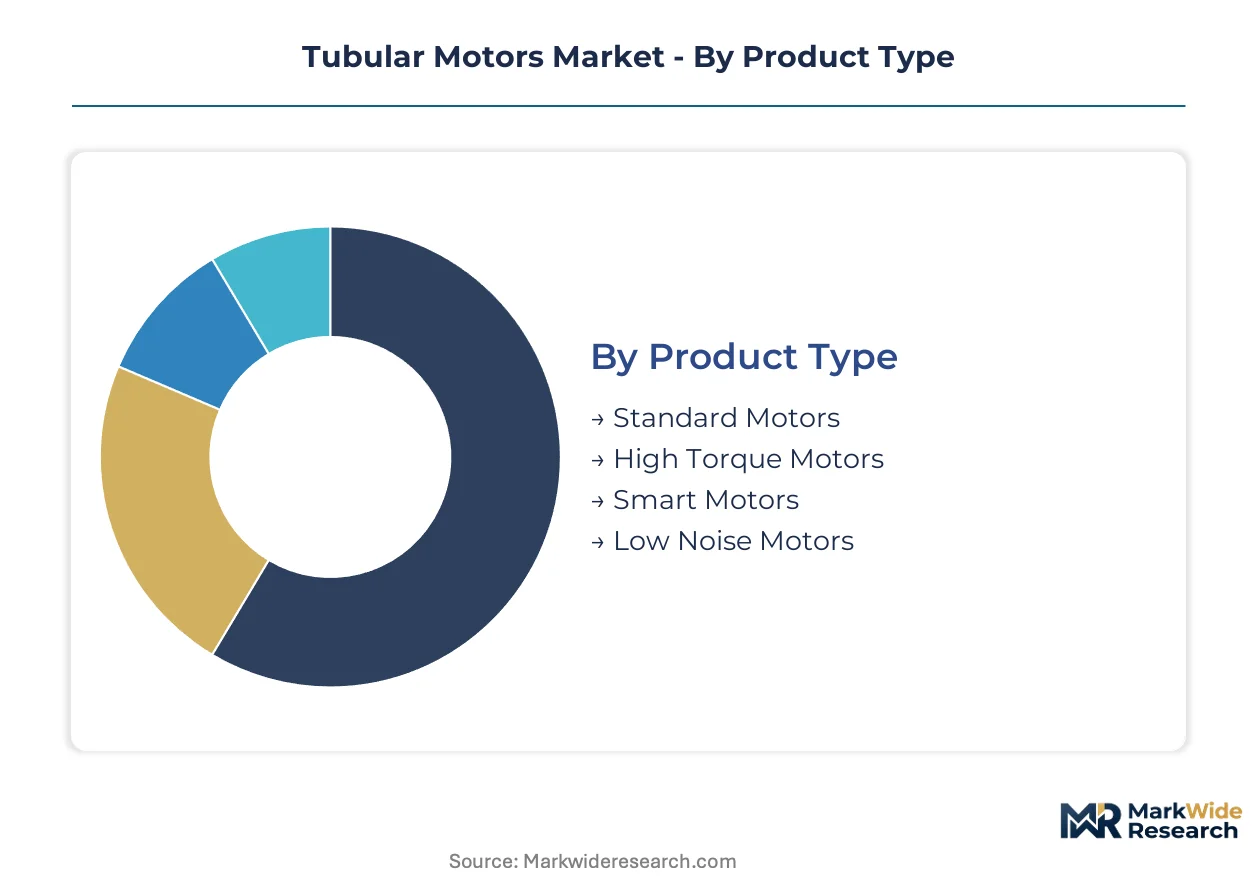
Tubular motor segmentation reflects divergent performance requirements across residential comfort, commercial security, and industrial automation channels. Specification consultants select motor configurations based on torque demands, noise constraints, and building management system compatibility rather than unit cost alone.
Product Type:
The use-case spectrum spans basic mechanical actuation to intelligent, connected drive systems with embedded position feedback and cloud integration capabilities.
- Standard Motors:Brushed AC induction architecture delivers 10-50 Nm torque for residential roller blinds and basic shutter applications. Southern European installers in Spain and Italy continue specifying these units for cost-sensitive retrofit projects despite Ecodesign efficiency mandates phasing out single-speed variants.
- Smart Motors:Factory-integrated Wi-Fi and Zigbee modules enable direct smartphone control and building automation integration without external controllers. Demand concentrates in Germany's industrial automation corridor where commercial real estate portfolios are accelerating replacement of legacy 230V AC systems with connected variants.
- High Torque Motors:Planetary gear reductions output 150-300 Nm for warehouse doors and heavy industrial shutters.
- Low Noise Motors:Helical gearing systems maintain sub-35 dB thresholds for patient room shading in healthcare construction.
The dominant share belongs to Standard Motors, while Smart Motors is closing the gap fastest.
Installation Type:
Mounting configuration directly determines service access, aesthetic integration, and compatibility with existing roller tube diameters across retrofit and new construction channels.
- Internal Installation:Motors insert directly into hollow roller tubes of 35mm, 45mm, or 58mm diameter, concealing all mechanical components within the shading element. This approach dominates residential window blind retrofits in France and Germany where exposed motor housings conflict with interior design specifications.
- Integrated Installation:Motor and control electronics ship as pre-wired assemblies from the factory, eliminating field splicing and reducing commissioning time for commercial automation contractors. China's Yangtze River Delta developers are bundling these configurations into single-source shading system contracts.
- External Installation:Surface-mounted motors attach to bracket systems outside the roller tube for oversized industrial applications.
- Modular Installation:Separable motor and gearhead units allow field torque reconfiguration without full replacement.
Internal Installation commands the largest volume position, though Integrated Installation is expanding most quickly through commercial specification channels.
Application:
End-use segmentation tracks divergent duty cycles, environmental exposure, and control sophistication requirements across building types.
- Roller Shutters:Security-focused applications demand high cycle durability and manual override capability for power failure scenarios. Germany's industrial automation corridor and China's smart building clusters anchor specification demand for these motors in commercial and residential security installations.
- Industrial Applications:High-cycle warehouse doors and material handling conveyance require continuous duty ratings and position feedback for automated logistics integration.
- Window Blinds:Residential and commercial shading systems prioritize compact diameter and quiet operation over torque output.
- Home Automation:Whole-building control integration drives demand for protocol-compatible motors with scene programming capability.
Roller Shutters retains the dominant application share, while Home Automation is gaining share fastest through smart building retrofit cycles.
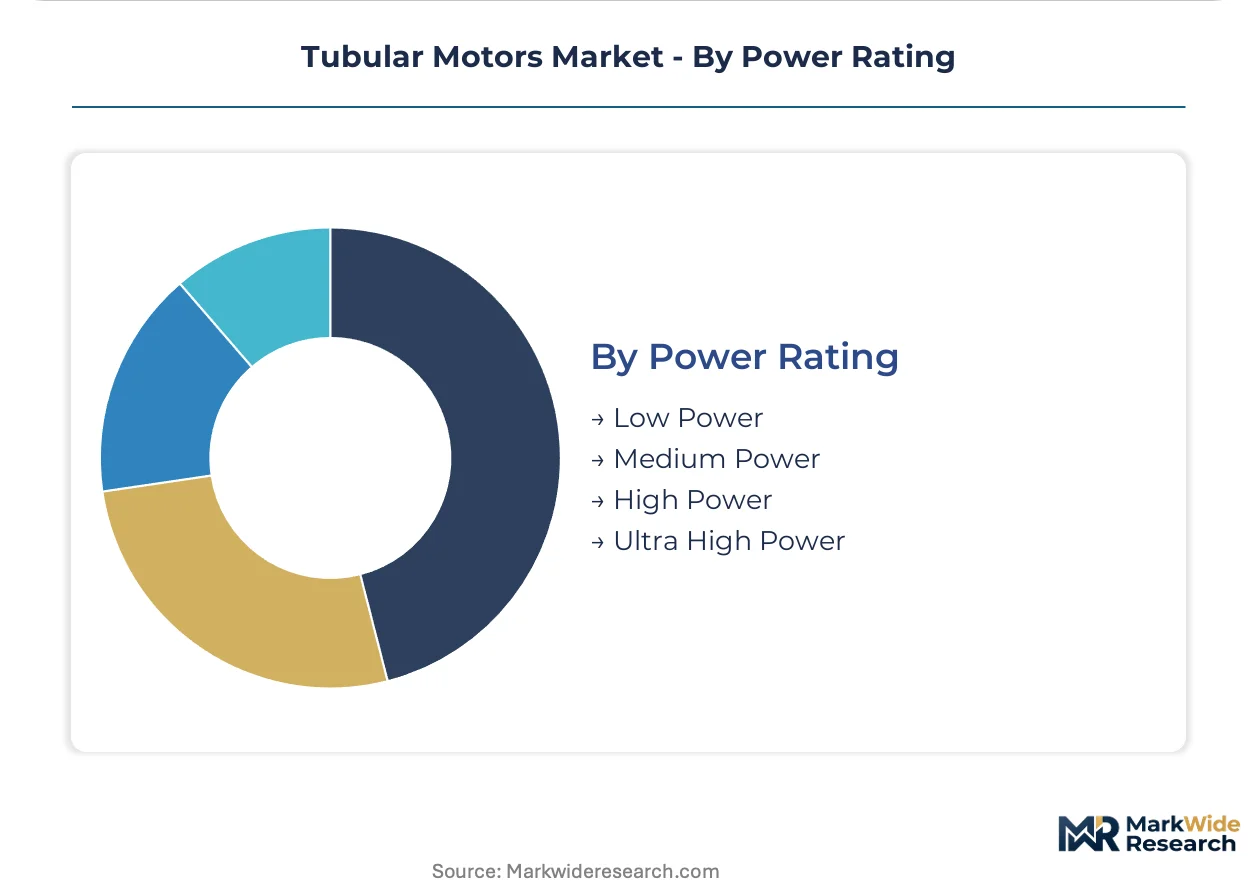
Power Rating:
Electrical input classification aligns motor thermal capacity with expected duty cycles and load profiles across residential through heavy industrial use cases.
- Medium Power:100-200W rated units balance torque output and thermal management for commercial roller shutters and mid-size awnings. India's Tier-1 metro developments under CEA building automation guidelines are specifying these motors for commercial structure mandates.
- High Power:200-400W continuous duty ratings serve industrial warehouse doors and high-cycle security barriers where load requirements exceed residential specifications.
- Low Power:Sub-100W units address residential window blinds with intermittent duty cycles.
- Ultra High Power:Specialized 400W+ configurations target heavy industrial material handling and oversized architectural shading systems.
Medium Power occupies the central volume position, while High Power is climbing the fastest through industrial automation corridor expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German motor exports flow primarily into France, Benelux, and Central European retrofit markets, while Chinese manufacturers supply volume tiers across Southeast Asia and the Middle East through direct OEM relationships.
Germany
Baden-Württemberg's precision gearhead fabricators and Bavaria's industrial automation clusters drive specification demand for Zigbee-enabled motors in commercial real estate portfolios. The EU Machinery Directive and Ecodesign framework enforce minimum efficiency standards that phase out single-speed AC induction variants. Stuttgart's industrial corridor anchors replacement cycles for legacy 230V systems in warehouse and logistics facilities.
China
Zhejiang province scales NdFeB magnet production for brushless DC stator assemblies while the Yangtze River Delta bundles motor, fabric, and control procurement into single-source contracts. SAMR-administered GB standards and CCC certification mandate electromagnetic compatibility and thermal protection for domestic sales. Ningbo's manufacturing base reduces cost premiums for high-torque tubular drives through captive magnet supply.
United States
Residential smart home installers specify factory-integrated Wi-Fi modules at accelerating rates across California and Texas metro markets. FCC Part 15 regulations govern radio certification for Zigbee and Thread protocol implementations. The Pacific Northwest's commercial construction pipeline absorbs medium-power motors for automated shading in LEED-certified office developments.
India
Tier-1 metro developments in Maharashtra and Karnataka specify Wi-Fi-integrated tubular motors under CEA building automation guidelines for commercial structures. BIS certification requirements and state-level smart city mandates create specification channels for medium-power units in hospitality and healthcare construction. Mumbai's real estate developers bundle motor procurement into integrated facade system contracts.
France
Residential window blind retrofits in Île-de-France and Auvergne-Rhône-Alpes favor internal installation configurations where exposed motor housings conflict with interior design specifications. ANSM and CNIL oversight intersects with CE marking requirements for connected motor deployments in healthcare facilities. Lyon's construction sector pulls low-noise helical gearing systems for hospital and hotel specifications.
Tubular Motors Market Competitive Landscape
On the supply side, the industry is consolidating around full-stack shading system providers rather than component motor suppliers, compressing margins for standalone manufacturers without integrated channel partnerships. Two strategic archetypes dominate: European specialists leveraging integrated smart control ecosystems to sustain pricing power, and Chinese scale manufacturers anchoring volume production through captive rare-earth magnet supply. Competitive moves concentrate on backward integration into magnet sourcing and RF engineering capability acquisition.
Among European specialists, Somfy Group and Elero GmbH exemplify the premium-tier positioning built around low-noise gearing and protocol integration. Ningbo Dooya Electromechanical occupies the scale-driven archetype, representing Zhejiang province's manufacturing concentration. These three anchors illustrate the bifurcation between specification-led and cost-led competitive vectors.
| Leading Market Players |
|---|
| Somfy Group |
| Nice S.p.A. |
| Ningbo Dooya Electromechanical |
| Elero GmbH |
| Lutron Electronics |
| Hunter Douglas |
| Zhejiang Walter Mech Electrical |
| Jiecang Linear Motion |
| FAAC Group |
| Others |
Value Network & Pricing Analysis
The Hamburg-Ningbo container corridor channels rare-earth magnet shipments and precision gearhead components, its freight cost volatility amplifying margin compression for brushless DC assemblers while reinforcing price stratification between European specification-grade motors and Chinese volume-tier units. Downstream procurement consolidation among Germany's commercial real estate developers and Yangtze River Delta facade contractors concentrates buyer leverage, forcing motor OEMs to absorb RF engineering and certification costs into base unit economics.
Pricing Analysis
Next-generation smart motor architectures with factory-integrated Wi-Fi modules command substantial premiums over legacy brushed AC induction units, while mid-tier positioning erodes as electronics miniaturization collapses the traditional three-tier structure. Three-tier pricing structure across premium, standard, and economy levels stratifies by connectivity protocol certification and noise performance grade, with CE-marked Zigbee-enabled variants from Baden-Württemberg specialists sustaining margin buffers against Zhejiang volume competition. Cost compression in standard AC tiers intensifies because Southern European installers continue specifying phased-out single-speed variants despite Ecodesign mandates. Residential retrofit contractors in Spain and Italy exhibit highest price sensitivity, while German commercial automation integrators prioritize protocol interoperability over unit cost.
Supply Chain Analysis
Chinese export controls on rare-earth processing technology limit NdFeB magnet flows to European stator assemblers, constraining brushless DC production scaling outside Zhejiang province. Manufacturing gravity centers on China's Ningbo magnet corridor, Germany's Baden-Württemberg gearhead precision cluster, and Italy's Emilia-Romagna motor winding facilities, with each node feeding distinct specification tiers. Raw material dependencies span neodymium-iron-boron permanent magnets, precision-machined steel planetary gear housings, and copper magnet wire for stator windings. Single-source vulnerability concentrates in planetary gearhead manufacturing, where Baden-Württemberg and Ningbo suppliers dominate precision-machined steel housing production. Distribution runs through full-stack shading system providers rather than component motor channels, compressing standalone manufacturer access to commercial specification pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement teams at Germany's commercial real estate developers and China's Yangtze River Delta facade contractors, fragmenting the vendor base as standalone motor manufacturers lose specification access without integrated channel partnerships.
For Market Incumbents: Insulate specification relationships by acquiring certified installer networks and RF engineering capabilities, countering the threat of full-stack shading system providers marginalizing component suppliers. Backward integration into captive NdFeB magnet sourcing through Zhejiang province partnerships reduces exposure to Chinese export quota volatility. Prioritize Ecodesign compliance certification investment to capture replacement cycles phasing out single-speed AC variants from Southern European retrofit channels.
For New Entrants and Emerging Players: India's Tier-1 metro developments under CEA building automation guidelines represent the most penetrable white-space target, with Mumbai and Bangalore real estate developers bundling motor procurement into integrated facade contracts. Low-noise helical gearing systems for healthcare construction in France and Germany offer specification entry points against established European specialists. Target acquisition of regional RF certification capabilities to bypass redundant Thread and Matter radio compliance cycles that extend product launch timelines.
For Investors and Strategic Acquirers: Brushless DC motor specialists with captive magnet supply and protocol integration capabilities represent the priority acquisition archetype for long-term positioning across the smart building automation horizon. Monitor EU Machinery Directive enforcement intensity and Ecodesign phase-out timelines for single-speed AC variants as the critical inflection signal for replacement cycle acceleration. Material shifts in Chinese rare-earth export licensing or REACH substance restriction expansion would require updated calibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Sourcing | Captive NdFeB supply from Zhejiang province insulates brushless DC assemblers against export quota volatility. |
| RF Engineering Capability Acquisition | In-house Wi-Fi and Zigbee module development eliminates redundant certification cycles for Thread protocol compliance. |
| Certified Installer Network Expansion | Direct channel control counters full-stack shading system providers consolidating commercial specification access. |
| Low-Noise Helical Gearing R&D | Sub-35 dB thresholds capture healthcare and hospitality construction specifications in France and Germany. |
| CE Ecodesign Compliance Investment | Preemptive efficiency certification captures replacement cycles phasing out single-speed AC induction variants. |
Research Methodology
Initial hypotheses were tested against primary input from commercial automation contractors, shading system specification consultants, motor OEM procurement directors, and rare-earth magnet supply specialists, then refined through secondary validation across EU Ecodesign directive filings, SAMR GB standard publications, customs trade data for NdFeB magnet flows, and SEC filings from publicly traded building automation firms. Bottom-up unit economics modeling triangulated against top-down addressable market sizing across residential, commercial, and industrial installation channels.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product architecture, installation configuration, end-use application, power rating tier, and regional regulatory cluster. CAGRs derived from installed base replacement cycle analysis, smart building retrofit penetration curves, and industrial automation corridor expansion rates. Forecast inputs incorporated EU Machinery Directive enforcement trajectories and Chinese dual carbon policy impacts on magnet production capacity.
Practitioners should monitor rare-earth export licensing adjustments, REACH substance restriction expansion, and Matter protocol adoption velocity for early signals of forecast deviation. Forecasts reflect assumptions on Ecodesign phase-out compliance timelines and smart home interoperability standard consolidation. Material shifts in Chinese environmental enforcement intensity or EU building renovation wave funding allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
Movable Scaffolding System Market
Electro-Mech Systems
Automatic Slack Adjusters Market
Electro-Mech Systems
Rodless Cylinders Market
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Elevator Door-Motor Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Wiring Duct Market
Electro-Mech Systems
HVAC Relay Market
Electro-Mech Systems
Rigid Metal Electrical Conduit Market