
 Electric Overhead Travelling (EOT) Cranes Market | 2026-2036
Electric Overhead Travelling (EOT) Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Overhead Travelling (EOT) Cranes Market Foresight
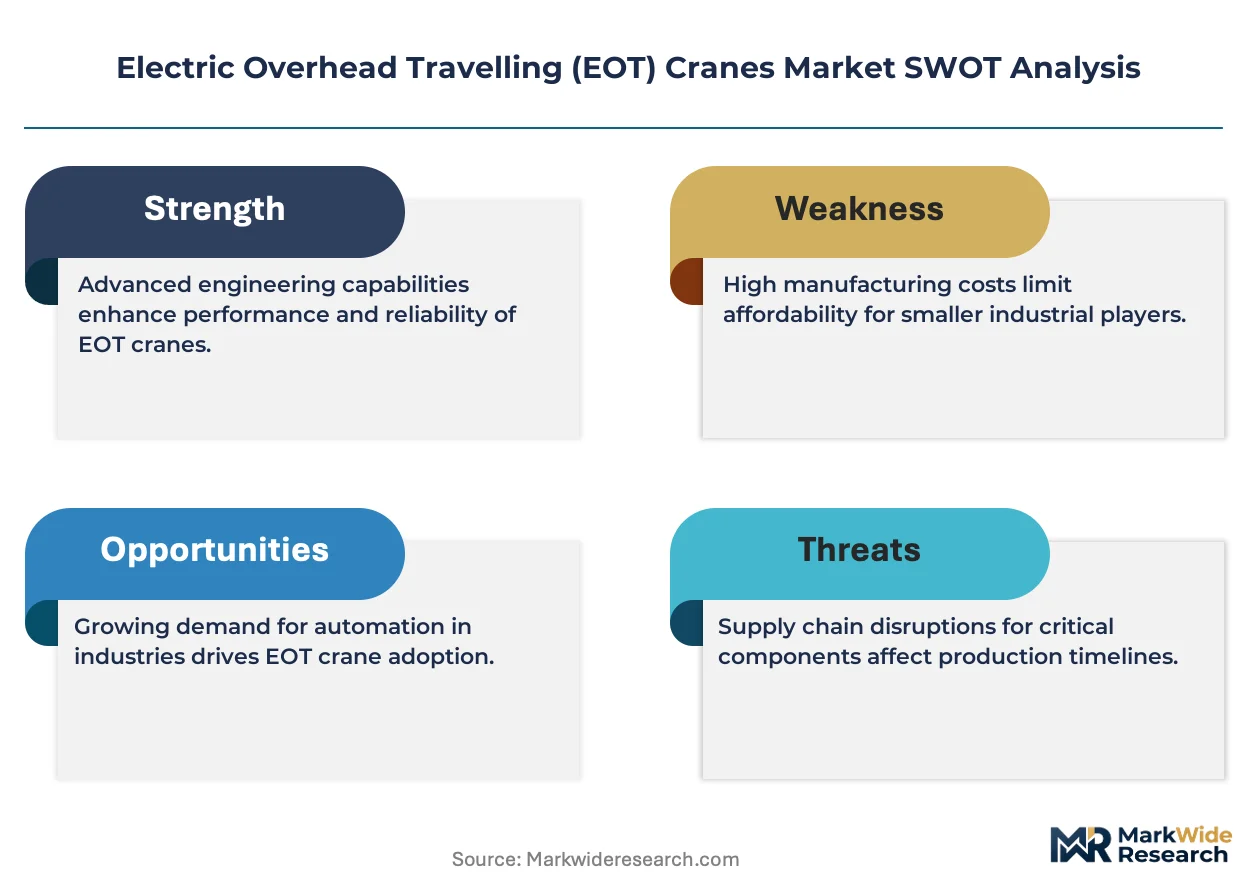
Premium EOT crane specifications is decoupling from commodity single-girder offerings as buyers prioritize load monitoring precision and predictive maintenance integration. Konecranes leverages its digital service platform to anchor long-term aftermarket revenue across Nordic and North American installed bases. Weihua Cranes dominates cost-optimized double-girder production for Asian infrastructure and energy projects. Demag Cranes differentiates through engineered solutions for process-critical automotive and aerospace handling applications.
Electric Overhead Travelling cranes are motorized overhead lifting systems comprising bridge girders, trolley hoists, and end trucks that traverse fixed runway beams, typically rated from one ton to over five hundred tons capacity and powered by conductor bars or festoon cable systems. These systems serve as the primary material handling backbone in manufacturing halls, shipyards, power plants, and logistics terminals where floor space optimization and vertical lift precision prove essential. Single girder configurations occupy the high-volume entry tier for light-to-medium duty cycles, while double girder architectures command the performance-critical segment where span length and hook height drive specification. Radio remote control technology is displacing wired pendants in new installations as operators demand mobility and reduced fatigue exposure. The above-twenty-ton capacity bracket concentrates margin pools tied to custom engineering and extended service contracts.
OSHA crane standards, EU machinery directives with CE marking requirements, and ISO 4309 inspection protocols collectively shape product certification burdens and replacement timelines across major demand centers. OSHA's updated crane operator certification mandates compel fleet owners to retire non-compliant legacy equipment or undertake costly control retrofits. Buyers must weigh total lifecycle ownership against upfront capital outlay as regulatory compliance layers compound with automation integration requirements.
Market Dynamics
Steel mills and heavy fabrication facilities are systematically retiring aging crane infrastructure, forcing capital allocation toward certified double-girder systems with integrated load monitoring and predictive maintenance architectures.
Growth Catalysts
- OSHA crane operator certification mandates:Fleet owners must replace non-compliant legacy equipment or undertake costly control retrofits, accelerating replacement cycles across US manufacturing bases.
- Process-critical automotive handling:Aerospace and automotive assembly lines demand engineered solutions with precision positioning for just-in-time component delivery.
- Ruhr industrial cluster renewal:Germany's aging crane infrastructure requires systematic replacement, concentrating visible demand in Europe's largest steel and heavy fabrication corridor.
Market Restraints
- Copper and steel input volatility:Conductor bar systems and bridge girder fabrication face margin compression from raw material price swings in commodity metals markets.
- EU machinery directive compliance burden:CE marking requirements and ISO 4309 inspection protocols extend certification timelines and inflate engineering overhead for smaller fleet operators.
- Alternative material handling systems:Automated guided vehicles and gantry robots threaten displacement in light-duty logistics terminals below ten-ton capacity thresholds.
Strategic Opportunities
- Radio remote control convergence:Wireless operator mobility technology combines with fatigue-reduction protocols to open retrofit markets in existing pendant-controlled installations.
- Aftermarket service unbundling:Digital service platforms enable predictive maintenance revenue streams independent of original equipment sales across Nordic installed bases.
- Above-twenty-ton custom engineering:Margin pools concentrate in extended service contracts and application-specific lifting configurations for power plant and shipyard verticals.
Industry Challenges
- Certified technician scarcity:Crane inspector and control systems specialist pipelines lag fleet expansion rates, extending commissioning timelines for complex double-girder installations.
- Legacy control integration friction:Retrofitting analog-era runway systems with modern safety monitoring architectures demands custom electrical engineering and extended downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Overhead Travelling (EOT) Cranes Market |
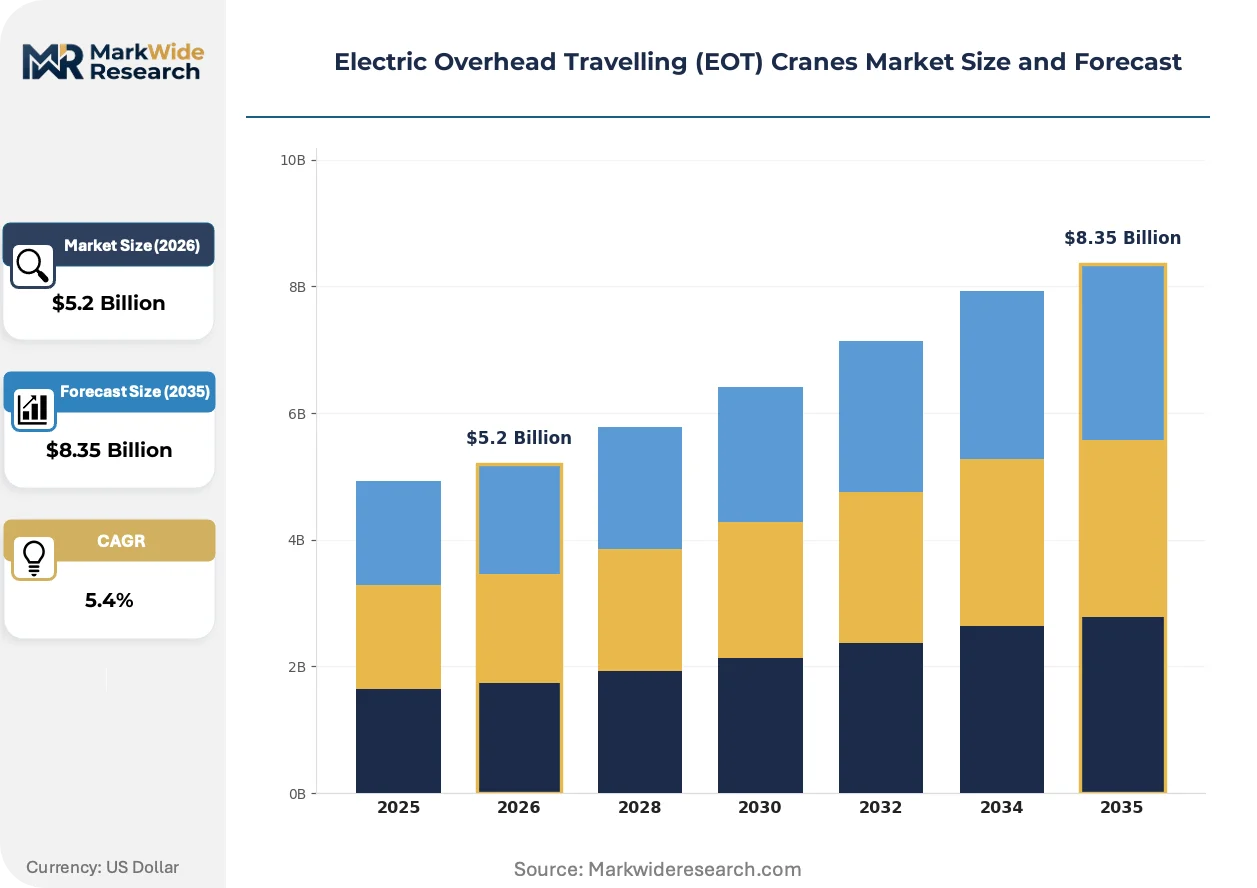
| Market Size in 2026 | $5.2 Billion |
| Market Size in 2035 | $8.35 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Girder, Double Girder, Gantry, Jib End User: Manufacturing, Construction, Transportation, Warehousing Control Technology: Radio Remote Control, Wired Control, Automatic, Manual Capacity: 1-5 Tons, 5-10 Tons, 10-20 Tons, Above 20 Tons |
| Companies Covered | Columbus McKinnon, Weihua Cranes, Konecranes, Gorbel, Kito, Demag Cranes, HY Crane, DeShazo Crane Company, ABUS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Overhead Travelling (EOT) Cranes Market Shifts & Advancements
Digital service platforms and wireless control architectures are compressing traditional equipment-sales cycles toward lifecycle revenue models. Buyers now prioritize predictive maintenance integration over upfront capital efficiency.
Radio remote control technology is rewriting operator mobility standards across new crane installations. Steel mills and heavy fabrication facilities are adopting wireless pendants to reduce fatigue exposure and improve sightline positioning. This shift is compressing demand for traditional wired pendant systems and forcing control-system suppliers to reorient toward RF engineering competencies.
EU machinery directives with CE marking requirements are tightening safety monitoring mandates for overhead lifting equipment. Manufacturers must integrate redundant limit switches and load moment indicators to satisfy conformity assessment procedures. Process-critical automotive and aerospace handling applications face the steepest compliance burden, driving specification toward engineered rather than commodity solutions.
Service contract structures are unbundling from equipment procurement across Nordic and North American installed bases. Fleet owners now separate predictive maintenance subscriptions from capital purchases, pressuring traditional crane suppliers to build digital monitoring platforms. This behavioral shift is most visible in Germany's Ruhr industrial cluster, where aging infrastructure demands systematic replacement combined with long-term aftermarket anchoring strategies.
Electric Overhead Travelling (EOT) Cranes Market Segmentation
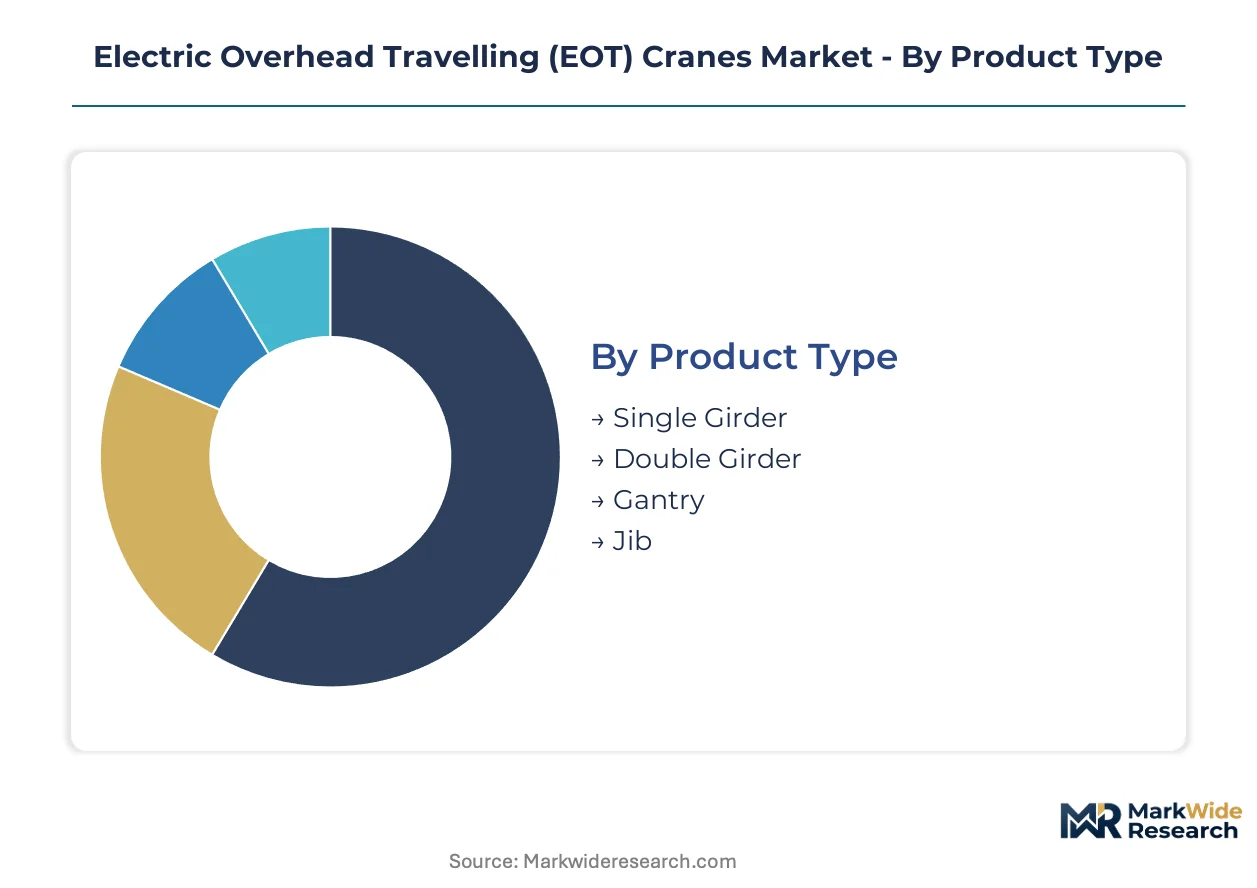
EOT crane specification divides sharply between commodity procurement for light-duty cycles and engineered systems for process-critical handling. Buyers segment procurement by duty classification, control sophistication, and capacity thresholds that determine regulatory compliance burdens and lifecycle ownership economics.
Product Type:
Buyers select girder architecture based on span requirements, hook height demands, and duty cycle intensity rather than upfront capital constraints alone.
- Single Girder:Bridge crane configuration utilizing one main beam with trolley hoist underslung, rated typically to twenty tons and optimized for moderate span lengths. Manufacturing halls in Germany's Ruhr cluster specify these for standard material flow where ceiling height permits reduced hook paths and OSHA compliance costs stay manageable.
- Double Girder:Twin-beam architecture supporting trolley hoist between girders, enabling greater spans and lift heights with concentrated wheel loads distributed across runway beams. Steel mills and heavy fabrication facilities across US Great Lakes manufacturing corridors demand these for billet and slab handling where integrated load monitoring and predictive maintenance architectures justify premium engineering.
- Gantry:Crane structure with legs riding on ground-level rails rather than elevated runways, eliminating building column dependence. Port terminals and outdoor fabrication yards specify these where existing structures cannot support overhead loading.
- Jib:Cantilevered boom rotating on fixed column or wall mounting, providing localized lift coverage without runway infrastructure. Machine shops and maintenance bays deploy these for repetitive workstation feeding below five-ton thresholds.
Volume sits with Single Girder configurations; growth tilts toward Double Girder systems.
End User:
Application environment dictates safety system redundancy, control interface specifications, and service contract structures more than purchase price.
- Manufacturing:Automotive assembly lines and aerospace component fabrication demand precision positioning with just-in-time delivery protocols. EU machinery directive CE marking requirements and ISO 4309 inspection protocols concentrate compliance investment here, pushing specification toward engineered solutions with redundant limit switches.
- Construction:Heavy civil infrastructure projects and commercial building erection require mobility and rapid deployment across uneven terrain. German construction firms increasingly specify radio remote control systems to reduce operator fatigue exposure during extended lift cycles.
- Transportation:Rail yards, intermodal terminals, and ship-to-shore logistics operations prioritize throughput velocity over precision positioning. These applications favor gantry configurations with festoon cable power delivery.
- Warehousing:Distribution centers and fulfillment operations below ten-ton capacity thresholds face displacement pressure from automated guided vehicles and gantry robots, compressing traditional crane demand in light-duty logistics terminals.
Procurement value concentrates in Manufacturing; Construction exhibits the steepest expansion trajectory.
Control Technology:
Operator mobility requirements and fatigue reduction protocols are rewriting control interface specifications across new installations and retrofit markets.
- Radio Remote Control:Wireless pendant systems enabling untethered operator positioning with improved sightlines and reduced physical strain. Steel mills across Nordic industrial bases adopt these to satisfy emerging ergonomic protocols while avoiding costly control retrofits on legacy installations.
- Wired Control:Traditional pendant stations connected via festoon cable or coiled cord, delivering reliable signal integrity in high-interference environments. These retain share in explosive atmosphere applications where RF spark risk exceeds regulatory tolerance.
- Automatic:Programmable logic controller-driven operation with minimal human intervention, integrated into manufacturing execution systems for repetitive cycle handling. Process-critical automotive lines specify these for component sequencing precision.
- Manual:Direct mechanical or pushbutton control requiring operator presence at fixed stations, now confined to maintenance access and emergency override functions in modern installations.
Installed base remains Wired; Radio Remote Control gains share fastest.
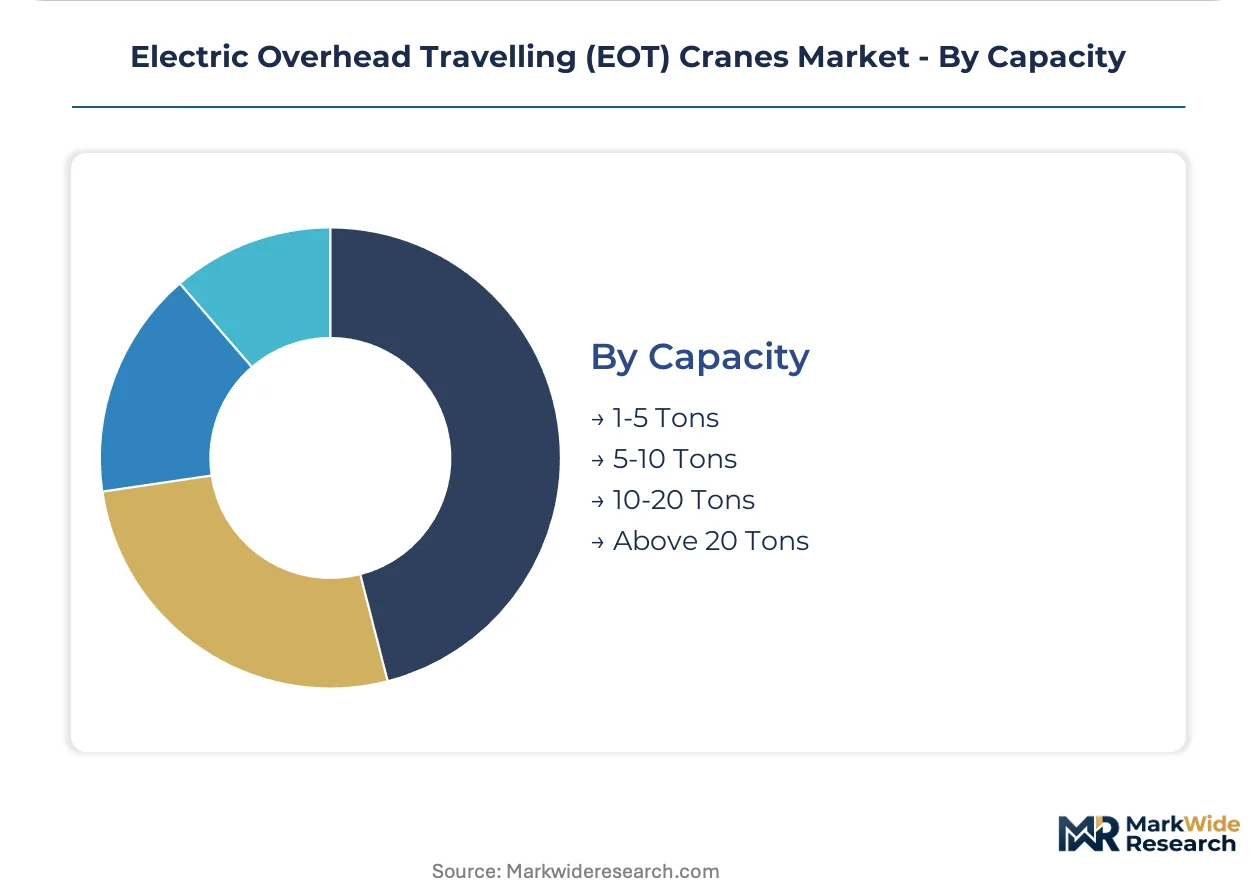
Capacity:
Lift rating thresholds determine regulatory classification, inspector certification requirements, and margin pool accessibility for suppliers.
- 1-5 Tons:Light-duty category serving machine shops, maintenance facilities, and small fabrication operations. These face maximum displacement threat from alternative material handling systems in warehousing applications.
- 5-10 Tons:Medium-duty segment capturing general manufacturing and assembly operations. Standardized configurations dominate here with limited customization opportunity.
- 10-20 Tons:Heavy-duty threshold triggering enhanced OSHA crane operator certification mandates and more frequent inspection intervals. US fleet owners must retire non-compliant legacy equipment or undertake costly control retrofits in this bracket.
- Above 20 Tons:Process-critical capacity tier where custom engineering and extended service contracts concentrate margin pools. Power plant turbine handling and shipyard drydock operations in Germany's Ruhr industrial corridor specify these with predictive maintenance platform integration.
Unit shipments peak at 5-10 Tons; value creation shifts Above 20 Tons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial cluster anchors replacement demand as aging crane infrastructure forces systematic capital allocation toward certified double-girder systems with integrated safety monitoring.
United States
OSHA crane operator certification mandates compel fleet owners to retire non-compliant legacy equipment or undertake costly control retrofits across Great Lakes manufacturing corridors. The updated OSHA standards accelerate replacement cycles for above-ten-ton capacity installations. Steel mills in Indiana and Ohio deploy these systems for billet and slab handling with predictive maintenance integration.
Germany
EU machinery directives with CE marking requirements tighten safety monitoring mandates for overhead lifting equipment in automotive and aerospace assembly lines. REACH and RoHS compliance layers compound engineering overhead for smaller fleet operators. The Ruhr industrial cluster concentrates visible demand where systematic replacement combines with long-term aftermarket anchoring strategies.
China
Infrastructure and energy projects drive cost-optimized double-girder procurement for steel production and heavy fabrication facilities. GB standards and MIIT industrial equipment regulations shape certification timelines for domestic and export-bound manufacturers. Yangtze River Delta shipyards specify above-twenty-ton custom engineering for drydock operations.
Japan
Automotive component fabrication demands precision positioning systems for just-in-time delivery protocols. METI industrial productivity guidelines and JIS standards govern equipment specification for process-critical handling applications. Kansai region automotive suppliers integrate redundant limit switches to satisfy conformity assessment procedures.
India
Steel capacity expansion and port modernization projects stimulate demand for gantry configurations in outdoor fabrication yards. BIS certification requirements and CEA electrical safety standards extend equipment approval timelines. Gujarat and Maharashtra industrial corridors specify radio remote control systems to reduce operator fatigue exposure during extended lift cycles.
Electric Overhead Travelling (EOT) Cranes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across engineering sophistication and service contract depth. The vendor base organizes into three tiers: digital platform operators capturing aftermarket revenue, cost-optimized fabricators serving infrastructure scale, and engineered solution specialists for process-critical applications. Consolidation pressure concentrates among mid-scale regional suppliers lacking predictive maintenance capabilities. Dominant competitive moves include M&A to acquire digital service platforms and backward integration into control system manufacturing.
Within the digital platform tier, Konecranes and Demag Cranes occupy positions emphasizing lifecycle revenue over equipment sales. Among Asian fabricators, Weihua Cranes exemplifies cost-optimized production scale for infrastructure and energy verticals. Columbus McKinnon represents North American aftermarket service depth across installed base maintenance contracts.
| Leading Market Players |
|---|
| Columbus McKinnon |
| Weihua Cranes |
| Konecranes |
| Gorbel |
| Kito |
| Demag Cranes |
| HY Crane |
| DeShazo Crane Company |
| ABUS |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators across Germany's Ruhr corridor and China's Yangtze River Delta anchor supply-side discipline, translating captive production control into pricing power for engineered double-girder systems while compressing margins for commodity single-girder procurement.
Pricing Analysis
Value-based pricing tied to equipment uptime guarantees and predictive maintenance outcomes anchors premium tiers for above-twenty-ton installations serving power plant and shipyard verticals. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked engineered solutions with redundant limit switches from basic OSHA-compliant configurations and cost-optimized Asian imports. Cost compression in the single-girder tier is intensifying because automated guided vehicles threaten displacement below ten-ton thresholds. Warehousing and light logistics buyers exhibit highest price sensitivity, while steel mills and heavy fabrication facilities prioritize lifecycle ownership economics over upfront capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with Chinese specialty steel producers supplying high-grade bridge girder material for European and North American crane fabricators. Manufacturing concentration spans China, Germany, and the United States for structural steel fabrication, with conductor bar systems and festoon cable assemblies drawing from South Korean and Japanese electrical component suppliers. Tariff exposure on steel inputs and copper conductor materials threatens margin stability for cost-optimized producers. Distribution runs through direct OEM sales for engineered solutions and regional distributor networks for standardized configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around digital service platform capabilities, with predictive maintenance integration forcing smaller regional fabricators toward acquisition or exit.
For Market Incumbents: Deploy backward integration into control system manufacturing to capture radio remote control and safety monitoring value pools currently held by specialist electronics suppliers. Acquire distressed regional service providers in Germany's Ruhr cluster to anchor long-term aftermarket contracts as fleet owners unbundle procurement from maintenance subscriptions. Automated guided vehicle encroachment below ten-ton thresholds demands defensive positioning through precision-engineered solutions for automotive and aerospace handling applications. For New Entrants and Emerging Players: Begin with gantry configuration specialization for Indian port modernization and steel capacity expansion projects, where outdoor fabrication yard demand outpaces incumbent service coverage. Target radio remote control retrofit markets in existing pendant-controlled installations across Nordic industrial bases, leveraging wireless operator mobility as a wedge against entrenched wired control suppliers. Pursue partnership routes with established electrical component distributors to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European fabricators lacking predictive maintenance capabilities but holding CE-marked product portfolios and installed base relationships in automotive assembly corridors. Long-term viability hinges on digital platform migration within a multi-year modernization window as regulatory compliance layers compound with automation requirements. Monitor OSHA enforcement intensity and EU machinery directive amendment timelines as signals for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Captures recurring revenue streams independent of equipment sales across Nordic installed bases. |
| Radio Remote Control Retrofit Programs | Opens replacement demand in existing pendant-controlled installations across steel mill verticals. |
| CE Marking and OSHA Certification Investment | Creates regulatory moat against non-compliant imports in process-critical automotive handling. |
| Backward Integration into Control Systems | Secures margin pools from safety monitoring and wireless operator mobility technologies. |
| Aftermarket Service Unbundling | Aligns with buyer behavioral shift separating predictive maintenance subscriptions from capital purchases. |
Research Methodology
Document review covered SEC filings from Columbus McKinnon and Konecranes, EU machinery directive conformity assessment databases, and OSHA crane standard enforcement records, complemented by interviews with maintenance directors at steel mills, plant engineers in automotive assembly facilities, aftermarket service heads at regional distributors, and procurement teams at heavy fabrication OEMs. Secondary validation drew from customs trade data for steel and copper inputs, German mechanical engineering association reports, and ISO 4309 inspection protocol documentation. Bottom-up capacity and demand estimates were triangulated against top-down macroeconomic indicators for industrial capital expenditure.
Unit shipment and value projections across the analysis window were derived from duty cycle intensity segmentation, girder architecture adoption curves, and control technology replacement rates. The analytical framework modeled capacity thresholds, end-use verticals, and regional regulatory clusters as primary segmentation dimensions. CAGRs were computed from historical replacement cycle data and forward-looking compliance mandate timelines, with steel production capacity expansion and port modernization project pipelines serving as industry-specific demand inputs.
Underlying measurement precision varies by segment; above-twenty-ton custom engineering and predictive maintenance platform adoption carry tighter precision than commodity single-girder procurement facing displacement uncertainty. Forecasts reflect assumptions regarding OSHA enforcement consistency, EU machinery directive implementation timelines, and copper and steel input price stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Rigid Metal Electrical Conduit Market
Electro-Mech Systems
HVAC Relay Market
Electro-Mech Systems
Rodless Cylinders Market
Electro-Mech Systems
Elevator Door-Motor Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Movable Scaffolding System Market
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
Tubular Motors Market
Electro-Mech Systems
Wiring Duct Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Automatic Slack Adjusters Market