
 HVAC Control System Market | 2026-2036
HVAC Control System Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Control System Market Intelligence
The adoption of open communication protocols like BACnet is decoupling control system hardware from proprietary software ecosystems, altering product economics. This shift allows for greater interoperability between components from different manufacturers. Johnson Controls leverages its extensive portfolio to offer integrated building management solutions. Siemens AG specializes in advanced automation controllers for complex commercial and industrial facilities.
An HVAC control system is an automated network of electronic devices designed to regulate heating, ventilation, and air conditioning equipment. These systems utilize components like sensors and controllers operating on PID control logic to maintain specific temperature and air quality parameters. While controllers and sensors form the core product segments, applications within data centers and commercial buildings represent the largest end-use categories. The need for precise thermal management in high-density computing environments drives specification for advanced control modules.
Regulatory frameworks directly shape system requirements and market access. In the United States, EPA rules on refrigerant management influence control strategies, while the EU's Energy Performance of Buildings Directive mandates efficiency. These standards compel manufacturers to integrate features that monitor and optimize energy consumption. The critical decision for system integrators and facility managers is how to balance the benefits of open, connected platforms against emerging cybersecurity vulnerabilities.
Market Dynamics
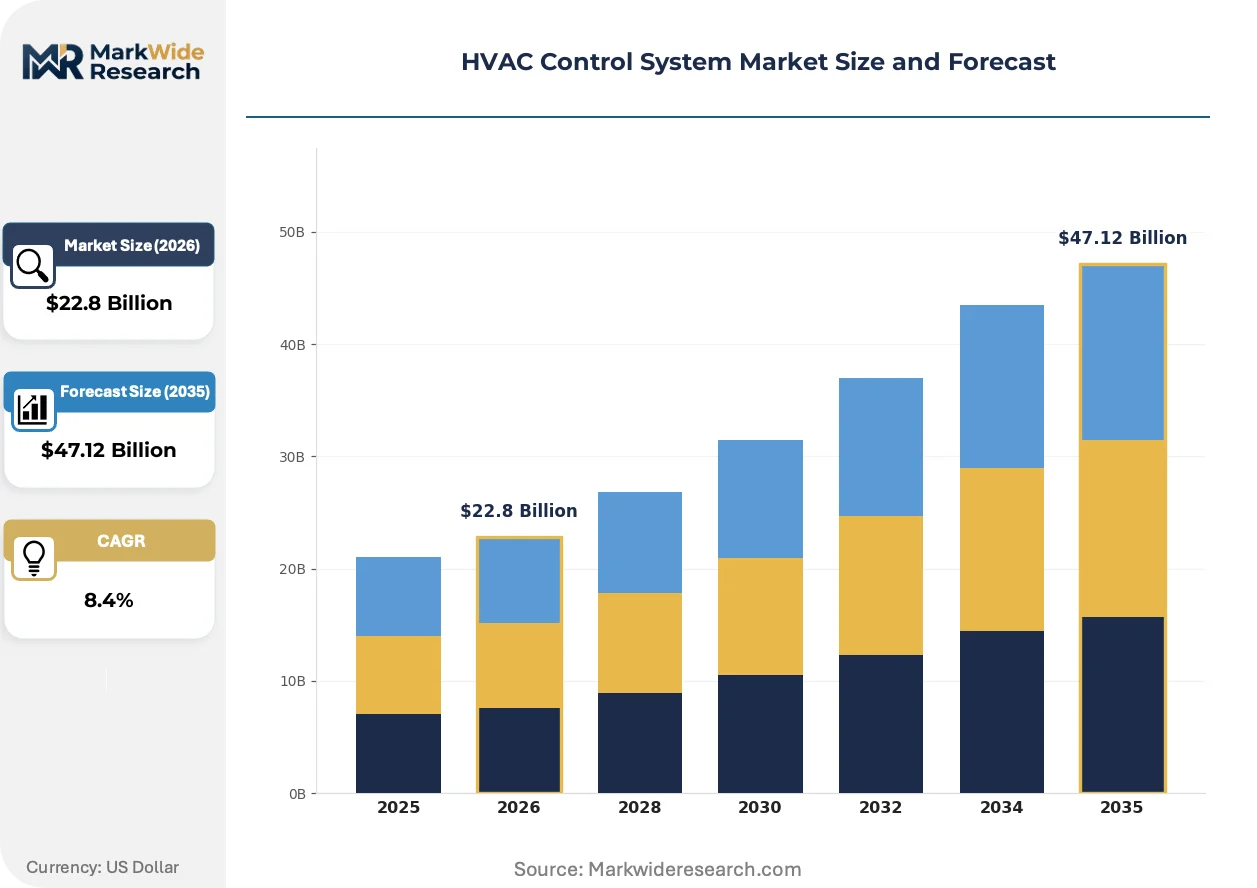
The central dynamic shaping the HVAC control system market is the dual pressure from stringent energy efficiency regulations and the thermal management requirements of high-density digital infrastructure. This forces a move from simple thermostatic control to networked, data-driven building automation.
Growth Catalysts
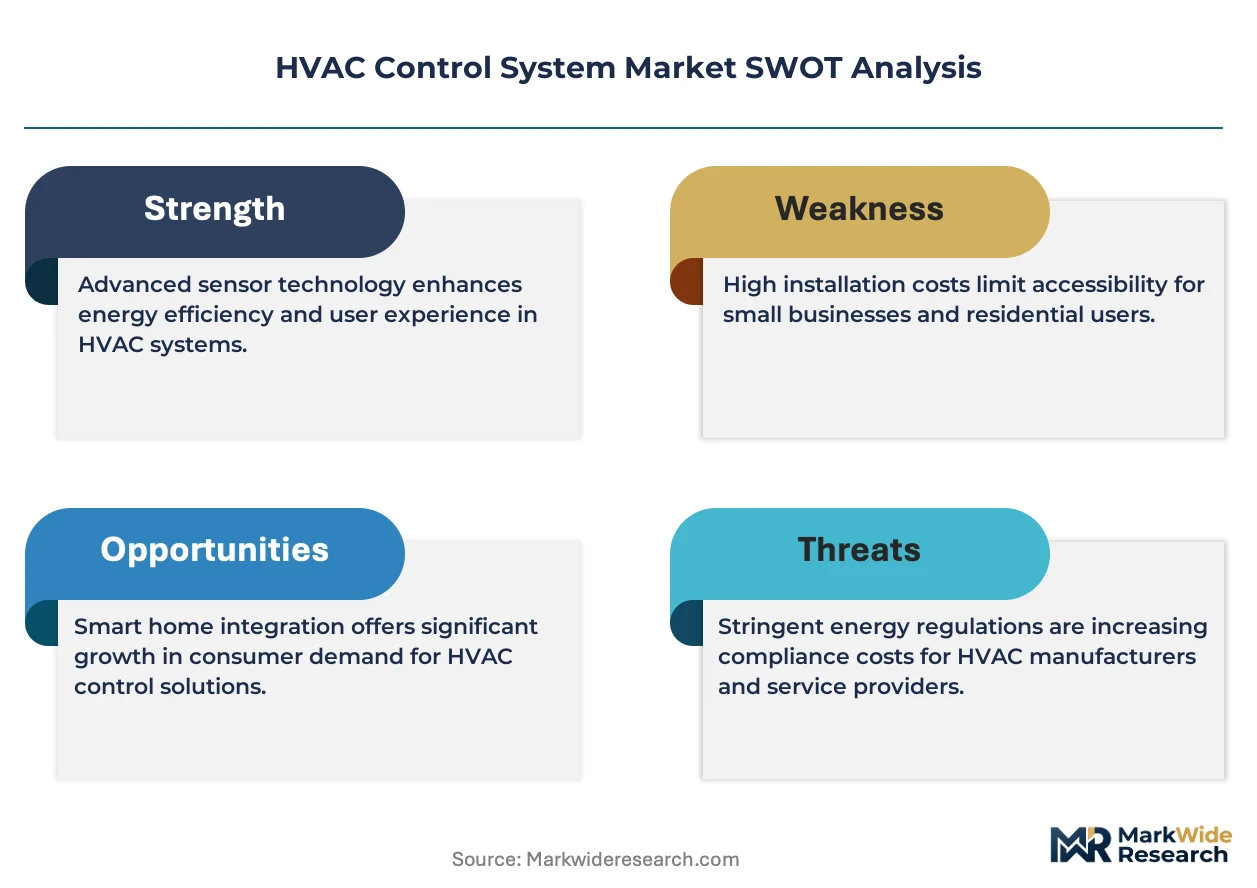
- Data Center Expansion:The proliferation of data centers for cloud computing and AI workloads requires precise, redundant thermal management, driving specifications for advanced, networked HVAC control systems to ensure uptime and equipment longevity.
- Regulatory Mandates:The European Union's F-Gas Regulation and Energy Performance of Buildings Directive (EPBD) compel building owners to adopt control systems capable of monitoring refrigerant leakage and optimizing energy consumption.
- Open Protocol Adoption:The increasing use of open communication protocols like BACnet and Modbus reduces vendor lock-in, lowering total cost of ownership and encouraging retrofits with interoperable components from multiple manufacturers.
Market Restraints
- High Initial Cost:The significant upfront investment required for sophisticated building automation systems, compared to basic standalone controls, acts as a major deterrent for small-to-medium enterprise and residential applications.
- Cybersecurity Risks:As HVAC controls become connected to enterprise IT networks and the internet, they introduce new attack vectors, with potential vulnerabilities deterring adoption in security-sensitive sectors like government and finance.
- Legacy System Integration:The complexity and cost associated with integrating modern digital control systems with older, analog-based HVAC equipment in existing buildings can be prohibitive for many retrofit projects.
Strategic Opportunities
- Predictive Maintenance Services:Leveraging AI and machine learning algorithms on sensor data allows for the development of predictive maintenance services, shifting revenue from one-time hardware sales to recurring software and service contracts.
- Indoor Agriculture:The controlled environment agriculture sector requires precise, multi-zone management of temperature, humidity, and ventilation, opening a new application vertical for customized HVAC control solutions.
- Building Decarbonization Incentives:Government programs, such as incentives within the US Inflation Reduction Act (IRA), provide financial tailwinds for retrofitting commercial buildings with high-efficiency, smart HVAC controls to reduce carbon emissions.
Industry Challenges
- Skilled Labor Gap:A persistent shortage of technicians proficient in both mechanical HVAC systems and modern IT networking complicates the installation, commissioning, and maintenance of complex, integrated control platforms.
- Interoperability Complexity:Despite open protocols, ensuring seamless data exchange and functionality between devices from different manufacturers remains a significant technical challenge for system integrators, often requiring custom programming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Control System Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostats, Sensors, Actuators, Controllers, Communication Modules Technology: PID Control, Fuzzy Logic Control, Neural Network Control, On-Off Control, Model Predictive Control Application: Commercial Buildings, Data Centers, Educational Institutions, Sports Facilities, Government Establishments End User: Facility Management Firms, HVAC Contractors, Energy Service Companies, Property Developers |
| Companies Covered | Johnson Controls, Honeywell International Inc., Daikin Industries Ltd., Carrier Corporation, Schneider Electric, Siemens AG, Emerson Electric Co., Trane Technologies plc, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Control System Market Strategic Shifts & Innovations
The evolution from isolated, mechanical thermostats to intelligent, networked building automation defines the market's trajectory. This transformation is driven by the convergence of operational technology with IT infrastructure, creating new capabilities for energy management and occupant comfort while introducing new system-level complexities.
Edge computing places data processing and decision-making capabilities directly within devices like sensors and controllers. Facility managers in data centers and critical industrial environments are adopting this to ensure low-latency responses to thermal events. Edge processing is integrating local control logic with cloud-based analytics, enabling more resilient and autonomous building operations that are not wholly dependent on constant network connectivity.
In the United States, the EPA's regulations under the AIM Act are phasing down the production and consumption of high-GWP hydrofluorocarbons (HFCs). This directly influences control system design, promoting technologies that can manage new, lower-GWP refrigerants which may have different operating characteristics. The sensor and controller segment is most affected, with a need for components certified for use with alternative refrigerants like A2L-class fluids.
A notable behavioral shift is the move by large commercial real estate portfolio owners to centralize building operations through remote command centers. This model supplants on-site facility management for routine monitoring and adjustments, relying on standardized, network-accessible HVAC control platforms. This trend is most visible in North America and Europe, where large property management firms seek to gain operational efficiencies across geographically dispersed assets.
HVAC Control System Market Segmentation
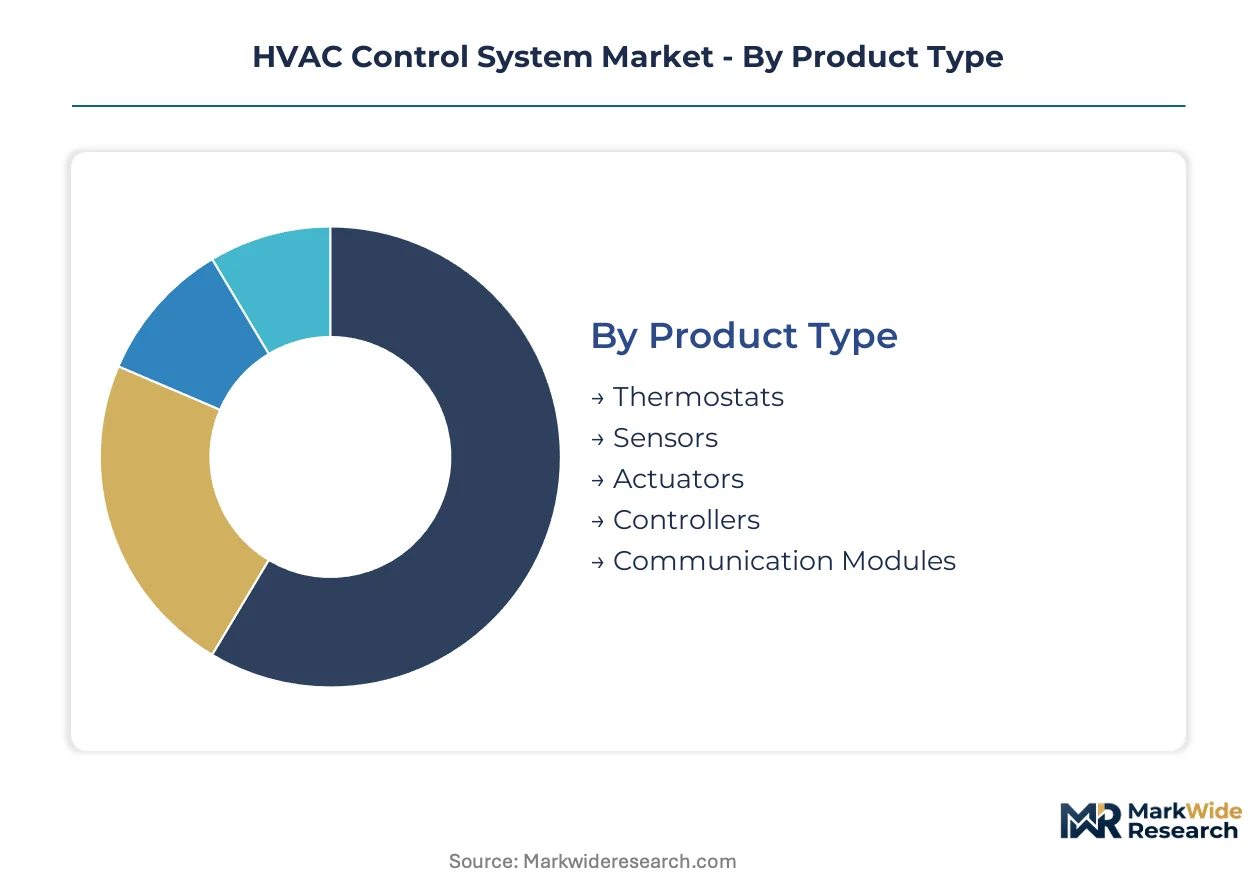
Understanding the HVAC control system market through segmentation reveals distinct demand patterns and technological preferences across various user groups. This granular view helps identify specific requirements for product development and strategic market penetration. Each segment reflects unique operational challenges and investment priorities for maintaining optimal environmental conditions.
Product Type:
Buyers in the product type category are differentiated by the specific function and integration complexity required for their HVAC systems.
- Thermostats:These devices provide basic temperature sensing and control, typically used for direct regulation of heating and cooling equipment in individual zones. Demand for smart thermostats is increasing in residential and small commercial settings due to energy saving features.
- Sensors:Sensors detect environmental parameters like temperature, humidity, CO2, and occupancy, providing critical data inputs for control algorithms. Precise thermal management in high-density computing environments drives specification for advanced sensor arrays.
- Actuators:Actuators are mechanical devices that translate control signals into physical actions, such as opening or closing dampers and valves to regulate airflow or fluid flow. Their robust design ensures reliable operation in demanding industrial applications.
- Controllers:Controllers are the central processing units that receive data from sensors, execute control logic, and send commands to actuators and other system components. Advanced controllers are essential for complex building automation systems in commercial and industrial facilities.
- Communication Modules:These modules facilitate data exchange between various HVAC components and central building management systems, often utilizing protocols like BACnet or Modbus. Interoperability is a key driver for communication module adoption in integrated building solutions.
Volume sits with Thermostats; growth tilts toward Communication Modules.
Technology:
The choice of technology often depends on the required precision and responsiveness of the control system for a given application.
- PID Control:Proportional-Integral-Derivative (PID) control is a widely adopted feedback loop mechanism used to maintain a desired setpoint by continuously calculating and adjusting output based on error. This robust control method is fundamental in ensuring stable temperature and pressure regulation across commercial HVAC systems.
- Fuzzy Logic Control:This control method handles imprecise or vague input data, mimicking human-like decision-making for complex systems where exact mathematical models are difficult to establish. Fuzzy logic finds application in optimizing energy consumption in variable and unpredictable environmental conditions.
- Neural Network Control:Neural network control systems use artificial intelligence to learn and adapt to dynamic environmental conditions, predicting optimal control strategies based on historical data. This advanced technology is gaining traction for predictive maintenance and energy optimization in smart buildings.
- On-Off Control:On-Off control is the simplest form of regulation, where a device is either fully on or fully off based on whether a setpoint is met. This basic technology remains prevalent in cost-sensitive, less critical applications.
- Model Predictive Control:Model Predictive Control (MPC) uses a dynamic model of the system to predict future behavior and optimize control actions over a prediction horizon. MPC is critical for energy efficiency in large-scale commercial and industrial facilities, balancing comfort with operational costs.
The market prioritizes PID Control for stability, while Neural Network Control represents an area of rapid advancement.
Application:
End-users in the application segment are distinguished by their operational needs and the critical nature of thermal management.
- Commercial Buildings:This segment includes offices, retail spaces, and hotels, where HVAC controls manage occupant comfort, indoor air quality, and energy efficiency across diverse zones. Regulatory mandates for energy performance drive significant demand in this category.
- Data Centers:Data centers require highly precise, redundant thermal management systems to prevent equipment overheating and ensure continuous operation. Demand for advanced control modules in this segment is directly tied to the proliferation of cloud computing and AI workloads.
- Educational Institutions:Schools and universities utilize HVAC control systems to create comfortable learning environments and manage energy consumption across large, multi-building campuses. Modernization projects frequently integrate smart controls for centralized management.
- Sports Facilities:Arenas, gymnasiums, and aquatic centers demand specialized HVAC controls to manage large volumes of air, humidity, and temperature for both athletes and spectators. These facilities often require rapid environmental adjustments based on events.
- Government Establishments:Government buildings, including administrative offices and public service centers, implement HVAC controls for energy efficiency, occupant comfort, and compliance with public sector sustainability goals. Security considerations often influence system design.
Demand is highest in Commercial Buildings, with Data Centers showing the most dynamic expansion.
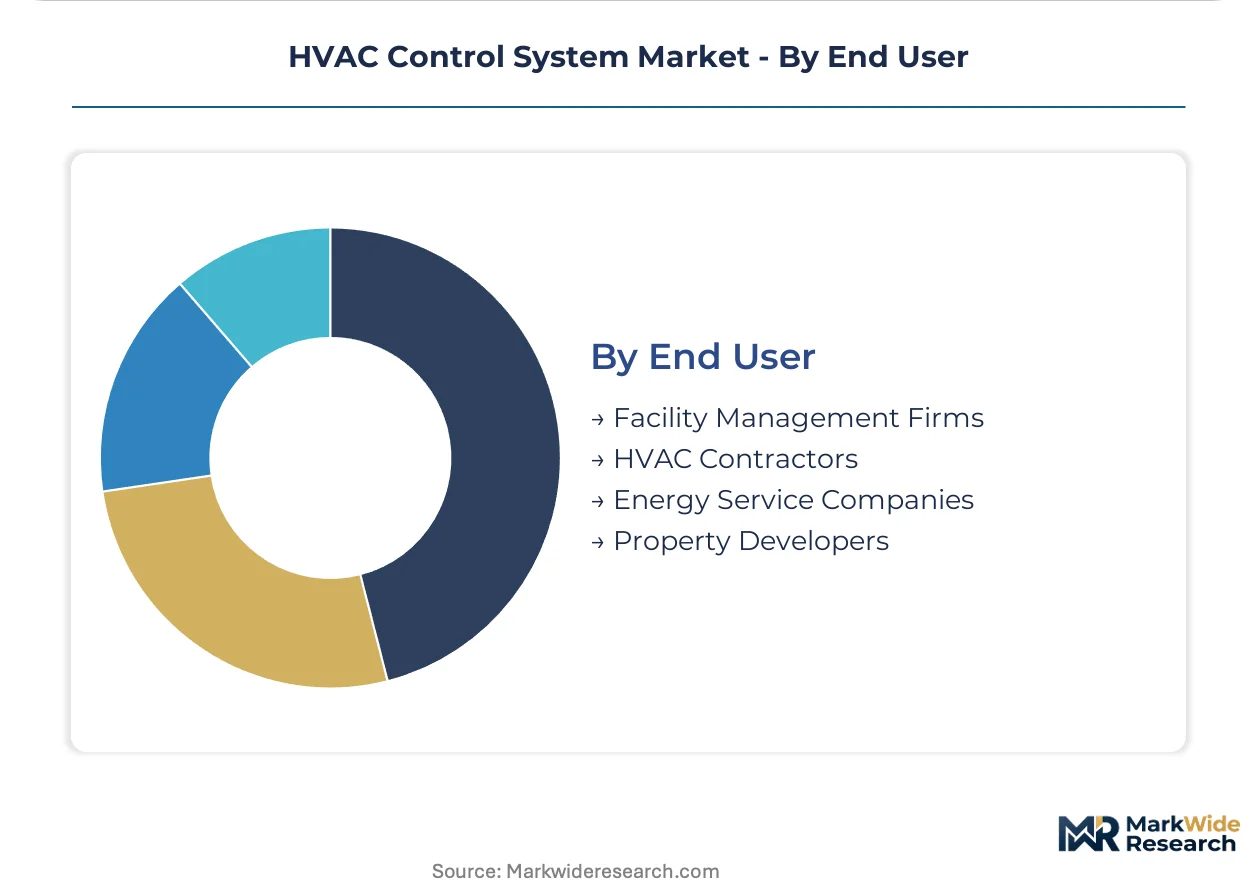
End User:
The maturity and operational scale of an end-user organization significantly influence the type of HVAC control solutions they procure.
- Facility Management Firms:These firms manage the operation and maintenance of commercial, industrial, and institutional buildings, requiring integrated HVAC control systems for centralized monitoring and efficiency. They often prioritize interoperability and remote management capabilities.
- HVAC Contractors:Contractors specialize in the installation, repair, and maintenance of HVAC systems, acting as primary implementers of control solutions for various building types. Their expertise is crucial for custom installations and system integration.
- Energy Service Companies:ESCOs provide comprehensive energy management solutions, including the design and implementation of advanced HVAC controls to optimize energy consumption and reduce operational costs. They focus on performance-based contracts and long-term savings.
- Property Developers:Developers integrate HVAC control systems into new construction projects, influencing system design and technology choices from the initial planning stages. Their decisions impact the long-term energy efficiency and operational costs of new buildings.
Established firms are served by Facility Management Firms, but Energy Service Companies are increasingly influential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta economic zone is concentrating significant demand for advanced HVAC control systems due to extensive development. This region drives new construction and retrofitting initiatives for commercial and industrial facilities. Precise thermal management needs from high-density computing environments are accelerating market expansion.
China
Demand for advanced HVAC controls in China stems from extensive new construction and retrofitting projects across commercial and industrial sectors. The national dual carbon goals mandate energy-efficient building systems and drive smart building adoption. Major smart city initiatives in Shenzhen are integrating intelligent HVAC solutions into new developments, supporting data center expansion.
United States
The United States market sees strong demand from data center expansion and commercial building retrofits. The US Inflation Reduction Act (IRA) provides significant financial incentives for energy-efficient HVAC control upgrades. Technology hubs like Silicon Valley are driving innovation in predictive maintenance services and smart building integration.
Germany
Germany experiences demand for HVAC control systems due to stringent energy efficiency standards in commercial and industrial facilities. The EU's Energy Performance of Buildings Directive (EPBD) compels building owners to modernize existing infrastructure. Advanced automation controllers are widely adopted in Frankfurt's financial district for complex building management.
Japan
Japan's demand for HVAC control systems is influenced by an aging infrastructure and a focus on disaster resilience in critical facilities. METI promotes energy conservation through various building efficiency regulations and incentive programs. Tokyo's urban development projects frequently incorporate advanced controls for smart building ecosystems.
India
India's rapid urbanization and commercial real estate growth are fueling demand for sophisticated HVAC control solutions. The Bureau of Energy Efficiency (BEE) standards encourage the adoption of energy-efficient building technologies. Major IT and business process outsourcing (BPO) centers in Bengaluru require precise thermal management.
HVAC Control System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the HVAC control system market, reflecting diverse customer needs. The market exhibits a tiered structure, with established giants offering comprehensive solutions alongside niche players focusing on specific technologies or applications. Strategic archetypes include integrated building management providers, specialized controller manufacturers, and software-centric analytics firms. Portfolio diversification through technology acquisition and strategic partnerships to enhance interoperability are dominant competitive moves.
Within the integrated building management archetype, Johnson Controls and Siemens AG exemplify global players providing extensive HVAC control portfolios. Johnson Controls leverages its broad product ecosystem to offer end-to-end building solutions, encompassing hardware, software, and services. Siemens AG, a German-based conglomerate, anchors the market for advanced automation controllers in complex commercial and industrial facilities. Schneider Electric, a French multinational, also occupies a significant position, emphasizing energy management and digital transformation in its offerings, representing the trend towards comprehensive, networked control platforms.
| Leading Market Players |
|---|
| Johnson Controls |
| Honeywell International Inc. |
| Daikin Industries Ltd. |
| Carrier Corporation |
| Schneider Electric |
| Siemens AG |
| Emerson Electric Co. |
| Trane Technologies plc |
| Mitsubishi Electric Corporation |
| Others |
Cost & Logistics Intelligence
The EU's F-Gas Regulation mandates a phase-down of high-GWP refrigerants, gating access to qualified suppliers and commanding premium pricing for compliant HVAC control systems. This regulatory pressure shifts procurement towards advanced, lower-GWP compatible components.
Pricing Analysis
Short lead times for advanced HVAC control systems command a premium, while readily available components may see discounts for spot inventory. The dominant pricing model is project-based, often incorporating subscription-tiered software services for analytics. Price differentiation arises from the customization level required for complex facilities and bundled after-sales service. Pricing softness emerges in the basic thermostat segment due to component standardization; data centers show minimal price sensitivity.
Supply Chain Analysis
The US Inflation Reduction Act's domestic content mandates are reshaping sourcing for HVAC control system components, favoring localized production. Geographic supply concentration for core electronics and specialized sensors centers on China, Germany, and the United States. The industry relies on microcontrollers, sensors, and communication chips, creating single-source vulnerability. Distribution runs through direct sales channels for large facility managers and via HVAC contractors for smaller installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HVAC control system market is experiencing a vertical-integration race, with players actively pursuing downstream control over building management software and service contracts. This strategic imperative aims to capture recurring revenue streams beyond hardware sales.
For Market Incumbents:
To counter emerging cybersecurity vulnerabilities, market incumbents must prioritize robust system security protocols and invest in continuous R&D for AI/ML-driven threat detection. Portfolio diversification through technology acquisition enhances integrated building management solutions. Strategic partnerships with IT security firms are crucial for maintaining trust and market share. Johnson Controls leverages its broad ecosystem for end-to-end building solutions.
For New Entrants and Emerging Players:
AI-driven predictive maintenance software offers a technology-first wedge for new entrants into the HVAC control market. White-space opportunities exist in specialized sectors like indoor agriculture and smart city infrastructure. Retrofits in commercial buildings within India represent a penetrable segment due to rapid urbanization. A SaaS-based control platform model provides a low-barrier entry point, focusing on recurring revenue.
For Investors and Strategic Acquirers:
Successful large-scale deployment of edge computing in critical facilities is the leading indicator that the HVAC control market's long-term viability remains strong over the next 5-10 years. Acquisition targets should focus on specialized software firms with expertise in AI/ML for energy optimization or advanced sensor technology. Monitoring the adoption rate of open communication protocols like BACnet signals interoperability maturity. Investment in companies offering integrated solutions for data centers aligns with dynamic expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Predictive Maintenance | Reduces operational costs for facility managers and extends equipment longevity in commercial buildings. |
| Expand Open Protocol Integration | Enhances interoperability between different manufacturer components, lowering total cost of ownership for building owners. |
| Target Indoor Agriculture Solutions | Captures new application vertical requiring precise multi-zone environmental management for crop optimization. |
| Invest in Edge Computing Capabilities | Ensures low-latency responses to thermal events in data centers, improving system resilience and autonomy. |
| Form Cybersecurity Partnerships | Mitigates new attack vectors introduced by networked HVAC controls, securing critical infrastructure for government establishments. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this market analysis. Primary interviews with facility managers, HVAC contractors, energy service company executives, and control system engineers provided critical market insights. Secondary validation included EPA rules, EU F-Gas Regulation documents, company annual reports, and industry journals. A rigorous bottom-up and top-down triangulation approach reconciled discrepancies, ensuring data accuracy.
Data-stream reconciliation across multiple sources informed the analytical framework throughout the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market shifts. Key forecast inputs included data center expansion rates and smart building adoption trajectories across major economies.
Several conditions sit outside the modeled scope, including rapid geopolitical instability and unforeseen technological disruptions in control logic. Forecasts reflect assumptions regarding stable regulatory environments and sustained economic growth. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Tunnel and Metro Fans Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
Industrial Hood Ventilation Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
Marine HVAC Market
HVAC Systems
Spray Booth Ventilation System Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Regenerative Heat Exchanger Market
HVAC Systems
Commercial Kitchen Ventilation System Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
Gas Wall Hung Boilers Market