
 Wiring Duct Market | 2026-2036
Wiring Duct Market Size, Share, and Industry Trends Forecast 2026-2036
Wiring Duct Market Intelligence
Polycarbonate is hardening its position against PVC in premium wiring duct applications as temperature resistance and flame-retardant specifications tighten across industrial specifications. Schneider Electric leverages captive resin partnerships to stabilize input costs for slotted and non-slotted product lines. ABB anchors its European manufacturing footprint with localized compounding operations that reduce lead times for German automotive and machinery builders. HellermannTyton specializes in flexible duct configurations for robotics and motion-intensive factory layouts.
Wiring duct denotes an enclosed channel system, typically extruded from thermoplastic or formed from sheet metal, designed to organize, protect, and route electrical conductors and data cables within enclosures or along structural surfaces. Wall thickness, flammability rating (UL 94 V-0 or V-2), and finger-safe slot geometry determine suitability for control panels versus open-floor industrial runs. Slotted duct dominates panel-builder demand where frequent tap-offs and reconfiguration occur, while aluminum duct commands higher margins in heavy-industrial settings exposed to coolant oils and metal shavings. Flexible duct represents the fastest-growing material format as collaborative robot installations multiply across discrete manufacturing.
UL 94 flammability testing, IEC 61439 low-voltage switchgear standards, and OSHA electrical safety mandates collectively constrain material selection and channel geometry for North American suppliers. ECHA REACH restrictions on halogenated flame retardants are pushing European formulators toward phosphorus-based alternatives in polycarbonate grades. Stakeholders must monitor evolving MEE enforcement on plastic product recyclability in China, as export-oriented producers face dual compliance burdens across Atlantic and Pacific regulatory domains.
Market Dynamics
Hyperscale data center construction is compressing cable density tolerances and forcing specification upgrades across slotted duct product lines. This infrastructure buildout concentrates procurement power among a narrow tier of facility operators who demand UL 94 V-0 certification and halogen-free material traceability as baseline entry requirements.
Growth Catalysts
- EU Green Deal compliance deadlines:REACH and RoHS restrictions on halogenated flame retardants are redirecting European panel-builder procurement toward phosphorus-based polycarbonate formulations.
- Industrial automation density:Collaborative robot installations across German and Chinese automotive assembly lines are multiplying flexible duct deployment for motion-intensive cable routing.
- Server rack power loads:Data center operators in the United States are expanding cable management investments to support higher-density server deployments and liquid cooling infrastructure.
Market Restraints
- Resin supply concentration:Polycarbonate feedstock availability tightens around Asian petrochemical complexes, exposing European extruders to freight cost volatility and extended lead times.
- Aluminum alloy pricing:Heavy-industrial duct segments face margin compression from LME-linked input costs for 6063-T6 extrusion grades used in coolant-resistant channel systems.
- PVC substitution ceiling:Cost-sensitive construction verticals in developing markets retain halogenated PVC duct for non-critical runs, limiting polycarbonate penetration in price-driven tenders.
Strategic Opportunities
- Modular data center standardization:Prefabricated electrical house (E-house) suppliers in China require plug-and-play duct systems with integrated grounding and snap-fit covers.
- Phosphorus-based compounding advances:European formulators are capturing margin premiums by developing transparent polycarbonate grades that maintain UL 94 V-0 ratings without brominated additives.
- Renewable energy balance-of-plant:Solar inverter and battery storage OEMs in the United States specify wide-channel aluminum duct for DC cable segregation in outdoor installations.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous UL, IEC 61439, and GB standard testing stretches product launch cycles for suppliers serving export markets.
- Legacy panel retrofit compatibility:Existing control enclosure footprints constrain adoption of finger-safe slot geometries without complete busbar reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wiring Duct Market |
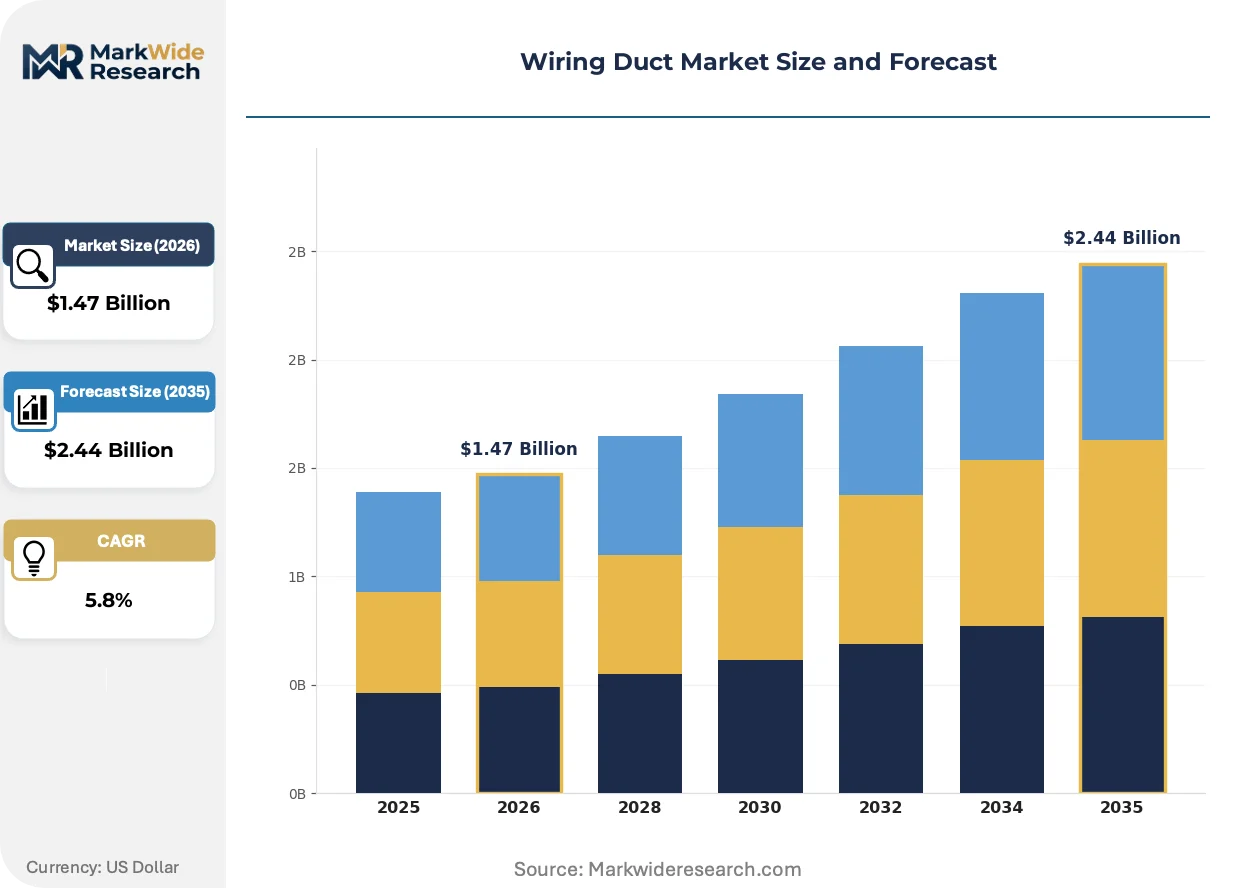
| Market Size in 2026 | $1.47 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slotted Duct, Non-Slotted Duct, Flexible Duct, Aluminum Duct, PVC Duct Material: Polycarbonate, PVC, ABS, Steel, Fiberglass Application: Telecommunications, Data Centers, Industrial Manufacturing, Commercial Infrastructure, Office Buildings End User: Telecom Operators, Data Facility Managers, Manufacturing Units, Corporate Facilities |
| Companies Covered | Schneider Electric, Legrand, ABB, Phoenix Contact, TE Connectivity, Panduit, Eaton, Atkore International, HellermannTyton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wiring Duct Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are rewriting formulation priorities across thermoplastic duct categories. Manufacturers now compete on traceability documentation and circularity credentials rather than purely dimensional tolerances.
Halogen-free polycarbonate compounds are expanding into premium wiring duct applications as temperature resistance specifications tighten across industrial machinery standards. German automotive OEMs and machinery builders specify these grades for control panels exposed to servo drive heat loads. The shift is compressing PVC's addressable market in safety-critical installations while elevating phosphorus-based flame retardants to default status.
REACH authorization requirements for halogenated flame retardants are forcing European compounders to requalify entire product portfolios ahead of sunset dates. Industrial consequence includes extended R&D cycles and reformulation costs passed through to panel-builder customers. German electrical enclosure manufacturers respond by consolidating supplier relationships with resin partners who guarantee compliant feedstock certificates.
Specification-driven procurement now dominates data center and automotive verticals, displacing price-first sourcing for cable management components. Tier-one facility operators in the United States require full material disclosure and recyclability roadmaps as mandatory bid elements. This behavioral shift concentrates contract awards among duct suppliers with in-house compounding capabilities and third-party sustainability verification.
Wiring Duct Market Segmentation
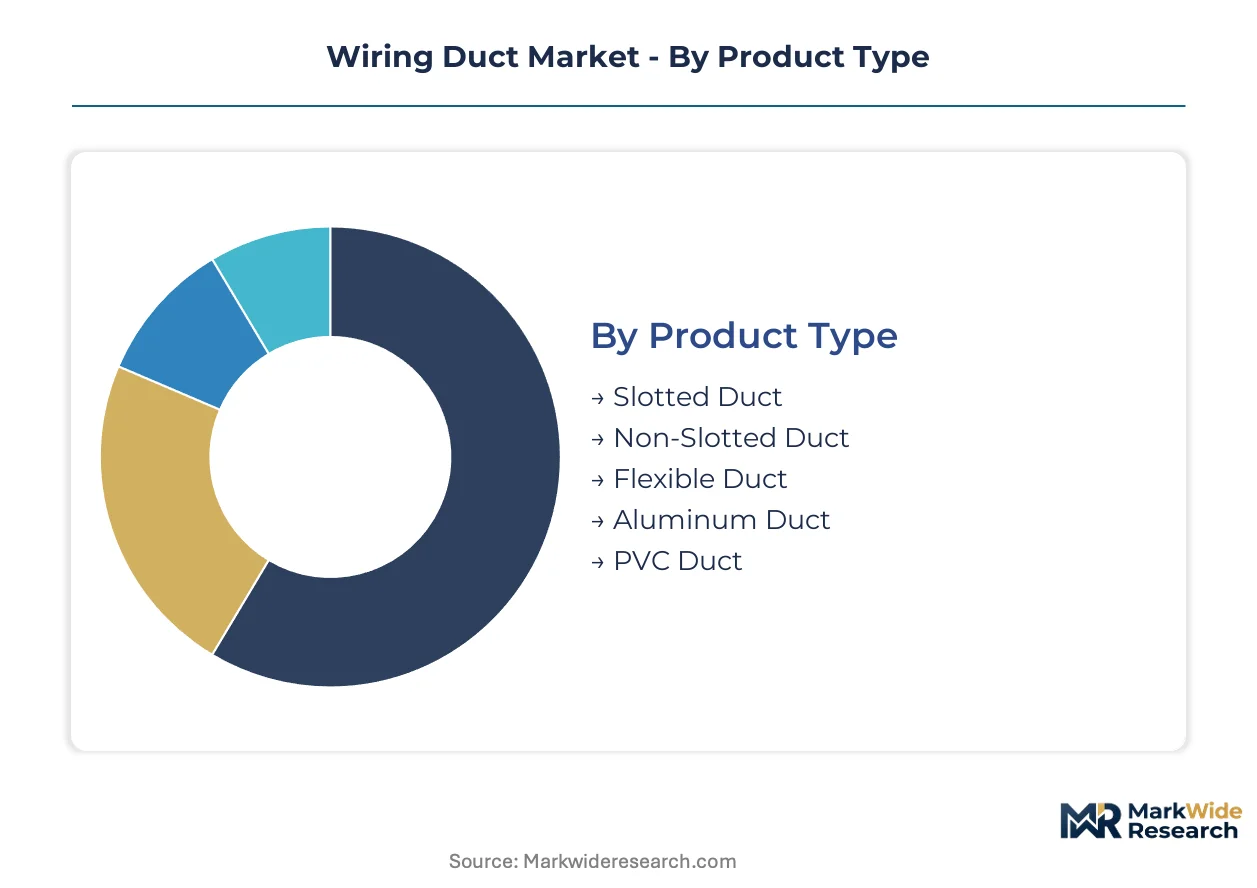
Wiring duct segmentation reveals how specification requirements fragment procurement across installation environments. Product geometry, material chemistry, and end-use intensity each create distinct margin tiers and supplier qualification barriers.
Product Type:
Customization intensity spans from standardized extrusions for bulk panel work to application-engineered channels for motion-intensive routing.
- Slotted Duct:Finger-safe slot geometry permits rapid tap-offs without duct removal. Control panel builders in Germany specify these for machinery requiring frequent electrical reconfiguration.
- Flexible Duct:Corrugated or segmented construction accommodates robotic arm movement and cable flex cycles. German and Chinese automotive assembly lines deploy this format for collaborative robot cable management.
- Non-Slotted Duct:Solid-wall construction protects conductors in permanent runs where access frequency is minimal.
- Aluminum Duct:6063-T6 extrusion grades resist coolant oils and metal shavings in heavy-industrial settings.
- PVC Duct:Halogenated formulations retain cost-driven specification in developing market construction verticals.
Most installed capacity flows through slotted duct for panel-builder procurement. Expansion is steepest in flexible duct as factory automation accelerates.
Material:
Cost tiers separate commodity thermoplastics from engineered compounds carrying regulatory compliance premiums.
- Polycarbonate:Transparent grades with phosphorus-based flame retardants achieve UL 94 V-0 without brominated additives. European E-house suppliers and data center operators now require halogen-free certificates.
- PVC:Lowest material cost positions this for non-critical infrastructure in price-sensitive tenders. REACH and RoHS restrictions constrain European specification.
- ABS:Moderate temperature resistance suits office and light commercial environments without industrial heat loads.
- Steel:Sheet-metal formed channels serve heavy-industrial applications demanding mechanical impact resistance.
- Fiberglass:Corrosion-resistant formulations target chemical processing and outdoor installations.
Polycarbonate commands premium positioning in safety-critical specifications. PVC retains volume leadership in cost-optimized construction segments.
Application:
Customer type determines whether procurement prioritizes material traceability or price-per-meter.
- Data Centers:Hyperscale operators mandate UL 94 V-0 certification and full material disclosure as baseline bid requirements. Liquid cooling infrastructure is compressing cable density tolerances.
- Industrial Manufacturing:German machinery builders and automotive OEMs specify temperature-resistant grades for servo drive heat exposure.
- Telecommunications:Central office and 5G facility upgrades drive channel demand for fiber and power cable segregation.
- Commercial Infrastructure:Mixed-use developments balance code compliance against contractor cost targets.
- Office Buildings:Low-voltage data and power routing favors standard-grade thermoplastics.
Data center procurement concentrates specification power among narrow facility operator tiers. Industrial manufacturing offers the broadest supplier entry points.
End User:
Buying behavior splits between specification-driven engineering departments and cost-focused procurement functions.
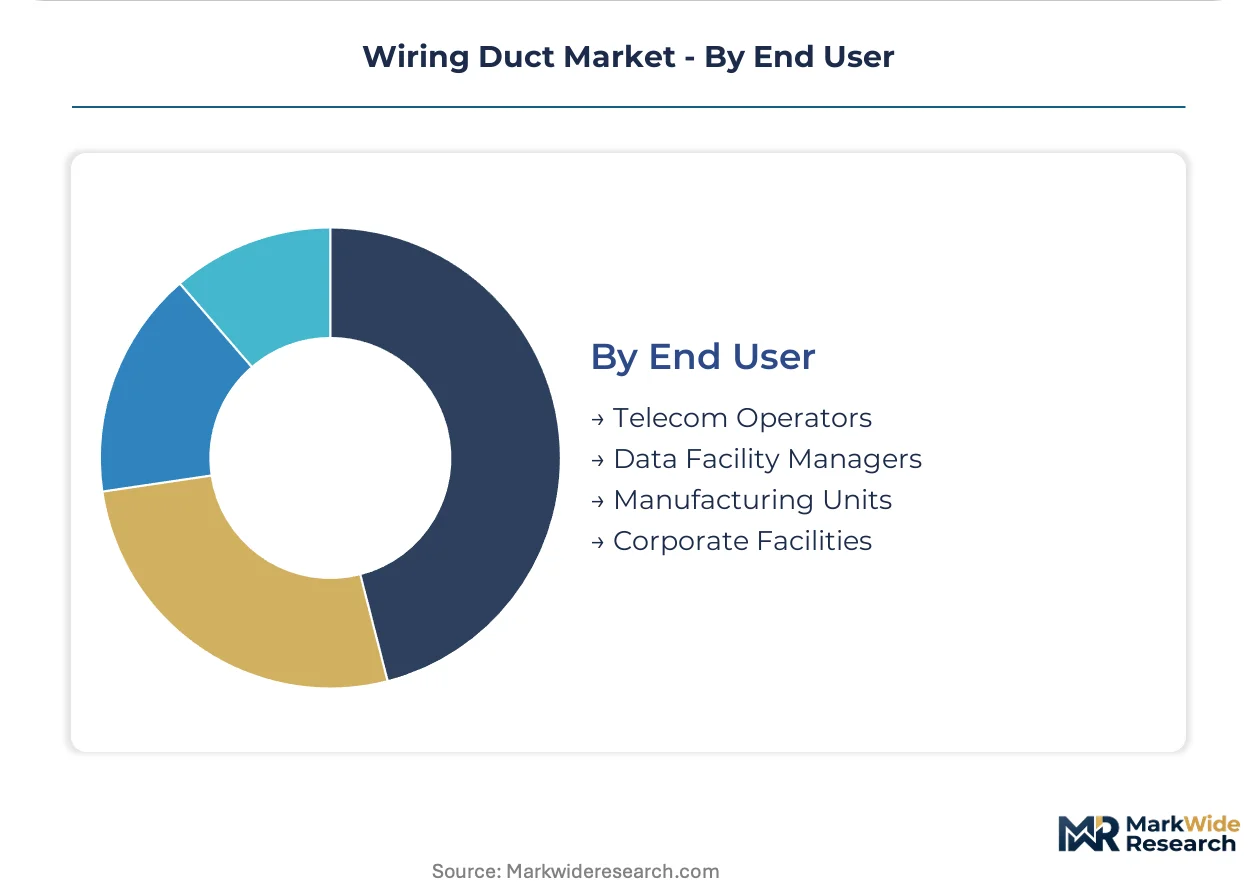
- Data Facility Managers:Sustainability roadmaps and recyclability documentation now accompany every cable management purchase. Tier-one US operators consolidate awards among suppliers with in-house compounding.
- Manufacturing Units:German automotive and machinery sectors prioritize localized supply chains with REACH-compliant feedstock guarantees.
- Telecom Operators:Network infrastructure capex cycles drive bulk purchasing with standardized geometries.
- Corporate Facilities:Commercial real estate owners balance tenant specifications against installed cost.
Data facility managers are tightening supplier qualification fastest. Manufacturing units retain the most fragmented procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive and machinery clusters anchor procurement intensity for temperature-resistant polycarbonate formulations across industrial control applications.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth compresses cable density tolerances for slotted duct specifications. OSHA electrical safety mandates and UL 94 V-0 certification requirements constrain material selection for facility operators. Phoenix Contact and Panduit serve tier-one operators with integrated grounding and snap-fit cover systems.
Germany
Automotive OEMs in Stuttgart and Munich specify REACH-compliant polycarbonate grades for servo drive heat exposure in control panels. ECHA restrictions on halogenated flame retardants redirect procurement toward phosphorus-based alternatives. Bavarian machinery builders consolidate supplier relationships with resin partners guaranteeing compliant feedstock certificates.
China
MEE enforcement on plastic product recyclability creates dual compliance burdens for export-oriented producers serving Atlantic and Pacific markets. GB standard testing stretches product launch cycles for suppliers. Yangtze River Delta E-house manufacturers demand plug-and-play duct systems with integrated grounding for prefabricated electrical infrastructure.
Japan
METI industrial automation initiatives accelerate collaborative robot installations across Toyota City and Nagoya manufacturing corridors. JIS standards govern channel geometry for motion-intensive cable routing. Kansai-based panel builders prioritize localized supply chains with temperature-resistant formulation guarantees.
India
PLI scheme incentives for electronics manufacturing concentrate wiring duct demand in Tamil Nadu and Karnataka industrial corridors. BIS certification requirements shape material selection for domestic versus export production. Chennai and Bengaluru automotive suppliers balance cost targets against emerging halogen-free specifications.
Wiring Duct Market Key Industry Players
Strategic partnerships dominate the current landscape as suppliers secure captive resin arrangements and localized compounding capabilities. The vendor base separates into three tiers: integrated electrical conglomerates with in-house polymer operations, specialized cable management fabricators, and regional extrusion houses serving cost-optimized construction verticals. Two archetypes define competitive positioning: specification-driven compounders capturing premium margins through traceability documentation, and scale-driven producers defending volume share in standardized geometries. M&A activity and backward integration into resin supply represent the dominant competitive moves.
Within the integrated conglomerate tier, Schneider Electric exemplifies captive supply chain control through resin partnerships stabilizing input costs across slotted and non-slotted product lines. ABB anchors European manufacturing positioning with localized compounding operations reducing lead times for German automotive and machinery builders. HellermannTyton occupies a specialist position representing flexible duct configuration expertise for robotics and motion-intensive factory layouts. These three companies illustrate how competitive advantage flows from either upstream supply control, geographic production proximity, or application-specific engineering depth.
| Leading Market Players |
|---|
| Schneider Electric |
| Legrand |
| ABB |
| Phoenix Contact |
| TE Connectivity |
| Panduit |
| Eaton |
| Atkore International |
| HellermannTyton |
| Others |
Cost & Logistics Intelligence
Polycarbonate resin feedstock costs cascade through three distinct pricing tiers as Asian petrochemical complexes dominate upstream supply and European compounders capture compliance premiums downstream. Phosphorus-based flame retardant formulations command margin separation from commodity PVC grades as REACH enforcement tightens material traceability requirements.
Pricing Analysis
Input-cost pass-through from polycarbonate resin and aluminum alloy feedstock drives contract renegotiation cycles between extruders and panel-builder customers. Three-tier pricing structure across premium halogen-free polycarbonate, standard ABS grades, and economy PVC separates data center operators from industrial machinery builders and construction contractors. Pricing pressure stems from LME-linked aluminum volatility and freight cost spikes on Asian resin imports. Construction verticals in developing markets exhibit highest price sensitivity, while German automotive OEMs and US hyperscale operators prioritize certification grade over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with polycarbonate resin production concentrated in China, South Korea, and Taiwan, exposing European extruders to maritime logistics chokepoints and tariff exposure. The wiring duct supply chain draws from brominated flame retardant precursors, phosphorus-based additive packages, and 6063-T6 aluminum extrusion billet as critical component dependencies. Regulatory restriction risk intensifies as ECHA authorization timelines and MEE recyclability enforcement create dual compliance burdens for export-oriented producers. Distribution runs through electrical distributor networks serving panel builders, direct OEM supply agreements with automotive and data center operators, and contractor channels for commercial infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wiring duct market represents a late-cycle quality story as specification-driven procurement displaces price-first sourcing across data center and automotive verticals demanding UL 94 V-0 certification and halogen-free material disclosure.
For Market Incumbents: Deploy captive resin partnerships as the primary lever to stabilize input cost volatility and secure phosphorus-based polycarbonate feedstock certificates ahead of REACH sunset dates. Consolidate supplier relationships with German automotive OEMs through localized compounding operations that guarantee compliant material traceability. Deepen channel control by integrating snap-fit cover and grounding accessory production to defend against specialized fabricators encroaching on premium slotted duct segments. For New Entrants and Emerging Players: Digital-channel routes through E-house and modular data center suppliers offer the most penetrable entry point for plug-and-play duct systems with pre-integrated components. Target flexible duct configurations for collaborative robot installations across Chinese automotive assembly lines where motion-intensive cable routing specifications remain underserved. Pursue a specification-first go-to-market angle by securing third-party sustainability verification and recyclability documentation that tier-one facility operators now mandate as baseline bid elements. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional extrusion houses lack in-house compounding capabilities and struggle to absorb multi-jurisdiction certification costs for UL, IEC 61439, and GB standard testing. The 5-10 year viability window favors acquisition targets with backward integration into resin supply or established partnerships with phosphorus-based flame retardant formulators. Watch for inflection signals in MEE enforcement intensity on plastic product recyclability, as dual compliance burdens will accelerate exit pressure among export-oriented producers unable to bridge Atlantic and Pacific regulatory domains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polycarbonate partnerships stabilize input costs against Asian petrochemical volatility. |
| Phosphorus-Based Compounding Scale-Up | European formulators capture REACH compliance premiums ahead of halogenated flame retardant sunset dates. |
| Modular Data Center Partnership | Prefabricated E-house suppliers in China demand plug-and-play systems with integrated grounding. |
| Third-Party Sustainability Verification | Tier-one US data center operators require recyclability roadmaps as mandatory bid elements. |
| Flexible Duct Configuration Expansion | Collaborative robot installations across German and Chinese automotive lines multiply motion-intensive routing demand. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrical enclosure procurement managers, panel builder operations directors, resin compounder technical leads, and data center facility engineers with secondary validation. Customs and trade data, SEC filings from integrated electrical conglomerates, ECHA REACH authorization databases, and MEE regulatory bulletins anchored supply-side assessment. Bottom-up extrusion capacity modeling and top-down end-use demand estimation triangulated market sizing across product type, material chemistry, and application segments.
Comparable-period anchoring linked forward projections to historical reference intervals across the modeling period, with segmentation dimensions spanning slotted versus flexible versus aluminum duct geometry, polycarbonate versus PVC versus ABS material tiers, and data center versus industrial manufacturing versus commercial infrastructure end-use intensity. CAGRs derived from elasticity-adjusted volume trajectories and value-per-unit trends incorporating phosphorus-based formulation premiums and aluminum alloy price linkage. Industry-specific forecast inputs included hyperscale facility capex cycles, collaborative robot installation rates, and ECHA authorization timeline probabilities.
The model assumes a particular technology adoption path; alternative pathways for halogen-free polycarbonate formulation would alter the outlook if breakthrough bio-based flame retardants achieve UL 94 V-0 equivalence at lower cost. Forecasts reflect assumptions about REACH enforcement continuity, MEE recyclability implementation pace, and resin supply concentration persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Rodless Cylinders Market
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Movable Scaffolding System Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
HVAC Relay Market
Electro-Mech Systems
Automatic Slack Adjusters Market
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Rigid Metal Electrical Conduit Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market
Electro-Mech Systems
Elevator Door-Motor Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Tubular Motors Market