
 Ship Port Infrastructure Market | 2026-2036
Ship Port Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Port Infrastructure Market Analytics
Software-defined terminal operating systems is expanding how port operators monetize berth allocation and yard management. DP World leverages its global network to sustain integrated logistics offerings across multiple continents. PSA International anchors its competitive position through deep automation expertise in container handling. Adani Ports & SEZ dominates Indian subcontinent throughput with captive hinterland connectivity.
Ship port infrastructure encompasses marine structures, cargo handling equipment, and terminal operating systems engineered to receive vessels with draft capacities exceeding twenty meters and to transfer containers at cycle times below thirty seconds per move. Its primary commercial purpose is minimizing vessel turnaround time while maximizing TEU throughput per hectare of terminal footprint. Container terminals command the largest share of capital deployment, while Ro-Ro terminals represent the fastest-growing infrastructure category driven by automotive export flows. Cargo handling services generate recurring revenue streams, whereas port management software captures expanding margin pools as operators digitize berth planning.
The International Maritime Organization enforces emission reduction targets that reshape bunker fuel infrastructure and shore power investments at commercial berths. Classification societies including Lloyd's Register and DNV GL certify structural integrity standards for quay walls and fendering systems under evolving environmental load criteria. Port authorities must weigh automation capital intensity against labor restructuring commitments as stakeholder decisions crystallize around terminal productivity benchmarks.
Market Dynamics
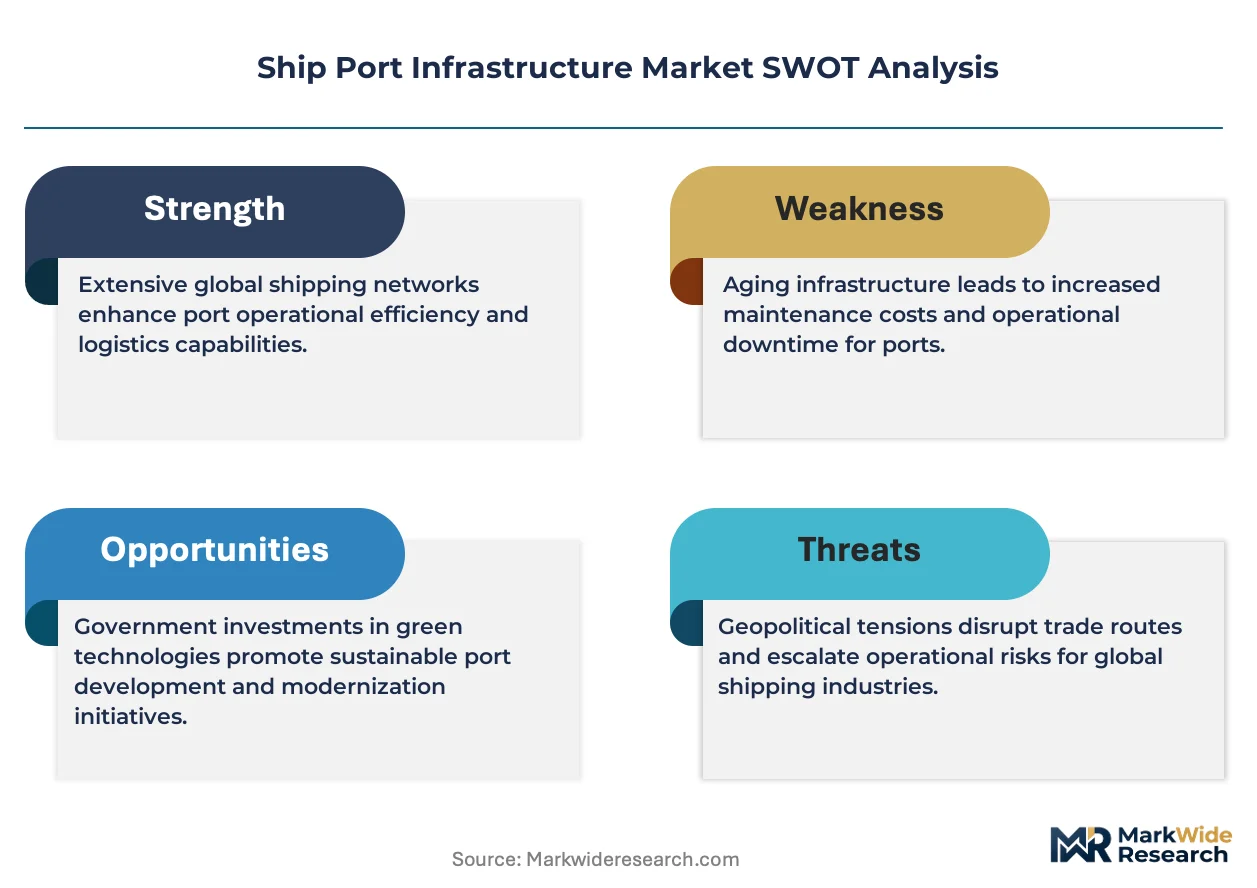
Container shipping lines are consolidating terminal procurement power while the EU Green Deal and IMO emission targets force simultaneous automation and electrification investments, compressing capital planning cycles for port authorities.
Growth Catalysts
- EU F-Gas Regulation:Mandates for low-global-warming-potential refrigerants in reefer infrastructure are accelerating berth electrification investments at transshipment hubs.
- Automotive export flows:Ro-Ro terminal demand from vehicle manufacturers in Germany, Japan, and South Korea is expanding dedicated vehicle handling infrastructure.
- Automated stacking cranes:Terminal operators in Singapore and Rotterdam are deploying AI-guided yard systems to compress container dwell times below seventy-two hours.
Market Restraints
- Steel price volatility:Quay wall construction faces input cost pressure from fluctuating steel reinforcement bar markets, squeezing fixed-price EPC contracts.
- Specialized crane manufacturing concentration:Heavy-lift equipment supply concentrates among German and Chinese fabricators, creating delivery timeline risk for greenfield terminals.
- Grid interconnection delays:Shore power infrastructure faces utility approval bottlenecks that extend commissioning schedules beyond terminal construction completion.
Strategic Opportunities
- Vietnam port expansion:Manufacturing relocation from China is creating unmet demand for deep-water container terminals at Cai Mep and Lach Huyen.
- Hydrogen bunkering infrastructure:Dual-fuel vessel orders from Korean shipyards are opening green hydrogen storage and dispensing facility opportunities.
- Digital twin convergence:Integration of IoT sensor networks with predictive maintenance platforms offers new software revenue streams for terminal operators.
Industry Challenges
- Automation technician scarcity:Terminal operators struggle to recruit PLC programmers and robotics specialists capable of maintaining automated stacking systems.
- Legacy TOS integration:Greenfield automation deployments must interface with decades-old terminal operating systems, creating data architecture friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Port Infrastructure Market |
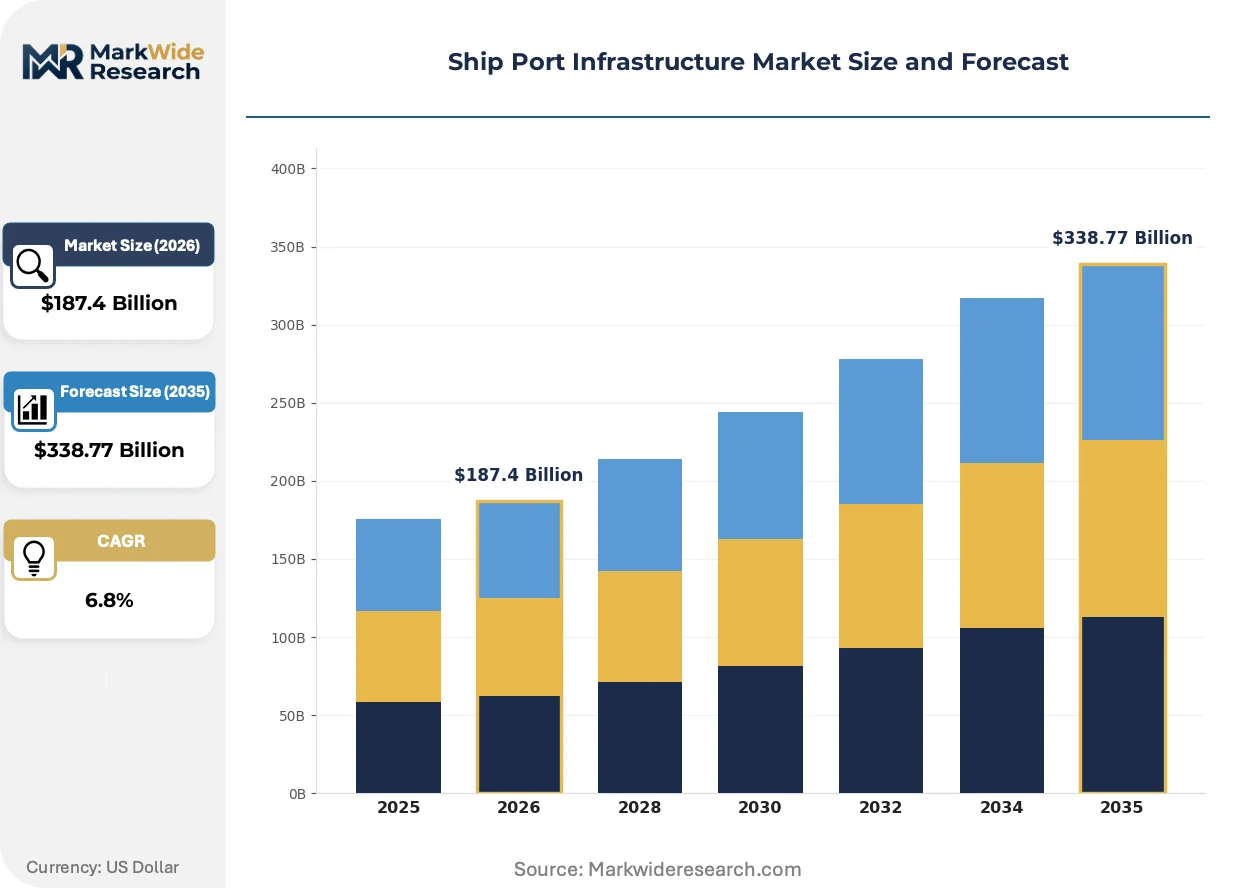
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Container Terminals, Bulk Terminals, Passenger Terminals, Ro-Ro Terminals Service Type: Logistics Services, Cargo Handling, Maintenance Services, Pilotage Services End User: Shipping Lines, Freight Forwarders, Port Authorities, Logistics Providers Technology: Automation Systems, Cargo Tracking, Port Management Software, Security Solutions |
| Companies Covered | DP World, APM Terminals, PSA International, Hutchison Ports, COSCO Shipping Ports, Adani Ports & SEZ, Terminal Investment Limited, ICTSI, Larsen & Toubro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Port Infrastructure Market Evolving Landscape
Software-defined infrastructure and emission compliance mandates are converging to reshape how port operators architect terminal systems and monetize berth capacity.
Artificial intelligence-powered berth allocation engines are absorbing scheduling complexity previously managed by human planners. Major transshipment hubs in Singapore and Rotterdam are deploying these systems to optimize vessel sequencing. The technology is absorbing margin pressure from larger vessel calls by compressing idle berth time.
The EU Green Deal's Fit for 55 package is tightening emission performance standards for vessels at berth. Port authorities in Hamburg and Antwerp must install shore power connections or face operational restrictions. Container terminals with reefer cargo are absorbing the highest compliance costs due to continuous energy demand.
Shipping lines are consolidating terminal service procurement under multi-year framework agreements with productivity guarantees. Smaller regional ports are losing direct carrier relationships to global terminal operators. This concentration is most visible in the Mediterranean, where MSC and CMA CGM are integrating owned terminal networks.
Ship Port Infrastructure Market Segmentation
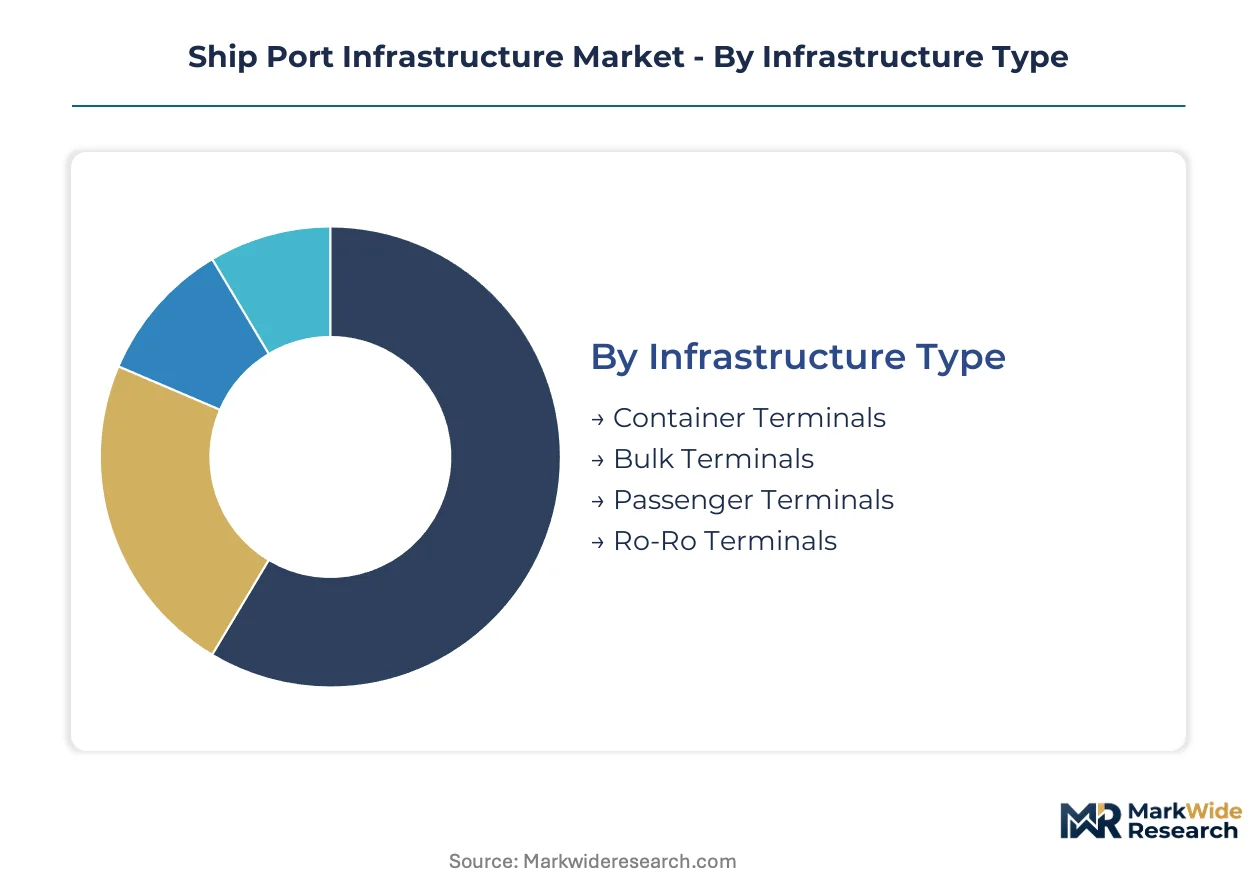
Ship port infrastructure segmentation reveals distinct capital deployment patterns across terminal types and service models. Terminal operators configure infrastructure investments around vessel size profiles, cargo mix volatility, and automation integration depth.
Infrastructure Type:
Standalone terminal facilities operate independently with dedicated berth and yard systems, while embedded infrastructure integrates with multimodal logistics parks and free trade zones.
- Container Terminals:Deep-water quay walls with super-post-Panamax crane rails and automated stacking yards engineered for twenty-thousand-TEU vessel calls. Singapore and Rotterdam operators compress dwell times through AI-guided yard allocation systems.
- Ro-Ro Terminals:Multi-deck vehicle handling ramps and specialized marshalling yards designed for automotive OEM export schedules. German and South Korean vehicle manufacturers drive dedicated berth investments at Bremerhaven and Pyeongtaek.
- Bulk Terminals:Continuous ship unloaders and conveyor systems for iron ore, coal, and grain flows.
- Passenger Terminals:Cruise ship berths with customs integration and passenger boarding bridge systems.
Volume placements concentrate in Container Terminals; the faster expansion belongs to Ro-Ro Terminals.
Service Type:
Service models stratify by margin structure, with recurring maintenance contracts delivering predictable cash flows against project-based cargo handling revenue.
- Cargo Handling:Crane operations, vessel stevedoring, and yard transfers billed per TEU or ton with productivity penalty clauses. Port authorities at Shanghai and Busan negotiate guaranteed moves-per-hour thresholds in terminal concession agreements.
- Maintenance Services:Scheduled quay wall inspection, fender replacement, and pavement rehabilitation programs. Classification societies including Lloyd's Register certify structural integrity protocols under evolving environmental load standards.
- Logistics Services:Warehousing, customs brokerage, and hinterland trucking coordination.
- Pilotage Services:Licensed harbor pilot dispatch for vessel approach and berthing maneuvers.
Revenue stability concentrates in Maintenance Services; Cargo Handling claims the steepest expansion trajectory during transshipment hub capacity additions.
End User:
Customer procurement power varies sharply, with consolidated shipping lines extracting volume discounts unavailable to fragmented freight forwarder networks.
- Shipping Lines:Terminal service procurement under multi-year framework agreements with berth priority guarantees. MSC and CMA CGM integrate owned terminal networks across Mediterranean transshipment corridors.
- Port Authorities:Public concession holders balancing automation capital intensity against labor restructuring commitments.
- Freight Forwarders:NVOCCs and customs brokers accessing terminal services through agency arrangements.
- Logistics Providers:Integrated 3PLs contracting dedicated yard space and empty container depot access.
Contract value concentrates in Shipping Lines; Port Authorities absorb the fastest-growing infrastructure ownership share through greenfield development.
Technology:
Technology deployment spans standalone automation hardware and embedded software platforms that interface with legacy terminal operating systems.
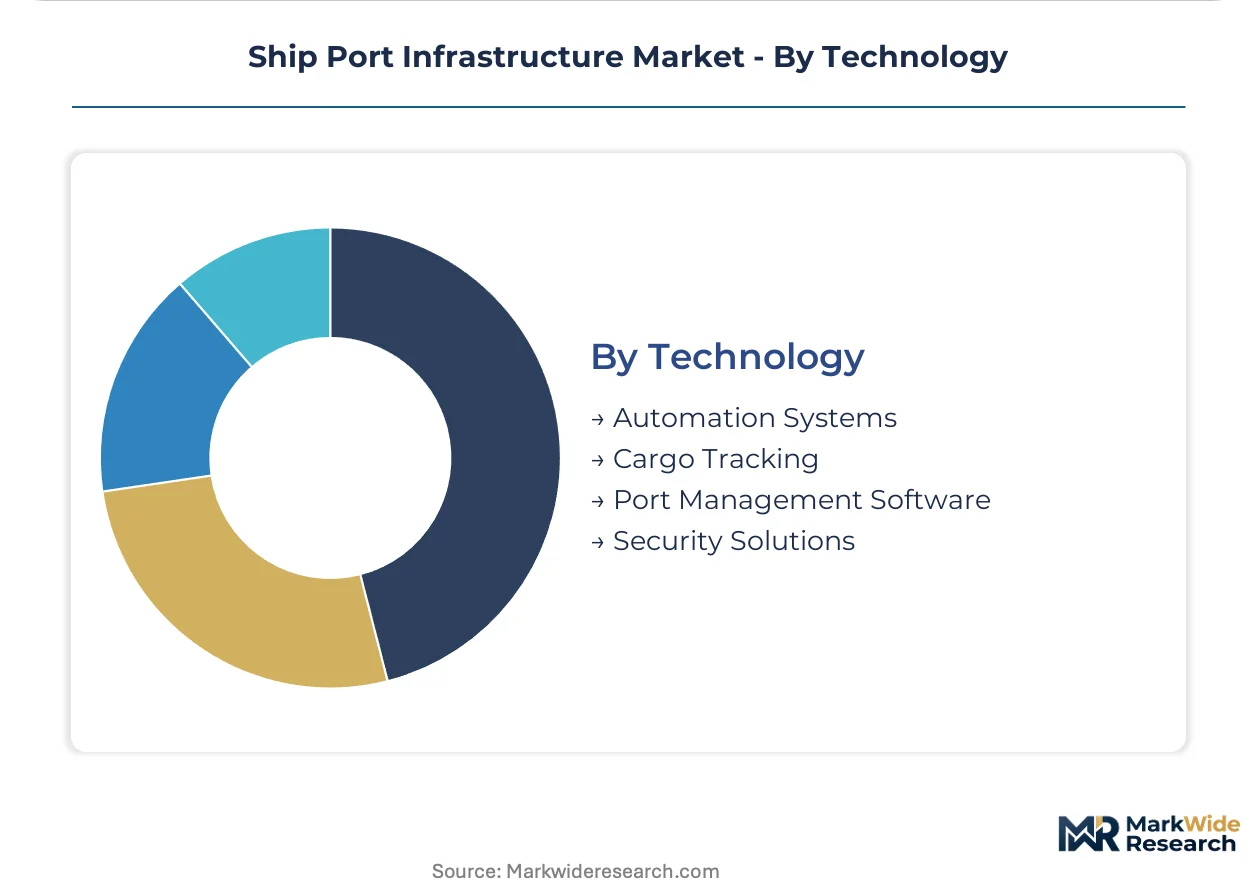
- Automation Systems:Automated stacking cranes, guided vehicle fleets, and remote-controlled ship-to-shore cranes with PLC-based control architectures. PSA International deploys deep automation expertise at Singapore terminals to sustain competitive positioning.
- Port Management Software:Terminal operating systems with berth allocation engines and yard optimization modules. Software-defined infrastructure enables port operators to monetize berth capacity through dynamic pricing algorithms.
- Cargo Tracking:RFID and GPS-enabled container visibility platforms.
- Security Solutions:Perimeter surveillance, radiation portal monitors, and access control systems.
Deployment maturity concentrates in Automation Systems; Port Management Software gains share fastest as operators digitize berth planning and yard management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port infrastructure investment concentrates where manufacturing exports intersect with deep-water vessel access. China consumes the largest share of terminal handling capacity while Singapore and Rotterdam anchor transshipment throughput.
Singapore
PSA International operates the world's largest fully automated container terminal at Tuas, compressing vessel turnaround through AI-guided yard systems. The Maritime and Port Authority of Singapore mandates shore power readiness for all new berth constructions under its Green Port Programme. Tuas Port's phased expansion will consolidate container operations from city terminals by 2027.
China
Shanghai Yangshan and Ningbo Zhoushan handle super-post-Panamax vessel calls exceeding twenty-four thousand TEU capacity. MIIT's smart port initiative funds 5G-enabled automation systems at Qingdao and Xiamen terminals. COSCO Shipping Ports anchors throughput concentration along the Yangtze River Delta manufacturing corridor.
Netherlands
Rotterdam's Maasvlakte terminals deploy automated stacking cranes to sustain European transshipment leadership. The EU Green Deal's Fit for 55 package forces shore power installation at container berths handling reefer cargo. Port of Rotterdam Authority coordinates hydrogen bunkering pilots for dual-fuel vessel calls.
India
Adani Ports & SEZ dominates Indian subcontinent throughput with captive hinterland rail connectivity at Mundra and Hazira. The Sagarmala programme funds deep-water container terminals at Vizhinjam and Vadhavan. Jawaharlal Nehru Port Trust faces automation pressure as private operators expand capacity.
Germany
Bremerhaven and Hamburg anchor European automotive export flows through dedicated Ro-Ro terminals serving German OEMs. The F-Gas Regulation mandates low-global-warming-potential refrigerants in reefer infrastructure, accelerating berth electrification investments. Hamburg Port Authority integrates shore power systems under EU emission performance standards.
Ship Port Infrastructure Market Competitive Landscape
Capital-heavy terminal operators compete with asset-light port management specialists for concession rights and cargo volume. The vendor base stratifies across three tiers: global integrated operators with multi-continent networks, regional specialists with captive hinterland control, and state-linked entities serving national trade corridors. Consolidation pressure intensifies as shipping lines integrate terminal ownership with vessel deployment. Strategic moves center on automation technology licensing and concession renewals with productivity guarantees.
Among global integrated operators, DP World and PSA International exemplify the capital-intensive archetype with deep automation expertise across multiple continents. Adani Ports & SEZ occupies a position as the dominant regional specialist, leveraging captive hinterland infrastructure to control Indian subcontinent throughput. APM Terminals and Hutchison Ports represent diversified port groups with concession portfolios spanning transshipment hubs and gateway terminals.
| Leading Market Players |
|---|
| DP World |
| APM Terminals |
| PSA International |
| Hutchison Ports |
| COSCO Shipping Ports |
| Adani Ports & SEZ |
| Terminal Investment Limited |
| ICTSI |
| Larsen & Toubro |
| Others |
Value Network & Pricing Analysis
Automated stacking crane deployment across Singapore and Rotterdam terminals compresses vessel turnaround economics while concentrating procurement leverage among German and Chinese fabricators. This technology shift forces terminal operators to absorb upfront capital intensity against long-term productivity gains, reshaping how berth electrification investments are financed and priced.
Pricing Analysis
Cost-down pressure on automated terminal systems accelerates because EU F-Gas Regulation mandates are forcing simultaneous berth electrification and reefer infrastructure upgrades. Three-tier pricing structure across premium automation, standard semi-automated, and economy manual handling tiers separates PSA International's fully automated deployments from regional port authorities' phased retrofits. Price differentiation traces to crane manufacturer certification tiers and after-sales service bundling. Shipping lines extract volume discounts through multi-year framework agreements, while freight forwarders face spot-rate volatility without berth priority guarantees.
Supply Chain Analysis
Heavy-lift crane manufacturing rests on German engineering specialists and Chinese fabricators, with PLC control systems drawing from Japanese automation component suppliers. Raw material dependencies span high-grade steel reinforcement bar, specialized electrical drives, and precision sensor arrays. Single-source vulnerability concentrates in automated stacking crane software architectures licensed from European control system vendors. Distribution runs through EPC contractors bidding fixed-price terminal construction contracts, with equipment procurement timelines extending twelve to eighteen months ahead of commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ship port infrastructure is consolidating toward operators with captive automation expertise and multi-continent concession portfolios, as EU Green Deal compliance costs force smaller regional ports into asset-light management contracts.
For Market Incumbents: Anchor competitive positioning through backward integration into terminal operating software development, reducing dependency on legacy TOS vendors. Deepen automation technician training pipelines in Singapore and Rotterdam to offset PLC programmer scarcity threatening yard system uptime. Defend against shipping line vertical integration by securing concession renewals with productivity guarantees exceeding twenty-five moves per hour. For New Entrants and Emerging Players: Mid-sized Vietnamese manufacturers relocating from China represent an underserved buyer archetype demanding dedicated deep-water container terminals at Cai Mep and Lach Huyen. Green hydrogen bunkering infrastructure for Korean-built dual-fuel vessels offers penetrable white-space with limited incumbent specialization. Pursue joint venture structures with state port authorities to share electrification capital burdens under Sagarmala-style development programs. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by global integrated operators seeking automation technology licensing capabilities and regional concession density. Long-term viability favors terminal operators with software-defined infrastructure monetization and shore power-ready berth portfolios. Watch for IMO emission target acceleration as the inflection signal triggering distressed asset availability from compliance-lagged regional ports.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Automation Deployment | AI-guided yard systems at Singapore's Tuas compress dwell times below seventy-two hours. |
| Shore Power Infrastructure Investment | EU Green Deal Fit for 55 mandates force Hamburg and Antwerp berth electrification for reefer cargo. |
| Hydrogen Bunkering Pilot | Rotterdam coordinates green hydrogen storage pilots for Korean dual-fuel vessel calls. |
| Digital Twin Integration | IoT sensor convergence with predictive maintenance opens software revenue streams for PSA International. |
| Concession Renewal with Productivity Guarantees | MSC and CMA CGM extract berth priority through multi-year framework agreements in Mediterranean corridors. |
Research Methodology
Document review covered customs trade databases, port authority annual reports, and IMO regulatory filings, complemented by interviews with terminal operations directors, EPC project managers, and shipping line procurement leads. Secondary validation drew from Lloyd's Register certification records, EU Green Deal implementation guidance, and classification society technical bulletins. Bottom-up terminal capacity modeling triangulated against top-down regional trade flow projections.
Segmentation outputs reflect infrastructure type, service model, end-user procurement power, and automation technology deployment depth across the projection horizon. CAGRs derived from vessel size evolution curves, transshipment hub expansion timelines, and emission compliance investment cycles. Forecast inputs incorporated steel price volatility indices and grid interconnection approval bottlenecks affecting shore power commissioning schedules.
Revisions become necessary when IMO emission targets accelerate, EU F-Gas Regulation enforcement tightens, or automated crane manufacturing concentration triggers delivery timeline disruptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
Bahrain Construction Market
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
Cofferdam Market