
 Agitator Drive Units Market | 2026-2036
Agitator Drive Units Market Size, Share, and Industry Trends Forecast 2026-2036
Agitator Drive Units Market Analytics
Market Context with Strategic Players
German industrial motor suppliers is repositioning output toward modular drive architectures for hygienic process environments. SPX FLOW leverages vertical integration across stainless-steel fabrication and seal technologies to control lead times in pharmaceutical-grade agitator deliveries. Sulzer Ltd anchors its position through R&D intensity in computational fluid dynamics modeling for impeller optimization. Alfa Laval competes via geographic dominance in Nordic dairy and brewery retrofit markets where clean-in-place compatibility governs procurement decisions.
Technical Definition and Structural Segments
Agitator drive units are electromechanical power transmission systems that convert rotational energy from motors into controlled torque output for impeller shafts, typically operating at speeds from 10 to 1,800 RPM with power ratings spanning 0.18 kW to 1,000 kW to achieve uniform mixing, heat transfer, or suspension in process vessels. Gearbox agitators occupy the largest installed base due to torque multiplication requirements in high-viscosity chemical slurries, though magnetic drive units are gaining share in pharmaceutical bioreactor applications where zero-seal leakage satisfies sterile process validation. Direct drive units command premium positioning in food processing lines where energy efficiency targets and reduced maintenance intervals justify higher capital outlay. Water treatment applications favor hydraulic agitators for variable-speed flexibility in flocculation basins with fluctuating influent loads.
Regulatory Frame and Forward-Looking Close
EU ATEX directives and the Machinery Directive enforce explosion-protection categories and fail-safe braking standards for drive units deployed in solvent-handling chemical plants. The US FDA's Current Good Manufacturing Practice regulations and 3-A Sanitary Standards constrain material selection and surface finish specifications for agitators in dairy and pharmaceutical contact applications. China's GB standards for mechanical safety and the National Medical Products Administration's pharmaceutical equipment guidelines shape import qualification pathways for foreign drive suppliers. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving energy efficiency labeling regimes in the European Union and North America alter total-cost-of-ownership calculations for electric drive configurations against pneumatic alternatives.
Market Dynamics
Magnetic drive technology is compressing the addressable market for mechanical seal systems as pharmaceutical and fine chemical producers prioritize zero-leakage validation over upfront capital cost in stirred-tank reactor procurement.
Growth Catalysts
- EU ATEX Directives:Explosion-protection mandates for solvent-handling facilities are accelerating replacement cycles for legacy drive units in German and Dutch chemical corridors.
- Bio-based polymer capacity:Chemical manufacturers in the United States and Germany are expanding stirred-tank reactor installations to meet renewable polymer output targets.
- China's eastern coastal provinces:State-backed petrochemical complexes are commissioning integrated agitation systems for fine chemical production, concentrating demand in Jiangsu and Zhejiang.
Market Restraints
- Permanent magnet cost volatility:Rare-earth element price swings constrain margin stability for magnetic drive unit producers dependent on neodymium supply.
- Specialized gearbox supplier concentration:Precision gear manufacturing for high-torque chemical applications clusters in southern Germany and northern Italy, creating single-source vulnerability.
- REACH substance restrictions:European chemical registration requirements are narrowing approved lubricant formulations for drive assemblies in food-contact applications.
Strategic Opportunities
- India's pharmaceutical manufacturing:CDSCO equipment qualification pathways for imported drive systems remain underpenetrated relative to domestic formulation capacity expansion.
- Carbon-border adjustment mechanisms:EU CBAM implementation creates competitive opening for drive suppliers with documented lifecycle emissions data against pneumatic alternatives.
- Computational fluid dynamics integration:Convergence of physics modeling software with modular drive architectures enables predictive impeller optimization as a service layer.
Industry Challenges
- ATEX certification timelines:Third-party conformity assessment for explosion-protected drive units extends 14-22 weeks, delaying project commissioning in fast-track chemical builds.
- Legacy DCS integration:Retrofitting variable-frequency drive units into 1990s-era distributed control systems requires custom protocol gateways that inflate engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agitator Drive Units Market |
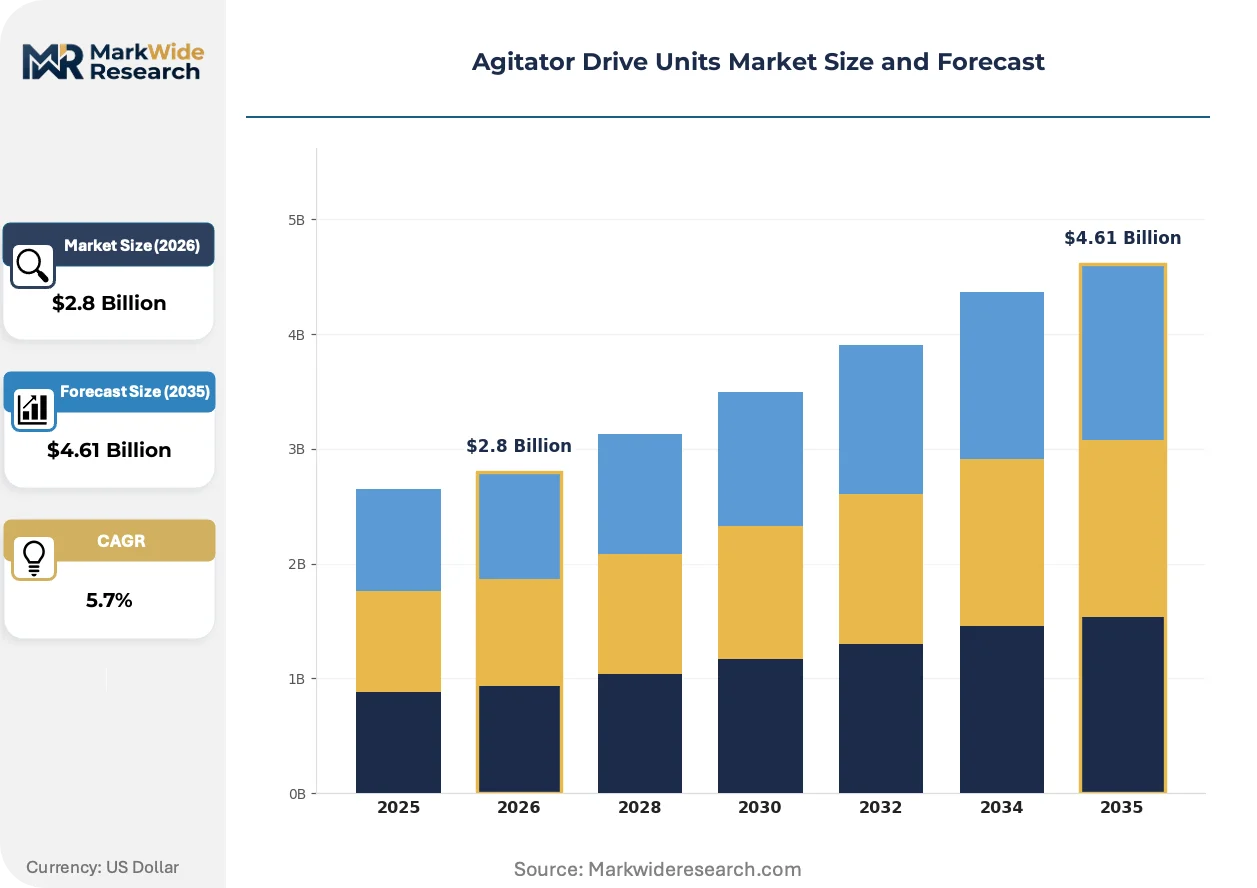
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gearbox Agitators, Direct Drive Units, Hydraulic Agitators, Magnetic Drive Units Industry Vertical: Food Processing, Chemical Manufacturing, Pharmaceutical, Water Treatment Application: Mixing, Emulsification, Dispersion, Heating Energy Source: Electric, Pneumatic, Hydraulic, Others |
| Companies Covered | SPX FLOW, Sulzer Ltd, Alfa Laval, Xylem Inc, EKATO Group, Philadelphia Mixing Solutions, National Oilwell Varco, Silverson Machines, Dynamix Agitators Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agitator Drive Units Market Evolving Landscape
Digital twin deployment and predictive torque analytics are redefining how process engineers specify agitation systems, shifting procurement criteria from capital expenditure minimization toward total lifecycle performance guarantees.
Magnetic drive technology is expanding into high-pressure pharmaceutical bioreactor applications where hermetic containment eliminates sterilization-in-place validation failures. Contract development and manufacturing organizations are adopting these systems at accelerating rates for multi-product facilities. The technology is expanding into territory previously dominated by double mechanical seals, compressing aftermarket seal replacement revenue pools.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of fluoropolymer coatings used in agitator wetted components. Drive unit suppliers must qualify alternative surface treatments for corrosion resistance in acidic process environments. Pharmaceutical-grade stainless steel fabrication facilities in Ireland and Belgium are most exposed to coating requalification costs.
Equipment-as-a-service contracting is displacing traditional capital purchase models in Nordic dairy processing retrofit programs. Skim milk powder and whey protein concentrate producers are unbundling drive unit ownership from maintenance responsibility, transferring operational risk to OEM service arms. This pattern is most visible in Denmark and Sweden where cooperative dairy structures favor operational expenditure treatment.
Agitator Drive Units Market Segmentation
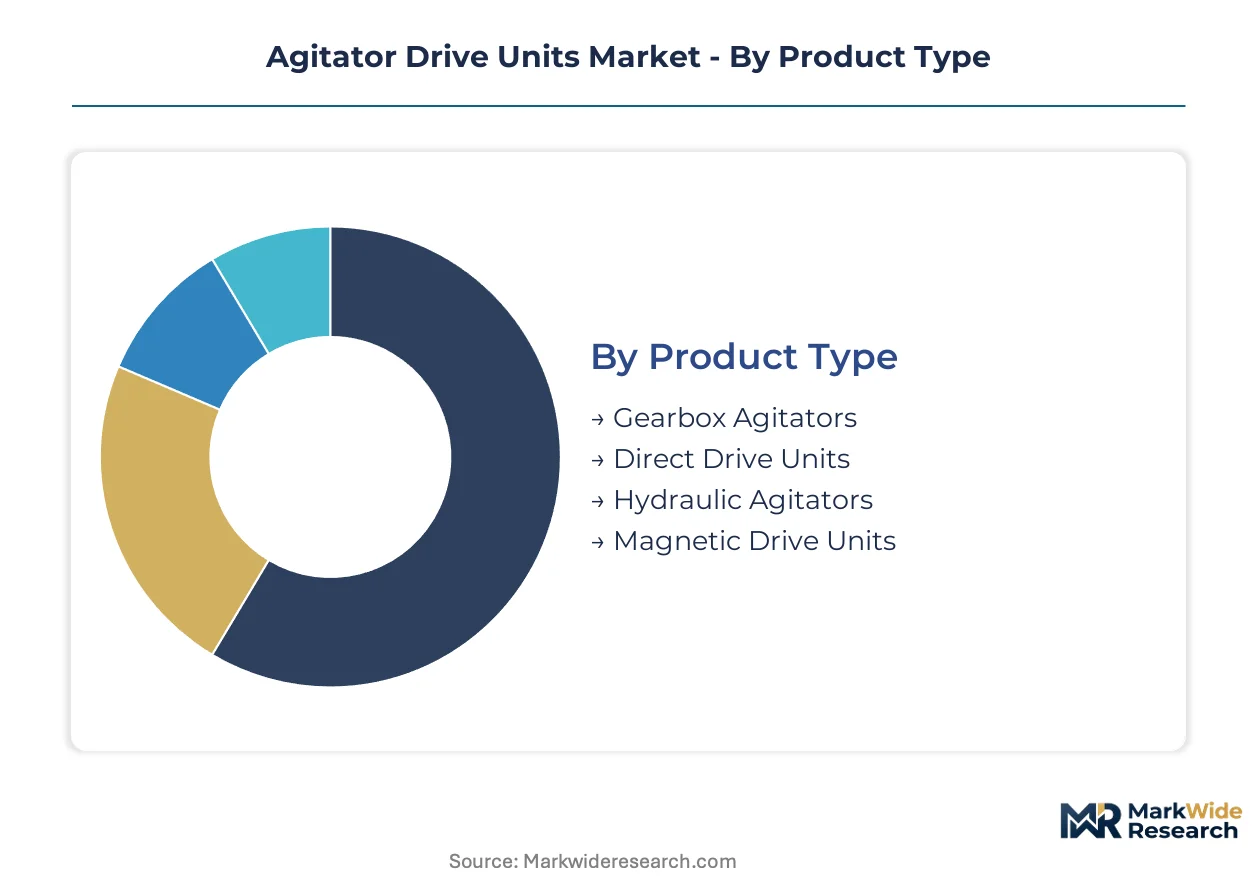
Segmentation in agitator drive units reveals how procurement criteria diverge across process environments. Torque requirements, sterility validation, and energy efficiency targets each favor distinct drive architectures. Understanding these splits enables suppliers to align R&D spend with buyer willingness-to-pay premiums.
Product Type:
Buyers select drive architecture based on viscosity load, leakage tolerance, and maintenance access constraints in their specific process vessels.
- Gearbox Agitators:Torque multiplication through helical or planetary gear stages handles high-viscosity chemical slurries above 10,000 cP. German and Dutch chemical corridors drive replacement demand as EU ATEX directives force upgrades to explosion-protected configurations in solvent-handling facilities.
- Magnetic Drive Units:Hermetic containment via synchronous magnetic couplings eliminates mechanical seal wear. Pharmaceutical bioreactor installations in Ireland and Belgium adopt these systems to satisfy FDA sterile process validation and eliminate sterilization-in-place failures.
- Direct Drive Units:Permanent magnet synchronous motors couple directly to impeller shafts, cutting energy losses from gear friction. Food processing lines in Denmark specify these for clean-in-place compatibility and reduced maintenance intervals.
- Hydraulic Agitators:Variable displacement pumps enable stepless speed control for flocculation basins with fluctuating influent loads. Water treatment utilities favor this flexibility over electric alternatives.
Gearbox agitators lead on scale; magnetic drive units lead on momentum.
Industry Vertical:
Regulatory intensity and batch value determine capital allocation tolerance for drive unit specifications across process industries.
- Chemical Manufacturing:High-torque requirements for polymerization reactors and corrosive slurry handling dominate specifications. Jiangsu and Zhejiang petrochemical complexes in China commission integrated agitation systems with ATEX-certified drive assemblies for fine chemical output targets.
- Pharmaceutical:Zero-leakage validation and surface finish specifications constrain material selection. CDSCO equipment qualification pathways in India remain underpenetrated relative to domestic formulation capacity expansion.
- Food Processing:Clean-in-place compatibility and 3-A Sanitary Standards govern procurement. Nordic dairy cooperatives in Sweden unbundle drive ownership through equipment-as-a-service contracts.
- Water Treatment:Variable-speed flexibility for coagulation and flocculation processes drives hydraulic agitator preference. Municipal utilities prioritize operational expenditure treatment over capital efficiency.
Chemical manufacturing leads on scale; pharmaceutical leads on momentum.
Application:
Fluid mechanics objectives dictate impeller geometry and speed range requirements that cascade into drive unit torque specifications.
- Mixing:Bulk homogenization of miscible fluids requires sustained moderate shear. Batch chemical reactors specify gearbox agitators for uniform temperature distribution during exothermic reactions.
- Dispersion:Particle size reduction and suspension stability demand high-shear impeller speeds. Magnetic drive units penetrate paint and coating manufacturing where solvent containment is critical.
- Emulsification:Immiscible phase stabilization requires precise tip speed control. Food-grade direct drive systems dominate mayonnaise and dressing production lines.
- Heating:Convective heat transfer enhancement in jacketed vessels favors low-speed high-torque operation. Polymer melt processing relies on gearbox configurations.
Mixing leads on scale; dispersion leads on momentum.
Energy Source:
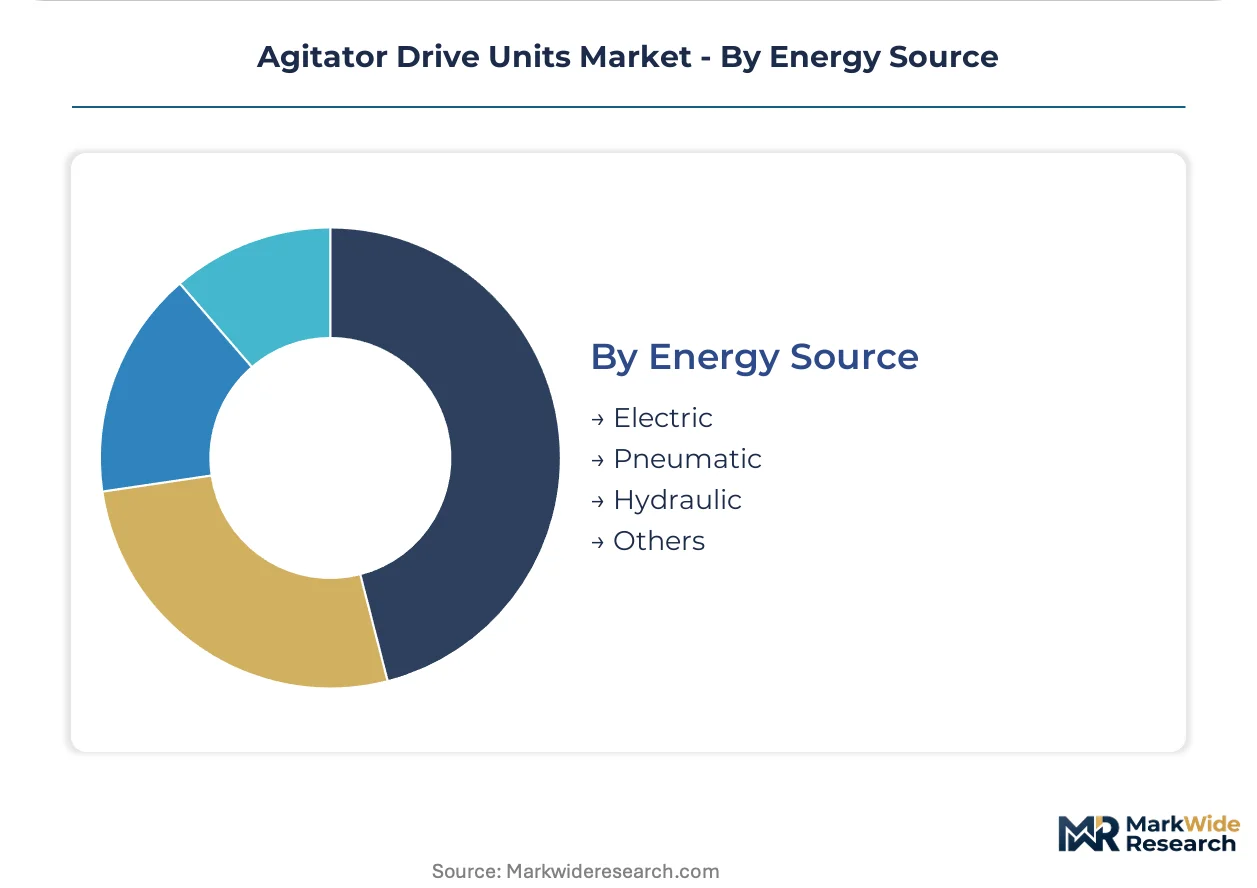
Site infrastructure and carbon accounting frameworks tilt procurement toward electric, pneumatic, or hydraulic power transmission.
- Electric:Variable frequency drives enable precise speed control and energy recovery. EU CBAM implementation favors suppliers with documented lifecycle emissions data.
- Hydraulic:Explosion-proof inherent safety suits offshore platform and solvent-handling environments without electrical classification complexity.
- Pneumatic:Compressed air availability in legacy facilities sustains niche demand, though energy efficiency penalties constrain expansion.
- Others:Emerging turbine-direct and spring-storage configurations address remote site power availability constraints.
Electric leads on scale; hydraulic leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's chemical manufacturing base demands higher torque density than India's pharmaceutical expansion, yet both markets impose distinct certification burdens on drive unit suppliers seeking local qualification.
United States
Bio-based polymer capacity expansion in Texas and Louisiana drives stirred-tank reactor installations requiring ATEX-equivalent explosion protection. EPA emissions regulations and OSHA process safety management standards constrain lubricant selection and seal specifications. Houston's petrochemical corridor commissions integrated agitation systems for renewable chemical output targets.
Germany
EU Machinery Directive compliance deadlines accelerate replacement cycles for legacy drive units in solvent-handling facilities along the Rhine-Ruhr chemical belt. REACH substance restrictions narrow approved lubricant formulations for food-contact applications. Bavaria's precision gearbox manufacturers face capacity constraints serving European fine chemical producers.
China
State-backed petrochemical complexes in Jiangsu and Zhejiang provinces commission high-torque agitation systems for specialty chemical production. NMPA pharmaceutical equipment guidelines and GB mechanical safety standards shape import qualification pathways for foreign suppliers. Shanghai's fine chemical clusters prioritize magnetic drive configurations for zero-leakage validation.
India
CDSCO equipment qualification pathways for imported drive systems remain underpenetrated relative to domestic formulation capacity expansion in Maharashtra and Gujarat. FSSAI food safety regulations and BIS mechanical standards govern material selection for dairy processing applications. Hyderabad's active pharmaceutical ingredient producers retrofit bioreactors with hermetic drive configurations.
Belgium
Pharmaceutical-grade stainless steel fabrication facilities in Flanders face coating requalification costs from REACH authorization requirements for per- and polyfluoroalkyl substances. EMA sterile process validation standards drive magnetic drive adoption in biologics manufacturing. Antwerp's chemical port infrastructure supports integrated agitation system deliveries to European fine chemical producers.
Agitator Drive Units Market Competitive Landscape
German industrial motor suppliers anchor one tier; Nordic hygienic equipment specialists hold differentiated positions in dairy and brewery retrofit markets. The vendor base clusters around three strategic archetypes: vertically integrated process equipment conglomerates, precision gearbox fabricators with captive metallurgy capabilities, and modular drive architects serving validated pharmaceutical environments. Capacity expansion and technology licensing represent the dominant competitive vectors as suppliers seek to compress ATEX certification timelines and secure rare-earth magnet supply agreements.
Within the integrated process equipment tier, SPX FLOW and Sulzer Ltd exemplify backward integration strategies spanning stainless-steel fabrication, seal technologies, and computational fluid dynamics modeling. Alfa Laval occupies a position among Nordic-based hygienic equipment specialists where clean-in-place compatibility governs procurement decisions in cooperative dairy structures. These three companies represent distinct geographic and technical positioning without overlapping core competence claims.
| Leading Market Players |
|---|
| SPX FLOW |
| Sulzer Ltd |
| Alfa Laval |
| Xylem Inc |
| EKATO Group |
| Philadelphia Mixing Solutions |
| National Oilwell Varco |
| Silverson Machines |
| Dynamix Agitators Inc |
| Others |
Value Network & Pricing Analysis
Precision gearbox fabricators in southern Germany anchor labor-cost differentials that widen pricing-tier spreads between ATEX-certified pharmaceutical-grade units and standard industrial configurations. Tiered pricing separates hermetic magnetic drive systems from conventional gearbox agitators from economy direct-drive units, with certification grade and volume scale governing procurement thresholds.
Pricing Analysis
Capacity additions in China's eastern coastal provinces are reshaping price floors for standard gearbox configurations while premium magnetic drive units maintain margin insulation through FDA validation requirements. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with ATEX and 3-A Sanitary Standards commanding substantial premiums. Cost compression in standard industrial tiers intensifies because of rare-earth magnet price volatility and gearbox supplier concentration. Municipal water treatment utilities exhibit highest price sensitivity; pharmaceutical CDMOs demonstrate lowest sensitivity due to sterile process validation requirements.
Supply Chain Analysis
Rare-earth magnet supply rests on Chinese processing facilities and Japanese specialty material producers, with neodymium procurement tethered to geopolitical export licensing regimes. Precision gear manufacturing clusters in southern Germany and northern Italy, while stainless-steel fabrication concentrates in Belgium and Ireland. Single-source vulnerability pervades high-torque gearbox sourcing for chemical applications. Distribution runs through integrated process equipment OEMs and specialized aftermarket service networks serving validated pharmaceutical environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic drive technology penetration enables margin expansion through premium-tier positioning and reduced aftermarket seal replacement revenue displacement. Permanent magnet cost volatility and REACH substance restrictions create cost-down pressure on legacy mechanical seal configurations.
For Market Incumbents: Anticipate compression in mechanical seal aftermarket revenue pools as pharmaceutical bioreactor specifications shift toward hermetic containment. Defensive moves center on securing rare-earth magnet supply agreements with Chinese processors and accelerating ATEX certification timelines through notified body partnerships. Backward integration into computational fluid dynamics software capabilities protects against equipment-as-a-service displacement in Nordic dairy markets. For New Entrants and Emerging Players: CDMOs in India's Maharashtra and Gujarat corridors represent an underserved buyer archetype with underpenetrated equipment qualification pathways relative to domestic formulation capacity expansion. White-space targets include hydraulic agitator retrofits for municipal water treatment utilities and modular drive architectures for multi-product pharmaceutical facilities. Go-to-market positioning emphasizes documented lifecycle emissions data to exploit EU CBAM implementation against pneumatic alternatives. For Investors and Strategic Acquirers: Process equipment conglomerates with captive metallurgy capabilities are the most active acquirer in this space, consolidating precision gearbox fabricators and seal technology specialists. Long-term viability hinges on exposure to bio-based polymer capacity expansion and pharmaceutical sterile process validation trends. Acquisition target archetypes include modular drive architects with predictive torque analytics software layers. Watch for carbon-border adjustment mechanism enforcement intensity as inflection indicator for electric drive configuration preference against pneumatic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Sourcing | Secures neodymium supply chains against Chinese export licensing volatility for magnetic drive production. |
| Computational Fluid Dynamics Platform Acquisition | Integrates predictive impeller optimization software with modular drive hardware for pharmaceutical bioreactor specifications. |
| Equipment-as-a-Service Contract Expansion | Transfers operational risk to OEM service arms in Nordic dairy cooperative structures favoring opex treatment. |
| ATEX Certification Timeline Compression | Reduces 14-22 week third-party conformity assessment delays through notified body partnership structures. |
| REACH-Compliant Coating Requalification | Replaces fluoropolymer surface treatments in Belgian and Irish stainless-steel fabrication facilities facing authorization requirements. |
Research Methodology
Multiple input streams — plant engineer interviews at chemical manufacturing facilities, procurement lead discussions at pharmaceutical CDMOs, distributor channel assessments, and aftermarket service provider consultations — were reconciled against customs trade data, EU ATEX notification databases, SEC equipment supplier filings, and Chinese petrochemical project registries. Bottom-up unit demand estimates from stirred-tank reactor installations and top-down value reconstructions from gearbox and magnetic drive supplier revenues were cross-validated.
Data-stream reconciliation applied product type, industry vertical, application objective, and energy source dimensions across the analysis window. CAGRs were derived from slope analysis of normalized replacement cycle frequencies and capacity expansion announcements. Forecast inputs incorporated EU Machinery Directive compliance deadlines, NMPA pharmaceutical equipment guideline evolution, and rare-earth element price trajectory assumptions.
Inputs from notified body certification records and customs trade databases were available through the study window; gaps in real-time rare-earth magnet inventory positioning introduce uncertainty bands around magnetic drive unit penetration assumptions. Forecasts reflect documented replacement cycle frequencies and regulatory compliance cost structures. Material deviation in EU CBAM enforcement intensity, REACH authorization timelines, or Chinese rare-earth export licensing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Rodless Cylinders Market
Electro-Mech Systems
HVAC Relay Market
Electro-Mech Systems
Elevator Door-Motor Market
Electro-Mech Systems
Movable Scaffolding System Market
Electro-Mech Systems
Tubular Motors Market
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Automatic Slack Adjusters Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
Rigid Metal Electrical Conduit Market
Electro-Mech Systems
Wiring Duct Market