
 Light Gauge Framing System Market | 2026-2036
Light Gauge Framing System Market Size, Share, and Industry Trends Forecast 2026-2036
Light Gauge Framing System Market Foresight
REACH compliance is broadening the cost-of-entry calculus for European suppliers of galvanized and cold-formed steel framing. Nucor Corporation leverages its electric arc furnace footprint to sustain low-carbon steel output for residential and commercial segments. ArcelorMittal S.A. anchors European supply through its integrated mills and recycling infrastructure. FRAMECAD Limited specializes in automated roll-forming equipment that controls design-to-manufacture workflows for modular builders.
Light gauge framing systems are structural assemblies fabricated from cold-formed steel sections typically ranging from 0.5 mm to 2.5 mm in thickness, engineered to carry axial, shear, and bending loads in low- to mid-rise buildings. Their primary purpose is to replace traditional timber or hot-rolled steel members with dimensionally stable, non-combustible components that enable faster erection cycles. Cold-formed steel dominates material selection for mid-rise residential podiums where fire ratings and dimensional consistency outweigh first-cost premiums. Modular installation types are capturing margin pools as developers seek factory-controlled quality and compressed site schedules. Pre-engineered systems retain volume leadership in commercial strip retail and distribution centers where design repeatability lowers engineering overhead.
FEMA and the International Code Council shape US seismic and wind-load standards that dictate connector detailing and bracing configurations for light gauge assemblies. The EU Green Deal and EMAS requirements are embedding lifecycle carbon thresholds into public procurement specifications for steel-intensive construction. Australia's NCC and steel certification schemes under the Steel Institute of Australia govern bushfire resistance and structural durability ratings. Stakeholders must monitor how tightening embodied carbon accounting alters material substitution patterns between galvanized steel and aluminum framing alternatives.
Market Dynamics
Off-site fabrication methods are compressing construction timelines and forcing material specification shifts across residential and commercial verticals, with building code stringency acting as the primary accelerant for cold-formed steel adoption.
Growth Catalysts
- EU Green Deal embodied carbon benchmarks:Public procurement specifications across European member states now favor lower-carbon steel grades, redirecting material specifications toward cold-formed alternatives in mid-rise residential podiums.
- Seismic and wind-load standard tightening:FEMA and the International Code Council in the United States dictate connector detailing requirements that favor engineered steel assemblies over timber framing in high-risk zones.
- Labor productivity pressures:Australia's National Construction Code and compressed site schedules drive developers toward factory-controlled quality through modular installation types.
Market Restraints
- Zinc input cost volatility:Galvanized coating requirements expose fabricators to London Metal Exchange zinc price swings that compress margin predictability on fixed-price contracts.
- European supply concentration:Integrated mill dominance in Germany and Benelux creates bottleneck risk for cold-formed coil feedstock during energy price spikes.
- Timber substitution persistence:Cross-laminated timber retains first-cost advantage in low-rise residential segments where fire ratings are less stringent.
Strategic Opportunities
- Bushfire-resistant construction mandates:Australia's Steel Institute Australia certification schemes create specification pull for non-combustible framing in wildland-urban interface zones.
- Design-to-manufacture workflow integration:Automated roll-forming equipment convergence with BIM platforms enables mass customization for modular builders seeking compressed engineering overhead.
- Mid-rise residential podium expansion:United States zoning liberalization in Texas and Florida municipalities permits five-over-one construction types that favor dimensional stability of steel assemblies.
Industry Challenges
- Structural engineer talent scarcity:Cold-formed steel-specific design expertise remains concentrated among aging practitioner cohorts, constraining project throughput for complex bracing configurations.
- Multi-jurisdictional certification timelines:EMAS and REACH compliance documentation requirements extend European product approval cycles, delaying market entry for new galvanized coating formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Gauge Framing System Market |
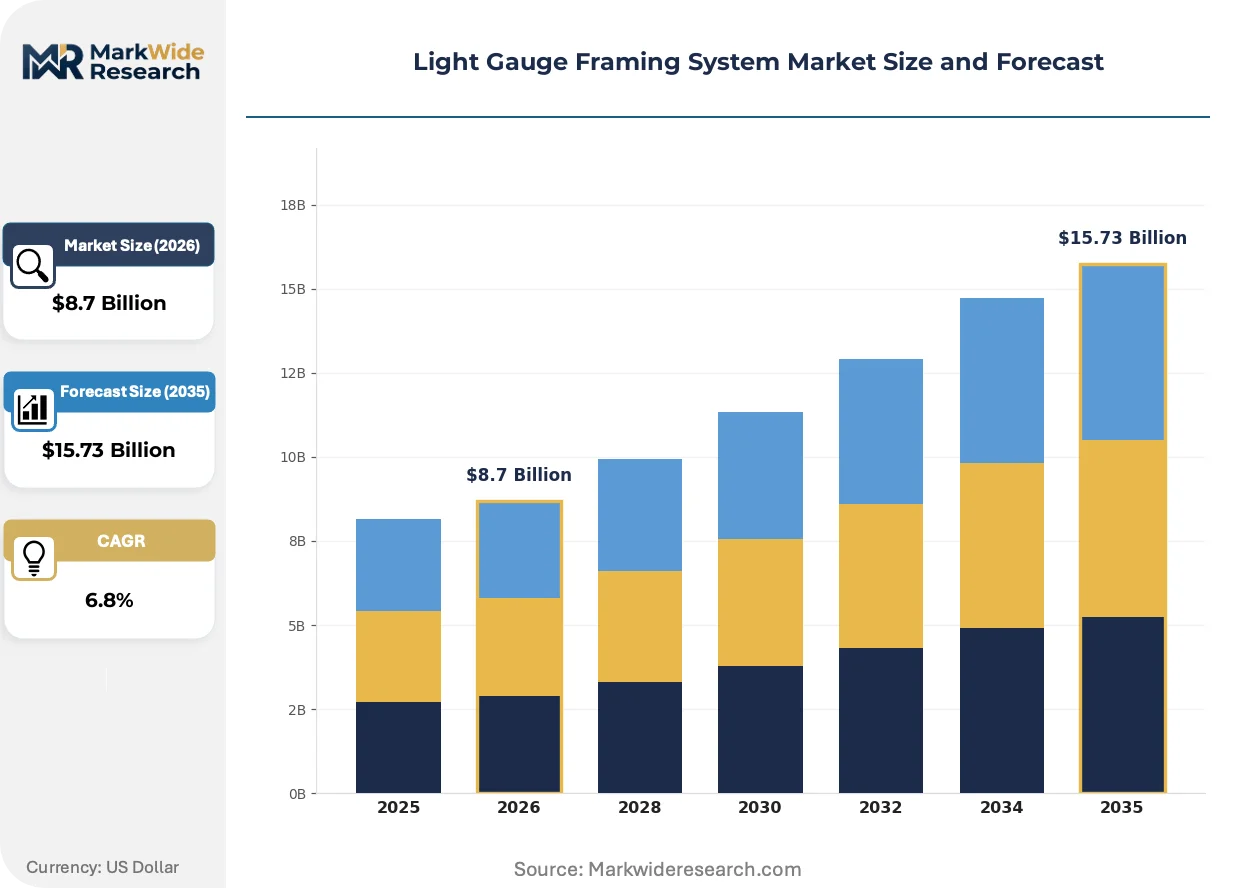
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Steel, Aluminum, Galvanized Steel, Cold-Formed Steel Application: Commercial Buildings, Residential Construction, Industrial Structures, Agricultural Facilities Installation Type: Pre-Engineered, Modular, On-Site, Prefabricated End User: Contractors, Architects, Builders, Developers |
| Companies Covered | ClarkDietrich Building Systems, Nucor Corporation, ArcelorMittal S.A., Hadley Group, FRAMECAD Limited, CEMCO, SCAFCO Steel Stud Company, Kingspan Group Plc, Tata Steel Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Gauge Framing System Market Shifts & Advancements
Digital fabrication workflows and embodied carbon accounting are simultaneously compressing design-to-erection cycles and reshaping material specification hierarchies across construction procurement.
Automated roll-forming equipment paired with parametric design software is consolidating control over light gauge framing production. Modular builders in the United States and Australia adopt these integrated systems to eliminate manual cutting errors and reduce on-site labor hours. The technology is consolidating fragmented regional fabricators into centralized production hubs capable of serving multi-state project portfolios.
REACH compliance and EMAS requirements are embedding lifecycle carbon thresholds into European steel-intensive construction procurement. Public sector clients now mandate Environmental Product Declarations for structural assemblies, filtering supplier pools toward electric arc furnace producers. German and Dutch housing authorities lead enforcement, with penalties for non-compliance extending to contract disqualification.
Developers are unbundling traditional general contractor relationships in favor of direct procurement from pre-engineered system providers. This channel compression eliminates markup layers in United States commercial strip retail and distribution center construction. Texas and Arizona markets exhibit the fastest behavioral shift, where repeatability of standardized bay designs lowers engineering overhead per project.
Light Gauge Framing System Market Segmentation
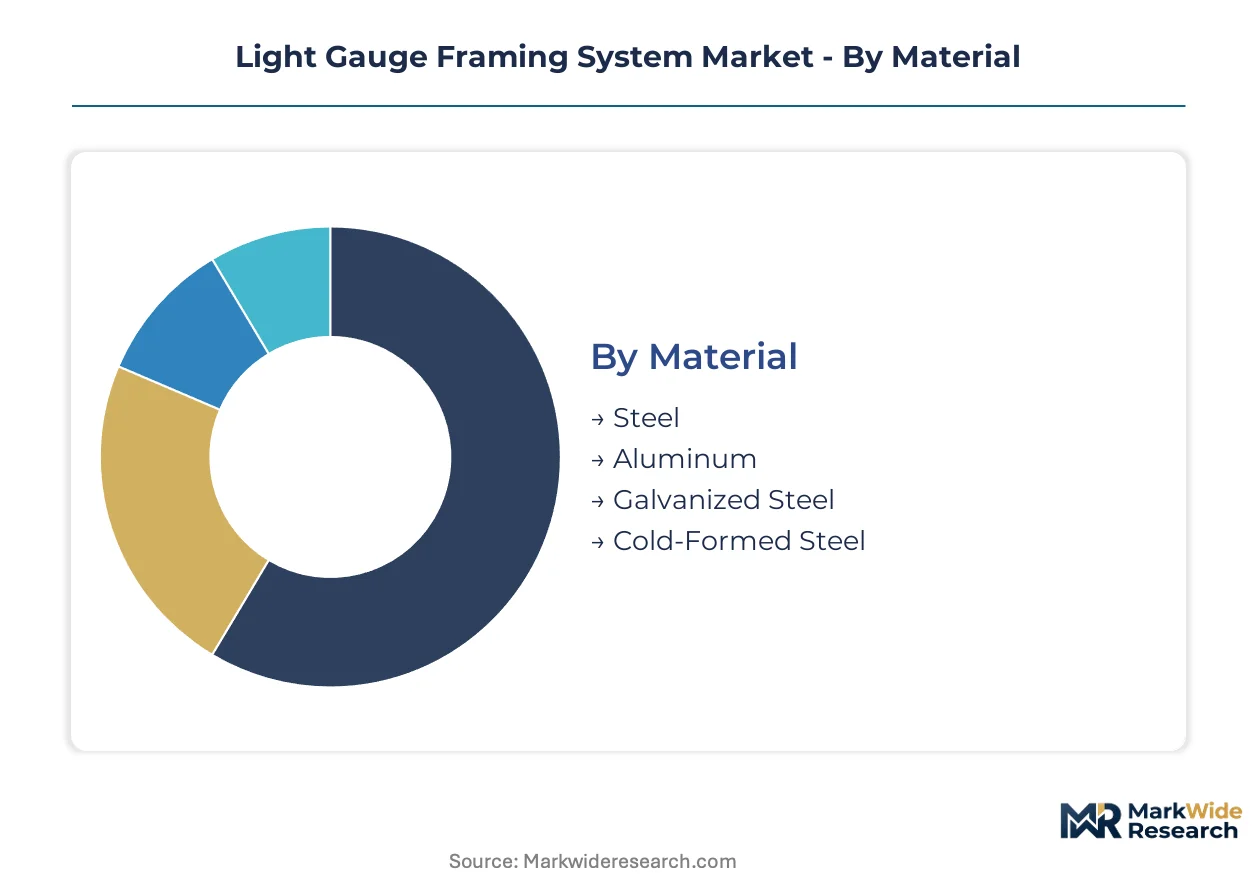
Segmentation in the light gauge framing market reveals how material chemistry, installation methodology, and procurement channel interact to determine project economics. Specification choices cascade through engineering workflows, fabrication lead times, and code compliance costs.
Material:
Feedstock concentration among integrated steel mills and specialty coil coaters shapes regional availability and carbon intensity profiles for each alloy grade.
- Cold-Formed Steel:Thin-gauge sections rolled at ambient temperatures achieve high strength-to-weight ratios through work hardening. Demand clusters in United States mid-rise residential podiums where FEMA seismic provisions and International Code Council wind-load standards favor dimensional stability over timber alternatives.
- Galvanized Steel:Zinc coating layers provide sacrificial corrosion protection for exterior and high-moisture applications. Australian bushfire-resistant construction mandates under Steel Institute Australia certification schemes specify non-combustible galvanized assemblies for wildland-urban interface zones.
- Steel:Uncoated carbon steel sections serve interior structural applications where humidity control eliminates corrosion risk.
- Aluminum:Lightweight extrusions compete in coastal and chemical-exposure environments where galvanic compatibility matters.
Cold-formed steel absorbs the bulk of installed capacity; galvanized steel is expanding most quickly.
Application:
Building typology dictates fire rating requirements, span configurations, and the economic viability of off-site fabrication versus stick-built erection.
- Residential Construction:Multi-family podiums and single-family detached housing employ light gauge studs and joists for non-combustible floor and wall assemblies. United States zoning liberalization in Texas and Florida municipalities permits five-over-one construction types that exploit steel's dimensional consistency.
- Commercial Buildings:Strip retail, office, and distribution centers leverage repetitive bay designs to amortize engineering costs across large footprints. Developers in Arizona and Texas markets bypass traditional general contractor markups through direct procurement from pre-engineered system providers.
- Industrial Structures:Warehouse and light manufacturing facilities require heavier gauge sections for crane loads and equipment anchorage.
- Agricultural Facilities:Barns, storage buildings, and processing plants prioritize corrosion resistance and rapid enclosure.
Residential construction commands the dominant share of fabrication volume; commercial buildings are climbing the fastest as channel compression accelerates.
Installation Type:
The degree of factory completion determines labor productivity, quality control, and the capital intensity required of fabricators.
- Modular:Volumetric units complete with MEP rough-in and interior finishes ship to site for crane stacking. Australian developers facing National Construction Code stringency and compressed site schedules specify modular steel framing for multi-story residential projects.
- Pre-Engineered:Componentized wall panels and trusses arrive cut-to-length with connection hardware pre-installed. United States commercial strip retail chains standardize bay dimensions across portfolios to minimize per-project engineering overhead.
- Prefabricated:Partial assemblies balance transport constraints with factory labor efficiency for mid-sized projects.
- On-Site:Traditional stick framing persists in renovation and remote locations where logistics favor field cutting.
Pre-engineered systems anchor current volume leadership; modular installation is gaining share fastest as labor scarcity intensifies.
End User:
Procurement authority and technical sophistication vary sharply across the value chain, shaping how specifications propagate from design intent to material orders.
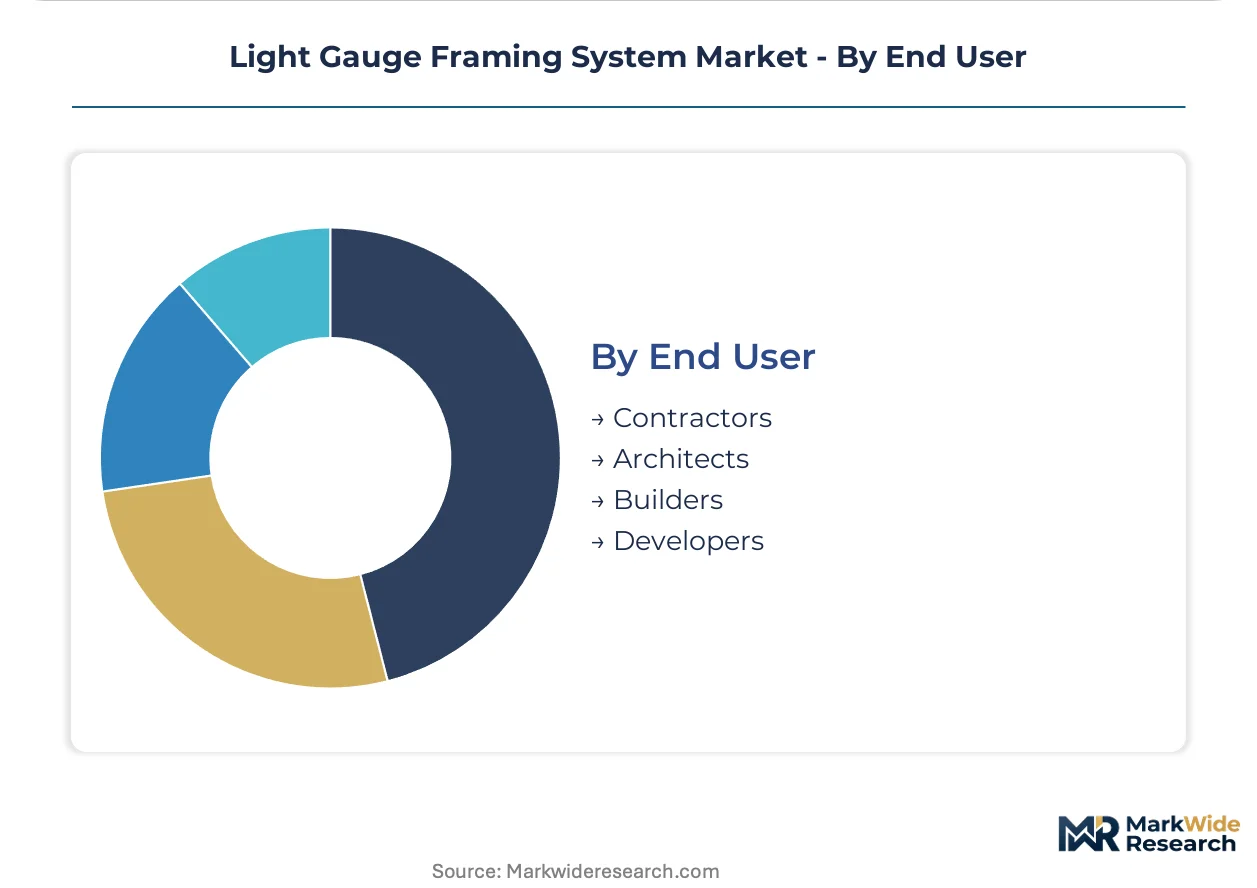
- Developers:Asset owners controlling capital deployment prioritize speed-to-revenue and risk transfer to design-build contractors. Large United States multifamily developers in Sun Belt markets maintain approved fabricator lists based on past cycle performance.
- Contractors:Trade specialists executing erection sequences influence connector selection and bracing configurations based on crew capabilities. Scarcity of cold-formed steel-specific structural engineering talent constrains project throughput for complex lateral systems.
- Architects:Design professionals specify systems early in schematic design, though their influence erodes under design-build delivery.
- Builders:Production homebuilders and custom constructors balance first-cost pressures with warranty exposure.
Developers concentrate specification authority for large projects; contractors are expanding their influence fastest through design-build procurement growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Australia where building code stringency and labor productivity pressures favor off-site fabrication methods. Each geography applies distinct regulatory levers that reshape material specification hierarchies and procurement channel structures.
United States
FEMA seismic provisions and International Code Council wind-load standards drive cold-formed steel adoption in mid-rise residential podiums. Texas and Florida municipalities permit five-over-one construction types that exploit steel's dimensional consistency. Sun Belt developers maintain approved fabricator lists based on past cycle performance.
Germany
REACH compliance and EU Green Deal embodied carbon benchmarks redirect public procurement toward lower-carbon steel grades. German housing authorities mandate Environmental Product Declarations for structural assemblies. The Rhine-Ruhr industrial corridor hosts integrated mills and recycling infrastructure serving pan-European feedstock demand.
Australia
National Construction Code stringency and compressed site schedules accelerate modular installation specifications. Steel Institute Australia certification schemes govern bushfire resistance ratings for wildland-urban interface zones. Sydney and Melbourne developers specify non-combustible galvanized assemblies for multi-story residential projects.
United Kingdom
EMAS requirements embed lifecycle carbon thresholds into steel-intensive construction procurement. Cross-laminated timber retains first-cost advantage in low-rise segments where fire ratings are less stringent. The Midlands manufacturing belt concentrates automated roll-forming equipment serving modular builders.
Canada
Health Canada building codes and provincial energy efficiency standards shape connector detailing requirements. Ontario and British Columbia developers face labor scarcity that favors factory-controlled quality. The Greater Toronto Area anchors pre-engineered system demand for commercial strip retail construction.
Light Gauge Framing System Market Competitive Landscape
United States producers anchor one tier; European specialists hold feedstock concentration through integrated mill networks. The vendor base organizes around three strategic archetypes: electric arc furnace operators with recycling infrastructure, automated equipment specialists controlling design-to-manufacture workflows, and pre-engineered system providers compressing procurement channels. Dominant competitive moves include capacity expansion in low-carbon steel output and strategic partnerships between fabricators and BIM platform providers.
Within the integrated steel tier, Nucor Corporation and ArcelorMittal S.A. exemplify divergent geographic anchoring strategies. FRAMECAD Limited occupies a position among automated equipment specialists. ClarkDietrich Building Systems represents the pre-engineered system provider archetype. These three companies illustrate how scale, technology control, and channel compression define competitive positioning without requiring uniform strategic postures.
| Leading Market Players |
|---|
| ClarkDietrich Building Systems |
| Nucor Corporation |
| ArcelorMittal S.A. |
| Hadley Group |
| FRAMECAD Limited |
| CEMCO |
| SCAFCO Steel Stud Company |
| Kingspan Group Plc |
| Tata Steel Ltd. |
| Others |
Supply & Pricing Matrix
EU Green Deal embodied carbon benchmarks gate qualified supply pools and premium-tier pricing access for fabricators serving European public procurement channels. Developers seeking Environmental Product Declaration compliance face tiered cost structures that reward electric arc furnace feedstock and penalize conventional integrated mill output.
Pricing Analysis
Short lead-time premiums separate urgent project tiers from standard fabrication queues in the United States Sun Belt and Australian metropolitan corridors. Cold-formed steel pricing stratifies across premium certified-grade, standard commercial-grade, and economy spot-inventory tiers, with galvanization thickness and seismic connector bundling as primary differentiation levers. Cost compression in economy-grade galvanized coil is intensifying as zinc price volatility feeds through London Metal Exchange contracts. Production homebuilders exhibit highest price sensitivity, while institutional developers prioritize speed-to-revenue over unit cost.
Supply Chain Analysis
Workforce availability constraints in Germany's Rhine-Ruhr corridor and the United States Southeast reshape coil processing capacity deployment and automation investment timelines. Supply concentrates in Germany, the United States, and Australia, with feedstock draws from integrated mills in Benelux and electric arc furnace operators in North America. Zinc ingot, cold-rolled coil, and protective coating chemicals anchor raw material dependencies. Single-source vulnerability runs through German integrated mill concentration during energy price spikes. Distribution runs through regional fabricator networks serving multi-state project portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The light gauge framing market sits in a technology-transition phase where automated roll-forming equipment paired with BIM platforms displaces manual cutting workflows and fragmented regional fabricators.
For Market Incumbents: Extend electric arc furnace capacity in low-carbon steel grades to capture EU Green Deal procurement mandates before integrated mill competitors retrofit. Anchor backward integration into zinc coating operations to buffer margin compression from London Metal Exchange volatility. Prioritize certification investment in Steel Institute Australia and EMAS compliance to lock out regional challengers.
For New Entrants and Emerging Players: Modular builders in Texas and Florida present the most penetrable channel partner type for automated equipment partnerships. Target five-over-one residential podium specifications where zoning liberalization and FEMA seismic standards favor cold-formed steel over timber. Pursue direct procurement relationships with Sun Belt developers bypassing traditional general contractor markups.
For Investors and Strategic Acquirers: Nucor Corporation's capacity announcements in low-carbon output are the leading indicator that electric arc furnace economics are crossing threshold viability for premium-tier pricing capture. The five-to-ten-year viability window favors equipment specialists controlling design-to-manufacture workflows over commodity coil processors. Watch for consolidation signals when regional fabricators face automation capex requirements beyond standalone balance sheet capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Arc Furnace Capacity Expansion | EU Green Deal procurement thresholds favor low-carbon steel grades from Nucor and ArcelorMittal recycling infrastructure. |
| Automated Roll-Forming Equipment Deployment | FRAMECAD systems compress design-to-manufacture cycles for modular builders in Australian and United States markets. |
| BIM Platform Integration Partnership | Parametric software convergence eliminates manual cutting errors and reduces on-site labor hours for ClarkDietrich fabricators. |
| Galvanized Coating Backward Integration | In-house zinc application buffers margin compression from London Metal Exchange price volatility on fixed-price contracts. |
| Steel Institute Australia Certification Investment | Bushfire-resistant construction mandates in wildland-urban interface zones create specification pull for non-combustible assemblies. |
Research Methodology
Multi-period observation of coil processing capacity utilization, zinc price volatility, and modular construction permit filings anchored the trend analysis, supplemented by interviews with plant managers at regional fabricators, procurement leads at United States multifamily developers, technical directors at automated equipment suppliers, and structural engineers specializing in cold-formed steel design. Secondary validation drew from SEC 10-K filings of integrated steel producers, Steel Institute Australia certification registries, FEMA seismic provision updates, and EU Green Deal public procurement databases. Bottom-up project pipeline tracking and top-down steel consumption models were triangulated against fabrication equipment shipment records.
Segment-weighting across material chemistry, installation methodology, application vertical, and end-user procurement authority shaped the analytical framework over the projection horizon. Cold-formed steel, galvanized steel, aluminum, and uncoated carbon steel grades were modeled separately with distinct carbon intensity profiles and code compliance cost structures. CAGRs were derived from elasticity-adjusted demand curves incorporating zoning liberalization timelines and labor productivity substitution rates. Forecast inputs included FEMA seismic map revisions, REACH compliance cost trajectories, and National Construction Code amendment schedules.
Caveats apply where zinc price spikes, energy cost shocks in German integrated mills, or timber substitution cost advantages in low-rise residential segments could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and automation capex deployment rates that may diverge from realized paths. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Tubular Motors Market
Electro-Mech Systems
Elevator Door-Motor Market
Electro-Mech Systems
Rigid Metal Electrical Conduit Market
Electro-Mech Systems
Automatic Slack Adjusters Market
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
HVAC Relay Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Movable Scaffolding System Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Wiring Duct Market
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Rodless Cylinders Market