
 Escalators and Moving Walkways Market | 2026-2036
Escalators and Moving Walkways Market Size, Share, and Industry Trends Forecast 2026-2036
Escalators and Moving Walkways Market Analysis
Transit infrastructure agencies are rotating toward airport and metro modernization as the dominant buyer archetype, displacing pure retail-led procurement cycles. Otis Worldwide Corporation leverages its service-installed base to capture replacement contracts across North American transit hubs. KONE Corporation sustains R&D intensity in smart-system escalators with predictive maintenance architectures. Schindler Group anchors European demand through EN 115-certified heavy-duty units for high-traffic rail terminals.
Escalators and moving walkways are continuous-loop, chain-driven or belt-driven passenger transport systems with step widths typically ranging from 600 mm to 1,000 mm and incline angles of 0° to 35°. These systems move pedestrians between building levels or across extended horizontal distances in commercial and transit environments. The product type dimension shows escalators occupying the dominant revenue pool while moving walkways capture premium margins in airport concourse applications. Smart systems technology is displacing mechanical drives as the fastest-growing segment, though electric traction units still lead total volume due to retrofit compatibility. Installation type splits heavily toward modernization and maintenance in mature economies, with new installation concentrated in emerging metro networks.
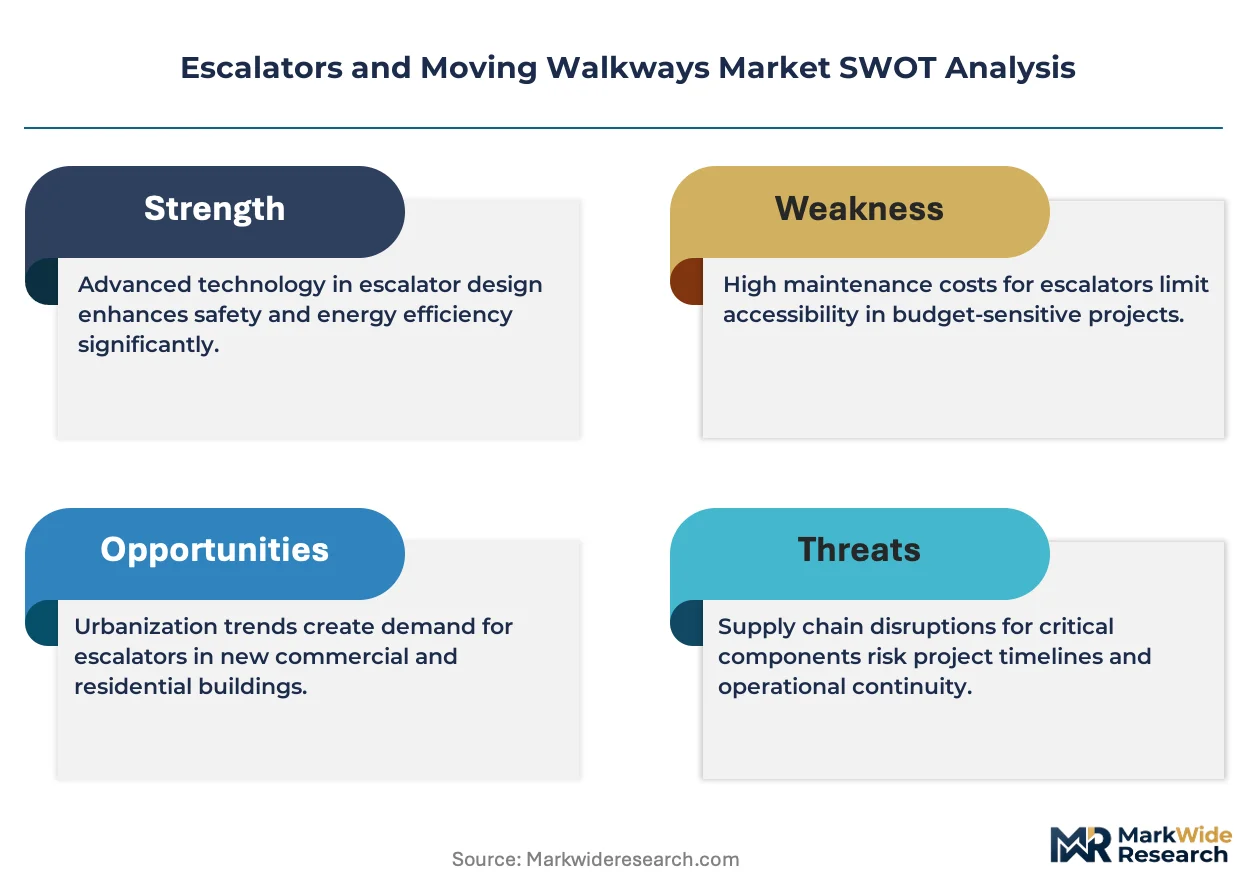
The EU Machinery Directive, EN 115 safety standards, and the US ASME A17.1 code collectively shape product certification timelines and barrier-to-entry height for non-compliant manufacturers. China's GB 16899 standard and India's BIS certification requirements add further compliance layers for suppliers targeting Asia-Pacific procurement. Stakeholders must monitor how AI-integrated predictive maintenance clauses in transit authority tenders reshape warranty structures and long-term service revenue models.
Market Dynamics
Transit authority procurement cycles are compressing warranty periods and mandating predictive maintenance clauses, forcing manufacturers to restructure long-term service revenue models around uptime guarantees rather than scheduled maintenance contracts.
Growth Catalysts
- Underground Metro Expansion:Asia-Pacific transit agencies are awarding multi-unit contracts for new-build installations in rapidly urbanizing corridors. China and India concentrate the bulk of this demand.
- EN 115 Safety Standards:The EU Machinery Directive's tightened certification requirements are accelerating replacement cycles for aging units in European airports and rail terminals.
- Predictive Maintenance Architectures:AI-integrated sensor networks are enabling condition-based monitoring that reduces unplanned downtime and extends equipment lifecycles.
Market Restraints
- Steel and Copper Input Volatility:Escalator step chains and drive motors depend on commodity metals whose price swings compress margin predictability for manufacturers.
- Certification Timeline Friction:GB 16899 compliance in China and BIS certification in India add 6-12 month approval delays for non-domestic suppliers.
- Moving Walkway Substitution:Autonomous shuttles and people-mover systems in airport concourses are capturing horizontal transport demand that moving walkways previously served.
Strategic Opportunities
- India Metro Build-Out:Tier-2 cities including Pune, Kochi, and Nagpur are launching inaugural metro lines with escalator specifications favoring heavy-duty units.
- CSRD Reporting Mandates:The EU Corporate Sustainability Reporting Directive is creating demand for energy-efficient regenerative drive systems that qualify for green procurement preferences.
- Convergence of IoT and Edge Computing:Real-time vibration analysis combined with localized processing is opening subscription-based maintenance contracts for transit operators.
Industry Challenges
- Skilled Installation Technician Shortage:Precision alignment of escalator trusses and step-band synchronization requires certified riggers whose training pipelines have not kept pace with project volume.
- Legacy Control System Integration:Modernization projects in North American transit hubs must interface with 1980s-era relay logic, complicating retrofit timelines and commissioning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Escalators and Moving Walkways Market |
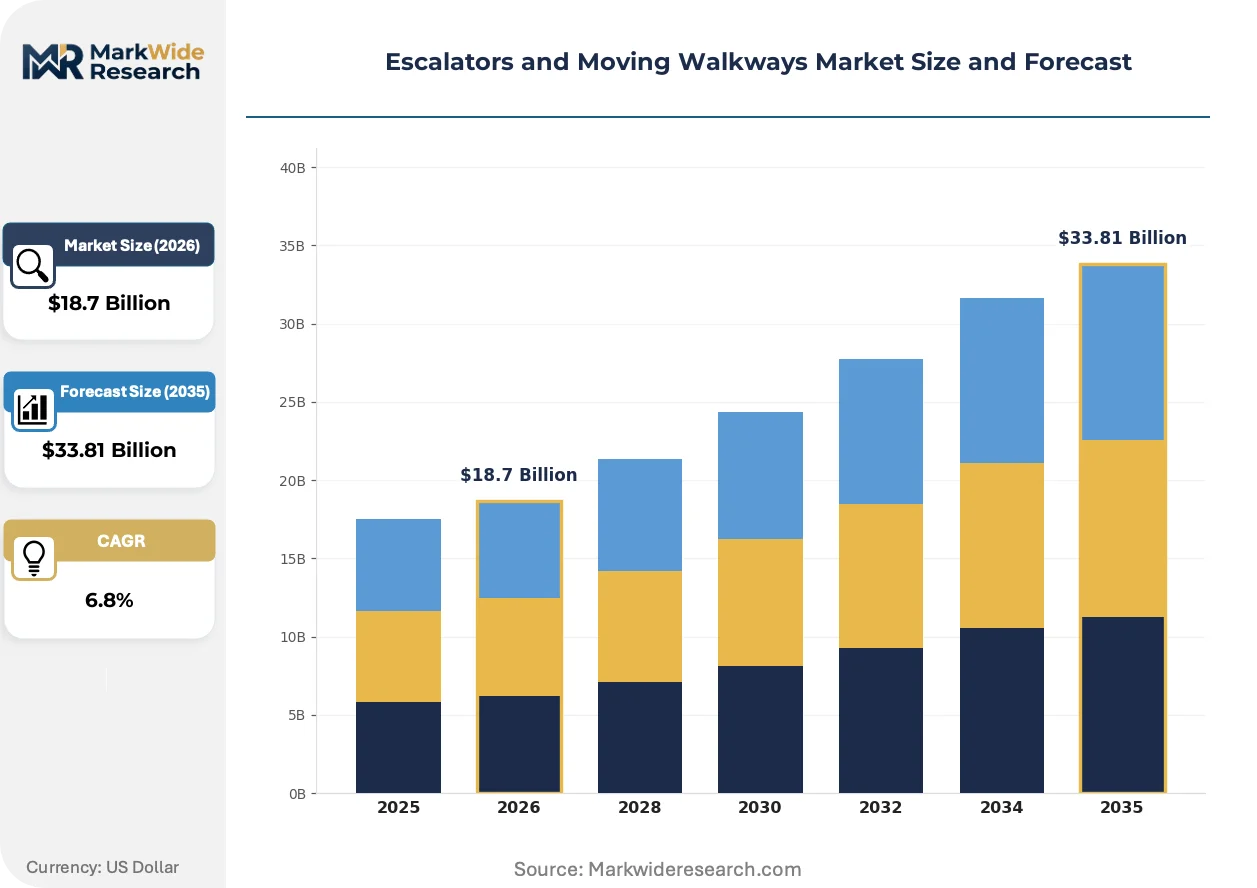
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Escalators, Moving Walkways, Inclined Lifts, Vertical Transport Systems End User: Retail Spaces, Airports, Hospitals, Commercial Buildings Installation Type: New Installation, Modernization, Replacement, Maintenance Technology: Mechanical, Hydraulic, Electric, Smart Systems |
| Companies Covered | Otis Worldwide Corporation, KONE Corporation, Schindler Group, Mitsubishi Electric Corporation, Fujitec Co., Ltd., Toshiba Corporation, Hitachi Ltd., ThyssenKrupp AG, Hyundai Elevator Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Escalators and Moving Walkways Market Emerging Trajectories
Mechanical drive architectures are giving way to intelligent systems that embed diagnostics directly into step chains and handrail drives, compressing the traditional separation between equipment supplier and service provider.
Magnetic levitation step propulsion is decomposing the century-old chain-and-sprocket paradigm by eliminating physical contact between moving parts. Dubai International Airport and Singapore Changi are piloting mag-lev units in high-traffic concourse segments. The technology is decomposing the aftermarket parts revenue model by reducing wear-component replacement frequency by an order of magnitude.
REACH restrictions on perfluorinated compounds are forcing lubricant reformulation for escalator step chains and guide rails. The European Chemicals Agency's 2023 amendment to Annex XVII limits long-chain PFAS in industrial applications. Manufacturers serving EU transit authorities are accelerating bio-based synthetic lubricant qualification to maintain CE marking compliance.
Transit authorities are unbundling equipment purchase from 20-year service contracts, fragmenting the vendor-customer relationship that previously locked in exclusive maintenance providers. Airport procurement departments in Germany and France are now running separate tenders for installation and aftermarket service. This pattern is most visible in high-frequency rail terminals where uptime penalties have sharpened buyer negotiating leverage.
Escalators and Moving Walkways Market Segmentation
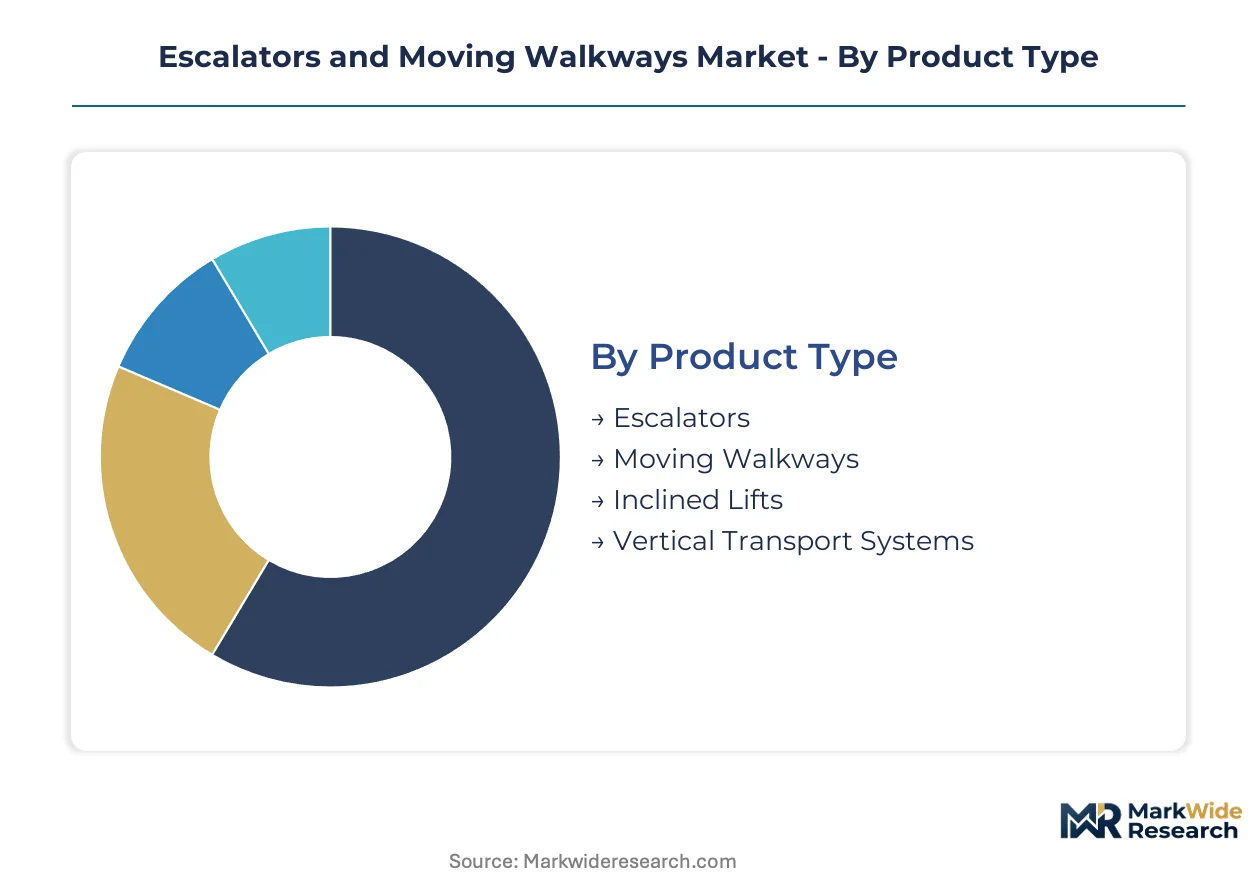
Segmentation in the escalators and moving walkways market reveals distinct procurement patterns across transit authorities, commercial developers, and facility managers. Each dimension—product type, end user, installation mode, and technology—carries different margin structures and compliance requirements that reshape supplier positioning.
Product Type:
Escalators dominate domestic procurement cycles in China and India where metro build-outs concentrate demand, while moving walkways skew toward export-led airport projects in the Gulf states and Southeast Asian hubs.
- Escalators:Continuous-loop step systems with 600-1,000 mm tread widths and 0°-35° incline angles. Chinese metro authorities in Shenzhen and Chengdu specify heavy-duty units for high-frequency underground corridors where daily ridership exceeds 50,000 passengers per station.
- Moving Walkways:Horizontal or shallow-incline belt-driven passenger transport spanning 50-150 meter distances. Dubai International Airport and Singapore Changi deploy premium-margin units in concourse connectors where walking distances between gates exceed 800 meters.
- Inclined Lifts:Wheelchair-accessible platform systems for low-rise vertical transport. German rail terminals specify these under EU accessibility mandates for stations with heritage architecture constraints.
- Vertical Transport Systems:Integrated elevator-escalator combinations for mixed-use towers. Mumbai commercial developers favor these for podium-level retail-to-office transitions.
Escalators command the established base. The steepest expansion runs through moving walkways.
End User:
Application-driven cost tiers separate premium-specification transit installations from standard commercial deployments, with warranty structures and service contract durations varying significantly across buyer archetypes.
- Retail Spaces:Shopping mall and department store installations prioritizing aesthetic integration and energy efficiency. Indian mall operators in Bangalore and Hyderabad now mandate regenerative drive systems to offset electricity costs in air-conditioned environments.
- Airports:High-availability specifications with 99.5% uptime guarantees and 20-year service attachments. Frankfurt Airport and Charles de Gaulle unbundle equipment purchase from maintenance contracts under sharpened procurement scrutiny.
- Hospitals:Infection-control specifications with antimicrobial handrail materials and wider 1,000 mm steps for gurney transport. Japan's aging hospital infrastructure drives replacement demand in Tokyo and Osaka medical districts.
- Commercial Buildings:Standard-duty units for office lobby and atrium applications. Brazilian commercial developers in São Paulo favor cost-optimized electric traction units for mid-rise towers.
Airport procurement concentrates the premium tier. Commercial buildings anchor volume scale.
Installation Type:
Mature economies tilt toward lifecycle services while emerging markets concentrate new-build capacity, creating divergent revenue models across geographic maturity curves.
- New Installation:Greenfield deployment in expanding metro networks and airport terminals. India's Pune Metro and Kochi Metro award turnkey contracts with 24-month commissioning timelines.
- Modernization:Control system upgrades and drive replacements in aging infrastructure. Chicago Transit Authority and New York MTA prioritize step-band and handrail modernization over full unit replacement.
- Replacement:Full truss removal and reinstallation where structural life expires. London Underground's Northern Line stations execute weekend shutdown replacements to minimize service disruption.
- Maintenance:Scheduled and predictive service contracts. Otis and KONE compete for 10-15 year exclusive maintenance agreements at North American transit hubs.
Maintenance locks in recurring revenue. Modernization is climbing the fastest as infrastructure ages.
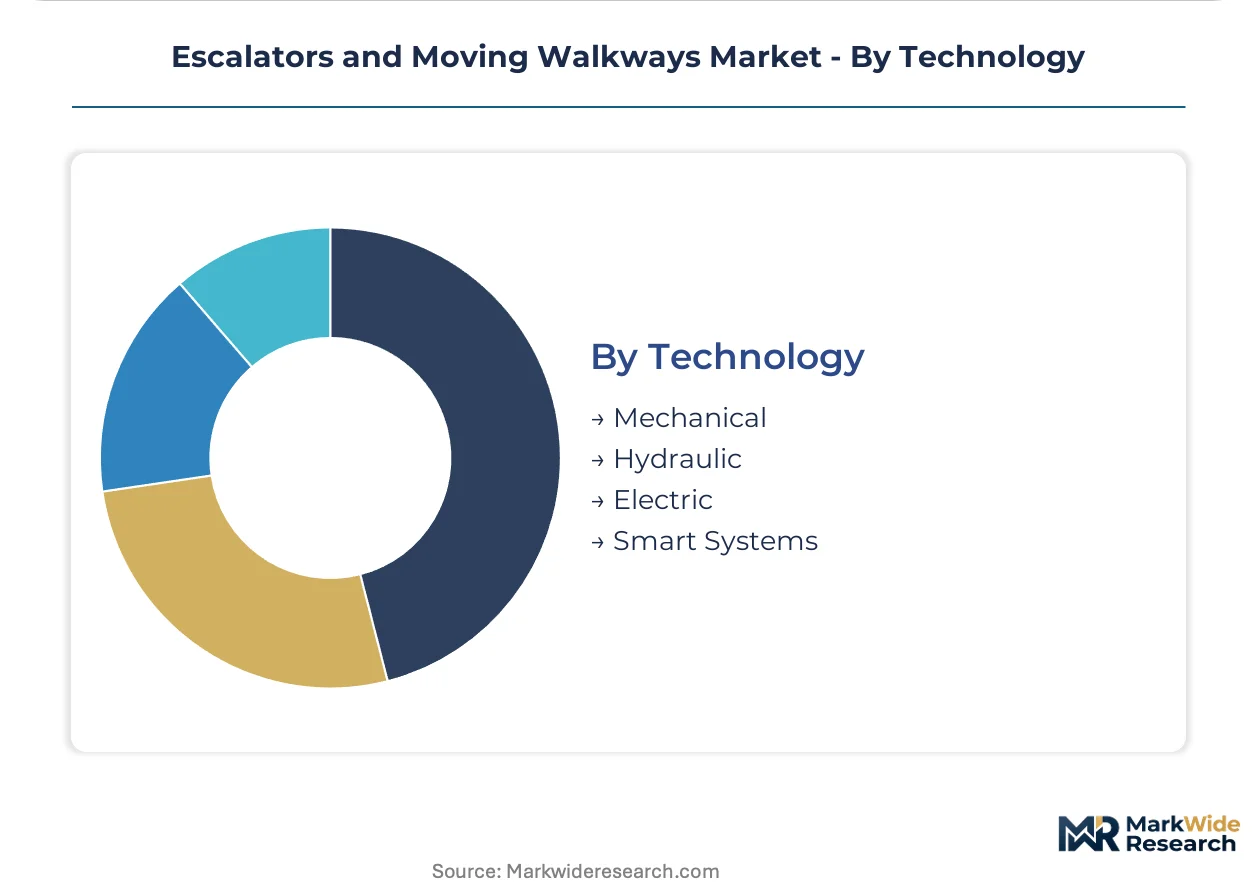
Technology:
Mechanical and electric architectures retain retrofit compatibility advantages while smart systems capture specification preference in new tenders requiring predictive maintenance integration.
- Mechanical:Chain-and-sprocket drive systems with proven field reliability. Legacy units in European rail terminals remain serviceable through parts availability guarantees.
- Hydraulic:Piston-driven systems for low-rise and heavy-load applications. Limited new deployment due to energy efficiency disadvantages versus electric alternatives.
- Electric:AC motor drives with regenerative braking capability. Chinese manufacturers optimize these for cost-sensitive metro procurement in tier-2 cities.
- Smart Systems:AI-integrated sensor networks enabling condition-based monitoring. Dubai and Singapore airport pilots embed vibration analysis and thermal imaging for zero-downtime operations.
Electric traction dominates installed volume. Smart systems gain share fastest in new specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss engineering houses export heavy-duty transit units to Middle Eastern airport authorities, while Chinese manufacturers supply cost-optimized escalators to India's expanding metro networks.
China
Shenzhen and Chengdu metro authorities specify heavy-duty escalators for underground corridors exceeding 50,000 daily passengers per station. GB 16899 certification requirements from SAMR add 6-12 month approval timelines for imported components. Shanghai's Yangtze River Delta cluster hosts domestic manufacturers optimizing electric traction units for tier-2 city procurement.
India
Pune, Kochi, and Nagpur metro corporations launch inaugural lines with escalator tenders favoring 24-month commissioning schedules. BIS certification mandates from the central standards body create compliance friction for non-domestic suppliers. Mumbai's commercial developers specify vertical transport systems for podium-level retail-to-office transitions in mixed-use towers.
Germany
Frankfurt Airport and Deutsche Bahn terminals unbundle equipment purchase from 20-year maintenance contracts under sharpened procurement scrutiny. REACH restrictions from ECHA force lubricant reformulation for step chains to maintain CE marking compliance. Bavaria's industrial fabricators anchor European demand for EN 115-certified heavy-duty rail terminal units.
United States
Chicago Transit Authority and New York MTA prioritize step-band modernization over full unit replacement in aging infrastructure. ASME A17.1 code compliance shapes certification timelines for control system upgrades. The Midwest corridor concentrates service-installed base competition for 10-15 year exclusive maintenance agreements.
United Arab Emirates
Dubai International Airport pilots magnetic levitation escalators in high-traffic concourse segments, eliminating chain-and-sprocket wear components. MOHAP building safety regulations govern installation standards for vertical transport in new terminal expansions. Dubai's aviation cluster drives premium-margin moving walkway demand for 800-meter gate connectors.
Escalators and Moving Walkways Market Vendor Landscape
Listed leaders compete with private specialists across capitalization tiers, with publicly traded conglomerates dominating service-installed base leverage while family-owned fabricators capture niche modernization contracts. The vendor base concentrates around elevator-escalator conglomerates with captive maintenance networks. Three archetypes define positioning: full-service conglomerates with predictive maintenance platforms, regional specialists in heavy-duty transit specifications, and cost-optimized manufacturers serving emerging market new-build. Competitive moves center on exclusive maintenance contract capture and predictive maintenance technology licensing.
Among Japanese electrical conglomerates, Mitsubishi Electric Corporation and Hitachi Ltd. occupy positions in the smart-systems tier, while Fujitec Co., Ltd. exemplifies the specialist archetype focused on transit authority specifications. These three anchors represent distinct geographic and structural approaches to the market.
| Leading Market Players |
|---|
| Otis Worldwide Corporation |
| KONE Corporation |
| Schindler Group |
| Mitsubishi Electric Corporation |
| Fujitec Co., Ltd. |
| Toshiba Corporation |
| Hitachi Ltd. |
| ThyssenKrupp AG |
| Hyundai Elevator Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
EN 115 safety certification gates both supplier qualification and price differentiation simultaneously, as transit authorities in Frankfurt and Paris mandate CE-marked heavy-duty units while tier-2 Indian metros optimize for cost-sensitive electric traction alternatives. This regulatory bifurcation concentrates margin capture among certified European fabricators while compressing pricing power for non-compliant manufacturers seeking airport procurement cycles.
Pricing Analysis
Next-generation mag-lev escalators command 40-60% premiums over current-gen electric traction units, while prior-gen mechanical drives trade at discount tiers in emerging market new-build. Three-tier pricing structure across premium smart-systems, standard electric traction, and economy mechanical levels reflects certification grade and predictive maintenance bundling. Cost compression in the economy tier is intensifying because Chinese manufacturers optimize for scale in tier-2 city metro procurement. Airport authorities exhibit lowest price sensitivity due to uptime penalty clauses, while Indian commercial developers demonstrate highest sensitivity to capital expenditure per unit.
Supply Chain Analysis
Strait of Malacca transit underwrites steel and copper raw material flows for step chain and drive motor fabrication, creating logistics vulnerability for European and North American assembly plants. Manufacturing concentrates in China, Germany, and Japan, with Shanghai's Yangtze River Delta cluster feeding cost-optimized electric traction units to India's metro build-out. Supply chains draw from specialty steel mills in South Korea, copper smelters in Chile, and rare-earth magnet processors in China. Single-source vulnerability in permanent magnet motors for regenerative drives threatens delivery timelines. Distribution runs through OEM captive service networks and authorized installer partnerships for commissioning and aftermarket capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transit infrastructure investment cycles are recovering from pandemic-depressed procurement, with Asia-Pacific metro authority capital programs driving equipment demand normalization across the analysis window.
For Market Incumbents: Consolidate predictive maintenance platform capabilities through sensor network integration and edge computing partnerships, defending against autonomous shuttle substitution in airport horizontal transport. Secure exclusive 15-year service contracts at North American transit hubs before procurement unbundling spreads. Vertical integration into step chain forging reduces commodity metal cost volatility exposure. For New Entrants and Emerging Players: Predictive maintenance software licensing gaps where Otis and KONE under-serve tier-2 Indian metro corporations present white-space entry points. Target modernization contracts in 1980s-era North American transit infrastructure where legacy control system integration expertise is scarce. Pursue partnership-based go-to-market models with regional installation contractors lacking OEM affiliation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across smart-systems technology development as AI-integrated diagnostics commoditize sensor hardware. Long-term viability favors asset-light platform licensors over capital-heavy manufacturers. Acquisition target archetype: regional specialists with EN 115 certification and captive maintenance bases in underserved European rail terminals. Signal to watch: transit authority tender unbundling velocity as indicator of service revenue fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Licensing | AI-integrated sensor networks enable subscription revenue capture at Dubai and Singapore airports. |
| Mag-Lev Technology Pilot Partnerships | Dubai International Airport trials eliminate wear-component replacement and decompose aftermarket models. |
| Backward Integration into Step Chain Forging | Captive steel processing mitigates commodity volatility for manufacturers serving EN 115-certified tenders. |
| Modernization-First Market Entry | Chicago Transit Authority and New York MTA prioritize control system upgrades over full replacement. |
| CSRD-Aligned Regenerative Drive Development | EU Corporate Sustainability Reporting Directive creates green procurement preference for energy-efficient systems. |
Methodological Framework
Initial hypotheses were tested against primary input from transit authority procurement directors, escalator maintenance technicians, airport facilities managers, and OEM regional sales heads, and refined through secondary validation against customs trade data, SEC 10-K equipment disclosures, EN 115 certification registries, and metro authority tender documentation. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows.
Variance-decomposition across product type, installation mode, technology generation, and end-user archetype shaped the analytical framework over the projection horizon. CAGRs were derived from installed base turnover rates and new-build procurement pipelines. Forecast inputs incorporated steel and copper price trajectory assumptions, certification timeline friction parameters, and predictive maintenance adoption curves.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement and China's GB 16899 administration; material policy shifts would require re-modeling. Commodity volatility, certification delays, and autonomous transport substitution pose revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Elevator Door-Motor Market
Electro-Mech Systems
Movable Scaffolding System Market
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
Automatic Slack Adjusters Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market
Electro-Mech Systems
Wiring Duct Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Rodless Cylinders Market
Electro-Mech Systems
Rigid Metal Electrical Conduit Market
Electro-Mech Systems
Tubular Motors Market
Electro-Mech Systems
HVAC Relay Market