
 Electric Winch Market | 2026-2036
Electric Winch Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Winch Market Analysis
EU machinery safety directives is expanding compliance costs for European winch manufacturers while simultaneously creating barriers for non-certified imports. WARN Industries leverages in-house motor manufacturing to sustain margin control across North American distribution channels. Ramsey Winch anchors its position through deep specialization in military and utility-grade recovery systems. Ingersoll Rand competes on integrated pneumatic-electric hybrid architectures for industrial material handling.
An electric winch converts electrical energy into mechanical torque through a sealed motor driving a drum or planetary gear reduction system, typically rated by line pull capacity, duty cycle percentage, and IP enclosure class against moisture and particulate ingress. Its primary industrial purpose centers on controlled load movement, vehicle recovery, and marine anchoring where precise tension management replaces manual or combustion-powered alternatives. Heavy-duty winches dominate margin pools in offshore and mining applications where failure costs exceed equipment price multiples. Portable winches represent the fastest-growing product configuration as construction contractors and overland vehicle owners prioritize field-deployable pulling capacity without permanent mounting infrastructure.
FCC electromagnetic compatibility standards govern wireless remote control integration for US-sold winches, while CE marking mandates comprehensive machinery risk assessment under the EU Machinery Directive for European market access. China's GB standards through SAMR enforce motor efficiency tiers that reshape sourcing requirements for manufacturers exporting to Asia-Pacific end users. Stakeholders must monitor evolving battery-electric vehicle recovery specifications and offshore wind installation load requirements as these applications redefine duty cycle and corrosion resistance benchmarks.
Market Dynamics
The EU F-Gas Regulation is accelerating displacement of hydraulic winch systems across European maritime and offshore infrastructure, compressing the technology transition timeline for port operators and vessel owners while elevating motor efficiency requirements for equipment suppliers.
Growth Catalysts
- Offshore wind installation scale-up:Floating turbine foundation deployment requires precision load handling at depth, pulling heavy-duty electric winch specifications into the 50-ton-plus line pull category.
- Battery-electric vehicle recovery specifications:EV manufacturers mandate dedicated low-speed high-torque recovery protocols that internal combustion winches cannot satisfy, opening certified electric winch procurement channels.
- CE marking machinery compliance:The EU Machinery Directive's risk assessment mandates create preferential procurement pathways for certified European suppliers in North Atlantic maritime corridors.
Market Restraints
- Permanent magnet motor material concentration:Rare earth processing capacity concentrates in China, exposing non-integrated winch manufacturers to supply disruption and input cost volatility.
- Hydraulic system installed base inertia:Existing offshore platform infrastructure carries sunk capital in hydraulic power units, delaying electric replacement cycles despite regulatory pressure.
- IP enclosure certification timelines:IP67 and IP69K testing protocols extend product launch schedules by 8-14 months for marine-grade winch variants.
Strategic Opportunities
- Modular portable winch platforms:Construction contractors in Norway's North Sea cluster demand field-deployable units without permanent mounting, opening rental and lease distribution channels.
- Synthetic rope integration:High-modulus polyethylene cable is expanding into heavy-lift applications previously reserved for steel wire, enabling weight reduction and corrosion immunity.
- Wireless remote control standardization:FCC electromagnetic compatibility mandates are converging with EU radio equipment directives, creating unified product platforms for transatlantic suppliers.
Industry Challenges
- Embedded software validation:Variable frequency drive firmware requires functional safety certification under IEC 61508, extending engineering headcount requirements and project timelines.
- Legacy vessel electrical infrastructure:Older offshore support vessels lack sufficient generator capacity for high-amperage electric winch operation, forcing costly shipyard retrofits or hybrid system design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Winch Market |
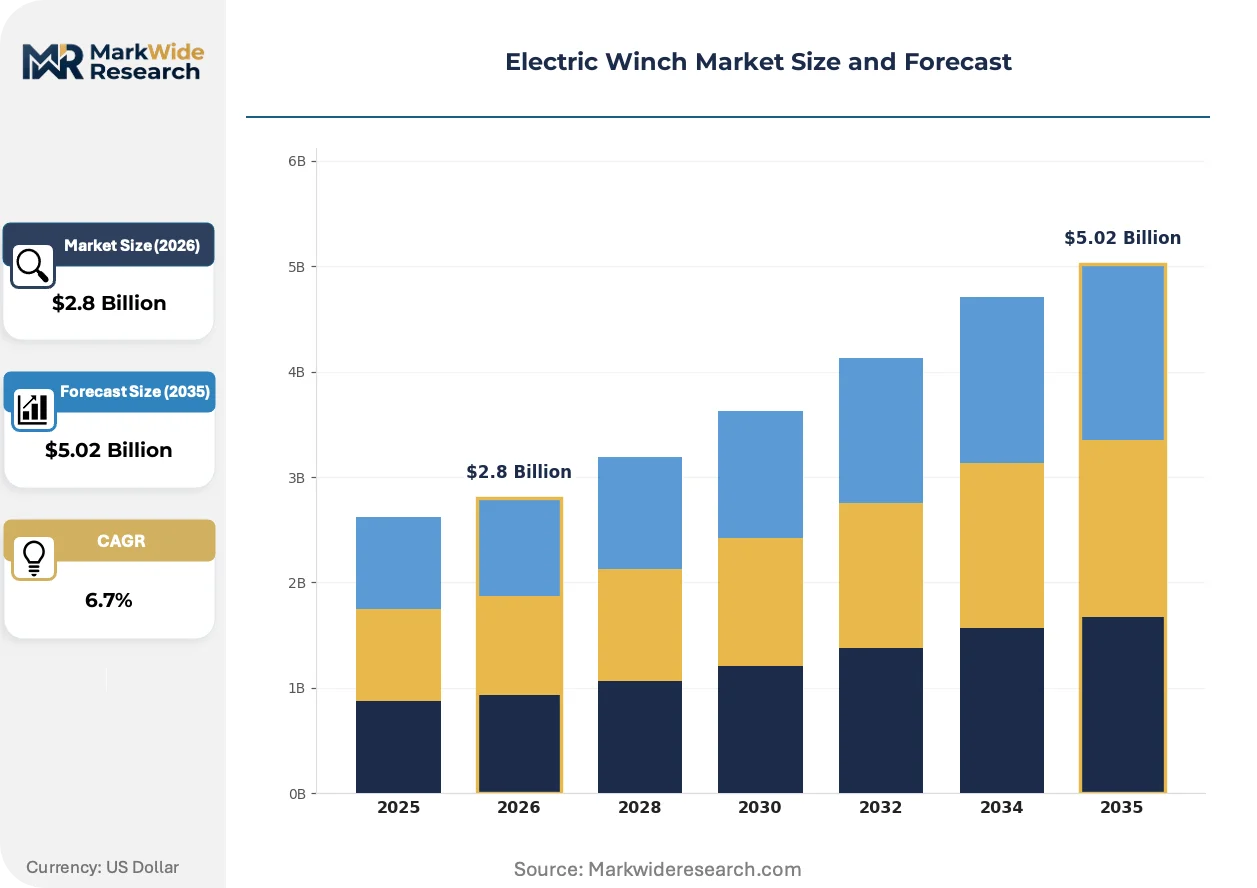
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Winches, Stationary Winches, Mini Winches, Heavy-Duty Winches End User: Construction, Marine, Automotive, Mining Installation Type: Fixed, Mobile, Integrated, Standalone Power Rating: Below 1 Ton, 1-5 Tons, 5-10 Tons, Above 10 Tons |
| Companies Covered | Ramsey Winch, Mile Marker Industries, WARN Industries, Thern, Harken, Ingersoll Rand, COMEUP Industries, Winchmax, Superwinch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Winch Market Emerging Trajectories
Permanent magnet synchronous motor technology is compressing winch footprint and energy consumption while expanding duty cycle ratings, forcing incumbent wound-rotor designs into commodity positioning.
Brushless DC motor architecture is expanding into mid-duty industrial winch categories previously dominated by AC induction systems. Warehouse automation integrators in Germany and the Netherlands are specifying these units for continuous-cycle material handling. The technology is compressing maintenance intervals and enabling predictive monitoring integration that wound-rotor alternatives cannot support.
REACH substance restrictions on hexavalent chromium plating are forcing marine winch manufacturers toward ceramic coating and stainless steel drum alternatives. The regulation eliminates traditional corrosion protection for North Sea and Baltic operators. Suppliers with pre-qualified alternative surface treatments capture specification preference in Norwegian and Danish procurement channels.
Rental fleet operators are unbundling after-sales service from equipment purchase, compressing OEM service revenue while expanding third-party maintenance certification demand. Construction equipment lessors in the United States and United Kingdom now require component-level replaceability and open diagnostic protocols. This procurement pattern favors modular winch architectures over sealed integrated units in commercial vehicle recovery and temporary lifting applications.
Electric Winch Market Segmentation
Electric winch procurement patterns diverge sharply across operational contexts, with capital intensity, duty cycle demands, and mounting infrastructure requirements reshaping supplier priorities. Segment boundaries increasingly blur as modular architectures enable cross-category deployment.
Product Type:
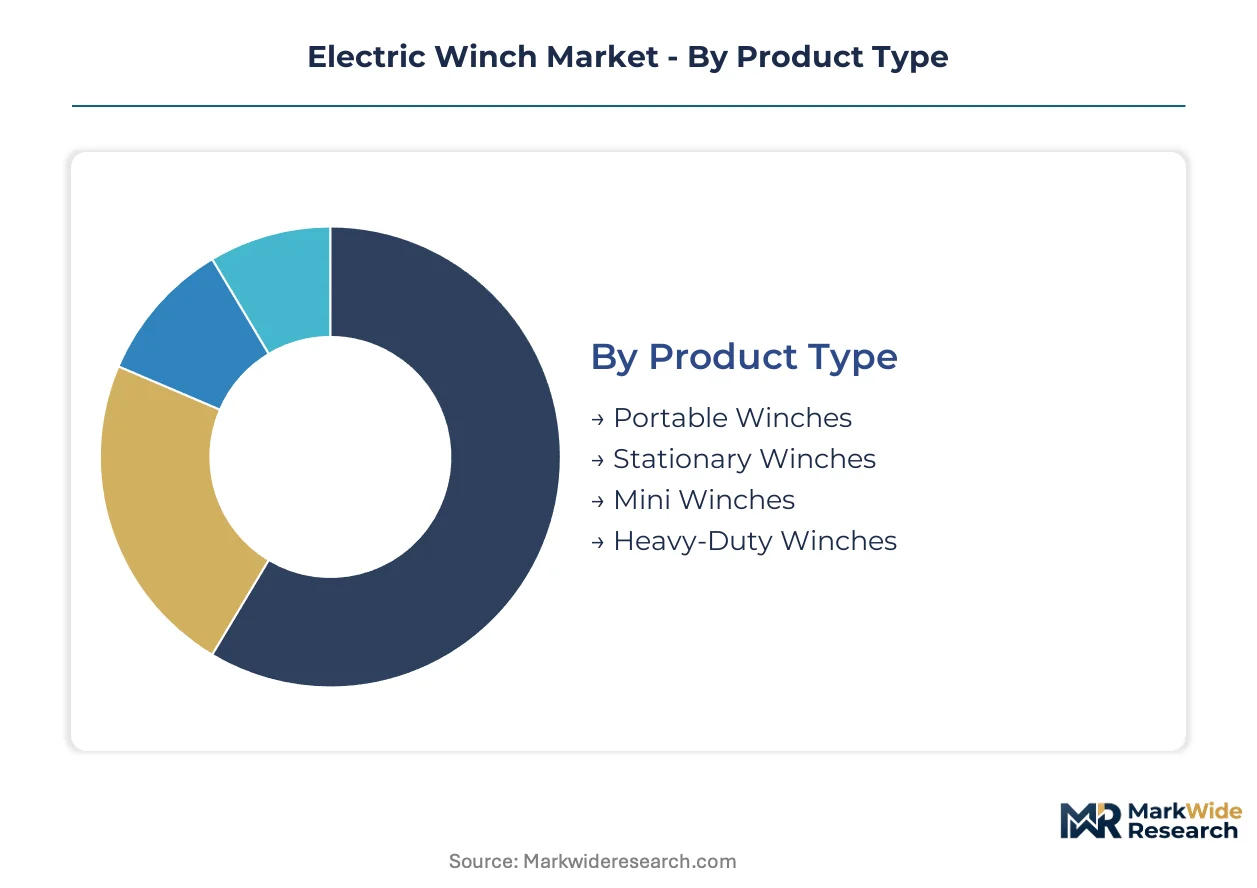
Heavy-duty configurations demand the steepest upfront capital commitment, driven by sealed motor assemblies, planetary reduction systems, and IP-rated enclosures for subsea or mining deployment.
- Heavy-Duty Winches:These units integrate permanent magnet synchronous motors with multi-stage planetary gears rated for continuous operation in offshore oil platform maintenance. Norway's North Sea cluster and adjacent North Atlantic maritime corridors concentrate procurement for floating turbine foundation deployment, where 50-ton-plus line pull ratings justify premium positioning.
- Portable Winches:Field-deployable units prioritize battery-electric compatibility and rapid rigging without permanent mounting infrastructure. Construction contractors in Norway's North Sea cluster and overland vehicle owners across Germany and the Netherlands are driving specifications toward synthetic rope integration and wireless remote control standardization.
- Stationary Winches:Fixed-installation industrial units dominate warehouse automation integrator specifications in Germany and the Netherlands for continuous-cycle material handling.
- Mini Winches:Compact DC-powered units serve recreational vehicle recovery and light utility applications where space constraints override pull capacity requirements.
Heavy-duty winches absorb the bulk of installed capacity; portable winches are expanding most quickly.
End User:
Application-specific duty cycles and regulatory exposure create divergent margin profiles across vertical markets.
- Marine:Offshore support vessels and port infrastructure require IP67 and IP69K certifications under EU F-Gas Regulation pressure, with REACH substance restrictions on hexavalent chromium plating forcing ceramic coating adoption for North Sea operators.
- Construction:Rental fleet operators in the United States and United Kingdom now mandate component-level replaceability and open diagnostic protocols, favoring modular architectures over sealed integrated units.
- Automotive:Battery-electric vehicle manufacturers mandate dedicated low-speed high-torque recovery protocols that internal combustion winches cannot satisfy, opening certified electric winch procurement channels.
- Mining:Underground operations specify explosion-proof motor housings and reinforced drum assemblies for continuous material extraction in high-particulate environments.
Marine applications command the highest specification density; automotive recovery protocols are climbing the fastest.
Installation Type:
Mounting flexibility determines aftermarket service revenue potential and fleet utilization rates.
- Fixed:Permanent deck or platform mounting dominates offshore oil and gas infrastructure where generator capacity supports high-amperage continuous operation.
- Mobile:Temporary rigging systems serve construction contractors requiring rapid redeployment across Norway's North Sea project sites without vessel modification.
- Integrated:OEM-embedded winch systems in electric vehicle platforms require FCC electromagnetic compatibility certification for wireless remote control functionality.
- Standalone:Self-contained power and control units address legacy vessel electrical infrastructure limitations where shipyard retrofits prove cost-prohibitive.
Fixed installations anchor replacement part revenue; mobile configurations are gaining share fastest.
Power Rating:
Torque density requirements scale non-linearly with capital cost, creating distinct supplier ecosystems.
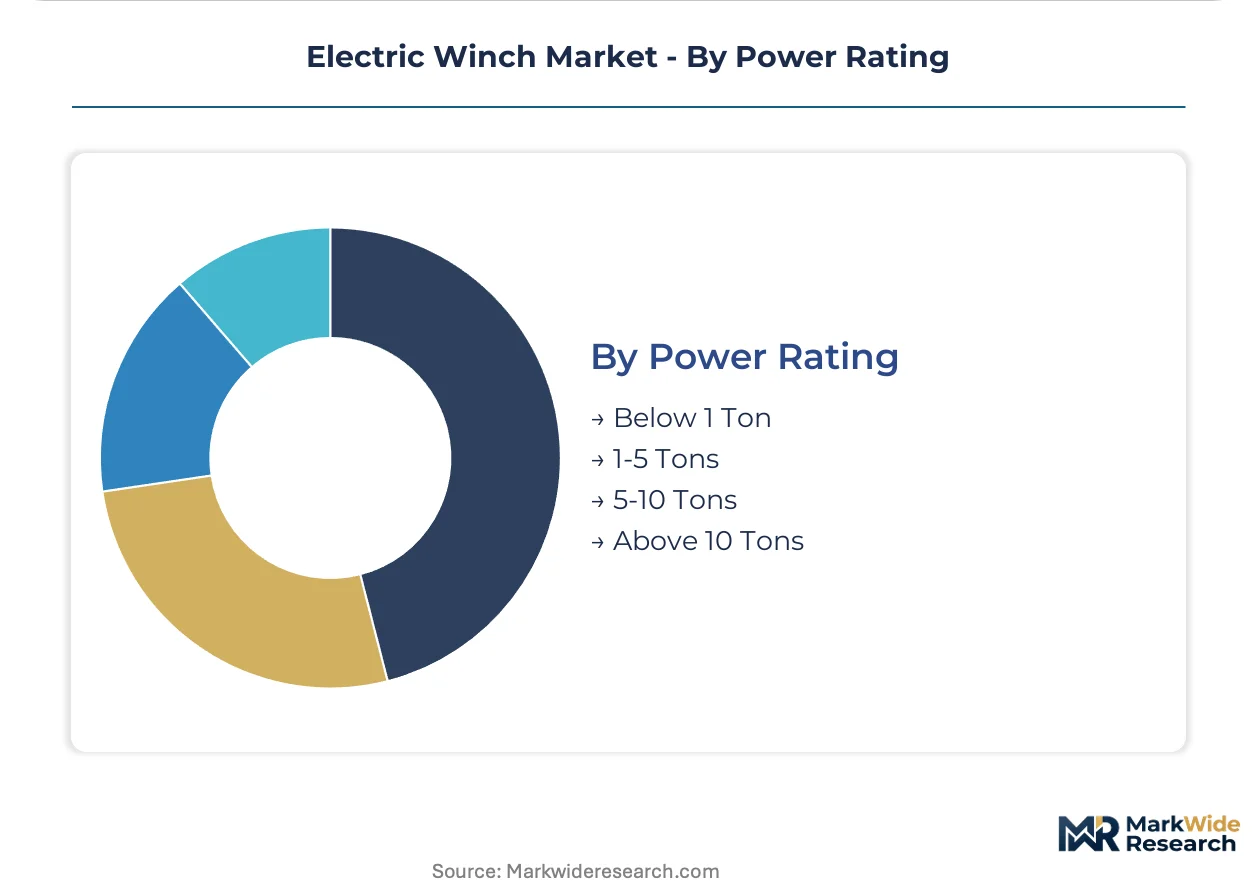
- Above 10 Tons:These systems integrate variable frequency drive firmware requiring IEC 61508 functional safety certification, extending engineering timelines but capturing offshore wind installation specifications.
- 5-10 Tons:Mid-duty industrial categories increasingly specify brushless DC motor architecture for predictive monitoring integration that wound-rotor alternatives cannot support.
- 1-5 Tons:Standard industrial and commercial vehicle recovery applications balance duty cycle ratings against portability requirements.
- Below 1 Ton:Light-duty segments face commoditization pressure as Chinese GB standards through SAMR enforce motor efficiency tiers that reshape sourcing requirements.
Above 10-ton ratings concentrate engineering resources; 5-10 ton configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electric winches concentrates in maritime corridors where offshore energy infrastructure and regulatory pressure on hydraulic systems intersect. Norway's North Sea cluster anchors heavy-duty procurement, while construction and automotive recovery specifications are climbing fastest in Germany and the United States.
Norway
Floating offshore wind foundation deployment and oil platform maintenance drive 50-ton-plus line pull demand. The EU F-Gas Regulation accelerates displacement of hydraulic systems across Stavanger and Bergen port infrastructure. Norwegian yards in the North Sea cluster specify IP67-certified electric winches for subsea load handling.
Germany
Warehouse automation integrators specify brushless DC motor architectures for continuous-cycle material handling. CE marking under the EU Machinery Directive mandates comprehensive risk assessment for winch certification. Industrial procurement concentrates in Baden-Württemberg and North Rhine-Westphalia for modular portable configurations.
United States
Battery-electric vehicle manufacturers mandate dedicated low-speed high-torque recovery protocols. FCC electromagnetic compatibility standards govern wireless remote control integration for aftermarket winch sales. Construction equipment rental fleets in Texas and California now require component-level replaceability.
United Kingdom
Offshore support vessel operators face REACH substance restrictions on hexavalent chromium plating for marine winch drums. The EU F-Gas Regulation extends compliance pressure to UK-flagged vessels operating North Atlantic routes. Aberdeen and Great Yarmouth anchor specification demand for corrosion-resistant ceramic coating alternatives.
China
GB standards through SAMR enforce motor efficiency tiers that reshape sourcing requirements for domestic and export markets. Rare earth processing capacity concentrates permanent magnet motor supply chains. Manufacturing clusters in Jiangsu and Zhejiang provinces feed component demand for international winch assemblers.
Electric Winch Market Vendor Landscape
German and US producers anchor the premium tier; Chinese fabricators hold volume positioning in standard-duty categories. The vendor base splits between integrated motor manufacturers and specialized winch assemblers sourcing driveline components. Three archetypes dominate: in-house motor producers, modular platform specialists, and rental-focused service integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms address IP certification timelines and rare earth supply concentration.
Among North American manufacturers, WARN Industries exemplifies in-house motor production as a margin defense archetype, while Ramsey Winch occupies a position within military and utility-grade recovery specialization. Ingersoll Rand represents integrated pneumatic-electric hybrid architectures for industrial material handling applications. These three firms illustrate how geographic origin and structural approach segment competitive positioning without requiring uniform strategic responses.
| Leading Market Players |
|---|
| Ramsey Winch |
| Mile Marker Industries |
| WARN Industries |
| Thern |
| Harken |
| Ingersoll Rand |
| COMEUP Industries |
| Winchmax |
| Superwinch |
| Others |
Supply Flow & Price Mechanics
Permanent magnet motor winding specialists in Jiangsu province anchor labor-cost differentials that stretch pricing-tier spreads between premium European-certified units and standard-duty Chinese assemblies. CE marking compliance and IP67 certification requirements widen the premium-to-economy gap as buyers in Norway's North Sea cluster absorb documentation and testing overhead that commodity purchasers avoid.
Pricing Analysis
Volume concentrates in below-5-ton standard-duty categories where Chinese GB motor efficiency tiers enforce baseline cost floors, while margins pool in above-10-ton offshore specifications where IEC 61508 functional safety certification creates scarcity rents. Price differentiation hinges on IP enclosure class and duty cycle rating, with marine-grade variants commanding substantial premia over industrial equivalents. Cost compression in mid-duty segments is intensifying as brushless DC motor commodification erodes wound-rotor positioning. Rental fleet operators exhibit highest price sensitivity; offshore wind developers show least.
Supply Chain Analysis
Direct-to-OEM channels handle battery-electric vehicle manufacturer demand for integrated recovery systems, while distributor networks serve aftermarket construction and marine buyers. Rare earth processing capacity concentrates in China, with secondary motor component clusters in Germany and the United States. Permanent magnet synchronous motor production draws from neodymium-iron-boron supply chains, copper winding stock, and precision-machined planetary gear sets. Single-source vulnerability in rare earth separation exposes non-integrated assemblers to input disruption. Distribution runs through specialized industrial equipment distributors and rental fleet procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric winch market sits in a technology-transition phase as permanent magnet synchronous motor architectures displace legacy wound-rotor designs across duty-cycle tiers. This displacement compresses incumbent positioning windows while opening specification gaps for certified entrants.
For Market Incumbents: Lock in rare earth supply agreements through captive offtake or joint venture structures in China before processing capacity tightens further. Accelerate IEC 61508 firmware certification pipelines to defend offshore wind specifications against brushless DC challengers. Deepen backward integration into motor manufacturing to sustain margin control as rental fleet operators unbundle service revenue. For New Entrants and Emerging Players: The 5-10 ton price-point gap between premium European-certified and economy Chinese units offers white-space capture for mid-tier modular platforms. Target construction contractors in Germany and the Netherlands demanding portable configurations with synthetic rope compatibility. Pursue wireless remote control standardization as a go-to-market wedge to bypass entrenched distribution relationships. For Investors and Strategic Acquirers: Re-rating potential sits with in-house motor producers given EU F-Gas Regulation acceleration and battery-electric vehicle recovery protocol mandates. Firms with pre-qualified ceramic coating surface treatments and SAMR GB efficiency tier compliance command acquisition premia. Monitor offshore wind foundation deployment announcements as inflection indicators for 50-ton-plus line pull demand.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Supply Agreement | Captures permanent magnet motor input security against Chinese processing concentration. |
| IEC 61508 Firmware Certification | Unlocks offshore wind and oil platform specifications requiring functional safety validation. |
| Ceramic Coating Surface Treatment | Qualifies marine winch drums under REACH hexavalent chromium restrictions for North Sea operators. |
| Modular Portable Platform Launch | Addresses Norway construction contractor demand for field-deployable units without vessel modification. |
| Wireless Remote Control Standardization | Converges FCC and EU radio equipment mandates for transatlantic product platform unity. |
Methodological Framework
Multi-period observation of offshore wind installation contracts, battery-electric vehicle recovery protocol specifications, and EU F-Gas Regulation compliance timelines anchored the trend analysis, supplemented by interviews with marine equipment procurement managers, construction rental fleet operators, offshore platform maintenance directors, and electric winch OEM engineering heads. Secondary validation drew from SAMR GB standard filings, ECHA REACH substance restriction updates, FCC electromagnetic compatibility rulings, and customs trade data for motor and winch component flows. Bottom-up segment sizing triangulated against top-down energy infrastructure capex projections.
The input-output matrix framed demand modeling across product type, power rating tier, installation configuration, and end-use vertical, with value outputs calibrated to capital equipment procurement patterns and aftermarket service unbundling trends. CAGRs derived from segment-level growth rate blending weighted by installed base replacement cycles and regulatory compliance deadlines. Offshore wind foundation deployment schedules and battery-electric vehicle platform ramp timelines supplied industry-specific demand inflection points across the projection horizon.
Inputs from offshore wind developers, vessel operators, and automotive OEMs were available through the study window; gaps in forward capital commitment disclosure for floating turbine projects introduce uncertainty bands in heavy-duty winch demand trajectories. Forecasts reflect assumptions around EU F-Gas Regulation enforcement intensity and rare earth supply chain stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Elevator Door-Motor Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Rodless Cylinders Market
Electro-Mech Systems
Automatic Slack Adjusters Market
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
HVAC Relay Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market
Electro-Mech Systems
Rigid Metal Electrical Conduit Market
Electro-Mech Systems
Wiring Duct Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
Movable Scaffolding System Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Tubular Motors Market