
 Elevator Door-Motor Market | 2026-2036
Elevator Door-Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Elevator Door-Motor Market Insights
High-rise residential construction is hardening demand for elevator door-motor systems with tighter cycle-time tolerances. Otis leverages its manufacturing scale across North America and Asia to sustain cost leadership in high-volume contracts. KONE Corporation anchors its position through R&D intensity in permanent-magnet synchronous motor technology for low-noise applications.
An elevator door-motor is an electromechanical drive unit that converts electrical energy into precise linear or rotational motion to open and close elevator car and landing doors, typically operating at 0.5 to 1.0 m/s door speed with torque ratings between 3 and 50 Nm depending on door mass and travel height. Its primary purpose is to ensure safe, synchronized, and repeatable door operation integrated with car control systems and safety edge sensors. Sliding doors dominate volume due to universal adoption in mid-rise and high-rise buildings, while magnetic technology represents the fastest-growing segment as building operators seek gearless, maintenance-reduced alternatives to hydraulic and pneumatic drives. Telescopic doors command premium positioning in space-constrained retrofit projects where shaft dimensions limit standard installations.
The US FDA and FAA influence medical and airport elevator specifications indirectly through facility accessibility mandates, while China's SAMR and GB standards directly govern door-motor safety certifications, energy efficiency tiers, and electromagnetic compatibility testing for domestic and imported equipment. Europe's CE marking and Machinery Directive establish conformity requirements for door-force limitation and emergency operation that shape export competitiveness for Asian manufacturers. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal tighten motor efficiency benchmarks and recast supplier qualification criteria across procurement channels.
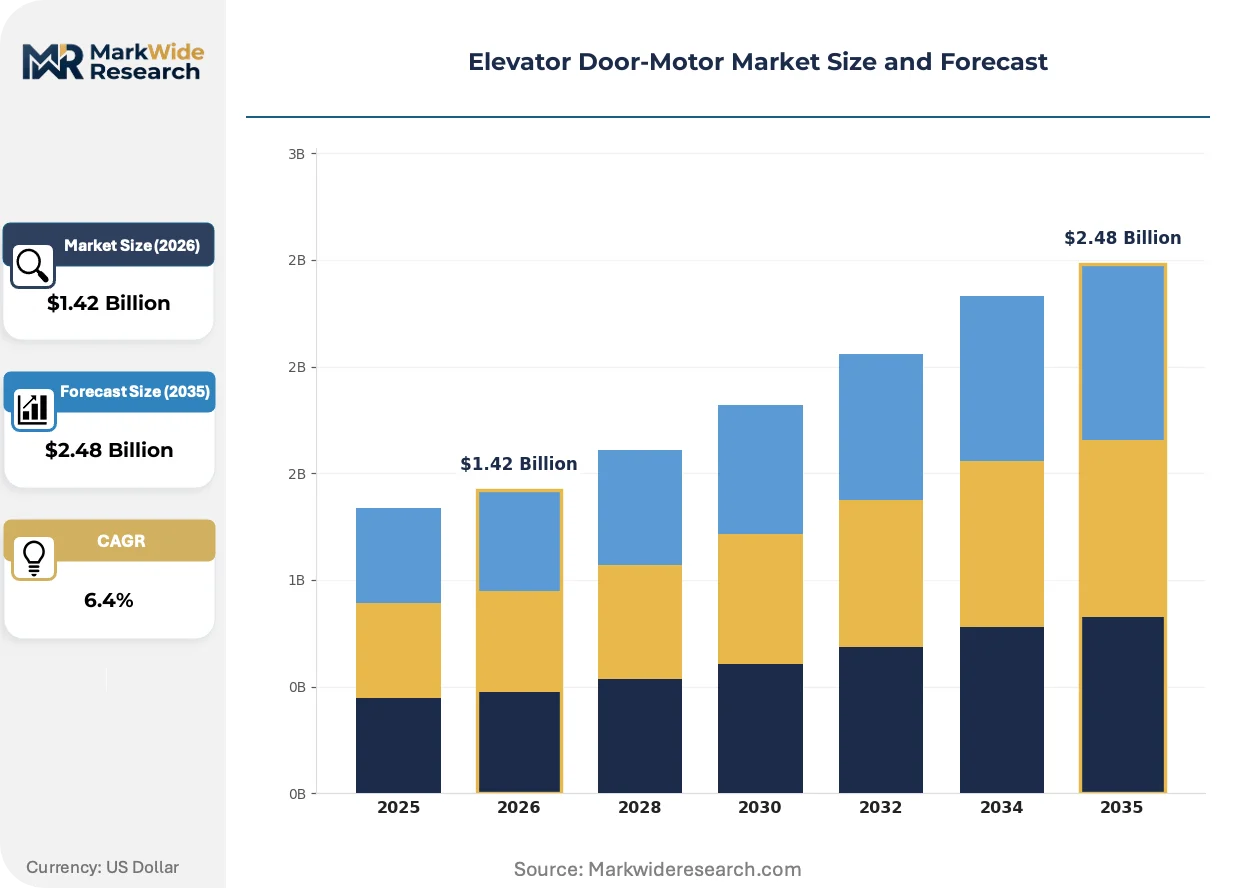
Market Dynamics
Permanent-magnet synchronous motor technology is compressing maintenance intervals and recasting supplier qualification criteria as building operators prioritize total cost of ownership over upfront capital expenditure in procurement decisions.
Growth Catalysts
- Urban verticalization in India:Government-backed smart city initiatives and metro rail expansions are accelerating elevator installations in Tier-2 and Tier-3 cities, hardening demand for precision door-motor systems with synchronized control architectures.
- China's dual carbon goals:SAMR efficiency tier classifications and GB 30253 motor standards are mandating premium-efficiency door-motor retrofits in commercial buildings, creating replacement cycles ahead of equipment end-of-life.
- Magnetic levitation door drives:Gearless linear motor technology eliminates mechanical wear components, reducing maintenance callbacks and enabling predictive service models that align with facility management outsourcing trends.
Market Restraints
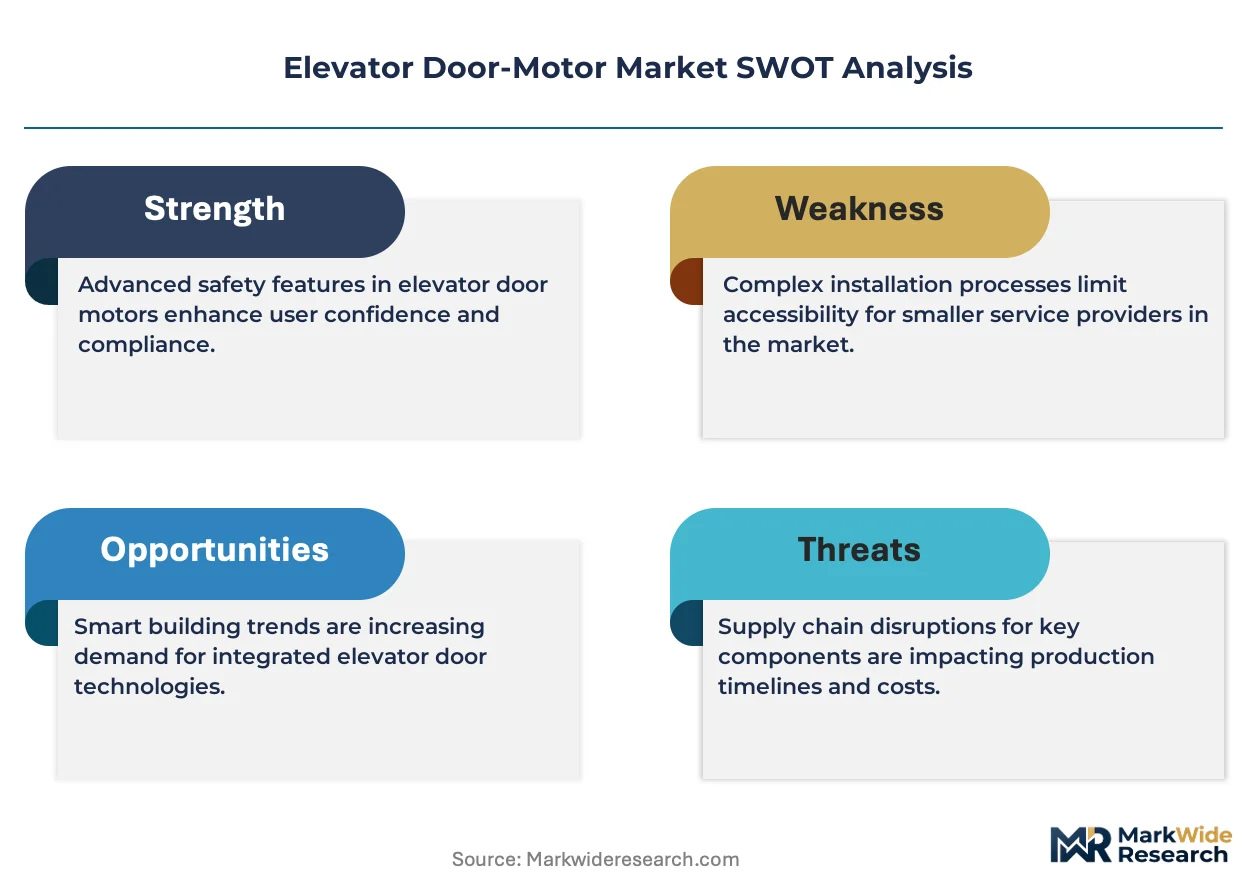
- Rare earth magnet supply concentration:Neodymium and dysprosium processing capacity concentrates in China's Inner Mongolia and Jiangxi provinces, exposing motor manufacturers to export quota volatility and forced technology transfer requirements.
- Shaft dimensional constraints in retrofits:Pre-1990 building stock across Southeast Asia features non-standard door openings that resist telescopic and center-opening configurations without structural modifications.
- Certification timeline friction:EU Machinery Directive 2006/42/EC conformity assessment for door-force limitation systems extends product launch cycles by 8-14 months for Asian OEMs seeking CE marking.
Strategic Opportunities
- Airport accessibility mandates:US FAA facility standards and ADA Title III enforcement are expanding heavy-duty door-motor specifications for baggage handling elevators and passenger boarding bridges in hub expansions.
- Service unbundling in Japan:METI-promoted maintenance deregulation allows third-party service providers to source replacement door-motors independently, fragmenting OEM captive aftermarket control.
- Digital twin convergence:Integration of door-motor torque sensors with building management system analytics enables condition-based maintenance contracts that shift revenue from equipment sales to performance guarantees.
Industry Challenges
- Embedded software certification:Functional safety validation to SIL 2 per IEC 61508 for door control firmware requires specialized validation engineers whose scarcity extends development timelines.
- Legacy controller protocol fragmentation:Proprietary CAN bus and serial communication implementations across installed elevator bases complicate drop-in door-motor replacements without controller upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elevator Door-Motor Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Swing Doors, Bi-Fold Doors, Telescopic Doors Technology: Hydraulic, Electric, Pneumatic, Magnetic End User: Residential Buildings, Commercial Offices, Industrial Facilities, Hospitals Installation Type: New Installation, Modernization, Retrofits, Maintenance |
| Companies Covered | Otis, KONE Corporation, Schindler Group, Mitsubishi Electric Corporation, TK Elevator, Hitachi Ltd., Nidec Corporation, Wittur Group, Fermator Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elevator Door-Motor Market Trends and Innovations
Electrification of building systems and convergence of mechanical and digital control layers are redefining how door-motor performance is specified, measured, and monetized across new construction and modernization channels.
Permanent-magnet synchronous motor technology is consolidating position in mid-rise and high-rise applications by eliminating gearbox maintenance and reducing acoustic signatures below 55 dB. Property developers in Singapore and Dubai specify PM synchronous units for luxury residential towers where noise specifications figure prominently in sales collateral. This technology is consolidating supplier margins by compressing the addressable market for conventional induction motor retrofits and favoring manufacturers with captive magnet supply arrangements.
China's GB 7588-2020 safety code and associated SAMR implementation rules are mandating redundant brake systems and door-lock monitoring circuits that increase bill-of-materials complexity. Domestic certification laboratories in Shanghai and Beijing face testing backlogs that delay product launches for imported equipment. European and Japanese manufacturers are responding by pre-certifying platforms to both GB and EN 81-20 standards to accelerate market entry.
Facility management outsourcing is fragmenting traditional OEM service relationships and creating procurement authority for independent maintenance contractors. Third-party service providers in Germany and South Korea now source door-motors through industrial distribution channels rather than manufacturer direct, compressing brand premiums and elevating price transparency. This shift is most visible in commercial office segments where multi-site property portfolios negotiate enterprise maintenance agreements.
Elevator Door-Motor Market Segmentation
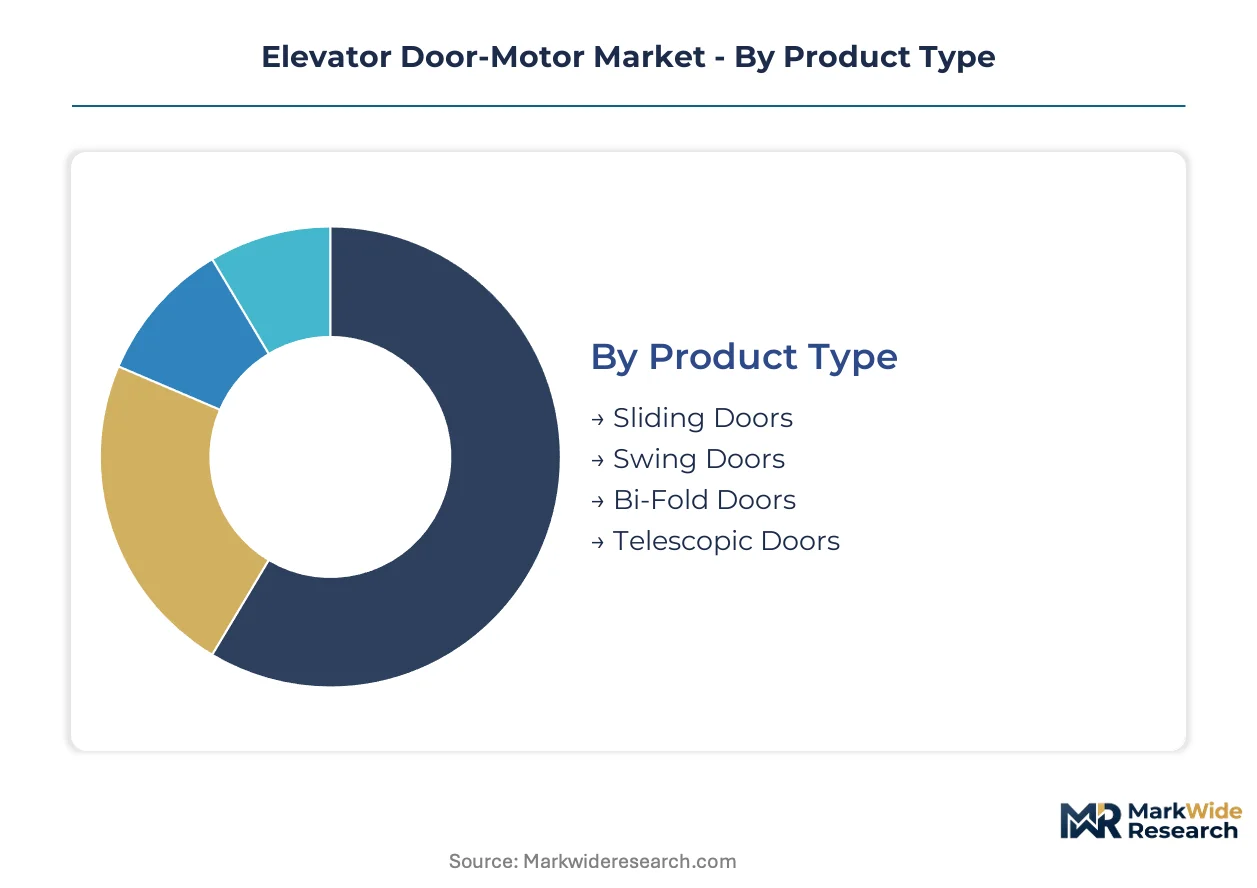
Door-motor replacement cycles vary sharply across building vintages and regulatory jurisdictions, forcing suppliers to maintain parallel product portfolios. Segmentation clarity enables targeting of high-margin modernization channels versus cost-pressured new construction tenders.
Product Type:
Upgrade cycles in aging commercial stock favor configurations that minimize shaft modifications while meeting current safety codes.
- Sliding Doors:Side-opening panels operate via rack-and-pinion or belt-driven mechanisms with typical clear opening widths of 700-1600 mm. Demand concentrates in India's Tier-2 city residential towers where developers prioritize cost-efficient standardization over customization.
- Telescopic Doors:Multi-panel nesting systems achieve full opening width in 65% of conventional shaft depth, enabling retrofit installations where structural expansion is prohibited. Singapore's conservation district commercial modernizations specify these units to preserve heritage facades while upgrading to EN 81-20 compliance.
- Swing Doors:Hinged single-panel designs serve low-rise accessibility retrofits and freight applications with lower cycle frequency requirements.
- Bi-Fold Doors:Folding panel assemblies address ultra-compact machine-room-less installations in Japan's urban infill residential projects.
Sliding doors sit at the top of the volume ranking, with telescopic doors climbing the fastest.
Technology:
Total cost of ownership calculations now dominate procurement evaluations, elevating technologies that reduce scheduled maintenance intervals.
- Magnetic:Linear synchronous motors eliminate mechanical transmission components, cutting acoustic output below 50 dB and enabling predictive maintenance through embedded position sensing. China's GB 30253 efficiency tiers and dual carbon mandates accelerate magnetic retrofits in Shanghai and Shenzhen commercial buildings ahead of regulatory deadlines.
- Electric:AC induction and permanent-magnet synchronous configurations dominate current installed base, with PM synchronous variants displacing geared systems in mid-rise segments.
- Hydraulic:Fluid-power drives persist in heavy-duty freight and industrial applications requiring sustained holding torque without continuous electrical draw.
- Pneumatic:Compressed-air systems retain niche presence in explosive-atmosphere industrial facilities where electrical spark containment is mandatory.
Electric technology maintains the broadest installed base, while magnetic systems are expanding most quickly.
End User:
Facility management outsourcing patterns fragment procurement authority differently across verticals, altering supplier access strategies.
- Commercial Offices:Multi-tenant buildings with centralized property management favor standardized door-motor platforms that simplify spare parts logistics across portfolios. Germany's facility management deregulation enables third-party service providers to source independently, compressing OEM brand premiums.
- Residential Buildings:High-rise towers in Southeast Asia drive volume for synchronous motor systems with noise specifications below 55 dB to support premium unit marketing.
- Hospitals:Bed elevator specifications prioritize smooth acceleration profiles and door dwell time adjustability for stretcher and equipment transfers.
- Industrial Facilities:Freight and vehicle elevator applications demand higher torque ratings and corrosion-resistant enclosures for harsh operating environments.
Commercial offices generate the largest replacement parts demand, with hospitals showing the steepest specification escalation.
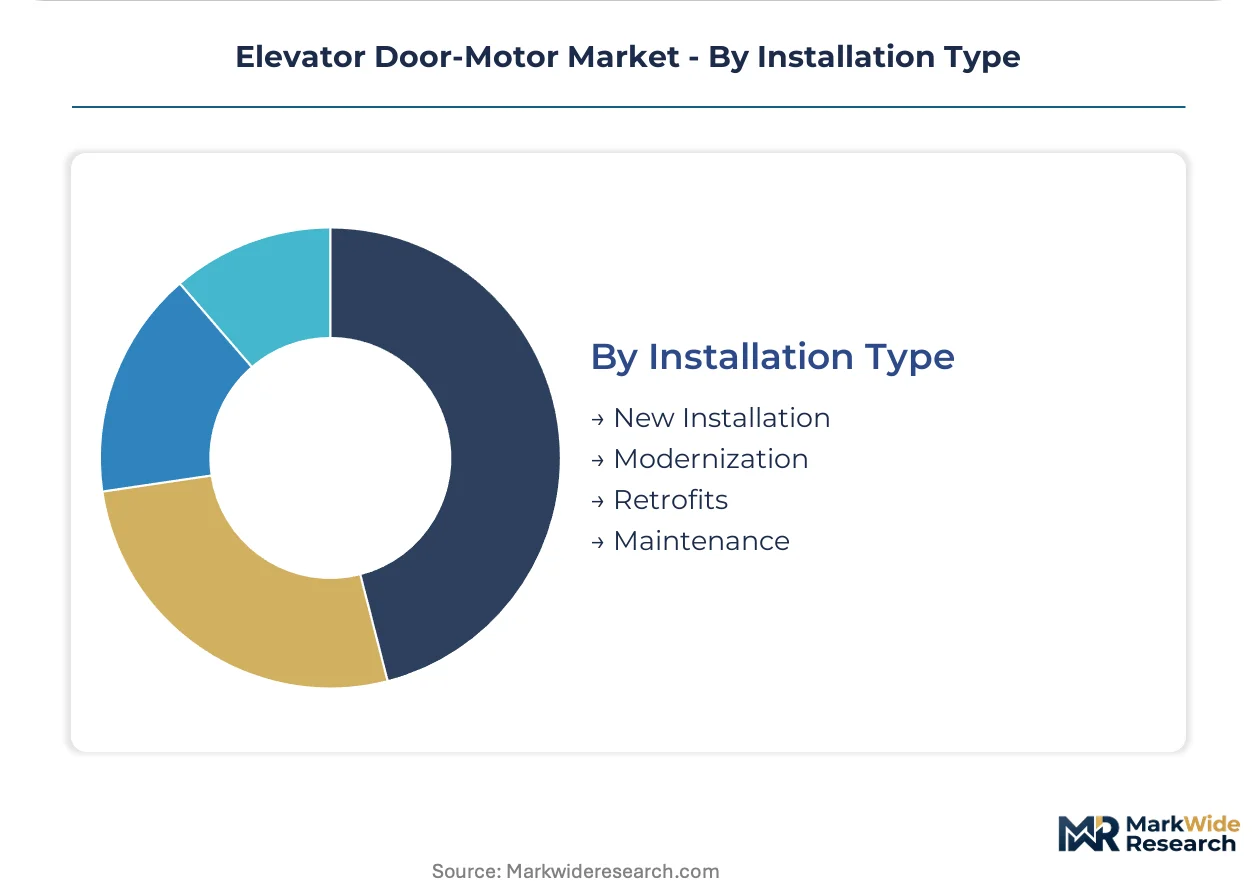
Installation Type:
Regulatory compliance deadlines in major jurisdictions create predictable replacement waves that suppliers must anticipate.
- Modernization:Partial system upgrades replace door-motor units while retaining existing controllers, requiring protocol compatibility layers. China's SAMR enforcement of GB 7588-2020 brake redundancy and door-lock monitoring mandates accelerates modernization spend in commercial buildings.
- New Installation:Greenfield projects allow integrated specification of gearless magnetic systems with building management system connectivity from commissioning.
- Retrofits:Complete door system replacements in constrained shafts demand telescopic or customized configurations with minimal structural intervention.
- Maintenance:Breakdown repair and preventive service sustain aftermarket revenue, though deregulation in Japan fragments OEM captive control.
Modernization commands the highest margin pool, with new installation volume scaling fastest in emerging verticalization markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as door-motor suppliers migrate production to jurisdictions with streamlined certification pathways and lower compliance overhead. China's GB standards and India's BIS safety codes create divergent cost structures that influence regional sourcing strategies.
China
Shanghai and Shenzhen commercial building retrofits are accelerating magnetic door-motor replacements ahead of SAMR's GB 30253 efficiency tier deadlines. The dual carbon policy framework is forcing equipment upgrades in Class A office towers before regulatory end-dates. Domestic certification laboratories in Beijing face testing backlogs that delay imported equipment launches.
India
Tier-2 city verticalization in Pune and Ahmedabad is hardening demand for synchronous motor systems with synchronized control architectures. Government smart city initiatives and metro rail expansions are channeling procurement toward standardized platforms. Mumbai's high-rise residential clusters specify noise-rated units below 55 dB for premium marketing positioning.
Germany
Facility management deregulation under EU Machinery Directive implementation is fragmenting OEM captive service relationships. Third-party maintenance contractors in Frankfurt and Munich now source door-motors through industrial distribution rather than manufacturer-direct channels. CE marking conformity assessment for door-force limitation systems extends launch cycles for Asian equipment suppliers.
United States
FAA facility standards and ADA Title III enforcement are expanding heavy-duty specifications for airport baggage handling elevators and passenger boarding bridges. Hub expansions in Atlanta and Denver are driving procurement for high-cycle door-motor systems. OSHA workplace safety guidelines indirectly influence maintenance protocol specifications in commercial office portfolios.
Japan
METI-promoted maintenance deregulation allows independent service providers to source replacement door-motors outside OEM channels. Tokyo's urban infill residential projects specify bi-fold configurations for machine-room-less installations. Osaka's commercial modernization wave favors telescopic systems that preserve existing shaft dimensions.
Elevator Door-Motor Market Competitive Landscape
Capacity expansion dominates the current landscape as established suppliers scale permanent-magnet synchronous motor production to capture efficiency-tier retrofit cycles. The vendor base clusters around three strategic archetypes: integrated elevator OEMs with captive motor production, specialized electromechanical component fabricators, and industrial motor suppliers diversifying into vertical transportation. M&A activity and technology licensing agreements are the primary competitive moves as firms secure rare earth magnet supply arrangements and embedded software validation capabilities.
Within the integrated OEM tier, Otis and KONE Corporation exemplify scale-driven positioning through manufacturing footprints across North America and Asia. Among Japanese electromechanical specialists, Mitsubishi Electric Corporation and Hitachi Ltd. occupy positions anchored in permanent-magnet motor R&D intensity. Wittur Group represents the independent component fabricator archetype, serving multiple elevator OEMs through standardized platform supply.
| Leading Market Players |
|---|
| Otis |
| KONE Corporation |
| Schindler Group |
| Mitsubishi Electric Corporation |
| TK Elevator |
| Hitachi Ltd. |
| Nidec Corporation |
| Wittur Group |
| Fermator Group |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between CE-marked synchronous systems and non-certified induction motor alternatives manifests in both price premiums of 15-25% and supply chain configurations that route premium-tier production through European validation hubs while commodity variants flow directly from Chinese assembly plants. This divergence hardens as GB 7588-2020 compliance deadlines in China and Machinery Directive enforcement in Europe elevate qualification costs for second-tier suppliers.
Pricing Analysis
Distributor margin compression in Germany and South Korea is reshaping channel economics as facility management deregulation enables third-party service providers to source door-motors through industrial distribution rather than manufacturer-direct channels. Three-tier pricing structure across premium PM synchronous, standard AC induction, and economy hydraulic systems reflects differentiation by noise specification and energy efficiency tier. Pricing pressure stems from rare earth magnet cost volatility as neodymium processing concentrates in China's Inner Mongolia province. Commercial office portfolios with enterprise maintenance agreements exhibit highest price sensitivity, while luxury residential developers in Singapore and Dubai absorb premiums for sub-55 dB specifications.
Supply Chain Analysis
Regional distribution centers in Shanghai, Stuttgart, and Chicago anchor hub-and-spoke fulfillment patterns that position finished door-motor inventory within 48-hour reach of major elevator OEM assembly plants. Manufacturing concentrates in China, Germany, and Japan, with rare earth magnet drawing from Jiangxi province processing facilities and precision machining anchored in Baden-Württemberg. Copper winding supply rests on Chilean concentrate and Zambian cathode flows through Asian wire-drawing facilities. Single-source vulnerability in dysprosium separation creates exposure to export quota adjustments. Distribution runs through captive OEM logistics networks for new installations, while independent service channels fragment aftermarket spare parts flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Elevator door-motor procurement has shifted toward premium-efficiency specifications as building operators prioritize total cost of ownership calculations over upfront capital expenditure, compressing addressable market for conventional induction retrofits.
For Market Incumbents: Acquire captive rare earth magnet supply arrangements to secure dysprosium and neodymium access against Chinese export quota volatility. Add permanent-magnet synchronous motor capacity in Southeast Asian manufacturing clusters to capture India's Tier-2 city verticalization wave. Defensive positioning requires pre-certification to both GB and EN 81-20 standards to bypass Beijing and Shanghai laboratory backlogs that delay competitor launches. For New Entrants and Emerging Players: Magnetic levitation linear drive technology offers white-space entry into gearless retrofit segments where noise specifications below 50 dB command premium positioning. Target Japan's deregulated maintenance market where METI-promoted reforms allow independent sourcing outside OEM captive channels. Penetrate India's smart city elevator installations through synchronized control architecture partnerships with domestic system integrators lacking magnetic drive expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where embedded software validation capabilities to SIL 2 per IEC 61508 concentrate among Japanese and European engineering teams. Five-to-ten-year viability favors component fabricators with backward integration into magnet supply and forward integration into predictive maintenance analytics. Acquisition target archetype: mid-cap electromechanical specialists with GB certification in place and torque sensor integration capabilities. Watch for inflection in China's SAMR enforcement velocity as indicator of replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Supply Agreement | Captive neodymium access from Jiangxi processors insulates margin against quota volatility. |
| Dual Certification Pre-Validation | Parallel GB 7588-2020 and EN 81-20 testing accelerates market entry in Shanghai and Shenzhen. |
| Predictive Maintenance Platform | Torque sensor integration with building management systems shifts revenue to performance guarantees. |
| Telescopic Door Configuration Expansion | Multi-panel nesting systems capture Singapore conservation district modernization demand. |
| Third-Party Channel Partnership | Industrial distribution relationships in Germany and South Korea fragment OEM captive control. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with elevator OEM procurement directors, facility management executives, and aftermarket service technicians alongside secondary validation through SAMR certification databases, GB standards documentation, and customs trade records. Bottom-up triangulation aggregated country-level installation permits and modernization project announcements against top-down manufacturer shipment disclosures.
Historical reference periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-regulatory implementation demand surges. Segmentation modeling spanned door configuration type, motor technology architecture, end-use vertical, and installation channel across the projection horizon. CAGRs derived from equipment replacement cycle analysis and regulatory deadline clustering, with magnetic levitation adoption curves and rare earth price elasticity as industry-specific sensitivity inputs.
The model holds under steady SAMR enforcement intensity and stable rare earth export flows; deviation in Chinese dual carbon policy acceleration or dysprosium supply disruption would shift replacement cycle timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electro-Mech Systems
Electric Overhead Travelling (EOT) Cranes Market
Electro-Mech Systems
Rigid Metal Electrical Conduit Market
Electro-Mech Systems
Wiring Duct Market
Electro-Mech Systems
Mechanical Auger Boring Machine Market
Electro-Mech Systems
Electric Winch Market
Electro-Mech Systems
Hydraulic Cab Tilt System Market
Electro-Mech Systems
Agitator Drive Units Market
Electro-Mech Systems
Escalators and Moving Walkways Market
Electro-Mech Systems
Automatic Slack Adjusters Market
Electro-Mech Systems
HVAC Relay Market
Electro-Mech Systems
Light Gauge Framing System Market
Electro-Mech Systems
Rodless Cylinders Market
Electro-Mech Systems
Movable Scaffolding System Market
Electro-Mech Systems
Tubular Motors Market