
 Egypt Residential Construction Market | 2026-2036
Egypt Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Residential Construction Market Analysis
After-sales property management and digital tenant service platforms is rebalancing developer revenue streams beyond unit sales. Talaat Moustafa Group leverages its integrated hospitality and retail arm to sustain recurring income from completed districts. Hassan Allam Construction anchors large-scale infrastructure-to-housing workflows through captive civil engineering capacity. Orascom Construction competes on energy-efficient building envelopes in Egypt's desert climate zones.
Egypt residential construction encompasses the planning, erection, and finishing of dwellings ranging from reinforced concrete frame structures with hollow-core slabs to steel-composite hybrid systems, typically achieving 2.5 to 4.5 kN per square meter live-load capacity for seismic Zone 2B compliance. Its primary purpose is to house a population where urbanization exceeds available formal stock, while creating collateral demand for utilities, retail, and transport infrastructure. Multi-family units and condominiums attract the deepest financing pipelines as mortgage penetration expands through the Mortgage Finance Fund. Single-family homes and villas retain premium margin pools in gated compounds along Cairo-Alexandria Desert Road. Sustainable construction methods remain nascent but draw pilot capital from green bond allocations targeting the New Administrative Capital.
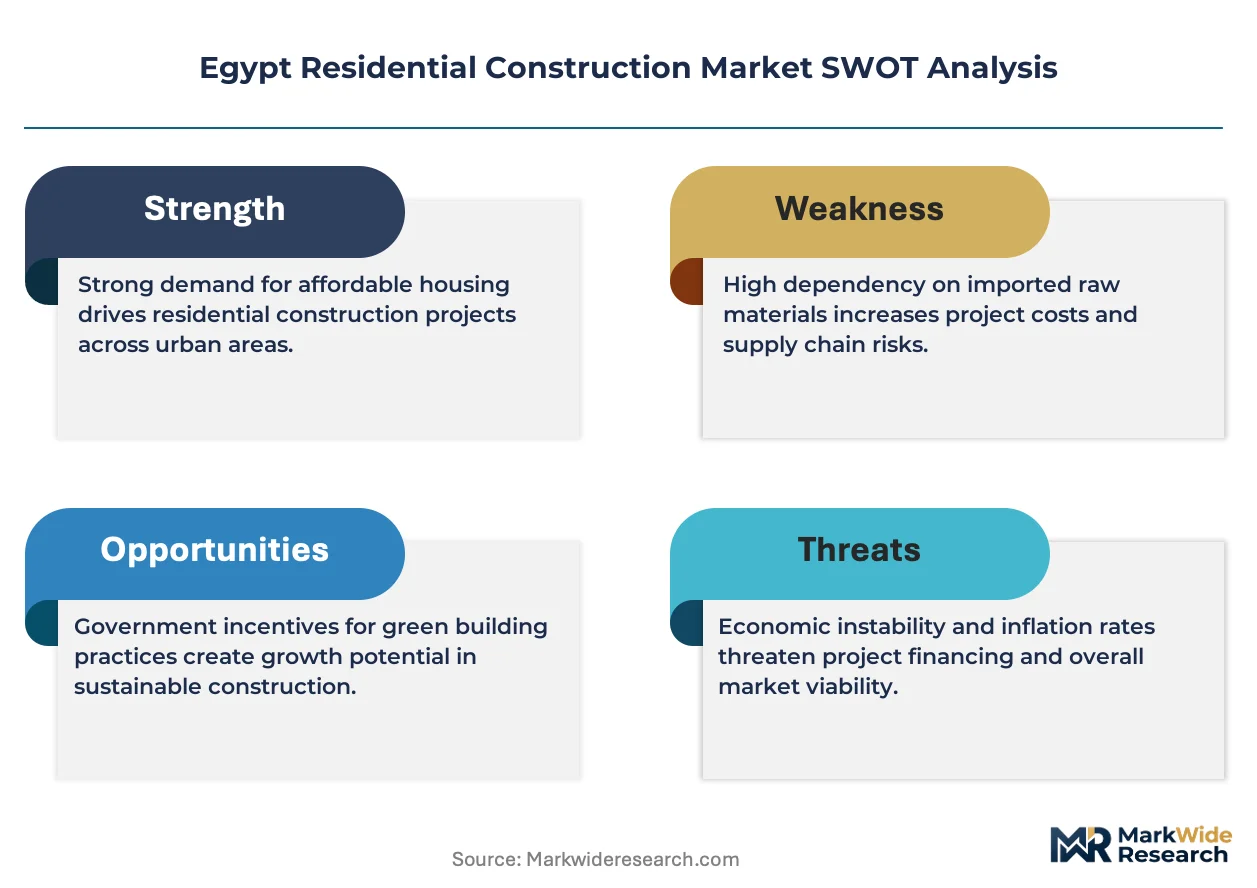
Egypt's New Urban Communities Authority and the Ministry of Housing enforce building codes that mandate earthquake-resistant design and govern land allocation in desert reclamation zones, directly shaping where developers may build and what structural standards apply. The Central Bank of Egypt, through the Mortgage Finance Fund, regulates lending terms and subsidy eligibility, channeling demand toward formally registered projects over informal construction. Stakeholders must monitor how currency availability affects imported steel and finish material costs, as this determines whether projects maintain schedule or shift to local substitutes.
Market Dynamics
The New Urban Communities Authority permitting framework is compressing project timelines in satellite cities while mortgage subsidy expansion through the Mortgage Finance Fund pulls first-time buyers into formal housing stock.
Growth Catalysts
- Mortgage Finance Fund subsidies:The Central Bank of Egypt channels preferential lending terms toward formally registered projects, expanding the buyer base beyond cash-only purchasers into credit-enabled segments.
- Desert reclamation land allocation:State-mandated land releases in the New Administrative Capital corridor concentrate developer activity where infrastructure precedes housing demand.
- Reinforced concrete frame systems:Local contractor capacity for seismic Zone 2B compliance enables rapid vertical construction at lower engineering cost than steel-composite alternatives.
Market Restraints
- Imported finish material dependency:Currency availability constraints disrupt ceramic tile, sanitary ware, and aluminum systems procurement from European and Gulf suppliers.
- Steel price volatility:Global scrap metal fluctuations transmit directly to rebar costs, compressing developer margins on fixed-price contracts.
- Informal construction competition:Unregistered builders in Greater Cairo's peripheral zones capture price-sensitive demand outside the formal mortgage ecosystem.
Strategic Opportunities
- Green bond pilot capital:Sustainable construction methods in the New Administrative Capital attract dedicated financing pools targeting low-carbon building envelopes.
- After-sales property management:Digital tenant service platforms enable recurring revenue streams beyond unit sales for developers with captive district infrastructure.
- Gated compound premium tier:Cairo-Alexandria Desert Road corridors retain margin pools for single-family villas targeting expatriate and high-net-worth Egyptian buyers.
Industry Challenges
- Seismic engineering talent scarcity:Limited local structural engineering capacity for Zone 2B compliance creates bottlenecks in design review and site supervision.
- Utility integration timelines:Water, sewage, and electricity connection delays in new desert cities extend project completion schedules beyond sales commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Residential Construction Market |
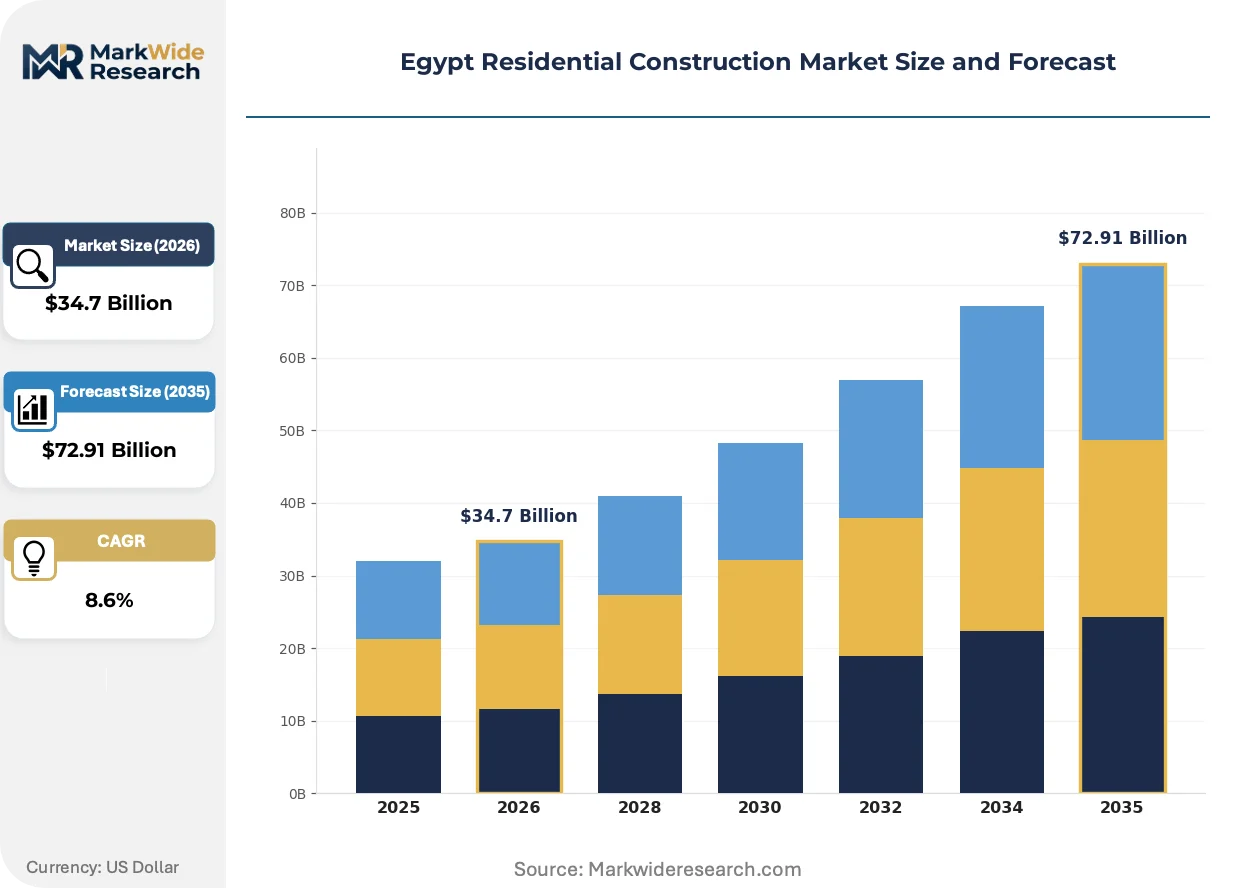
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Family Homes, Multi-Family Units, Condominiums, Villas End User: First-Time Buyers, Investors, Developers, Contractors Construction Method: Traditional, Modular, Prefabricated, Sustainable Material: Concrete, Steel, Wood, Composite |
| Companies Covered | Talaat Moustafa Group, Hassan Allam Construction, Orascom Construction, Gama Construction, Redcon Construction, The Arab Contractors, SODIC, BIC for Contracting & Construction, Palm Hills Developments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Residential Construction Market Emerging Trajectories
Digital platforms and policy mandates are restructuring how residential projects reach buyers and comply with evolving standards. Three forces are actively reshaping competitive positioning.
Modular prefabrication is decentralizing construction workflows in Egypt's desert climate zones. Developers in the New Administrative Capital corridor adopt factory-cast wall panels and pre-installed MEP modules to compress on-site labor requirements. This technology is decentralizing project timelines from weather-dependent cast-in-place sequences toward controlled-environment manufacturing.
REACH-aligned chemical disclosure requirements for imported coatings and adhesives are elevating compliance costs for European-sourced finish materials. Egyptian developers responding to export-market investor pressure now specify low-VOC alternatives in premium compounds. The segment most affected—Giza and New Cairo luxury units—has shifted procurement toward GCC suppliers with established Middle East conformity certification.
First-time buyer digital mortgage pre-qualification is compressing the sales cycle from site visit to contract signature. The Mortgage Finance Fund's online eligibility portal enables developers to convert showroom traffic faster than paper-based underwriting allowed. This pattern concentrates in the 6th of October City and Sheikh Zayed districts where young professional demand clusters.
Egypt Residential Construction Market Segmentation
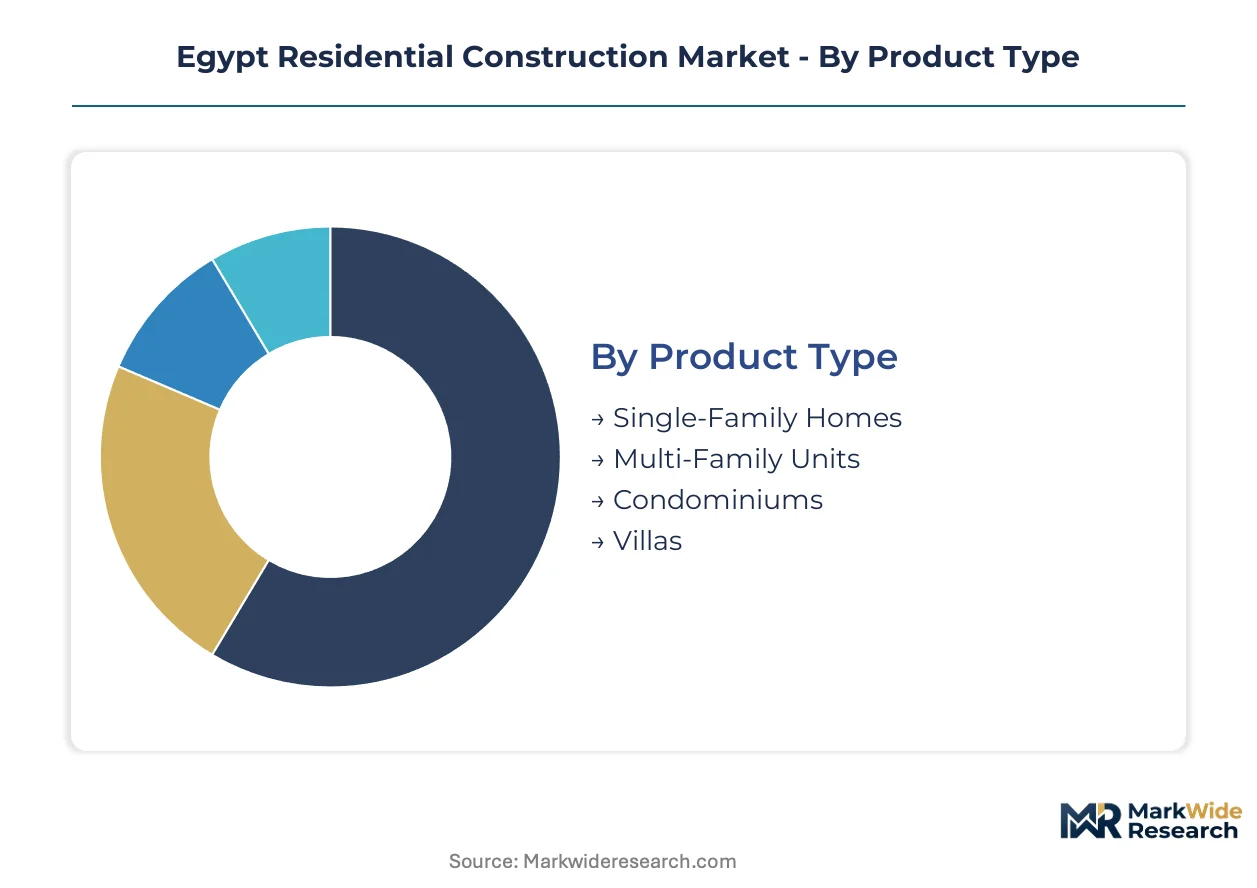
Structural specifications and buyer financing access determine competitive positioning across Egypt's residential construction value chain. Segmentation reveals where mortgage subsidy eligibility, material import dependencies, and seismic compliance requirements concentrate margin and risk.
Product Type:
Structural load-bearing systems and unit density specifications differentiate construction economics and buyer financing pathways.
- Single-Family Homes:Reinforced concrete frame structures with independent utility connections dominate Cairo-Alexandria Desert Road compounds. Demand clusters where expatriate and high-net-worth Egyptian buyers seek gated privacy beyond mortgage subsidy thresholds.
- Multi-Family Units:Hollow-core slab systems achieving 2.5 to 4.5 kN per square meter live-load capacity enable rapid vertical stacking in 6th of October City and Sheikh Zayed districts. The Mortgage Finance Fund channels the deepest subsidy pipelines toward formally registered multi-family stock.
- Condominiums:Shared-wall construction with centralized MEP distribution reduces per-unit land costs in New Administrative Capital corridor developments.
- Villas:Steel-composite hybrid systems command premium engineering margins in desert reclamation zones with seismic Zone 2B compliance requirements.
Mature deployment sits with Multi-Family Units. Newer deployment is concentrated in Villas.
End User:
Financing instrument availability and regulatory registration status segment buyer access to formal versus informal construction stock.
- First-Time Buyers:Young professionals entering through Mortgage Finance Fund pre-qualification portals convert fastest in digitally-enabled showroom environments. Eligibility compression from site visit to contract signature is reshaping developer sales operations in satellite cities.
- Investors:Recurring revenue seekers target completed districts with captive property management infrastructure for rental yield extraction.
- Developers:Integrated hospitality and retail arm capabilities sustain revenue beyond unit sales in master-planned communities.
- Contractors:Captive civil engineering capacity anchors infrastructure-to-housing workflow control for large-scale project delivery.
First-Time Buyers are expanding most quickly. Investors retain the deepest margin capture mechanisms.
Construction Method:
On-site labor dependency versus factory-controlled environment manufacturing determines timeline risk and weather exposure.
- Traditional:Cast-in-place concrete sequences remain dominant where local contractor capacity for seismic Zone 2B compliance enables rapid vertical construction at lower engineering cost than alternatives.
- Modular:Factory-cast wall panels decentralize project timelines from weather-dependent sequences toward controlled-environment manufacturing in New Administrative Capital pilot zones.
- Prefabricated:Pre-installed MEP modules compress on-site labor requirements where skilled trade scarcity creates bottlenecks.
- Sustainable:Low-carbon building envelope methods draw pilot capital from green bond allocations targeting desert climate zone energy efficiency.
Traditional methods anchor current volume. Sustainable construction is gaining share fastest.
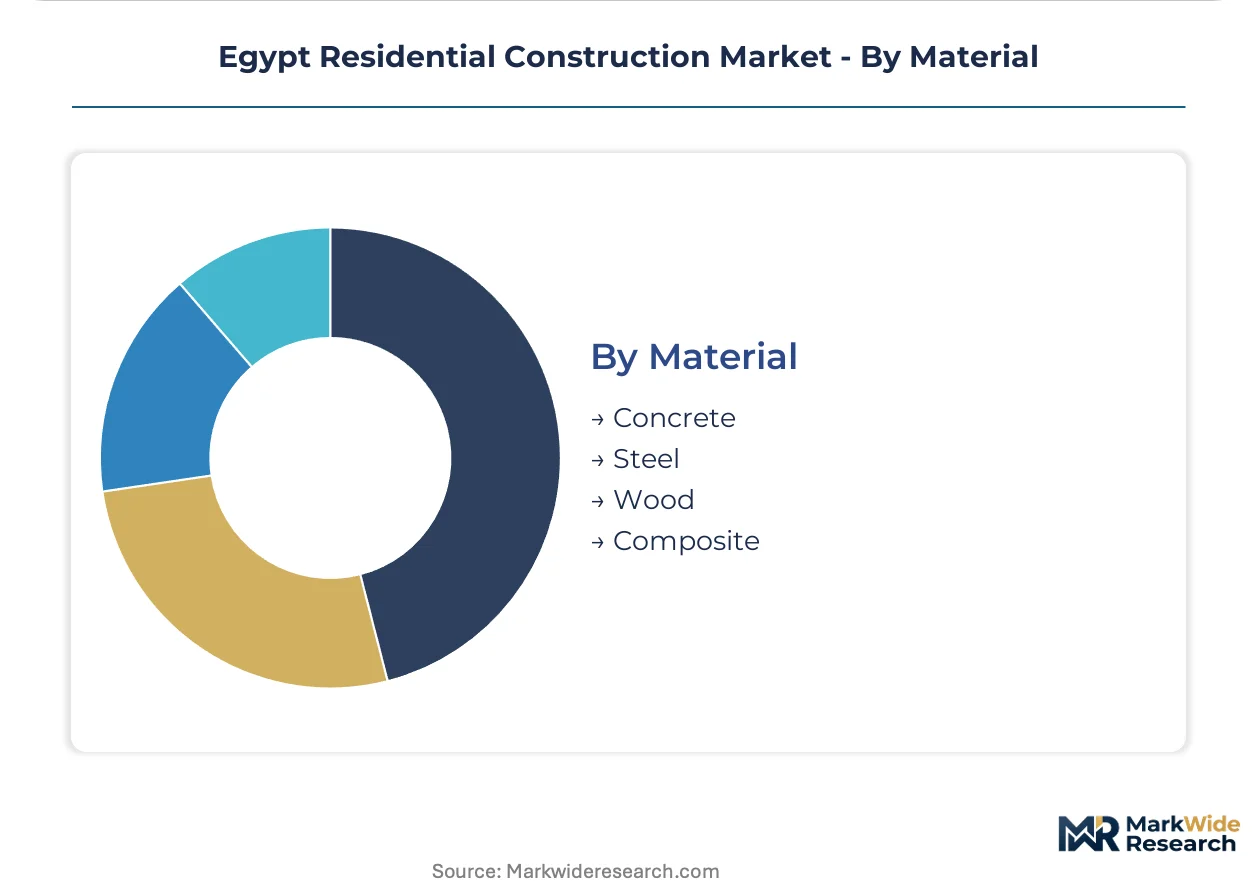
Material:
Import dependency and currency availability constraints segment procurement risk and margin compression exposure.
- Concrete:Local supply chains for reinforced concrete frame systems minimize foreign exchange exposure where steel rebar constitutes the primary import-linked cost component.
- Steel:Global scrap metal fluctuations transmit directly to rebar costs, compressing developer margins on fixed-price contracts in high-rise applications.
- Wood:Limited desert climate durability restricts application to interior finish and premium villa fit-out specifications.
- Composite:Energy-efficient building envelope systems compete on thermal performance in Egypt's extreme temperature variation zones.
Concrete dominates structural applications. Composite materials show steepest expansion trajectory in premium tier specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's residential construction output concentrates in desert reclamation zones where state land allocation precedes private demand, while consumption clusters in Greater Cairo's satellite cities where mortgage finance penetration is deepest.
Greater Cairo Satellite Cities
New Cairo and 6th of October City absorb the bulk of first-time buyer demand through Mortgage Finance Fund pre-qualification portals. The New Urban Communities Authority compresses permitting timelines in these zones, accelerating developer project launches. Sheikh Zayed district anchors digital mortgage conversion where young professional demand clusters fastest.
Alexandria Coastal Corridor
Gated compounds along Cairo-Alexandria Desert Road capture expatriate and high-net-worth Egyptian buyers seeking premium villa specifications. Hassan Allam Construction anchors infrastructure-to-housing workflows through captive civil engineering capacity in this corridor. Borg El Arab city concentrates mid-rise multi-family stock where mortgage subsidy eligibility expands.
New Administrative Capital
The state-mandated desert reclamation zone channels developer activity where infrastructure precedes housing demand. Green bond allocations pilot low-carbon building envelope methods in this corridor. Modular prefabrication adoption decentralizes project timelines from weather-dependent cast-in-place sequences.
Red Sea Coastal Zone
Hurghada and Marsa Alam secondary home markets attract recurring revenue seekers targeting rental yield extraction. Talaat Moustafa Group leverages integrated hospitality and retail arms to sustain income from completed districts. Sustainable construction methods draw pilot capital from tourism-linked investment vehicles.
Upper Egypt Urban Centers
Asyut and Sohag informal construction competition captures price-sensitive demand outside formal mortgage ecosystems. The Central Bank of Egypt's Mortgage Finance Fund channels limited subsidy pipelines toward formally registered projects in these governorates. Local contractor capacity for seismic Zone 2B compliance enables rapid vertical construction at lower engineering cost.
Egypt Residential Construction Market Vendor Landscape
Capital-heavy integrated developers compete with specialized construction contractors across Egypt's residential value chain. The market structures around three tiers: master-planned community developers with captive hospitality and retail arms, infrastructure-to-housing contractors with civil engineering capacity, and regional specialists competing on finish quality and speed-to-market. Dominant competitive moves include backward integration into land banking and forward integration into property management services.
Among integrated master-planned community developers, Talaat Moustafa Group exemplifies the archetype combining residential sales with recurring hospitality and retail revenue streams. Hassan Allam Construction and Orascom Construction occupy positions on the infrastructure-to-housing contractor vector, anchoring large-scale project delivery through captive engineering capabilities. These three entities represent distinct strategic postures within a market where scale and integration depth separate sustainable margin capture from commodity construction competition.
| Leading Market Players |
|---|
| Talaat Moustafa Group |
| Hassan Allam Construction |
| Orascom Construction |
| Gama Construction |
| Redcon Construction |
| The Arab Contractors |
| SODIC |
| BIC for Contracting & Construction |
| Palm Hills Developments |
| Others |
Supply Flow & Price Mechanics
Steel rebar costs transmit directly from global scrap metal markets through reinforced concrete frame pricing tiers, with currency availability constraints on European ceramic tile imports forcing substitution toward Gulf-sourced alternatives in premium villa specifications.
Pricing Analysis
Margin tightening in multi-family units reflects fixed-price contract exposure to rebar volatility, while single-family villa premiums absorb steel-composite engineering costs. Three-tier pricing structure across premium, standard, and economy levels separates gated compound villas from mortgage-eligible multi-family stock from informal peripheral construction. First-time buyers exhibit highest price sensitivity, constrained by Central Bank of Egypt lending thresholds. Expatriate purchasers in desert road corridors show lowest sensitivity, prioritizing seismic Zone 2B compliance and finish quality.
Supply Chain Analysis
Dual-sourcing mandates from developers facing currency disruption now qualify both European and Gulf Cooperation Council finish material suppliers. Egypt draws structural steel from Turkey, China, and Ukraine, with ceramic tile and sanitary ware dependencies resting on Italy, Spain, and UAE manufacturing bases. Single-source vulnerability concentrates in seismic engineering talent for Zone 2B design review. Distribution runs through New Urban Communities Authority-permitted developer channels rather than open wholesale markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular prefabrication is displacing cast-in-place concrete as the dominant construction methodology, compressing project timelines and reducing on-site labor dependency across New Administrative Capital developments.
For Market Incumbents: Lock in captive property management infrastructure to sustain recurring revenue beyond unit sales, while backward integration into land banking secures pipeline depth against New Urban Communities Authority allocation competition. Threats from informal construction competition in Greater Cairo peripheral zones demand formal mortgage ecosystem expansion through digital pre-qualification platforms. For New Entrants and Emerging Players: Green building envelope technology offers entry into New Administrative Capital pilot zones where green bond allocations seek deployable projects. White-space concentrates in sustainable construction methods for desert climate zones, with after-sales digital tenant service platforms as the most penetrable revenue layer. Go-to-market through Mortgage Finance Fund-registered project partnerships accelerates buyer conversion. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated master-planned community developers with hospitality and retail arms in Greater Cairo satellite cities. Long-term viability hinges on recurring revenue share exceeding unit sales dependency. The signal to watch is Mortgage Finance Fund subsidy expansion velocity as first-time buyer demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Adoption | Factory-cast wall panels compress New Administrative Capital timelines from weather-dependent sequences. |
| Green Bond Capital Mobilization | Low-carbon building envelopes attract dedicated financing pools targeting desert climate efficiency. |
| Digital Mortgage Platform Integration | Mortgage Finance Fund pre-qualification portals accelerate 6th of October City sales conversion. |
| Captive Property Management Buildout | Talaat Moustafa Group's integrated hospitality arm sustains recurring district revenue post-completion. |
| Seismic Engineering Talent Acquisition | Zone 2B compliance capacity anchors Hassan Allam's infrastructure-to-housing workflow control. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across project developers, structural engineers, Mortgage Finance Fund administrators, and finish material procurement leads. Egyptian Contractors Federation bulletins, New Urban Communities Authority permit databases, Central Bank of Egypt mortgage disbursement records, and steel import customs declarations supplied quantitative foundations. Bottom-up project pipeline enumeration triangulated against top-down construction value-added estimates from national accounts.
Data-stream reconciliation aligned permit approval timelines with mortgage origination velocity and material import flows across the projection horizon. Segmentation dimensions encompassed structural system type, buyer financing access tier, construction methodology, and regional regulatory cluster. CAGRs derived from slope-log regression on annualized permit values, with specific inputs including rebar price indices, currency availability proxies, and satellite city infrastructure completion schedules.
Several conditions sit outside the modeled scope, including informal construction volume estimation, unregistered land transaction activity, and military-affiliated project disclosure limitations. Forecasts reflect assumptions on subsidy program continuity and currency availability stabilization. Deviation in Central Bank of Egypt foreign exchange allocation policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
ASEAN Prefab Wood Buildings Market
Building Construction
Honduras Construction Market
Building Construction
GCC Cement Market
Building Construction
Kuwait Construction Market
Building Construction
Global Modular Fabrication Market
Building Construction
Russia Prefabricated Buildings Market
Building Construction
Global Dry Construction Market
Building Construction
UAE Transportation Infrastructure Construction Market
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
3D Printing Building Construction Market
Building Construction
UAE Facade Market
Building Construction
Australia Construction Market
Building Construction
Dominican Republic Construction Market
Building Construction
Early Production Facility Market
Building Construction
Vertical Garden Construction Market