
 Earthquake Sensor Market | 2026-2036
Earthquake Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Earthquake Sensor Market Analytics
Government procurement channels is reshaping how earthquake sensor manufacturers access large-scale monitoring contracts. Kinemetrics Inc. leverages its established relationships with national seismic networks across multiple continents. Güralp Systems Ltd. anchors its position through deep specialization in broadband seismometers for research-grade applications. Nanometrics Inc. competes aggressively on digital telemetry integration and real-time data streaming capabilities.
Earthquake sensors are instruments that detect ground motion through inertial mass-spring systems, piezoelectric crystals, or fiber optic interferometry, typically measuring acceleration from micro-g to several g with frequencies spanning DC to 100 Hz for seismic applications. Their primary purpose is to provide early warning signals, structural response data, and post-event analysis for hazard mitigation. Accelerometers dominate product type revenue due to their versatility across structural health monitoring deployments, while fiber optic technology represents the fastest-growing segment as it offers immunity to electromagnetic interference and enables distributed sensing over kilometer-scale distances. Wireless technology is maturing rapidly in disaster management applications where rapid deployment without fixed infrastructure proves critical.
FEMA guidelines in the United States, Japan's METI technical standards for seismic instrumentation, and the EU's CSRD disclosure requirements for infrastructure resilience collectively shape product certification pathways and public funding eligibility. Japan's Building Standard Law mandates specific sensor performance thresholds for high-rise structures, directly driving replacement cycles and upgrade demand. Stakeholders must monitor how evolving building codes in seismically active zones redefine minimum sensor density requirements and data interoperability standards.
Market Dynamics
Government seismic network expansion is compressing procurement cycles and forcing manufacturers to pre-certify products against multiple national standards simultaneously. MEMS miniaturization is simultaneously lowering unit costs and enabling dense urban deployments that were previously economically unfeasible.
Growth Catalysts
- Japan's Building Standard Law:Mandatory sensor thresholds for high-rise structures are forcing replacement cycles across Tokyo, Osaka, and Yokohama commercial portfolios.
- Fiber optic distributed sensing:Immunity to electromagnetic interference enables kilometer-scale infrastructure monitoring along pipelines, bridges, and rail corridors.
- Wireless rapid-deployment protocols:Post-disaster temporary networks in seismically active zones eliminate fixed infrastructure dependencies for emergency response agencies.
Market Restraints
- Piezoelectric crystal supply concentration:Synthetic quartz production clusters in limited geographic zones create input vulnerability for broadband seismometer manufacturers.
- EU CSRD disclosure complexity:Infrastructure resilience reporting requirements impose documentation burdens that elongate public procurement timelines.
- MEMS noise-floor limitations:Micro-electromechanical systems struggle to match research-grade electromechanical sensors for weak-motion detection applications.
Strategic Opportunities
- Indonesia's national early warning system:Archipelago geography and subduction zone exposure create demand for 8,000+ additional sensor nodes across Sumatra and Java.
- AI-driven real-time processing:Machine learning integration with digital telemetry enables sub-second earthquake detection and automated structural response triggering.
- Subscription telemetry services:Cloud-based data streaming replaces capital-intensive on-premise seismic processing for municipal governments and universities.
Industry Challenges
- Seismologist-data engineer skill gap:Hybrid expertise combining geophysical interpretation with IoT network management remains scarce across installation and maintenance functions.
- Multi-standard certification timelines:Simultaneous FEMA, METI, and ISO compliance testing extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earthquake Sensor Market |
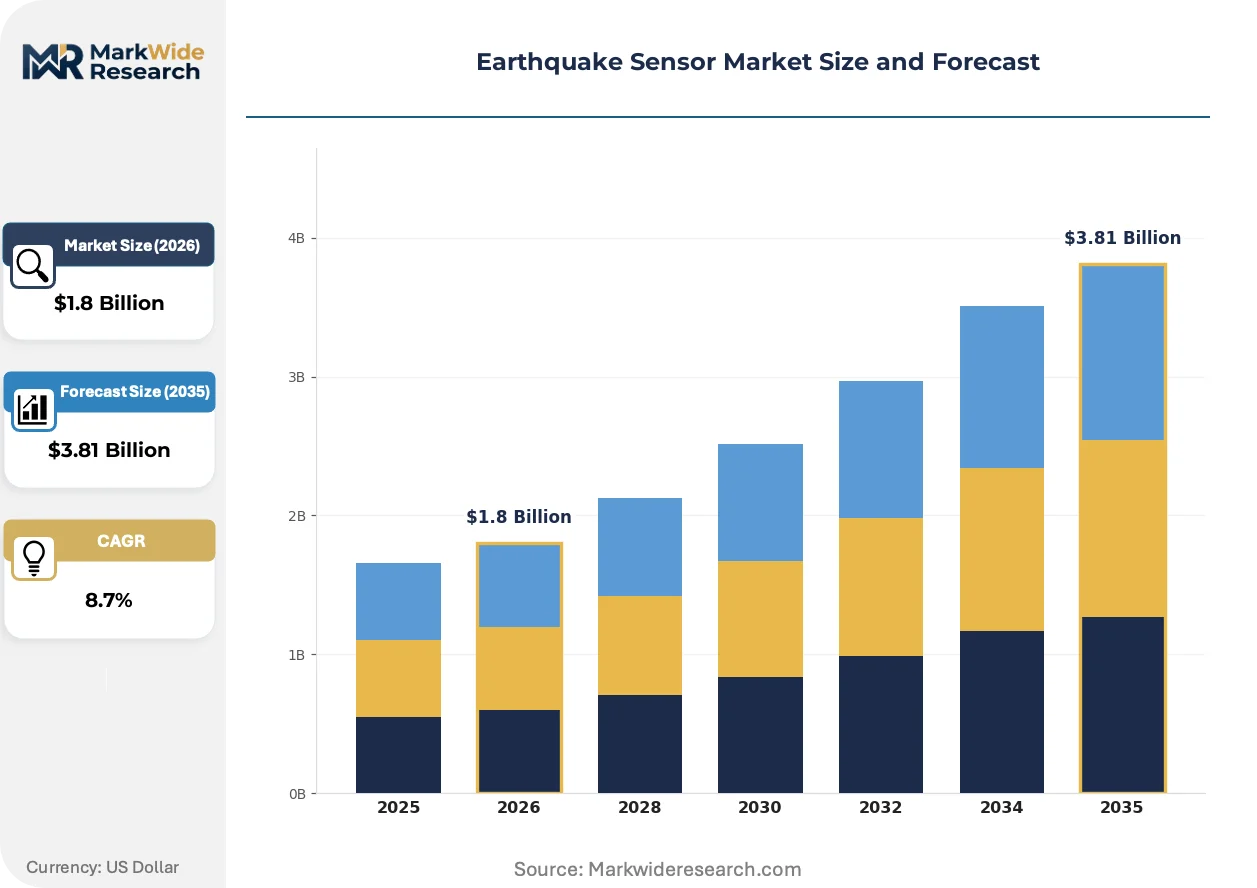
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seismic Sensors, Accelerometers, Geophones, Displacement Sensors Technology: Analog, Digital, Wireless, Fiber Optic End User: Government Agencies, Research Institutions, Oil & Gas Companies, Construction Firms Application: Seismology, Structural Health Monitoring, Tsunami Warning, Disaster Management |
| Companies Covered | Kinemetrics Inc., Güralp Systems Ltd., GeoSIG Ltd., Nanometrics Inc., Sercel, REF TEK, Azbil, GEObit Instruments, Meisei Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earthquake Sensor Market Evolving Landscape
Silicon photonics and edge computing are converging to transform how seismic data is captured, processed, and acted upon at the network periphery. These shifts are compressing the value chain and redefining competitive differentiation.
MEMS accelerometer arrays with onboard digital signal processing are rendering obsolete electromechanical velocity sensors for structural health monitoring applications. Building operators in California and Japan are specifying chip-scale packages for new construction, eliminating the mechanical calibration and thermal drift maintenance that analog systems require. The shift is compressing sensor replacement cycles from decade-long intervals to technology-refresh timelines.
The EU's Corporate Sustainability Reporting Directive is mandating infrastructure resilience disclosure for critical asset operators. Seismic instrumentation now qualifies as climate adaptation expenditure under CSRD scope, unlocking green financing instruments for public monitoring networks. European utilities and transport operators are accelerating sensor deployment to meet 2026 disclosure deadlines.
Performance-based service contracts are displacing equipment-only procurement in government seismic networks. Chile's national network and New Zealand's GeoNet now specify uptime guarantees and data latency thresholds rather than hardware specifications. Vendors absorb sensor maintenance and telemetry costs, shifting capital expenditure to operational budgets and locking in decade-long relationships.
Earthquake Sensor Market Segmentation
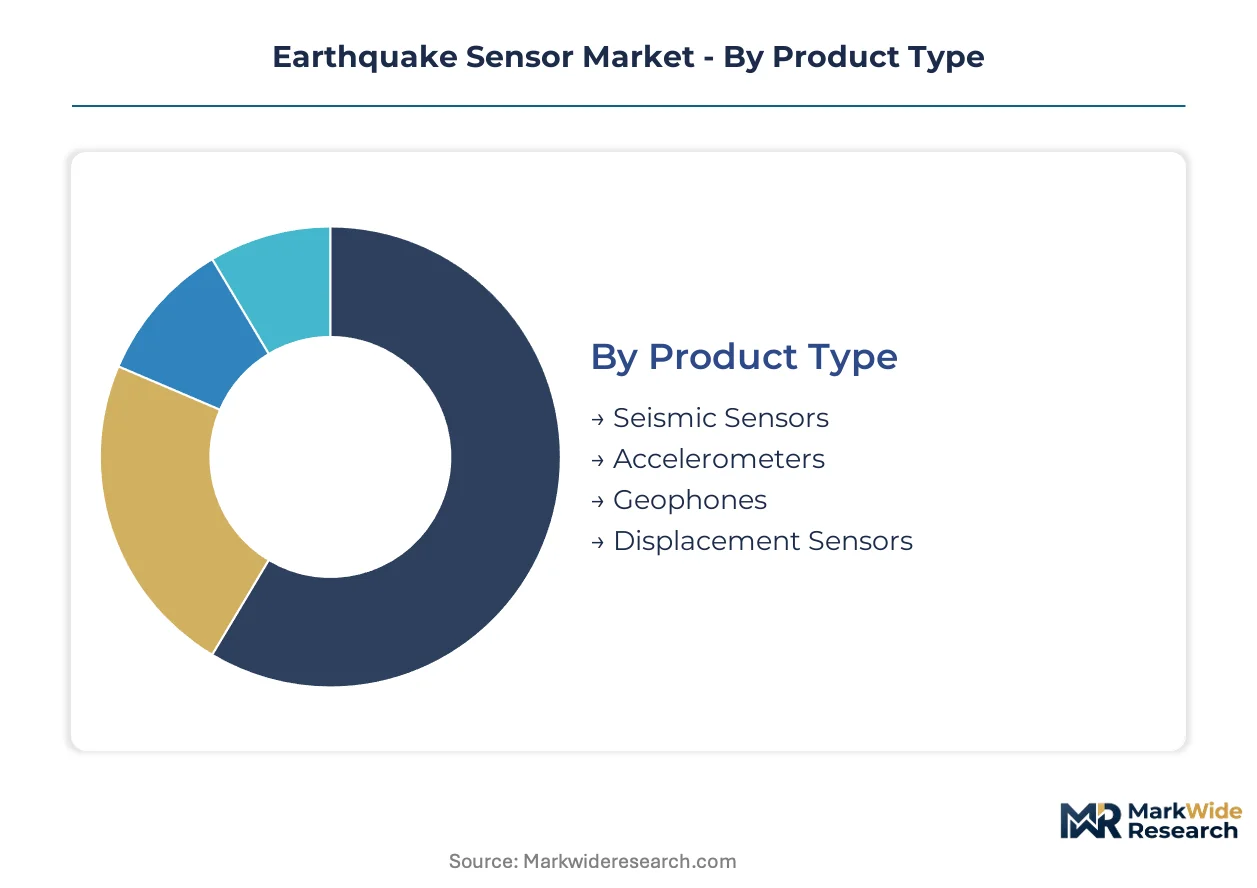
Segmentation in earthquake sensors reveals distinct service intensity profiles across product architectures. Installation complexity, calibration frequency, and telemetry maintenance requirements vary sharply between electromechanical and solid-state technologies.
Product Type:
After-sales service intensity diverges substantially across sensor architectures, with electromechanical systems demanding periodic recalibration and MEMS-based units requiring minimal field intervention.
- Seismic Sensors:Broadband seismometers utilize suspended mass-spring systems with force-feedback electronics to detect ground velocities from micro-g to several g across DC to 100 Hz bandwidth. Research institutions in Japan and California anchor procurement for permanent network installations where thermal stability and long-term drift specifications dominate vendor selection.
- Accelerometers:MEMS-based chip-scale packages integrate capacitive sensing elements with onboard digital signal processing, eliminating mechanical calibration requirements. Construction firms in Tokyo, Osaka, and Yokohama specify these for high-rise structural health monitoring under Japan's Building Standard Law mandates.
- Geophones:Moving-coil velocity sensors optimized for reflection seismology in oil and gas exploration.
- Displacement Sensors:Laser and fiber optic interferometers measuring absolute ground displacement for geodetic applications.
By volume, Accelerometers lead. By growth pace, Seismic Sensors is ahead.
Technology:
Cost tier stratification separates legacy analog deployments from premium digital and fiber optic installations, with wireless protocols capturing mid-market rapid-deployment scenarios.
- Analog:Voltage-output sensors with external digitization remain prevalent in legacy government seismic networks where wholesale infrastructure replacement faces budget constraints.
- Digital:Integrated analog-to-digital converters with embedded calibration coefficients and real-time telemetry streaming. Government agencies across Indonesia and Chile specify these for national early warning networks where sub-second latency thresholds are mandatory.
- Wireless:Battery-powered nodes with mesh networking protocols eliminate fixed infrastructure for post-disaster temporary deployments. Disaster management agencies in seismically active zones favor these for rapid network establishment.
- Fiber Optic:Distributed acoustic sensing converts standard telecommunications fiber into continuous seismic arrays, offering immunity to electromagnetic interference. Pipeline operators and rail corridors specify these for kilometer-scale infrastructure monitoring where conventional point sensors prove economically unfeasible.
By installed base, Analog dominates. By expansion trajectory, Fiber Optic is climbing the fastest.
End User:
Customer type determines procurement modality, with government agencies favoring performance-based service contracts and research institutions prioritizing technical specifications over cost optimization.
- Government Agencies:National seismic networks and early warning systems specify uptime guarantees and data latency thresholds rather than hardware specifications. Chile and New Zealand have shifted to decade-long service contracts where vendors absorb maintenance and telemetry costs.
- Research Institutions:Broadband seismometer procurement for global seismic monitoring and academic research networks. These buyers prioritize low-noise specifications and open data formats over unit economics.
- Oil & Gas Companies:Exploration seismology and reservoir monitoring applications drive geophone and nodal accelerometer demand.
- Construction Firms:Structural health monitoring mandates in Japan and California accelerate MEMS accelerometer deployment for new high-rise construction.
By contract value, Government Agencies lead. By specification intensity, Research Institutions sets the pace.
Application:
Application maturity varies from established seismology networks to emerging AI-driven structural response automation, with service revenue potential scaling alongside real-time processing requirements.
- Seismology:Permanent global and regional seismic networks for earthquake detection, location, and magnitude determination. Government-funded networks in Japan, the United States, and Europe maintain the largest installed bases with systematic replacement cycles.
- Structural Health Monitoring:Real-time building response measurement for automated safety system triggering. Japan's Building Standard Law mandates specific sensor performance thresholds for high-rise structures in Tokyo, Osaka, and Yokohama.
- Tsunami Warning:Offshore and coastal sensor networks for rapid sea-level displacement detection and warning dissemination.
- Disaster Management:Rapid-deployment temporary networks for post-earthquake damage assessment and emergency response coordination.
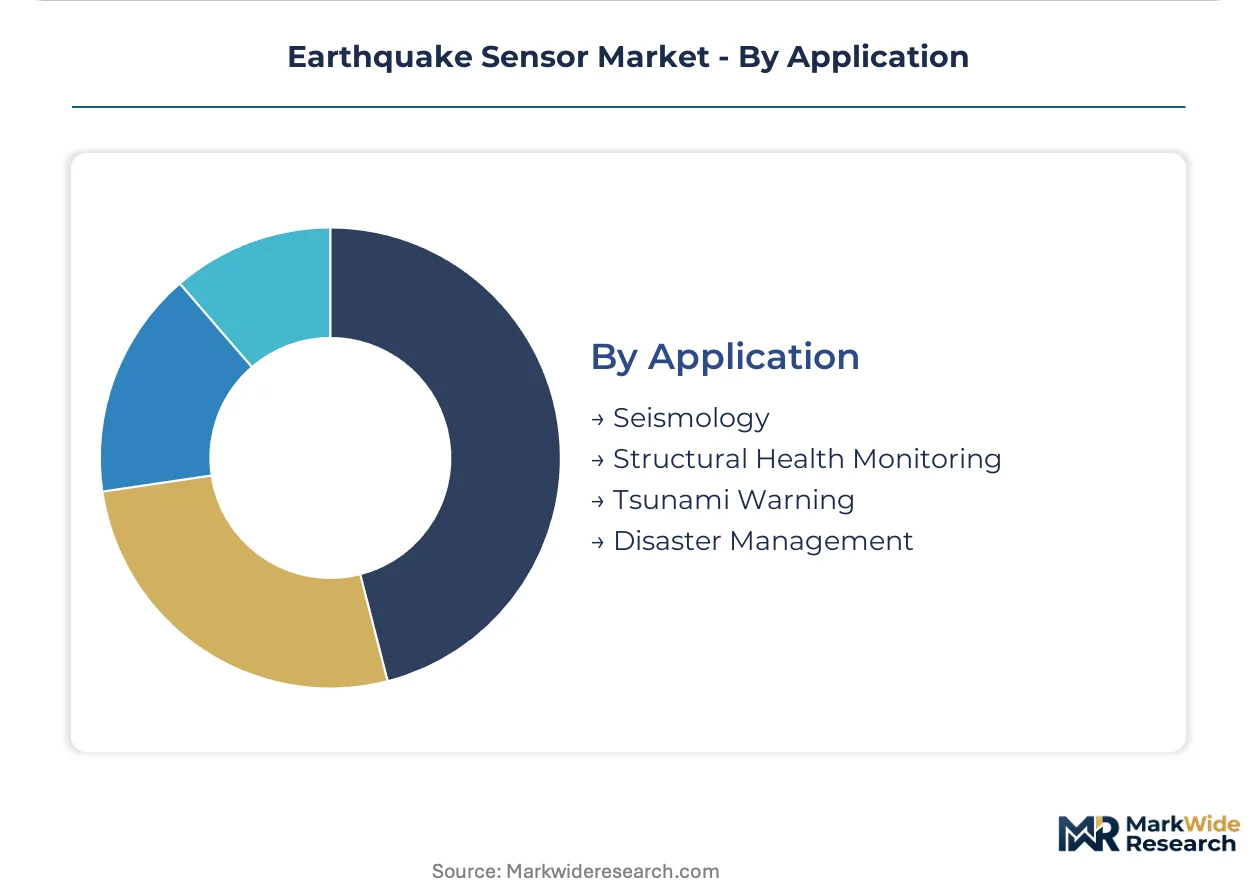
By network maturity, Seismology leads. By deployment velocity, Disaster Management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands premium pricing for research-grade instrumentation while Indonesia operates on compressed procurement budgets for network-scale deployment. This asymmetry shapes vendor portfolio stratification across the Pacific Rim.
United States
FEMA guidelines and USGS network modernization drive demand for digital telemetry systems. The Infrastructure Investment and Jobs Act channels funding toward seismic resilience in critical infrastructure. California's dense urban corridors concentrate deployment, with Los Angeles and San Francisco metropolitan areas mandating structural health monitoring for high-rise construction.
Japan
METI technical standards and the Building Standard Law enforce strict sensor performance thresholds for high-rise structures. National seismic network expansion targets subduction zone monitoring with real-time early warning capabilities. Tokyo, Osaka, and Yokohama commercial portfolios face systematic replacement cycles under mandatory compliance deadlines.
Indonesia
Archipelago geography and Sumatra-Java subduction exposure create demand for over 8,000 additional sensor nodes. The national early warning system procurement prioritizes cost-optimized digital sensors with wireless mesh capabilities. Jakarta and Bandung serve as logistics hubs for network deployment across the volcanic arc.
Chile
Performance-based service contracts now dominate government procurement for the national seismic network. SERNAGEOMIN specifications emphasize uptime guarantees and data latency thresholds over hardware specifications. Santiago anchors vendor operations, with Valparaíso and Concepción hosting dense instrumentation clusters along the subduction margin.
Germany
EU CSRD disclosure requirements for infrastructure resilience unlock green financing instruments for seismic monitoring. Research institutions prioritize broadband seismometers with open data format compatibility. Bavaria and Baden-Württemberg concentrate academic procurement, while North Rhine-Westphalia utilities accelerate deployment for critical asset disclosure compliance.
Earthquake Sensor Market Competitive Landscape
Research-grade specialists and network-scale integrators split the market between specification-driven and procurement-optimized segments. The vendor base concentrates around three strategic archetypes: broadband seismometer purists serving academic networks, MEMS-accelerator fabricators targeting structural health mandates, and telemetry-integrated platform providers capturing government early-warning contracts. Consolidation pressure intensifies through strategic partnerships bridging hardware manufacturing with cloud-based data services, while portfolio diversification into adjacent geophysical instrumentation expands addressable revenue per installed node.
Within the research-grade tier, Kinemetrics Inc. and Güralp Systems Ltd. occupy positions anchored by established relationships with national seismic networks across multiple continents. Nanometrics Inc. exemplifies the telemetry-integrated archetype, competing aggressively on digital data streaming capabilities and real-time processing architectures. These three entities represent distinct competitive vectors: Kinemetrics leverages multi-continental network relationships, Güralp anchors through deep specialization in broadband instrumentation, and Nanometrics drives differentiation through digital-native platform integration.
| Leading Market Players |
|---|
| Kinemetrics Inc. |
| Güralp Systems Ltd. |
| GeoSIG Ltd. |
| Nanometrics Inc. |
| Sercel |
| REF TEK |
| Azbil |
| GEObit Instruments |
| Meisei Electric |
| Others |
Value Network & Pricing Analysis
The Pacific Rim container freight corridor from Yokohama to Los Angeles carries precision seismometer components and MEMS wafers at rates that compress margins for mid-tier manufacturers while amplifying price premiums for research-grade instrumentation with expedited customs handling.
Pricing Analysis
The customization-premium spread between configured-to-order broadband seismometers and standard MEMS accelerometer units spans roughly three-to-one, with research institutions absorbing premium pricing for low-noise specifications while construction firms in Tokyo and Osaka drive standard-tier volume procurement. Pricing stratifies across research-grade, industrial-grade, and commercial-grade certification tiers, with METI-compliant installations commanding additional compliance premiums. Pricing pressure stems from Indonesian government tenders prioritizing cost-optimized digital sensors for network-scale deployment. Government agencies exhibit lowest price sensitivity due to performance-based service contract structures, while municipal early-warning programs in developing seismic networks demonstrate highest sensitivity.
Supply Chain Analysis
Export-control regimes governing force-feedback electronics and high-precision quartz resonators limit technology flows from Japan and the United States to certain national seismic programs, fragmenting supplier access. Manufacturing concentrates in Japan, the United States, and Switzerland for research-grade instrumentation, with MEMS fabrication anchored in Taiwan and South Korea. Synthetic quartz crystal supply rests on limited geographic production zones, creating single-source vulnerability for broadband seismometer manufacturers. Distribution runs through government procurement channels and authorized seismic network integrators rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Government procurement consolidation into decade-long performance-based service contracts has shifted buyer power toward national seismic networks, compressing vendor margins while locking in long-term relationships.
For Market Incumbents: Build telemetry-integration moats through cloud-based data streaming platforms that embed switching costs. Absorb maintenance and sensor replacement costs within subscription structures to preempt challenger price undercutting. Pursue backward integration into MEMS foundry partnerships to secure volume supply for structural health monitoring mandates. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's national early-warning system procurement, where cost-optimized digital sensors with wireless mesh capabilities face limited incumbent saturation. Target rapid-deployment disaster management applications where fixed infrastructure constraints favor battery-powered nodal architectures. Lead with AI-driven real-time processing as a differentiated service layer rather than hardware-only positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors telemetry-integrated platform providers over pure hardware manufacturers, as service revenue compounds per-node economics. Long-term viability hinges on recurring data-streaming relationships rather than transactional equipment sales. Monitor Indonesia's 8,000-node procurement timeline and Chile's contract renewal cycles as inflection indicators for platform-provider valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Secures captive supply for Japan's Building Standard Law-mandated high-rise deployments. |
| AI Real-Time Processing Integration | Enables sub-second earthquake detection for Indonesia's national early-warning network specifications. |
| Performance-Based Service Contract | Shifts Chile and New Zealand procurement from capital expenditure to operational budget capture. |
| Fiber Optic Distributed Sensing Deployment | Unlocks kilometer-scale pipeline and rail corridor monitoring previously uneconomical with point sensors. |
| Cloud Telemetry Platform Launch | Replaces on-premise seismic processing for municipal governments and university networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with seismic network directors at government agencies, procurement officers at national meteorological institutes, R&D heads at MEMS foundries, and installation contractors for structural health monitoring systems. Secondary validation drew from FEMA guideline documentation, METI technical standard filings, EU CSRD infrastructure resilience disclosure frameworks, USGS network modernization reports, and customs data on seismometer component trade flows. Bottom-up unit economics triangulated against top-down government budget appropriations for seismic monitoring networks.
Calibration across historical procurement cycles, replacement timelines under Japan's Building Standard Law, and Indonesia's national early-warning system deployment schedule anchored volume projections. Segmentation dimensions modeled include product architecture, technology tier, end-user procurement modality, and application real-time processing intensity. CAGRs were derived from elasticity-adjusted demand curves across government network expansion, MEMS cost curves, and fiber optic distributed sensing adoption rates.
Macroeconomic conditions sit as an overlay; deviation in public infrastructure spending cycles, semiconductor capital expenditure patterns, or rare earth export restrictions would shift the trajectory. Forecasts reflect documented assumptions on government procurement continuity, MEMS noise-floor improvement rates, and fiber optic sensing cost reduction curves. Material shifts in Japan's mandatory replacement deadlines, Indonesia's funding authorization, or export-control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Glove Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Current Sensor Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Multi Touch Sensing Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Laser Scanner Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
Asia-Pacific MEMS and Sensors Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
Body Worn Temperature Sensors Market