
 Odor Sensor Market | 2026-2036
Odor Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Odor Sensor Market Analysis
The EU Green Deal's industrial emissions monitoring mandates is repositioning odor sensor procurement across European manufacturing. Sensirion AG leverages its MEMS-based gas sensing platform to dominate precision environmental monitoring applications. Figaro Engineering anchors the metal-oxide semiconductor segment through decades of sensor material expertise. NEW COSMOS ELECTRIC sustains leadership in combustible gas and odor detection for industrial safety systems across East Asian markets.
An odor sensor detects and quantifies volatile organic compounds and specific malodorous molecules through transduction mechanisms that convert chemical interactions into measurable electrical or optical signals, typically achieving detection thresholds in the parts-per-billion range for applications requiring real-time air quality assessment. Metal-oxide semiconductor technology occupies the largest installed base due to mature manufacturing economics, while optical sensors and nanotechnology represent the fastest-expanding technology categories as photonic integration and graphene-based materials enable superior selectivity. Fixed sensors lead in industrial deployment scale, though wearable sensors are gaining traction in healthcare and personal exposure monitoring where miniaturization and low power consumption command premium positioning.
The US Environmental Protection Agency enforces ambient air quality standards that mandate continuous emissions monitoring at industrial facilities, directly expanding demand for calibrated odor detection systems. Japan's Ministry of Economy, Trade and Industry promotes sensor technology development through JIS standards harmonization and smart factory initiatives. China's Ministry of Ecology and Environment implements dual carbon goals that tighten volatile organic compound discharge limits across chemical and petrochemical sectors. Stakeholders must monitor regulatory divergence between jurisdictions as compliance thresholds fragment certification requirements and reshape product development roadmaps.
Market Dynamics
Smart manufacturing adoption in Germany's automotive sector is embedding odor detection into quality assurance workflows, compressing deployment timelines and reshaping procurement specifications across precision electronics supply chains.
Growth Catalysts
- EU Green Deal industrial emissions mandates:The EU Green Deal's tightening compliance requirements are mandating continuous odor monitoring at chemical processing facilities across member states.
- MEMS miniaturization:Advances in microelectromechanical systems are enabling wearable form factors for personal exposure monitoring in healthcare applications.
- Japan's smart factory initiatives:METI's JIS standards harmonization is accelerating sensor integration into automated quality control systems for precision manufacturing.
Market Restraints
- Palladium supply concentration:Metal-oxide semiconductor production depends on palladium inputs concentrated in Russian and South African mining operations.
- Cross-sensitivity limitations:Existing metal-oxide sensors struggle with humidity interference in tropical climates, degrading measurement reliability.
- REACH certification costs:European chemical compliance testing adds eighteen to twenty-four months to product launch timelines for new sensing materials.
Strategic Opportunities
- China's dual carbon enforcement:MEE volatile organic compound discharge limits are creating replacement demand across petrochemical clusters in Shandong and Jiangsu provinces.
- Optical-graphene convergence:Photonic integration with graphene-based materials is opening selectivity improvements for food freshness monitoring applications.
- Direct-to-facility distribution:Bypassing traditional instrumentation distributors through embedded sensor partnerships with HVAC original equipment manufacturers.
Industry Challenges
- Calibration technician scarcity:Certified odor sensor calibration requires specialized training programs that few technical institutes currently offer.
- Legacy system integration:Brownfield industrial facilities face protocol mismatches between new optical sensors and existing SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Odor Sensor Market |
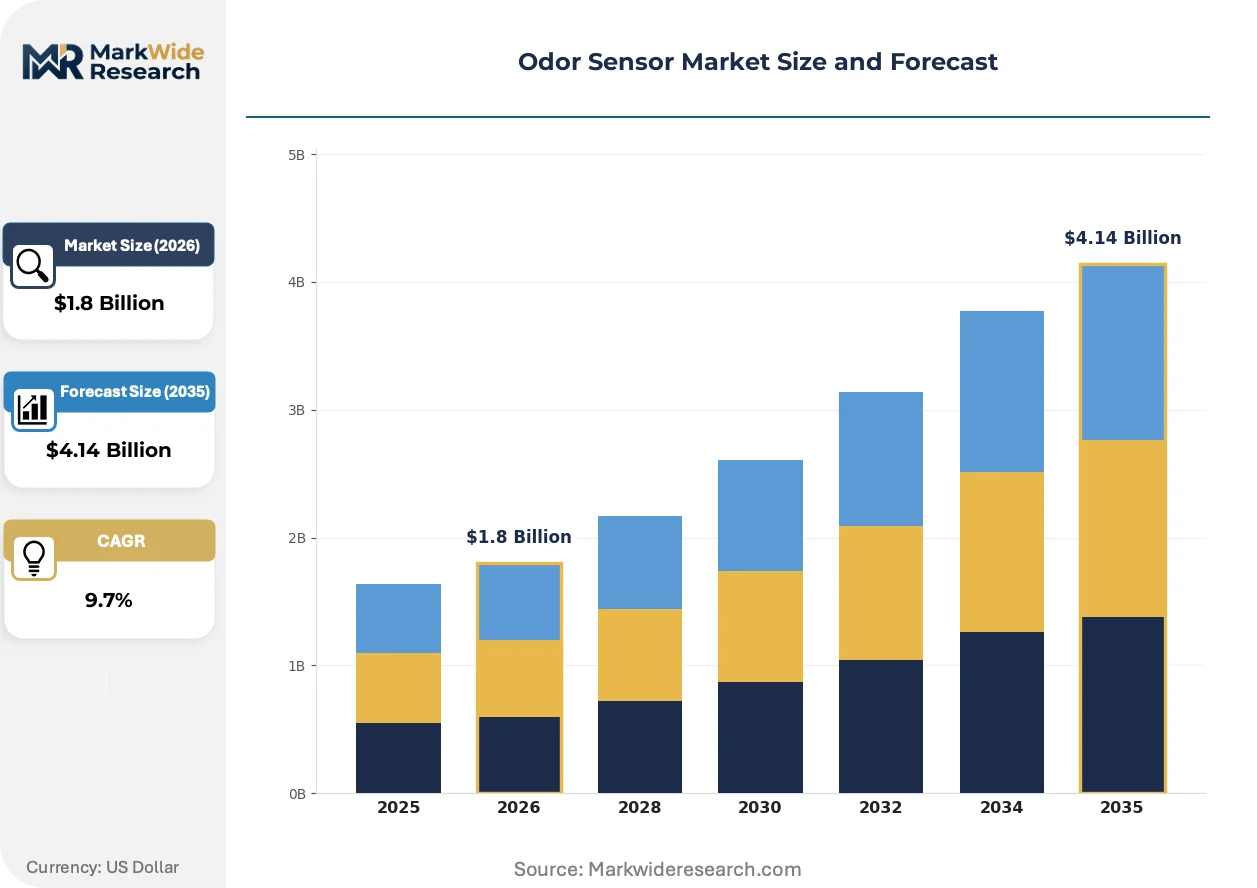
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Sensors, Fixed Sensors, Integrated Sensors, Wearable Sensors Technology: Electrochemical, Metal-Oxide Semiconductors, Optical Sensors, Nanotechnology Application: Food Safety, Air Quality Monitoring, Industrial Safety, Waste Management End User: Manufacturing, Healthcare, Agriculture, Environmental Monitoring |
| Companies Covered | Sensirion AG, NEW COSMOS ELECTRIC, Figaro Engineering, Aeroqual, Honeywell International, Airsense Analytics GmbH, Aryballe Technologies, Odotech Inc., Alpha MOS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Odor Sensor Market Emerging Trajectories
Sensor architectures are fragmenting across three vectors: transduction physics, deployment form factors, and data processing locations. This fragmentation is compressing traditional technology lifecycles and forcing modular design approaches.
Nanotechnology-enabled sensing is decentralizing odor detection from centralized laboratory gas chromatography to edge-deployed devices. Automotive suppliers in Japan are adopting graphene-based arrays for cabin air quality management. This shift is decentralizing analytical capability from quality labs to production lines, compressing feedback loops from hours to seconds.
REACH regulation amendments are tightening volatile organic compound threshold reporting for chemical manufacturers. Industrial facilities must now deploy continuous monitoring rather than periodic stack testing. German chemical processors are retrofitting fixed sensor networks to avoid penalty structures under the updated framework.
Buyers are unbundling sensor hardware from calibration service contracts. Large industrial operators in the US are bringing metrology verification in-house, displacing original equipment manufacturer service agreements. This pattern is most visible in EPA-regulated facilities where internal environmental compliance teams have expanded technical capabilities.
Odor Sensor Market Segmentation
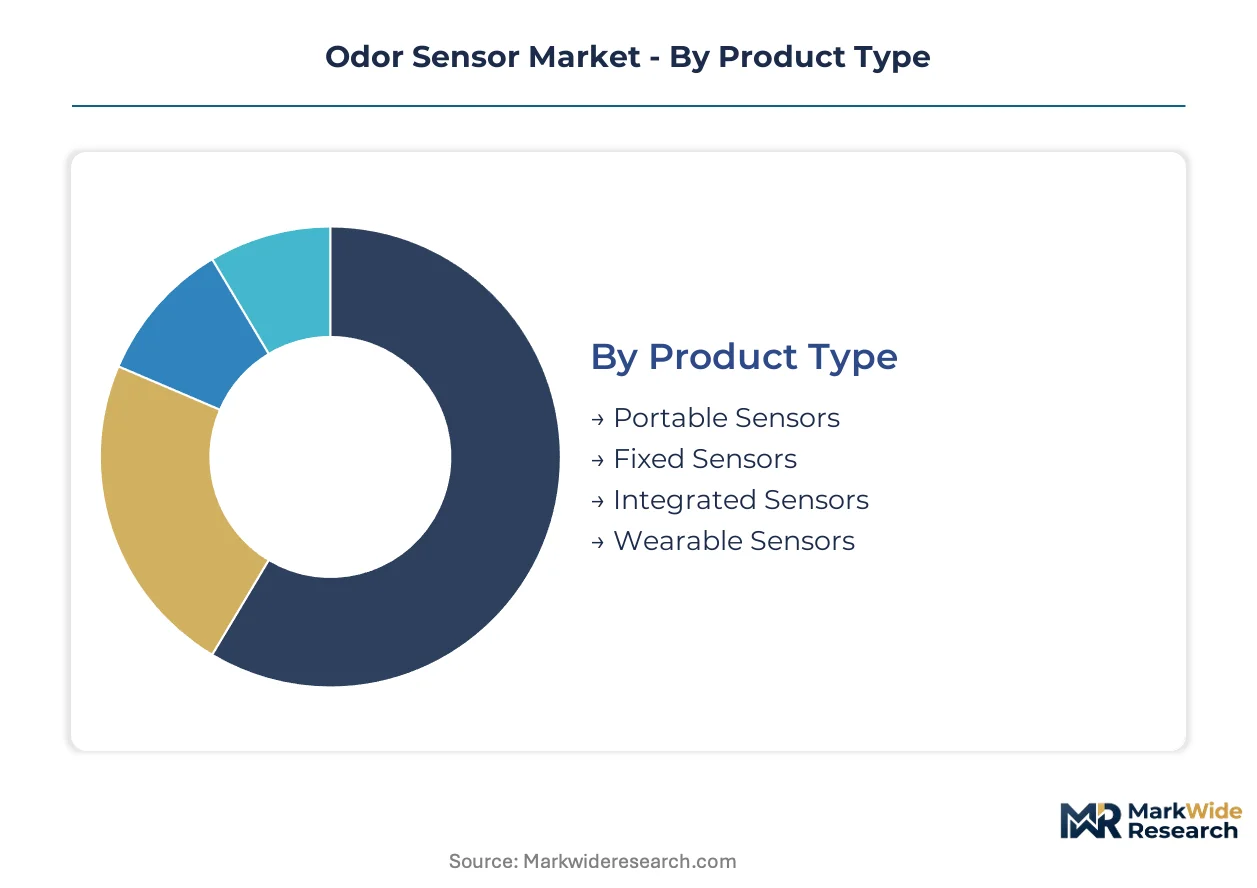
Odor sensor procurement patterns diverge sharply across deployment contexts, with industrial buyers prioritizing calibration stability while consumer-facing applications demand miniaturization. Technology selection and form factor decisions cascade through regulatory compliance requirements and maintenance economics.
Product Type:
Supply concentration for fixed sensor assemblies centers on German and Japanese precision manufacturers with captive MEMS fabrication capacity, compressing lead times for large industrial orders while squeezing margins for modular suppliers.
- Fixed Sensors:Stationary installations with hardwired power and data connections dominate petrochemical and wastewater treatment facilities. Demand concentrates in Germany's chemical processing corridor where EU Green Deal mandates require continuous emissions verification at discharge points.
- Portable Sensors:Battery-operated handheld units with onboard data logging serve field inspection and emergency response roles. Procurement is accelerating across China's environmental enforcement agencies conducting spot checks at Shandong province manufacturing clusters.
- Wearable Sensors:Miniaturized personal exposure monitors with Bluetooth connectivity target occupational health programs.
- Integrated Sensors:Embedded modules designed for HVAC and appliance OEM integration.
Fixed sensors absorb the bulk of installed capacity; portable sensors are expanding most quickly.
Technology:
Cost tier stratification separates mature metal-oxide production from premium optical and nanotechnology platforms, with foundry economics determining accessible price points for volume applications.
- Metal-Oxide Semiconductors:Tin dioxide and zinc oxide films on ceramic substrates achieve parts-per-million detection thresholds through resistance changes upon gas adsorption. Manufacturing concentrates in Japanese suppliers serving automotive cabin air systems under METI harmonized standards.
- Optical Sensors:Photonic detection using infrared absorption or fluorescence quenching delivers superior selectivity for complex gas mixtures. Demand is climbing fastest in food freshness monitoring across European retail cold chains where false positives from humidity interference are unacceptable.
- Electrochemical:Amperometric cells with liquid electrolyte barriers for targeted gas specificity.
- Nanotechnology:Graphene and carbon nanotube architectures enabling sub-ppb detection limits.
Metal-oxide semiconductors retain the largest installed base; nanotechnology is gaining share fastest.
Application:
Volume concentration tracks regulatory enforcement intensity, with air quality and industrial safety deployments outpacing food safety adoption in absolute unit terms.
- Industrial Safety:Combustible gas and toxic vapor detection for worker protection and explosion prevention. Procurement is concentrating in Japan's automotive supply chain where JIS-certified sensors integrate into automated quality gates.
- Air Quality Monitoring:Ambient and indoor VOC tracking for regulatory compliance and ventilation control. China's MEE dual carbon enforcement is driving replacement cycles across Jiangsu province chemical parks.
- Food Safety:Spoilage indicator detection for cold chain integrity.
- Waste Management:Landfill and composting facility odor emission tracking.
Industrial safety absorbs the bulk of installed capacity; air quality monitoring is expanding most quickly.
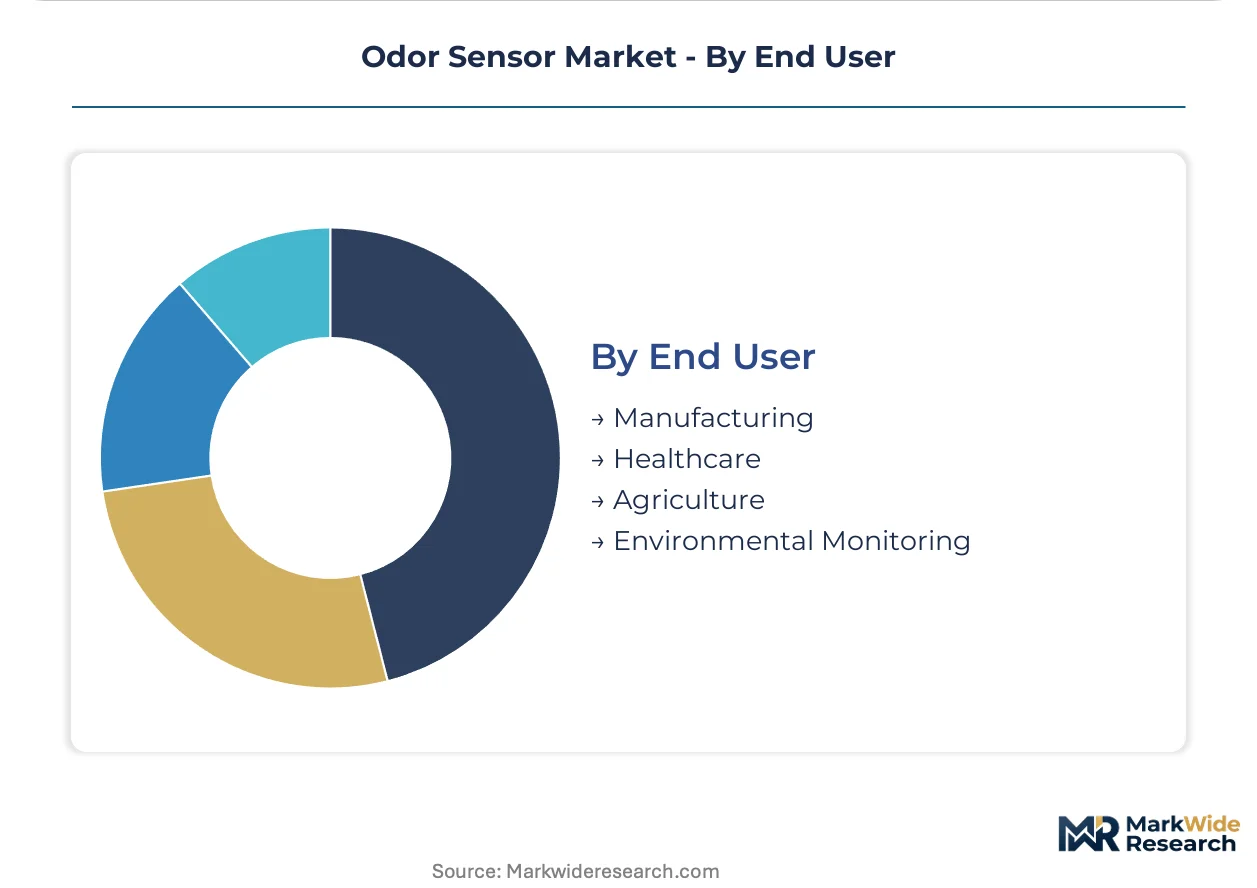
End User:
Customer type determines specification rigor, with environmental monitoring agencies demanding full traceability while agricultural buyers prioritize field durability over laboratory precision.
- Manufacturing:Process control and quality assurance integration across automotive, electronics, and chemical production. Germany's smart factory initiatives are embedding odor detection into paint shop and adhesive curing workflows.
- Environmental Monitoring:Regulatory compliance networks for ambient air and stack emissions. EPA-mandated continuous emissions monitoring systems in the US require calibrated optical sensors with quarterly verification protocols.
- Healthcare:Breath analysis and infection control applications.
- Agriculture:Livestock facility ammonia monitoring and grain storage spoilage detection.
Manufacturing absorbs the bulk of installed capacity; environmental monitoring is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Japanese and German precision manufacturing clusters while consumption spreads across regulatory enforcement zones in China, the United States, and European industrial corridors.
United States
EPA-mandated continuous emissions monitoring systems drive procurement across petrochemical facilities along the Gulf Coast. The Clean Air Act amendments require quarterly calibration verification for optical sensors at major stationary sources. Houston's refining corridor hosts the densest sensor network deployments for stack emissions compliance.
Germany
Smart factory initiatives in automotive paint shops embed odor detection into quality assurance workflows. EU Green Deal industrial emissions mandates tighten volatile organic compound thresholds for chemical processors. The Ruhr industrial belt leads retrofit installations of fixed sensor networks to avoid penalty structures.
China
MEE dual carbon enforcement creates replacement demand across Shandong and Jiangsu province chemical parks. National volatile organic compound discharge limits now require continuous monitoring rather than periodic stack testing. Yangtze River Delta manufacturing clusters deploy portable sensors for environmental enforcement spot checks.
Japan
METI's JIS standards harmonization accelerates sensor integration into automated quality control systems. Automotive supply chains demand JIS-certified sensors for cabin air quality management. Kansai region electronics manufacturers adopt graphene-based arrays for production line feedback loops.
South Korea
Semiconductor fabrication facilities deploy metal-oxide sensors for process gas monitoring under national industrial safety codes. The Ministry of Employment and Labor mandates combustible gas detection in high-tech manufacturing zones. Gyeonggi-do province hosts the fastest sensor replacement cycles for foundry air handling systems.
Odor Sensor Market Vendor Landscape
The competitive structure tilts toward technology specialists with captive MEMS fabrication capacity. Japanese and Swiss precision manufacturers hold supply-side concentration through decades of sensor material expertise. Three archetypes dominate: integrated device manufacturers with in-house foundries, modular suppliers sourcing wafers externally, and application-specific software-layer specialists. Capacity expansion in graphene-based platforms and strategic partnerships with HVAC original equipment manufacturers represent the dominant competitive vectors.
Among Swiss precision specialists, Sensirion AG exemplifies the integrated MEMS platform archetype. Japanese metal-oxide semiconductor specialists Figaro Engineering and NEW COSMOS ELECTRIC occupy positions anchoring industrial safety and combustible gas detection segments. These three represent distinct competitive postures: MEMS miniaturization leadership, decades-long material science accumulation, and East Asian market penetration depth respectively.
| Leading Market Players |
|---|
| Sensirion AG |
| NEW COSMOS ELECTRIC |
| Figaro Engineering |
| Aeroqual |
| Honeywell International |
| Airsense Analytics GmbH |
| Aryballe Technologies |
| Odotech Inc. |
| Alpha MOS |
| Others |
Supply Flow & Price Mechanics
EPA-regulated petrochemical operators concentrate procurement for continuous emissions monitoring systems, anchoring contract-based long-term offtake pricing that bundles hardware with mandatory calibration services. This buyer archetype's compliance-driven purchasing power compresses margins for modular suppliers while rewarding integrated device manufacturers with captive MEMS fabrication.
Pricing Analysis
Cost-down pressure on standard-grade metal-oxide sensors accelerates because Chinese environmental enforcement agencies are consolidating portable sensor procurement through centralized tenders. Three-tier pricing structure across premium optical, standard electrochemical, and economy metal-oxide levels separates JIS-certified units for Japanese automotive OEMs from unbranded modules for spot-check applications. REACH certification costs and palladium input volatility drive pricing pressure upward, with agricultural buyers in livestock monitoring showing highest price sensitivity and German chemical processors showing lowest due to penalty avoidance calculus.
Supply Chain Analysis
Calibration technician shortages in Japan and Germany constrain output expansion for precision optical sensor assemblies. Manufacturing gravity centers on Japanese metal-oxide specialists, Swiss MEMS foundries, and South Korean semiconductor fabrication facilities. Palladium for sensing films draws from Russian and South African mining operations; graphene nanomaterials hinge on Chinese chemical vapor deposition capacity. Single-source vulnerability in noble metal inputs threatens continuity. Distribution runs through HVAC original equipment manufacturer partnerships and industrial instrumentation distributors serving EPA-regulated facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
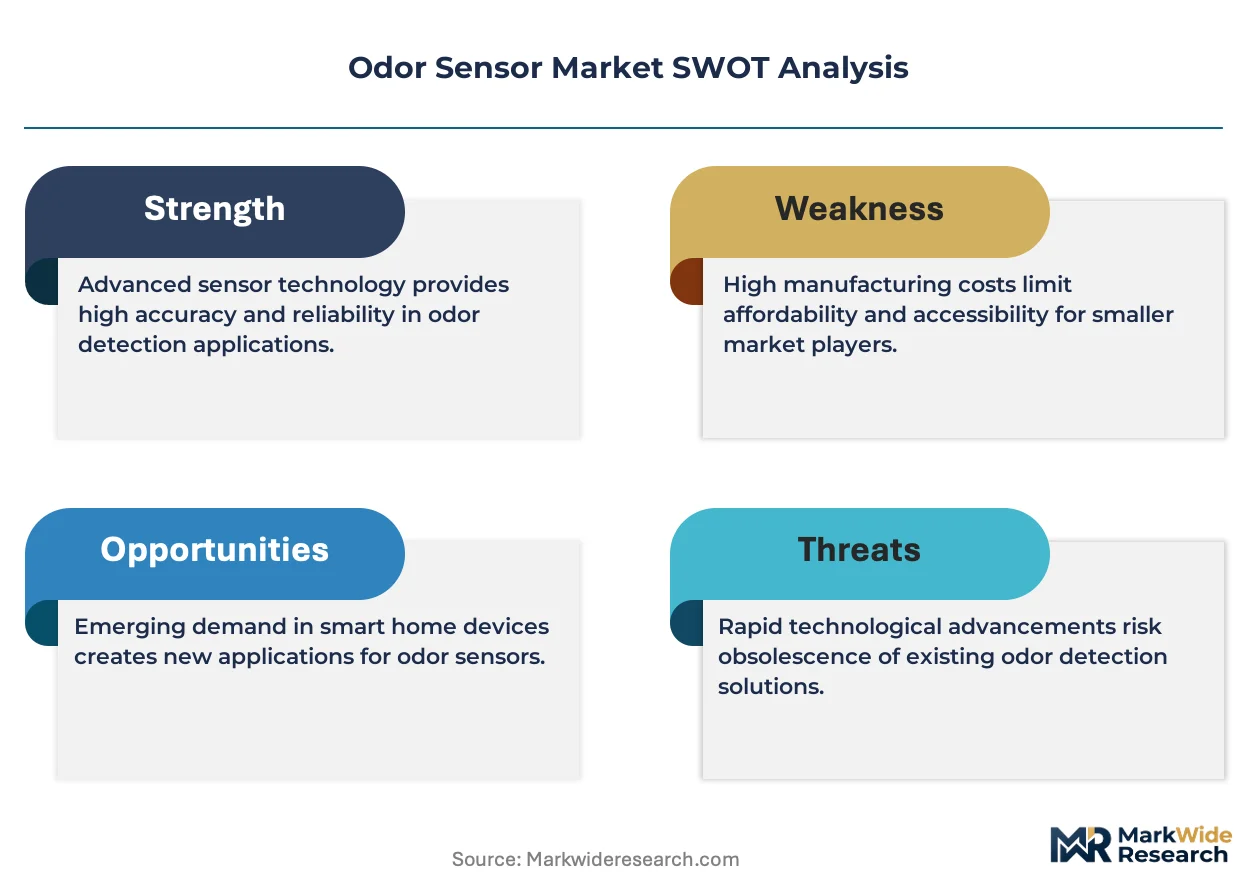
The odor sensor market functions as a cost-of-compliance arena where EU Green Deal industrial emissions mandates erect certification barriers that protect entrenched players with REACH-tested material portfolios and calibrated service networks.
For Market Incumbents: Hedge against graphene-based optical disruption by securing palladium supply agreements with South African mining operations and accelerating MEMS miniaturization roadmaps for wearable healthcare applications. Defensive consolidation through acquisition of calibration service providers in Houston's refining corridor locks in recurring revenue streams. Capacity addition in Yangtze River Delta manufacturing clusters captures China's MEE enforcement replacement cycles. For New Entrants and Emerging Players: EU Green Deal amendments in Germany open a window for optical sensor specialists targeting food freshness monitoring in European retail cold chains where humidity-resistant selectivity commands premium positioning. White-space concentration sits with direct-to-facility HVAC integration partnerships bypassing traditional instrumentation distributors. Agricultural ammonia monitoring in Midwest US livestock operations offers lowest competitive density. Go-to-market through embedded sensor partnerships with climate-control OEMs sidesteps incumbent calibration service bundling. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular sensor suppliers with external wafer sourcing and stranded REACH certification investments in the Ruhr industrial belt. Long-term viability frames around 5-10 year regulatory enforcement intensification rather than technology substitution risk. Acquisition target archetype: application-specific software-layer specialists with SCADA integration capabilities. Signal to watch: quarterly EPA calibration verification waiver rates as indicator of in-house metrology adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palladium Sourcing | Secures noble metal supply continuity against Russian mining disruption for metal-oxide production. |
| Graphene Nanomaterial Partnership | Accelerates optical sensor selectivity roadmaps for food freshness applications in European cold chains. |
| Calibration Service Acquisition | Locks recurring revenue from EPA-regulated Gulf Coast petrochemical facilities requiring quarterly verification. |
| HVAC OEM Embedded Integration | Bypasses traditional instrumentation distribution through direct climate-control system partnerships. |
| MEMS Miniaturization Scale-Up | Enables wearable form factors for occupational health programs under Japan's METI harmonized standards. |
Methodological Framework
Document review covered EPA enforcement databases, EU Green Deal implementation guidance, JIS standards documentation, and MEE discharge limit circulars, complemented by interviews with environmental compliance officers at German chemical processors, calibration technicians in Houston's refining corridor, and procurement leads at Japanese automotive Tier 1 suppliers. Secondary validation drew from SEC filings of precision sensor manufacturers, customs trade data for palladium and graphene inputs, and hospital procurement databases for healthcare exposure monitoring applications. Bottom-up unit shipment estimates triangulated against top-down regulatory mandate scaling projections.
Cross-referencing historical installation rates against panel input from plant engineers and SCADA integration specialists shaped the analytical framework across the analysis window. Segmentation dimensions modeled include sensor form factor, transduction technology, end-use application, and regional regulatory enforcement intensity. CAGRs derived from regulatory mandate phase-in schedules and replacement cycle assumptions for existing metal-oxide installed base. Industry-specific inputs incorporated REACH certification timeline data and METI smart factory initiative deployment tracking.
The model assumes a particular technology adoption path; alternative pathways for graphene-based optical sensors would alter the outlook if manufacturing cost curves steepen faster than projected. Forecasts embed assumptions regarding EU member state transposition timelines for industrial emissions mandates and Chinese provincial enforcement uniformity. Material deviation in EPA calibration waiver rates or palladium supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Automotive Steering Sensors Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Europe Temperature Sensors Market
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
Gyro Sensors Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Europe Fingerprint Sensor Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Temperature Monitoring System Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market