
 Phototransistor Market | 2026-2036
Phototransistor Market Size, Share, and Industry Trends Forecast 2026-2036
Phototransistor Market Analytics
IEC 60747-5-5 qualification for optoelectronic semiconductor safety is reorganizing supplier eligibility across the phototransistor landscape. Infineon Technologies leverages captive SiGe foundry capacity to anchor European automotive sensor supply. Hamamatsu Photonics K.K. dominates ultra-fast response segments through proprietary III-V epitaxy processes. Excelitas Technologies sustains North American defense and aerospace qualification pipelines with hermetic packaging expertise.
A phototransistor is a bipolar junction or field-effect transistor whose base current is modulated by incident photons, typically exhibiting current gains of 100–1000× relative to photodiodes and fabricated on silicon, germanium, or compound semiconductor substrates. Its primary purpose is converting optical signals to amplified electrical output in ambient light sensors, optical isolators, and fiber-optic receivers. Silicon phototransistors occupy the volume core due to CMOS compatibility and foundry scalability, while gallium arsenide variants command premium positioning in high-speed optical communication where bandwidth exceeds 1 GHz. Organic phototransistors remain nascent but attract R&D allocation for flexible electronics integration in medical wearables.
RoHS and REACH frameworks in Europe restrict cadmium and lead content in optoelectronic packages, compelling substrate and metallization redesigns. FDA device classification rules in the United States govern phototransistor incorporation into pulse oximeters and diagnostic imaging equipment, creating compliance moats around medical-grade suppliers. China's GB/T semiconductor standards and dual carbon goals are reshaping domestic sourcing mandates for industrial automation components. Stakeholders must monitor divergence between regional substance restrictions and performance benchmarks as qualification cycles lengthen.
Market Dynamics
Automotive sensor arrays are restructuring phototransistor procurement as electrified powertrains demand higher ambient light detection density and faster optical response cycles than legacy combustion architectures required.
Growth Catalysts
- Electrified powertrain expansion:Battery management systems and cabin automation in electric vehicles require phototransistor arrays for proximity sensing and display dimming, pulling volume from industrial into automotive qualification pipelines.
- REACH substance restrictions:ECHA-mandated cadmium and lead reductions in optoelectronic packages are accelerating substrate redesigns toward silicon-germanium heterostructures that incidentally improve quantum efficiency.
- Industrial automation clusters:Chinese domestic robotics deployment under GB/T semiconductor standards is absorbing silicon phototransistor volume for position sensing and safety interlocks.
Market Restraints
- III-V epitaxy supply concentration:Gallium arsenide substrate availability for high-bandwidth variants concentrates with limited merchant foundries, creating allocation risk during automotive qualification surges.
- RoHS compliance friction:Lead-free solder alternatives in hermetic packaging reduce thermal cycling reliability, extending qualification timelines for aerospace and medical-grade suppliers.
- Photodiode substitution:Avalanche photodiodes with integrated transimpedance amplifiers are displacing discrete phototransistors in fiber-optic receivers above 1 GHz bandwidth thresholds.
Strategic Opportunities
- Organic phototransistor R&D:Solution-processed organic semiconductors enable flexible substrate integration for wearable pulse oximeters, opening medical device categories inaccessible to rigid silicon.
- Dual carbon alignment:China's MEE carbon intensity mandates for industrial components are favoring domestic phototransistor sourcing with verified supply chain emissions documentation.
- Optical isolator miniaturization:Integration of phototransistor-LED pairs into single-chip packages for gate drivers in silicon carbide inverters addresses space constraints in automotive power electronics.
Industry Challenges
- IEC 60747-5-5 certification timelines:Optoelectronic semiconductor safety qualification cycles now exceed eighteen months, compressing product launch windows for automotive Tier-1 suppliers.
- Epitaxial growth technician scarcity:III-V MOCVD reactor operation expertise concentrates with aging workforces in Japan and Germany, constraining capacity expansion for ultra-fast response variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phototransistor Market |
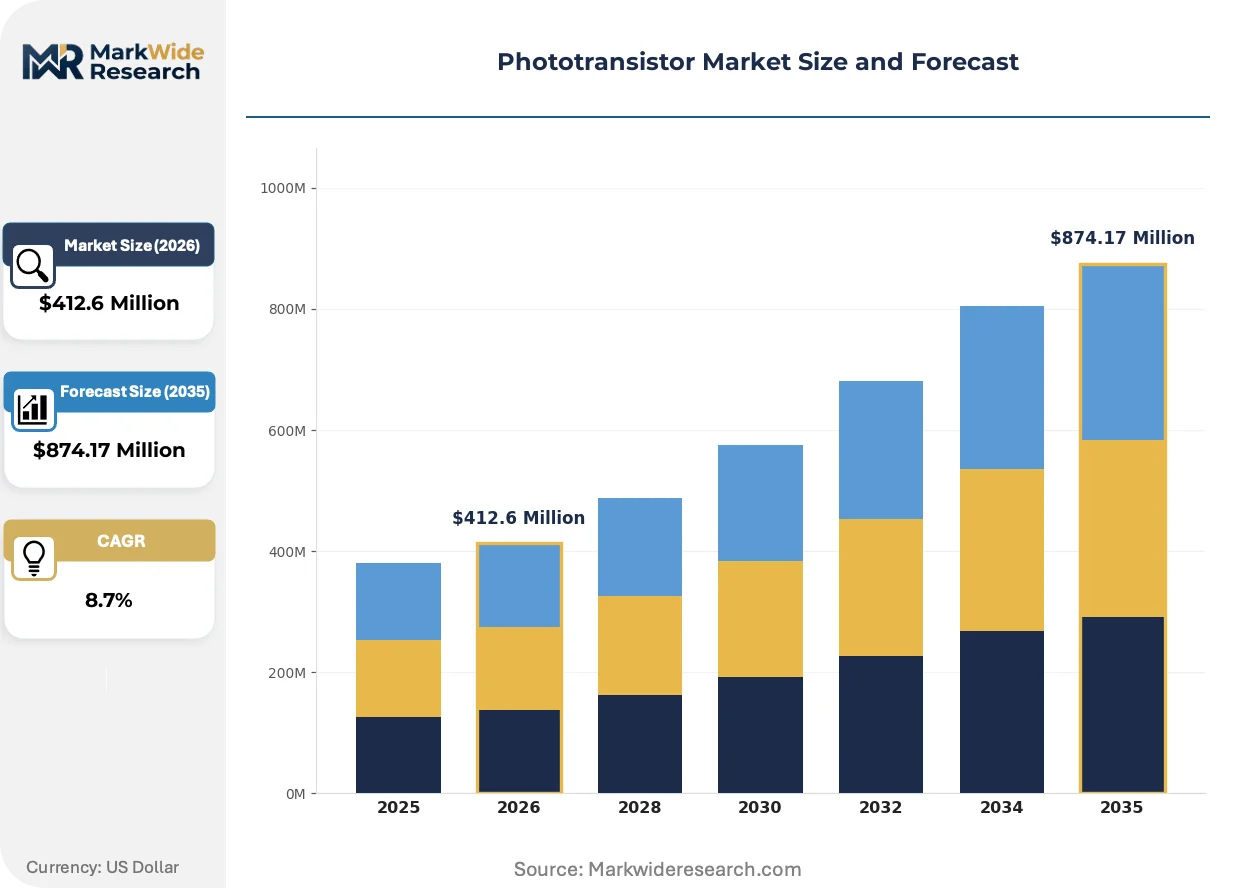
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon, Germanium, Gallium Arsenide, Organic Technology: Analog, Digital, Optoelectronics, High-Speed End User: Consumer Electronics, Automotive, Industrial Automation, Medical Devices Application: Light Detection, Optical Communication, Environmental Monitoring, Security Systems |
| Companies Covered | AMS AG, Excelitas Technologies, Honeywell International, ON Semiconductor, LITE-ON Technology Corporation, Infineon Technologies, Everlight Electronics, Kodenshi AUK, Hamamatsu Photonics K.K., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phototransistor Market Evolving Landscape
Phototransistor architecture is diverging along bandwidth-performance axes as end-use requirements stratify, with silicon CMOS-compatible processes defending volume positions while compound semiconductor variants capture premium optical communication slots.
Silicon phototransistor design is fragmenting into specialized variants optimized for specific automotive sensing modalities rather than general-purpose ambient light detection. Tier-1 suppliers are specifying customized spectral response curves for headlamp auto-leveling and rain-sensing applications. This specialization is compressing margins on standardized products while creating captive design relationships between sensor module integrators and foundry partners.
EU F-Gas Regulation phase-down schedules are indirectly reshaping phototransistor packaging by restricting fluorinated greenhouse gases used in plasma cleaning processes for hermetic sealing. European suppliers are migrating to hydrogen-based cleaning chemistries that require modified metallization adhesion protocols. Medical-grade phototransistor suppliers with existing FDA device master files are absorbing compliance costs faster than new entrants, widening qualification moats.
Automotive procurement patterns are consolidating around single-source qualification for phototransistor arrays within specific sensor modules, reversing previous dual-sourcing norms. Tier-1 suppliers are accepting sole-source risk in exchange for dedicated capacity commitments and co-development roadmaps. This concentration is most visible in German automotive sensor clusters, where Infineon and Osram have established captive design partnerships spanning multiple electrified vehicle platforms.
Phototransistor Market Segmentation
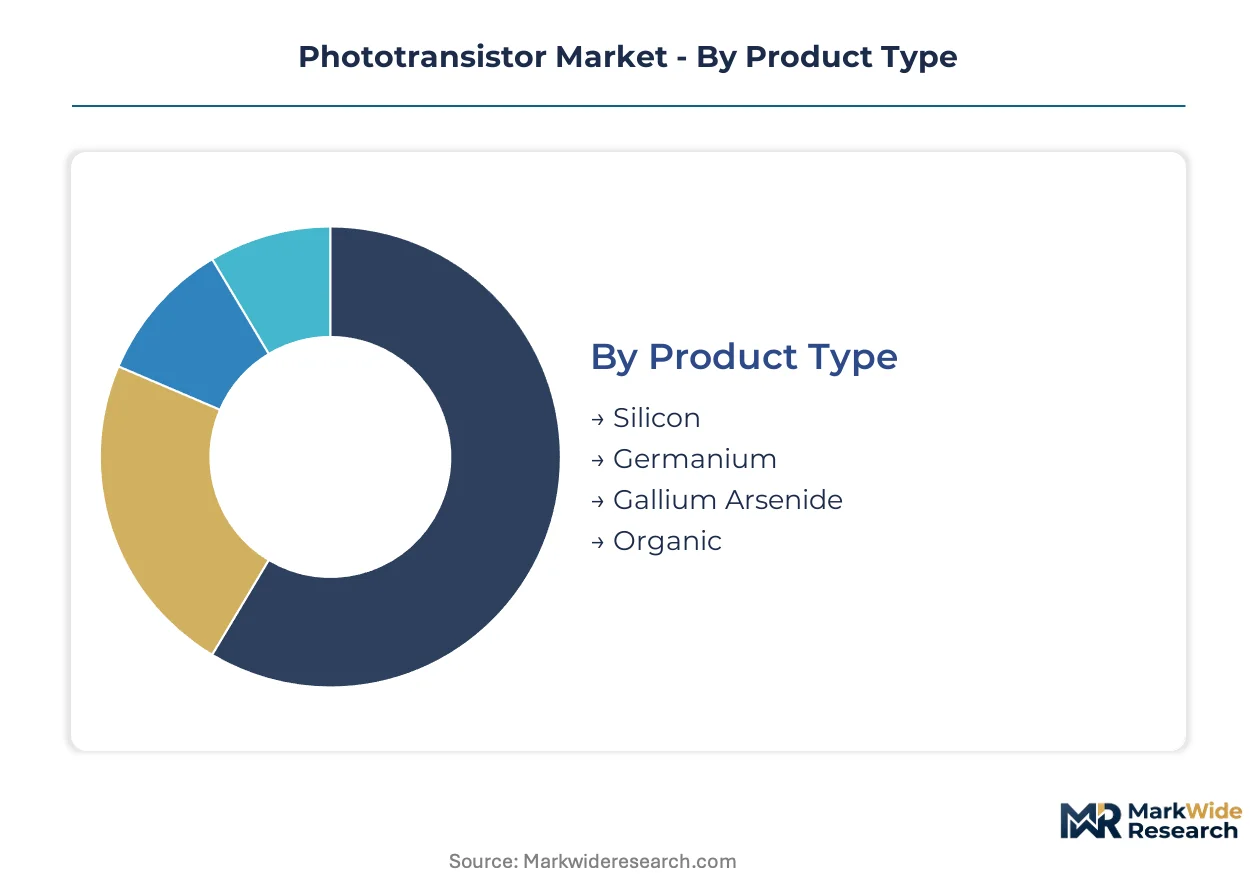
Phototransistor procurement channels diverge sharply by substrate material and response bandwidth, with silicon variants flowing through high-volume automotive Tier-1 contracts while compound semiconductors route through specialized optical communication distributors. Understanding these channel dynamics exposes where margin pools concentrate versus where volume scales.
Product Type:
Silicon phototransistors move through automotive sensor module integrators and industrial automation distributors, while III-V substrates and organic variants channel through specialized optoelectronics distributors serving defense, medical, and R&D customers.
- Silicon:Fabricated on standard CMOS-compatible wafers with current gains of 100–1000×, these devices dominate automotive ambient light sensors and industrial position sensing. German automotive clusters under KBA safety mandates pull disproportionate volume through Infineon and Osram captive supply chains.
- Gallium Arsenide:III-V epitaxy enables bandwidth exceeding 1 GHz for fiber-optic receivers and high-speed optical isolators. Limited merchant MOCVD foundry capacity in Japan and Germany creates allocation bottlenecks during telecom infrastructure buildouts.
- Germanium:Near-infrared sensitivity suits these devices for optical communication at 1300–1550 nm wavelengths. Defense and aerospace qualification pipelines absorb specialty volume through hermetic packaging specialists.
- Organic:Solution-processed semiconductor layers enable flexible substrate integration for wearable medical devices. FDA device classification rules create compliance moats around pulse oximeter and diagnostic imaging applications.
Silicon dominates installed base across automotive and industrial channels. Gallium Arsenide is where expansion concentrates for optical communication bandwidth upgrades.
Technology:
Cost tiers separate analog and digital output variants, with analog commanding premium pricing in automotive safety-critical applications while digital integration drives economies in consumer electronics.
- Analog:Continuous current output enables precise ambient light measurement for automotive headlamp auto-leveling and display dimming. Tier-1 suppliers specify customized spectral response curves, creating captive design relationships with foundry partners.
- Digital:Integrated ADC and I2C interfaces reduce microcontroller pin count in consumer electronics and IoT sensors. Chinese domestic robotics deployment under GB/T standards pulls volume through cost-optimized packaging.
- Optoelectronics:Phototransistor-LED paired architectures serve optical isolators for gate drivers in silicon carbide inverters. Space constraints in automotive power electronics favor single-chip integration.
- High-Speed:Sub-nanosecond response times target fiber-optic receivers above 1 GHz where avalanche photodiodes with transimpedance amplifiers increasingly compete.
Analog variants capture premium pricing in safety-critical automotive modules. Digital integration is climbing the fastest in cost-sensitive consumer and industrial applications.
End User:
Customer type dictates qualification intensity, with medical and automotive demanding eighteen-month IEC 60747-5-5 cycles while industrial and consumer electronics compress procurement timelines.
- Automotive:Electrified powertrains require higher ambient light detection density for battery management systems and cabin automation. German automotive sensor clusters consolidate procurement around single-source qualification with dedicated capacity commitments.
- Consumer Electronics:Smartphone ambient light sensors and wearable devices drive volume through foundry-scale silicon production. Display dimming and proximity detection absorb standardized product portfolios.
- Industrial Automation:Chinese domestic robotics deployment under MEE carbon intensity mandates favors domestic sourcing with verified supply chain emissions documentation. Position sensing and safety interlocks dominate application mix.
- Medical Devices:FDA device classification rules govern phototransistor incorporation into pulse oximeters and diagnostic imaging equipment. Existing device master files widen qualification moats against new entrants.
Automotive anchors revenue concentration through long-term platform contracts. Industrial automation is gaining share fastest under China's dual carbon alignment sourcing mandates.
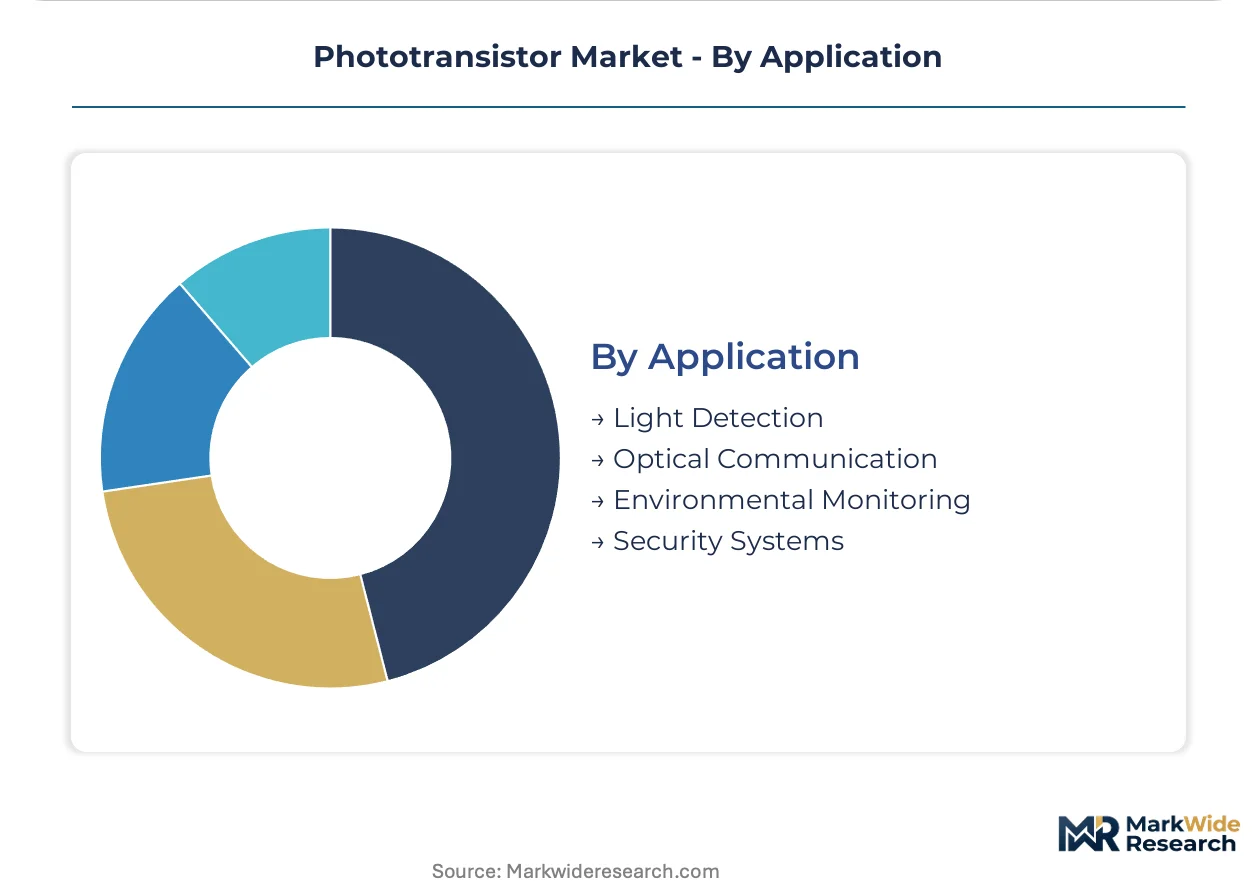
Application:
Application maturity stratifies supply concentration, with light detection saturating toward commodity pricing while optical communication and environmental monitoring sustain technology premiums.
- Light Detection:Ambient light sensing for automotive displays, smartphones, and industrial panels represents the volume core. Silicon CMOS compatibility enables foundry-scale cost reduction.
- Optical Communication:Fiber-optic receivers and optical isolators demand III-V substrates for bandwidth performance. Telecom infrastructure buildouts in Japan and South Korea concentrate demand.
- Environmental Monitoring:Spectral analysis applications in agriculture and industrial emissions sensing pull specialized spectral response variants. EU Green Deal monitoring requirements expand addressable market.
- Security Systems:Infrared motion detection and optical beam interruption for perimeter security favor cost-optimized silicon packages. Commercial building automation drives replacement cycles.
Light detection saturates toward margin compression. Optical communication sustains technology premiums where bandwidth requirements exclude silicon alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and domestic sourcing mandates are redirecting procurement flows across industrial automation supply chains. European REACH substance restrictions are tightening material compliance requirements for optoelectronic components. United States FDA device classification rules are creating compliance moats around medical-grade phototransistor suppliers.
China
Domestic robotics deployment under GB/T semiconductor standards is absorbing silicon phototransistor volume for position sensing and safety interlocks. The Ministry of Ecology and Environment enforces carbon intensity mandates favoring domestic sourcing with verified supply chain emissions documentation. Yangtze River Delta industrial clusters are consolidating phototransistor procurement around state-backed foundry partnerships.
Germany
Automotive sensor arrays for electrified powertrains are demanding higher ambient light detection density than legacy combustion architectures required. The Federal Motor Transport Authority imposes KBA safety mandates that consolidate procurement around single-source qualification with dedicated capacity commitments. Bavarian automotive clusters under Infineon and Osram captive supply chains are absorbing disproportionate volume.
United States
FDA device classification rules govern phototransistor incorporation into pulse oximeters and diagnostic imaging equipment. Defense and aerospace qualification pipelines absorb specialty volume through hermetic packaging specialists. Greater Boston medical device clusters are widening qualification moats against new entrants through existing device master files.
Japan
Ultra-fast response segments for fiber-optic receivers concentrate demand for III-V epitaxy processes. The Ministry of Economy, Trade and Industry oversees JIS standards alignment for industrial automation components. Hamamatsu-based optoelectronics specialists are anchoring premium positioning in high-bandwidth optical communication.
South Korea
Telecom infrastructure buildouts are concentrating demand for high-bandwidth phototransistor variants. The Ministry of Food and Drug Safety enforces MFDS medical device regulations affecting wearable diagnostic applications. Seoul Capital Area electronics clusters are pulling compound semiconductor volume during network upgrade cycles.
Phototransistor Market Competitive Landscape
Listed leaders compete with private specialists across substrate material and response bandwidth dimensions. The supplier base fragments between high-volume silicon CMOS fabricators and niche III-V epitaxy houses serving premium optical communication slots. Three archetypes dominate: automotive-captive foundries with dedicated capacity commitments, defense-aerospace hermetic packaging specialists, and merchant optoelectronics distributors bridging industrial automation demand. Competitive moves concentrate on strategic partnerships for co-development roadmaps and backward integration into epitaxial growth capacity.
Among European-listed semiconductor conglomerates, Infineon Technologies and AMS AG exemplify automotive-captive archetypes with foundry-scale silicon production. Hamamatsu Photonics K.K. occupies a position within the ultra-fast response tier where III-V epitaxy expertise concentrates. Excelitas Technologies represents the defense-aerospace qualification specialist archetype, anchoring North American hermetic packaging pipelines.
| Leading Market Players |
|---|
| AMS AG |
| Excelitas Technologies |
| Honeywell International |
| ON Semiconductor |
| LITE-ON Technology Corporation |
| Infineon Technologies |
| Everlight Electronics |
| Kodenshi AUK |
| Hamamatsu Photonics K.K. |
| Others |
Value Network & Pricing Analysis
IEC 60747-5-5 qualification gates both supply eligibility and price stratification simultaneously, compressing procurement timelines for automotive Tier-1 suppliers while extending certification premiums for medical-grade phototransistor vendors. This regulatory architecture funnels volume through pre-qualified foundry partnerships that command dedicated capacity pricing, while excluding merchant suppliers from safety-critical automotive sensor arrays.
Pricing Analysis
Certification level creates the primary spread between automotive IEC 60747-5-5-qualified silicon phototransistors and unqualified industrial variants. Three-tier pricing structure across premium, standard, and economy levels reflects spectral response customization, hermetic packaging grades, and volume commitment scale. Cost compression in standard silicon ambient light sensors is intensifying because Chinese domestic foundries are absorbing industrial automation volume under GB/T procurement mandates. Consumer electronics OEMs exhibit highest price sensitivity due to foundry-scale commoditization, while defense-aerospace buyers accept 3-5x premiums for hermetic germanium variants with established device master files.
Supply Chain Analysis
Inventory buffers for III-V epitaxy wafers stretch lead times beyond eighteen months during telecom infrastructure buildout cycles. Merchant MOCVD capacity concentrates in Japan and Germany for gallium arsenide substrates, while silicon CMOS fabrication draws from Taiwan, South Korea, and China. Raw material dependencies span high-purity germanium ingots, III-V precursor gases, and lead-free solder alloys for RoHS-compliant hermetic sealing. Single-source vulnerability pervades automotive sensor arrays where German Tier-1 suppliers have consolidated around Infineon-Osram captive partnerships. Distribution runs through specialized optoelectronics distributors for compound semiconductor variants, contrasting with high-volume automotive direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phototransistor demand sits in early-cycle expansion as electrified powertrain architectures multiply ambient light detection nodes per vehicle platform. Automotive procurement consolidation around single-source qualification creates asymmetric returns for incumbent foundry partners versus merchant suppliers.
For Market Incumbents: Fortify captive design relationships with German automotive sensor clusters through co-development roadmaps spanning multiple electrified vehicle platforms. Expand in-house MOCVD capacity for III-V epitaxy to offset allocation risk during telecom infrastructure surges. Prioritize IEC 60747-5-5 certification pipeline investment to widen qualification moats against merchant challengers seeking automotive Tier-1 entry. For New Entrants and Emerging Players: Differentiate on organic phototransistor flexibility for wearable pulse oximeter applications where FDA device classification rules deter silicon incumbents. Target Chinese industrial automation clusters under MEE carbon intensity mandates favoring domestic sourcing with verified supply chain emissions documentation. Pursue foundry partnership models rather than greenfield fabrication to bypass eighteen-month qualification barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across III-V epitaxy capacity as merchant MOCVD reactor availability tightens. Five-to-ten year viability favors suppliers with backward integration into substrate growth and established automotive safety certification pipelines. Monitor Hamamatsu-dominated ultra-fast response segments for consolidation signals as aging workforce constraints limit Japanese capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 60747-5-5 Certification Acceleration | Compresses eighteen-month safety qualification timelines for automotive Tier-1 sensor module integration. |
| III-V MOCVD Capacity Expansion | Addresses gallium arsenide allocation bottlenecks during Japan and South Korea telecom buildouts. |
| Organic Phototransistor R&D Partnership | Unlocks flexible substrate medical wearable categories inaccessible to rigid silicon CMOS processes. |
| Hermetic Packaging Technology Acquisition | Absorbs defense-aerospace qualification premiums through Excelitas-proven sealing protocols. |
| Chinese Domestic Foundry Joint Venture | Captures GB/T-standard industrial automation volume under MEE carbon intensity sourcing mandates. |
Research Methodology
Operator-level perspectives from automotive Tier-1 procurement directors, optoelectronics foundry engineering managers, medical device regulatory affairs leads, and industrial automation system integrators anchored the qualitative base. Primary interview insights combined with secondary validation from IEC standards documentation, ECHA REACH substance restriction filings, FDA device classification databases, and SEC semiconductor supplier disclosures. Bottom-up phototransistor shipment aggregation by substrate material and response bandwidth tier triangulated against top-down automotive sensor module production forecasts.
Sensitivity analysis tested forecast robustness across electrified vehicle penetration scenarios and III-V epitaxy capacity expansion timelines. Segmentation dimensions modeled span substrate material, output technology, end-user industry, and application bandwidth tier across the analysis window. CAGRs derived from fitted growth curves incorporating automotive platform lifecycle data, telecom infrastructure capex cycles, and Chinese industrial robotics deployment trajectories under GB/T semiconductor standards.
Decision-makers should treat outputs as directional under sustained automotive electrification and REACH substance restriction compliance assumptions; material deviation in gallium arsenide substrate availability or FDA device reclassification would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Global Light Sensors Market
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Two Wheeler Sensors Market