
 Meteorological Equipment Market | 2026-2036
Meteorological Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Meteorological Equipment Market Outlook
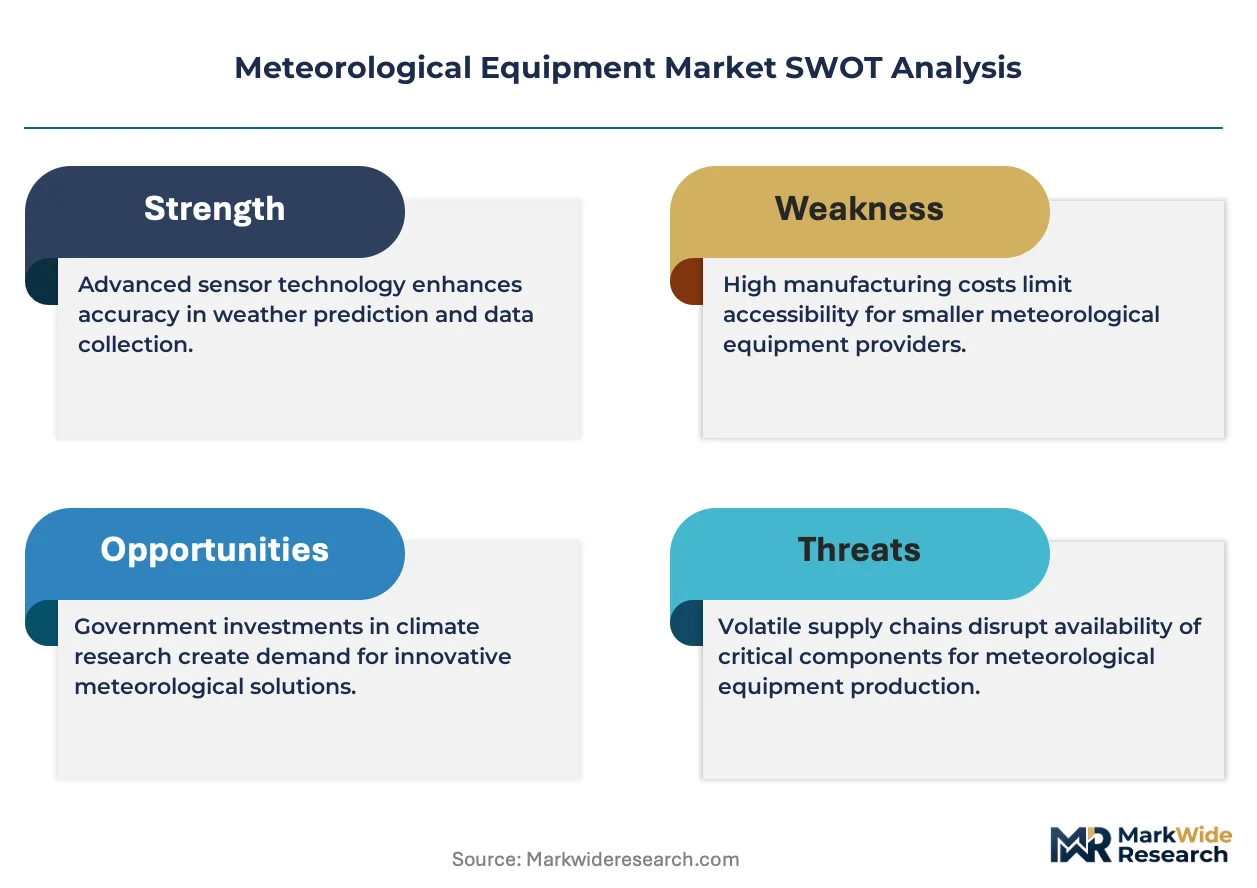
European sensor manufacturers is consolidating around precision instrumentation for climate monitoring networks. Vaisala Oyj anchors its position through deep specialization in radiosonde and sounding systems for atmospheric profiling. Lufft Mess- und Regeltechnik GmbH differentiates via compact weather stations engineered for road and rail transport applications. Campbell Scientific, Inc. extends its reach through rugged dataloggers that dominate ecological and agricultural research deployments across North America and Australia.
Meteorological equipment encompasses instruments that measure atmospheric parameters including temperature, humidity, pressure, wind velocity, and precipitation, typically operating within calibrated ranges such as barometric sensors detecting 300 to 1100 hPa with accuracy to 0.1 hPa for synoptic-grade applications. These systems feed real-time data into numerical weather prediction models, aviation safety systems, and hydrological forecasting platforms that protect infrastructure and human life. Weather stations command the largest installed base among product types, though remote sensing technology is gaining fastest as satellite-ground hybrid architectures replace legacy point-source observation. Government agencies represent the dominant end-user channel, while aviation applications generate premium pricing due to stringent ICAO certification requirements for terminal aerodrome forecasts.
The World Meteorological Organization establishes instrument standards through its Commission for Instruments and Methods of Observation, while national regulators including the FAA in the United States and EASA in Europe enforce equipment certification for aviation meteorology applications. China's GB standards and the MIIT framework govern domestic sensor procurement, creating localized compliance barriers for foreign suppliers. Stakeholders must weigh interoperability demands against regional certification requirements when configuring product portfolios for multinational meteorological service contracts.
Market Dynamics
The meteorological equipment sector is experiencing a fundamental sensor-architecture transition as government meteorological services replace legacy analog networks with digital arrays, compressing replacement cycles and reshaping vendor competitive positioning around interoperability certification.
Growth Catalysts
- ICAO Terminal Aerodrome Forecast Mandates:Aviation authorities across Asia-Pacific are expanding surface observation networks to comply with stricter flight safety protocols, driving premium-grade sensor procurement from airport authorities.
- China Upper-Air Modernization:The national weather service is undertaking large-scale replacement of radiosonde infrastructure, concentrating demand for sounding systems and telemetry hardware.
- Numerical Weather Prediction Integration:Meteorological agencies are deploying denser automatic weather station grids to feed higher-resolution models, accelerating digital sensor adoption.
Market Restraints
- Precision Sensor Supply Concentration:High-accuracy barometric and hygrometric sensors rely on specialized MEMS fabrication concentrated in German and Japanese facilities, creating single-source vulnerability.
- GB Standards Localization Barriers:China's MIIT framework and domestic certification requirements impose compliance friction that fragments procurement for multinational suppliers.
- Calibration Infrastructure Costs:Synoptic-grade accuracy demands traceable calibration chains that require capital-intensive metrology laboratories, elevating total cost of ownership.
Strategic Opportunities
- Road and Rail Transport Networks:Lufft Mess- und Regeltechnik GmbH has demonstrated viable positioning for compact weather stations in intelligent transport systems, an underpenetrated channel beyond aviation and government meteorological services.
- Satellite-Ground Hybrid Architectures:Convergence of GNSS radio occultation receivers with in-situ surface stations is creating integrated observation platforms that command higher system-level pricing.
- EU Green Deal Climate Monitoring:The European Commission's funding for long-term climate reference networks is generating dedicated procurement streams for precision instrumentation distinct from operational weather services.
Industry Challenges
- ICAO Certification Timeline Compression:Aviation-grade equipment must complete multi-year qualification cycles with national regulators, delaying revenue recognition and freezing product roadmaps.
- Legacy System Integration Complexity:Government meteorological departments operate heterogeneous equipment vintages that require custom protocol adapters, inflating deployment engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meteorological Equipment Market |
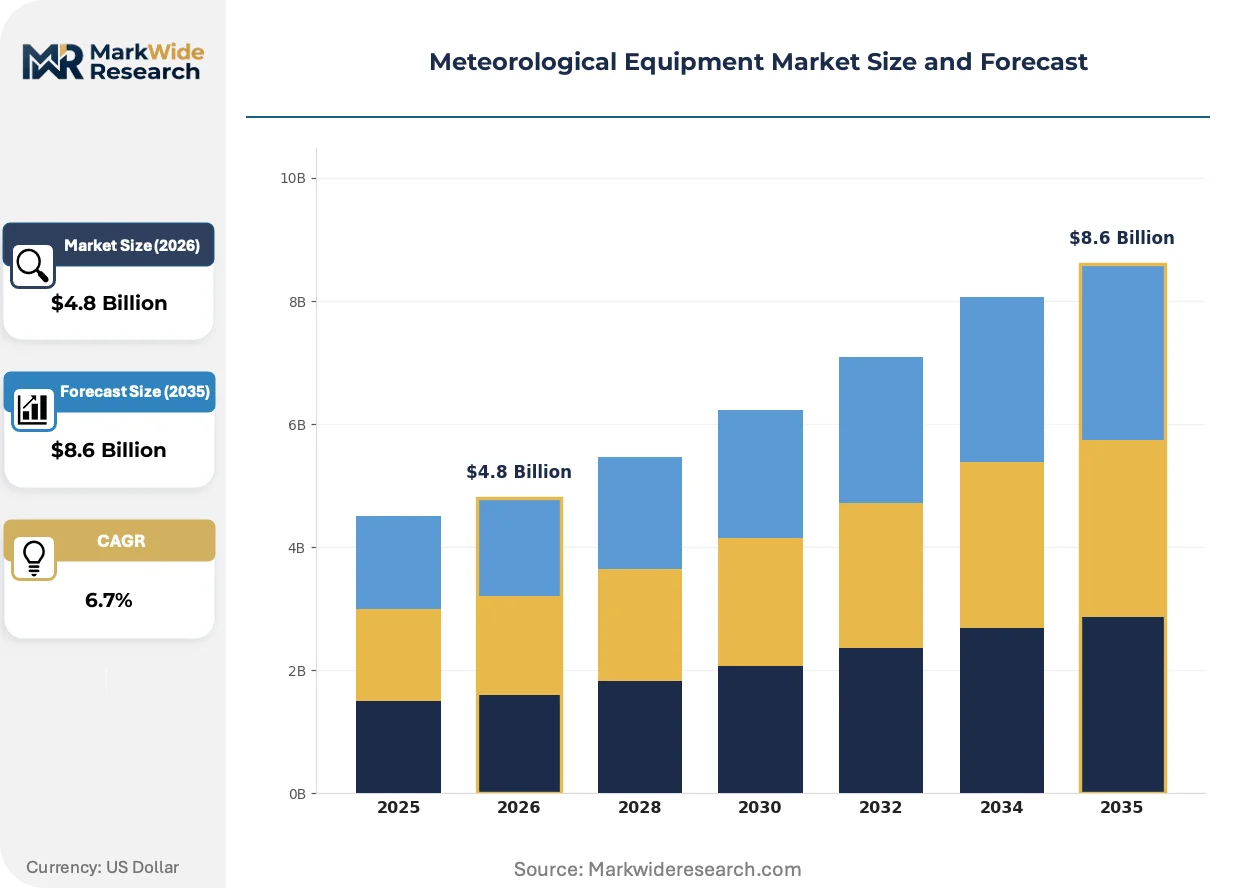
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weather Stations, Anemometers, Barometers, Hygrometers Application: Agriculture, Research, Aviation, Disaster Management End User: Government Agencies, Private Sector, Educational Institutions, Research Organizations Technology: Analog, Digital, Wireless, Remote Sensing |
| Companies Covered | Lockheed Martin Corporation, Lufft Mess- und Regeltechnik GmbH, Vaisala Oyj, Met One Instruments, Inc., Airmar Technology Corporation, Campbell Scientific, Inc., Gill Instruments Limited, Davis Instruments Corp., OTT HydroMet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meteorological Equipment Market Strategic Shifts
Digital sensor architectures are displacing electromechanical instruments across every atmospheric parameter, while regulatory fragmentation and procurement centralization are simultaneously reshaping how vendors configure product portfolios and route to market.
Solid-state MEMS barometers and capacitive humidity sensors are rewriting the economics of dense weather station deployment. National meteorological services in Australia and Canada are adopting these devices for mesoscale networks that previously required maintenance-intensive mechanical instruments. The shift is compressing unit economics and enabling tenfold increases in observation density without proportional staffing expansion.
The EU F-Gas Regulation is phasing out refrigerant-dependent chilled-mirror hygrometers used in radiosonde systems, forcing manufacturers to qualify polymer-based alternatives for stratospheric profiling missions. European sounding system suppliers are accelerating polymer sensor validation programs to maintain EASA certification continuity for aviation upper-air observations. This regulatory pressure is propagating through WMO instrument working groups as de facto global standards.
Centralized procurement frameworks at national weather services are consolidating vendor relationships and unbundling after-sales service contracts. The UK Met Office and Deutscher Wetterdienst have moved to multi-year framework agreements with designated system integrators, displacing direct equipment purchasing by individual observatory stations. This channel consolidation is most advanced in Western Europe, where budget austerity has forced procurement function centralization.
Meteorological Equipment Market Segmentation
Equipment certification requirements fragment procurement pathways across the meteorological equipment sector. Vendors must align product configurations with distinct approval regimes governing aviation safety, research precision, and operational weather services.
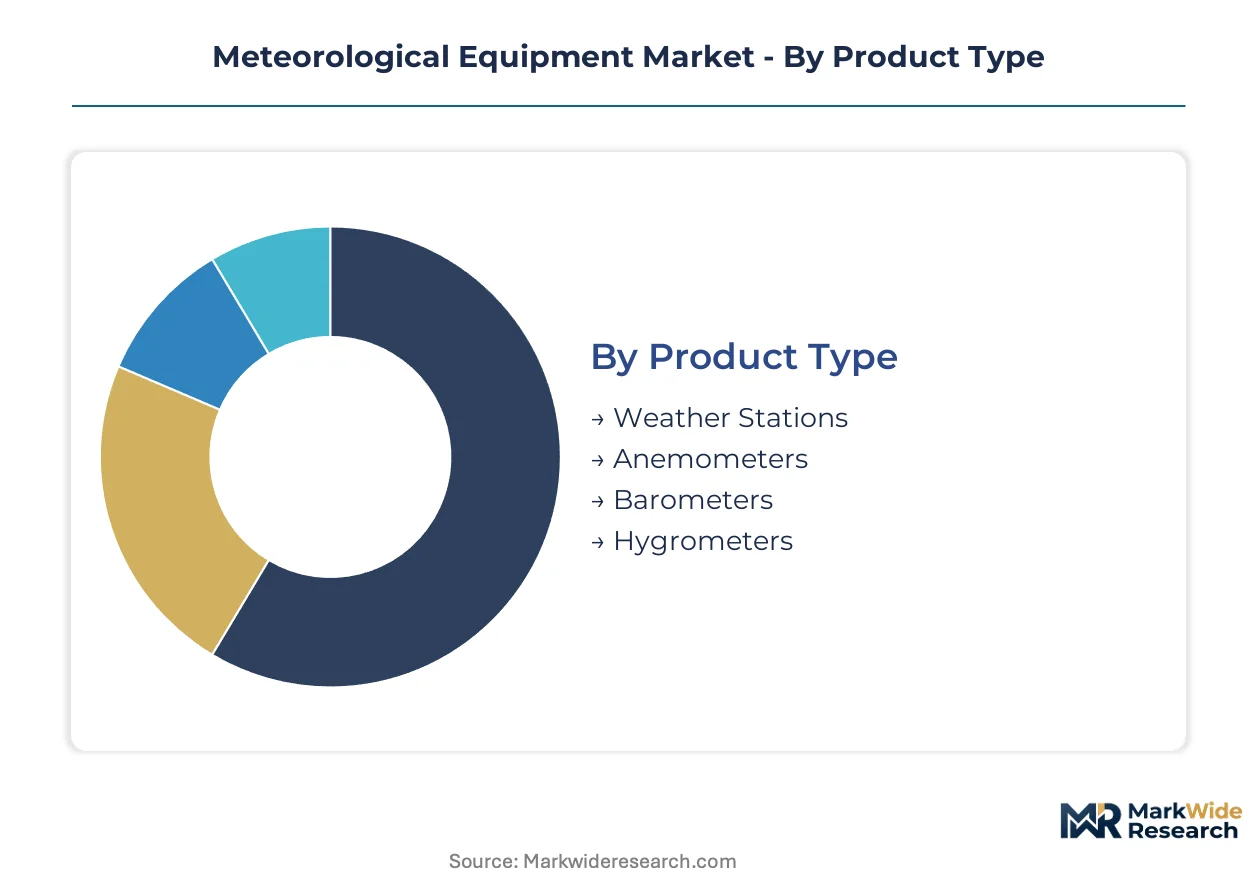
Product Type:
ICAO certification mandates separate aviation-grade instruments from general-purpose meteorological sensors, with synoptic-grade accuracy demanding traceable calibration chains that inflate cost structures for barometric and hygrometric devices.
- Weather Stations:Automatic surface observation platforms integrate multiple sensors into unified telemetry systems. Government meteorological services in Australia and Canada are deploying dense mesoscale networks using solid-state MEMS architectures that compress maintenance overhead and enable tenfold observation density expansion.
- Anemometers:Wind velocity instruments span cup-and-vane mechanical designs to ultrasonic solid-state arrays. Aviation authorities across Asia-Pacific are expanding surface observation networks to comply with stricter flight safety protocols, concentrating procurement from airport authorities for premium-grade sensors.
- Barometers:Pressure sensors detect atmospheric variations across 300 to 1100 hPa ranges with synoptic-grade accuracy to 0.1 hPa.
- Hygrometers:Humidity measurement devices face EU F-Gas Regulation pressure as refrigerant-dependent chilled-mirror designs phase out for polymer-based alternatives.
Weather Stations sits at the top of the volume ranking, with Remote Sensing climbing the fastest.
Application:
Pricing stratifies sharply across application tiers, with aviation terminal forecasts commanding premium certification overhead while agricultural deployments prioritize unit economics over precision traceability.
- Agriculture:Soil moisture integration and frost warning systems drive demand for ruggedized automatic weather stations. Campbell Scientific dataloggers dominate ecological and agricultural research deployments across North America and Australia through proven field reliability.
- Research:Climate reference networks require precision instrumentation with long-term stability verification distinct from operational weather services. The European Commission's Green Deal funding generates dedicated procurement streams for these installations.
- Aviation:Terminal aerodrome forecasts and upper-air sounding missions demand multi-year ICAO qualification cycles with national regulators including FAA and EASA.
- Disaster Management:Rapid-deployment portable stations serve flood forecasting and wildfire monitoring agencies requiring battery-independent operation.
Aviation commands the highest margin tier, with Agriculture expanding most quickly as precision farming adoption accelerates sensor deployment.
End User:
Procurement centralization at national weather services is consolidating vendor relationships and unbundling after-sales service contracts, displacing direct equipment purchasing by individual observatory stations.
- Government Agencies:National meteorological services operate the largest installed base and drive replacement cycles through network modernization programs. China's national weather service is undertaking large-scale upper-air observation infrastructure replacement, concentrating demand for radiosonde and sounding systems.
- Private Sector:Commercial weather services and renewable energy developers purchase certified instrumentation for proprietary forecasting networks.
- Educational Institutions:Universities deploy teaching-grade equipment with reduced accuracy requirements for atmospheric science curricula.
- Research Organizations:Climate monitoring programs require traceable calibration chains and long-term stability documentation.
Government Agencies anchor procurement volume, with Private Sector gaining share fastest as commercial meteorology and renewable energy forecasting expand.
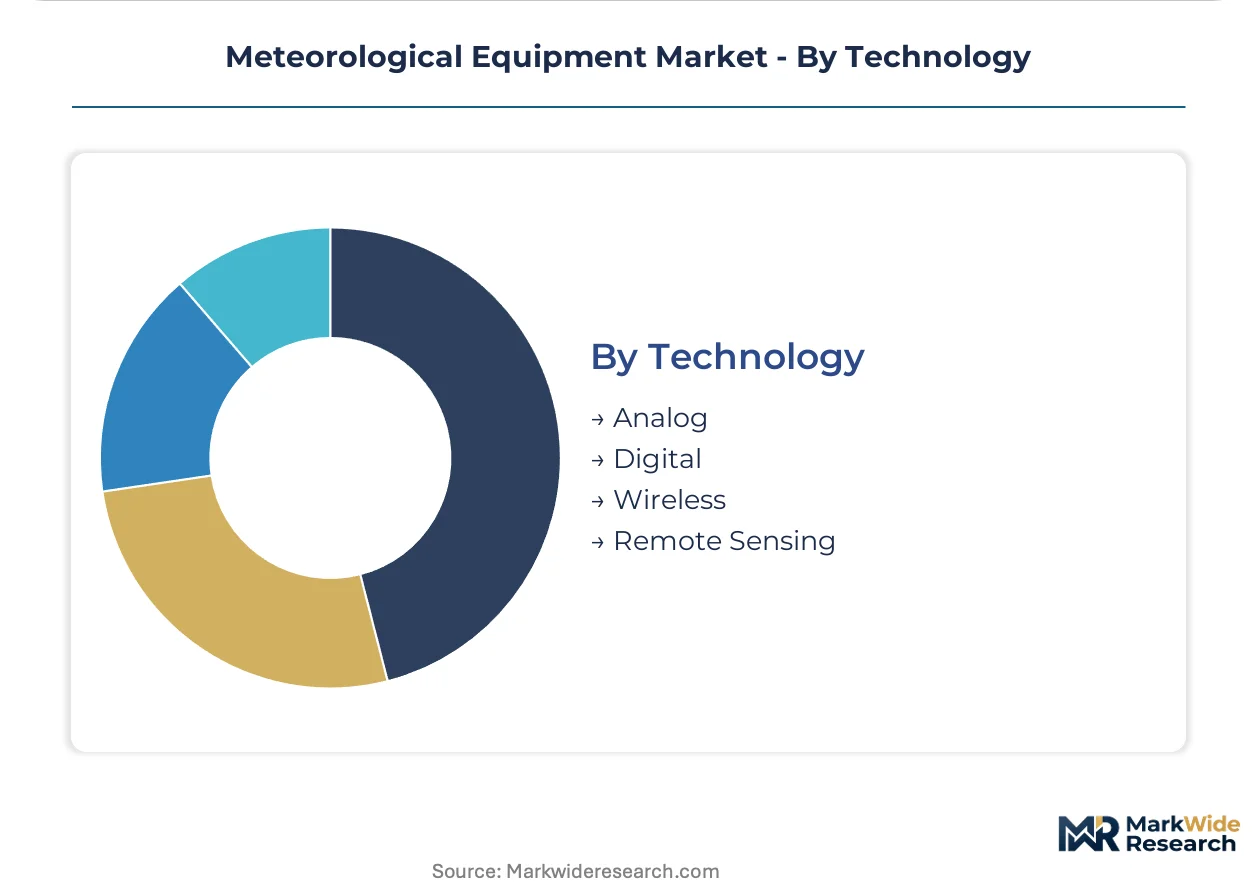
Technology:
Supply-side concentration in specialized MEMS fabrication creates single-source vulnerability for high-accuracy digital sensors, with German and Japanese facilities dominating precision barometric and hygrometric component production.
- Analog:Electromechanical instruments including mercury barometers and mechanical anemometers face accelerating replacement as maintenance costs and observer staffing requirements become unsustainable.
- Digital:Solid-state MEMS barometers and capacitive humidity sensors are rewriting deployment economics for dense observation networks.
- Wireless:Cellular and satellite telemetry modules enable autonomous station operation in remote terrain without infrastructure investment.
- Remote Sensing:Satellite-ground hybrid architectures combine GNSS radio occultation with in-situ surface stations for integrated observation platforms commanding higher system-level pricing.
Digital holds the dominant installed position, with Remote Sensing showing the steepest expansion trajectory as hybrid architectures displace point-source observation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates upper-air infrastructure investment while Germany anchors precision sensor fabrication, creating divergent procurement dynamics across major meteorological equipment markets.
China
The national weather service is replacing radiosonde infrastructure at scale, concentrating demand for sounding systems and telemetry hardware. MIIT certification requirements and GB standards govern domestic sensor procurement, creating localized compliance barriers. Manufacturing clusters in Beijing and Shanghai host system integrators serving the modernization program.
Germany
Specialized MEMS fabrication for high-accuracy barometric and hygrometric sensors concentrates in German facilities, creating single-source vulnerability for precision components. The EU F-Gas Regulation is phasing out refrigerant-dependent chilled-mirror hygrometers, forcing polymer sensor validation programs. Industrial centers in Stuttgart and Munich host precision instrumentation specialists supplying climate monitoring networks.
United States
FAA certification mandates drive premium-grade sensor procurement from airport authorities expanding surface observation networks. Numerical weather prediction integration is accelerating digital sensor adoption across government meteorological services. Research deployments in Colorado and California rely on rugged dataloggers for ecological and agricultural applications.
Japan
Specialized MEMS fabrication for precision atmospheric sensors shares supply concentration with German facilities, creating cross-border component dependencies. METI frameworks influence domestic procurement standards for meteorological instrumentation. Industrial clusters in Tokyo and Osaka support precision manufacturing for regional weather services.
Australia
Mesoscale network expansion using solid-state MEMS architectures is compressing maintenance overhead and enabling denser observation grids. The Bureau of Meteorology operates automatic weather station networks feeding higher-resolution forecast models. Research installations in Queensland and New South Wales deploy ruggedized equipment for agricultural and ecological monitoring.
Meteorological Equipment Market Competitive Environment
European producers anchor the precision instrumentation tier; North American specialists hold positions in ruggedized field equipment and aviation systems. The vendor base separates into consolidated national champions and fragmented regional equipment suppliers. Three strategic archetypes dominate: precision sensor fabricators, integrated weather station assemblers, and specialized datalogger manufacturers. Competitive moves center on certification-driven product roadmaps and framework agreement positioning with centralized procurement functions.
Among Finnish precision instrumentation specialists, Vaisala Oyj exemplifies the deep specialization archetype in atmospheric profiling systems. German engineering-focused entities including Lufft Mess- und Regeltechnik GmbH occupy positions in compact transport infrastructure applications. North American field equipment specialists such as Campbell Scientific, Inc. represent the ruggedized deployment segment serving research and agricultural end users.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Lufft Mess- und Regeltechnik GmbH |
| Vaisala Oyj |
| Met One Instruments, Inc. |
| Airmar Technology Corporation |
| Campbell Scientific, Inc. |
| Gill Instruments Limited |
| Davis Instruments Corp. |
| OTT HydroMet |
| Others |
Value Chain & Pricing Dynamics
Specialized MEMS fabrication engineers in Stuttgart and Munich command wage premiums that compress margin structures for precision barometric sensors, widening spreads between aviation-grade certified instruments and economy-tier agricultural deployments.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for compact weather station assemblies, forcing European precision specialists toward three-tier pricing structure across premium, standard, and economy levels. ICAO certification tier and volume scale drive price differentiation, with aviation terminal forecasts commanding certification overhead that agricultural buyers reject. Pricing pressure stems from centralized procurement frameworks at national weather services unbundling after-sales service contracts. Government meteorological departments show least price sensitivity due to traceable calibration requirements, while educational institutions prioritize unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore maintain hub-and-spoke patterns for telemetry hardware, feeding government meteorological services across Africa and Southeast Asia. Precision MEMS fabrication concentrates in Germany, Japan, and select US facilities. Supply chains draw from specialized semiconductor-grade silicon, rare-earth magnetic components for anemometer bearings, and polymer substrates for next-generation hygrometers. Single-source vulnerability in chilled-mirror hygrometer refrigerants creates exposure to EU F-Gas Regulation phaseouts. Distribution runs through designated system integrators under multi-year framework agreements with centralized procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as aviation authorities across Asia-Pacific mandate ICAO-compliant instrumentation that resists commoditization.
For Market Incumbents: To counter polymer sensor validation delays threatening EASA certification continuity, deepen backward integration into MEMS fabrication capacity in Germany and accelerate qualification cycles with FAA for terminal aerodrome forecast systems. Anchor positions through exclusive framework agreements with UK Met Office and Deutscher Wetterdienst procurement consolidations. For New Entrants and Emerging Players: The price-point gap between premium aviation-grade sensors and economy agricultural stations offers entry vectors into intelligent transport systems for road and rail weather monitoring. Target underpenetrated commercial meteorology services and renewable energy forecasting networks. Pursue satellite-ground hybrid architecture partnerships to bypass direct competition with established precision specialists. For Investors and Strategic Acquirers: Defense contractors expanding environmental intelligence capabilities are the most active acquirer in this space, seeking radiosonde and sounding system specialists. Long-term viability hinges on climate reference network funding durability distinct from operational weather service budgets. Monitor EU Green Deal allocation trajectories as inflection indicator for precision instrumentation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Captive supply of high-accuracy barometric sensors reduces single-source dependency on German and Japanese facilities. |
| ICAO Certification Fast-Track Investment | Compressed qualification cycles with FAA and EASA accelerate revenue recognition for aviation-grade systems. |
| Polymer Sensor Validation Program | EASA-compliant alternatives to chilled-mirror hygrometers maintain certification continuity under EU F-Gas Regulation. |
| Framework Agreement Positioning | Exclusive supplier status with UK Met Office and Deutscher Wetterdienst secures multi-year procurement streams. |
| Satellite-Ground Hybrid Platform Development | GNSS radio occultation integration commands premium system-level pricing beyond point-source observation. |
Study Parameters
Multiple input streams — meteorological equipment procurement officers at national weather services, MEMS fabrication engineers at precision sensor facilities, aviation authority certification specialists, and ecological research station managers — were reconciled against WMO instrument standards documentation, FAA certification registries, EU F-Gas Regulation implementation reports, and customs trade data for atmospheric sensor components. Bottom-up installation base estimates across government agencies, private sector, and research organizations were triangulated against top-down market value reconstructions.
Historical deployment trajectories for radiosonde infrastructure, automatic weather station networks, and remote sensing platforms were cross-referenced against panel input from national meteorological service budget directors. The analytical framework modeled product type, application tier, end-user channel, and technology architecture dimensions across the projection horizon. CAGRs were derived from replacement cycle compression rates and network densification targets. Forecast inputs incorporated ICAO mandate implementation timelines and China upper-air modernization procurement schedules.
Caveats apply where MIIT certification requirement shifts or EU F-Gas Regulation acceleration could materially shift the outlook for polymer sensor adoption and cross-border procurement access. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Gimbal Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Capacitive Pressure Sensor Market
Sensors and Controls
Safety Laser Scanner Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Global E-Nose Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Middle East and Africa Lidar Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Digital Barometer Market