
 Meteorological Devices Market | 2026-2036
Meteorological Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Meteorological Devices Market Analysis
Aviation authorities and disaster management agencies are reorganizing procurement priorities around real-time remote sensing, pulling budget share from traditional research institutions. Vaisala Oyj leverages its Finnish manufacturing base to dominate calibrated humidity and pressure instrumentation for airport operations. Campbell Scientific, Inc. anchors its position through ruggedized datalogger architectures purpose-built for remote alpine and coastal deployments. Davis Instruments Corporation competes in the consumer-prosumer boundary layer with integrated wireless console ecosystems.
Meteorological devices comprise calibrated sensors, transducers, and telemetry assemblies that measure atmospheric variables including wind velocity, barometric pressure, relative humidity, and precipitation depth, typically achieving measurement uncertainties below 0.5% full scale through thermally compensated piezoelectric or capacitive sensing elements. These instruments feed numerical weather prediction models, irrigation automation platforms, and air traffic management systems with sub-minute refresh intervals. Automated technology segments are capturing margin pools as unattended stations displace manual observation networks across agriculture and government end-user channels. Wireless telemetry architectures are growing fastest where cellular and LoWAN backhaul eliminate costly site visits in environmental monitoring applications.
The World Meteorological Organization's Integrated Global Observing System and the FAA's NextGen weather requirements shape product certification pathways and interoperability standards for vendors seeking institutional contracts. EPA ambient monitoring regulations and EU Green Deal emissions accounting rules are tightening sensor accuracy thresholds, forcing analog-to-digital upgrades across legacy installations. Stakeholders must calibrate R&D roadmaps against evolving dual-use specifications that serve both civilian meteorology and emerging climate attribution litigation demands.
Market Dynamics
Aviation authorities and disaster management agencies are reorganizing procurement priorities around real-time remote sensing, pulling budget share from traditional research institutions. The European Union's Green Deal and CSRD disclosure mandates are accelerating replacement of legacy analog systems with automated digital networks.
Growth Catalysts
- EU Green Deal emissions accounting:The EU Green Deal and CSRD disclosure mandates are forcing industrial emitters to install certified meteorological monitoring for Scope 1 and Scope 2 verification, creating pull-through demand for calibrated sensor networks.
- Precision agriculture sensor densification:Farm operators in Germany and the Netherlands are deploying mesoscale observation grids to optimize irrigation timing and chemical application rates as climate volatility intensifies growing-season uncertainty.
- FAA NextGen weather requirements:The FAA's NextGen weather requirements are mandating sub-minute refresh intervals for terminal area observations, driving airport authorities to replace legacy manual stations with automated sensor suites.
Market Restraints
- MEMS sensor price erosion:Commodity MEMS pressure and humidity chips from Asian foundries are collapsing price floors for entry-tier weather stations, compressing margins for mid-tier instrument vendors.
- Calibration labor bottleneck:Certified calibration technicians remain concentrated in Finland, Germany, and the United States, creating service backlogs that delay deployment timelines for remote installations.
- Cellular backhaul coverage gaps:Rural and alpine deployment sites frequently lack reliable cellular or LoWAN infrastructure, forcing expensive satellite telemetry upgrades that extend payback periods.
Strategic Opportunities
- Climate attribution litigation infrastructure:Law firms and insurers are commissioning forensic meteorological datasets for damage attribution cases, creating demand for court-certifiable sensor chains with documented calibration histories.
- India agricultural extension networks:The country's national meteorological service and state agricultural universities are piloting dense automatic weather station grids under the PLI scheme for precision farming.
- Edge-AI sensor fusion:Converging on-device inference with multi-parameter sensing is decomposing cloud dependency for real-time irrigation and aviation decisions at bandwidth-constrained sites.
Industry Challenges
- WMO certification backlog:The World Meteorological Organization's instrument certification queue now exceeds 18 months for new sensor submissions, delaying product launches and freezing R&D roadmaps.
- Legacy analog integration friction:Government meteorological services with decades-old manual observation networks face complex data harmonization challenges when grafting automated digital feeds onto existing archival systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meteorological Devices Market |
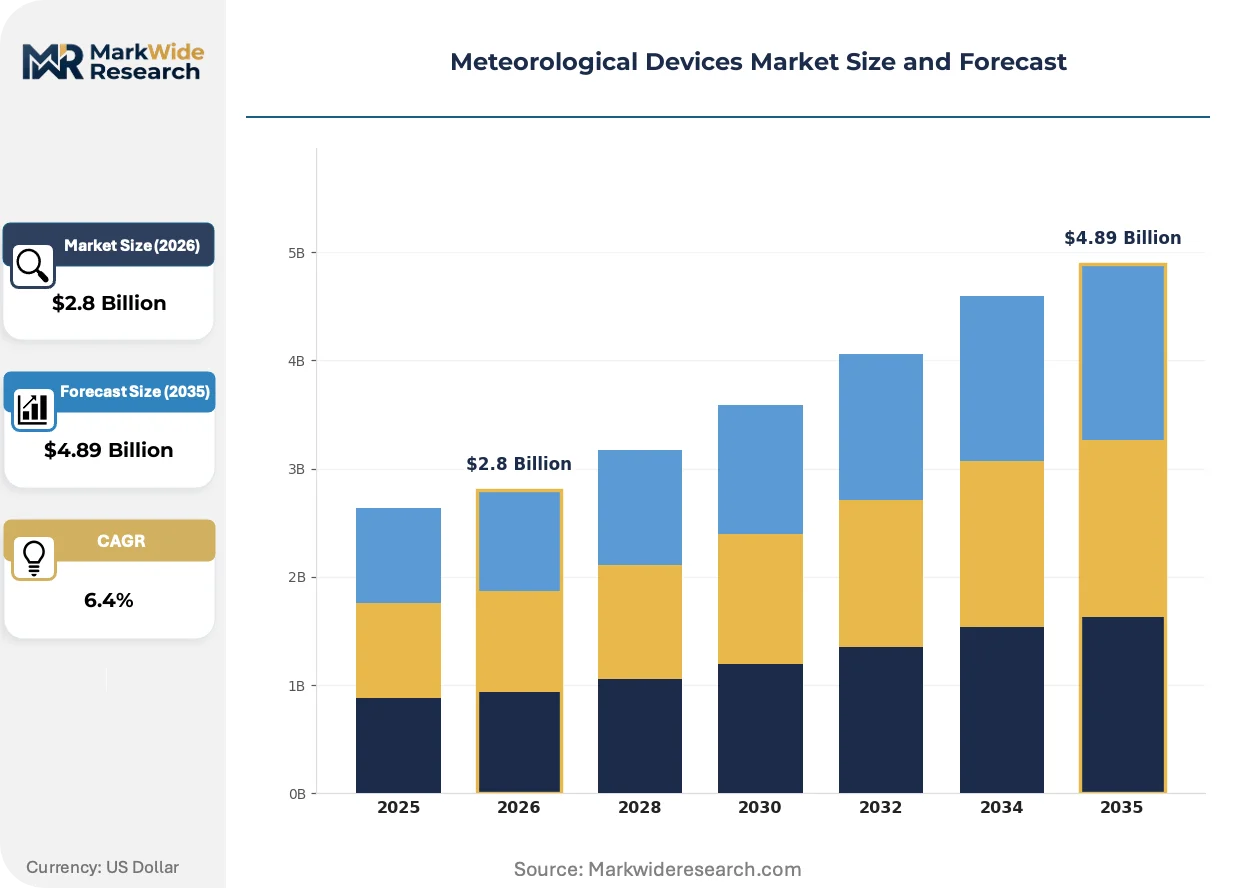
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anemometers, Barometers, Hygrometers, Rain Gauges Technology: Digital, Analog, Wireless, Automated End User: Agriculture, Aviation, Research Institutions, Government Application: Weather Forecasting, Environmental Monitoring, Climate Research, Disaster Management |
| Companies Covered | Earth Networks, Lufft USA Inc., Vaisala Oyj, Gill Instruments Limited, Davis Instruments Corporation, Campbell Scientific, Inc., Columbia Weather Systems, Inc., OTT HydroMet, Optical Scientific, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meteorological Devices Market Emerging Trajectories
Sensor architectures are fragmenting into modular, software-defined configurations that separate measurement elements from telemetry and power subsystems. This decomposition is enabling rapid field reconfiguration and extending equipment lifecycles through component-level replacement rather than full-station retirement.
Solid-state optical precipitation sensors are decomposing the dominance of mechanical tipping-bucket rain gauges in unattended station deployments. Hydrological monitoring agencies in Norway and Switzerland are piloting these units for alpine snowpack measurement. The technology is decomposing maintenance schedules by eliminating moving parts that freeze or clog in sub-zero conditions.
The EPA's revised ambient monitoring regulations are tightening sensor accuracy thresholds for PM2.5 and ozone correlation with meteorological variables. Industrial fence-line monitoring networks must now deploy certified meteorological instrumentation alongside air quality sensors. Refinery operators in Texas and California are responding by bundling meteorological and emissions hardware into single procurement packages.
Buyers are unbundling after-sales service contracts from initial hardware purchases, forcing vendors to compete on calibration subscription pricing rather than bundled maintenance. Environmental consulting firms and agricultural cooperatives are driving this shift toward transparent lifecycle cost accounting. The pattern is most visible in Germany, where the national meteorological service now mandates separate pricing for hardware, installation, and ongoing calibration services.
Meteorological Devices Market Segmentation
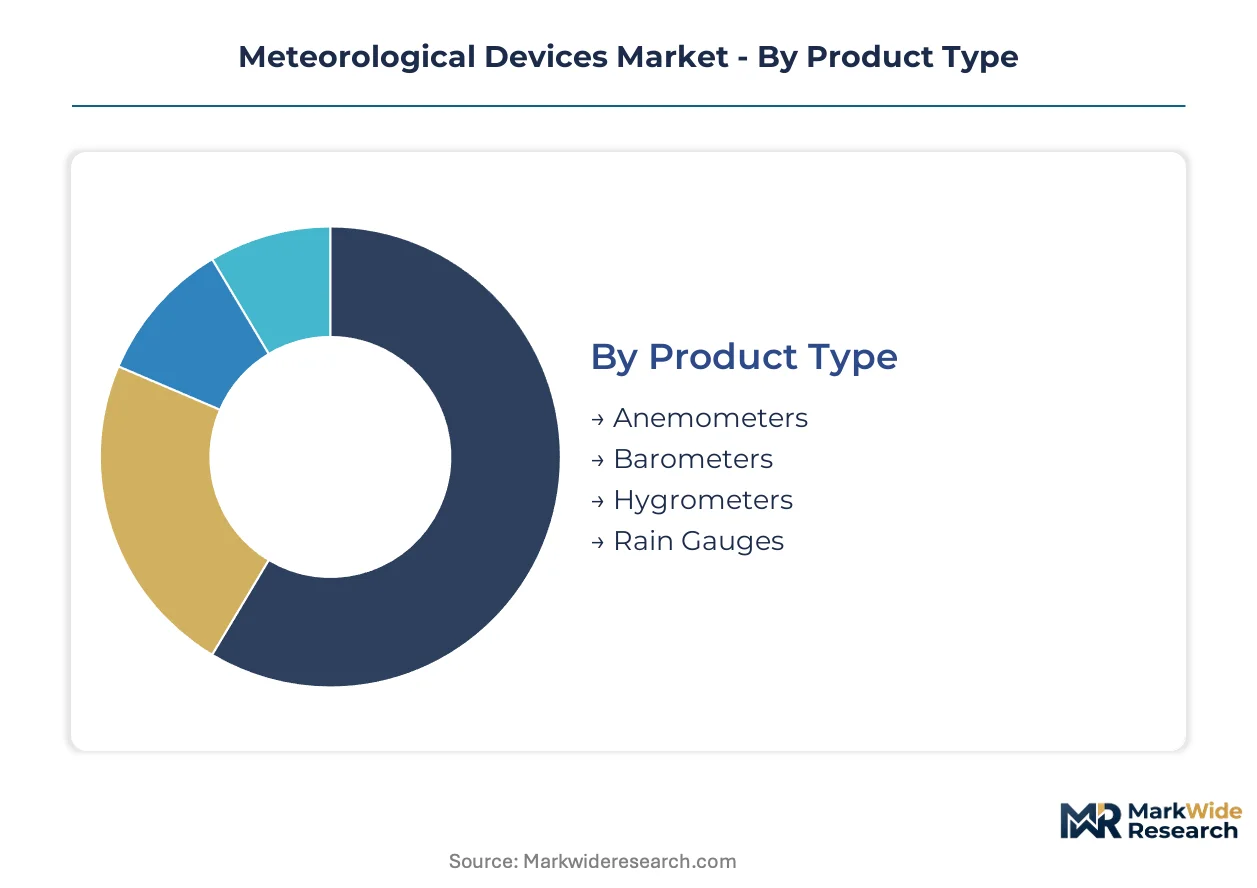
Product architectures in meteorological instrumentation fragment along precision thresholds, connectivity protocols, and regulatory certification tiers. Margin capture concentrates in calibrated digital systems serving aviation and emissions compliance end-users, while commodity analog equipment faces sustained price compression.
Product Type:
Margin pools concentrate in multi-parameter integrated stations where calibration certificates command pricing premiums over single-sensor commodity units.
- Anemometers:Ultrasonic and cup-and-vane configurations dominate wind velocity measurement, with heated ultrasonic variants capturing alpine and offshore installations where ice accumulation disables mechanical rotors. German airport authorities and North Sea wind farm operators are specifying heated ultrasonic units for sub-zero reliability.
- Barometers:Capacitive silicon and resonant quartz pressure transducers achieve measurement uncertainties below 0.1 hectopascal, feeding numerical weather prediction models and altimetry systems. Demand clusters in FAA-certified installations and EU Green Deal emissions accounting networks where pressure correlation with gas density measurements is mandatory.
- Hygrometers:Chilled-mirror dewpoint sensors and polymer capacitive elements serve humidity measurement across environmental monitoring and industrial process control.
- Rain Gauges:Tipping-bucket mechanisms face displacement by solid-state optical and piezoelectric precipitation sensors in unattended remote deployments.
Anemometers hold installed capacity across aviation and renewable energy infrastructure. Rain gauges are rotating up the share rankings as hydrological agencies accelerate alpine sensor densification.
Technology:
Procurement patterns split between legacy analog replacement cycles and greenfield automated network deployments, with wireless telemetry architectures gaining preference in bandwidth-constrained environments.
- Digital:Thermally compensated piezoelectric and capacitive sensing elements with onboard analog-to-digital conversion achieve sub-0.5% full-scale uncertainty, enabling direct integration with SCADA and IoT platforms. EPA ambient monitoring regulations and EU CSRD disclosure mandates are forcing industrial emitters toward certified digital instrumentation.
- Automated:Unattended weather stations with programmable sampling intervals and self-diagnostic routines displace manual observation networks across agricultural extension services and disaster management agencies. India's national meteorological service is piloting dense automatic weather station grids under production-linked incentive schemes.
- Wireless:Cellular and LoWAN backhaul architectures eliminate costly site visits, though rural coverage gaps force satellite telemetry upgrades in alpine and desert installations.
- Analog:Mercury barometers and mechanical hygrographs persist in legacy research installations facing complex data harmonization challenges when integrating with digital archival systems.
Digital systems anchor current revenue concentration in regulatory-driven replacement cycles. Automated technology is climbing the fastest as precision agriculture and aviation authorities reorganize procurement priorities.
End User:
Customer concentration tilts toward institutional buyers with multi-year calibration service contracts, while agricultural cooperatives drive unbundling of hardware and lifecycle service pricing.
- Aviation:Airport authorities and air navigation service providers mandate sub-minute refresh intervals for terminal area observations, driving replacement of legacy manual stations with automated sensor suites certified to WMO and FAA NextGen specifications.
- Agriculture:Farm operators in Germany and the Netherlands deploy mesoscale observation grids to optimize irrigation timing and chemical application rates, with state agricultural universities in India piloting extension network densification.
- Government:National meteorological services and environmental protection agencies maintain observation backbone infrastructure, with procurement fragmented across federal, state, and municipal budget authorities.
- Research Institutions:Universities and climate research centers face budget share erosion as aviation and disaster management agencies capture priority funding for operational sensor networks.
Aviation holds installed capacity in certified high-precision instrumentation. Agriculture is gaining share fastest as climate volatility intensifies growing-season uncertainty and irrigation automation investments.
Application:
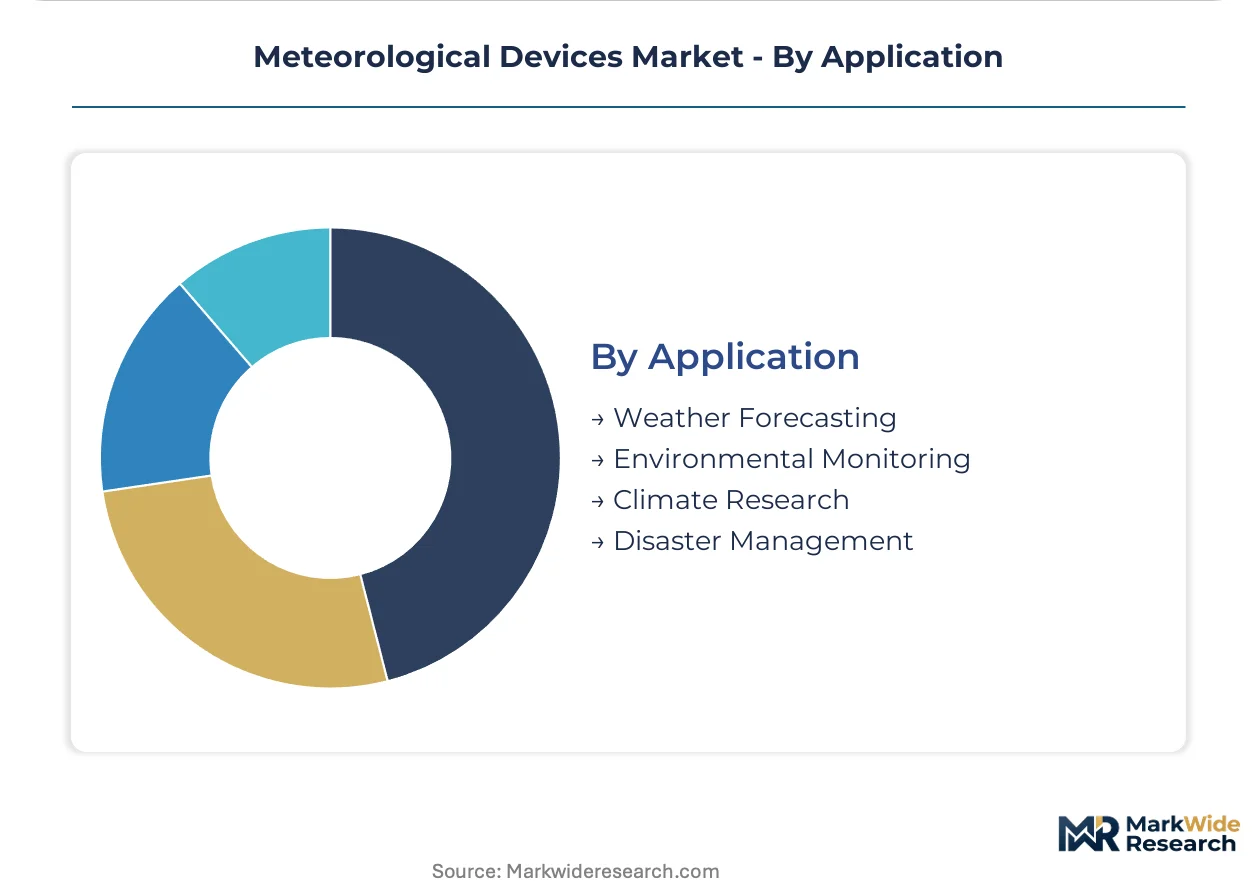
Use case differentiation centers on temporal resolution requirements, with real-time operational systems commanding premium pricing over archival research datasets.
- Weather Forecasting:Numerical weather prediction models ingest sub-minute atmospheric variable streams from dense observation networks, with WMO Integrated Global Observing System specifications shaping vendor certification pathways.
- Disaster Management:Real-time flood, wildfire, and severe weather alert systems require ruggedized telemetry architectures for remote alpine and coastal deployments where cellular infrastructure is unreliable.
- Environmental Monitoring:Industrial fence-line networks must deploy certified meteorological instrumentation alongside air quality sensors under tightened EPA correlation requirements for PM2.5 and ozone measurements.
- Climate Research:Long-term homogenized datasets support attribution studies and model validation, though funding concentration shifts toward operational real-time applications.
Weather forecasting holds installed capacity in institutional observation infrastructure. Disaster management is expanding most quickly as agencies reorganize procurement around remote sensing capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish manufacturers export calibrated humidity and pressure instrumentation to German airport authorities and Dutch agtech cooperatives. This trade corridor channels precision meteorological hardware into EU Green Deal compliance networks and FAA-certified aviation installations across Northern Europe and North America.
United States
Airport authorities in Texas and California drive automated sensor suite procurement under FAA NextGen mandates for sub-minute terminal area observations. EPA ambient monitoring regulations tighten PM2.5 correlation requirements, forcing refinery operators to bundle meteorological and emissions hardware. Dallas-Fort Worth and Houston industrial corridors concentrate fence-line monitoring network deployments.
Germany
The national meteorological service co-invests with private agtech buyers in dense mesoscale observation grids across Bavaria and Lower Saxony. EU CSRD disclosure mandates accelerate analog-to-digital replacement cycles in industrial emissions accounting. Stuttgart and Munich anchor precision agriculture sensor densification for irrigation automation platforms.
India
State agricultural universities pilot automatic weather station grids under PLI scheme incentives for precision farming extension networks. The national meteorological service expands unattended station deployments in Maharashtra and Gujarat as climate volatility intensifies monsoon uncertainty. Pune and Hyderabad concentrate domestic sensor assembly and calibration service capacity.
China
Dual carbon goals and MEE emissions accounting rules drive certified meteorological monitoring for industrial Scope 1 verification. The Yangtze River Delta and Pearl River Delta concentrate smart agriculture pilot zones deploying wireless telemetry architectures. Shanghai and Shenzhen anchor domestic MEMS sensor foundry output for entry-tier weather stations.
Japan
METI-funded disaster management agencies reorganize procurement around real-time remote sensing for alpine and coastal hazard alert systems. JIS standards certification shapes vendor pathways for institutional contracts in Hokkaido and Tohoku snowpack monitoring. Nagoya and Osaka industrial clusters supply ruggedized datalogger architectures for bandwidth-constrained sites.
Meteorological Devices Market Vendor Landscape
Player mix skews toward specialized instrumentation houses with deep calibration expertise and diversified conglomerates with environmental monitoring portfolios. Tiered competitive structure separates premium certified systems serving aviation and regulatory compliance from commodity hardware facing MEMS price erosion. Strategic archetypes include Finnish precision calibration specialists, American ruggedized telemetry architects, and German integrated station bundlers. Dominant competitive moves center on unbundled service contract pricing and modular software-defined sensor architectures that extend equipment lifecycles.
Among Finnish-based precision houses, Vaisala Oyj exemplifies the calibrated instrumentation archetype for airport and emissions compliance end-users. American ruggedized telemetry specialists include Campbell Scientific, Inc. and Davis Instruments Corporation, which occupy positions spanning research-grade dataloggers and consumer-prosumer wireless console ecosystems. These three anchors illustrate the geographic and technical stratification defining procurement decisions across institutional and agricultural channels.
| Leading Market Players |
|---|
| Earth Networks |
| Lufft USA Inc. |
| Vaisala Oyj |
| Gill Instruments Limited |
| Davis Instruments Corporation |
| Campbell Scientific, Inc. |
| Columbia Weather Systems, Inc. |
| OTT HydroMet |
| Optical Scientific, Inc. |
| Others |
Supply Flow & Price Mechanics
WMO certification requirements gate both supplier qualification and price differentiation simultaneously, forcing vendors to absorb 18-month approval delays while buyers pay premiums for pre-certified instrumentation. This regulatory chokepoint stratifies the vendor base into calibration-capable incumbents and commodity assemblers locked out of institutional procurement channels.
Pricing Analysis
Current-generation digital sensor suites command substantial premiums over prior-generation analog replacements and nascent edge-AI configurations still awaiting certification. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aviation systems from agricultural automation platforms and consumer-grade weather stations. Price differentiation rests on calibration certificate depth and wireless telemetry integration density. Cost compression in entry-tier MEMS hardware is intensifying because Asian foundry output floods prosumer channels. Agricultural cooperatives exhibit highest price sensitivity, while aviation authorities prioritize refresh-interval performance over unit economics.
Supply Chain Analysis
Finnish calibration expertise and German precision manufacturing anchor the upstream tier, with Chinese MEMS foundries feeding component volumes to downstream assemblers. Piezoelectric sensing elements, resonant quartz pressure transducers, and polymer capacitive humidity substrates constitute critical input dependencies. Single-source vulnerability concentrates in certified calibration technician pools concentrated in Helsinki, Stuttgart, and Denver. Distribution runs through direct institutional contracting for aviation and government verticals, with agricultural channels fragmenting across regional equipment distributors and cooperative procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The meteorological devices market is cycling through a regulatory-driven replacement wave as EU CSRD mandates and FAA NextGen deadlines synchronize procurement calendars across institutional buyers.
For Market Incumbents: Secure calibration service contract renewals through multi-year subscription pricing before agricultural cooperatives complete their unbundling transition. Deepen backward integration into resonant quartz transducer production to offset MEMS commodity pressure. Anchor position in Indian PLI scheme pilot networks before domestic assembly capacity matures. For New Entrants and Emerging Players: Lead with solid-state optical precipitation sensors targeting alpine hydrological agencies in Norway and Switzerland where mechanical gauge maintenance costs create displacement urgency. Exploit WMO certification backlogs by acquiring distressed calibration houses with queued submissions. Penetrate climate attribution litigation infrastructure through court-certifiable sensor chain documentation services. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across edge-AI sensor fusion sub-segments as inference chip costs decline and on-device processing reduces cloud dependency. Five-to-ten-year viability favors vendors with software-defined modular architectures enabling component-level lifecycle extension. Target acquisition archetype: mid-tier automated station assemblers with installed base conversion potential. Monitor cellular backhaul coverage expansion in rural India and alpine Europe as inflection indicator for wireless telemetry growth acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Unbundling | Transparent lifecycle cost accounting reshapes German DWD procurement specifications and agricultural cooperative RFP structures. |
| Modular Software-Defined Architectures | Component-level replacement extends equipment lifecycles and defends margin pools against full-station retirement cycles. |
| Edge-AI Sensor Fusion Development | On-device inference reduces cloud dependency for bandwidth-constrained aviation and irrigation automation decisions. |
| India PLI Scheme Localization | Domestic assembly capacity in Pune and Hyderabad captures state agricultural university extension network densification demand. |
| Climate Attribution Litigation Infrastructure | Court-certifiable sensor chains with documented calibration histories serve law firm and insurer forensic meteorological dataset commissions. |
Methodological Framework
A standing panel of national meteorological service procurement officers, airport authority engineering directors, agricultural cooperative equipment managers, and environmental consulting firm instrumentation specialists provided ongoing calibration against secondary validation sources. Primary interview intelligence triangulated with WMO instrument certification databases, EPA ambient monitoring regulatory filings, EU CSRD disclosure registries, and FAA NextGen implementation documentation. Bottom-up sensor deployment counts across aviation, agriculture, and government verticals reconciled against top-down market value estimates through iterative convergence testing.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for precision instrumentation, national weather service capital expenditure disclosures, and production-linked incentive scheme allocation announcements. The analytical framework modeled demand across product type, technology generation, end-user vertical, and application use case throughout the forecast period. CAGRs derived from segment-level deployment trajectories, replacement cycle compression, and regulatory mandate implementation schedules. Forecast inputs incorporated cellular backhaul coverage expansion maps and WMO certification queue duration trends.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement and FAA NextGen terminal area refresh deadlines would require recalibration. Forecasts reflect documented assumptions regarding MEMS price erosion velocity and calibration technician training pipeline expansion. Practitioners should keep alternative scenarios live as CSRD disclosure granularity requirements and climate attribution litigation precedent evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Laser Displacement Sensor Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
Smart Flow Meter Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
RET Controller Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
North America Occupancy Sensors Market