
 India Industrial Sensors and Transmitters Market | 2026-2036
India Industrial Sensors and Transmitters Market Size, Share, and Industry Trends Forecast 2026-2036
India Industrial Sensors and Transmitters Market Foresight
Buyer concentration across India's process industries is rebalancing as mid-sized chemical and pharmaceutical manufacturers automate quality assurance workflows. ABB India Limited leverages its installed base in power and water utilities to sustain recurring transmitter replacement cycles. Honeywell Automation India Limited anchors its position through backward integration into control system software. Siemens Limited competes by extending its digital twin offerings into sensor-level data architecture.
Industrial sensors and transmitters encompass electromechanical devices that convert physical variables—pressure, temperature, flow, or proximity—into standardized output signals, typically 4–20 mA analog or digital protocols, for real-time process monitoring and closed-loop control. These instruments enable automated safety interlocks, energy optimization, and regulatory compliance across continuous and batch manufacturing operations. Pressure sensors occupy the largest share of the sensor type dimension, reflecting entrenched demand from oil refineries and compressed gas distribution networks. Wireless sensors represent the fastest-expanding technology category, as battery-powered ISA100 and WirelessHART devices reduce cabling costs in remote tank farms and solar installations. Predictive maintenance applications command premium pricing due to integration with vibration analytics and edge computing platforms.
BIS certification requirements and the CEA's technical standards for grid-connected equipment shape product qualification timelines for domestic and import suppliers. India's PLI scheme for specialty steel and automotive components indirectly stimulates transmitter demand by mandating traceable process parameters. Stakeholders must monitor how BIS adoption of IEC 61508 functional safety standards affects supplier certification costs and market access thresholds.
Market Dynamics
India's PLI scheme for advanced manufacturing is compressing qualification timelines for domestic sensor suppliers while forcing import-dependent OEMs to localize transmitter sourcing. This policy pressure is redrawing procurement hierarchies across Gujarat's petrochemical corridors and Maharashtra's automotive clusters.
Growth Catalysts
- WirelessHART deployment:Battery-powered ISA100 devices are cutting cabling costs by half in remote solar installations and tank farms across Rajasthan and Gujarat.
- CEA grid standards:Mandatory technical specifications for grid-connected equipment are creating replacement demand for legacy transmitters in power utilities.
- Pharmaceutical automation:CDSCO's tightened quality traceability mandates are driving bulk orders for pressure and temperature sensors from Mumbai-Pune drug manufacturers.
Market Restraints
- Semiconductor input volatility:MEMS chip shortages from East Asian foundries are extending lead times for pressure sensor modules by 8-14 weeks.
- BIS certification friction:IEC 61508 functional safety adoption is raising compliance costs for small domestic transmitter assemblers in Tamil Nadu and Karnataka.
- Wireless protocol fragmentation:Competing ISA100 and WirelessHART standards are forcing buyers into redundant hardware investments.
Strategic Opportunities
- Andhra Pradesh pharma corridor:Visakhapatnam's emerging bulk drug parks lack established sensor service networks, creating first-mover whitespace for transmitter vendors.
- Edge-AI convergence:Vibration analytics platforms are pulling predictive maintenance sensors into integrated hardware-software bundles with premium pricing power.
- DGFT localization incentives:Import substitution mandates under the PLI scheme are opening public tender access for domestic sensor manufacturers.
Industry Challenges
- Functional safety engineering scarcity:SIL-rated transmitter design expertise concentrates in Bangalore and Pune, constraining expansion timelines for tier-2 suppliers.
- Legacy 4-20 mA integration:Digital protocol migration is forcing pharmaceutical and refinery operators into costly control system retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Industrial Sensors and Transmitters Market |
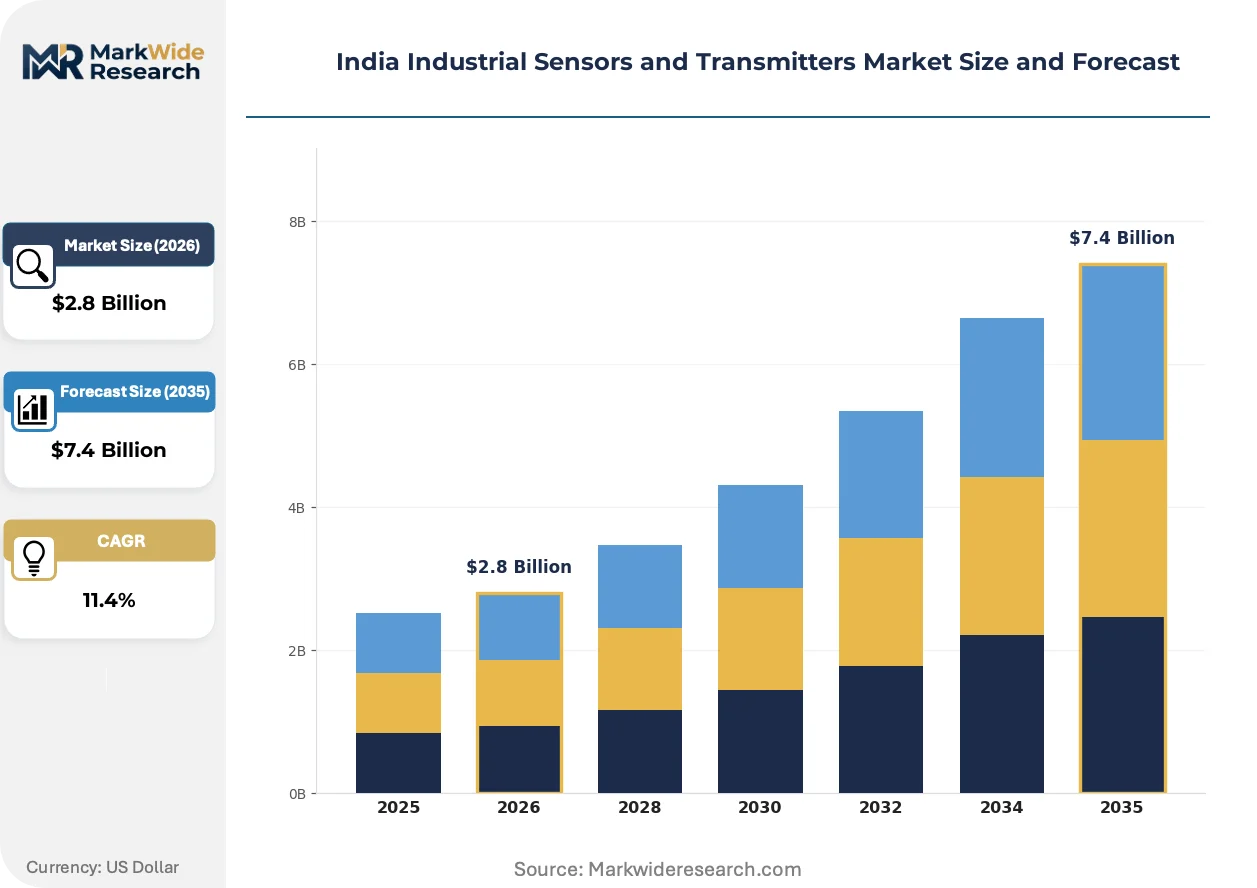
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Pressure Sensors, Temperature Sensors, Proximity Sensors, Flow Sensors Technology: Analog Sensors, Digital Sensors, Wireless Sensors, Capacitive Sensors End User: Manufacturing, Oil & Gas, Automotive, Renewable Energy Application: Process Control, Environmental Monitoring, Predictive Maintenance, Quality Assurance |
| Companies Covered | ABB India Limited, Honeywell Automation India Limited, Siemens Limited, Yokogawa India Ltd., Emerson Process Management (India) Pvt. Ltd., Endress+Hauser Pvt. Ltd., Schneider Electric India Pvt. Ltd., WIKA Instruments India Pvt. Ltd., Turck India Automation Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Industrial Sensors and Transmitters Market Shifts & Advancements
Edge computing architectures are pulling sensor data processing away from centralized DCS platforms. This shift is compressing response times for safety interlocks while demanding new hardware-software bundling strategies from transmitter suppliers.
Silicon-carbide MEMS pressure sensors are expanding into high-temperature refinery applications previously served by piezoelectric alternatives. Reliance Industries and Indian Oil are piloting these devices in catalytic cracking units. The technology is expanding into markets where thermal drift has historically forced redundant sensor installations.
BIS adoption of IEC 61508 is mandating SIL certification for safety-critical transmitters in petrochemical and power applications. The standard is disqualifying uncertified imports from project tenders while raising R&D amortization burdens for domestic manufacturers. Gujarat's refinery operators are accelerating replacement cycles to meet the compliance deadline.
Asset-as-a-service contracting is displacing capital purchase models among mid-sized chemical manufacturers. Endress+Hauser and Yokogawa India are unbundling hardware from calibration and cloud analytics subscriptions. This shift is most visible in Maharashtra's specialty chemical belt, where working capital constraints favor operational expenditure structures.
India Industrial Sensors and Transmitters Market Segmentation
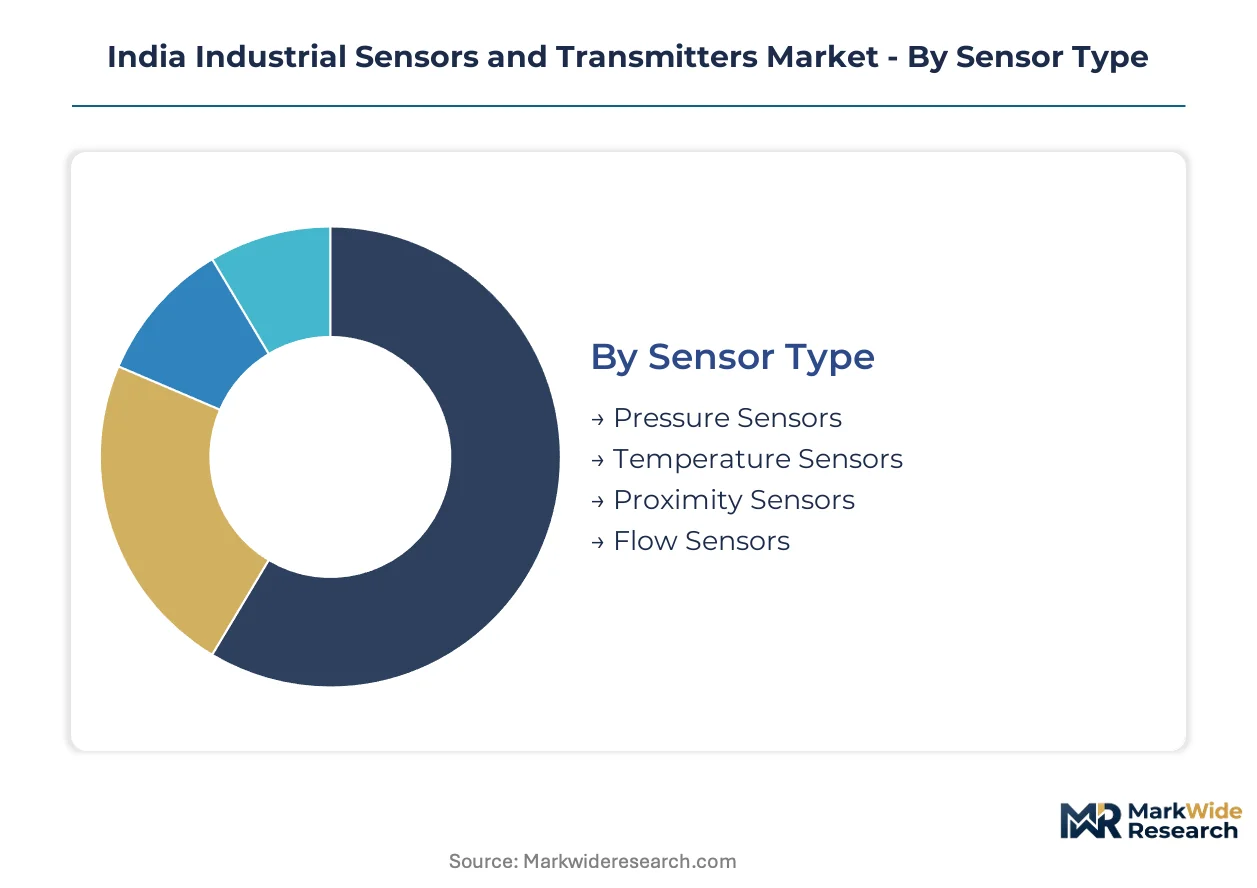
Procurement patterns across India's industrial sensor market diverge sharply by deployment context. Buyers in Gujarat's petrochemical corridors prioritize SIL-rated pressure transmitters, while Maharashtra's pharmaceutical clusters favor wireless temperature sensors for cleanroom validation.
Sensor Type:
Cost tier separates buyers most clearly in this dimension, with refinery operators paying premium prices for precision while mid-tier manufacturers optimize for replacement cycle economics.
- Pressure Sensors:Piezoresistive and capacitive transducers dominate process instrumentation, converting mechanical strain into 4–20 mA signals. Reliance Industries and Indian Oil specify these for catalytic cracking units across Gujarat's Jamnagar and Vadodara complexes, where CEA grid standards mandate redundant safety loops.
- Temperature Sensors:RTD and thermocouple assemblies provide millikelvin stability for pharmaceutical sterilization cycles. Mumbai-Pune drug manufacturers bulk-order these under CDSCO's tightened batch traceability mandates, driving demand for calibrated transmitter-sensor pairs.
- Proximity Sensors:Inductive and capacitive variants detect metallic object presence without contact. Automotive press shops in Chennai and Pune deploy these for tool protection and part positioning.
- Flow Sensors:Coriolis and electromagnetic meters measure mass and volumetric rates in custody transfer applications. City gas distribution networks in Delhi and Mumbai specify these for compressed natural gas metering.
Pressure sensors lead volumes today; wireless-enabled temperature variants are gaining share fastest.
Technology:
Application environment dictates technology selection, with hazardous area classifications and cable infrastructure availability driving the analog-to-wireless migration timeline.
- Analog Sensors:4–20 mA current loop devices remain the installed base standard across legacy DCS architectures. Refinery operators in Gujarat defer digital migration due to control system retrofit costs.
- Digital Sensors:HART and Foundation Fieldbus protocols enable device-level diagnostics and multivariable transmission. Greenfield pharmaceutical plants in Hyderabad specify these for electronic batch record integration.
- Wireless Sensors:ISA100 and WirelessHART devices eliminate cabling in remote tank farms. Rajasthan solar installations and Gujarat LNG terminals deploy battery-powered pressure and temperature transmitters to cut installation costs by half.
- Capacitive Sensors:Non-contact displacement measurement suits semiconductor and precision assembly lines. Bengaluru electronics manufacturing clusters use these for wafer handling equipment.
Analog sensors dominate installed value; wireless variants are expanding most quickly into greenfield projects.
End User:
Customer type shapes procurement sophistication, with multinational oil majors demanding global spare part interoperability while domestic manufacturers prioritize local service response.
- Manufacturing:Discrete automation lines in automotive and electronics assembly require proximity and vision sensors for quality gates. Tamil Nadu's Sriperumbudur industrial belt sources these for just-in-time production cells.
- Oil & Gas:Upstream offshore platforms and downstream refineries specify explosion-proof pressure and flow transmitters. Reliance's Jamnagar complex maintains India's largest concentration of SIL-rated safety instrumented systems.
- Automotive:Press shops, paint lines, and final assembly stations deploy sensors for robotic guidance and torque monitoring. Maharashtra's Chakan-Talegaon corridor drives demand for automotive-grade inductive sensors.
- Renewable Energy:Solar farms and wind turbines require ambient temperature and vibration sensors for predictive maintenance. Rajasthan's Bhadla solar park and Tamil Nadu wind clusters represent emerging demand centers.
Oil and gas anchors revenue today; renewable energy installations are climbing the fastest.
Application:
Margin structure varies by application, with predictive maintenance commanding software-integrated premiums while environmental monitoring competes on sensor hardware cost.
- Process Control:Closed-loop regulation of pressure, temperature, and flow parameters in continuous manufacturing. Gujarat's petrochemical clusters specify redundant transmitter architectures for distillation column control.
- Environmental Monitoring:Emission stack analyzers and effluent quality sensors for regulatory compliance. Maharashtra's MIDC industrial areas deploy these for MPCB consent condition verification.
- Predictive Maintenance:Vibration and temperature trending for rotating equipment failure anticipation. Edge-AI platforms in Karnataka's industrial corridors bundle these with cloud analytics subscriptions.
- Quality Assurance:In-process dimensional and contamination verification for pharmaceutical and food processing. CDSCO's data integrity guidelines drive validated sensor installations across Goa and Himachal Pradesh tablet manufacturing.
Process control generates the largest installed base; predictive maintenance shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's industrial sensor deployment outpaces neighboring manufacturing hubs, while Bangladesh and Vietnam trail in process automation density despite comparable labor costs. Sub-regional specialization concentrates demand in five distinct industrial corridors.
Maharashtra
Automotive press shops and pharmaceutical sterilization facilities drive bulk orders for proximity and temperature transmitters. CDSCO's batch traceability mandates compel Mumbai-Pune drug manufacturers to validate sensor calibration records. The Chakan-Talegaon corridor anchors India's largest concentration of automotive-grade inductive sensor installations.
Gujarat
Petrochemical complexes and LNG terminals specify explosion-proof pressure transmitters for hazardous area operations. CEA grid standards mandate redundant safety instrumented systems in power generation assets. The Jamnagar-Vadodara industrial belt hosts India's densest cluster of SIL-rated process control architectures.
Karnataka
Electronics manufacturing and precision assembly lines demand capacitive displacement sensors for wafer handling equipment. BIS certification timelines for IEC 61508 functional safety compress supplier qualification windows. Bengaluru's industrial corridors concentrate edge-AI predictive maintenance platform deployments.
Tamil Nadu
Wind turbine predictive maintenance and automotive just-in-time cells drive vibration and proximity sensor demand. MEMS chip shortages from East Asian foundries extend lead times for pressure module replacements. The Sriperumbudur-Oragadam belt sustains high-volume sensor consumption for export-oriented manufacturing.
Telangana
Greenfield pharmaceutical plants specify digital HART protocol transmitters for electronic batch record integration. DGFT localization incentives under the PLI scheme open tender access for domestic sensor assemblers. Hyderabad's bulk drug parks lack established service networks, creating whitespace for transmitter vendors.
India Industrial Sensors and Transmitters Market Competitive Landscape
European producers anchor the premium tier with functional safety certifications; Indian specialists hold mid-market replacement cycles through localized service networks. The vendor structure stratifies across three tiers: multinational system integrators, regional component distributors, and domestic calibration service providers. Dominant competitive moves include backward integration into control system software and asset-as-a-service contracting models that unbundle hardware from recurring revenue streams.
Within the multinational tier, ABB India Limited, Honeywell Automation India Limited, and Siemens Limited exemplify divergent strategic positioning. ABB leverages installed base relationships in power utilities to sustain recurring transmitter replacement cycles. Honeywell anchors its position through captive supply of control system software that locks in sensor compatibility requirements. Siemens competes by extending digital twin architectures into sensor-level data infrastructure, bundling hardware with analytics subscriptions.
| Leading Market Players |
|---|
| ABB India Limited |
| Honeywell Automation India Limited |
| Siemens Limited |
| Yokogawa India Ltd. |
| Emerson Process Management (India) Pvt. Ltd. |
| Endress+Hauser Pvt. Ltd. |
| Schneider Electric India Pvt. Ltd. |
| WIKA Instruments India Pvt. Ltd. |
| Turck India Automation Private Limited |
| Others |
Supply & Pricing Matrix
Silicon wafer spot prices and MEMS foundry utilization rates cascade through three distinct pricing tiers for Indian sensor buyers. Refinery operators absorb premium markups for SIL-certified transmitters while mid-tier manufacturers negotiate volume discounts on standard analog devices. Cost compression in the wireless sensor tier stems from battery and RF module localization under PLI incentives.
Pricing Analysis
Capacity additions in Tamil Nadu and Karnataka are reshaping price floors for domestic transmitter assemblers. Three-tier pricing structure across SIL-certified premium, HART-enabled standard, and legacy analog economy levels stratifies the market. Price differentiation hinges on IEC 61508 certification grade and after-sales calibration bundling. Cost compression in the economy tier intensifies as Chinese MEMS imports displace domestic piezoresistive modules. Pharmaceutical OEMs in Maharashtra show least price sensitivity due to CDSCO validation requirements, while commodity chemical buyers in Gujarat drive hardest bargain on replacement cycles.
Supply Chain Analysis
Dual-sourcing mandates from Reliance Industries and Indian Oil compel transmitter vendors to qualify secondary MEMS foundries beyond primary Taiwan and South Korea suppliers. The supply chain draws from German precision machining for ceramic pressure modules, Japanese ceramic substrates for high-temperature applications, and Chinese battery cells for wireless devices. Single-source vulnerability concentrates in 8-inch MEMS wafer supply from East Asian foundries. Distribution runs through regional instrumentation distributors in Mumbai, Chennai, and Ahmedabad who hold calibration inventory and service relationships with plant maintenance teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on software-integrated predictive maintenance bundles displacing commodity hardware sales. Wireless sensor adoption and edge-AI analytics subscriptions enable recurring revenue capture at premium pricing tiers.
For Market Incumbents: Lock in replacement cycle revenue by embedding transmitters into captive control system architectures that raise switching costs for refinery and pharmaceutical operators. Defend against emerging domestic challengers through accelerated BIS certification timelines and localized MEMS assembly investments in Tamil Nadu. Prioritize backward integration into edge computing hardware to capture analytics subscription margins.
For New Entrants and Emerging Players: WirelessHART-enabled vibration sensors for wind turbine predictive maintenance represent the most penetrable whitespace. Target Andhra Pradesh's Visakhapatnam bulk drug parks where established service networks remain absent and CDSCO mandates create urgent demand. Lead with asset-as-a-service contracting to bypass capital budget constraints among mid-sized chemical manufacturers.
For Investors and Strategic Acquirers: Asymmetric upside sits with domestic calibration service providers who aggregate fragmented plant maintenance relationships across Maharashtra and Gujarat. Five-to-ten year viability hinges on PLI scheme continuity and import substitution enforcement. Watch DGFT tender participation rates for domestic sensor manufacturers as inflection indicator for policy-driven market share shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Foundry Operations | Captive wafer supply insulates against East Asian lead time volatility for pressure sensor modules. |
| SIL Certification Acceleration Program | BIS adoption of IEC 61508 creates compliance barrier disqualifying uncertified imports from Gujarat refinery tenders. |
| Edge-AI Platform Partnership | Vibration analytics bundling with cloud subscriptions commands premium pricing from Karnataka predictive maintenance buyers. |
| Andhra Pradesh Service Network Buildout | First-mover calibration infrastructure captures Visakhapatnam bulk drug park demand before incumbent establishment. |
| Asset-as-a-Service Contracting Model | Operational expenditure structures unlock Maharashtra specialty chemical belt working capital constrained buyers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged plant engineers at Gujarat petrochemical complexes, procurement leads at Mumbai-Pune pharmaceutical manufacturers, maintenance directors at Tamil Nadu automotive facilities, and aftermarket service heads at regional instrumentation distributors. Secondary validation drew from BIS certification registries, CDSCO device approval databases, CEA technical standard notifications, PLI scheme disbursement records, and customs import data for sensor and transmitter HS codes. Bottom-up unit demand estimates triangulated against top-down industrial automation capex projections.
Segment-weighting approaches distributed value across sensor type, technology protocol, end-user industry, application, and regional industrial corridor dimensions. CAGRs derived from regression against historical industrial production indices, process automation investment cycles, and regulatory compliance deadline clustering. Forecast inputs incorporated WirelessHART deployment trajectories in Rajasthan solar installations, SIL-rated replacement cycles at Jamnagar refinery, and edge-AI platform adoption rates in Bengaluru electronics manufacturing.
The model holds under sustained PLI scheme enforcement and stable East Asian semiconductor supply; deviation in BIS certification timeline acceleration or MEMS foundry capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Automotive Image Sensors Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
Area Sensor Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
Magnetoresistance Sensor Market
Sensors and Controls
Inertial Sensors Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Ozone Meter Market
Sensors and Controls
Sensor Signal Conditioner (SSC) Ics Market