
 UV Sensors Market | 2026-2036
UV Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
UV Sensors Market Analytics
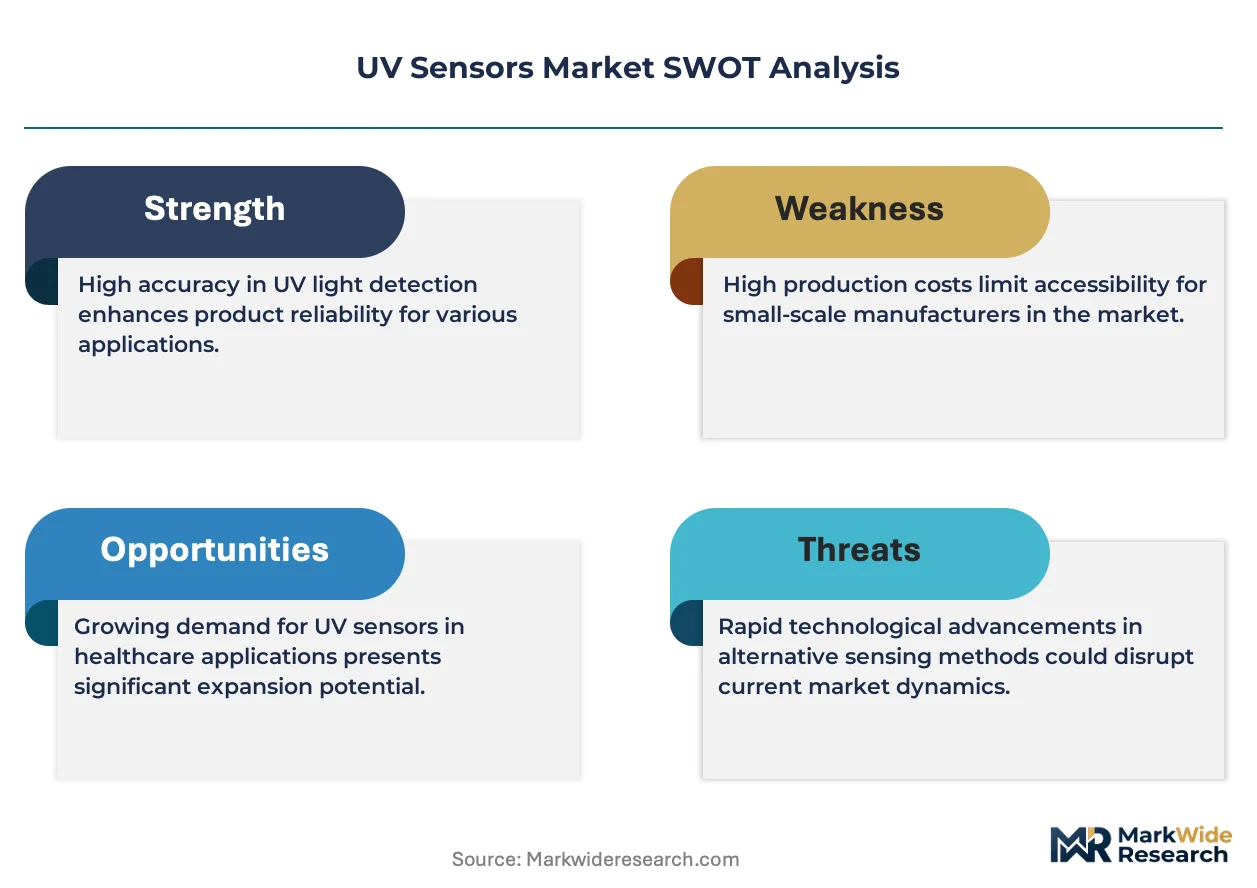
Gallium nitride is pivoting from niche aerospace applications into mainstream industrial UV sensing, slashing unit costs by half versus silicon-carbide predecessors. Hamamatsu Photonics leverages vertical integration across crystal growth and packaging to dominate high-precision photomultiplier production. Vishay Intertechnology anchors its position through captive silicon foundry capacity and automotive-grade qualification pipelines. STMicroelectronics competes by extending MEMS-compatible process nodes into sub-280nm detection ranges.
UV sensors are semiconductor devices that convert ultraviolet radiation into measurable electrical signals, typically operating across UVA (315–400nm), UVB (280–315nm), and UVC (100–280nm) bands with responsivity calibrated to NIST-traceable standards. Their primary commercial purpose spans disinfection validation, occupational exposure limits, and spectral irradiance mapping in controlled environments. Photodiodes command the largest installed base due to decades of silicon process maturity and foundry accessibility, while gallium nitride devices represent the fastest-expanding technology tier as epitaxial yields improve and wafer diameters scale beyond six inches. Water treatment applications concentrate margin pools because validation protocols demand redundant sensor arrays and mandatory recalibration cycles.
The EPA mandates UV dose verification under the Long Term 2 Enhanced Surface Water Treatment Rule, compelling municipal utilities to maintain redundant sensor networks with NIST-traceable calibration intervals. ECHA REACH restrictions on mercury-containing instruments accelerate solid-state UV detector substitution across European industrial hygiene monitoring. FDA 21 CFR Part 11 compliance requirements shape data-integrity specifications for pharmaceutical sterilization applications. Stakeholders must monitor gallium nitride epitaxy yield trajectories and emerging ISO 21469 hygienic design standards to time capacity investments and product roadmap commitments.
Market Dynamics
Gallium nitride epitaxy yield improvements are collapsing the cost barrier between precision UV photodiodes and legacy mercury-vapor detection systems, forcing incumbent silicon suppliers to defend foundry relationships through automotive qualification pipelines.
Growth Catalysts
- EPA Long Term 2 Enhanced Surface Water Treatment Rule:Municipal utilities in the United States must deploy redundant UV dose verification networks with NIST-traceable calibration intervals, creating mandatory replacement cycles for solid-state sensors.
- EU Drinking Water Directive revisions:German water treatment facilities face expanded monitoring mandates that favor multi-sensor arrays over single-point mercury instruments.
- Silicon photodiode process maturity:Decades of foundry accessibility and CMOS-compatible fabrication enable cost scaling that gallium nitride has yet to match in high-volume applications.
Market Restraints
- Epitaxial substrate costs:Gallium nitride production remains tethered to sapphire and silicon carbide wafer prices, which fluctuate with LED and power electronics demand cycles.
- Calibration infrastructure concentration:NIST-traceable standards and accredited laboratories cluster in Germany, Japan, and the United States, creating logistics friction for facilities elsewhere.
- Mercury instrument installed base:Legacy detection systems in industrial hygiene applications enjoy decades of technician familiarity and repair part availability that slows solid-state substitution.
Strategic Opportunities
- Pharmaceutical sterilization validation:FDA 21 CFR Part 11 compliance requirements for data integrity create premium demand for sensors with embedded audit trails and encrypted output streams.
- MEMS-compatible sub-280nm detection:Process node extension by European semiconductor foundries enables chip-scale UVC sensors for portable disinfection devices.
- ISO 21469 hygienic design standards:Emerging machinery safety protocols favor smooth-surface, crevice-free sensor housings that eliminate bacterial harborage points in food processing equipment.
Industry Challenges
- Gallium nitride epitaxy talent scarcity:Crystal growth engineers and MOCVD operators command premium compensation in competing LED and RF device markets, constraining sensor-dedicated production scale-up.
- Cross-industry calibration interval conflicts:Water treatment protocols demand annual recalibration while semiconductor fabs operate on quarterly cycles, forcing manufacturers to maintain incompatible service architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Sensors Market |
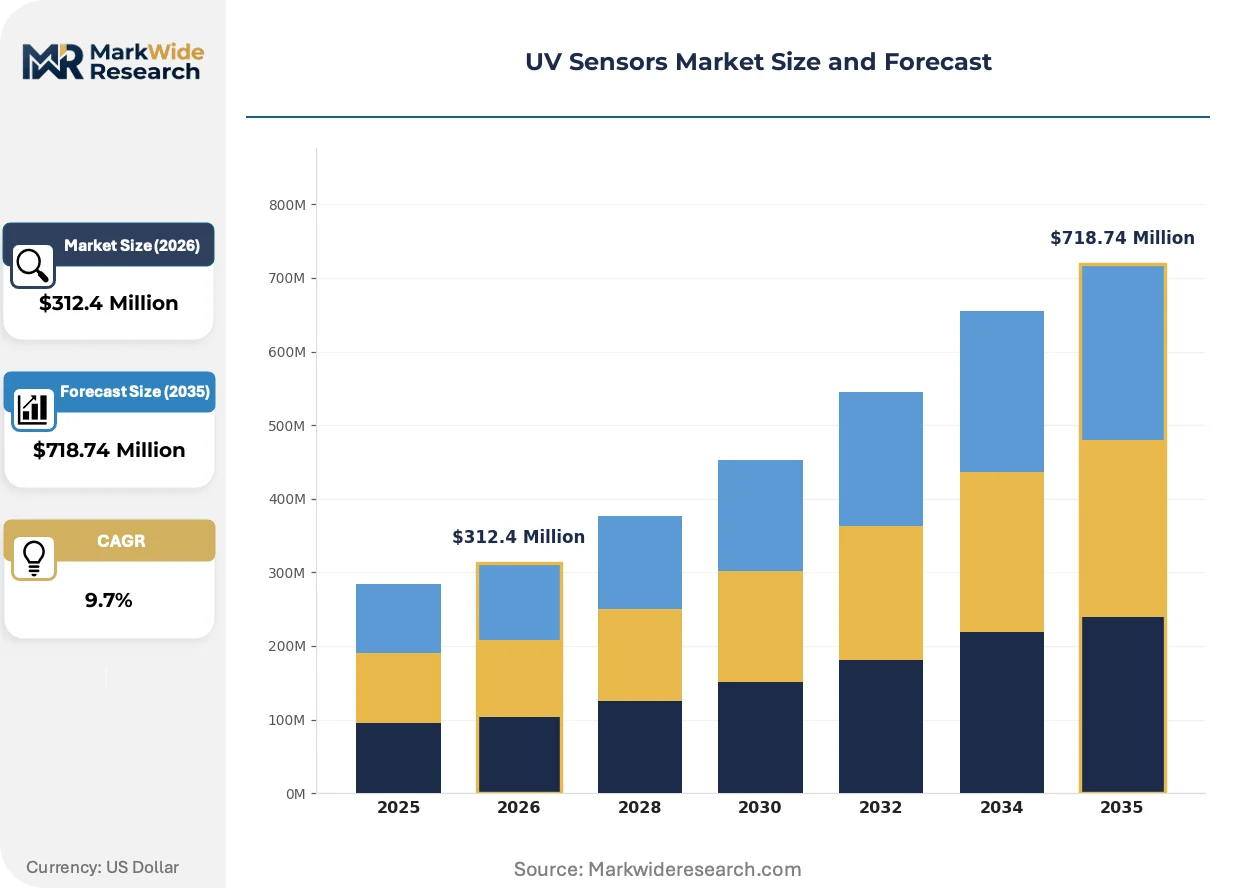
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photodiodes, Phototransistors, Photomultiplier Tubes, UV Light Sensors Technology: Silicon-based, Gallium Nitride, Organic Photodetectors, Thin Film Application: Water Treatment, Environmental Monitoring, Industrial Safety, Agriculture End User: Manufacturers, Research Institutions, Healthcare Facilities, Laboratories |
| Companies Covered | Panasonic Corporation, Hamamatsu Photonics, Vishay Intertechnology, Skye Instruments, Solar Light Company, STMicroelectronics, sglux, Apogee Instruments, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Sensors Market Evolving Landscape
Silicon carbide is losing ground to gallium nitride in precision UV detection as epitaxial yields improve and wafer diameters scale, while regulatory mandates across multiple geographies harden data-integrity requirements for critical infrastructure applications.
Gallium nitride is rewriting the economics of UVC sensing by delivering sub-280nm responsivity without the thermal management burden of silicon carbide predecessors. Water treatment OEMs in Germany and Japan are qualifying GaN-based arrays for validation-redundant installations. The technology is compressing the price-performance gap that has protected silicon photodiode dominance in cost-sensitive industrial monitoring.
ECHA REACH restrictions on mercury-containing instruments are accelerating solid-state detector substitution across European industrial hygiene monitoring networks. The regulation forces replacement of legacy mercury-vapor lamps and their paired sensors in occupational exposure limit verification. Pharmaceutical manufacturers in Switzerland and France face compressed compliance timelines as accredited calibration laboratories absorb qualification backlogs.
Buyers in municipal water utilities are unbundling sensor procurement from system integrator contracts, establishing direct relationships with component manufacturers for recalibration and replacement parts. This disintermediation concentrates volume with suppliers capable of maintaining NIST-traceable documentation and regional service presence. The pattern is most visible in the United States, where EPA enforcement of LT2 rule compliance has hardened technical specifications beyond generic catalog offerings.
UV Sensors Market Segmentation
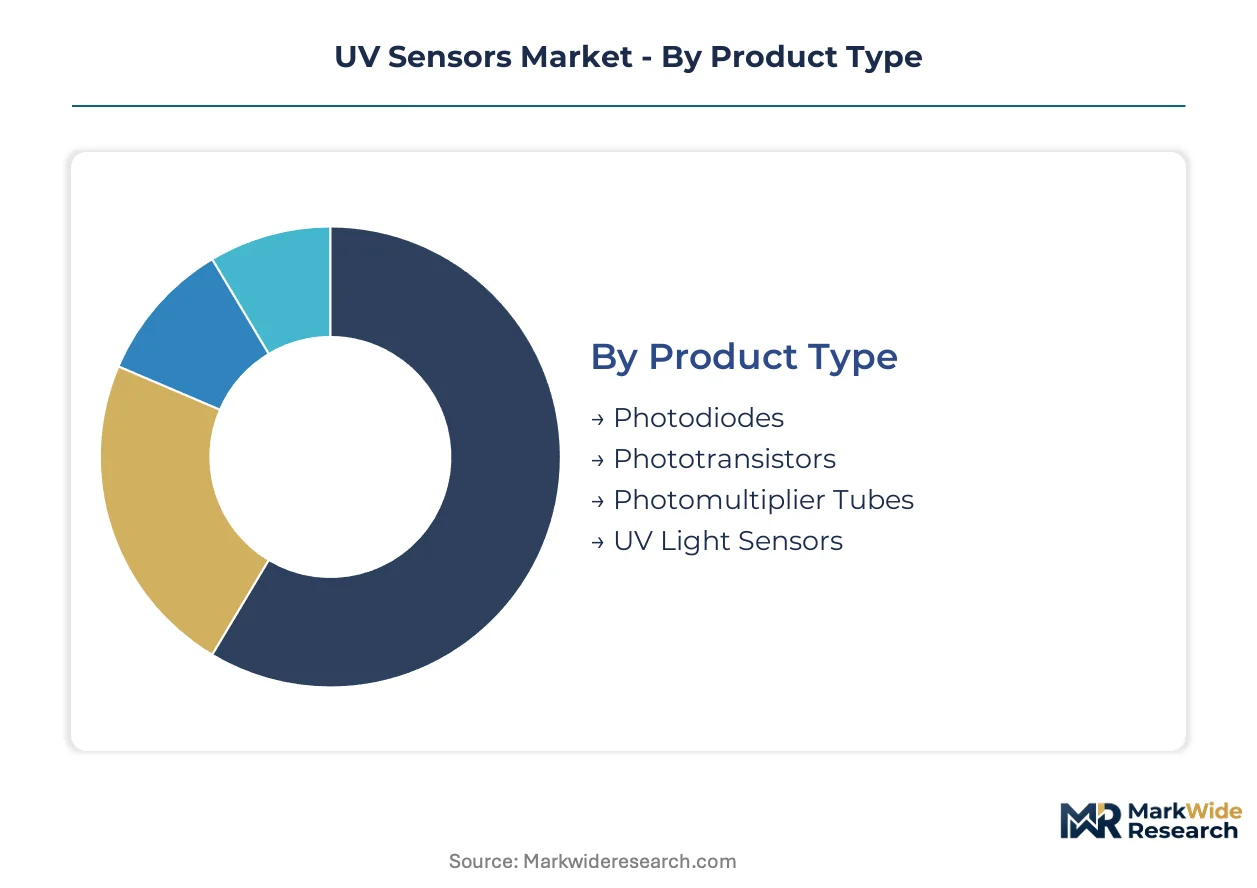
UV sensor procurement patterns diverge sharply across product architectures and end-use contexts, with capital deployment decisions hinging on calibration infrastructure requirements and foundry accessibility. Technology selection cascades into application suitability, creating distinct margin pools that reward early qualification investments in regulated environments.
Product Type:
Capital intensity concentrates in photomultiplier tube fabrication, where vacuum-sealed dynode chains demand specialized cleanroom infrastructure and extended burn-in protocols.
- Photodiodes:Silicon junction devices dominate installed capacity through decades of CMOS-compatible process maturity. Municipal water utilities in Germany specify these for redundant UV dose verification arrays under EU Drinking Water Directive mandates.
- Phototransistors:Bipolar gain structures amplify low-irradiance signals without external circuitry. Industrial hygiene monitors in Japan favor these for portable occupational exposure limit verification where battery life constrains design.
- Photomultiplier Tubes:Dynode cascade architectures deliver single-photon sensitivity for spectroscopy applications.
- UV Light Sensors:Integrated analog front-end modules reduce BOM complexity for high-volume OEMs.
Photodiodes absorb the bulk of installed capacity; photomultiplier tubes are expanding most quickly in pharmaceutical sterilization validation.
Technology:
Process node accessibility determines which technology tiers can leverage existing semiconductor foundry relationships versus requiring dedicated epitaxy investments.
- Silicon-based:Mature diffusion and implant processes enable cost scaling unmatched by compound semiconductors. EPA-mandated municipal water treatment networks in the United States rely on silicon photodiodes for NIST-traceable calibration cycles.
- Gallium Nitride:Wide-bandgap epitaxy delivers native UVC responsivity without phosphor conversion losses. Japanese water treatment OEMs are qualifying GaN arrays for validation-redundant installations as sapphire substrate costs decline.
- Organic Photodetectors:Solution-processed active layers enable flexible form factors for wearable exposure monitors.
- Thin Film:Amorphous and polycrystalline depositions on glass or polymer substrates suit cost-constrained consumer applications.
Silicon-based platforms retain the deepest installed base; gallium nitride is gaining share fastest as epitaxial yields improve.
Application:
Regulatory compliance burdens vary dramatically across use cases, with validation protocols in water treatment demanding sensor redundancy that inflates unit economics.
- Water Treatment:Disinfection validation requires redundant sensor arrays with mandatory recalibration intervals. German utilities face expanded monitoring mandates under revised EU Drinking Water Directive provisions.
- Environmental Monitoring:Spectral irradiance mapping for ozone layer assessment and solar UV indexing. Research stations in Japan deploy precision radiometers for atmospheric chemistry programs.
- Industrial Safety:Arc flash detection and welding exposure limits in manufacturing environments.
- Agriculture:Controlled-environment horticulture uses UV-B dosing to trigger secondary metabolite production in specialty crops.
Water treatment commands the steepest expansion trajectory; environmental monitoring maintains the most stable replacement cycles.
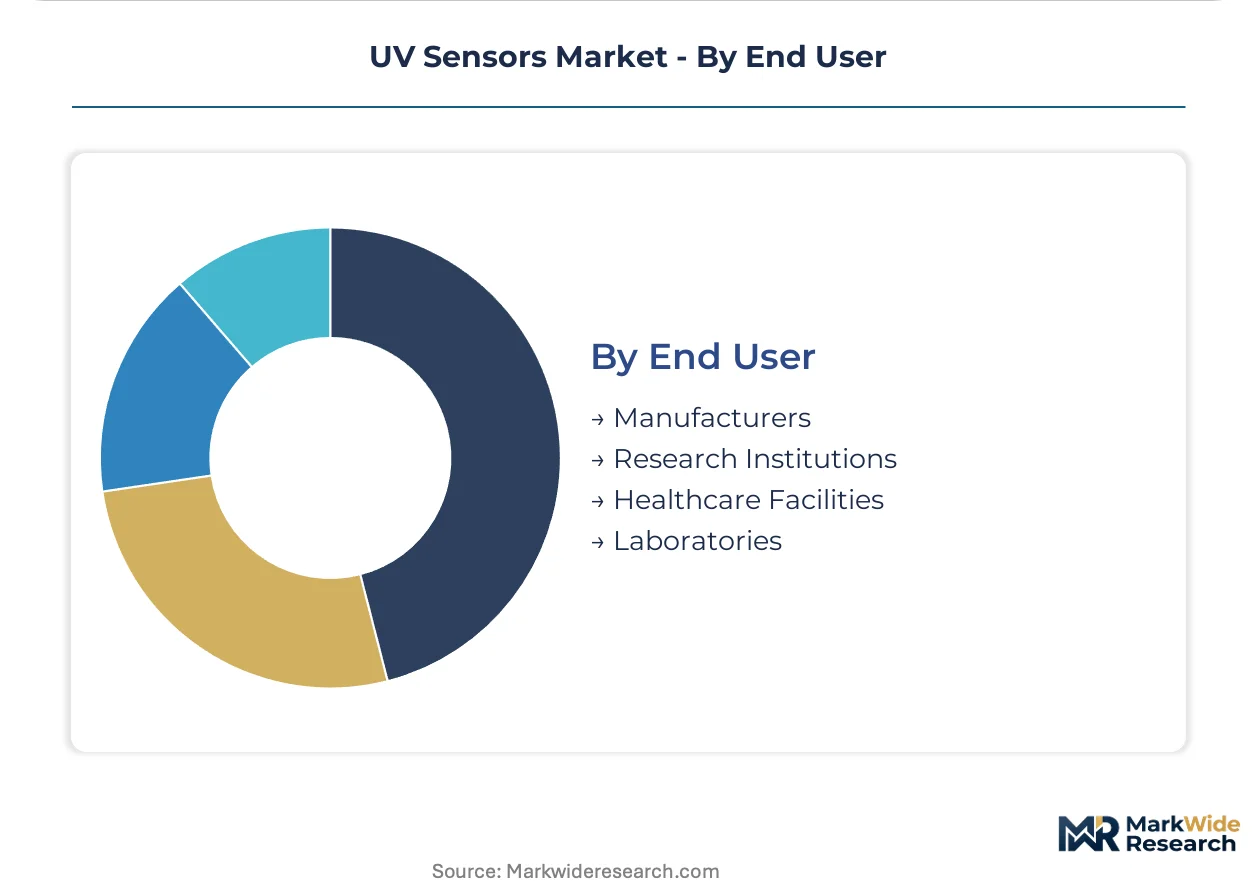
End User:
Procurement sophistication separates volume buyers with captive calibration capabilities from fragmented purchasers dependent on third-party service networks.
- Manufacturers:System integrators and OEMs specify sensors for embedded disinfection and monitoring equipment. Automotive suppliers in the United States are qualifying UV sensors for cabin air sterilization modules.
- Research Institutions:National laboratories and universities demand NIST-traceable spectral responsivity data. Swiss research facilities under ECHA REACH timelines are replacing mercury-vapor instruments with solid-state alternatives.
- Healthcare Facilities:Hospital sterilization departments validate UV-C dosing for terminal room disinfection.
- Laboratories:Analytical and clinical labs require calibrated irradiance references for photostability testing.
Manufacturers represent the largest volume channel; healthcare facilities are climbing the fastest as infection control budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, the United States, and Japan where water treatment infrastructure upgrades and semiconductor fabrication investments drive procurement volumes. Municipal utilities and industrial OEMs in these markets specify redundant sensor arrays with NIST-traceable calibration protocols. Regional expansion patterns follow regulatory enforcement timelines rather than organic demand growth.
Germany
Water treatment OEMs in Bavaria and North Rhine-Westphalia are qualifying gallium nitride sensor arrays for validation-redundant installations. ECHA REACH restrictions on mercury-containing instruments force accelerated replacement of legacy detection systems in industrial hygiene networks. The Rhine-Main cluster around Frankfurt hosts accredited calibration laboratories absorbing qualification backlogs from Swiss and French pharmaceutical manufacturers.
United States
EPA enforcement of Long Term 2 Enhanced Surface Water Treatment Rule compliance hardens technical specifications for municipal UV dose verification networks. Utilities in California and Texas are unbundling sensor procurement from system integrator contracts to establish direct manufacturer relationships. The Southwest water corridor faces compressed replacement cycles as drought conditions intensify disinfection validation requirements.
Japan
METI-backed semiconductor initiatives in the Kyushu and Tohoku regions expand domestic gallium nitride epitaxy capacity for UVC sensing applications. Water treatment OEMs in the Kansai industrial belt are deploying multi-sensor arrays under voluntary standards anticipating formal EU alignment. Tokyo-based research stations operate precision radiometers for atmospheric chemistry programs requiring NIST-traceable spectral responsivity data.
China
MIIT industrial upgrading programs in the Yangtze River Delta subsidize domestic photodiode foundry investments targeting water treatment export markets. Municipal utilities in Shenzhen and Shanghai pilot solid-state UV validation systems as alternatives to mercury-vapor instrumentation. The Pearl River Delta concentration of LED epitaxy facilities creates supply chain spillovers for emerging GaN sensor fabrication.
Switzerland
Swissmedic pharmaceutical sterilization standards and ECHA REACH timelines compress compliance windows for solid-state detector substitution. Research facilities in Basel and Zurich are replacing mercury-vapor instruments with silicon photodiode alternatives under accelerated accreditation schedules. The country's precision instrumentation cluster maintains captive calibration capabilities serving adjacent EU markets.
UV Sensors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with photodiode fabrication consolidating around captive foundry relationships while gallium nitride sensing remains fragmented among epitaxy-dependent specialists. The vendor landscape organizes into three archetypes: silicon-based volume suppliers defending automotive qualification pipelines, compound semiconductor entrants exploiting GaN yield improvements, and precision photomultiplier manufacturers serving spectroscopy niches. Dominant competitive moves include backward integration into crystal growth capacity and geographic expansion of NIST-traceable calibration service networks.
Among Japanese precision instrumentation specialists, Hamamatsu Photonics exemplifies the vertically integrated archetype spanning crystal growth through vacuum-sealed packaging. Vishay Intertechnology and STMicroelectronics occupy positions within the silicon-based tier, with the former representing captive foundry capacity and the latter extending MEMS-compatible process nodes. These three anchors illustrate how technology selection cascades into divergent margin pools across water treatment, automotive, and pharmaceutical validation applications.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Hamamatsu Photonics |
| Vishay Intertechnology |
| Skye Instruments |
| Solar Light Company |
| STMicroelectronics |
| sglux |
| Apogee Instruments |
| Broadcom |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Japan and Germany anchor foundry capacity for silicon photodiodes, translating captive wafer supply into pricing discipline that resists gallium nitride erosion in municipal water treatment contracts. Their long-tenured relationships with NIST-traceable calibration laboratories create switching costs that sustain margin premiums against Asian contract manufacturers.
Pricing Analysis
Volume absorption concentrates in standard-grade silicon photodiodes for EPA-mandated municipal utilities, while margin extraction clusters in pharmaceutical-grade sensors with embedded FDA 21 CFR Part 11 audit trails. Price differentiation separates NIST-traceable certified tiers from uncertified catalog offerings. Cost compression in silicon photodiodes is intensifying because foundry utilization rates in automotive qualification pipelines are diverting capacity. Municipal water utilities exhibit the highest price sensitivity due to procurement unbundling from system integrators, whereas pharmaceutical sterilization departments accept premium pricing for encrypted output streams.
Supply Chain Analysis
Freight costs for sapphire and silicon carbide substrates from Japan and the United States fluctuate with LED and power electronics demand cycles, compressing logistics budgets for gallium nitride sensor startups. Raw material dependencies center on high-purity gallium metal, specialized epitaxy gases, and NIST-traceable calibration reference standards. Single-source vulnerability concentrates in accredited calibration laboratories clustered in Germany, Japan, and the United States. Distribution runs through direct manufacturer relationships with municipal utilities and OEM system integrators, bypassing traditional component distributors for validation-critical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over gallium nitride epitaxy capacity and NIST-traceable calibration infrastructure determines pricing power and customer lock-in across water treatment and pharmaceutical validation segments.
For Market Incumbents: Deploy automotive qualification pipeline leverage to defend foundry relationships against gallium nitride substitution. Expand backward integration into crystal growth capacity to secure sapphire substrate supply amid LED demand competition. Deepen regional calibration service networks to match EPA-mandated replacement cycles and EU Drinking Water Directive compliance timelines. For New Entrants and Emerging Players: Portable disinfection device OEMs represent an underserved buyer archetype seeking MEMS-compatible sub-280nm sensors at consumer price points. Target Swiss and French pharmaceutical manufacturers facing compressed ECHA REACH compliance windows with solid-state alternatives to mercury-vapor instruments. Pursue direct calibration-as-a-service contracts to bypass incumbent distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor compound semiconductor specialists with proven MOCVD yield trajectories in Japan and the United States during LED market downturns. Long-term viability hinges on gallium nitride epitaxy talent retention and ISO 21469 hygienic design certification progress. Monitor sapphire substrate price inflections as the signal to time capacity investment commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Growth | Captive sapphire substrate supply insulates Hamamatsu and Vishay from LED demand cycle volatility. |
| NIST-Traceable Calibration Network Expansion | Regional service presence secures municipal utility contracts under EPA LT2 rule enforcement. |
| MEMS-Compatible Process Node Extension | STMicroelectronics leverages European foundry partnerships for chip-scale UVC sensor miniaturization. |
| Pharmaceutical Data Integrity Certification | FDA 21 CFR Part 11 compliance creates premium pricing power in sterilization validation segments. |
| Gallium Nitride Epitaxy Yield Improvement | Japanese water treatment OEMs qualify GaN arrays as sapphire costs decline and wafer diameters scale. |
Research Methodology
Multi-period observation of gallium nitride epitaxy yield trajectories, NIST-traceable calibration laboratory capacity, and municipal utility procurement unbundling anchored the trend analysis, supplemented by interviews with water treatment OEM procurement directors, semiconductor foundry operations managers, pharmaceutical sterilization validation engineers, and EPA compliance officers. Secondary validation drew from EPA enforcement records, ECHA REACH restriction timelines, FDA 21 CFR Part 11 guidance documents, and METI semiconductor initiative disclosures. Bottom-up sensor shipment estimates triangulated against top-down water treatment infrastructure investment flows.
Segment-weighting across product architecture, technology tier, application context, and end-user sophistication shaped the analytical framework across the projection horizon. Modeled dimensions included photodiode versus photomultiplier tube versus gallium nitride device splits, silicon versus compound semiconductor process nodes, water treatment versus pharmaceutical versus environmental monitoring applications, and manufacturer versus research institution versus healthcare facility procurement channels. CAGRs derived from installed base replacement cycles, regulatory mandate enforcement timelines, and epitaxy capacity expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gallium nitride epitaxy yield breakthroughs, ECHA REACH enforcement acceleration, and municipal utility budget constraints under drought-induced water stress. Forecasts reflect documented assumptions about regulatory timeline adherence and substrate cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
North America Nano Sensors Market
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
Middle East and Africa Lidar Market
Sensors and Controls
Air Pressure Sensor Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
Latin America Proximity Sensors Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Specialty Control Plasma Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
Piezoelectric Accelerometer Market