
 ASEAN Safety Sensors and Switches Market | 2026-2036
ASEAN Safety Sensors and Switches Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Safety Sensors and Switches Market Outlook
Modular safety component bundles is repositioning procurement patterns across ASEAN industrial buyers. Schneider Electric leverages its regional distribution network to anchor premium positioning in Thailand and Vietnam. SICK AG competes through deep specialization in photoelectric sensor arrays for robotic cells. Pepperl+Fuchs extends its wireless safety portfolio to capture retrofit demand in aging Malaysian manufacturing parks.
ASEAN safety sensors and switches encompass electromechanical and electronic devices engineered to detect proximity, pressure, light interruption, or mechanical position, typically rated for IP67 environmental sealing and SIL 2/3 functional safety integrity. These components halt hazardous motion, isolate energy sources, or trigger emergency sequences when operators enter danger zones. Photoelectric sensors dominate value capture due to precision requirements in high-speed automation lines across Indonesian electronics factories. Safety relay modules command outsized margins as system integrators specify redundant architectures for automotive welding operations. Wireless technology segments accelerate fastest where cable routing proves impractical in Vietnam's sprawling food-processing plants.
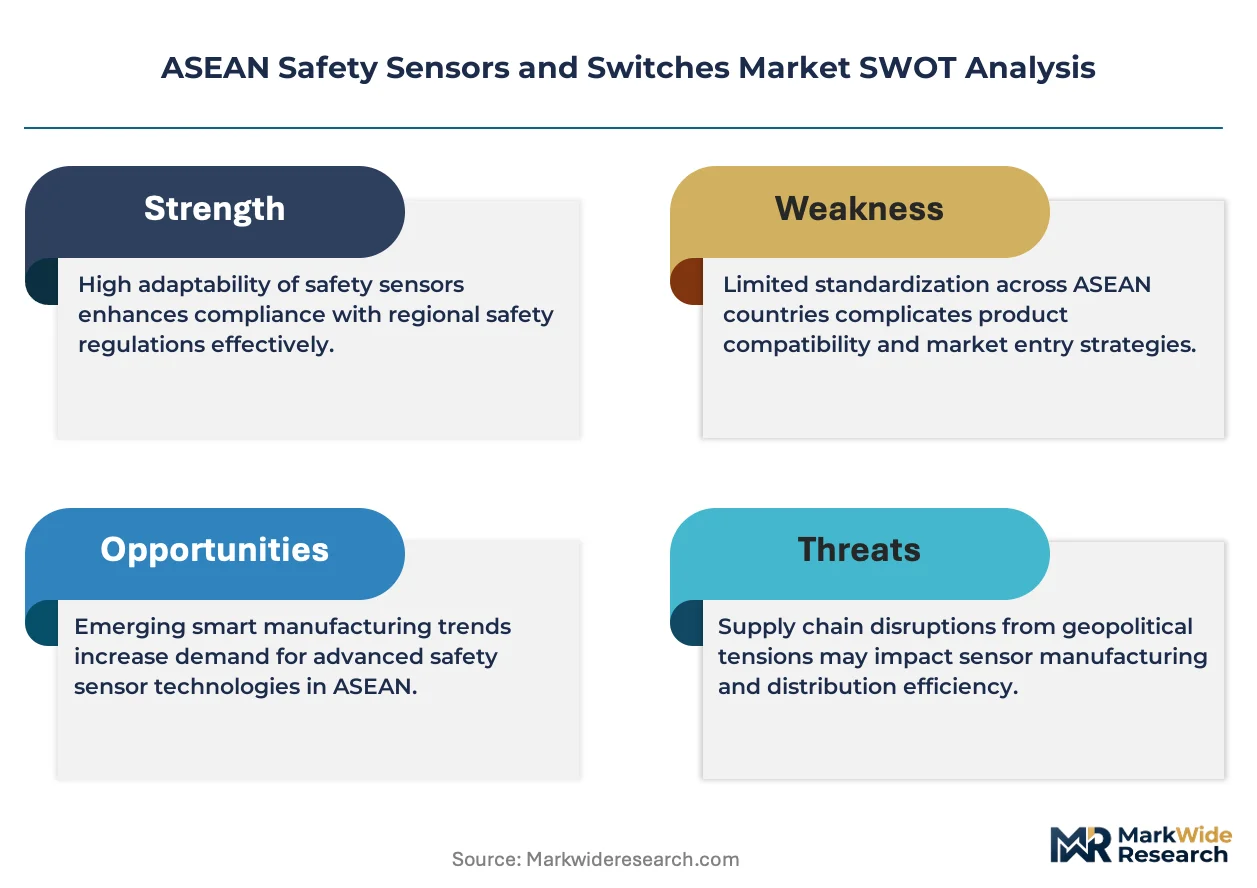
Thailand's Ministry of Industry enforces Factory Act amendments mandating risk-assessed machine guarding, directly expanding sensor replacement cycles. Malaysia's Department of Occupational Safety and Health aligns with IEC 62061 and ISO 13849 standards, compelling importers to certify products through accredited national bodies. Singapore's Workplace Safety and Health Council pushes outcome-based compliance frameworks that reward predictive maintenance integration. Stakeholders must monitor divergence between national implementation timelines and ASEAN-wide mutual recognition agreements to optimize certification investments.
Market Dynamics
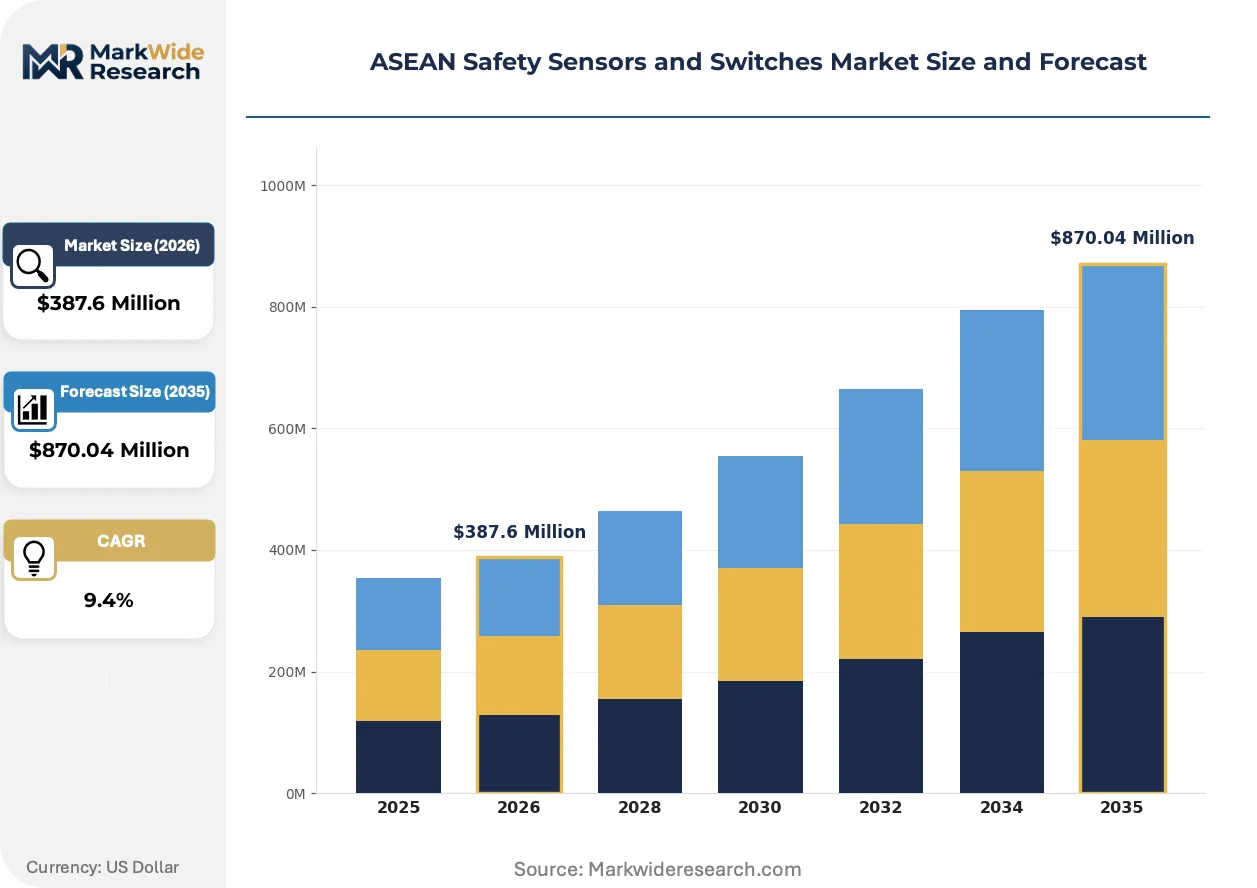
Factory automation across Thailand and Vietnam is forcing rapid sensor replacement cycles as Japanese and Korean OEMs mandate fail-safe architectures at new automotive and electronics plants. The shift from electromechanical to solid-state detection systems is compressing supplier lead times and rewiring procurement relationships.
Growth Catalysts
- Factory Act Amendments:Thailand's Ministry of Industry mandates risk-assessed machine guarding, directly expanding replacement demand for proximity switches and light curtains in metalworking facilities.
- Japanese OEM Specifications:Automotive assemblers in Indonesia's Bekasi corridor require SIL 2-certified photoelectric arrays at all new welding stations, pulling premium sensor volumes.
- Wireless Retrofit Cycles:Aging cable infrastructure in Malaysian food-processing parks drives demand for battery-free safety switches eliminating conduit runs.
Market Restraints
- Semiconductor Input Volatility:Safety relay modules depend on automotive-grade microcontrollers subject to allocation constraints from Taiwanese foundries.
- Certification Fragmentation:Divergent timelines between Malaysia's DOSH accreditation and Singapore's outcome-based compliance create duplicated testing costs for pan-ASEAN suppliers.
- Pneumatic Substitution:Compressed-air interlocks retain cost advantage in low-speed Vietnamese textile machinery, delaying electronic sensor penetration.
Strategic Opportunities
- Myanmar Industrial Zones:Special economic zones near Yangon lack established safety infrastructure, creating first-mover positioning for wireless safety system providers.
- Predictive Maintenance Integration:Singapore's Workplace Safety and Health Council rewards sensor data feeds into condition-monitoring platforms with reduced inspection frequency.
- IO-Link Convergence:Standardized digital communication between safety switches and PLCs enables remote parameterization, reducing commissioning labor in remote Indonesian installations.
Industry Challenges
- Functional Safety Engineering Shortage:Certified TÜV Rheinland engineers for SIL verification remain concentrated in Singapore and Bangkok, constraining Vietnamese system integrator capacity.
- Legacy PES Integration:Programmable electronic safety controllers from 2010-2015 lack modern fieldbus compatibility, forcing expensive rip-and-replace decisions at Philippine electronics plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Safety Sensors and Switches Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $870.04 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photoelectric Sensors, Proximity Switches, Pressure Sensors, Safety Relay End User: Manufacturing, Automotive, Aerospace, Consumer Electronics Technology: Analog, Digital, Safety-Related, Wireless Application: Automation, Industrial Safety, Home Security, Robotics |
| Companies Covered | Schneider Electric, SICK AG, Banner Engineering Corp., Omron, Rockwell Automation, ABB, Honeywell International, Pepperl+Fuchs, Eaton Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Safety Sensors and Switches Market Strategic Shifts
Safety sensor architectures are converging around digital communication protocols and solid-state detection methods, displacing hardwired electromechanical systems across ASEAN manufacturing floors. Three developments are compressing deployment timelines and rewiring value capture.
Time-of-flight photoelectric sensors are expanding into high-speed robotic cells where millimeter-precision position verification prevents collision damage. Vietnamese automotive parts suppliers adopt these arrays at twice the pace of conventional through-beam setups. The technology is expanding into collaborative robot applications previously served by mechanical interlocks, compressing the addressable market for legacy limit switches.
Malaysia's Department of Occupational Safety and Health now enforces IEC 62061 conformity for all imported safety relays, rejecting uncertified products at port. This industrial consequence forces European and Japanese suppliers to pre-certify through accredited national bodies before shipment. Automotive welding operations in Selangor face the strictest scrutiny, driving specification of redundant dual-channel architectures.
System integrators in Thailand's Eastern Economic Corridor now bundle safety component procurement with five-year maintenance contracts, unbundling hardware margins from service revenue. This channel shift displaces traditional distributor relationships where sensors sold standalone. The model concentrates most visibly at Rayong's petrochemical complexes, where uptime guarantees override upfront hardware cost considerations.
ASEAN Safety Sensors and Switches Market Segmentation
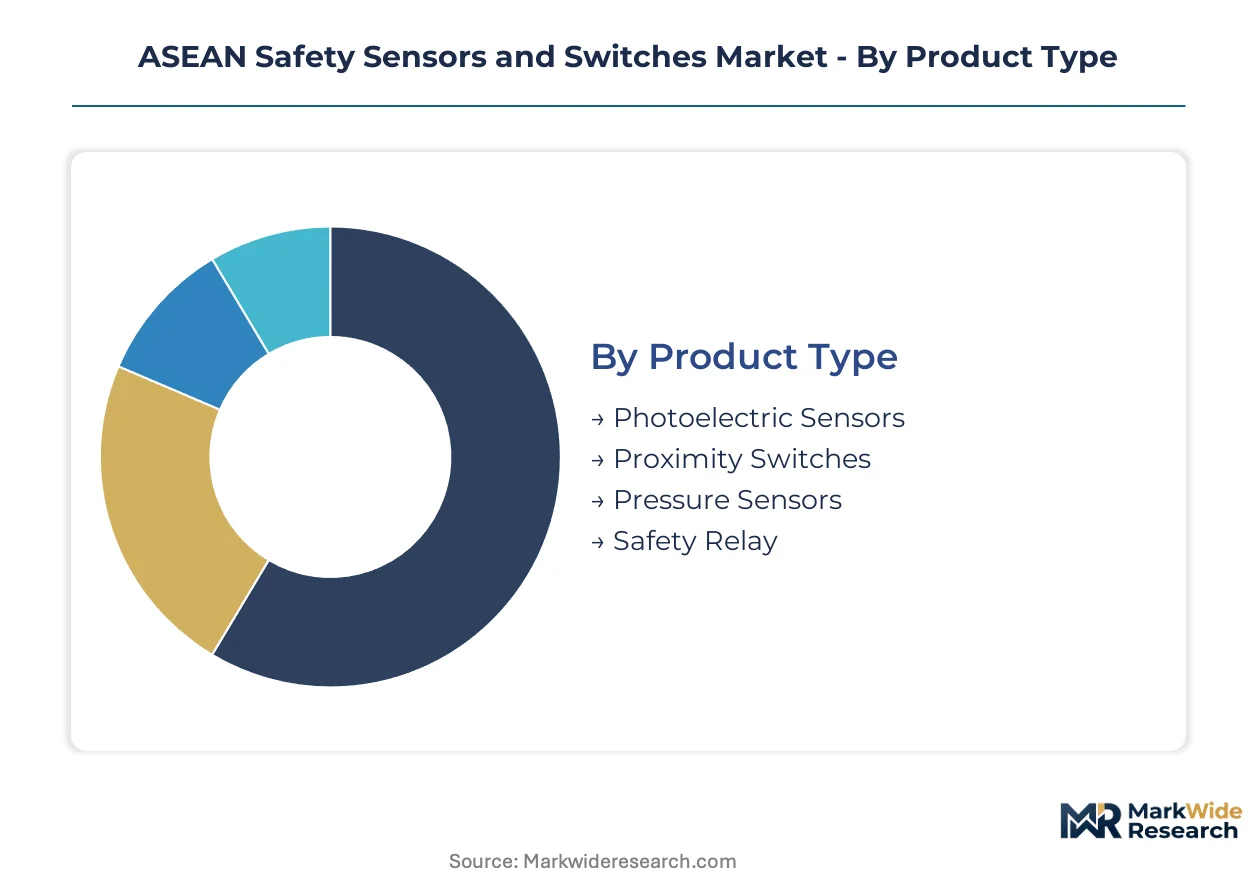
Safety sensor procurement across ASEAN diverges sharply by capital intensity and certification requirements. Japanese OEM specifications and national Factory Act amendments create tiered demand patterns that reward specialized product configurations.
Product Type:
Capital deployment varies dramatically across sensor categories, with SIL-rated architectures demanding substantially higher upfront engineering investment than standard industrial variants.
- Photoelectric Sensors:Time-of-flight and through-beam configurations achieve millimeter-precision position verification using modulated light emission and receiver arrays. Indonesian electronics factories in Bekasi and Batam deploy these at welding stations where Japanese automotive OEMs mandate fail-safe collision prevention. Solid-state architectures displace mechanical interlocks in high-speed robotic cells.
- Safety Relay:Redundant dual-channel modules with force-guided contacts achieve SIL 2/3 functional safety integrity through monitored internal logic. Malaysia's Department of Occupational Safety and Health now enforces IEC 62061 conformity at port entry, compelling pre-certification through accredited national bodies before shipment to Selangor automotive plants.
- Proximity Switches:Inductive and capacitive variants detect metallic and non-metallic targets without physical contact.
- Pressure Sensors:Piezoelectric and strain-gauge elements monitor hydraulic and pneumatic system integrity.
Most installed capacity flows through Photoelectric Sensors. Expansion is steepest in Safety Relay as regulatory enforcement tightens.
End User:
Application complexity and compliance burden separate premium-specification buyers from price-sensitive procurement.
- Automotive:Welding robot cells and paint shops require SIL 2-certified photoelectric arrays with redundant architectures. Thailand's Eastern Economic Corridor and Indonesia's Bekasi corridor concentrate Japanese and Korean OEM demand where fail-safe integration is non-negotiable at new plant commissioning.
- Manufacturing:Metalworking, food processing, and packaging lines deploy mixed sensor portfolios. Vietnam's sprawling textile and food-processing parks favor wireless retrofit solutions where aging cable infrastructure makes conduit runs economically unviable.
- Aerospace:MRO facilities and component suppliers specify aerospace-grade proximity detection.
- Consumer Electronics:Assembly automation drives demand for compact, high-speed sensing arrays.
Procurement volumes concentrate in Automotive. Steepest expansion trajectory appears in Manufacturing as Thailand's Factory Act amendments accelerate replacement cycles.
Technology:
Signal processing architecture determines integration complexity and lifecycle maintenance burden across ASEAN installations.
- Digital:Microprocessor-based detection with self-diagnostic capabilities and configurable parameters via software interfaces. IO-Link standardization enables remote parameterization, reducing commissioning labor at remote Indonesian installations where certified safety engineers remain scarce.
- Wireless:Battery-free energy harvesting and radio-frequency transmission eliminate cable infrastructure. Malaysian food-processing parks and Vietnamese textile facilities adopt these for retrofit applications where conduit routing through existing structures proves impractical.
- Analog:Continuous voltage or current output without digital processing.
- Safety-Related:Dedicated architectures meeting IEC 61508 and ISO 13849 for functional safety.
Deployment favors Digital technology for new installations. Wireless gains share fastest in retrofit-heavy manufacturing corridors.
Application:
Operational criticality and downtime cost structure shape specification intensity across use cases.
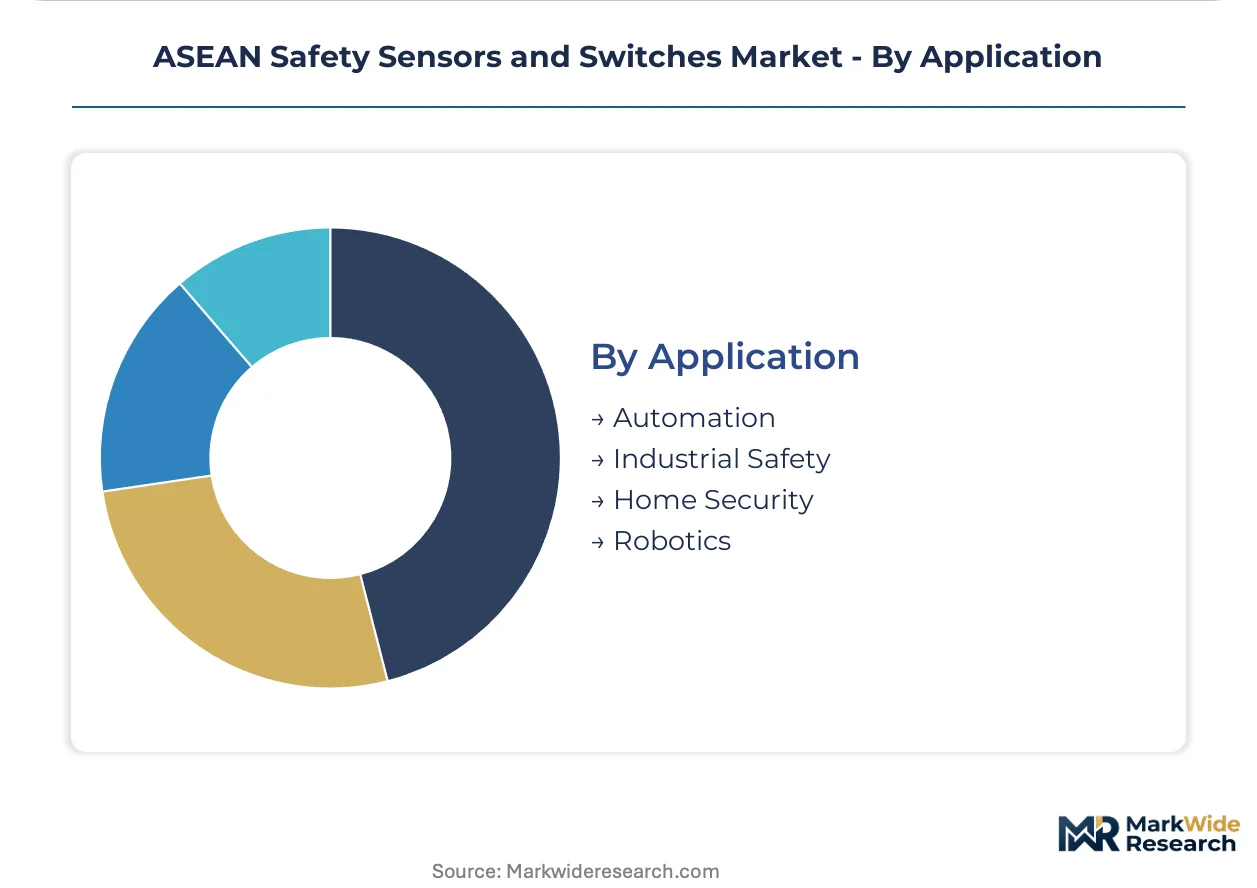
- Industrial Safety:Machine guarding, emergency stop systems, and access control demand the highest functional safety ratings. Thailand's Ministry of Industry enforces risk-assessed guarding under Factory Act amendments, directly expanding replacement demand for light curtains and safety mats in metalworking facilities nationwide.
- Robotics:Collaborative and industrial robot cells require proximity verification with response times under 10 milliseconds. Vietnamese automotive parts suppliers adopt time-of-flight arrays at twice the pace of conventional setups for collision prevention in high-density work envelopes.
- Automation:Process control and material handling integration.
- Home Security:Perimeter and access detection for residential and commercial buildings.
Revenue concentrates in Industrial Safety applications. Robotics represents the fastest-climbing segment as collaborative automation penetrates ASEAN electronics assembly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ASEAN safety sensors and switches industry traces its scaling to Japanese automotive OEM expansion into Thailand and Indonesia during the 1990s, establishing fail-safe component demand patterns that now propagate across Vietnam and Malaysia as factory automation deepens.
Thailand
Thailand's Eastern Economic Corridor concentrates Japanese and Korean automotive assembly where welding robot cells mandate SIL 2-certified photoelectric arrays. The Ministry of Industry enforces Factory Act amendments requiring risk-assessed machine guarding, accelerating replacement cycles for proximity switches in Rayong's petrochemical complexes and metalworking facilities nationwide.
Indonesia
Indonesia's Bekasi corridor anchors Japanese OEM demand where new plant commissioning requires redundant safety architectures at every welding station. The country's national industrial regulator harmonizes with ASEAN Economic Community standards, pushing importers toward CE-compatible product lines certified through accredited national bodies before port entry.
Vietnam
Vietnamese automotive parts suppliers adopt time-of-flight photoelectric sensors at twice the pace of conventional setups for high-density robotic cells. The sprawling textile and food-processing parks in Binh Duong and Dong Nai favor wireless retrofit solutions where aging cable infrastructure makes conduit runs economically unviable.
Malaysia
Malaysia's Selangor state faces strictest safety relay scrutiny as the Department of Occupational Safety and Health enforces IEC 62061 conformity at port, rejecting uncertified products. Aging manufacturing parks in Penang and Johor drive battery-free safety switch demand for retrofit applications eliminating conduit runs through existing structures.
Singapore
Singapore's precision engineering clusters specify predictive maintenance integration where the Workplace Safety and Health Council rewards sensor data feeds into condition-monitoring platforms with reduced inspection frequency. Jurong Island's process industries and Tuas biomedical parks concentrate demand for IO-Link-enabled digital architectures enabling remote parameterization.
ASEAN Safety Sensors and Switches Market Competitive Environment
The competitive structure tilts toward diversified industrial automation conglomerates with established regional distribution networks. European and Japanese suppliers dominate premium specification tiers through pre-certified product portfolios, while specialized sensor manufacturers capture retrofit niches with wireless and solid-state innovations. Three archetypes define positioning: full-line automation providers bundling safety with control systems, photoelectric specialists leveraging precision detection expertise, and component-focused suppliers targeting wireless retrofit cycles. Geographic expansion through local system integrator partnerships and portfolio diversification into predictive maintenance integration represent the dominant competitive moves reshaping channel relationships.
Within the diversified automation tier, Schneider Electric exemplifies full-line positioning through its regional distribution anchoring premium market presence across Thailand and Vietnam. SICK AG occupies a position as the photoelectric detection specialist, with its German engineering heritage representing deep technical focus on robotic cell applications. Pepperl+Fuchs sits within the component innovation archetype, its wireless safety portfolio capturing retrofit demand in aging Malaysian manufacturing infrastructure where cable elimination drives procurement decisions.
| Leading Market Players |
|---|
| Schneider Electric |
| SICK AG |
| Banner Engineering Corp. |
| Omron |
| Rockwell Automation |
| ABB |
| Honeywell International |
| Pepperl+Fuchs |
| Eaton Corporation |
| Others |
Value Chain & Pricing Dynamics
Thailand's Factory Act amendments mandating risk-assessed machine guarding gate qualified supply access for SIL-certified sensor architectures, compressing premium-tier pricing power into pre-certified European and Japanese supplier networks while excluding uncertified competitors from automotive procurement channels.
Pricing Analysis
Three-tier pricing structure across SIL 3-certified premium, SIL 2-compliant standard, and uncertified economy levels dominates ASEAN safety sensor transactions. Price differentiation centers on IEC 62061 certification grade and bundled after-sales service contracts, with Thai automotive OEMs least sensitive and Vietnamese textile operators most price-constrained. Cost compression in economy-tier proximity switches is intensifying because pneumatic interlocks retain cost advantage in low-speed machinery.
Supply Chain Analysis
Workforce availability constraints in Thailand and Vietnam limit certified safety engineering capacity, forcing supply chain reliance on Singapore and Bangkok-based TÜV Rheinland verification services. Manufacturing concentrates in Germany, Japan, and China, with solid-state photoelectric arrays and force-guided relay contacts as critical component inputs. Single-source vulnerability runs through Taiwanese automotive-grade microcontroller foundries. Distribution runs through system integrator partnerships bundling hardware with maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN safety sensors and switches constitute a late-cycle quality story as Japanese OEM specifications harden toward SIL 2/3 architectures, elevating premium-tier suppliers while marginalizing uncertified competitors.
For Market Incumbents: Acquire certified safety engineering talent pools in Singapore and Bangkok to defend against Vietnamese system integrator capacity constraints. Deepen backward integration into solid-state photoelectric array production to offset Taiwanese foundry allocation risks. Lock channel control through five-year maintenance contract bundling at Thailand's Eastern Economic Corridor petrochemical complexes. For New Entrants and Emerging Players: Enter via wireless retrofit specialization targeting aging Malaysian manufacturing parks in Penang and Johor where cable elimination drives procurement urgency. Capture white-space in Myanmar's Yangon special economic zones lacking established safety infrastructure. Lead with battery-free energy harvesting switches and IO-Link digital architectures to bypass certified engineer scarcity. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with certified safety engineering capabilities because functional safety verification scarcity concentrates margin capture in service-heavy business models. Five-to-ten year viability favors acquisition targets with pre-certified product portfolios and established Thai or Indonesian automotive OEM relationships. Monitor divergence between Malaysia's DOSH accreditation timelines and Singapore's outcome-based compliance frameworks as regulatory fragmentation inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| IO-Link Digital Architecture Deployment | Enables remote parameterization at remote Indonesian installations where certified engineers remain scarce. |
| Wireless Safety Portfolio Extension | Captures retrofit demand in Malaysian food-processing parks where aging cable infrastructure blocks conduit runs. |
| Certified Safety Engineering Acquisition | Addresses TÜV Rheinland engineer concentration in Singapore and Bangkok constraining Vietnamese integrator capacity. |
| Predictive Maintenance Integration | Aligns with Singapore's Workplace Safety and Health Council rewards for sensor data feeds into condition-monitoring platforms. |
| Myanmar First-Mover Positioning | Establishes wireless safety system presence in Yangon special economic zones before infrastructure standardization. |
Study Parameters
Coverage spans Thailand, Vietnam, Indonesia, Malaysia, and Singapore, with primary inputs from each combining interviews with plant engineers, OEM procurement teams, system integrators, and aftermarket service heads alongside secondary validation through IEC certification databases, ASEAN trade customs records, and national Factory Act regulatory filings. Bottom-up unit demand estimates triangulate against top-down industrial automation capex flows.
Granularity-level modeling disaggregates volume and value across product type, end-use industry, technology architecture, and application criticality, with additional dimensioning by national regulatory compliance tier. CAGRs derive from fitted growth curves incorporating Japanese OEM specification timelines, Factory Act amendment implementation schedules, and wireless retrofit penetration rates across aging manufacturing infrastructure.
Inputs from regulatory certification bodies and automotive OEM technical specifications were available through the study window; gaps in real-time Vietnamese and Myanmar factory automation deployment data introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions regarding ASEAN Economic Community harmonization progress and semiconductor input allocation stability. Material deviation in Taiwanese foundry capacity allocation or national safety standard implementation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Pressure Monitoring Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Area Sensor Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Infrared Gas Sensor Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
Millimeter Wave Sensors Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Global Tilt Sensor Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Middle East Robotic Sensors Market