
 Impedance Tester Market | 2026-2036
Impedance Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Impedance Tester Market Foresight
Equipment leasing and project finance is narrowing the competitive field for precision test instrument procurement. Keysight Technologies leverages its R&D intensity across high-frequency measurement architectures. Hioki E.E. Corporation anchors its position through geographic dominance in Asian calibration networks. Wayne Kerr Electronics specializes in bench-top configurations for component analysis workflows.
An impedance tester measures opposition to alternating current flow across a frequency spectrum, typically operating from millihertz to gigahertz ranges to characterize resistive, capacitive, and inductive properties of electronic components and materials. Manufacturers deploy these instruments for pass-fail quality control, failure analysis, and material validation in production environments. Digital product types lead volume shipments due to automation integration demands, while handheld units represent the fastest-growing configuration for field service applications. Frequency response analysis technology commands premium positioning where precision in electrochemical impedance spectroscopy determines battery safety certifications.
FDA oversight of medical device electromagnetic compatibility, FCC equipment authorization rules for RF-emitting test instruments, and ISO 17025 laboratory accreditation standards collectively shape product development roadmaps and market access requirements. CE marking under the EU's electromagnetic compatibility directive constrains design architectures for European-bound shipments. Stakeholders must monitor evolving battery safety test mandates across automotive and energy storage verticals to align R&D priorities with compliance trajectories.
Market Dynamics
Battery safety mandates in Germany and South Korea are compressing test cycle timelines, forcing manufacturers to integrate impedance spectroscopy into inline production monitoring rather than offline sampling protocols.
Growth Catalysts
- EU Battery Regulation:Mandatory electrochemical impedance testing for EV cell certification creates dedicated demand for high-precision instruments in European automotive supply chains.
- Silicon carbide power electronics:Wide-bandgap semiconductor qualification protocols require expanded frequency range characterization, extending tester utilization into new component categories.
- Shenzhen electronics cluster:Concentrated procurement from contract manufacturers serving global OEMs generates volume demand for automated test configurations.
Market Restraints
- Precision oscillator components:Dependence on specialized crystal suppliers in Taiwan and Japan exposes instrument makers to lead time volatility and input cost pressure.
- ISO 17025 calibration infrastructure:Sparse accredited laboratories in Southeast Asia and Latin America extend service intervals and raise total cost of ownership for distributed operations.
- Bench-top form factor saturation:Mature replacement cycles in established electronics manufacturing regions limit organic expansion opportunities.
Strategic Opportunities
- India PLI scheme for electronics:Contract manufacturing incentives under the Production Linked Incentive program attract greenfield test equipment deployment for smartphone and component exports.
- Grid-scale battery storage:Utility-scale energy installations require field-portable impedance diagnostics for warranty validation and predictive maintenance protocols.
- 5G millimeter-wave materials:Dielectric characterization for antenna substrates and RF laminates opens adjacent application space beyond traditional component testing.
Industry Challenges
- RF calibration technician scarcity:Specialized expertise in high-frequency measurement uncertainty analysis constrains service network expansion and extends commissioning timelines.
- Multi-standard compliance stacking:Simultaneous CE marking, FCC authorization, and Korea's KC certification for a single product variant fragments engineering resources and delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impedance Tester Market |
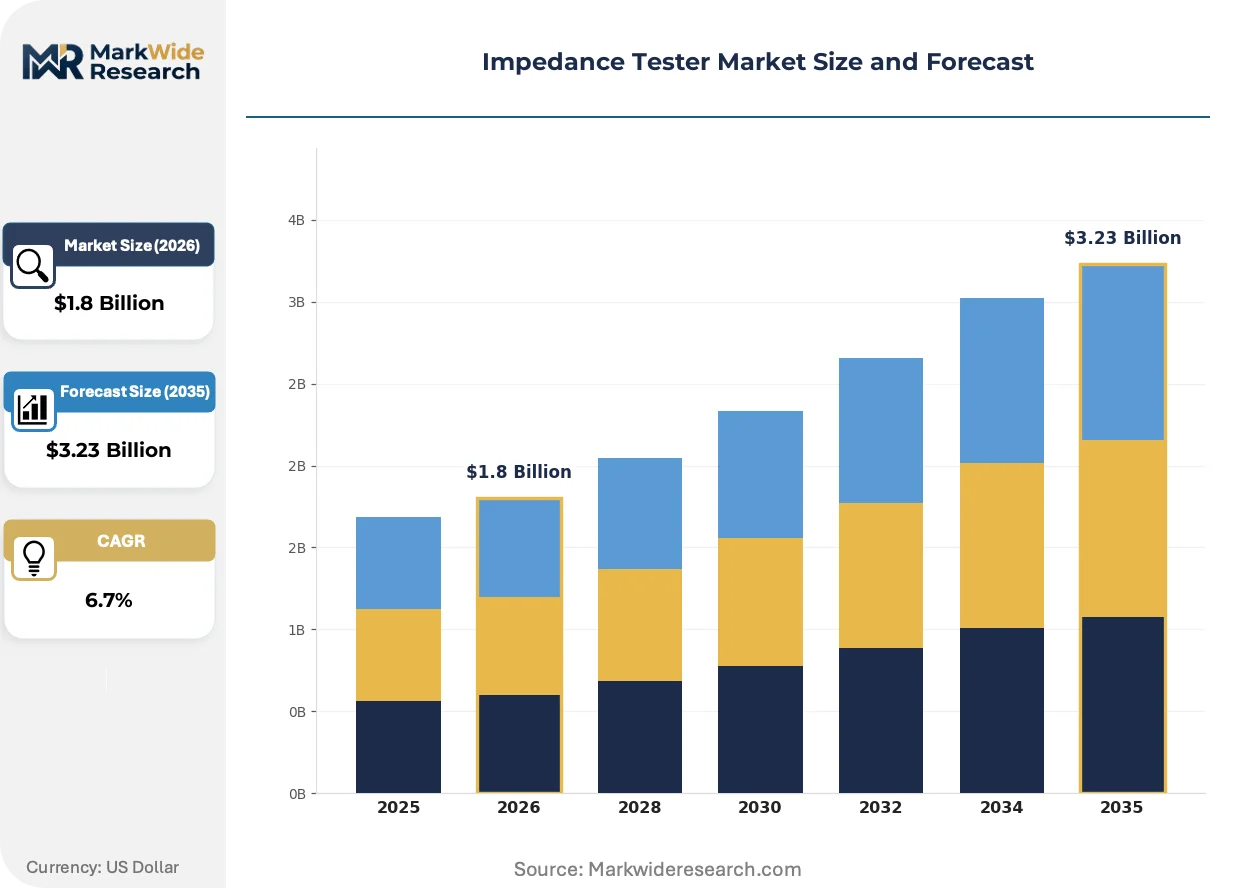
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Analog, Handheld, Bench-Top End User: Manufacturers, Laboratories, Research Institutes, Educational Institutions Application: Electronics Testing, Component Analysis, Quality Control, Material Characterization Technology: Capacitance Measurement, Conductance Measurement, Resistance Measurement, Frequency Response Analysis |
| Companies Covered | Keysight Technologies, Hioki E.E. Corporation, Wayne Kerr Electronics, Chroma ATE Inc., B&K Precision, Fluke Corporation, Good Will Instrument, Nf Corporation, Zurich Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impedance Tester Market Shifts & Advancements
Test instrumentation architectures are converging around software-defined measurement platforms that decouple hardware acquisition from analysis algorithms, enabling faster protocol updates without hardware replacement.
Software-defined radio architectures are digitizing impedance measurement front-ends, replacing analog heterodyne stages with direct digital synthesis and FPGA-based signal processing. Automotive battery engineers in Stuttgart and Ulsan are adopting these platforms for real-time quality gates. This compression of hardware complexity is digitizing margin structures away from precision analog components toward embedded software licensing.
REACH substance restrictions on lead-bearing solders and cadmium-plated hardware are forcing redesigns of test fixture materials and probe assemblies. The regulation's downstream scope extension to professional equipment categories catches impedance tester manufacturers in compliance sweeps previously focused on consumer electronics. European-bound instrument lines now specify RoHS-Exempt-free construction, adding material qualification overhead but creating differentiation against non-compliant competitors.
Equipment-as-a-service contracting is displacing capital purchase models among mid-tier contract manufacturers managing cash flow volatility. Third-party test houses in Shenzhen and Penang are unbundling instrument ownership from measurement access, charging per-test fees that align costs with production volume fluctuations. This financial engineering is most visible among EMS providers serving volatile consumer electronics programs where capacity utilization swings unpredictably.
Impedance Tester Market Segmentation
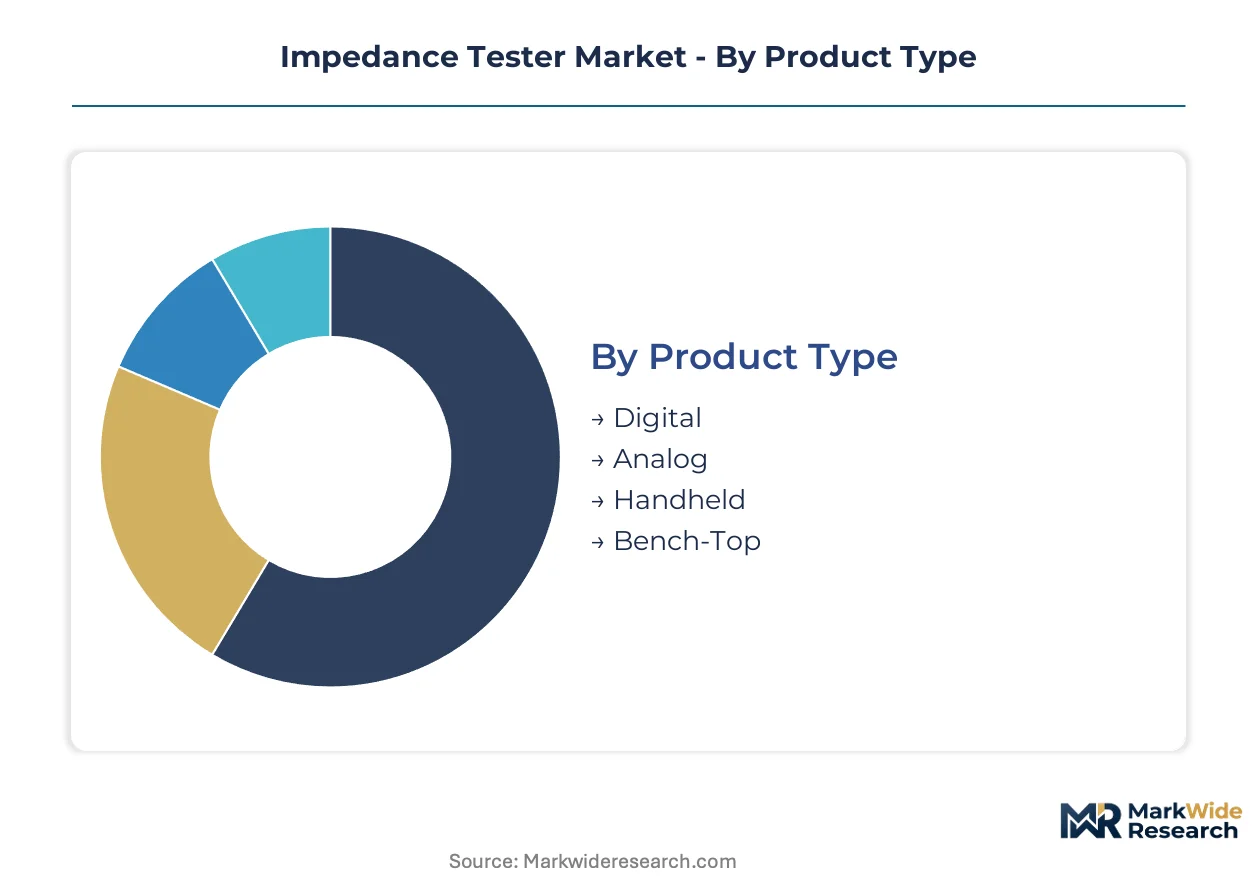
Impedance tester procurement patterns diverge sharply across product configurations and end-use contexts. Understanding these segment boundaries clarifies why digital architectures dominate automated production lines while handheld units penetrate field service applications.
Product Type:
Mature bench-top configurations anchor established electronics manufacturing workflows, while emerging handheld formats address mobility requirements in distributed battery maintenance.
- Digital:Software-defined architectures integrate with MES platforms for automated pass-fail sorting in high-volume production environments. Demand concentrates in Shenzhen contract manufacturers serving automotive OEMs, driven by CE marking compliance for European-bound battery shipments.
- Handheld:Battery-powered portable units with simplified interfaces target field technicians performing warranty validation on grid-scale storage installations. Procurement from South Korean EV service networks accelerates fastest under tightened national safety inspection mandates.
- Analog:Traditional swept-frequency designs persist in legacy calibration laboratories with established uncertainty budgets.
- Bench-Top:Full-featured laboratory instruments with precision oscillators dominate component characterization workflows in German automotive supplier labs.
Digital configurations handle the majority of throughput; handheld is the fastest mover on share.
End User:
Cost tier stratification separates capital-intensive manufacturing deployments from budget-constrained educational procurement.
- Manufacturers:Inline production monitoring systems with automated handling robotics characterize high-volume electronics assembly in Penang and Dongguan. German battery cell plants drive specification tightening for electrochemical impedance spectroscopy under EU Battery Regulation compliance deadlines.
- Laboratories:ISO 17025-accredited facilities in Stuttgart and Ulsan require traceable calibration chains and extended frequency ranges for silicon carbide qualification protocols.
- Research Institutes:Custom-configured systems support dielectric characterization for 5G millimeter-wave substrate development.
- Educational Institutions:Entry-level units with simplified software interfaces serve undergraduate electronics laboratories in Indian technical institutes under PLI scheme workforce development programs.
Manufacturers absorb the largest equipment budgets; laboratories command the steepest specification requirements.
Application:
Volume concentration in quality control workflows contrasts with margin-rich material characterization for advanced semiconductor substrates.
- Quality Control:Automated sorting stations with sub-milliohm resolution separate conforming from non-conforming battery cells at production speeds exceeding 100 units per minute. South Korean cathode material suppliers deploy these systems under MFDS-mandated safety verification protocols.
- Material Characterization:Broadband dielectric spectroscopy identifies moisture ingress and ionic contamination in antenna substrates for 5G base station deployments. German RF laminate manufacturers in Bavaria drive specification evolution toward 110 GHz characterization ranges.
- Electronics Testing:General-purpose validation covers passive component screening across consumer electronics supply chains.
- Component Analysis:Detailed equivalent circuit modeling supports failure analysis in warranty return investigations.
Quality control commands the highest unit volumes; material characterization expands most quickly on specification intensity.
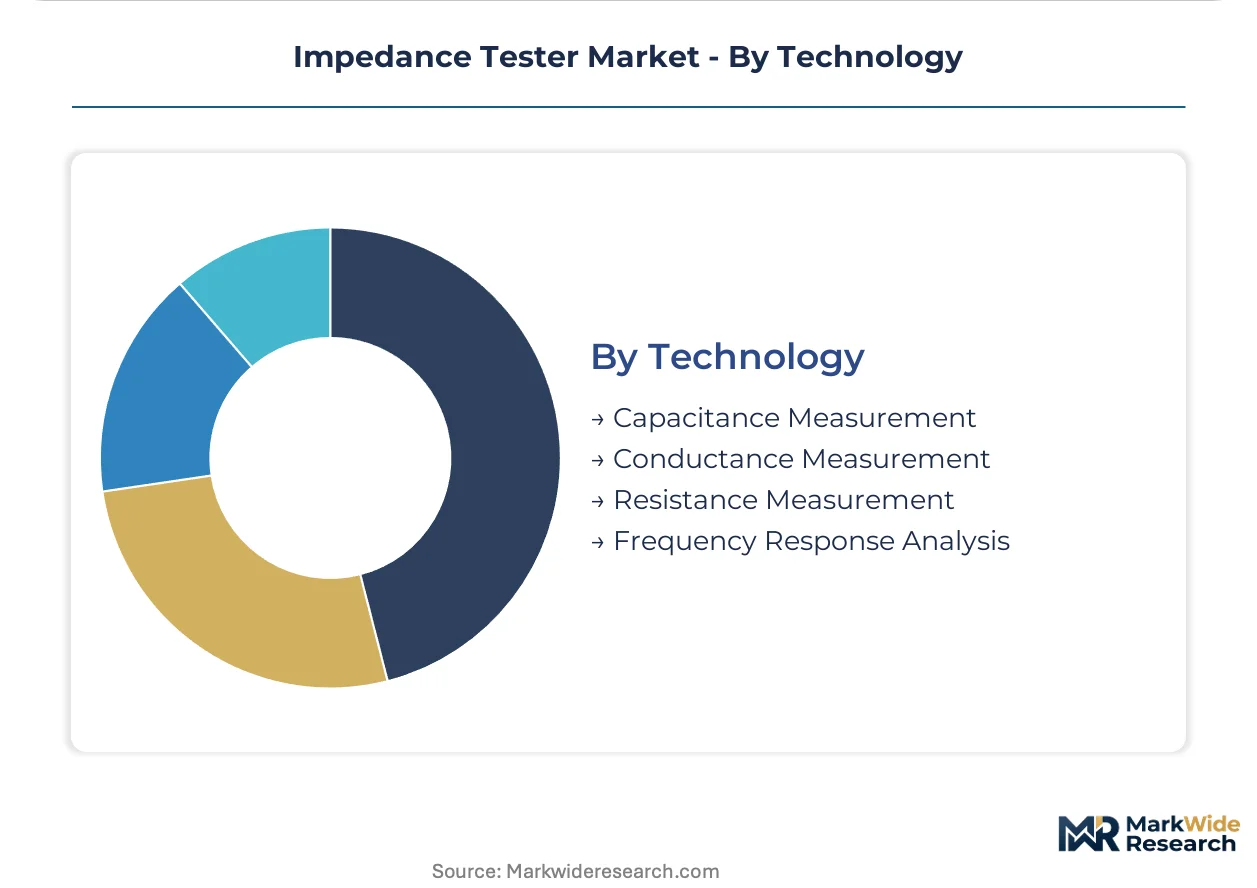
Technology:
Customer type differentiation separates precision metrology laboratories from production-floor technicians requiring simplified operation.
- Frequency Response Analysis:Electrochemical impedance spectroscopy with 0.1% amplitude accuracy and 0.1 degree phase resolution enables battery safety certification under EU Battery Regulation Article 14. Stuttgart automotive labs and Ulsan cell manufacturers standardize on these platforms for regulatory submission packages.
- Capacitance Measurement:Automated balancing bridges achieve femtofarad resolution for MEMS sensor validation in Japanese consumer electronics supply chains.
- Resistance Measurement:Four-wire Kelvin configurations eliminate lead resistance errors in milliohm-range battery tab welding quality verification.
- Conductance Measurement:Battery state-of-health estimation algorithms translate conductance readings into remaining capacity predictions for utility-scale storage maintenance contracts.
Frequency response analysis carries the premium positioning; conductance measurement is gaining share fastest in field service applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led manufacturing clusters in Asia-Pacific and Europe generate concentrated instrument demand, while import-dependent calibration networks in emerging economies extend service intervals and raise operational costs for distributed battery maintenance operations.
Germany
Automotive battery cell plants in Stuttgart and Bavaria drive specification tightening for electrochemical impedance spectroscopy under EU Battery Regulation compliance deadlines. CE marking requirements under the EU's electromagnetic compatibility directive constrain design architectures for European-bound shipments. The Baden-Württemberg supplier ecosystem concentrates procurement from ISO 17025-accredited laboratories requiring traceable calibration chains for silicon carbide qualification protocols.
South Korea
Ulsan-based EV manufacturers and Seoul Capital Area cathode material suppliers deploy inline quality control systems under MFDS-mandated safety verification protocols. National battery safety inspection mandates compress test cycle timelines and accelerate handheld unit procurement for field service networks. The Busan-Ulsan industrial corridor anchors domestic demand for frequency response analysis platforms serving regulatory submission packages.
China
Shenzhen's contract manufacturing cluster generates volume demand for automated test configurations serving global OEMs. MIIT standards for wide-bandgap semiconductor qualification extend tester utilization into new component categories across the Pearl River Delta. The Yangtze River Delta battery production base concentrates procurement for electrochemical impedance spectroscopy equipment under tightened export certification requirements.
United States
FCC equipment authorization rules for RF-emitting test instruments shape product development roadmaps for domestic-bound shipments. FDA oversight of medical device electromagnetic compatibility creates parallel compliance requirements for diagnostic equipment manufacturers. The Pacific Northwest and Greater Boston research corridors drive custom-configured system demand for dielectric characterization in 5G millimeter-wave substrate development.
India
PLI scheme incentives for electronics contract manufacturing attract greenfield test equipment deployment for smartphone and component exports. BIS standards alignment with international accreditation frameworks shapes procurement specifications for ISO 17025 laboratory infrastructure. Karnataka and Tamil Nadu technical institutes under workforce development programs generate entry-level unit demand for undergraduate electronics laboratories.
Impedance Tester Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in precision oscillator and probe assembly supply chains. The vendor base stratifies across three tiers: multinational measurement platforms with software-defined architectures, regional calibration service providers with geographic density advantages, and specialized bench-top fabricators serving legacy laboratory workflows. Consolidation pressure concentrates among mid-tier players lacking R&D scale to fund FPGA-based signal processing transitions. Dominant competitive moves include equipment-as-a-service contracting displacing capital purchases, and strategic partnerships with third-party test houses unbundling instrument ownership from measurement access.
Among precision measurement specialists, Keysight Technologies and Hioki E.E. Corporation exemplify platform-tier positioning through R&D intensity across high-frequency measurement architectures and geographic dominance in Asian calibration networks respectively. Wayne Kerr Electronics occupies a position within the bench-top specialization tier, serving component analysis workflows in established electronics manufacturing regions. These three anchors illustrate how competitive positioning diverges between software-defined platform strategies and precision analog legacy preservation.
| Leading Market Players |
|---|
| Keysight Technologies |
| Hioki E.E. Corporation |
| Wayne Kerr Electronics |
| Chroma ATE Inc. |
| B&K Precision |
| Fluke Corporation |
| Good Will Instrument |
| Nf Corporation |
| Zurich Instruments |
| Others |
Supply & Pricing Matrix
The Shenzhen-Penang maritime corridor carries precision oscillator components from Taiwan and Japan to contract manufacturers, with freight cost volatility amplifying price differentiation between automated production-line systems and handheld field-service units. This logistics backbone concentrates supply-side leverage among crystal suppliers while forcing downstream equipment makers to absorb margin compression or pass through to battery cell manufacturers in Germany and South Korea.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by ISO 17025 calibration certification and FPGA-based signal processing capability. Price erosion runs through the economy tier as Shenzhen contract manufacturers consolidate procurement volumes, while premium frequency response analysis platforms maintain pricing power through EU Battery Regulation compliance bundling. Academic and research institutes exhibit highest price sensitivity; automotive battery plants in Stuttgart and Ulsan show lowest sensitivity due to regulatory mandate rigidity.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier-financing arrangements between Taiwanese crystal oscillator manufacturers and Japanese probe assembly specialists, straining working capital for mid-tier instrument fabricators. Component sourcing draws from Taiwan, Japan, and Germany, with precision ADCs and FPGA modules resting on single-source vulnerability at 7nm process nodes. Distribution runs through direct OEM relationships for high-volume automated configurations, while third-party test houses in Shenzhen and Penang intermediate handheld unit access through equipment-as-a-service contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined measurement platforms are reshaping competitive economics around embedded software licensing rather than precision analog hardware, with interoperability across MES platforms becoming the decisive ecosystem battleground.
For Market Incumbents: Build calibration network density as the defensive moat, extending ISO 17025-accredited service points into India's PLI scheme manufacturing zones and Southeast Asian battery maintenance corridors. Acquire FPGA firmware specialists to accelerate software-defined transitions before mid-tier competitors consolidate. The threat of equipment-as-a-service unbundling demands channel control through captive financing arms.
For New Entrants and Emerging Players: India's nascent electronics manufacturing clusters present the most penetrable white space, with Karnataka and Tamil Nadu technical institutes generating entry-level unit demand under workforce development programs. Target grid-scale battery storage field service through portable conductance measurement platforms, leveraging South Korea's MFDS-mandated inspection timelines as the regulatory wedge. Partner with third-party test houses for per-test revenue sharing rather than capital sales.
For Investors and Strategic Acquirers: Regional calibration service providers with geographic density in Asian manufacturing corridors represent the priority acquisition archetype, capturing recurring revenue streams detached from hardware replacement cycles. Long-term viability hinges on software licensing attach rates rather than instrument shipment volumes. Watch for inflection when equipment-as-a-service contracts exceed 30% of industry revenue mix.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | ISO 17025 accreditation in India and Southeast Asia compresses service intervals for distributed battery operations. |
| Software-Defined Platform Migration | FPGA-based architectures decouple hardware from analysis algorithms, enabling faster EU Battery Regulation protocol updates. |
| Equipment-as-a-Service Contracting | Per-test fee structures align costs with production volume fluctuations for Shenzhen contract manufacturers. |
| Strategic Partnership with Test Houses | Third-party unbundling of instrument ownership from measurement access penetrates mid-tier EMS providers. |
| Backward Integration into Precision Oscillators | In-house crystal sourcing mitigates Taiwan and Japan supplier lead time volatility for high-frequency architectures. |
Research Methodology
Cross-validation between primary interviews with test equipment procurement managers, battery cell plant quality directors, and calibration laboratory technical leads anchors the qualitative findings, supplemented by secondary validation against MIIT semiconductor qualification filings, EU Battery Regulation compliance submissions, and FCC equipment authorization databases. Bottom-up shipment data from Shenzhen contract manufacturers triangulates against top-down instrumentation spend estimates from German automotive supplier associations.
Calibration against historical CAGRs from adjacent precision measurement instrument categories informs the projection framework across the analysis window. Segmentation dimensions modeled include product configuration, end-user vertical, application workflow, and measurement technology tier. Forecast inputs incorporate battery safety mandate implementation timelines in Germany and South Korea, plus silicon carbide qualification protocol adoption rates in wide-bandgap semiconductor supply chains.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or battery cell manufacturing capacity buildouts would shift the trajectory. Forecasts reflect documented assumptions around regulatory compliance deadlines and technology transition rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Transformer Testing Equipment Market
Test and Measurement
Video Measuring System Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
E-Axle and Inverter Efficiency and Reliability Test Platforms Market
Test and Measurement
Digital Height Gauges Market
Test and Measurement
Surface Inspection Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Shock Data Logger Market
Test and Measurement
State Transition Testing Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Latin America Measurement and Test Equipment Market
Test and Measurement
Industrial Metrology Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market