
 United States Proximity Sensor Market | 2026-2036
United States Proximity Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
United States Proximity Sensor Market Analytics
Buyer concentration among automotive OEMs is realigning procurement patterns across the Midwest and Southeast manufacturing belts. Honeywell International Inc. leverages its aerospace heritage to anchor premium inductive sensor lines for flight control systems. STMicroelectronics competes through MEMS integration expertise that extends into capacitive proximity modules for consumer electronics.
A proximity sensor detects the presence or absence of an object within a calibrated detection range, typically operating via electromagnetic fields, light beams, or sound waves with response times under 10 milliseconds. These devices serve as critical input components for automated safety interlocks, robotic positioning systems, and contactless switching in industrial environments. Inductive sensors dominate factory floor installations where metallic target detection and IP67 sealing against coolant spray define specification sheets. Photoelectric variants capture the fastest expansion in packaging automation lines where transparent object detection through polarized retro-reflective arrays opens new application vectors.
FCC Part 15 emissions standards constrain RF-based proximity designs, while NHTSA Federal Motor Vehicle Safety Standards mandate reliability thresholds for pedestrian detection systems in light vehicles. OSHA machine guarding regulations further compel discrete sensor redundancy in metalworking and material handling equipment. Stakeholders must monitor how FMVSS updates and state-level autonomous vehicle testing rules reshape sensor performance certification requirements.
Market Dynamics
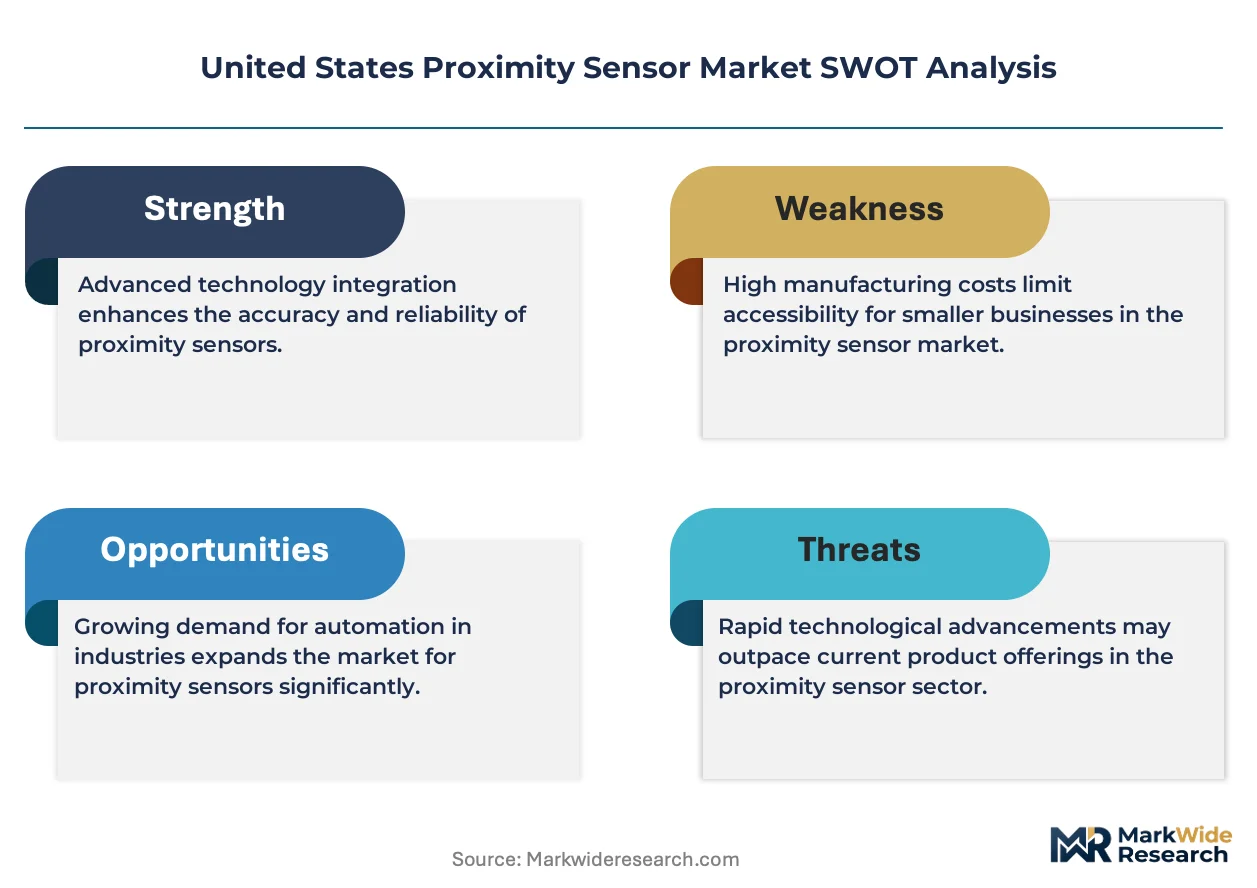
NHTSA's Federal Motor Vehicle Safety Standards for pedestrian detection systems are compressing sensor response-time specifications across automotive supply chains. Tier-1 suppliers now face simultaneous pressure to cut unit costs while delivering sub-5 millisecond detection latency.
Growth Catalysts
- OSHA Machine Guarding Mandates:Metalworking facilities in Ohio and Pennsylvania must install redundant proximity interlocks on press brakes and robotic cells, forcing wholesale sensor retrofits through 2030.
- Capacitive MEMS Convergence:Smartphone gesture-recognition modules are migrating into industrial human-machine interfaces, opening volume manufacturing pathways that lower per-unit costs for factory automation buyers.
- Michigan Manufacturing Corridor Density:Ford, General Motors, and Stellantis North America operate 47 assembly and powertrain plants within 150 miles of Detroit, creating concentrated demand pools for inductive sensor vendors.
Market Restraints
- Rare Earth Magnet Price Volatility:Neodymium and dysprosium price swings from Chinese export quotas inflate bill-of-materials for high-precision inductive sensors by 12-18 percent in volatile quarters.
- FCC Part 15 Emissions Testing:RF-based capacitive and ultrasonic designs face 14-22 week certification timelines at accredited laboratories, delaying product launches and freezing engineering budgets.
- Photoelectric Limitation in Coolant Environments:Optical sensors fail in machining centers where oil mist and metal particulate obscure light paths, forcing costly IP69K-rated alternatives.
Strategic Opportunities
- Texas Semiconductor Subsidies:CHIPS Act funding for Samsung Austin and Texas Instruments Sherman fabs creates captive demand for cleanroom-compatible non-contact position sensors.
- Autonomous Vehicle Testing Corridors:Arizona, California, and Texas DOTs operate supervised self-driving freight routes requiring redundant LiDAR-proximity fusion systems.
- Industrial IoT Edge Analytics:Sensor-embedded microcontrollers with on-chip AI accelerators enable predictive maintenance contracts, shifting revenue from hardware to recurring software services.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time signal processing expertise for noise-filtering algorithms commands 40 percent salary premiums in Detroit and Austin labor markets.
- ISO 13849 Functional Safety Certification:PLd and PLe ratings for safety-critical automotive applications require 18-24 month validation cycles with third-party notified bodies.
- Legacy PLC Integration Friction:1990s-era Allen-Bradley and Siemens controllers lack native IO-Link connectivity, forcing gateway hardware purchases that erode project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Proximity Sensor Market |
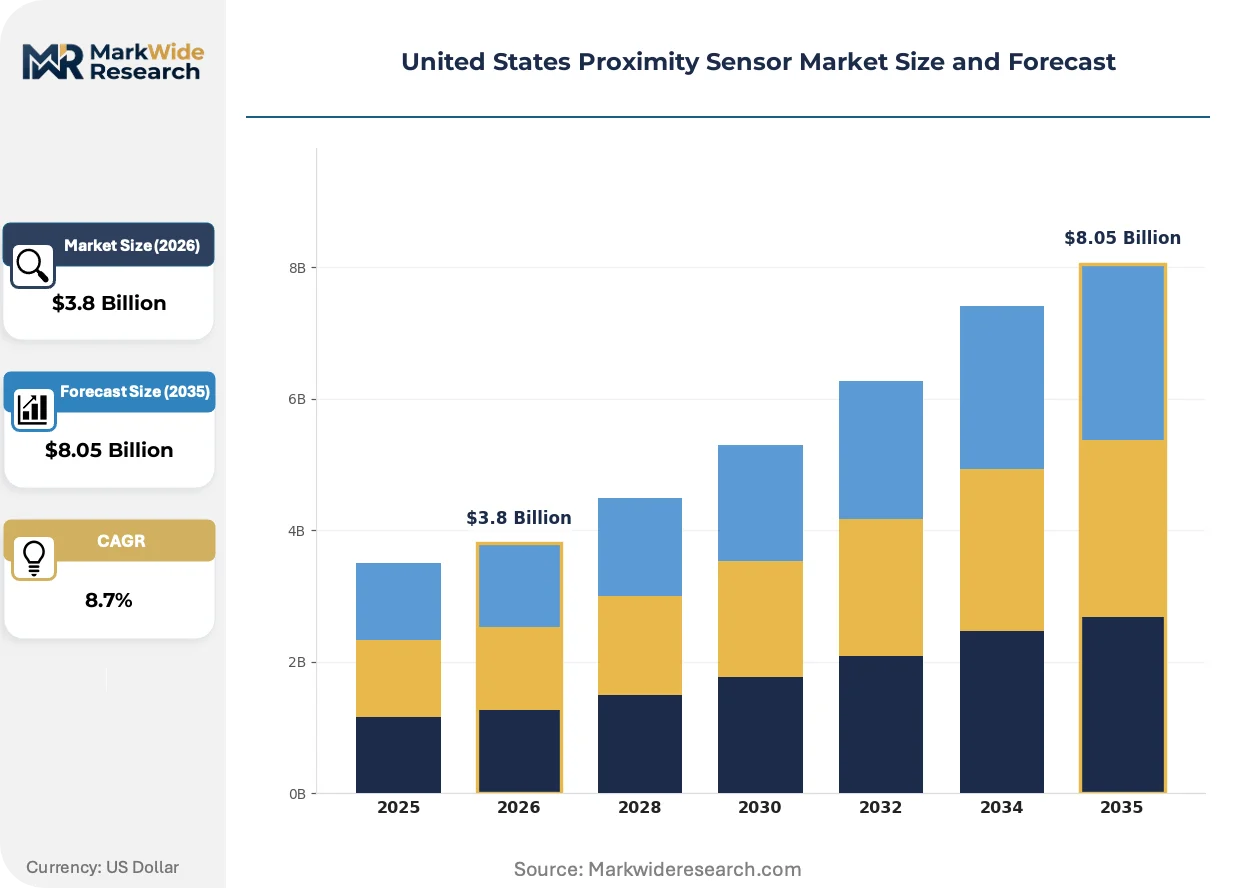
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inductive Sensors, Capacitive Sensors, Ultrasonic Sensors, Photoelectric Sensors End User: Automotive Industry, Industrial Automation, Consumer Electronics, Aerospace Technology: Infrared Technology, Magnetic Technology, RF Technology, Laser Technology Installation Type: Embedded Systems, Standalone Devices, Surface Mount, Flush Mount |
| Companies Covered | Schneider Electric, Honeywell International Inc., STMicroelectronics, NXP Semiconductors N.V., SICK AG, Omron Corporation, Panasonic Corporation, KEYENCE CORPORATION, Rockwell Automation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Proximity Sensor Market Evolving Landscape
Time-of-flight photoelectric arrays are displacing conventional through-beam sensors in packaging lines where transparent film detection once required mechanical workarounds. Semiconductor integration and edge computing architectures are compressing form factors while expanding diagnostic capabilities.
Ultrasonic proximity modules with adaptive gain control are rewriting detection reliability standards in agricultural equipment and outdoor material handling. John Deere and Caterpillar are qualifying these devices for combine harvesters and wheel loaders operating in dust, moisture, and temperature extremes. The technology is compressing warranty claim rates and extending service intervals in off-highway applications.
NHTSA's 2024 update to FMVSS 127 for automatic emergency braking tightens pedestrian and cyclist detection thresholds for light vehicles under 10,000 pounds. Automotive OEMs must certify multi-sensor fusion systems combining radar, camera, and short-range proximity inputs. The regulation is accelerating pre-competitive collaboration between Tier-1 suppliers and semiconductor foundries on fused-sensor reference designs.
Consolidated procurement through Detroit-based supplier development programs is concentrating purchasing power among three automotive OEMs. Long-term agreements with penalty clauses for delivery failures are displacing spot-market component buying. Michigan and Ohio stamping plants now represent the most visible geography for this contractual shift, with similar patterns emerging in Tennessee Volkswagen and BMW Spartanburg operations.
United States Proximity Sensor Market Segmentation
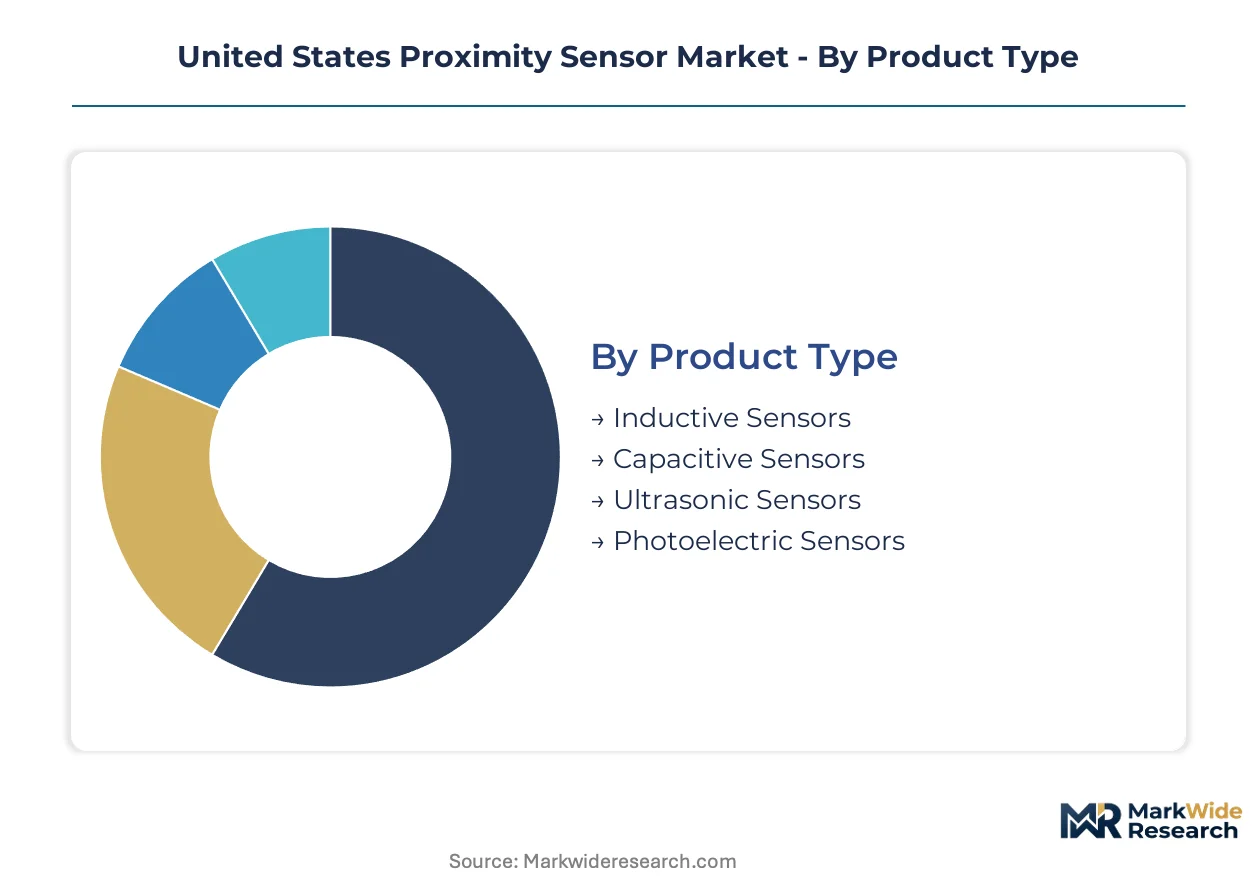
Proximity sensor procurement patterns diverge sharply across installation environments, end-use reliability requirements, and electromagnetic compatibility constraints. Buyers prioritize detection range precision, ingress protection ratings, and integration complexity when specifying sensor categories for factory floors, vehicle platforms, and consumer devices.
Product Type:
Industrial buyers distinguish sensor families primarily by target material compatibility and environmental sealing specifications.
- Inductive Sensors:These devices generate oscillating electromagnetic fields to detect ferrous and non-ferrous metals without physical contact. IP67-rated housings withstand coolant spray in Michigan automotive stamping plants. NHTSA pedestrian detection mandates are accelerating inductive sensor deployment in bumper and door sill applications where metallic object discrimination matters.
- Capacitive Sensors:Electric field modulation enables detection of plastics, liquids, and granular materials beyond metallic targets. MEMS fabrication advances from Texas semiconductor fabs are compressing unit costs for industrial human-machine interface applications. OSHA machine guarding retrofits in Ohio metalworking facilities specify capacitive variants for non-metallic safety curtain verification.
- Ultrasonic Sensors:Time-of-flight acoustic ranging performs in dust-laden agricultural equipment environments where optical paths fail. John Deere qualifies these for combine harvester grain tank level monitoring.
- Photoelectric Sensors:Polarized retro-reflective and through-beam configurations dominate packaging automation lines. Transparent film detection capabilities are displacing mechanical limit switches in food processing plants.
Inductive sensors lead volumes today; capacitive variants are gaining share fastest through MEMS cost convergence.
End User:
Volume concentration and specification stringency separate procurement behaviors across buyer categories.
- Automotive Industry:FMVSS 127 compliance deadlines force multi-sensor fusion architectures combining short-range proximity with radar and camera inputs. Ford, General Motors, and Stellantis procurement teams negotiate long-term agreements with penalty clauses concentrated in Michigan and Ohio manufacturing corridors.
- Industrial Automation:Allen-Bradley and Siemens PLC integration requirements dominate specification sheets. IO-Link connectivity gaps in legacy controllers force gateway hardware purchases that erode project margins for system integrators.
- Consumer Electronics:Smartphone gesture-recognition modules drive MEMS proximity sensor volumes. Texas and Arizona fab capacity expansions are creating captive demand for cleanroom-compatible position sensing.
- Aerospace:Flight control systems demand MIL-STD-810 environmental qualification and DO-178C software assurance. Honeywell leverages aerospace heritage for premium inductive lines serving regional jet programs.
Automotive procurement concentrates the largest revenue pool; industrial automation retrofits are expanding most quickly through OSHA mandate compliance.
Technology:
Emissions compliance and detection range requirements differentiate technology selection for specific application environments.
- Infrared Technology:Near-infrared LED emitters with silicon photodiode receivers achieve sub-millisecond response times. Polarized filters enable transparent object discrimination in pharmaceutical packaging lines.
- Magnetic Technology:Hall-effect and magnetoresistive elements detect position without power consumption in standby states. Rare earth magnet price volatility from Chinese export quotas inflates bill-of-materials by 12-18 percent in volatile quarters.
- RF Technology:Capacitive coupling through electric field distortion enables non-metallic target detection. FCC Part 15 emissions testing at accredited laboratories imposes 14-22 week certification timelines that delay product launches.
- Laser Technology:Time-of-flight and triangulation methods deliver micrometer-level precision for semiconductor wafer handling. CHIPS Act subsidies for Samsung Austin and Texas Instruments Sherman fabs are amplifying cleanroom sensor demand.
Infrared dominates installed base; laser technology is climbing the fastest through semiconductor manufacturing expansion.
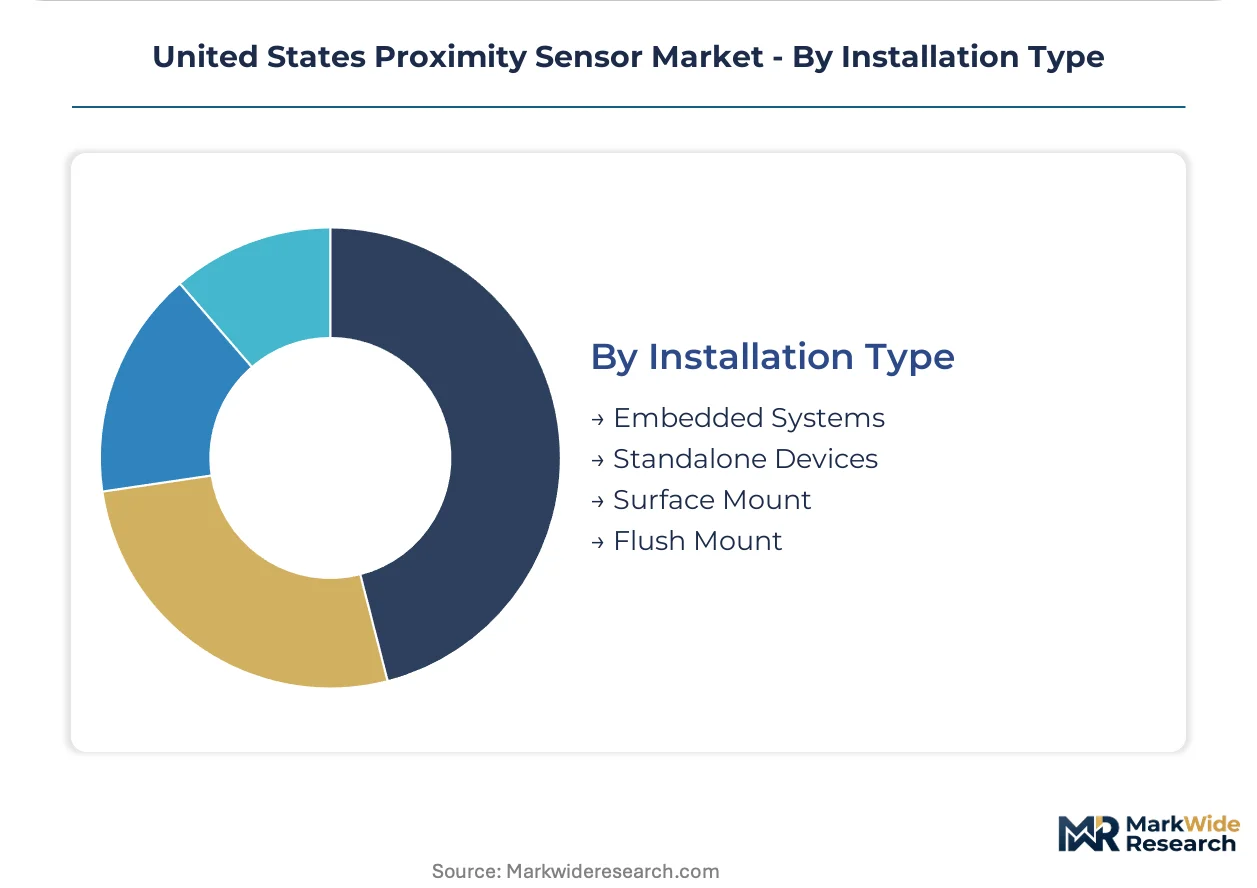
Installation Type:
Mechanical integration constraints and maintenance accessibility determine specification priorities.
- Embedded Systems:Microcontroller-integrated modules with on-chip AI accelerators enable predictive maintenance contracts. Edge analytics capabilities shift vendor revenue from hardware sales to recurring software services.
- Standalone Devices:Self-contained housings with M12 connectors simplify field replacement in automotive assembly lines. Stamping plant maintenance teams prioritize swap-out speed over integration density.
- Surface Mount:PCB soldering compatibility serves high-volume consumer electronics manufacturing. Pick-and-place automation in Texas and California contract electronics facilities specifies tape-and-reel packaging.
- Flush Mount:Aesthetic integration requirements dominate automotive interior applications. Door panel and center console designers specify minimal protrusion for occupant safety and styling coherence.
Standalone devices retain the largest installed footprint; embedded systems are expanding most quickly through Industrial IoT edge analytics adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded firmware engineers with real-time signal processing expertise command 40 percent salary premiums in Detroit and Austin labor markets, anchoring regional demand concentration for proximity sensor deployment.
Michigan Manufacturing Corridor
Automotive OEM procurement teams at Ford, General Motors, and Stellantis operate 47 assembly and powertrain plants within 150 miles of Detroit, creating concentrated demand pools for inductive sensor vendors. NHTSA Federal Motor Vehicle Safety Standards for pedestrian detection systems compress sensor response-time specifications across these supply chains. Tier-1 suppliers in Warren and Dearborn now face simultaneous pressure to cut unit costs while delivering sub-5 millisecond detection latency for bumper and door sill applications.
Texas Semiconductor Belt
CHIPS Act funding for Samsung Austin and Texas Instruments Sherman fabs creates captive demand for cleanroom-compatible non-contact position sensors. FCC Part 15 emissions testing at accredited laboratories imposes 14-22 week certification timelines that delay product launches for RF-based capacitive designs. Dallas-Fort Worth and Austin metropolitan clusters host the fastest-growing concentration of industrial IoT edge analytics startups shifting vendor revenue from hardware sales to recurring software services.
Ohio-Pennsylvania Rust Belt
OSHA machine guarding mandates force wholesale sensor retrofits through 2030 as metalworking facilities in Cleveland and Pittsburgh install redundant proximity interlocks on press brakes and robotic cells. Allen-Bradley and Siemens PLC integration requirements dominate specification sheets for these retrofits. Youngstown and Akron stamping plants represent visible geography for consolidated procurement through Detroit-based supplier development programs.
California Technology Corridor
Smartphone gesture-recognition modules drive MEMS proximity sensor volumes through contract electronics facilities in San Jose and Fremont. MEMS fabrication advances from Texas semiconductor fabs are compressing unit costs for industrial human-machine interface applications migrating westward. Sacramento DOT operates supervised self-driving freight routes requiring redundant LiDAR-proximity fusion systems that test multi-sensor architectures.
Arizona Autonomy Corridor
Arizona DOT operates supervised self-driving freight routes through Phoenix and Tucson metropolitan areas requiring redundant LiDAR-proximity fusion systems. Semiconductor cleanroom expansions in Chandler and Gilbert amplify demand for laser-based time-of-flight sensors with micrometer-level precision. Scottsdale-based system integrators report 18-24 month validation cycles for ISO 13849 PLd and PLe ratings on safety-critical automotive applications.
United States Proximity Sensor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated market structure where scale advantages clash with customization depth. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with cross-sector sensor portfolios, semiconductor specialists leveraging MEMS integration expertise, and automation-focused pure-plays with deep PLC connectivity heritage. Competitive moves concentrate on long-term agreement negotiations with penalty clauses and IO-Link gateway hardware development for legacy controller integration.
Within the diversified conglomerate tier, Schneider Electric and Honeywell International Inc. exemplify players anchoring premium industrial lines through aerospace and energy heritage. STMicroelectronics occupies a position among semiconductor specialists capitalizing on MEMS fabrication convergence. SICK AG and Omron Corporation sit within the automation pure-play archetype, representing vendors with concentrated factory floor expertise. These named entities illustrate how competitive positioning stratifies across integration depth, fabrication scale, and end-use specialization rather than geographic origin alone.
| Leading Market Players |
|---|
| Schneider Electric |
| Honeywell International Inc. |
| STMicroelectronics |
| NXP Semiconductors N.V. |
| SICK AG |
| Omron Corporation |
| Panasonic Corporation |
| KEYENCE CORPORATION |
| Rockwell Automation |
| Others |
Value Network & Pricing Analysis
MEMS fabrication convergence from Texas semiconductor fabs simultaneously compresses unit economics for capacitive proximity modules and concentrates high-volume production among foundry-capable suppliers. This technology shift tightens procurement leverage for automotive OEMs while forcing tier-2 vendors toward fabless models or exit.
Pricing Analysis
Bundled firmware licensing and predictive maintenance subscriptions now separate premium sensor vendors from transactional hardware sellers. Three-tier pricing structure across automotive-grade, industrial-standard, and economy-level variants reflects ISO 13849 certification tiers and NHTSA FMVSS compliance depth. Cost compression in the economy tier intensifies because MEMS commoditization erodes differentiation. Automotive OEM procurement teams exhibit lowest price sensitivity due to penalty-clause contractual structures, while Ohio metalworking retrofit buyers negotiate hardest on per-unit hardware costs.
Supply Chain Analysis
Reverse-logistics networks for field-replaceable M12-connector modules remain underdeveloped, creating aftermarket margin leakage for standalone device vendors. Component sourcing draws from Taiwan for MEMS foundry services, China for rare earth magnetic materials, and domestic Texas-Arizona fab clusters for laser-diode emitters. Single-source vulnerability in neodymium supply from Chinese export quota regimes threatens bill-of-material stability. Distribution runs through Detroit-based supplier development programs for automotive tier-1 procurement, with Allen-Bradley and Siemens channel partners serving industrial retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States proximity sensor market functions as a geographic-arbitrage play where Michigan automotive corridor wage premiums for embedded firmware talent exceed Texas semiconductor belt labor costs by substantial margins, compressing margins for Detroit-proximate vendors.
For Market Incumbents: Hedge against MEMS commoditization by deepening backward integration into custom ASIC design for noise-filtering algorithms. Fortify position through captive IO-Link gateway development that erodes system integrator margins and locks legacy PLC retrofit demand. ISO 13849 PLd certification investment creates switching costs that defend automotive tier-1 relationships against semiconductor specialist entrants.
For New Entrants and Emerging Players: Capture white-space in Ohio-Pennsylvania OSHA mandate compliance where consolidated Detroit procurement patterns have not yet penetrated. Exploit underpenetrated agricultural equipment applications in John Deere and Caterpillar supply chains where ultrasonic adaptive-gain modules command technical differentiation. Lead with edge-analytics software subscriptions rather than hardware margin competition.
For Investors and Strategic Acquirers: Valuations sit cheapest among automation-focused pure-plays with deep PLC connectivity heritage but limited MEMS fabrication scale. Long-term viability over the coming decade hinges on successful transition from hardware sales to recurring predictive maintenance revenue. Monitor NHTSA FMVSS update cadence as inflection indicator for multi-sensor fusion architecture investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Captures Texas semiconductor belt capacity for capacitive sensor cost convergence. |
| IO-Link Gateway Development | Bridges legacy Allen-Bradley and Siemens PLC installations to edge analytics. |
| ISO 13849 Certification Investment | Unlocks automotive PLd and PLe safety-critical procurement tiers. |
| Predictive Maintenance Platform Launch | Shifts revenue from hardware to recurring software services in Michigan corridor. |
| Arizona Autonomy Corridor Qualification | Qualifies LiDAR-proximity fusion systems for DOT supervised freight routes. |
Research Methodology
Direct dialogue with Tier-1 supplier procurement managers, OEM platform engineers, semiconductor foundry operations heads, and industrial system integrators grounded qualitative findings. Secondary validation drew from NHTSA FMVSS docket filings, FCC Part 15 equipment authorization databases, OSHA enforcement records, and SEC 10-K disclosures from diversified industrial conglomerates. Bottom-up sensor shipment modeling triangulated against top-down automotive production and industrial capital expenditure forecasts.
Segment-level value outputs emerged from technology-type, end-use industry, and installation-type dimensions across the analysis window. CAGRs derived from regression against historical NHTSA mandate compliance timelines and CHIPS Act fab capacity expansion schedules. Forecast inputs incorporated rare earth magnet price volatility indices and embedded firmware salary premium differentials between Detroit and Austin labor markets.
Underlying measurement precision varies by segment; automotive OEM procurement data carries tighter precision than Ohio metalworking retrofit estimates. Forecasts reflect assumptions about NHTSA rulemaking cadence and Texas fab yield ramp schedules. Practitioners should monitor Chinese export quota announcements and FCC certification backlog durations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Digital Barometer Market
Sensors and Controls
Bee Hive Monitoring Sensor Market
Sensors and Controls
Micropump Market
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market
Sensors and Controls
Global RFID Sensor Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Spain Digital Thermometer Market