
 Frictionless Remote Monitoring Devices Market | 2026-2036
Frictionless Remote Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Frictionless Remote Monitoring Devices Market Foresight
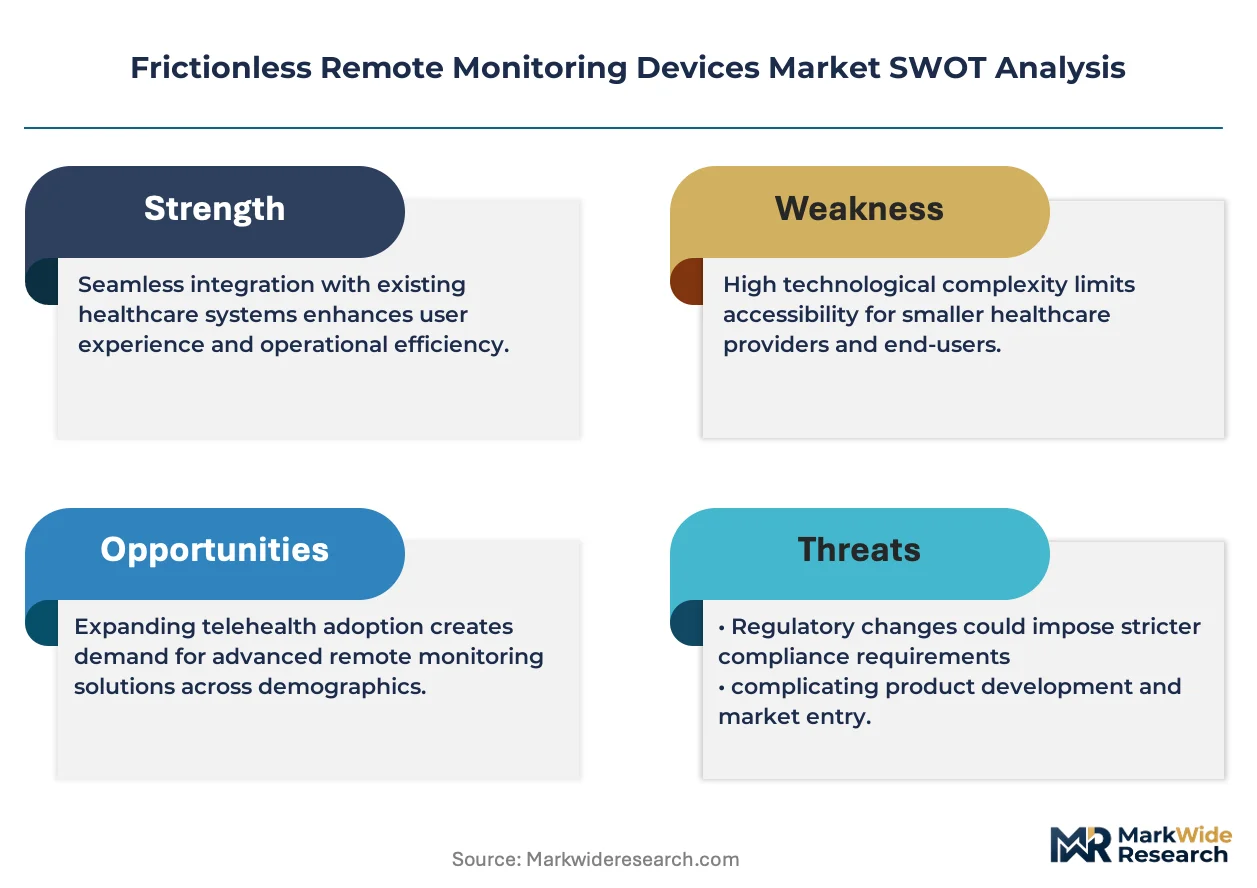
FDA 510(k) clearance pathways for software-as-medical-device are repositioning the cost-of-entry calculus for frictionless monitoring startups. Abbott Laboratories leverages its vertically integrated glucose biosensor manufacturing to sustain pricing power in continuous monitoring. Philips Healthcare anchors its hospital-at-home strategy through FDA-cleared wearable ecosystems that extend from acute discharge to chronic management. Dexcom dominates the direct-to-consumer channel with factory-calibrated sensors that eliminate fingerstick calibration requirements.
Frictionless remote monitoring devices integrate non-invasive or minimally invasive sensors with wireless telemetry to capture physiological or environmental data without deliberate patient action, typically operating at sampling frequencies of 1 Hz to 250 Hz and transmitting via sub-1 GHz or 2.4 GHz ISM bands. Their primary commercial purpose is enabling longitudinal health datasets for clinical decision support while minimizing adherence friction that plagues traditional patient-reported outcomes. Wearable sensors currently lead absolute revenue contribution due to established reimbursement for cardiac and metabolic indications, while ambient sensors represent the fastest-expanding margin pool as smart home infrastructure penetrates elderly care facilities. Cellular Networks technology commands premium pricing in implantable devices where patient mobility demands seamless handoff across geographies, though Bluetooth Low Energy captures volume leadership in fitness and workplace safety applications.
FDA, HIPAA, and the EU MDR collectively shape product architecture by mandating encryption standards, clinical validation thresholds, and post-market surveillance protocols that determine market access timelines. The EU AI Act introduces additional conformity requirements for diagnostic algorithms embedded in monitoring software, forcing vendors to segregate training datasets by geography. Stakeholders must decide whether to pursue parallel regulatory filings or sequence market entry based on reimbursement velocity rather than population size.
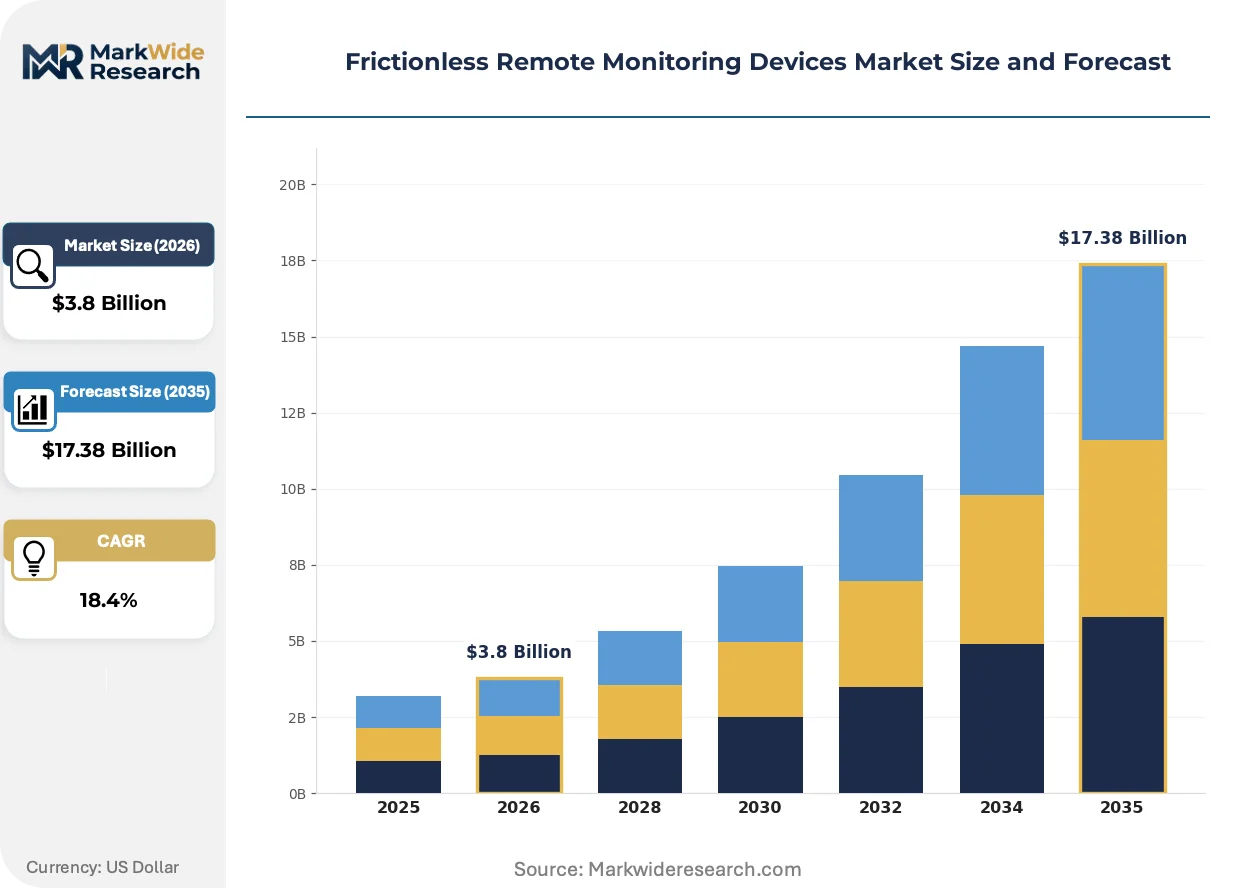
Market Dynamics
Medicare reimbursement expansion for remote patient monitoring is restructuring procurement authority from hospitals toward payers and patients, compressing traditional channel hierarchies while accelerating direct-to-consumer sensor adoption.
Growth Catalysts
- Bluetooth Low Energy miniaturization:Power consumption thresholds for continuous glucose trackers now enable 14-day wear without patient intervention, expanding addressable populations beyond insulin-dependent diabetics.
- Germany's occupational health mandates:Real-time exposure monitoring requirements in chemical processing plants are generating institutional demand for ambient environmental sensors with cellular backhaul.
- FDA 510(k) software-as-medical-device pathways:Streamlined clearance timelines for algorithm-driven monitoring platforms are lowering capital barriers for algorithm-native entrants against incumbent hardware manufacturers.
Market Restraints
- EU MDR clinical validation thresholds:Post-market surveillance protocols and notified body capacity constraints are extending time-to-revenue for implantable cardiac monitors by 18-24 months.
- Li-ion battery supply concentration:Cathode precursor refining in China creates single-source vulnerability for wearable device manufacturers targeting continuous sampling frequencies above 100 Hz.
- HIPAA encryption standards:State-level privacy fragmentation beyond federal baselines forces redundant compliance architecture, raising per-device certification costs for multi-state deployments.
Strategic Opportunities
- India's PLI scheme for medical electronics:Production-linked incentives for domestic sensor assembly are attracting contract manufacturers to establish captive capacity for export markets.
- Japan's smart elderly care infrastructure:METI-funded ambient sensor networks in municipal housing complexes represent greenfield deployment absent legacy device replacement cycles.
- AI-driven predictive triage:Convergence of edge computing with sub-1 GHz telemetry is enabling pre-symptomatic alert generation for sepsis in post-acute settings.
Industry Challenges
- Firmware-over-the-air validation:FDA's evolving stance on software updates as device modifications creates uncertainty for continuous improvement cycles in factory-calibrated sensors.
- Biocompatibility material science talent:Scarcity of polymer chemists with ISO 10993 testing experience is constraining development timelines for next-generation adhesive patches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frictionless Remote Monitoring Devices Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Sensors, Ambient Sensors, Implantable Devices, Mobile Monitors, Environmental Monitors Technology: Bluetooth Low Energy, Wi-Fi, Zigbee, NFC, Cellular Networks Use Case: Chronic Disease Management, Elderly Care, Vital Sign Tracking, Fitness Monitoring, Workplace Safety End User: Healthcare Providers, Telehealth Services, Assisted Living Facilities, Sports Organizations, Occupational Health Departments |
| Companies Covered | Abbott Laboratories, Medtronic, Philips Healthcare, Dexcom, Nike, Fitbit, LG Electronics, iHealth Lab Inc, Garmin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frictionless Remote Monitoring Devices Market Shifts & Advancements
Sensor fusion architectures and ambient computing infrastructure are dissolving the boundary between patient-worn and environmental monitoring modalities, creating unified data streams that bypass traditional episodic clinical encounters.
Photoplethysmography is converging with accelerometer arrays to enable cuffless blood pressure estimation through pulse wave velocity modeling. Hospital-at-home programs in the United States are piloting these multi-modal wristbands for hypertension management during 30-day post-discharge windows. This convergence is compressing the addressable market for traditional ambulatory blood pressure monitors while expanding reimbursement eligibility for continuous cardiovascular surveillance.
The EU AI Act's risk classification framework for diagnostic algorithms is mandating segregated training datasets by geography, forcing vendors to maintain parallel model versions for European and non-European patient populations. MDR-cleared monitoring software must now document algorithmic drift detection protocols alongside hardware biocompatibility files. Cardiac arrhythmia detection algorithms face the steepest compliance burden, with notified bodies requiring prospective validation studies exceeding 10,000 patient-hours.
Hospital procurement committees are unbundling device hardware from data analytics subscriptions, reversing the bundled SaaS contracts that dominated 2018-2023 vendor relationships. Large integrated delivery networks in Texas and Florida are negotiating direct sensor sourcing while contracting separately with AI platform vendors for predictive analytics. This disintermediation is most advanced in Medicare Advantage plans with capitated risk arrangements, where payer-owned data infrastructure reduces dependency on device manufacturer cloud platforms.
Frictionless Remote Monitoring Devices Market Segmentation
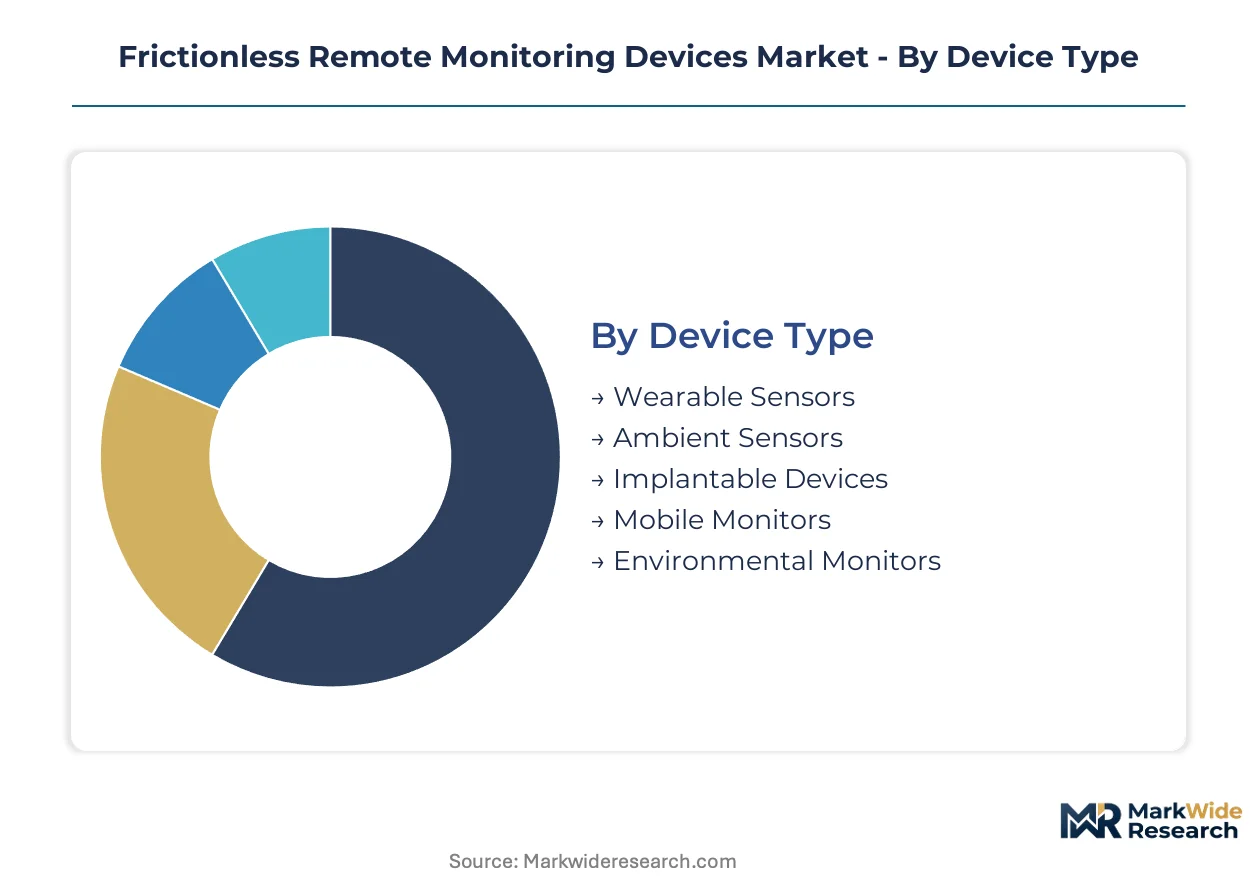
Device architecture and connectivity protocol choices determine reimbursement eligibility and deployment economics across clinical and consumer settings. Segmentation reveals where procurement authority concentrates and which technology combinations unlock new addressable populations.
Device Type:
Wearable sensors currently dominate replacement cycles as Medicare reimbursement accelerates procurement of cardiac and metabolic monitors for home-based chronic management.
- Wearable Sensors:Factory-calibrated biosensors with adhesive patches enable continuous glucose and ECG sampling without fingerstick calibration. Demand concentrates in United States Medicare Advantage plans where capitated risk arrangements favor longitudinal datasets over episodic encounters.
- Ambient Sensors:Environmental monitors deployed in smart home infrastructure capture movement, air quality, and acoustic patterns without patient-worn hardware. Germany's occupational health mandates in chemical processing plants are driving institutional procurement with cellular backhaul requirements.
- Implantable Devices:Miniaturized sensors with sub-1 GHz telemetry for cardiac arrhythmia detection and neurological monitoring.
- Mobile Monitors:Handheld or cart-mounted devices with intermittent sampling for point-of-care diagnostics.
- Environmental Monitors:Fixed-position sensors tracking particulate exposure, noise levels, and thermal conditions in industrial and residential settings.
Volume placements concentrate in Wearable Sensors; the faster expansion belongs to Ambient Sensors.
Technology:
Power consumption thresholds and transmission range requirements segment procurement across fitness, clinical, and industrial applications with distinct mobility demands.
- Bluetooth Low Energy:Protocol miniaturization has cut power draw for continuous glucose trackers to enable 14-day wear cycles. Fitness and workplace safety applications in United States and Germany capture volume leadership due to smartphone ecosystem integration.
- Cellular Networks:Premium connectivity enables seamless handoff across geographies for implantable cardiac monitors and elderly care deployments. Japan's METI-funded ambient sensor networks in municipal housing complexes favor this technology for absent legacy infrastructure.
- Wi-Fi:Higher bandwidth protocol for stationary installations with continuous video or multi-sensor data streams.
- Zigbee:Mesh networking standard for smart home sensor arrays with low-latency device-to-device communication.
- NFC:Proximity-based pairing and data transfer for factory-calibrated sensor initialization.
Bluetooth Low Energy commands absolute unit volume; Cellular Networks capture the steepest margin expansion trajectory.
Use Case:
Reimbursement velocity and patient adherence economics determine which clinical applications justify hardware investment versus software-only alternatives.
- Chronic Disease Management:Continuous monitoring for diabetes, heart failure, and hypertension generates longitudinal datasets for clinical decision support. United States Medicare reimbursement expansion is restructuring procurement authority from hospitals toward payers and patients.
- Elderly Care:Fall detection, medication adherence, and activity pattern monitoring in independent living settings. Japan's smart elderly care infrastructure represents greenfield deployment absent legacy device replacement cycles.
- Vital Sign Tracking:Post-acute surveillance during 30-day hospital-at-home discharge windows.
- Fitness Monitoring:Consumer-directed biometric tracking with direct-to-consumer sensor adoption.
- Workplace Safety:Real-time exposure monitoring for chemical, thermal, and ergonomic hazards in industrial environments.
Chronic Disease Management sustains the largest installed base; Elderly Care is climbing the fastest as smart home infrastructure penetrates aging populations.
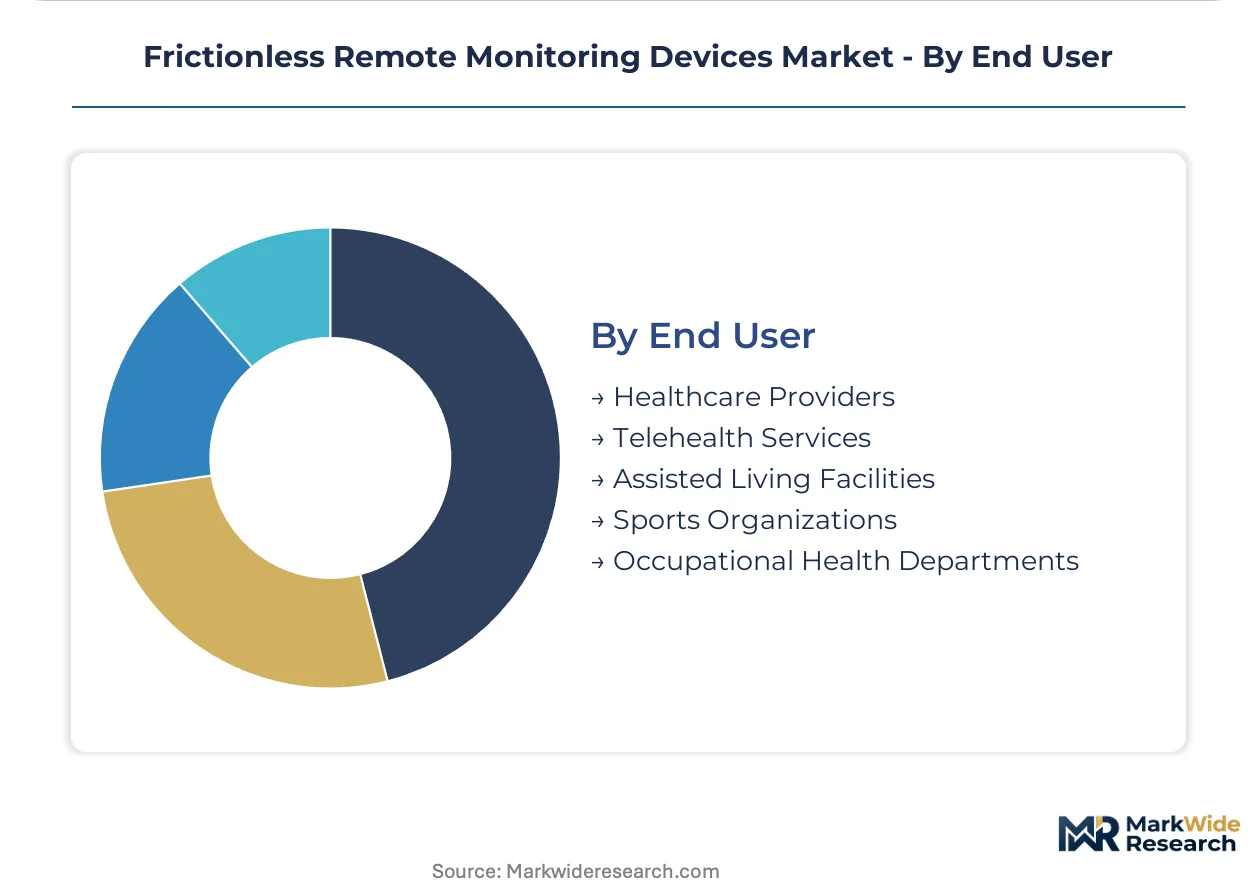
End User:
Procurement committee composition and data infrastructure ownership determine whether vendors sell bundled hardware-software contracts or unbundled sensor sourcing.
- Healthcare Providers:Hospital procurement committees are unbundling device hardware from analytics subscriptions. Large integrated delivery networks in Texas and Florida negotiate direct sensor sourcing while contracting separately with AI platform vendors.
- Telehealth Services:Remote care platforms requiring continuous data streams for virtual visit augmentation. Medicare reimbursement expansion is compressing traditional channel hierarchies toward direct-to-consumer adoption.
- Assisted Living Facilities:Institutional purchasers of ambient sensor networks for resident safety monitoring.
- Sports Organizations:Elite and amateur athletic programs tracking performance and recovery biomarkers.
- Occupational Health Departments:Corporate and regulatory compliance buyers for mandated exposure monitoring.
Healthcare Providers account for the deepest volume commitments; Telehealth Services are gaining share fastest as virtual care infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Medicare reimbursement expansion is restructuring procurement authority toward payers and patients, while Germany's occupational health mandates and Japan's elderly care infrastructure create parallel demand centers across three continents.
United States
Medicare Advantage plans with capitated risk arrangements favor longitudinal datasets from continuous glucose and ECG monitors. FDA 510(k) pathways for software-as-medical-device are compressing clearance timelines for algorithm-native entrants. Texas and Florida integrated delivery networks are negotiating direct sensor sourcing while contracting separately with AI platform vendors.
Germany
Chemical processing plants face mandated real-time exposure monitoring requirements under occupational health regulations. EU MDR clinical validation thresholds extend time-to-revenue for implantable devices by 18-24 months. Industrial clusters in North Rhine-Westphalia are driving institutional procurement of ambient environmental sensors with cellular backhaul.
Japan
METI-funded ambient sensor networks in municipal housing complexes represent greenfield deployment absent legacy device replacement cycles. PMDA clearance protocols favor hardware-software bundled submissions for elderly care applications. The Kanto region around Tokyo anchors manufacturing partnerships for sub-1 GHz telemetry modules.
India
Production-linked incentives for domestic medical electronics assembly are attracting contract manufacturers to establish captive capacity. CDSCO regulatory harmonization with IMDRF standards is accelerating import substitution for wearable biosensors. Karnataka and Telangana host emerging clusters for Bluetooth Low Energy device contract manufacturing.
China
NMPA innovation fast-track pathways for breakthrough diagnostic devices are shortening registration timelines for AI-embedded monitoring software. Dual carbon goals are pressuring battery supply chains for continuous sampling devices above 100 Hz. The Yangtze River Delta concentration of cathode precursor refining creates single-source vulnerability for wearable manufacturers.
Frictionless Remote Monitoring Devices Market Competitive Landscape
United States producers anchor one tier; European and Asian specialists hold differentiated positions in regulatory-heavy and manufacturing-intensive segments respectively. The market structure is consolidating around vertically integrated biosensor manufacturers and algorithm-native platform vendors. Three archetypes dominate: legacy medical device conglomerates with FDA-cleared hardware ecosystems, consumer electronics firms leveraging smartphone integration, and contract manufacturers capturing PLI-driven assembly migration. Competitive moves concentrate on unbundling hardware from analytics subscriptions and establishing captive battery precursor supply.
Within the legacy medical device tier, Abbott Laboratories and Medtronic represent vertically integrated archetypes with in-house biosensor manufacturing capabilities. Dexcom occupies a position exemplifying the direct-to-consumer channel specialist. Among consumer electronics crossovers, Garmin Ltd. and Fitbit sit within the fitness-originated expansion archetype.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Philips Healthcare |
| Dexcom |
| Nike |
| Fitbit |
| LG Electronics |
| iHealth Lab Inc |
| Garmin Ltd. |
| Others |
Supply & Pricing Matrix
Medicare Advantage procurement committees with capitated risk arrangements command subscription-based pricing for longitudinal monitoring datasets, compressing per-unit hardware margins while expanding recurring SaaS revenue pools.
Pricing Analysis
Short lead-time premiums attach to factory-calibrated sensors with FDA 510(k) clearance, while spot inventory discounts characterize uncertified consumer-grade wearables. The dominant structure stratifies across premium, standard, and economy tiers differentiated by ISO 10993 biocompatibility grade and after-sales algorithm update bundling. Pricing pressure stems from hospital procurement committees unbundling hardware from analytics subscriptions. Direct-to-consumer channels exhibit highest price sensitivity; implantable cardiac monitors show lowest sensitivity due to reimbursement capture.
Supply Chain Analysis
ISO 10993 and FDA biocompatibility qualifications gate adhesive patch suppliers, extending qualification timelines for new polymer chemists. Cathode precursor refining concentrates in China, South Korea, and Japan, with sub-1 GHz telemetry module assembly anchored in the Kanto region. Li-ion battery supply draws from Yangtze River Delta concentration, creating single-source vulnerability for continuous sampling devices. Distribution runs through hospital procurement committees, direct-to-consumer platforms, and occupational health departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around algorithm-native platform vendors as EU MDR clinical validation thresholds force capital-constrained hardware manufacturers toward exit or acquisition.
For Market Incumbents: Acquire ISO 10993-testing polymer chemistry capabilities to compress next-generation adhesive patch development timelines. Abbott Laboratories and Medtronic should deepen backward integration into glucose biosensor manufacturing to defend pricing power against factory-calibrated sensor entrants. Threat substitution emerges from algorithm-native vendors with streamlined FDA 510(k) software-as-medical-device clearances. For New Entrants and Emerging Players: Telehealth platforms represent the most penetrable channel partner type for direct-to-consumer sensor distribution. White-space targets include Japan's METI-funded municipal housing complexes and India's PLI-driven contract manufacturing clusters. A reimbursement-first go-to-market angle unlocks Medicare Advantage procurement pathways ahead of hardware-software bundling. For Investors and Strategic Acquirers: The window for entry favors algorithm-native monitoring software vendors with EU MDR-notified body relationships and FDA 510(k) precedent submissions. Long-term viability hinges on segregated training dataset infrastructure for EU AI Act compliance. Watch FDA firmware-over-the-air guidance evolution as inflection indicator for continuous improvement cycle economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-Medical-Device Submission | Streamlined clearance timelines compress capital barriers for algorithm-native entrants against incumbent hardware manufacturers. |
| EU MDR Notified Body Engagement | Post-market surveillance protocol alignment extends time-to-revenue but secures premium pricing in European clinical settings. |
| Hospital System Partnership | Texas and Florida integrated delivery networks negotiate direct sensor sourcing separate from AI platform vendor contracts. |
| Software Companion Development | Photoplethysmography-accelerometer fusion enables cuffless blood pressure estimation for hospital-at-home hypertension programs. |
| Reimbursement Strategy | Medicare expansion for remote patient monitoring restructures procurement authority toward payers and patients. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads. FDA 510(k) databases, EU MDR notified body certificates, CMS Medicare reimbursement schedules, and CDSCO import substitution reports provided secondary validation. Bottom-up sensor shipment estimates triangulated against top-down healthcare IT spending allocations.
Data-stream reconciliation across device architecture, connectivity protocol, and end-use segmentation dimensions modeled volume and value outputs throughout the forecast period. CAGRs derived from longitudinal reimbursement velocity curves and smart home infrastructure penetration rates. Bluetooth Low Energy power consumption thresholds and cellular backhaul deployment economics informed technology-segment trajectories.
Caveats apply where EU AI Act algorithmic drift detection protocols or FDA firmware-over-the-air guidance revisions could materially shift the outlook. Forecasts reflect assumptions on Medicare reimbursement expansion velocity and PLI scheme manufacturing migration timing. A model refresh is warranted upon material change in notified body capacity constraints or cathode precursor supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
Eye Tracking Systems Market
Sensors and Controls
Global Accelerometers Market
Sensors and Controls
Corrosion Monitoring Market
Sensors and Controls
Piezoresistive Pressure Sensor Market
Sensors and Controls
Middle East and Africa Pressure Sensors Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Refrigeration Gauge Market
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
Wireless Flow Sensors Market
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Sensor Hub Market