
 Fiber Optic Plates (FOP) Market | 2026-2036
Fiber Optic Plates (FOP) Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Plates (FOP) Market Insights
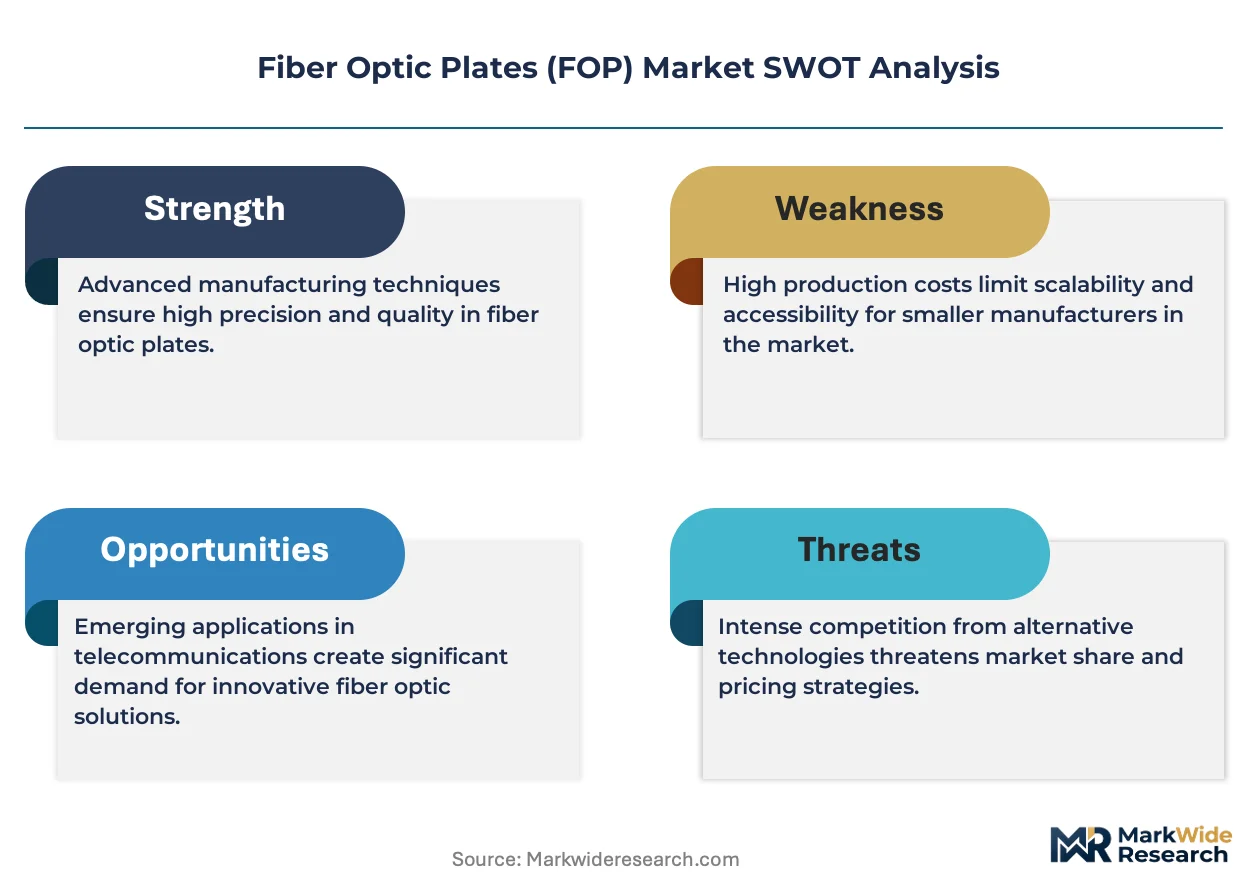
Synthetic silica is consolidating its position over conventional borosilicate substrates in high-resolution FOP manufacturing, narrowing unit cost gaps while extending transmission bandwidth. Corning Incorporated leverages captive fused silica capacity to anchor supply for medical and defense-grade plates. SCHOTT AG sustains European leadership through deep specialization in polarizing fiber arrays for aerospace applications. Incom Inc. competes on custom-drawn multi-mode configurations for niche scientific instrumentation.
Fiber optic plates are fused arrays of millions of optical glass fibers that transmit images or light with minimal distortion, typically specified by numerical aperture, fiber diameter below 10 micrometers, and packing density exceeding 85 percent active area. Their primary purpose is to couple scintillation light or images between phosphor screens and sensors in radiation-hardened environments. Multi-mode plates dominate volume in military night-vision and industrial inspection systems where cost tolerance permits moderate resolution. Single-mode configurations command premium positioning in telecom backhaul and coherent optical switching where modal dispersion must approach zero. Polarizing technology segments attract outsized R&D allocation as augmented-reality waveguide manufacturers seek angular selectivity in compact form factors.
FDA 21 CFR Part 1020 governs diagnostic X-ray system performance, directly mandating minimum image quality thresholds that favor high-efficiency FOP-to-sensor coupling in digital radiography retrofits. CE marking under EU MDR and Japan's PMDA quality management standards create parallel compliance ladders that filter low-specification imports from Asian contract manufacturers. Stakeholders must monitor divergence between FDA and PMDA testing protocols for fiber integrity under thermal cycling, as harmonization gaps threaten to fragment qualification costs for dual-certified product lines.
Market Dynamics
Medical imaging OEMs are accelerating digital detector retrofits as legacy CCD-to-FOP coupling architectures reach obsolescence thresholds, compressing replacement cycles from seven-year baselines toward four-year refresh mandates.
Growth Catalysts
- FDA 21 CFR Part 1020:Minimum image quality thresholds for diagnostic X-ray systems mandate high-efficiency FOP-to-sensor coupling, forcing hospital network upgrades across the United States.
- Synthetic silica substrate migration:Narrowing unit cost gaps against borosilicate alternatives extend transmission bandwidth for high-resolution plate manufacturing in precision optics clusters.
- Japan's precision optics concentration:Hamamatsu and AGC anchor domestic OEM supply chains serving export demand for defense-grade and medical-grade fused arrays.
Market Restraints
- Captive fused silica supply:Corning's vertical control over high-purity substrate limits second-source availability for mid-tier plate fabricators.
- Polarizing fiber array technical ceiling:Aerospace angular selectivity requirements exceed current draw-tower precision limits below 6-micrometer fiber diameters.
- CE marking under EU MDR:Parallel compliance ladders with FDA protocols fragment qualification costs for dual-certified product lines.
Strategic Opportunities
- Augmented-reality waveguide integration:Polarizing FOP technology convergence with micro-LED engines creates angular selectivity demand in compact head-mounted displays.
- Scientific instrumentation multi-mode configurations:Custom-drawn arrays for niche spectroscopy applications bypass volume-price pressure from military night-vision commoditization.
- PMDA-FDA harmonization gaps:Fiber integrity testing protocol divergence creates first-mover advantage for laboratories qualifying dual-standard thermal cycling procedures.
Industry Challenges
- Draw-tower technician scarcity:Multi-fiber array fusion expertise concentrates in aging workforces across Japanese and German precision optics clusters.
- Scintillation phosphor integration complexity:Legacy CCD-based radiography systems require mechanical retrofit engineering for FOP-coupled digital detector compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Plates (FOP) Market |
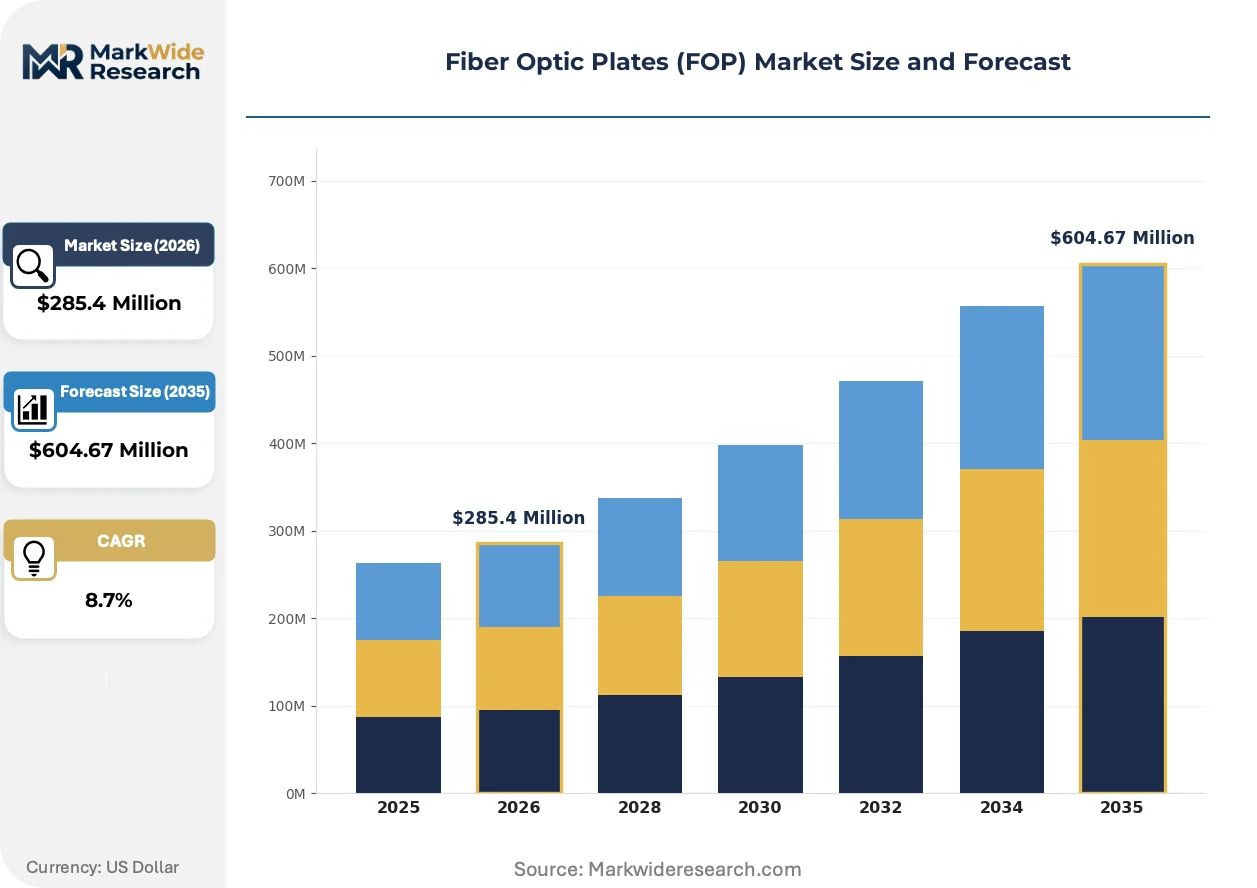
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode, Multi-Mode, Polarizing, Non-Polarizing Application: Telecommunications, Medical Imaging, Military, Consumer Electronics End User: Telecom Operators, Healthcare Providers, Defense Agencies, Electronics Manufacturers Technology: Active, Passive, Fiber Laser, Light Guide |
| Companies Covered | Corning Incorporated, SCHOTT AG, Incom Inc., Asahi Glass Co. Ltd. (AGC), Hamamatsu Photonics K.K., Nippon Electric Glass Co. Ltd., II-VI Incorporated, Saint-Gobain S.A., Furukawa Electric Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Plates (FOP) Market Trends and Innovations
Synthetic silica draw processes are compressing cost structures for high-transmission substrates while regulatory agencies tighten radiation safety coupling standards. These forces reshape competitive positioning around material purity and certification velocity.
Sub-micron synthetic silica preform drawing is unifying medical and defense-grade specifications previously split between borosilicate economy tiers and fused silica premium tiers. Hospital procurement committees now specify 92-percent-plus packing density as standard rather than optional. This compression eliminates mid-tier substrate suppliers lacking captive high-purity silica capacity.
EU MDR technical documentation requirements for fiber optic components in diagnostic equipment extend CE marking timelines from 12 to 18 months. German notified bodies prioritize thermal cycling test data above legacy mechanical stress protocols. Plate manufacturers serving European OEMs now pre-qualify fiber integrity under expanded temperature ranges.
Radiology department procurement committees now bundle detector replacement with extended service contracts rather than sourcing plates through independent distributors. Original equipment manufacturers capture margin previously allocated to aftermarket channels. This consolidation concentrates most visibly in North American hospital network purchasing agreements.
Fiber Optic Plates (FOP) Market Segmentation
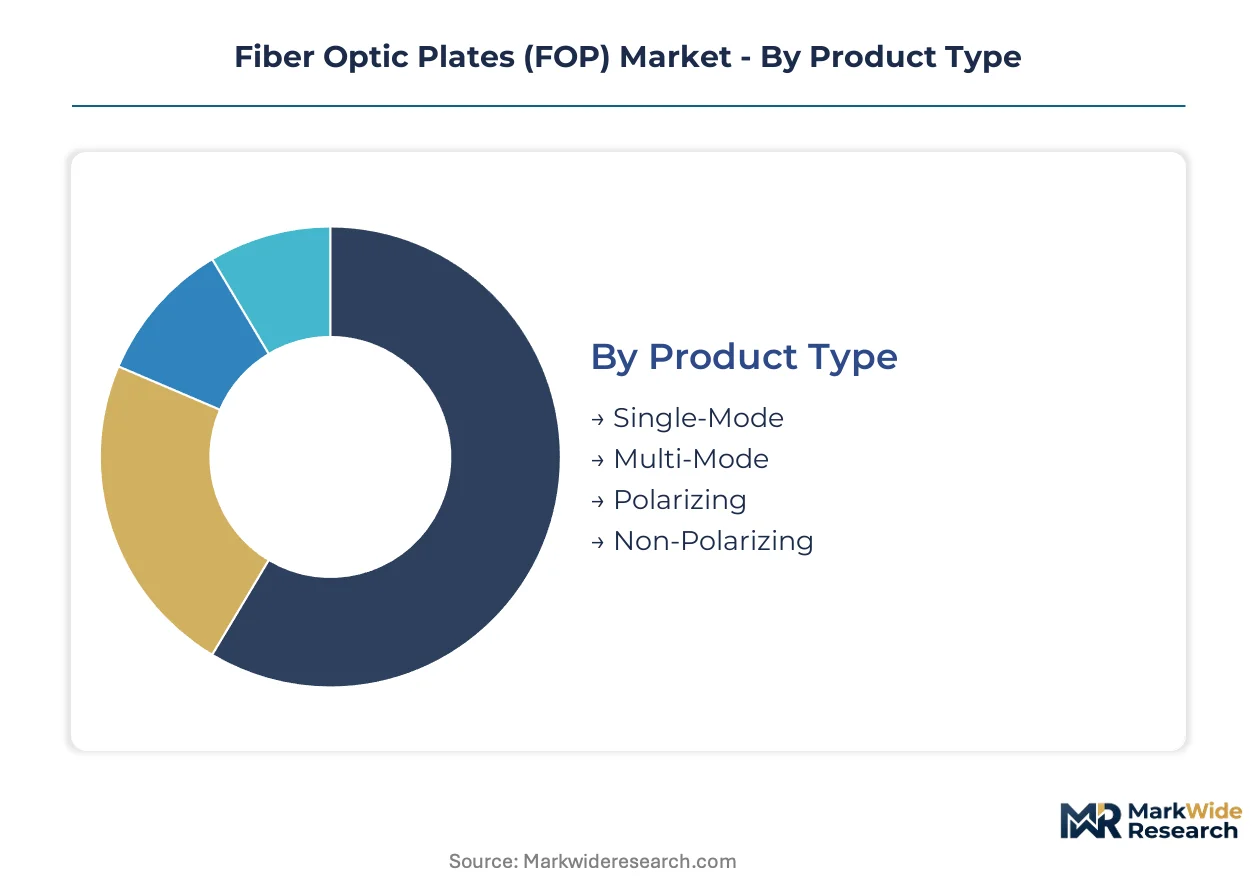
Fiber optic plate procurement splits across four distinct dimensions. Each category reflects divergent technical specifications, certification requirements, and replacement cycle pressures that reshape supplier positioning.
Product Type:
Upgrade cycles from legacy CCD architectures to digital detector coupling are compressing refresh timelines across all plate configurations.
- Single-Mode:Core diameters below 10 micrometers eliminate modal dispersion for coherent optical switching. Telecom backhaul deployments in Japan and Germany specify these plates for wavelength-division multiplexing systems where signal integrity over distance dominates procurement criteria.
- Multi-Mode:Larger core diameters permit cost-efficient light transmission in applications tolerating moderate dispersion. Military night-vision systems and industrial inspection equipment in the United States absorb the majority of volume, though price pressure from commoditized defense procurement is narrowing margins.
- Polarizing:Angular selectivity layers integrated during draw-tower processing enable compact waveguide applications.
- Non-Polarizing:Standard fused arrays without polarization filtering serve general-purpose scintillation coupling.
Volume placements concentrate in Multi-Mode; the faster expansion belongs to Polarizing.
Application:
End-use demand clusters around regulatory compliance deadlines and digital retrofit mandates rather than greenfield installations.
- Telecommunications:Dense wavelength-division multiplexing backbones require sub-micron synthetic silica plates with 92-percent-plus packing density. Japanese carriers and German network operators are standardizing these specifications for 400G coherent transmission upgrades.
- Medical Imaging:Digital radiography retrofits are displacing legacy CCD-to-FOP coupling architectures. FDA 21 CFR Part 1020 minimum image quality thresholds are forcing hospital procurement committees toward four-year replacement cycles from seven-year baselines.
- Military:Night-vision goggle and helmet-mounted display programs specify radiation-hardened fused arrays.
- Consumer Electronics:Augmented-reality waveguide manufacturers are sampling polarizing plates for micro-LED engine integration.
Procurement scale tilts toward Medical Imaging; steepest expansion trajectory sits with Consumer Electronics.
End User:
Customer concentration patterns follow captive supply agreements and extended service contract bundling rather than spot purchasing.
- Telecom Operators:National carriers in Japan and Germany specify single-mode plates through multi-year framework agreements with precision optics clusters. These contracts prioritize transmission bandwidth over unit cost.
- Healthcare Providers:North American hospital networks are consolidating detector replacement procurement through OEM-direct channels. Radiology departments bundle plate replacement with extended service contracts, eliminating independent distributor margins.
- Defense Agencies:Military specification plates flow through prime contractor supply chains with multi-year program commitments.
- Electronics Manufacturers:AR headset assemblers represent emerging demand with unproven volume scaling.
Contract value concentrates with Healthcare Providers; share gains are climbing fastest among Electronics Manufacturers.
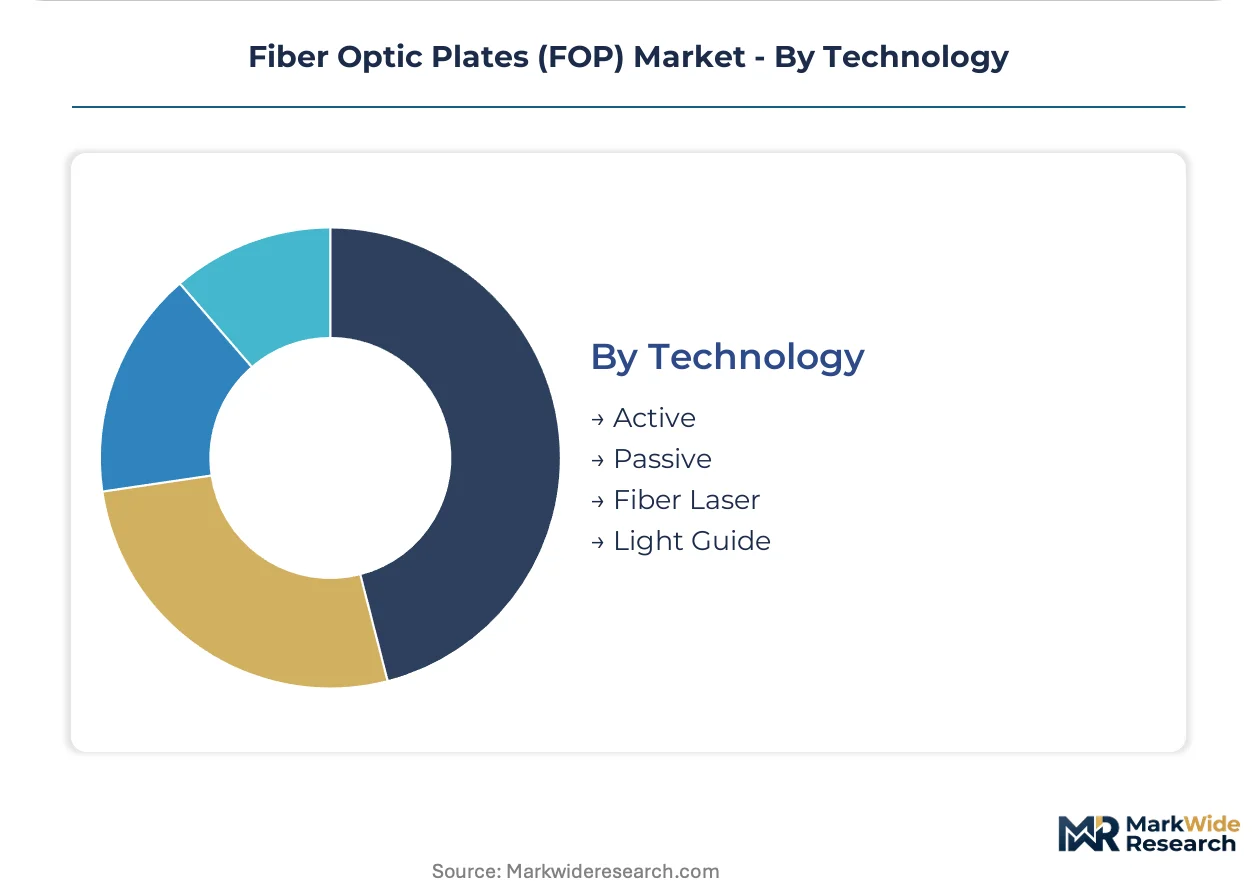
Technology:
Process differentiation separates active signal manipulation from passive transmission architectures with distinct qualification pathways.
- Active:Signal amplification and switching functions integrated within the fused array structure. Telecom infrastructure in Germany and Japan specifies active plates for coherent optical switching nodes where signal regeneration replaces external amplifier hardware.
- Passive:Unamplified light transmission dominates medical and military applications where radiation hardness and thermal stability outweigh signal processing integration.
- Fiber Laser:Gain medium integration enables compact laser sources for industrial cutting and medical procedures.
- Light Guide:Simplified transmission structures serve display backlighting and general illumination coupling.
Shipment volume clusters in Passive; technology migration is accelerating most quickly toward Active.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese precision optics clusters concentrate the highest density of fiber optic plate fabrication capacity, with domestic OEM supply chains serving export demand for medical and defense-grade fused arrays. Hospital procurement committees in North America and telecom operators in Germany are accelerating replacement cycles and 400G coherent transmission upgrades respectively.
United States
FDA 21 CFR Part 1020 mandates minimum image quality thresholds for diagnostic X-ray systems, forcing hospital networks toward four-year detector replacement cycles. Radiology departments now bundle plate procurement with extended service contracts, eliminating independent distributor channels. Corning Incorporated anchors domestic supply through captive fused silica capacity in upstate New York.
Japan
Hamamatsu Photonics and AGC anchor precision optics clusters serving both domestic OEMs and export markets for high-resolution plate manufacturing. METI industrial policy supports sub-micron synthetic silica preform drawing capabilities that unify medical and defense-grade specifications. Draw-tower technician scarcity concentrates in aging workforces across Nagoya and Hamamatsu production facilities.
Germany
Telecom backhaul deployments specify single-mode plates for wavelength-division multiplexing systems where signal integrity dominates procurement criteria. EU MDR technical documentation extends CE marking timelines from 12 to 18 months, with German notified bodies prioritizing thermal cycling test data. SCHOTT AG sustains European leadership through specialization in polarizing fiber arrays for aerospace applications.
China
Domestic optical component manufacturers are expanding multi-mode plate capacity for industrial inspection systems and military night-vision programs. NMPA quality management standards for diagnostic equipment create parallel compliance requirements for imported medical-grade plates. Yangtze River Delta clusters concentrate draw-tower infrastructure serving both domestic consumption and export assembly.
Fiber Optic Plates (FOP) Market Competitive Landscape
Capacity expansion dominates the current landscape as synthetic silica substrate migration narrows unit cost gaps against borosilicate alternatives. The vendor base stratifies across three tiers: integrated material suppliers with captive high-purity silica capacity, specialized plate fabricators serving niche scientific instrumentation, and regional contract manufacturers competing on volume scale. Strategic archetypes include backward-integrated substrate specialists, custom-drawn multi-mode configuration providers, and polarizing array technology developers. M&A activity and qualification velocity for dual-certified product lines represent the dominant competitive moves.
Among Japanese precision optics specialists, Hamamatsu Photonics K.K. and Asahi Glass Co. Ltd. exemplify the integrated substrate-fabrication archetype, while Corning Incorporated anchors the North American tier through upstream control over fused silica supply. These three occupy positions that reflect divergent geographic and vertical strategies within the broader competitive structure.
| Leading Market Players |
|---|
| Corning Incorporated |
| SCHOTT AG |
| Incom Inc. |
| Asahi Glass Co. Ltd. (AGC) |
| Hamamatsu Photonics K.K. |
| Nippon Electric Glass Co. Ltd. |
| II-VI Incorporated |
| Saint-Gobain S.A. |
| Furukawa Electric Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Premium-grade fused silica certification against standard borosilicate qualification creates a three-tier pricing structure across premium, standard, and economy levels that simultaneously concentrates procurement leverage among captive substrate holders and fragments second-source availability for mid-tier fabricators. This divergence compresses margins at the standard tier while elevating pricing power for medical-grade and defense-grade plates bearing dual FDA-PMDA certification.
Pricing Analysis
Volume placements cluster in commoditized multi-mode military night-vision programs where defense procurement price erosion narrows fabricator margins, while single-mode telecom backhaul and polarizing AR waveguide applications sustain premium positioning through modal dispersion tolerances and angular selectivity specifications. Price differentiation rests on packing density thresholds and thermal cycling certification grade rather than raw material cost. Pricing pressure stems from synthetic silica substrate migration compressing cost structures at the premium tier. Hospital procurement committees exhibit lowest price sensitivity due to bundled service contract structures, while industrial inspection OEMs face acute margin compression.
Supply Chain Analysis
Dual FDA-PMDA thermal cycling qualification gates downstream distribution, extending CE marking timelines and fragmenting supplier certification costs for European market access. Geographic supply concentration centers on Japan, Germany, and the United States, with Nagoya and Hamamatsu precision optics clusters anchoring draw-tower capacity. Raw material dependencies include high-purity synthetic silica preforms, specialized draw-tower equipment, and scintillation phosphor integration chemistries. Single-source vulnerability concentrates in Corning's captive fused silica substrate supply. Distribution runs through OEM-direct channels for medical imaging retrofits and prime contractor supply chains for defense programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification velocity and captive substrate capacity as synthetic silica migration eliminates mid-tier borosilicate suppliers lacking backward integration into high-purity material production.
For Market Incumbents: Hedge against draw-tower technician scarcity by securing multi-year employment contracts with aging Japanese and German precision optics workforces before retirement cliffs accelerate. Anchor defensive positioning through PMDA-FDA harmonization gap exploitation, qualifying dual-standard thermal cycling procedures ahead of protocol convergence. Prioritize captive synthetic silica capacity expansion to maintain substrate cost advantages as borosilicate alternatives face elimination from hospital procurement specifications. For New Entrants and Emerging Players: Direct-to-scientific-instrumentation digital channels offer white-space penetration around custom-drawn multi-mode configurations for niche spectroscopy applications bypassing military commoditization pressure. Target polarizing plate sampling programs with augmented-reality waveguide manufacturers seeking micro-LED engine integration, where volume scaling remains unproven and incumbent qualification advantages are weakest. Pursue OEM-direct hospital procurement committee relationships in North American networks consolidating detector replacement away from independent distributors. For Investors and Strategic Acquirers: Re-rating potential sits with specialized plate fabricators possessing polarizing array technology and existing PMDA certification infrastructure given FDA-PMDA harmonization timeline uncertainty extending qualification moats. Long-term viability favors acquisition targets with demonstrated thermal cycling test data under expanded temperature ranges meeting German notified body prioritization. Monitor CE marking timeline compression as inflection signal for European OEM procurement consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Synthetic Silica Capacity Expansion | Secures substrate supply independence as borosilicate tiers face elimination from medical specifications. |
| Dual FDA-PMDA Certification Investment | Creates first-mover qualification advantage before thermal cycling protocol harmonization closes gaps. |
| Polarizing Array R&D Partnership | Positions for AR waveguide angular selectivity demand as micro-LED engine integration accelerates. |
| Draw-Tower Technician Workforce Contracts | Defends against aging workforce retirement cliffs concentrated in Japanese precision optics clusters. |
| OEM-Direct Hospital Procurement Channel | Captures margin previously allocated to independent distributors under bundled service contract structures. |
Research Methodology
Document review covered FDA 21 CFR Part 1020 filings, PMDA quality management standards, EU MDR technical documentation requirements, and precision optics cluster trade data, complemented by interviews with draw-tower operations managers, hospital procurement committee chairs, biomedical engineering directors, and defense prime contractor supply chain leads. Secondary validation drew from customs records, SEC filings of listed optics manufacturers, METI industrial policy disclosures, and German notified body thermal cycling protocol publications. Bottom-up plate shipment estimates by product configuration and application were triangulated against top-down synthetic silica substrate consumption figures.
Segment-level value outputs were generated across product type, application, end user, and technology dimensions over the projection horizon, with coherent optical switching and medical imaging retrofits modeled as distinct growth trajectories. CAGRs were derived from replacement cycle compression analysis and digital detector retrofit penetration curves. Industry-specific forecast inputs included FDA radiation safety standard revision timelines, sub-micron synthetic silica preform draw yield improvements, and augmented-reality waveguide manufacturer sampling program conversion rates.
The model holds under stable regulatory harmonization timelines and synthetic silica cost compression trajectories; deviation in FDA-PMDA protocol convergence acceleration or draw-tower technician attrition rates would shift capacity expansion feasibility and certification velocity assumptions. Stakeholders should weight these assumptions against their own operating context and qualification infrastructure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Duplication Disc Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Package Shell for Optical Communication Modules Market
Optical Components
Europe Lithium Niobate Modulator Market
Optical Components
Optical Transceiver Market
Optical Components
Bio-Optics Market
Optical Components
North America Laser Diode Market
Optical Components
3-7mm Galvo Scanner Market
Optical Components
Optical Amplifier Market
Optical Components
Europe Tunable Laser Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Photointerrupter Market
Optical Components
Photomask Pellicle Market
Optical Components
Global Non Dispersive Infrared (NDIR) Market
Optical Components
Global Optical Coating Equipment Market