
 Global Digital Temperature and Humidity Sensor Market | 2026-2036
Global Digital Temperature and Humidity Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Temperature and Humidity Sensor Market Intelligence
The shift towards System-on-Chip (SoC) integration, which combines the sensor element and processing electronics onto a single die, is narrowing the physical footprint and power consumption of sensor modules. Sensirion AG specializes in CMOS-MEMS based sensor components, achieving high performance in compact form factors. Texas Instruments leverages its broad semiconductor portfolio for integrated solutions, while STMicroelectronics dominates in MEMS technology for industrial and automotive end-users.
A digital temperature and humidity sensor is a device that measures ambient thermal conditions and moisture, converting them into a calibrated digital signal. These units communicate via I2C or SPI interfaces, providing precise data for automated control systems. Capacitive sensors form a mature product segment, while MEMS technology drives innovation across new applications. HVAC systems provide a large volume base, but smart agriculture and pharmaceutical storage applications are expanding rapidly.
Compliance with the EU's RoHS directive restricts the use of hazardous materials in sensor manufacturing, impacting material selection and supply chains. In parallel, FDA guidelines for pharmaceutical storage in the US and China's GB standards for consumer electronics mandate specific accuracy and reliability levels. Vendor selection increasingly depends on the ability to provide certified, pre-calibrated sensors that meet these divergent international requirements.
Market Dynamics
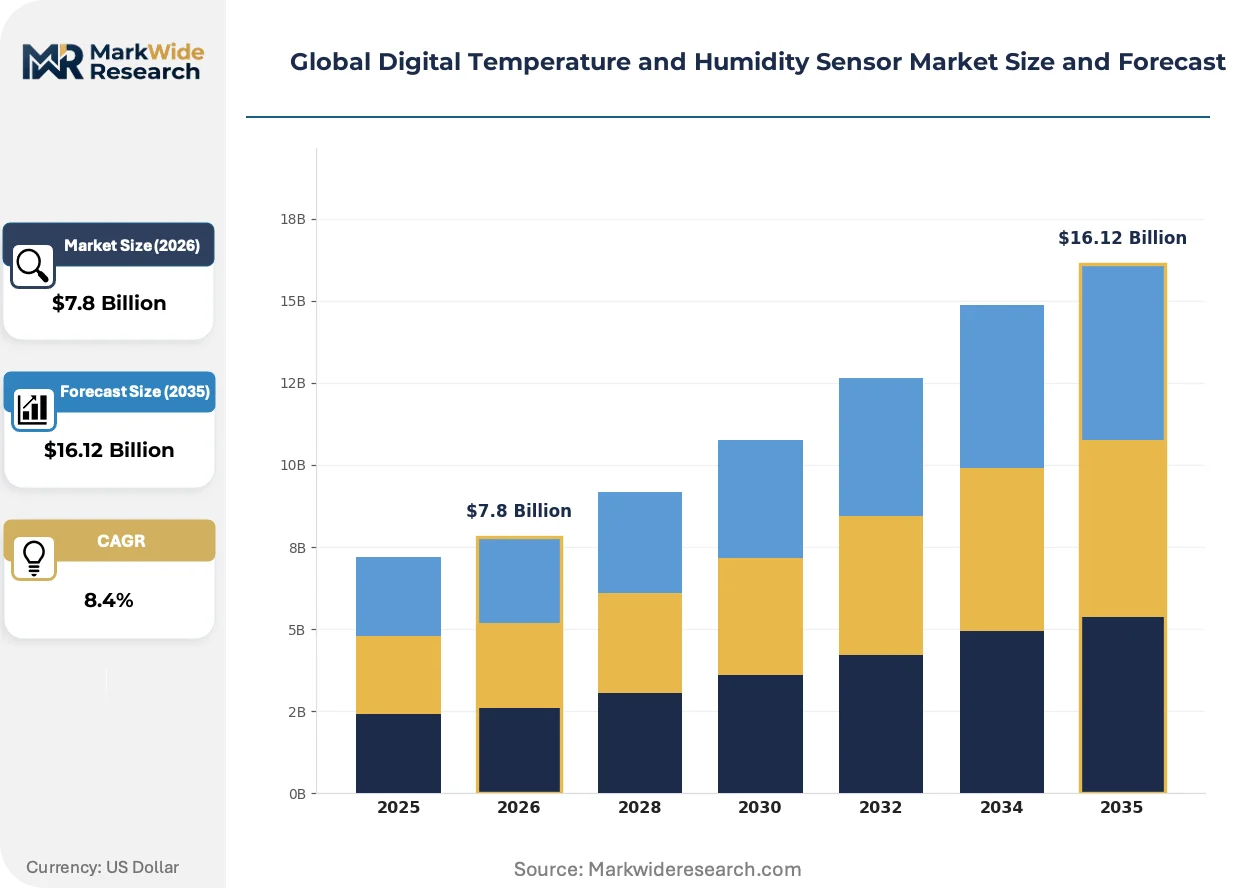
The market's central dynamic is the tension between miniaturization, driven by MEMS and System-on-Chip technology, and the escalating demand from regulated industries for higher accuracy, stability, and certified compliance for critical applications.
Growth Catalysts
- MEMS Integration:The adoption of Micro-Electro-Mechanical Systems enables smaller, energy-efficient sensors, opening new applications in IoT devices and consumer electronics.
- Smart Agriculture Expansion:The need for precise climate control in greenhouses and vertical farms to optimize yields drives volume demand for networked sensors.
- Pharmaceutical Cold Chain:Strict monitoring rules from regulators like the FDA and EMA for drug storage mandate the use of high-reliability, calibrated sensors.
Market Restraints
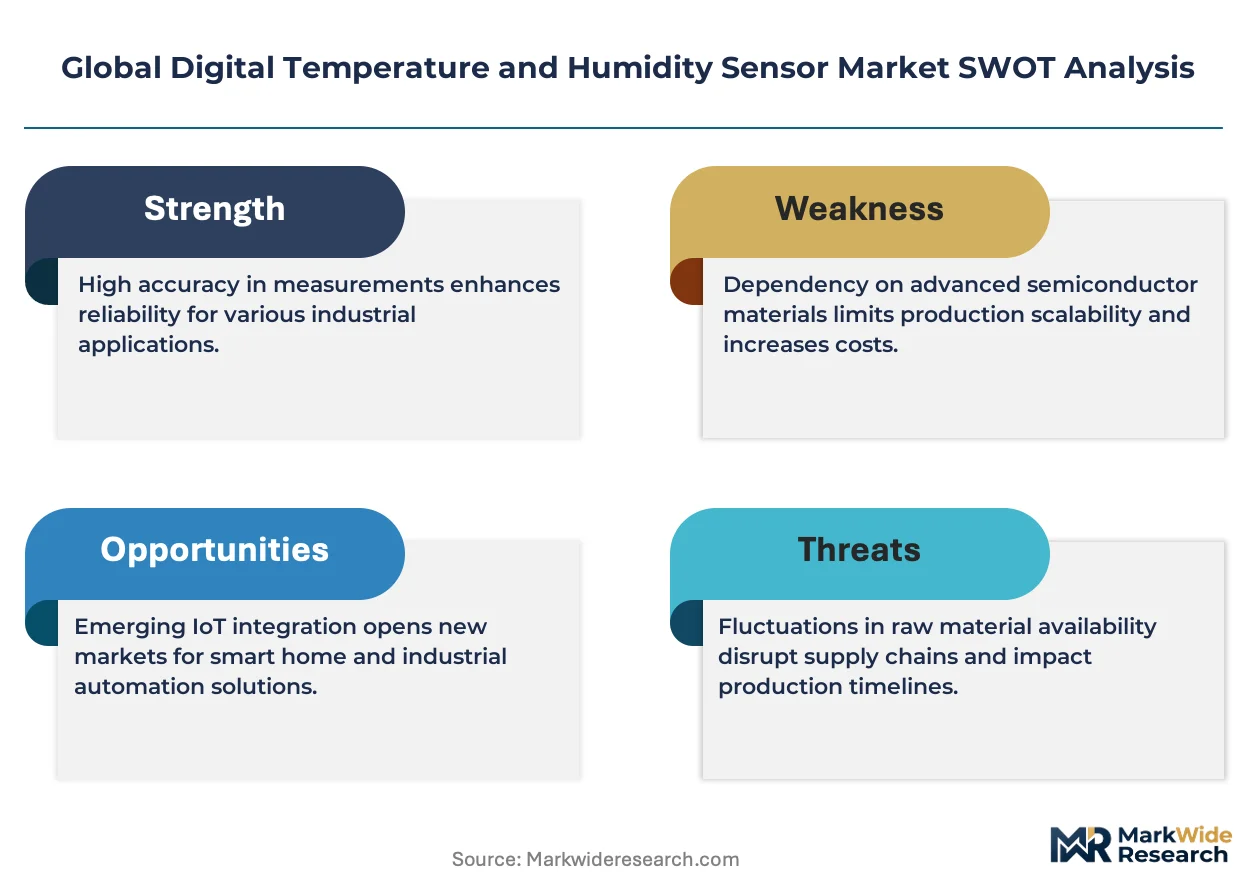
- Input Cost Volatility:Fluctuations in semiconductor-grade silicon prices directly impact manufacturing costs and create margin pressure for component suppliers.
- Calibration Drift:The gradual loss of accuracy in harsh industrial environments requires costly recalibration or replacement, increasing the total cost of ownership.
- Substitution by Integrated ICs:For non-critical uses, multi-function environmental ICs combining multiple sensing types offer a lower-cost alternative, capping price points.
Strategic Opportunities
- EV Battery Management:Electric vehicle batteries require precise thermal and humidity monitoring for safety and longevity, creating a new high-volume automotive application.
- On-Chip AI Processing:Integrating machine learning onto the sensor enables predictive analytics for HVAC fault detection, reducing reliance on cloud infrastructure.
- Southeast Asia Manufacturing:Expanding electronics and food processing sectors in Vietnam and Thailand represent an underpenetrated market for advanced climate control sensors.
Industry Challenges
- Compliance Fragmentation:Manufacturers face significant costs and delays navigating divergent international standards, such as the EU's RoHS, China's GB standards, and US FDA requirements.
- Legacy System Integration:Ensuring seamless interoperability of modern sensors using I2C or SPI interfaces with older industrial control systems remains a significant hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Temperature and Humidity Sensor Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive Sensors, Resistive Sensors, Thermal Sensors, Digital Output Sensors, Optical Sensors Technology: CMOS, MEMS, Thermistor-Based, Semiconductor, Infrared, Piezoelectric Application: HVAC Systems, Pharmaceutical Storage, Smart Agriculture, Food Processing, Environmental Monitoring, Cold Chain Management End User: Embedded Systems, Consumer Electronics, Industrial Automation, Aerospace & Defense, Building Management, Telecommunications |
| Companies Covered | Analog Devices, Inc, Honeywell International, Texas Instruments, Sensirion AG, STMicroelectronics, TE Connectivity, NXP Semiconductors, Robert Bosch GmbH, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Temperature and Humidity Sensor Market Strategic Shifts & Innovations
The market is advancing from simple data logging toward providing actionable system-level intelligence. This evolution is driven by the fusion of MEMS hardware with on-chip processing, enabling smarter, more autonomous end-systems.
System-on-Chip (SoC) design integrates the sensing element, signal processing, and digital interface on a single silicon substrate. Industrial automation and consumer electronics sectors are adopting these modules for their compact size and low power use. This integration of processing power at the node is digitizing environmental monitoring, transforming raw data into actionable information at the source.
Compliance with the EU's RoHS directive restricts hazardous materials in electronic components. This regulation forces manufacturers to redesign products and re-qualify supply chains, impacting production costs and timelines. The automotive and medical device segments are most affected due to stringent re-certification requirements for European market access.
Buyer preference is shifting toward pre-calibrated, certified sensors that guarantee accuracy out of the box. This trend diminishes the role of distributors performing secondary calibration, favoring direct sourcing from manufacturers with accredited metrology labs. This is most pronounced in pharmaceutical and food safety verticals where regulatory traceability is paramount.
Global Digital Temperature and Humidity Sensor Market Segmentation
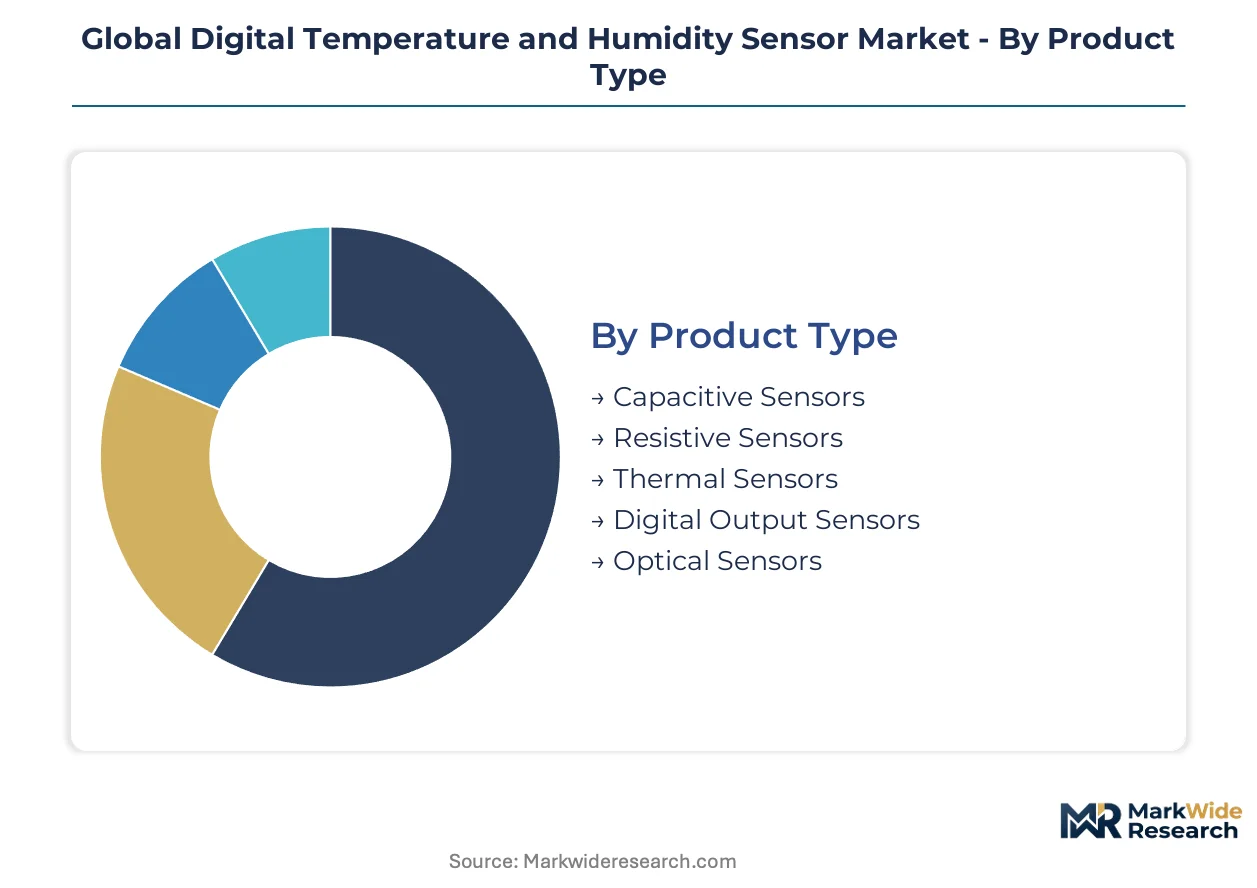
The digital temperature and humidity sensor market segments define distinct value propositions and operational requirements for manufacturers. Understanding these divisions helps in tailoring product development, sales strategies, and supply chain management. Performance characteristics and compliance needs vary significantly across different market verticals.
Product Type:
The intensity of after-sales service and recalibration requirements varies considerably across sensor product types, influencing total cost of ownership for end-users.
- Capacitive Sensors:These devices measure humidity by detecting changes in capacitance due to moisture absorption by a dielectric material. They form a mature product segment with established reliability in HVAC systems and industrial process control.
- Digital Output Sensors:These integrated units combine the sensing element, signal conditioning, and an analog-to-digital converter, providing a calibrated digital signal directly. Demand concentrates in IoT devices and smart agriculture for their ease of integration and precise data communication.
- Resistive Sensors:These sensors measure humidity through changes in electrical resistance of a conductive polymer film as it absorbs or desorbs water vapor. They offer a cost-effective solution for less critical environmental monitoring applications.
- Thermal Sensors:These devices rely on the principle of thermal conductivity to measure moisture content, often used for specific gas or material analysis.
- Optical Sensors:Utilizing changes in light absorption or reflection due to humidity, these sensors provide non-contact measurement in niche applications.
Capacitive Sensors holds the largest share; momentum sits with Digital Output Sensors.
Technology:
The cost tier of sensor technology significantly impacts the final product's price point and its suitability for various applications, from high-volume consumer goods to specialized industrial equipment.
- MEMS:Micro-Electro-Mechanical Systems technology enables the fabrication of smaller, more energy-efficient sensors on a silicon chip. This technology drives innovation across new applications, especially in compact form factors for consumer electronics.
- CMOS:Complementary Metal-Oxide-Semiconductor technology integrates sensor elements with processing electronics onto a single die, narrowing the physical footprint. Sensirion AG specializes in CMOS-MEMS based components for high performance in compact designs.
- Thermistor-Based:These sensors use a resistor whose resistance changes significantly with temperature, offering a simple and cost-effective solution for basic temperature measurement.
- Semiconductor:Utilizing the temperature-dependent electrical characteristics of semiconductor materials, these sensors provide stable and accurate temperature readings.
- Infrared:These non-contact sensors detect infrared radiation emitted by objects to measure temperature, suitable for inaccessible or moving targets.
- Piezoelectric:These sensors generate an electrical charge in response to mechanical stress, finding applications in specialized pressure and vibration sensing.
Thermistor-Based technology dominates current deployments, while MEMS exhibits the steepest expansion trajectory.
Application:
Application-specific requirements dictate sensor accuracy, reliability, and regulatory compliance, influencing design choices and market penetration.
- HVAC Systems:Heating, Ventilation, and Air Conditioning systems require precise climate control for occupant comfort and energy efficiency. These systems provide a large volume base for digital temperature and humidity sensors in commercial and residential buildings.
- Pharmaceutical Storage:Strict monitoring rules from regulators like the FDA and EMA mandate high-reliability, calibrated sensors for drug storage. This ensures product stability and patient safety across the cold chain.
- Smart Agriculture:The need for precise climate control in greenhouses and vertical farms optimizes yields and resource use. Networked sensors facilitate environmental monitoring in modern agricultural practices.
- Food Processing:Maintaining specific temperature and humidity levels is critical for food safety and quality during processing, storage, and transportation.
- Environmental Monitoring:Sensors are deployed in weather stations, air quality systems, and research facilities to track atmospheric conditions.
- Cold Chain Management:This application ensures temperature-sensitive goods, like vaccines and perishable foods, remain within specified ranges during transit.
HVAC Systems commands the largest installed base, with Pharmaceutical Storage showing significant growth.
End User:
The type of end-user dictates sensor integration complexity, required durability, and volume demand, shaping vendor product portfolios.
- Industrial Automation:Manufacturing hubs in Germany and China drive demand for sensors in process control, machine monitoring, and predictive maintenance. These applications require robust and reliable sensors for continuous operation.
- Consumer Electronics:IoT devices, smart home appliances, and wearables integrate compact, energy-efficient sensors for environmental sensing. Miniaturization driven by MEMS technology is crucial in this segment.
- Embedded Systems:These dedicated computer systems control specific functions within larger mechanical or electrical systems. Sensors provide critical input for their operation.
- Aerospace & Defense:High-reliability sensors are essential for environmental control within aircraft, spacecraft, and military equipment.
- Building Management:Sensors optimize energy use and occupant comfort by monitoring conditions in commercial and residential structures.
- Telecommunications:Environmental monitoring in data centers and communication infrastructure ensures optimal operating conditions for sensitive equipment.
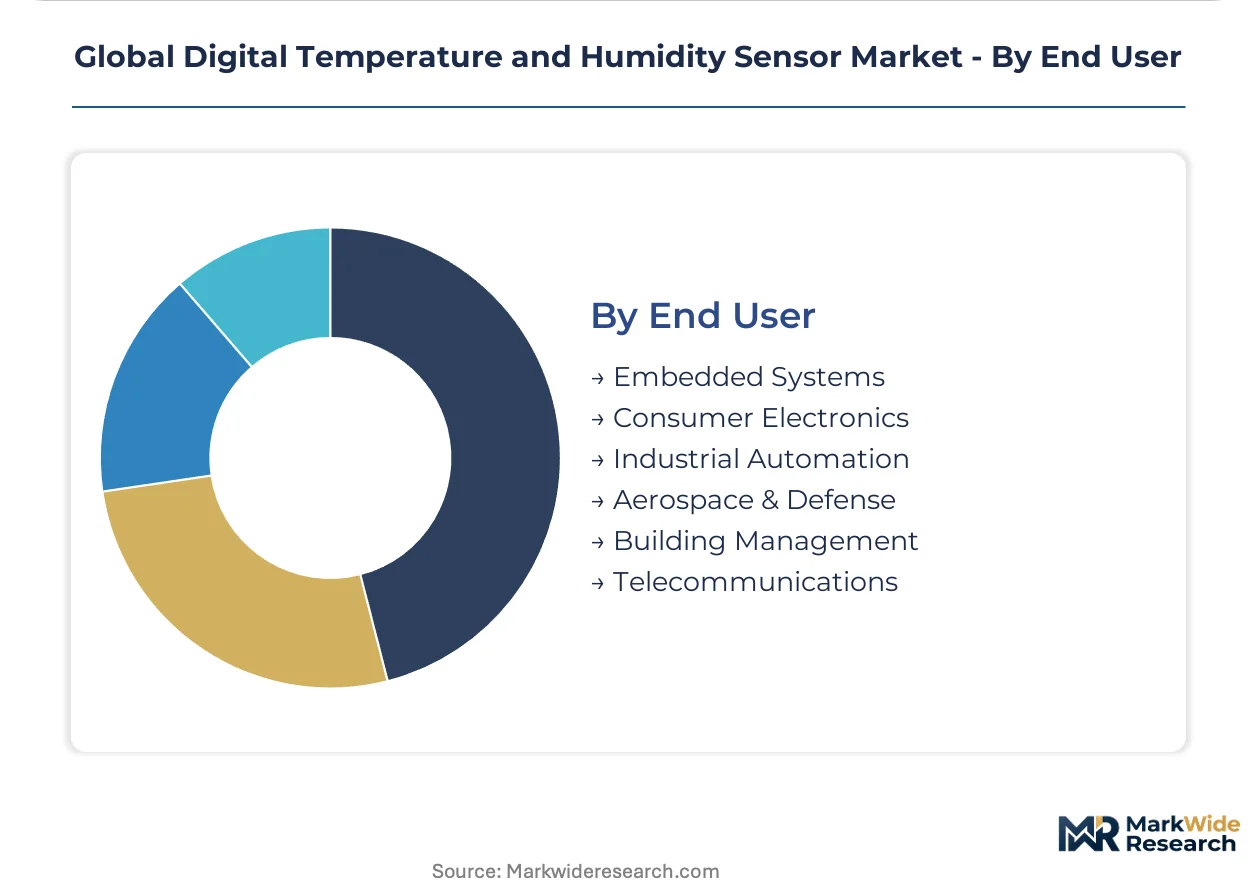
Industrial Automation accounts for the majority of sensor deployments, as Consumer Electronics expands its footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flow of sensor components from Asian manufacturing hubs to European and North American industrial sectors shapes global market dynamics. Digital temperature and humidity sensors find critical applications across diverse geographies. This global market is characterized by varying regulatory landscapes and distinct industrial demands.
Germany
Germany's advanced manufacturing sector, particularly in industrial automation and automotive applications, generates substantial demand. The EU's RoHS directive influences material selection for sensors supplied within its borders. Industrial clusters in Baden-Württemberg integrate high-precision sensors for machine monitoring and predictive maintenance.
China
Chinese manufacturing hubs require digital sensors for industrial automation and expanding consumer electronics production. China's GB standards mandate specific accuracy and reliability levels for electronic components. The Pearl River Delta, a vast electronics manufacturing cluster, integrates compact sensors into diverse IoT devices.
United States
The United States market demands high-reliability sensors for pharmaceutical cold chain monitoring and EV battery management systems. FDA guidelines strictly regulate sensor performance for drug storage and transport applications. The Silicon Valley region integrates advanced sensors into smart home devices and data center environmental controls.
Japan
Japanese automotive and industrial sectors demand precise temperature and humidity sensors for advanced manufacturing and robotics. Compliance with JIS standards ensures quality and reliability in sensor components for domestic applications. Manufacturers in the Kansai region focus on integrating sensors into sophisticated industrial equipment and smart infrastructure.
Vietnam
Expanding electronics manufacturing and food processing sectors in Vietnam create new demand for climate control sensors. Local regulations regarding product quality and environmental monitoring influence sensor specification requirements. Industrial parks near Hanoi are increasingly adopting networked sensors for efficient production and quality control.
Global Digital Temperature and Humidity Sensor Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with a few large integrated semiconductor companies alongside numerous specialized sensor manufacturers. This market features archetypes ranging from broad-portfolio component suppliers to niche technology innovators focusing on specific sensor types and applications. Dominant competitive moves include strategic partnerships for ecosystem integration and continuous portfolio diversification to address new application areas like EV battery management and smart agriculture. Capacity expansion in key manufacturing regions also remains a significant competitive lever.
Integrated semiconductor giants, such as Texas Instruments, exemplify the broad-portfolio archetype, offering extensive sensor solutions that leverage their wider component ecosystems. Sensirion AG, a Swiss-based company, represents the specialized innovator archetype, focusing on CMOS-MEMS based sensor components for high performance in compact designs. Meanwhile, STMicroelectronics, a prominent European semiconductor manufacturer, anchors the MEMS technology segment, particularly for industrial and automotive end-users requiring robust and certified solutions. These companies collectively illustrate the market's segmentation by technological specialization and integration capability.
| Leading Market Players |
|---|
| Analog Devices, Inc |
| Honeywell International |
| Texas Instruments |
| Sensirion AG |
| STMicroelectronics |
| TE Connectivity |
| NXP Semiconductors |
| Robert Bosch GmbH |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Semiconductor-grade silicon volatility, primarily sourced from Asian fabrication facilities, directly influences the cost structure and margin pools for digital temperature and humidity sensor manufacturers. This upstream concentration impacts downstream pricing power.
Pricing Analysis
The MEMS-based sensor technology generation commands a premium over established capacitive or thermistor-based solutions. Pricing stratifies across performance tiers, with certified sensors for pharmaceutical storage and automotive applications commanding higher prices due to stringent regulatory compliance. Volume scale and after-sales service bundling also differentiate pricing. Pricing softness in the consumer electronics segment is intensifying because multi-function environmental ICs offer lower-cost alternatives, making this segment highly price-sensitive compared to industrial users.
Supply Chain Analysis
Upstream feedstock for digital temperature and humidity sensors relies heavily on semiconductor manufacturing in Taiwan, South Korea, and China. Key component dependencies include specialized silicon wafers, integrated circuits, and packaging materials. Commodity price volatility for semiconductor-grade silicon presents a structural supply chain risk. Distribution runs through a mix of direct manufacturer-to-OEM sales and specialized electronics distributors, particularly for high-volume consumer electronics applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense, with integrated environmental ICs presenting a named substitute threat that incumbents must navigate.
For Market Incumbents: Build an intellectual property moat through continuous R&D in CMOS-MEMS integration and on-chip AI processing. This defends against margin pressure from lower-cost alternatives and addresses the threat of commoditization. Investing in accredited metrology labs and expanding certification capabilities, especially for FDA and EMA compliance, strengthens market position in critical applications like pharmaceutical cold chain monitoring.
For New Entrants and Emerging Players: Build out specialized sensor solutions targeting underpenetrated niches such as smart agriculture in Southeast Asia, particularly Vietnam and Thailand. These regions offer white-space opportunities due to expanding electronics and food processing sectors. A go-to-market angle focused on providing pre-calibrated, certified sensors with seamless legacy system integration can facilitate rapid adoption.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap specialized sensor manufacturers possessing strong MEMS or CMOS-MEMS expertise. These firms often hold proprietary calibration technologies or niche application certifications. Long-term viability hinges on their ability to scale production while maintaining high accuracy and compliance. A signal to watch is the increasing patent activity in on-chip AI for predictive maintenance applications.
| Strategic Initiative | Industry Significance |
|---|---|
| CMOS-MEMS Integration | Reduces sensor footprint and power consumption, enabling new applications in compact IoT devices. |
| On-Chip AI Development | Enables predictive analytics at the edge, reducing reliance on cloud infrastructure for fault detection. |
| Certification Expansion | Ensures compliance with divergent international standards, crucial for market access in regulated industries. |
| Southeast Asia Market Entry | Captures demand from expanding electronics manufacturing and food processing sectors in Vietnam. |
| Strategic Partnerships | Leverages broad semiconductor portfolios for integrated solutions, enhancing competitive offerings. |
Research Approach
Findings reconcile primary fieldwork against secondary review of academic journals, corporate annual reports, and regulatory filings from the FDA, EMA, and China's GB standards agency. This involved detailed conversations with sensor design engineers, procurement leads at HVAC and automotive OEMs, and quality assurance managers in pharmaceutical companies. Bottom-up data from specific product segments validated top-down market sizing estimates.
Forecast inputs considered technology adoption curves, regulatory compliance timelines, and macroeconomic growth projections over the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, and end-user, alongside regional market dynamics. Compound Annual Growth Rates were derived from historical data trends and projected future demand, with EV battery management and smart agriculture representing key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated semiconductor giants or specialized MEMS innovators would shift outcomes. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Cross-checking against national statistical agency data and industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Digital Electronic Thermometers Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
Global E-Compass Market
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
Temperature Transmitter Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
Machine Control System Market