
 Hospital Acquired Infections Market | 2026-2036
Hospital Acquired Infections Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Acquired Infections Market Intelligence
The customer base for hospital acquired infection control products is broadening beyond large hospitals to include outpatient surgical centers and independent diagnostic laboratories. This fragmentation of purchasing power requires more flexible supply chain strategies from manufacturers. Getinge AB sustains its position through its portfolio of large-scale sterilization equipment for major medical centers. Meanwhile, 3M Company leverages its material science background to offer specialized antimicrobial coatings and protective apparel.
Hospital acquired infections are infections contracted by a patient during their stay in a healthcare facility, which were not present at admission. These control solutions specifically target pathogens like MRSA and C. difficile through methods designed to interrupt transmission pathways. In terms of product types, sterilization equipment and disinfectants constitute mature, high-volume categories. Conversely, the market for advanced diagnostic kits and nanotechnology-based solutions is expanding rapidly to meet demands for faster, more accurate detection and prevention.
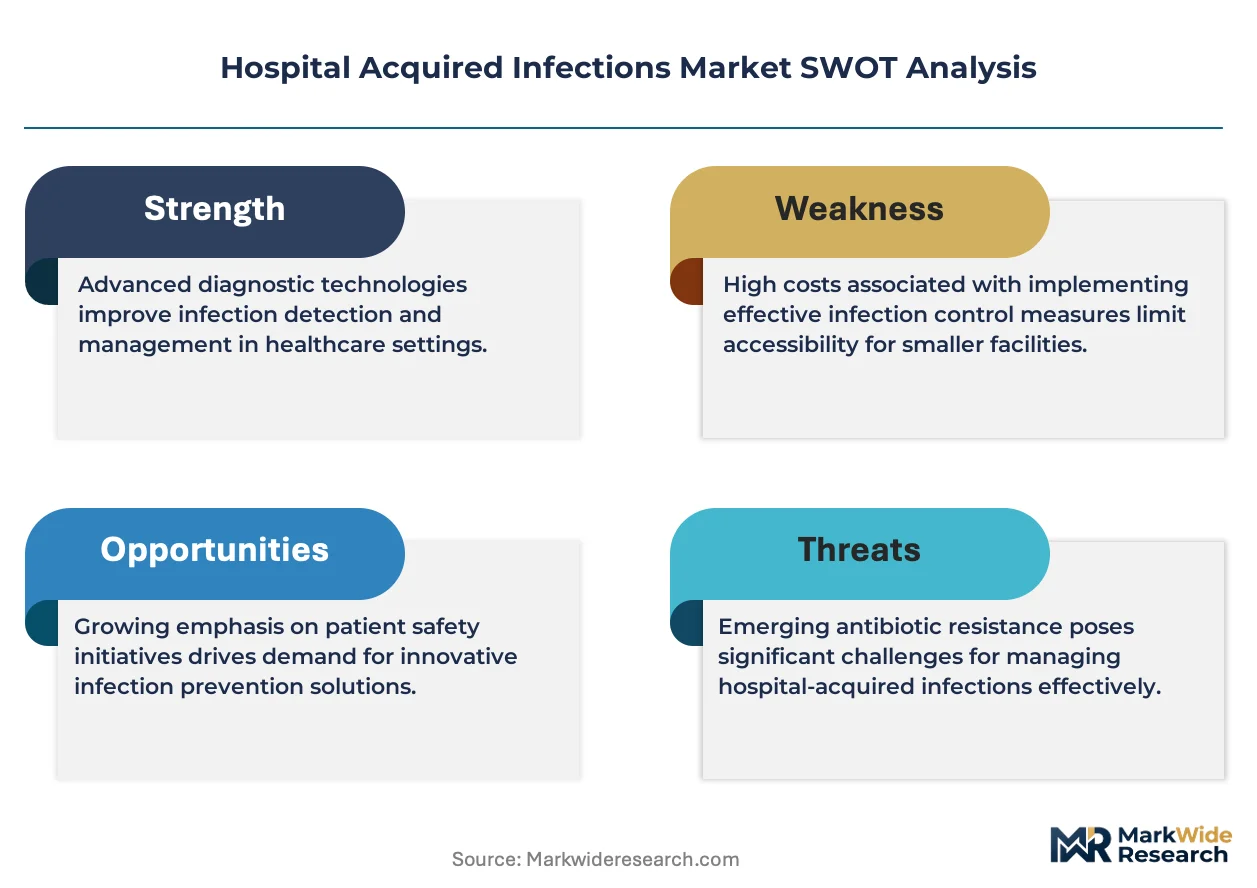
Regulatory oversight from the US FDA and the European Medicines Agency (EMA) governs the marketing authorization for disinfectants and medical devices. Concurrently, infection control guidelines issued by the World Health Organization (WHO) and national bodies like Germany's Robert Koch Institute shape hospital procurement protocols. The critical decision for providers centers on balancing investments between rapid diagnostic kits for early detection and advanced sterilization equipment for comprehensive prevention.
Market Dynamics
The central dynamic shaping the market is the fragmentation of the customer base. Demand is expanding beyond large, centralized hospitals to include a growing number of smaller outpatient surgical centers and independent diagnostic laboratories, requiring more flexible and responsive supply chain strategies.
Growth Catalysts
- Stricter Infection Control Mandates:Guidelines from bodies like the World Health Organization and Germany's Robert Koch Institute are compelling healthcare facilities to adopt more rigorous hygiene and sterilization protocols, directly driving procurement of control products.
- Advanced Diagnostics:The availability of rapid diagnostic kits for pathogens like MRSA enables earlier detection and targeted intervention. This reduces transmission rates within Intensive Care Units and other high-risk environments, stimulating demand for testing technologies.
- Aging Demographics:In countries with older populations, such as Japan and across Western Europe, a higher prevalence of chronic diseases and longer hospital stays increases patient susceptibility to infections, elevating the baseline demand for prevention measures.
Market Restraints
- High Capital Costs:The significant upfront investment required for large-scale sterilization equipment, such as autoclaves, presents a substantial budget barrier for smaller clinics and healthcare facilities in resource-constrained regions.
- Microbial Resistance:The evolution of antibiotic-resistant bacteria and reduced efficacy of some chemical disinfectants against pathogens like C. difficile forces continuous investment in research and development, making product lifecycles shorter.
- Regulatory Hurdles:Lengthy and complex approval pathways for new antimicrobial agents and medical devices, governed by regulators like the US FDA and the European Medicines Agency, can delay the introduction of innovative solutions to the market.
Strategic Opportunities
- Expansion in Emerging Markets:Modernization of healthcare infrastructure in countries across Asia-Pacific and Latin America creates significant white-space opportunities for suppliers of infection control solutions as new hospitals and clinics are built to higher standards.
- Smart Antimicrobial Surfaces:The integration of nanotechnology-based coatings with IoT sensors presents an opportunity to develop intelligent surfaces that not only kill pathogens but also provide real-time data on contamination levels and cleaning compliance.
- Direct-to-Clinic Channels:Developing direct sales and distribution channels to serve outpatient surgical centers and diagnostic labs allows manufacturers to capture a growing, fragmented customer segment that is often bypassed by traditional hospital-focused procurement.
Industry Challenges
- Ensuring Protocol Compliance:A primary operational challenge is ensuring consistent and correct adherence to complex infection control protocols among healthcare staff across diverse and often disconnected settings, from large hospitals to small independent clinics.
- Supply Chain Adaptation:Manufacturers face the logistical challenge of adapting supply chains designed for large, bulk hospital orders to also serve the smaller, more frequent, and geographically dispersed orders from outpatient and diagnostic facilities.
- Data System Integration:Integrating new, rapid diagnostic testing platforms with legacy Hospital Information Systems (HIS) creates a significant technical hurdle, complicating workflow and data management for healthcare providers seeking to leverage real-time results.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Acquired Infections Market |
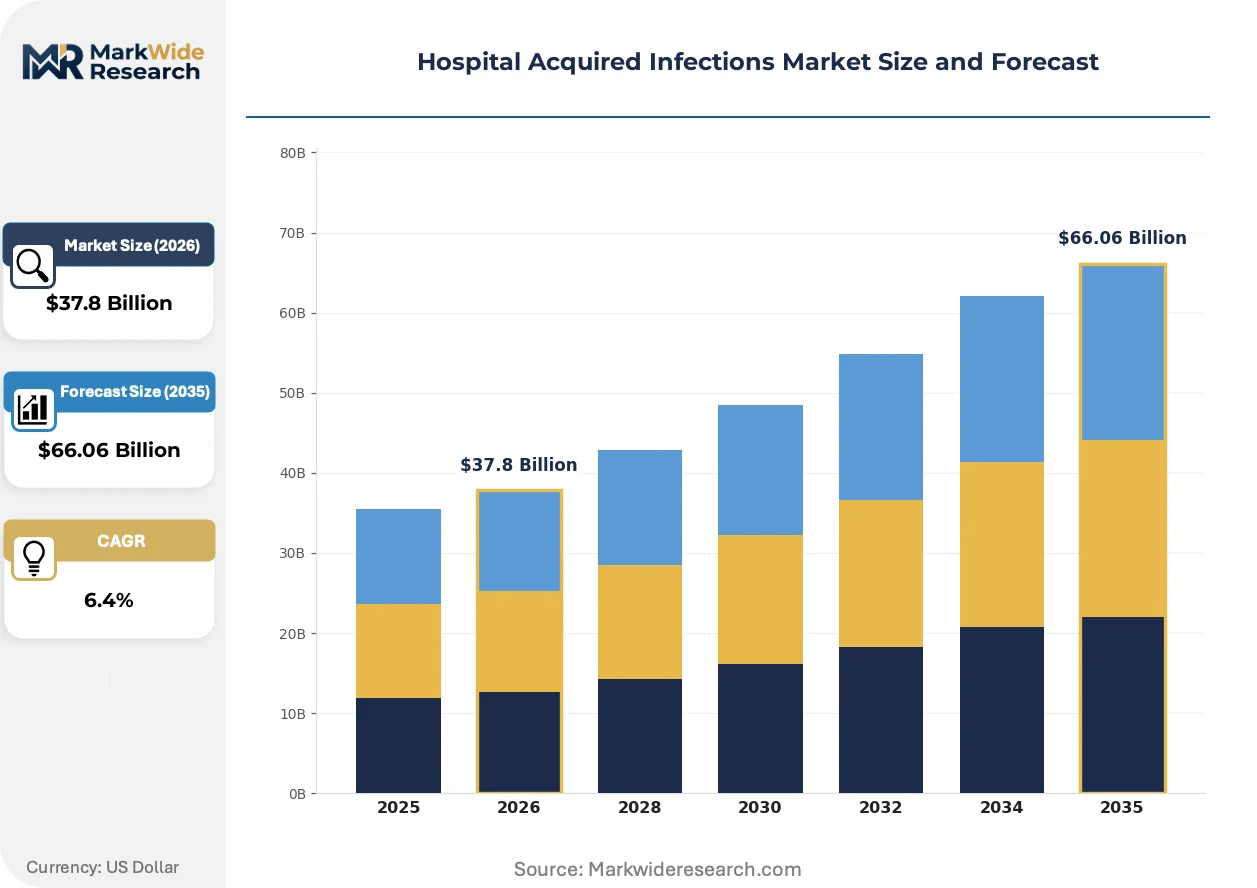
| Market Size in 2026 | $37.8 Billion |
| Market Size in 2035 | $66.06 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobial Coatings, Disinfectants, Diagnostic Kits, Protective Apparel, Sterilization Equipment Infection Type: Bloodstream Infections, Surgical Site Infections, Urinary Tract Infections, Pneumonia, Gastrointestinal Infections End User: Patient Care Units, Diagnostic Laboratories, Intensive Care Units, Surgical Centers, Emergency Departments Treatment Technology: Antibiotic Therapy, Photodynamic Therapy, Immunotherapy, Probiotic Treatment, Nanotechnology-Based Solutions |
| Companies Covered | STERIS plc, 3M Company, Getinge AB, Ecolab Inc., Advanced Sterilization Products, Belimed AG, Becton, Dickinson and Company, Kimberly-Clark Corporation, Midmark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Acquired Infections Market Strategic Shifts & Innovations
The market's focus is pivoting from reactive treatment toward proactive, system-wide prevention. This evolution is driven by the fusion of advanced material science with data analytics and is reinforced by more stringent public health mandates across developed economies.
Nanotechnology-based coatings are creating self-disinfecting surfaces that provide continuous antimicrobial action. High-traffic areas within hospitals in the United States and Germany are progressively adopting these materials for bed rails, IV poles, and door handles. This material science innovation is converging with smart building management systems, enabling facilities to monitor surface integrity and verify cleaning efficacy.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance on products used for infection control. This directive increases the compliance burden for manufacturers of sterilization equipment and diagnostic kits aiming for market access in Europe. The sterilizer segment is particularly affected, as companies must now generate more extensive data to maintain their CE marking.
A notable behavioral shift involves healthcare providers demanding comprehensive infection control programs rather than just purchasing standalone products. This change disrupts the traditional transactional sales model for consumables like disinfectants, creating an advantage for suppliers offering bundled contracts that include products, staff training, and compliance monitoring. This trend is most prominent in large hospital networks in North America seeking to guarantee infection rate reductions.
Hospital Acquired Infections Market Segmentation
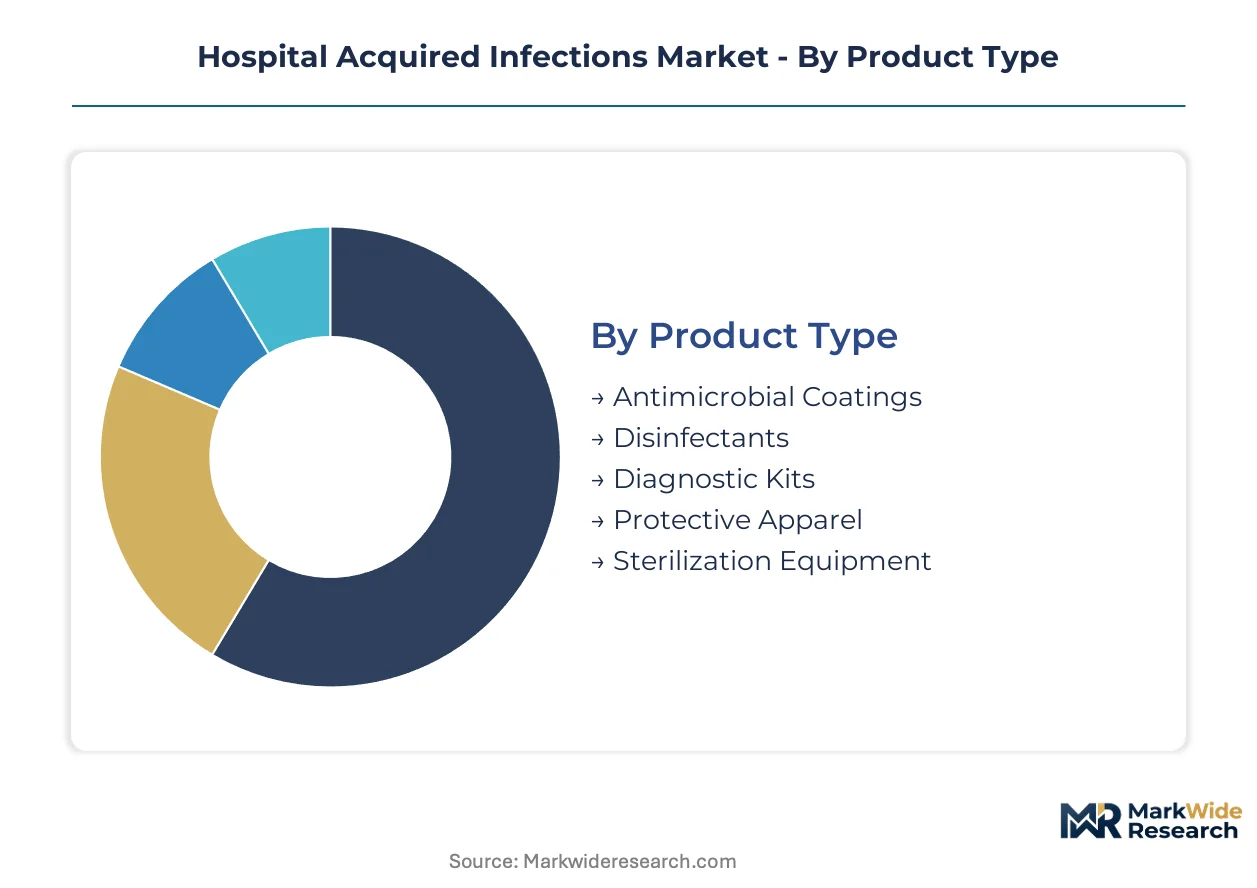
The Hospital Acquired Infections market segmentation provides a granular view of the diverse product offerings, infection types, end-user settings, and technological approaches employed in preventing and controlling healthcare-associated infections. Understanding these distinct segments is crucial for manufacturers to tailor solutions and for providers to optimize procurement strategies for comprehensive infection management.
Product Type:
Product Type segmentation examines the functional characteristics and material science innovations integrated into infection control solutions.
- Sterilization Equipment:Large-scale autoclaves and specialized decontamination systems provide comprehensive microbial eradication for reusable medical instruments. Major medical centers in Germany prioritize these systems to meet stringent hygiene protocols and ensure patient safety.
- Diagnostic Kits:Molecular assays and immunoassay-based kits offer rapid identification of specific pathogens like MRSA, enabling timely intervention. Intensive Care Units in the United States increasingly deploy these kits for early detection to reduce transmission rates.
- Antimicrobial Coatings:Nanotechnology-based solutions create self-disinfecting surfaces for high-traffic areas within healthcare environments.
- Disinfectants:Chemical agents are widely used for surface sanitation and environmental cleaning across diverse healthcare facilities.
- Protective Apparel:Personal protective equipment, including gowns and masks, forms a critical barrier against pathogen transmission for healthcare staff.
Sterilization Equipment leads on scale; Diagnostic Kits lead on momentum.
Infection Type:
Infection Type segmentation delineates control efforts based on the specific clinical manifestations and pathogen pathways within healthcare settings.
- Surgical Site Infections:Directly linked to invasive procedures, these infections require rigorous pre- and post-operative sterilization protocols and wound care. Outpatient surgical centers across Western Europe focus on preventing SSIs to maintain patient safety and reduce readmissions.
- Urinary Tract Infections:Often associated with catheter use, UTIs necessitate strict aseptic techniques and targeted antimicrobial interventions. Patient Care Units in Japan emphasize UTI prevention due to their aging demographic's increased susceptibility.
- Bloodstream Infections:These severe infections demand rapid diagnostic intervention and immediate treatment within critical care settings.
- Pneumonia:Hospital-acquired pneumonia, particularly ventilator-associated, requires specialized respiratory hygiene and continuous monitoring.
- Gastrointestinal Infections:Pathogens like C. difficile cause these infections, necessitating enhanced environmental cleaning and isolation measures to control spread.
Surgical Site Infections dominate prevention efforts; Bloodstream Infections require targeted rapid solutions.
End User:
End User segmentation reflects the diverse operational environments and specific patient populations requiring infection control.
- Intensive Care Units:These units house critically ill patients highly susceptible to infections, driving demand for advanced sterilization and rapid diagnostics. ICUs in the United States implement comprehensive infection control programs due to high patient acuity and stringent regulatory oversight.
- Surgical Centers:Both inpatient and outpatient centers require stringent aseptic environments to prevent surgical site infections during procedures. Outpatient surgical centers in Germany are increasingly adopting flexible supply chain strategies for infection control products.
- Patient Care Units:General wards require consistent application of disinfectants and protective apparel for routine patient care and environmental hygiene.
- Diagnostic Laboratories:These facilities use specialized diagnostic kits for pathogen identification, influencing early intervention strategies for patients.
- Emergency Departments:High patient turnover and diverse pathogen exposure necessitate rapid disinfection and protective measures to prevent transmission.
Intensive Care Units are central to comprehensive prevention; Diagnostic Laboratories are experiencing significant expansion.
Treatment Technology:
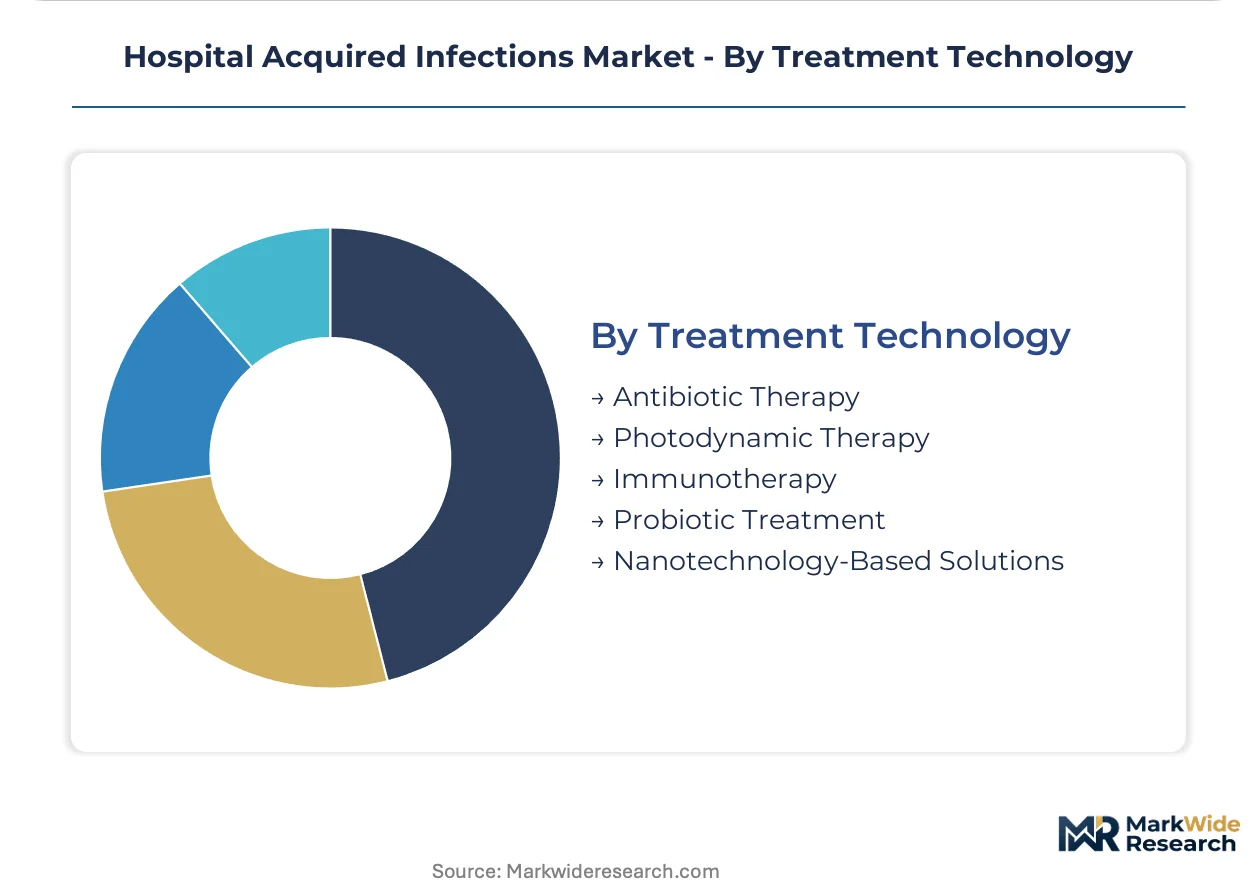
Treatment Technology segmentation categorizes solutions by their underlying scientific principles and therapeutic mechanisms for infection control.
- Nanotechnology-Based Solutions:These advanced materials offer self-disinfecting surfaces and targeted antimicrobial delivery, representing a prevention paradigm shift. Coatings embedded with silver nanoparticles provide continuous pathogen inactivation in high-touch areas.
- Antibiotic Therapy:While primarily a treatment, the judicious use of antibiotics is crucial in managing existing infections and preventing their spread. Targeted antimicrobial agents are administered based on pathogen identification and resistance profiles.
- Photodynamic Therapy:This emerging technology uses light-activated compounds to destroy pathogens, offering a non-antibiotic approach for localized infections.
- Immunotherapy:Approaches leveraging the body's immune response are being explored for preventing and treating specific infections in vulnerable populations.
- Probiotic Treatment:Modulating the microbiome with beneficial bacteria can help prevent pathogen colonization in susceptible patients, particularly in gastrointestinal contexts.
Antibiotic Therapy remains a foundational approach; Nanotechnology-Based Solutions are driving future innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A highly skilled healthcare workforce and robust research infrastructure anchor demand in several key global regions for hospital acquired infection control products. These regions prioritize patient safety and advanced diagnostic capabilities. Stringent regulatory frameworks further compel investment in prevention technologies.
United States
The United States market sees high demand for rapid diagnostic kits within Intensive Care Units. The US FDA regulates medical devices and disinfectants, ensuring product efficacy and safety. Major biotech hubs like Boston focus on developing next-generation pathogen detection systems.
Germany
Germany's advanced healthcare system and aging population drive consistent demand for sterilization equipment. The Robert Koch Institute's guidelines mandate comprehensive infection control protocols across facilities. Medical technology clusters in Bavaria actively develop innovative antimicrobial solutions.
Japan
Japan's significantly aging demographic increases susceptibility to infections, particularly urinary tract infections. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees product approvals for infection control solutions. Healthcare technology firms in Tokyo innovate patient care unit hygiene protocols and environmental cleaning.
China
China's ongoing healthcare infrastructure modernization creates substantial opportunities for infection control suppliers. The National Medical Products Administration (NMPA) sets standards for medical devices and disinfectants. Manufacturing centers in the Yangtze River Delta produce a growing array of sterilization equipment and protective apparel for new facilities.
Hospital Acquired Infections Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the hospital acquired infections market. The landscape features large entities offering broad portfolios alongside niche providers concentrating on specific technologies like nanotechnology or advanced diagnostics. Strategic partnerships and targeted acquisitions are common competitive moves, alongside continuous portfolio diversification.
Large industrial players, often with global reach, occupy a significant position in the market. Companies like 3M Company and STERIS plc exemplify this archetype, leveraging extensive material science and sterilization expertise to serve a broad client base. Getinge AB, a Sweden-based corporation, also sits within this tier, focusing on large-scale medical equipment for major medical centers and maintaining its position through comprehensive offerings.
| Leading Market Players |
|---|
| STERIS plc |
| 3M Company |
| Getinge AB |
| Ecolab Inc. |
| Advanced Sterilization Products |
| Belimed AG |
| Becton, Dickinson and Company |
| Kimberly-Clark Corporation |
| Midmark Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps in sterilization equipment maintain pricing discipline through long-standing hospital contracts. Their specialized manufacturing processes and regulatory compliance influence global supply availability and cost structures.
Pricing Analysis
Bundled service contracts increasingly define pricing in the hospital acquired infections market, moving beyond transactional product sales. Value-based pricing models reward suppliers for demonstrated infection rate reductions. Price differentiation stems from after-sales service quality and specific product certification levels, such as CE marking or FDA approval. Pricing pressure stems from cost compression in high-volume disinfectants due to commodity input fluctuations. Smaller outpatient surgical centers often exhibit greater price sensitivity compared to large hospital networks with dedicated procurement budgets.
Supply Chain Analysis
Regulatory certification and qualification requirements gate access to the hospital acquired infections supply chain, particularly for medical devices. Geographic supply concentrates manufacturing in China for protective apparel and Germany for advanced sterilization equipment, with Japan providing specialized diagnostic components. Raw material dependencies include specialty chemicals for disinfectants and advanced polymers for antimicrobial coatings. Single-source vulnerability for proprietary nanotechnology-based solutions presents a structural supply chain risk. Distribution runs through traditional group purchasing organizations for large hospitals, while direct-to-clinic channels are expanding for smaller facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hospital acquired infections market presents a geographic-arbitrage opportunity, as stricter EU MDR compliance costs in Europe drive manufacturing shifts to regions with less burdensome regulatory frameworks.
For Market Incumbents: Deepen portfolio integration by offering comprehensive infection control programs, not just standalone products. Invest in R&D for next-generation antimicrobial surfaces to counter the threat of rapidly evolving microbial resistance. Strengthen channel control through direct-to-clinic sales to capture fragmented customer segments. Prioritize investment in advanced sterilization equipment to maintain a competitive edge in major medical centers.
For New Entrants and Emerging Players: Nanotechnology-based solutions present a technology-first wedge for new entrants targeting high-value niche applications. Focus on developing smart antimicrobial surfaces with IoT integration or rapid diagnostic kits for emerging pathogens. Outpatient surgical centers represent the most penetrable segment due to their need for flexible and cost-efficient solutions. Implement a direct sales model emphasizing compliance and demonstrable efficacy for smaller facilities.
For Investors and Strategic Acquirers: Private equity firms are the most active acquirers in this space, seeking to consolidate fragmented diagnostic and specialized treatment providers. The market offers long-term viability driven by aging populations and ongoing healthcare infrastructure modernization. Target mid-sized firms with proprietary nanotechnology or advanced diagnostic platforms. Accelerated FDA or EMA approvals for novel prevention technologies will serve as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop comprehensive infection control programs | Hospital networks in North America demand bundled solutions to guarantee infection rate reductions. |
| Invest in nanotechnology-based antimicrobial surfaces | High-traffic areas in German hospitals are progressively adopting these materials for continuous pathogen inactivation. |
| Expand direct-to-clinic distribution channels | Outpatient surgical centers require flexible supply chain strategies for infection control products. |
| Pursue strategic acquisitions of diagnostic firms | Early detection of pathogens like MRSA enables timely intervention within Intensive Care Units. |
| Obtain CE Marking under EU MDR for sterilization equipment | European market access for sterilization equipment depends on extensive clinical evidence. |
Research Approach
Direct dialogue with hospital procurement managers, infection control specialists, and medical device manufacturers formed the primary data foundation. This qualitative grounding was combined with secondary validation from World Health Organization guidelines, US FDA submissions, and national health agency reports. The methodology ensured bottom-up and top-down triangulation across diverse data points.
Quantitative projections for the hospital acquired infections market were developed using a multi-factor analytical framework across the analysis window. The model segmented by product type, infection type, end-user, and treatment technology, incorporating regional regulatory changes. Compound annual growth rates were derived from historical trends and projected technological advancements. Patient demographics and healthcare expenditure served as key forecast inputs.
The model holds under current healthcare spending patterns and regulatory stability; deviation in pandemic severity or antimicrobial resistance evolution would shift projections. Forecasts reflect assumptions regarding technological adoption and market dynamics. A model refresh is warranted upon material change in global public health mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Preventable Vaccines Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Medical Activated Carbon Dressing Market
Infection Control
Hand Hygiene Products Market
Infection Control
Sterilization Monitoring Market
Infection Control
Global Dental Infection Control Products Market
Infection Control
Botulism Market
Infection Control
Antimicrobial Suture Market
Infection Control
Patient Hygiene Aids Market
Infection Control
Blood Stream Infection Testing Market
Infection Control
Surgical Site Infection Control Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Sterility Indicators Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Intra Abdominal Infection Market