
 Europe Ultrasound Probe Disinfection Market | 2026-2036
Europe Ultrasound Probe Disinfection Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ultrasound Probe Disinfection Market Foresight
Subscription-based reprocessing software is recalibrating how disinfection vendors monetize probe hygiene workflows across European healthcare networks. Germitec leverages its automated UV-C systems to anchor high-throughput hospital contracts in France and Spain. Nanosonics competes through specialized trophon devices that dominate obstetric and cardiac imaging departments. Siemens Healthineers extends its installed base advantage by bundling disinfection protocols with ultrasound hardware service agreements.
Ultrasound probe disinfection encompasses the chemical, thermal, or radiation-based elimination of pathogens from transducer surfaces between patient contacts, requiring compatibility with materials such as silicone, latex, and thermoplastic elastomers while preserving acoustic coupling properties. Automated systems lead product type demand where throughput constraints and traceability requirements concentrate margin pools, while ultraviolet light technology captures fastest-growing adoption as hospitals phase out aldehyde-based chemistries. Diagnostic imaging centers represent the most expansion-ready end user segment as independent operators face rising accreditation pressure.
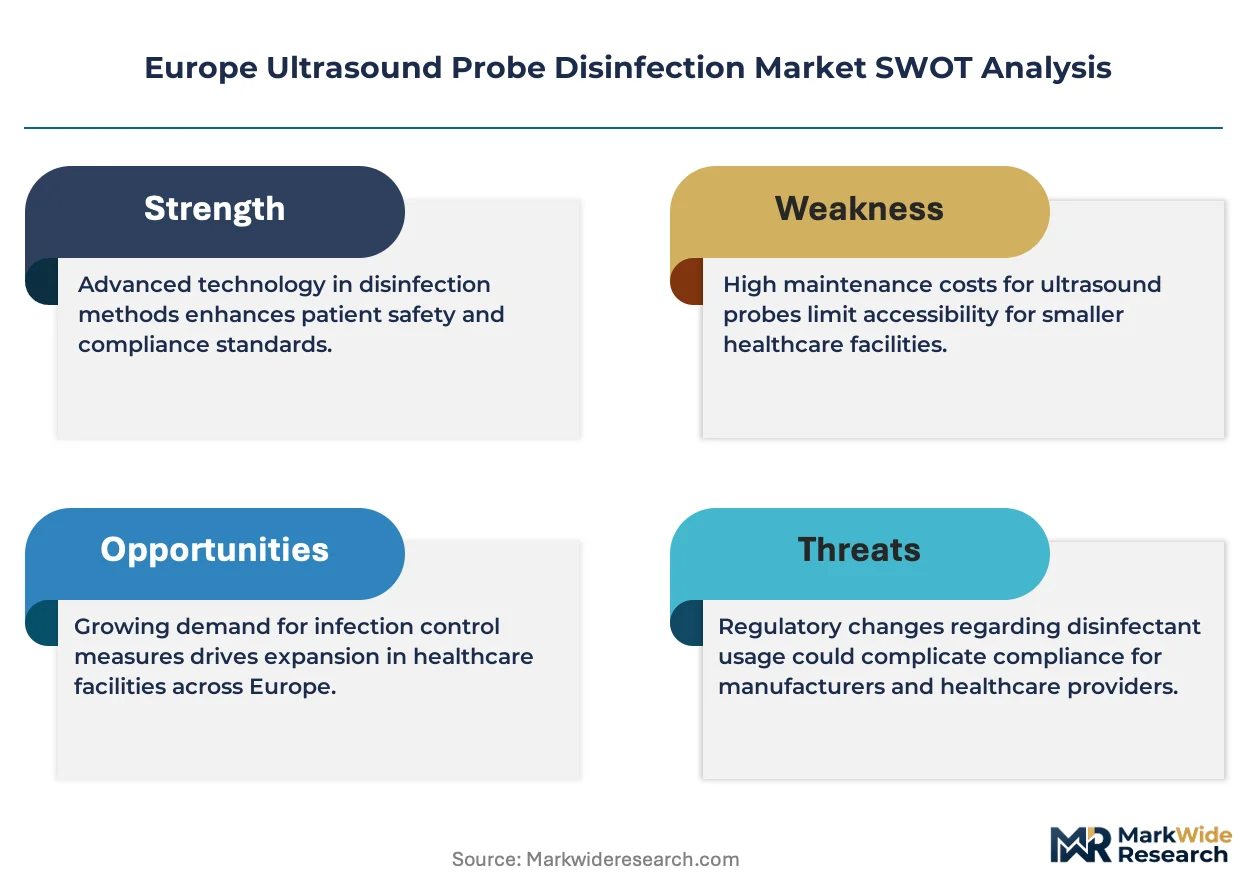
EMA device sanitation guidelines, ECHA biocidal product regulations under BPR 528/2012, and EU MDR conformity requirements collectively mandate validated reprocessing documentation and residue testing that elevates automated system demand over manual wipes. France's ANSM and Germany's BfArM enforce hospital-acquired infection reporting that ties probe hygiene to reimbursement eligibility. Stakeholders must monitor pending EU Green Deal amendments to chemical disinfectant classifications that could disqualify current formulations before the decade closes.
Market Dynamics
Automated UV-C disinfection systems are compressing manual chemical workflows across European maternity wards and cardiac imaging departments, forcing vendors to rebuild service architectures around traceability software and subscription monetization.
Growth Catalysts
- ECHA BPR 528/2012:Biocidal product regulations are accelerating hospital transitions from aldehyde-based chemistries to validated automated systems with residue documentation.
- France ANSM reporting mandates:Mandatory hospital-acquired infection disclosure ties probe hygiene protocols directly to reimbursement eligibility in maternity networks.
- UV-C technology maturation:Advances in mercury-free lamp systems and cycle-time optimization are displacing hydrogen peroxide vapor in high-throughput German diagnostic centers.
Market Restraints
- Capital intensity:Automated disinfection systems require upfront hardware investments that strain independent imaging center budgets.
- Supply concentration:UV-C lamp components concentrate among East Asian semiconductor foundries, exposing European vendors to input bottlenecks.
- Material incompatibility:Certain thermoplastic elastomer probe housings degrade under sustained UV-C exposure, limiting device applicability.
Strategic Opportunities
- Spain diagnostic imaging expansion:Independent ultrasound operators face rising accreditation pressure from regional health authorities, creating automated system demand.
- EU Green Deal amendments:Pending chemical disinfectant reclassifications before decade-end will disqualify current quaternary ammonium formulations.
- Software-hardware convergence:Integration of RFID traceability with hospital information systems enables outcome-based service contracting.
Industry Challenges
- Validation timeline compression:EU MDR conformity documentation requirements extend product certification cycles by 12-18 months.
- Legacy system integration:Automated disinfection workflows must interface with existing ultrasound fleet management software from multiple OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ultrasound Probe Disinfection Market |
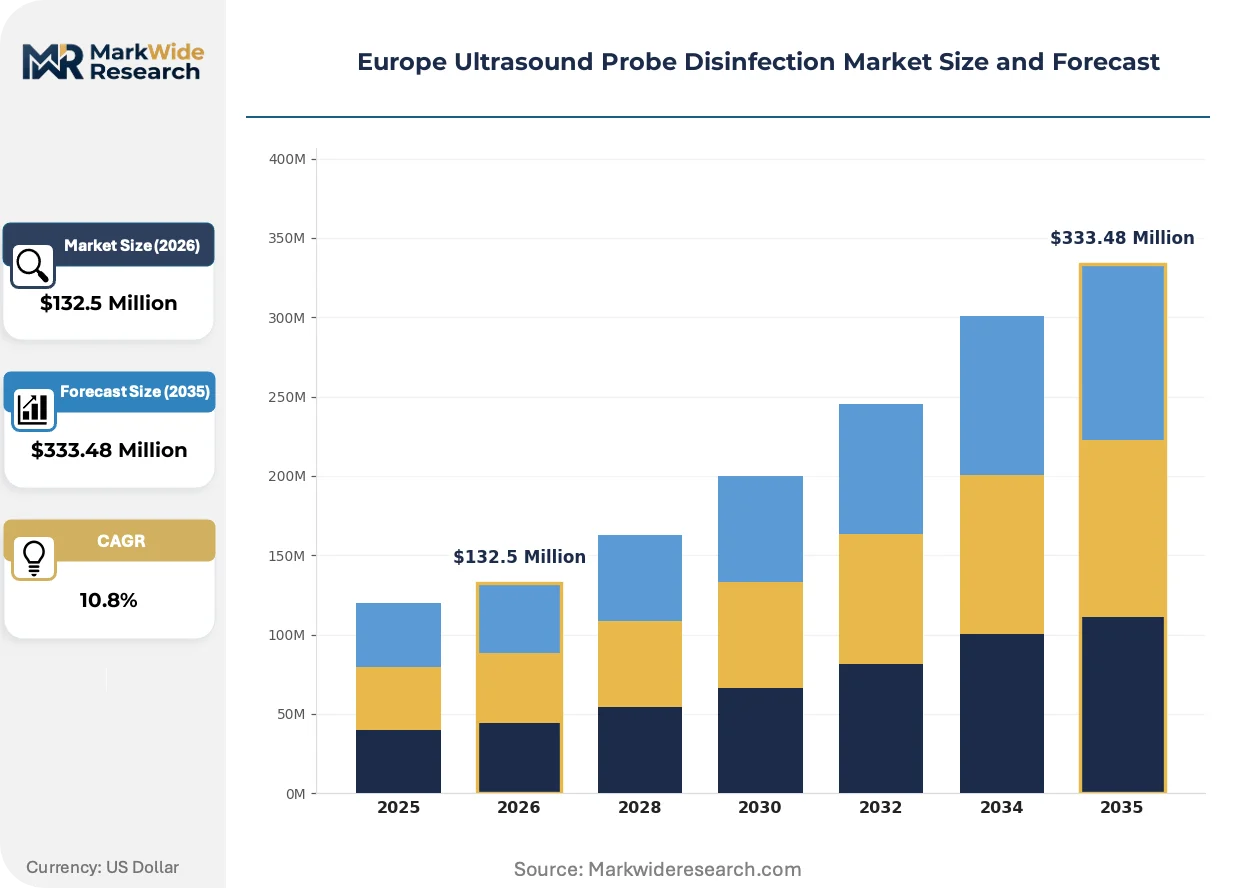
| Market Size in 2026 | $132.5 Million |
| Market Size in 2035 | $333.48 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Wipes, Liquid Disinfectants, Sterilization Trays End User: Hospitals, Clinics, Diagnostic Imaging Centers, Veterinary Facilities Application: Pregnancy Scanning, Cardiac Imaging, Abdominal Imaging, Emergency Services Technology: Ultraviolet Light, Chemical Agents, Thermal Methods, Hydrogen Peroxide Vapors |
| Companies Covered | Germitec, CIVCO Medical Solutions, Nanosonics, Koninklijke Philips, Siemens Healthineers, STERIS, Tristel Plc, GE HealthCare Technologies, Ecolab, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ultrasound Probe Disinfection Market Shifts & Advancements
Probe hygiene workflows are fragmenting from centralized sterile processing departments toward point-of-care automation, compressing reprocessing time windows while elevating documentation requirements.
UV-C disinfection technology is decentralizing probe reprocessing from remote sterile supply departments to imaging suites and bedside locations. Cardiac catheterization labs and obstetric emergency departments are adopting compact automated cabinets that complete high-level disinfection in under three minutes. This shift is compressing capital allocation toward distributed units rather than centralized high-capacity systems.
EU MDR Article 10 post-market surveillance requirements are mandating real-time reprocessing documentation that traces individual probe serial numbers to patient encounters. Device manufacturers must now validate compatibility claims across automated system portfolios. French and German notified bodies are prioritizing audits of disinfection efficacy claims under the updated conformity assessment routes.
Subscription-based service contracts are displacing capital equipment purchases among mid-sized hospital networks. Independent imaging centers in the United Kingdom are bundling disinfection protocols with equipment leasing arrangements. This preference shift concentrates vendor margins in recurring software licenses and consumable supply chains rather than hardware margins.
Europe Ultrasound Probe Disinfection Market Segmentation
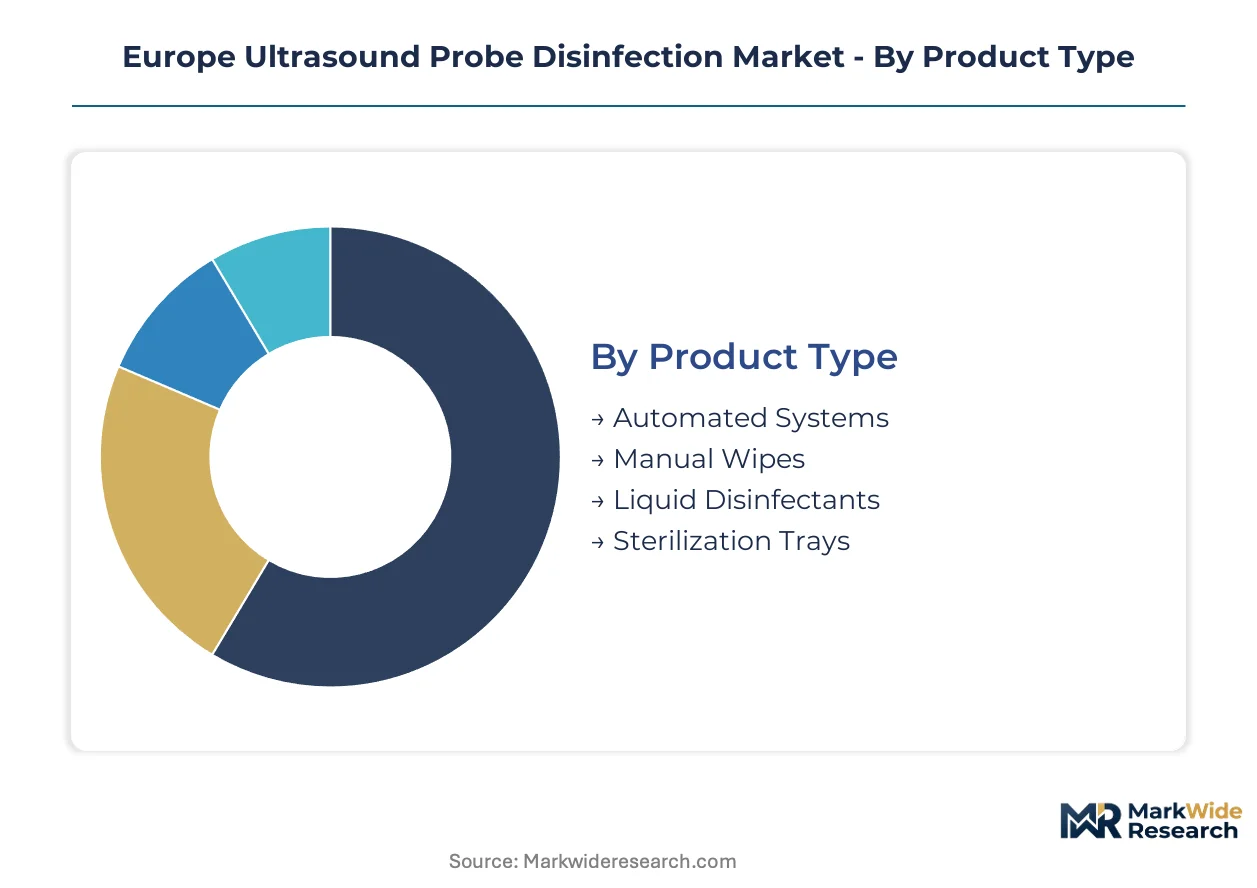
Ultrasound probe disinfection purchasing decisions hinge on throughput requirements, regulatory documentation burdens, and probe material compatibility. Segment boundaries blur as vendors bundle hardware, consumables, and software into integrated service contracts.
Product Type:
Capital allocation patterns separate high-throughput hospital networks from budget-constrained independent operators.
- Automated Systems:UV-C and hydrogen peroxide-based cabinets deliver validated high-level disinfection with automated cycle documentation. German maternity wards and French cardiac catheterization labs prioritize these units to satisfy ANSM and BfArM reporting mandates while compressing turnaround times.
- Manual Wipes:Pre-saturated towelettes containing quaternary ammonium or alcohol formulations serve low-volume settings and field deployments. United Kingdom independent imaging centers retain these for cost containment despite ECHA pressure to phase out certain biocidal actives.
- Liquid Disinfectants:Bulk refill solutions for manual immersion baths.
- Sterilization Trays:Steam or low-temperature hydrogen peroxide gas plasma containers for critical semi-invasive procedures.
Automated Systems lead on scale; Manual Wipes lead on installed base persistence despite regulatory headwinds.
End User:
Reimbursement eligibility rules and accreditation pressure create divergent procurement rhythms across facility types.
- Hospitals:Consolidated procurement through sterile processing departments favors enterprise-scale automated systems with RFID traceability. German hospital networks bundle disinfection protocols into ultrasound equipment service agreements to standardize compliance across merged entities.
- Diagnostic Imaging Centers:Independent operators face rising pressure from regional health authorities in Spain and Italy to achieve accreditation parity with hospital-based competitors. Subscription-based disinfection services gain traction here as capital constraints meet documentation requirements.
- Clinics:Smaller patient volumes sustain manual wipe protocols.
- Veterinary Facilities:Lower regulatory scrutiny permits simpler chemistries.
Hospitals concentrate procurement volume; Diagnostic Imaging Centers generate the steepest expansion trajectory for automated system vendors.
Application:
Probe contact classification—critical, semi-critical, non-critical—determines disinfection level requirements and equipment selection.
- Pregnancy Scanning:Transvaginal and transabdominal obstetric probes require high-level disinfection between patients. French maternity wards drive UV-C cabinet adoption following ANSM guidance linking probe hygiene to hospital-acquired infection reporting.
- Cardiac Imaging:Transesophageal echocardiography probes demand sterilization-equivalent processing. German cardiac centers favor automated hydrogen peroxide vapor systems with sub-three-minute cycles to maintain catheterization lab throughput.
- Abdominal Imaging:External surface probes tolerate intermediate-level disinfection.
- Emergency Services:Point-of-care ultrasound in ambulatory settings prioritizes speed.
Cardiac Imaging commands premium pricing; Pregnancy Scanning drives volume deployment across national health networks.
Technology:
Material compatibility constraints and residue elimination requirements filter technology adoption across probe portfolios.
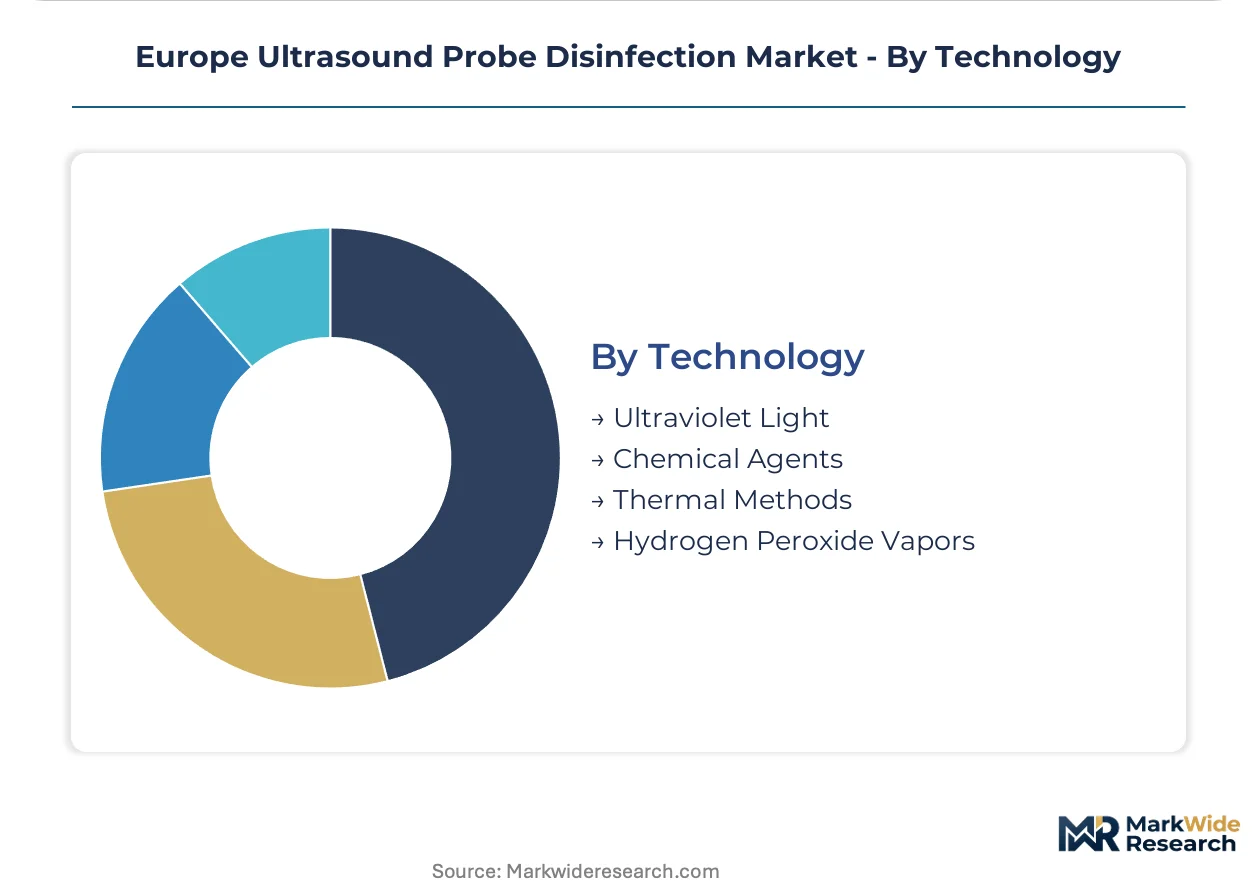
- Ultraviolet Light:Mercury-free UV-C LED systems eliminate aldehyde residues while preserving thermoplastic elastomer probe housings. Advances in lamp efficiency and cycle optimization displace chemical methods in high-throughput German diagnostic centers.
- Chemical Agents:Glutaraldehyde, ortho-phthalaldehyde, and peracetic acid formulations face ECHA BPR 528/2012 reauthorization pressure. French hospitals accelerate transitions away from these chemistries as residue testing requirements tighten.
- Thermal Methods:Automated pasteurization systems for heat-tolerant probe materials.
- Hydrogen Peroxide Vapors:Low-temperature sterilization for temperature-sensitive electronics.
Chemical Agents retain legacy installed base; Ultraviolet Light gains share fastest as biocide regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is compressing as ECHA BPR 528/2012 harmonizes compliance costs across member states, yet procurement patterns still diverge based on hospital network consolidation timelines and national infection reporting mandates.
Germany
BfArM enforcement of hospital-acquired infection disclosure drives automated system adoption in merged hospital networks. The country's medical device regulator mandates validated reprocessing documentation that elevates UV-C cabinet demand. Bavaria's cardiac catheterization clusters in Munich and Erlangen prioritize sub-three-minute cycle systems to maintain throughput.
France
ANSM reporting requirements tie probe hygiene directly to maternity ward reimbursement eligibility, accelerating automated disinfection deployment. The national medicines agency audits disinfection efficacy claims under updated EU MDR conformity routes. Paris and Lyon hospital networks standardize on traceability-integrated systems following regional health authority pressure.
United Kingdom
Independent imaging centers face accreditation parity demands from NHS England that compress capital budgets toward subscription disinfection services. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance documentation. London and Southeast imaging clusters bundle protocols with equipment leasing to circumvent upfront hardware costs.
Spain
Regional health authorities in Catalonia and Madrid impose accreditation standards on independent ultrasound operators that mirror hospital requirements. The Spanish Agency for Medicines and Health Products aligns with ECHA biocide reauthorization timelines. Barcelona diagnostic imaging expansion creates automated system demand among mid-sized private operators.
Italy
Lombardy and Emilia-Romagna hospital procurement consortia favor enterprise-scale automated systems with RFID traceability integration. The Italian Medicines Agency implements EU MDR documentation requirements that extend certification cycles. Milan's cardiac imaging centers adopt hydrogen peroxide vapor systems for transesophageal echocardiography probe processing.
Europe Ultrasound Probe Disinfection Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automated system vendors capturing margin pools in consolidated hospital networks while consumable suppliers retain persistence in independent settings. The vendor base concentrates around three strategic archetypes: UV-C technology specialists, chemical disinfection incumbents, and imaging OEMs bundling hygiene protocols with service agreements. Dominant competitive moves include backward integration into lamp component supply and software-hardware convergence for outcome-based contracting.
Among UV-C technology specialists, Germitec and Nanosonics occupy positions anchored to high-throughput hospital contracts and obstetric department penetration respectively. Siemens Healthineers exemplifies the imaging OEM archetype that leverages installed base advantages through bundled service agreements. Tristel Plc represents chemical disinfection incumbents navigating ECHA biocide reauthorization pressure through portfolio diversification.
| Leading Market Players |
|---|
| Germitec |
| CIVCO Medical Solutions |
| Nanosonics |
| Koninklijke Philips |
| Siemens Healthineers |
| STERIS |
| Tristel Plc |
| GE HealthCare Technologies |
| Ecolab |
| Others |
Supply & Pricing Matrix
Mercury-free UV-C LED lamp maturation is simultaneously compressing unit production costs and concentrating component sourcing among East Asian semiconductor foundries, reshaping how European vendors negotiate supply security against pricing power erosion.
Pricing Analysis
Distributor margin layers absorb 15-25 points before hospital procurement committees, compressing vendor net pricing. Three-tier pricing structure across premium, standard, and economy levels separates RFID-traceable automated cabinets from basic UV-C units and manual wipe consumables. Cost compression in economy tiers is intensifying because ECHA biocide reauthorization is forcing chemical wipe vendors into compliance investment. Independent imaging centers in the United Kingdom exhibit highest price sensitivity; consolidated German hospital networks leverage volume scale for least sensitivity.
Supply Chain Analysis
Refurbishment flows for UV-C lamp assemblies and hydrogen peroxide vapor generators concentrate service revenue with authorized depots in Germany and France, creating captive aftermarket economics. UV-C LED chips draw from Taiwan, South Korea, and Japan; thermoplastic elastomer probe housings source from Germany and Italy; hydrogen peroxide concentrate feeds from Belgian and Dutch chemical processors. Single-source vulnerability sits with mercury-free UV-C LED diode supply. Distribution runs through medical device distributors with sterile processing specialization, bypassing general hospital supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily because regulatory documentation mandates embed automated disinfection into hospital reimbursement eligibility, creating non-discretionary procurement cycles.
For Market Incumbents: Anchor enterprise-scale contracts through backward integration into UV-C LED component supply, insulating margin pools from East Asian input bottlenecks. Defend against chemical disinfection incumbents pivoting to automated portfolios by accelerating RFID-traceability software development. Certification investment in EU MDR Article 10 documentation capabilities extends competitive moats as validation timelines compress. For New Entrants and Emerging Players: Begin with Spain's independent diagnostic imaging centers, where accreditation pressure from regional health authorities meets capital constraints that favor subscription service models. Mid-sized private operators in Barcelona and Madrid represent the most penetrable segment. A software-first go-to-market angle—lead with traceability platform trials before hardware placement—circumvents upfront capital barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among chemical disinfection incumbents with ECHA BPR 528/2012 reauthorization exposure but automated system pipelines in development. Long-term viability frames around 5-10 year regulatory tailwinds embedding disinfection documentation into EU-wide hospital payment systems. Acquisition target archetype: UV-C technology specialists with installed base in French maternity networks. Monitor ECHA biocide reauthorization timelines for early signals of accelerated chemical-to-automated transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity documentation extends certification cycles for automated system vendors. |
| Hospital System Partnership | Bundled service agreements with Siemens Healthineers and Philips anchor high-throughput contracts. |
| Software Companion Development | RFID traceability integration with hospital information systems enables outcome-based contracting. |
| Backward Integration into UV-C LEDs | Captive diode supply insulates Germitec and Nanosonics from East Asian semiconductor bottlenecks. |
| Reimbursement Strategy | ANSM and BfArM reporting mandates tie probe hygiene directly to maternity ward payment eligibility. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract reviews, ECHA biocide registration filings, and UV-C technology patent landscapes — were reconciled through structured primary interviews with sterile processing department heads, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from EU MDR notified body audit records, ANSM hospital-acquired infection surveillance reports, BfArM device safety databases, and EMA device sanitation guidelines. Bottom-up installed base modeling and top-down healthcare expenditure allocation were cross-referenced for triangulation.
Historical adoption curves for automated disinfection systems were cross-referenced against panel input from 12 industry stakeholders across France, Germany, and the United Kingdom. Segmentation dimensions modeled include product type, end user facility scale, probe application criticality, and disinfection technology chemistry. CAGRs were derived from regression analysis of capital equipment replacement cycles and consumable attach rates. Industry-specific forecast inputs incorporated ECHA biocide reauthorization timelines and EU MDR implementation phase transitions.
Several conditions sit outside the modeled scope, including pending EU Green Deal amendments to chemical disinfectant classifications and unannounced UV-C LED efficiency breakthroughs. Forecasts reflect documented assumptions about hospital consolidation velocity and regulatory enforcement consistency. Practitioners should monitor ECHA BPR 528/2012 reauthorization decisions and ANSM audit priority shifts for early signals of demand acceleration or compliance cost revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Infection Control Market
Infection Control
Air Sanitizer Market
Infection Control
Global Hospital Infection Therapeutics Market
Infection Control
Global Dental Infection Control Products Market
Infection Control
Healthcare Protective Masks Market
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Infection Prevention Market
Infection Control
Surgical Site Infections Market
Infection Control
Intra-Abdominal Infection Treatment Market
Infection Control
Salivary Gland Infection Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Preventable Vaccines Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Disinfection Equipment Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market