
 Sterilization Monitoring Market | 2026-2036
Sterilization Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilization Monitoring Market Outlook
The migration from manual indicator reading to connected digital verification systems is narrowing the error window in load-release decisions. 3M leverages its embedded sensor portfolio to capture recurring consumable revenue across integrated hospital systems. Mesa Laboratories sustains a diversified instrument-and-service model that spans biological indicator incubation and software analytics. STERIS anchors its position through backward integration into sterilization equipment, creating captive demand for proprietary monitoring consumables.
Sterilization monitoring encompasses biological indicators containing defined populations of Geobacillus stearothermophilus or Bacillus atrophaeus spores, chemical indicators with calibrated color-change chemistry, and electronic integrators that measure multiple sterilization parameters in real time; these systems validate that sterilization cycles achieve specified lethality thresholds before medical devices or pharmaceutical components enter patient contact. Biological indicators command the highest trust level in terminal sterilization validation, though chemical indicators and integrators capture volume share in routine load monitoring where faster turnaround matters. Steam sterilization technology dominates installed base economics, while ethylene oxide monitoring carries premium pricing tied to lower-temperature pharmaceutical and device applications.
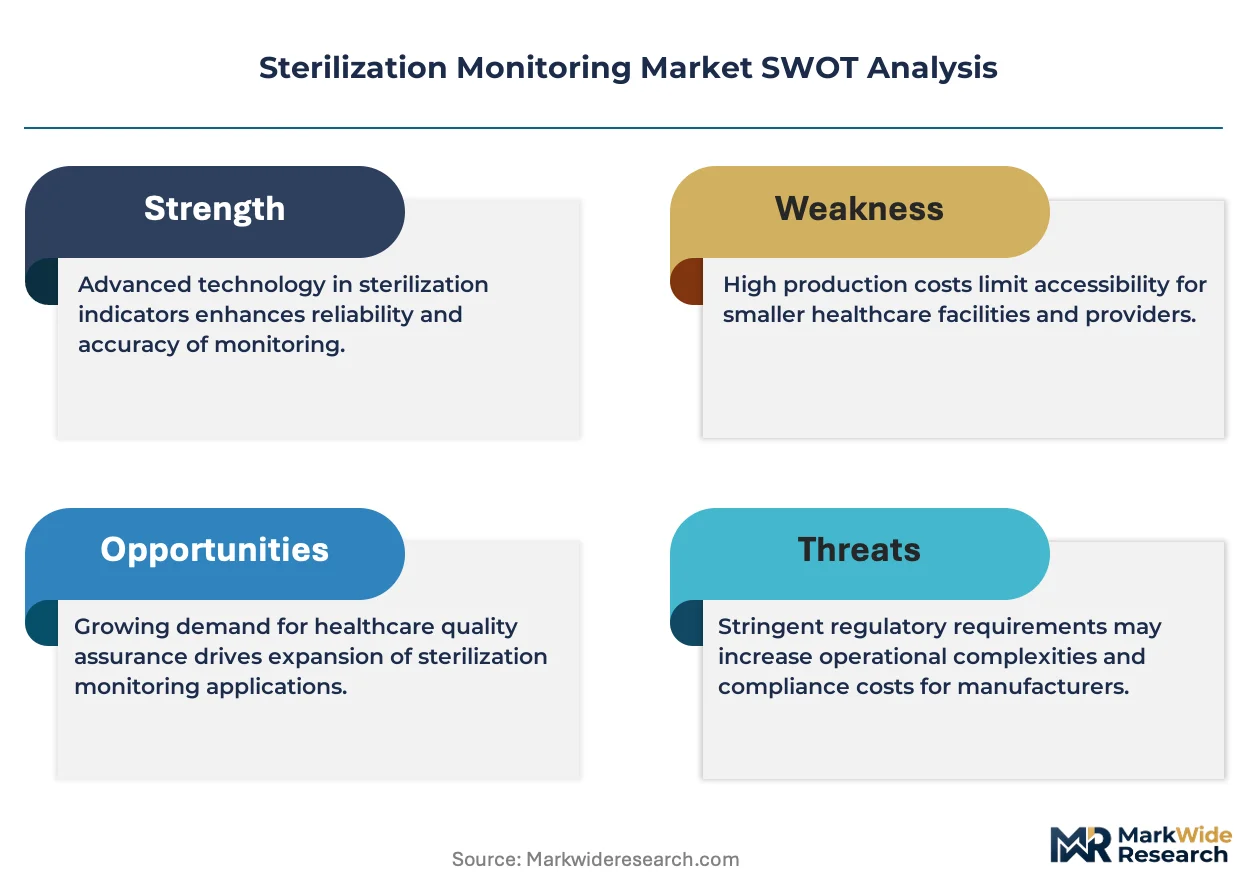
The FDA enforces Quality System Regulation requirements for sterilization process validation, while ISO 11138 and ISO 11140 standards define biological and chemical indicator performance specifications that manufacturers must meet for market access; these frameworks compel hospitals and sterilization centers to maintain documented monitoring programs with traceable records. The EU Medical Device Regulation imposes stricter post-market surveillance and sterilization validation documentation on manufacturers placing products in European markets. Stakeholders must weigh capital allocation between point-of-use digital integration and centralized laboratory-based biological indicator incubation as connectivity standards consolidate.
Market Dynamics
The sterilization monitoring market is undergoing structural compression as automated digital verification systems displace manual indicator reading workflows in hospital sterile processing departments. This technology shift is narrowing decision windows for load release while tightening documentation requirements under evolving FDA guidance.
Growth Catalysts
- ISO 11138 compliance mandates:Biological indicator performance standards compel hospitals to upgrade from chemical-only monitoring to documented spore-based validation protocols, expanding consumable demand.
- Ambulatory surgical center expansion:Freestanding ASCs in the United States are adopting compact automated incubation systems to match hospital-grade sterilization assurance without full laboratory infrastructure.
- Ethylene oxide residual testing:Low-temperature sterilization for heat-sensitive devices requires specialized monitoring chemistries that command premium positioning in pharmaceutical packaging applications.
Market Restraints
- Biological indicator supply concentration:Spore crop cultivation for Geobacillus stearothermophilus concentrates among specialized agricultural biotechnology suppliers, creating batch-to-batch variability risk.
- Capital intensity of digital integration:RFID-enabled load tracking systems require upfront hardware investment that delays payback periods for mid-sized sterilization service providers.
- Reusable device validation complexity:FDA's updated guidance on complex device reprocessing imposes extended validation timelines that strain sterilization department throughput capacity.
Strategic Opportunities
- Point-of-use connectivity standards:Integration between sterilizer equipment and hospital information systems creates recurring software-as-a-service revenue streams for monitoring platform vendors.
- EU MDR documentation requirements:European manufacturers face intensified post-market surveillance obligations that expand demand for traceable sterilization validation records across the supply chain.
- Steam-ETO hybrid monitoring:Facilities running mixed sterilization modalities seek unified indicator platforms that reduce SKU complexity and simplify staff training protocols.
Industry Challenges
- Microbiology technician scarcity:Hospital sterile processing departments struggle to recruit personnel trained in biological indicator incubation, reading, and documentation protocols.
- Legacy equipment interoperability:Older steam sterilizers lack digital output ports, forcing expensive retrofit or replacement decisions to enable connected monitoring workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilization Monitoring Market |
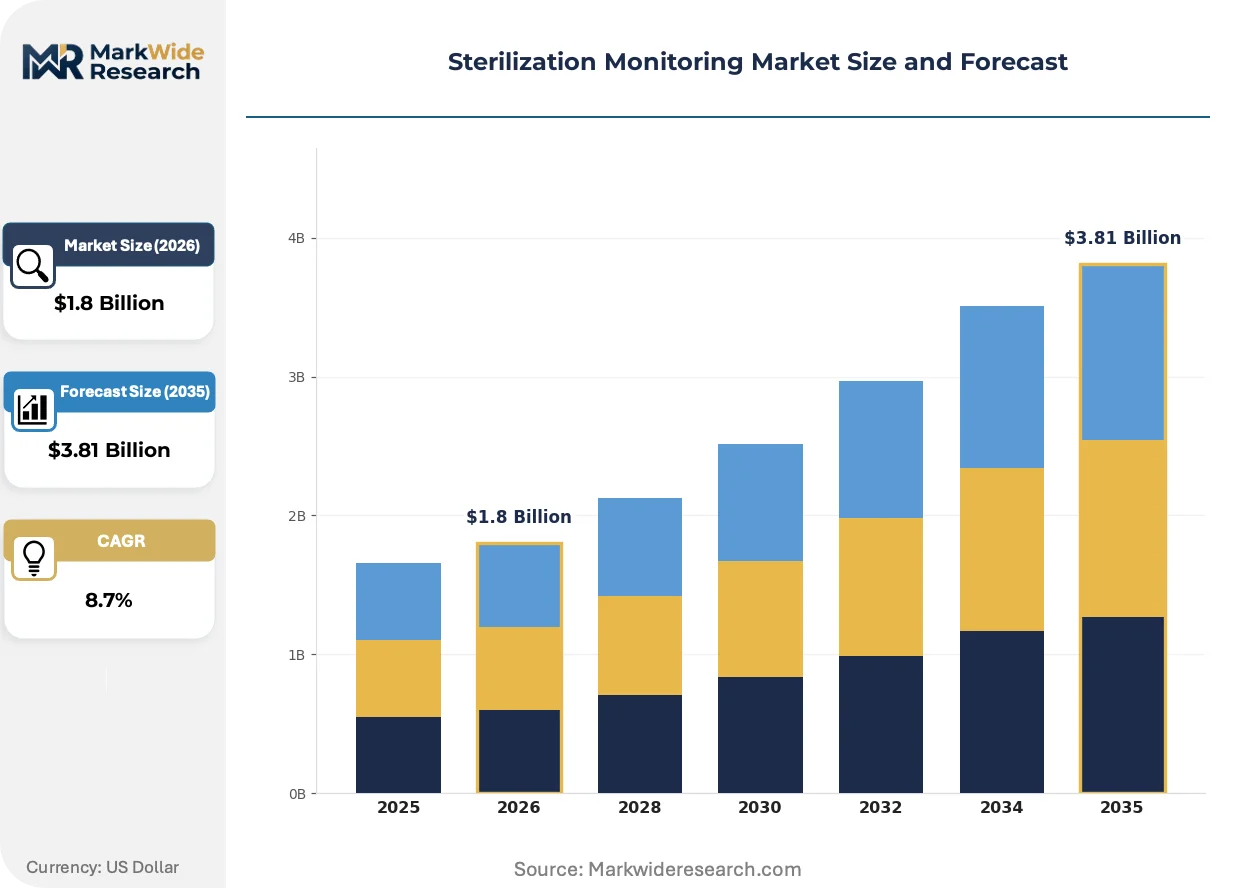
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biological Indicators, Chemical Indicators, Integrators, Test Packs Technology: Steam Sterilization, Ethylene Oxide, Dry Heat, Radiation Application: Healthcare Facilities, Pharmaceutical Industry, Research Laboratories, Biotechnology End User: Hospitals, Clinics, Sterilization Centers, Dental Practices |
| Companies Covered | 3M, STERIS, Mesa Laboratories, Getinge, Cardinal Health, Propper Manufacturing, MATACHANA, Tuttnauer, Andersen Sterilizers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilization Monitoring Market Strategic Shifts
Digital verification technologies are compressing the sterilization assurance workflow from hours to minutes, while regulatory documentation requirements intensify traceability demands across the supply chain. These forces are reshaping competitive positioning around data infrastructure rather than consumable chemistry alone.
RFID-embedded biological indicators are collapsing the time gap between cycle completion and load release authorization. Large hospital networks in the United States are deploying these systems across multiple sterile processing departments simultaneously. The technology is collapsing the error window in manual transcription and enabling real-time exception alerting that prevents recalled loads from reaching operating rooms.
ISO 11140 chemical indicator classification standards are tightening color-change performance specifications for steam and ethylene oxide exposure. Manufacturers must now demonstrate calibrated response across defined temperature, humidity, and sterilant concentration bands to maintain market access. European notified bodies are enforcing these requirements most stringently, driving reformulation investments among indicator chemistry suppliers.
Consolidated procurement by multi-hospital health systems is compressing vendor negotiation cycles and unbundling after-sales service from consumable supply agreements. Group purchasing organizations are centralizing sterilization monitoring contracts across member facilities, displacing individual hospital purchasing autonomy. This pattern is most visible in the United States, where major networks are standardizing on single-source indicator platforms to simplify inventory management and staff training.
Sterilization Monitoring Market Segmentation
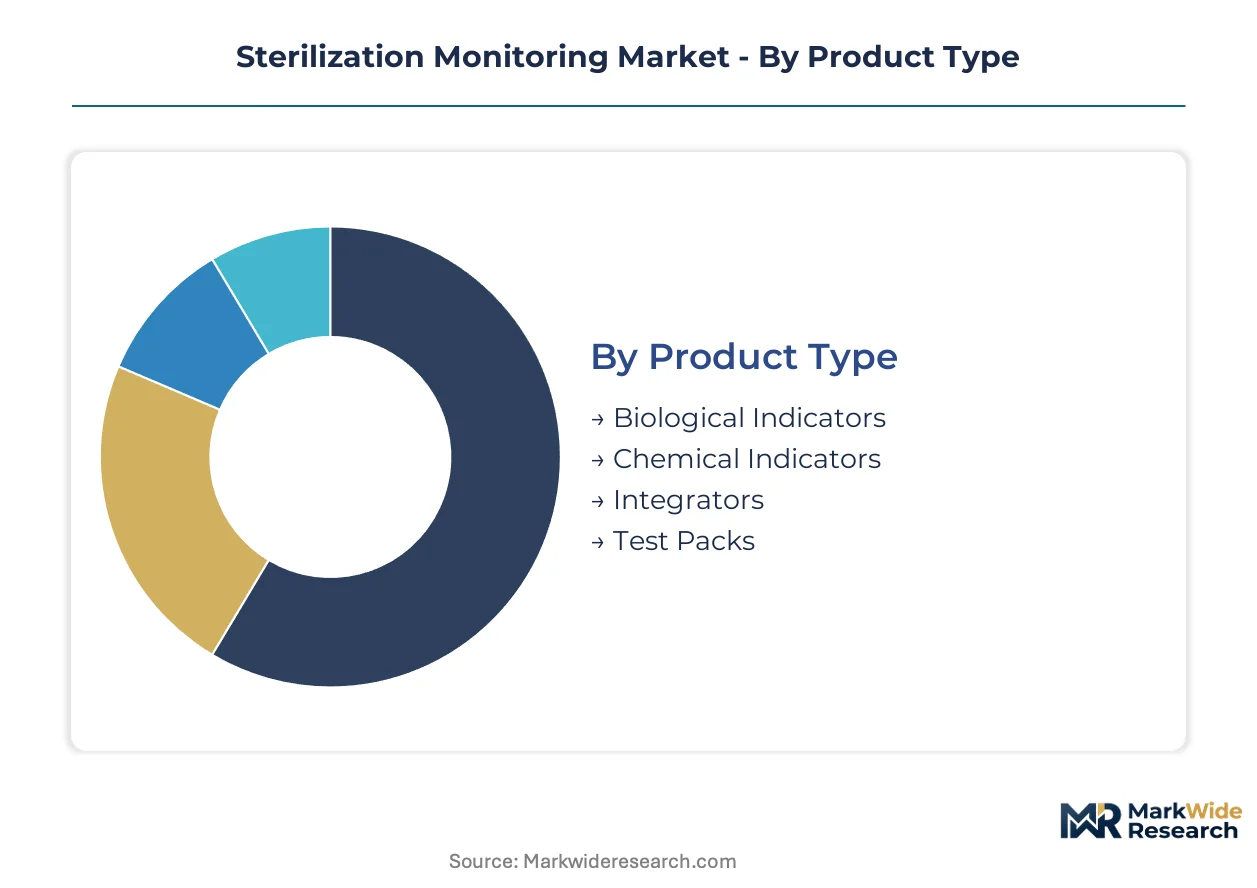
Sterilization monitoring segments fracture along technical validation hierarchy and sterilization modality. Product type determines consumable economics, while technology choice locks in indicator chemistry and equipment compatibility.
Product Type:
Cost tier stratification separates premium spore-based validation from routine chemical screening.
- Biological Indicators:Defined populations of Geobacillus stearothermophilus or Bacillus atrophaeus spores deliver terminal lethality validation. United States hospital networks concentrate demand here as FDA Quality System Regulation tightens documented proof-of-sterility requirements for implantable devices.
- Chemical Indicators:Calibrated color-change chemistry provides immediate visual confirmation of sterilant exposure. Ambulatory surgical centers in Texas and Florida rotate toward these for faster load-release turnaround where spore incubation infrastructure is limited.
- Integrators:Electronic multi-parameter sensors measure time, temperature, and sterilant concentration simultaneously. Compact units are displacing manual reading in mid-sized sterilization centers.
- Test Packs:Standardized challenge devices simulate worst-case load configurations for routine sterilizer efficacy verification. Group purchasing organizations bundle these with biological indicator contracts.
Biological Indicators hold installed capacity. Chemical Indicators is rotating up the share rankings.
Technology:
Application temperature thresholds dictate sterilant selection and corresponding monitoring chemistry.
- Steam Sterilization:Saturated steam at 121-134°C remains the dominant installed base for heat-tolerant medical devices. United States health systems standardize monitoring protocols here, though ethylene oxide alternatives are climbing fastest for polymer instruments.
- Ethylene Oxide:Low-temperature gas penetration enables sterilization of heat-sensitive implants and electronic components. Pharmaceutical packaging lines in New Jersey and Massachusetts command premium monitoring chemistries for residual testing compliance.
- Dry Heat:Oxidative sterilization at 160-180°C serves specialized applications where moisture damage risks exceed steam tolerance. Niche demand concentrates in ophthalmic device manufacturing.
- Radiation:Gamma and electron beam sterilization for single-use disposables requires dosimetric monitoring rather than biological challenge. Contract sterilization facilities in California and Illinois anchor volume.
Steam Sterilization holds installed capacity. Ethylene Oxide is expanding most quickly.
Application:
End-use regulatory intensity varies across patient-contact risk categories.
- Healthcare Facilities:Hospital sterile processing departments and ambulatory surgery centers require continuous load monitoring with traceable documentation. Joint Commission accreditation audits in the United States drive standardization of biological indicator protocols.
- Pharmaceutical Industry:Aseptic manufacturing and terminal sterilization of parenteral products demand validated monitoring with batch records. FDA sterile drug guidance imposes the strictest indicator performance requirements here.
- Research Laboratories:Academic and government labs prioritize cost-efficient chemical monitoring for non-patient research materials. Funding constraints limit biological indicator adoption.
- Biotechnology:Cell therapy and regenerative medicine manufacturing require specialized low-temperature validation. Emerging demand centers on Boston and San Diego clusters.
Healthcare Facilities hold installed capacity. Pharmaceutical Industry is gaining share fastest.
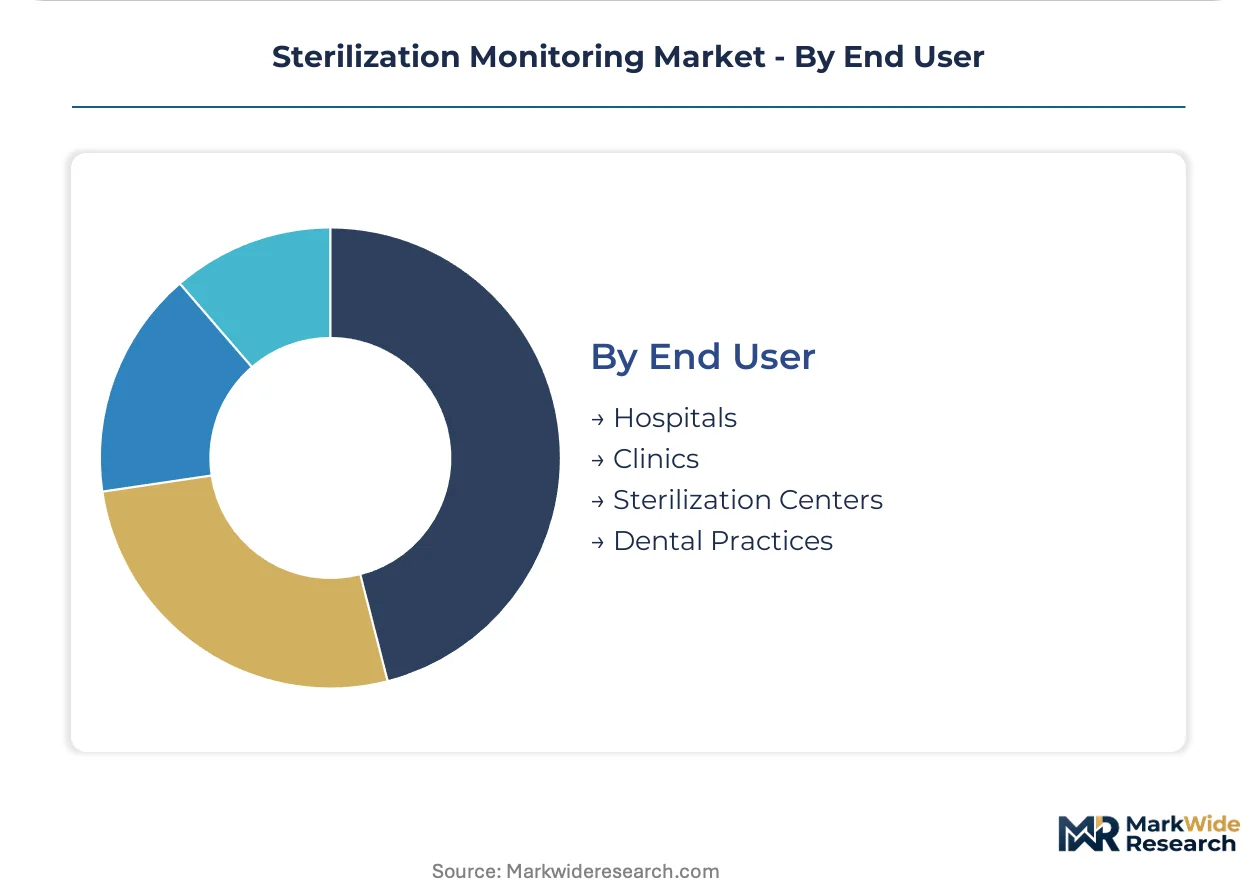
End User:
Customer scale determines procurement autonomy and service bundling preferences.
- Hospitals:Large health systems with centralized sterile processing departments negotiate multi-year indicator supply agreements. United States networks exceeding 50 facilities command steepest volume discounts.
- Clinics:Outpatient facilities and physician offices rely on compact chemical indicator systems with minimal training requirements. Rural and suburban locations dominate this tier.
- Sterilization Centers:Third-party contract sterilizers process devices for multiple OEM customers, requiring flexible indicator platforms across modalities. ISO 13485 certification mandates rigorous documentation.
- Dental Practices:Small-scale steam sterilization for handpieces and instruments uses basic integrator strips. Price sensitivity limits premium product penetration.
Hospitals hold installed capacity. Sterilization Centers is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sterilization equipment manufacturers export monitoring consumables to United States hospital networks, while Swiss pharmaceutical packaging firms import validation systems for ethylene oxide residual testing compliance.
United States
FDA Quality System Regulation enforcement tightens biological indicator documentation requirements for implantable devices. Joint Commission accreditation audits drive standardization across hospital sterile processing departments. Major health systems in Texas and Florida expand ambulatory surgical center networks with compact automated incubation systems.
Germany
ISO 11138 compliance mandates accelerate hospital upgrades from chemical-only to spore-based validation protocols. EU Medical Device Regulation imposes stricter post-market surveillance documentation on sterilization validation. Industrial clusters in North Rhine-Westphalia concentrate pharmaceutical packaging line monitoring chemistry production.
Switzerland
Swissmedic enforces rigorous sterilization process validation for medical device manufacturers exporting into European markets. Precision manufacturing hubs around Basel demand premium ethylene oxide monitoring for heat-sensitive polymer instruments. Contract sterilizers serving orthopedic implant OEMs anchor regional consumable demand.
Japan
METI industrial standards for reusable medical device reprocessing tighten validation timelines for sterilization departments. PMDA guidance on complex device reprocessing strains throughput capacity in Tokyo-area hospitals. Osaka-based sterilization equipment manufacturers integrate proprietary monitoring consumables into captive demand systems.
India
CDSCO medical device rules align with international standards for sterilization process validation in domestic manufacturing. Central Drugs Standard Control Organization mandates documented monitoring programs for imported device reprocessing. Maharashtra pharmaceutical clusters adopt biological indicator protocols for parenteral product terminal sterilization.
Sterilization Monitoring Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement structures. Large health systems negotiate multi-year supply agreements that bundle consumables with equipment service contracts, compressing vendor margins. Three archetypes dominate: diversified conglomerates with embedded sensor portfolios, instrument-and-service specialists spanning incubation and analytics, and sterilization equipment manufacturers with backward integration into proprietary consumables. Competitive moves concentrate on strategic partnerships for digital integration and portfolio diversification across steam-ethylene oxide hybrid modalities.
Within the diversified conglomerate tier, 3M exemplifies the embedded sensor-to-consumable revenue model across integrated hospital systems. Mesa Laboratories occupies a position among instrument-and-service specialists with diversified biological indicator incubation and software analytics capabilities. STERIS anchors the equipment-integrated archetype through captive demand generation for proprietary monitoring consumables tied to sterilizer installed base.
| Leading Market Players |
|---|
| 3M |
| STERIS |
| Mesa Laboratories |
| Getinge |
| Cardinal Health |
| Propper Manufacturing |
| MATACHANA |
| Tuttnauer |
| Andersen Sterilizers |
| Others |
Value Chain & Pricing Dynamics
Spore crop cultivation for Geobacillus stearothermophilus concentrates among specialized agricultural biotechnology suppliers in the United States and Germany, anchoring margin pools downstream with biological indicator manufacturers who control formulation and distribution. This upstream concentration creates asymmetric pricing power where consumable suppliers capture recurring revenue while sterilization departments face switching costs tied to validation protocol changes.
Pricing Analysis
Next-generation RFID-embedded biological indicators command premium positioning over conventional color-change chemical indicators and legacy spore strips. Three-tier pricing structure across premium, standard, and economy levels separates connected digital verification systems from manual-reading consumables and basic integrator strips. Price differentiation hinges on FDA 510(k) clearance tier and ISO 11138 certification grade. Cost compression in the chemical indicator tier is intensifying because ambulatory surgical centers prioritize turnaround speed over terminal validation. Clinics and dental practices exhibit highest price sensitivity; pharmaceutical packaging lines show lowest.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as group purchasing organizations consolidate procurement leverage across United States hospital networks. Biological indicator manufacturing draws from spore crop suppliers in the United States, Germany, and Japan, with chemical substrate production concentrated in Switzerland and the Netherlands. Single-source vulnerability exists for Geobacillus stearothermophilus master seed stocks. Distribution runs through GPO-negotiated contracts to health system warehouses, bypassing traditional medical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as sterilizer equipment manufacturers integrate proprietary monitoring consumables into captive demand systems, creating interoperability lock-in that favors early movers in digital verification standards.
For Market Incumbents: Build data infrastructure moats through backward integration into sterilizer connectivity protocols. STERIS and 3M should deepen software-as-a-service revenue streams by embedding analytics platforms that make load-release decisions dependent on proprietary cloud infrastructure. Defensive priority: secure GPO exclusivity clauses before next contract renewal cycle. Threat vector: emerging entrant specialists offering open-architecture APIs that bypass vendor lock-in. For New Entrants and Emerging Players: Establish a beachhead in the ambulatory surgical center segment where compact automated incubation demand outpaces supply. White-space targets include RFID-enabled biological indicators for mid-sized sterilization centers lacking capital for full laboratory infrastructure, and steam-ethylene oxide hybrid monitoring platforms that reduce SKU complexity for mixed-modality facilities. Go-to-market angle: subscription pricing that converts capital expenditure into operational expenditure for ASC administrators. For Investors and Strategic Acquirers: Capital is best deployed toward instrument-and-service specialists with diversified incubation and analytics capabilities rather than pure consumable chemistry plays. Long-term viability favors vendors controlling both biological indicator manufacturing and software validation platforms. Acquisition target archetype: mid-cap European firms with EU MDR documentation capabilities and established notified body relationships. Signal to watch: FDA guidance on complex device reprocessing that extends validation timelines and strains hospital throughput capacity.| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Enabled Biological Indicator Launch | Collapses load-release authorization from hours to minutes for Joint Commission-accredited hospitals. |
| Hospital System Partnership | Locks in multi-year consumable supply through sterilizer equipment captive demand generation. |
| Software-as-a-Service Platform Integration | Creates recurring revenue from real-time exception alerting and load traceability documentation. |
| EU MDR Documentation Capability Investment | Captures post-market surveillance validation record demand from European pharmaceutical packaging lines. |
| Steam-ETO Hybrid Monitoring Portfolio Expansion | Reduces SKU complexity for facilities running mixed sterilization modalities in Texas and Florida. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, ISO 11138 certification databases, hospital procurement contracts, and GPO agreement disclosures. Interviews with sterile processing department managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at biological indicator manufacturers informed demand-side and supply-side validation. Bottom-up modeling of consumable unit economics triangulates against top-down health system expenditure analysis.
Forecast inputs include sterilization modality mix shifts, Joint Commission audit frequency changes, and ambulatory surgical center expansion trajectories across the analysis window. Segmentation dimensions span product type hierarchy, technology temperature thresholds, application regulatory intensity, and end-user procurement scale. CAGRs derive from installed base erosion rates for manual indicator systems and penetration curves for connected digital verification platforms. Industry-specific inputs incorporate FDA guidance timeline uncertainty and EU MDR implementation pacing.
Sensitivities concentrate around FDA enforcement intensity for reusable device reprocessing, spore crop batch variability events, and GPO consolidation pace in United States hospital networks. Forecasts reflect assumptions on digital verification adoption curves and interoperability standard convergence. Macroeconomic contraction affecting ASC capital budgets, regulatory deviation in sterilization validation requirements, or breakthrough in rapid molecular sterility testing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Intra-Amniotic Infection Treatment Market
Infection Control
Intra-Abdominal Infection Treatment Market
Infection Control
Alcohol Wipes Market
Infection Control
Germicidal UV Lamp Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Medical Washer Disinfector Market
Infection Control
Sanitizers Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Surgical Site Infections Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Ultraviolet Disinfection Equipment Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Salivary Gland Infection Market
Infection Control
Sterilization Technologies Market