
 Global Dental Infection Control Products Market | 2026-2036
Global Dental Infection Control Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Infection Control Products Market Foresight
Dental distributor networks is fragmenting as direct-to-clinic digital procurement platforms gain share alongside legacy medical supply stores. Henry Schein, Inc. leverages its broad warehouse footprint to sustain same-day delivery commitments in saturated urban corridors. Dentsply Sirona competes through bundled infection control SKUs tied to its installed base of chairside equipment. Crosstex International, Inc. specializes in barrier film and sterilization pouch lines, anchoring its position in private-practice accounts.
Dental infection control products encompass chemical disinfectants, steam sterilizers, single-use barriers, and hand hygiene formulations engineered to eliminate or inactivate pathogenic microorganisms on instruments, surfaces, and clinician hands; ethylene oxide and steam sterilization cycles must achieve spore-kill validation per ISO 17665 thermal parameters. Disinfectants occupy the largest volume share due to recurring surface wipe-down protocols between patients, while barrier films represent a faster-growing margin pool as single-use plastics replace reusable draping in orthodontics and oral surgery settings. Instrument sterilization applications dominate capital spending, though hand hygiene SKUs generate steadier replenishment revenue through dental clinic recurring orders.
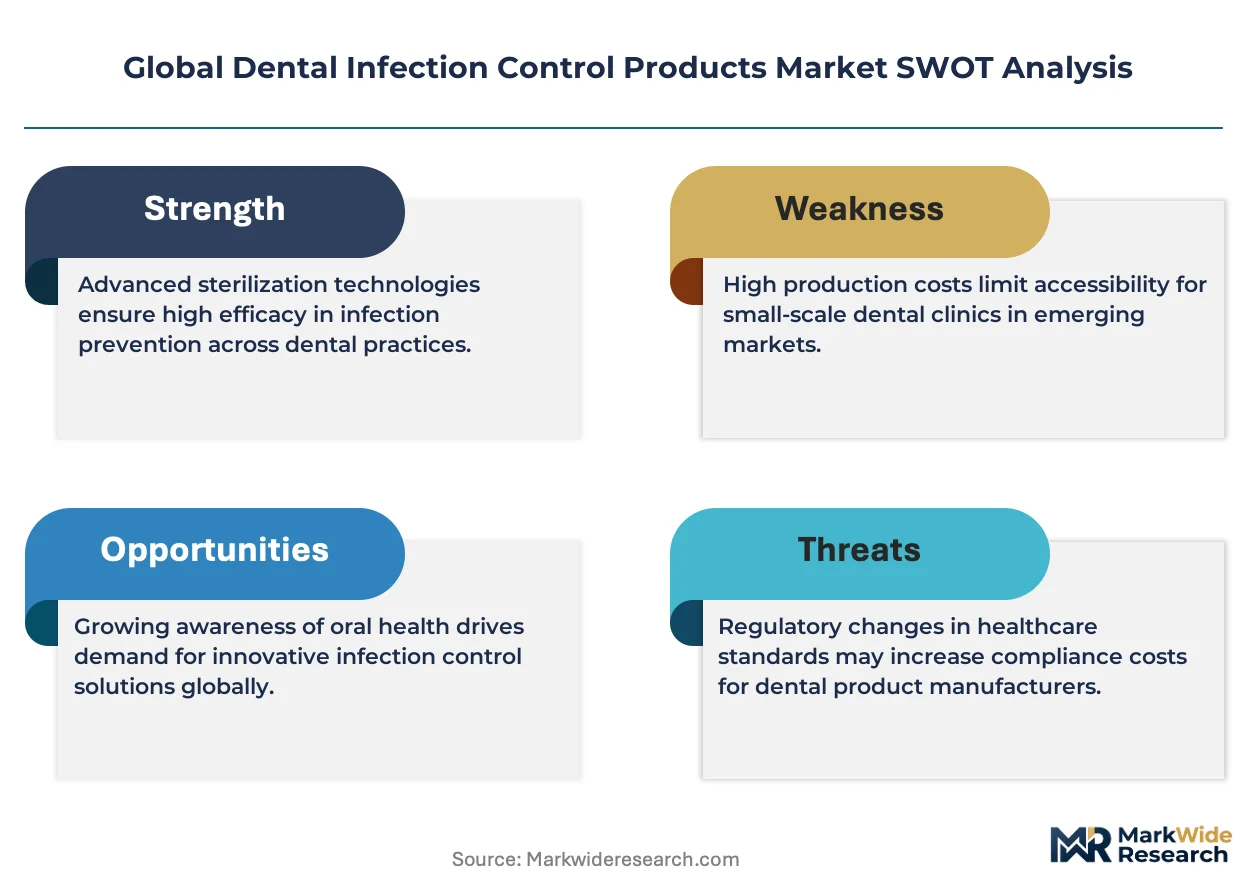
The FDA enforces premarket notification requirements for sterilization equipment under 21 CFR Part 872, while EPA regulates surface disinfectant efficacy claims through FIFRA registration protocols; ISO 13485 quality management standards shape supplier qualification for OEM partnerships. The EU MDR and REACH chemical restrictions are tightening formulation disclosure burdens for disinfectant manufacturers exporting to European dental markets. Stakeholders must monitor evolving spore-test mandates and bioburden validation thresholds as regulators align hospital-grade standards with outpatient dental settings.
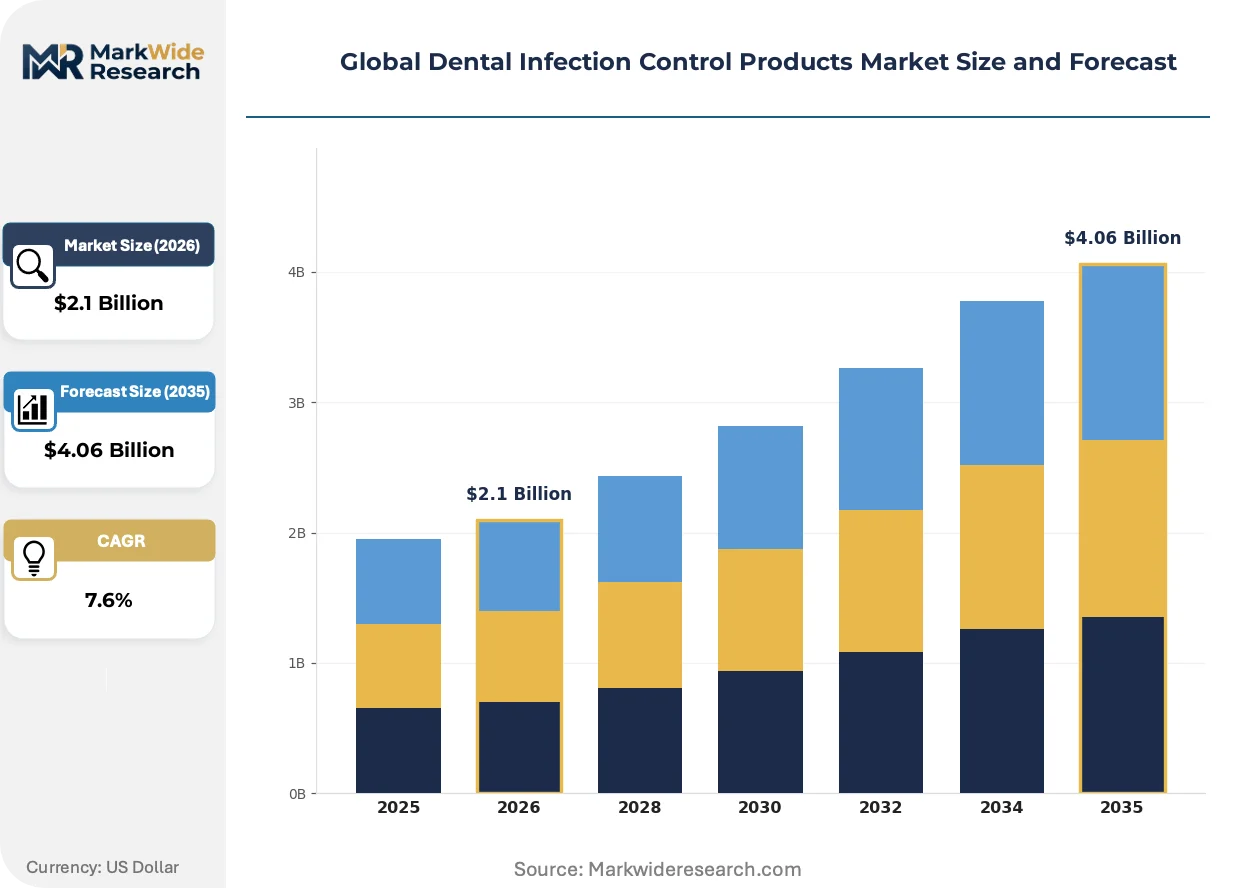
Market Dynamics
Dental service organizations are consolidating procurement authority across multi-clinic networks, compressing supplier margins while elevating compliance and documentation requirements for infection control vendors serving these aggregated accounts.
Growth Catalysts
- ISO 17665 Thermal Validation Mandates:Spore-kill documentation requirements for steam sterilization cycles are expanding addressable equipment upgrade cycles in outpatient dental settings across Germany and the United States.
- Single-Use Barrier Conversion:Orthodontic and oral surgery practices are replacing reusable draping with disposable barrier films, opening margin-rich SKU expansion opportunities for pouch and film manufacturers.
- Hand Hygiene Protocol Intensification:Between-patient wipe-down frequencies are elevating chemical disinfectant consumption volumes in high-throughput clinic environments.
Market Restraints
- Ethylene Oxide Residue Constraints:EPA FIFRA registration protocols and EU REACH chemical restrictions are lengthening formulation approval timelines for low-temperature sterilization chemistries.
- Capital Equipment Replacement Cycles:Steam sterilizer hardware typically operates 7-10 year lifespans, creating lumpy revenue recognition and elongated payback periods for autoclave manufacturers.
- Supplier Concentration in Central European Manufacturing:Barrier film and sterilization pouch production clusters in Germany and Switzerland create geographic supply vulnerability for North American distributors.
Strategic Opportunities
- Direct-to-Clinic Digital Procurement:Amazon Business and specialized dental supply platforms are disintermediating legacy distributor networks, enabling manufacturers to capture margin previously allocated to wholesale intermediaries.
- EU MDR Quality System Certification:ISO 13485 compliance investments by Asian manufacturers unlock OEM private-label partnerships with European dental device brands seeking outsourced infection control bundling.
- Bioburden Validation Services:Spore-test kit subscription models and remote sterilization monitoring software create recurring revenue streams adjacent to physical product sales.
Industry Challenges
- Regulatory Documentation Burden:FDA 21 CFR Part 872 premarket notification requirements and EPA FIFRA efficacy claim substantiation demand specialized regulatory affairs staffing that mid-tier suppliers struggle to maintain.
- Legacy Equipment Integration Friction:New sterilization monitoring systems must interface with installed bases of chairside equipment from disparate OEMs, complicating software-hardware compatibility certification.
- Reusable-to-Disposable Transition Costs:Clinics converting from laundered textiles to single-use barriers face waste disposal compliance and storage space reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Infection Control Products Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.06 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disinfectants, Sterilizers, Barrier Films, Hand Sanitizers, Surface Cleaners Application: Instrument Sterilization, Surface Disinfection, Hand Hygiene, Waste Management, Air Purification End User: Dental Clinics, Orthodontic Centers, Periodontics Facilities, Dental Laboratories, Oral Surgery Units Distribution Channel: Direct Sales, Online Platforms, Medical Supply Stores, Dental Distributors, Wholesale Suppliers |
| Companies Covered | 3M, Dentsply Sirona, Kerr Corporation, Young Innovations, Inc., Henry Schein, Inc., A-dec Inc., Crosstex International, Inc., COLTENE Group, Steris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Infection Control Products Market Shifts & Advancements
Automation in sterilization workflow documentation and real-time bioburden sensing are compressing compliance labor costs while elevating traceability standards across outpatient dental settings.
Plasma-based low-temperature sterilization systems are penetrating orthodontic and implantology practices requiring rapid instrument turnaround without thermal degradation of polymer components. European dental service organizations in France and the Netherlands are piloting these units to reduce chairside downtime. Hydrogen peroxide vapor sterilization is rendering obsolete traditional ethylene oxide cycles in clinics prioritizing same-day instrument availability.
EU MDR and REACH chemical disclosure mandates are forcing reformulation of quaternary ammonium disinfectant concentrates sold into European dental markets. Manufacturers must now submit full toxicological profiles and biodegradation data to ECHA, extending product registration timelines by 12-18 months. Surface disinfectant suppliers serving Germany and Italy are responding by consolidating SKU portfolios to focus on highest-volume, pre-validated chemistries.
Dental clinic purchasing managers are aggregating infection control spend across supply categories to negotiate tiered volume rebates previously unavailable to single-practice accounts. This buyer-side consolidation is squeezing distributor margins and accelerating platform migration to digital procurement portals. The United States exhibits the most advanced concentration of this behavior, with multi-location dental groups in Texas and Florida leading contract standardization efforts.
Global Dental Infection Control Products Market Segmentation
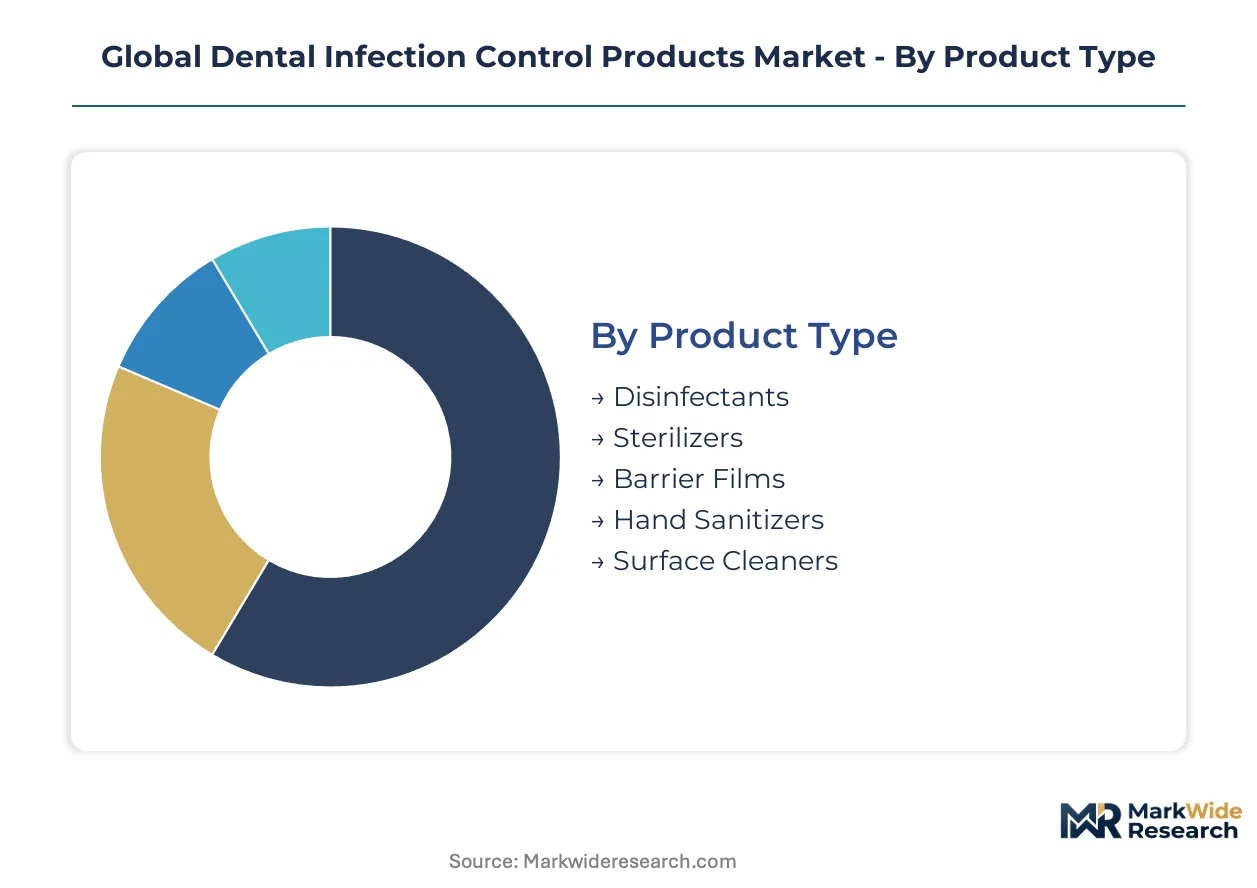
Dental infection control procurement cycles vary dramatically across product categories, with consumables replenishing weekly and capital equipment requiring decade-long replacement intervals. Understanding these velocity differentials helps suppliers align inventory, service, and pricing models to the specific economics of each segment.
Product Type:
Surface disinfectants and hand sanitizers turn over fastest, often weekly, while steam sterilizers anchor decade-long capital cycles. Barrier films occupy a middle rhythm, with monthly to quarterly reorder patterns tied to patient volume fluctuations.
- Disinfectants:Quaternary ammonium and chlorine-based formulations dominate surface wipe-down protocols between patients. German dental service organizations are consolidating these purchases into centralized contracts, compressing per-unit margins while elevating volume commitments.
- Sterilizers:Steam autoclaves and low-temperature hydrogen peroxide systems represent the longest replacement cycles in dental equipment. FDA 21 CFR Part 872 premarket notification requirements and ISO 17665 thermal validation mandates are extending upgrade timelines in United States outpatient settings.
- Barrier Films:Single-use plastic drapes and chair covers are displacing laundered textiles in orthodontic and oral surgery practices.
- Hand Sanitizers:Alcohol-based and benzalkonium chloride formulations generate steady replenishment revenue through recurring clinic orders.
- Surface Cleaners:Pre-saturated wipes and concentrated chemistries serve pre-sterilization instrument cleaning and operatory turnover protocols.
Disinfectants dominate installed base volume. Sterilizers represent where expansion concentrates as thermal validation mandates force equipment upgrades.
Application:
Hand hygiene protocols execute dozens of times daily per clinician, while air purification systems run continuously in the background. Instrument sterilization sits at the critical path of chairside scheduling, making throughput optimization the primary selection criterion.
- Instrument Sterilization:Steam and chemical vapor cycles must achieve spore-kill validation per ISO 17665 parameters, with cycle documentation now mandatory for liability protection. United States dental clinics are upgrading to automated sterilization logging systems to satisfy tightening FDA inspection protocols.
- Surface Disinfection:Between-patient wipe-down frequencies have intensified, elevating chemical consumption in high-throughput environments. EPA FIFRA registration requirements govern efficacy claims, with formulation approvals lengthening for novel chemistries.
- Hand Hygiene:Surgical scrubs and alcohol rubs represent the highest-frequency consumption point in infection control protocols.
- Waste Management:Sharps containment and biohazard disposal systems serve regulatory compliance rather than clinical efficacy.
- Air Purification:HEPA filtration and UV-C systems gained traction following enhanced ventilation requirements in outpatient healthcare settings.
Surface disinfection commands the largest chemical spend. Instrument sterilization is climbing the fastest as throughput demands intensify.
End User:
General dental clinics operate standardized protocols across high patient volumes, while oral surgery units demand specialized sterilization documentation for implant and bone-graft procedures. Orthodontic centers present unique barrier film consumption profiles due to extended chairside appointments.
- Dental Clinics:General practice settings account for the broadest infection control SKU requirements, from surface disinfectants to hand hygiene and instrument processing. Texas and Florida multi-location groups are pioneering aggregated procurement contracts that standardize supplier relationships across dozens of locations.
- Orthodontic Centers:Extended appointment durations and polymer-heavy instrument sets drive demand for low-temperature sterilization alternatives to steam autoclaving.
- Periodontics Facilities:Surgical instrument intensity elevates sterilization throughput requirements beyond general practice norms.
- Dental Laboratories:Removable prosthesis fabrication demands distinct infection control protocols for impression handling and model work.
- Oral Surgery Units:Implantology and bone-graft procedures require validated sterilization documentation for liability protection.
Dental clinics anchor volume concentration. Orthodontic centers are gaining share fastest as disposable barrier conversion accelerates.
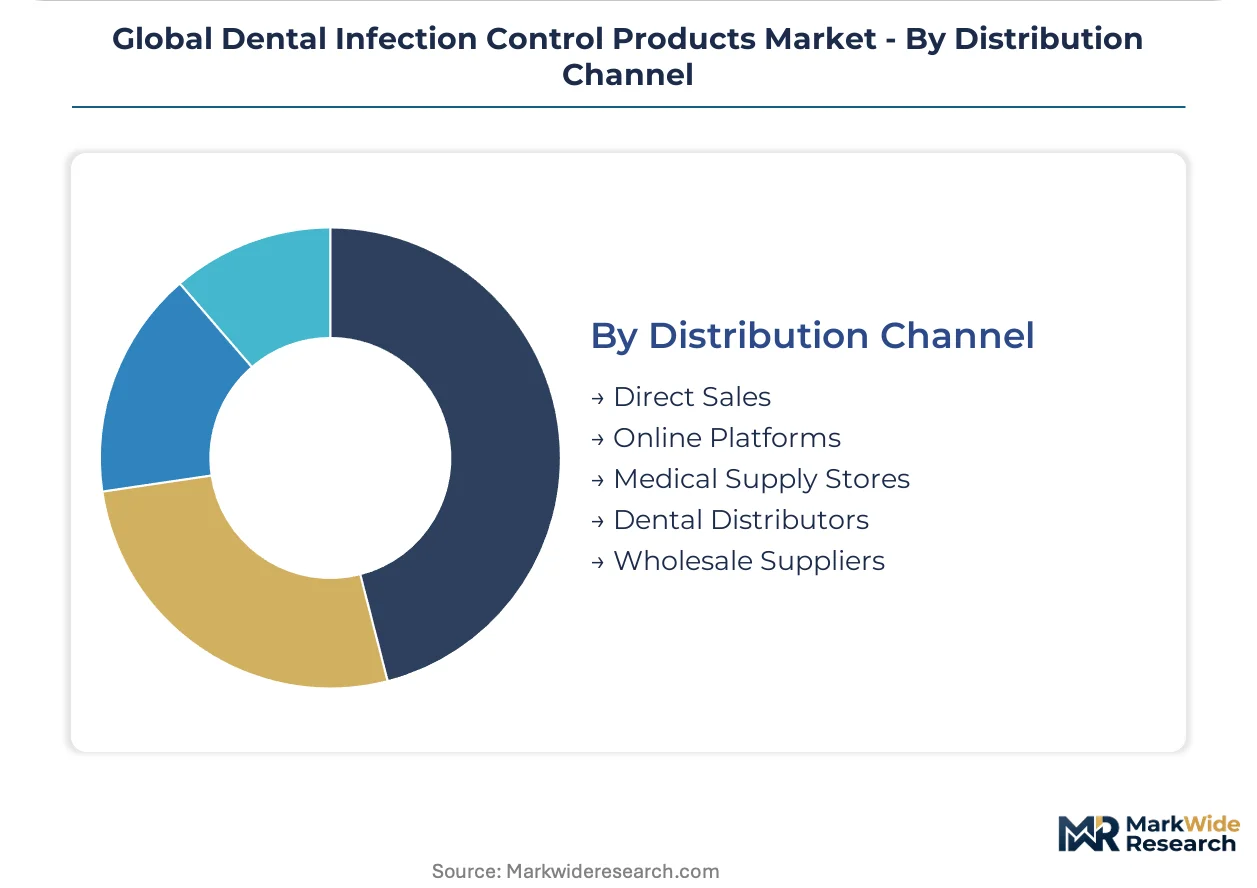
Distribution Channel:
Direct sales relationships sustain capital equipment transactions requiring installation and validation support, while digital platforms capture consumable replenishment with minimal service overhead. Legacy dental distributors retain value in compliance documentation and credit extension.
- Direct Sales:Steam sterilizer and automated washer-disinfector purchases require factory-trained technicians for installation, thermal validation, and staff training. Henry Schein leverages its United States warehouse footprint to sustain same-day delivery commitments in saturated urban corridors.
- Online Platforms:Amazon Business and specialized dental supply portals are disintermediating legacy distributors for consumable categories with standardized specifications.
- Medical Supply Stores:Local inventory access serves emergency replenishment needs for smaller independent practices.
- Dental Distributors:Full-line catalog relationships retain relevance for multi-category procurement consolidation.
- Wholesale Suppliers:Volume aggregation serves group purchasing organizations and dental service organization networks.
Dental distributors retain the deepest installed base relationships. Online platforms are expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European distribution for dental infection control consumables, while the Los Angeles-Long Beach port complex handles Pacific Rim sterilization equipment imports into North American clinical networks.
United States
Dental service organizations in Texas and Florida are consolidating procurement across multi-clinic networks, compressing supplier margins while elevating compliance documentation requirements. The FDA enforces premarket notification for sterilization equipment under 21 CFR Part 872, with spore-kill validation mandates expanding upgrade cycles. Henry Schein leverages its broad warehouse footprint to sustain same-day delivery commitments in saturated urban corridors.
Germany
Dental service organizations are consolidating supplier relationships across private-practice accounts, with barrier film and sterilization pouch demand concentrating in Baden-Württemberg manufacturing clusters. The EU MDR and REACH chemical restrictions tighten formulation disclosure burdens for disinfectant manufacturers exporting to European dental markets. ISO 17665 thermal validation mandates are expanding addressable equipment upgrade cycles in outpatient dental settings.
China
Domestic dental clinic expansion is elevating consumption of surface disinfectants and hand hygiene formulations, with manufacturing capacity clustering in the Yangtze River Delta. NMPA registration requirements for imported sterilization equipment create compliance barriers for foreign OEMs. Zhengzhou and Shanghai anchor production networks serving both domestic clinics and export markets across Southeast Asia.
Japan
Orthodontic centers in the Kanto region are accelerating conversion from reusable draping to disposable barrier films, opening margin-rich SKU expansion opportunities. METI guidelines on medical device quality management shape supplier qualification protocols. Osaka-based dental distributors are piloting direct-to-clinic digital procurement platforms to disintermediate legacy supply networks.
India
Dental clinic chains in Maharashtra and Karnataka are standardizing infection control protocols across metropolitan practices, elevating demand for steam sterilizers and chemical disinfectants. CDSCO medical device registration requirements are lengthening import approval timelines for European and American sterilization equipment. Mumbai and Bengaluru anchor distribution networks serving tier-1 and tier-2 city expansion.
Global Dental Infection Control Products Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct tiers: full-line dental distributors with warehouse networks, specialized infection control manufacturers with OEM partnerships, and emerging digital-first procurement platforms. Strategic archetypes include scale-driven logistics players, compliance-focused sterilization specialists, and technology-integrated monitoring service providers. Dominant competitive moves encompass direct-to-clinic digital channel expansion and ISO 13485 quality system certification investments to unlock European private-label partnerships.
Among United States-based distributors, Henry Schein, Inc. and Crosstex International, Inc. exemplify contrasting archetypes within the infection control value chain. Henry Schein occupies a position representing scale-driven logistics capabilities and broad warehouse footprint coverage. Crosstex International, Inc. sits within the specialized tier, anchoring its market presence through barrier film and sterilization pouch concentration. Dentsply Sirona, with its German-American corporate heritage, represents equipment-integrated bundling strategies tied to chairside installed bases.
| Leading Market Players |
|---|
| 3M |
| Dentsply Sirona |
| Kerr Corporation |
| Young Innovations, Inc. |
| Henry Schein, Inc. |
| A-dec Inc. |
| Crosstex International, Inc. |
| COLTENE Group |
| Steris |
| Others |
Supply & Pricing Matrix
German and Swiss sterilization pouch manufacturing clusters anchor barrier film supply, concentrating margin capture among converters serving dental service organizations with tiered volume commitments. This upstream concentration funnels pricing power downstream toward multi-clinic procurement networks while squeezing independent distributor margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates dental infection control procurement, with ISO 13485 certification and FDA 510(k) clearance status driving price differentiation between tiers. Henry Schein and Dentsply Sirona bundle sterilization monitoring services into premium contracts, while unbranded Asian imports compete on per-unit cost for high-volume disinfectant replenishment. Pricing pressure stems from dental service organization consolidation in Texas and Florida, where aggregated purchasing compresses per-unit margins by 15-20% in standardized consumable categories. Small independent practices exhibit highest price sensitivity on capital equipment, whereas multi-clinic networks prioritize compliance documentation over per-unit cost.
Supply Chain Analysis
Polypropylene resin and medical-grade paperboard feedstock availability shapes sterilization pouch production economics, with supply drawing from petrochemical complexes in Germany, Belgium, and the Netherlands. Ethylene oxide sterilization chemistries hinge on specialized chemical manufacturing concentrated in Switzerland and the United States, creating single-source vulnerability for low-temperature sterilization alternatives. Tariff exposure on Chinese-manufactured hand sanitizer active ingredients threatens margin stability for mid-tier disinfectant suppliers. Distribution runs through Henry Schein's United States warehouse network for same-day urban delivery, while Amazon Business and specialized dental platforms capture consumable replenishment with minimal service overhead.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17665 thermal validation mandates and EU MDR chemical disclosure requirements are accelerating equipment replacement cycles, creating a high-growth disruption window for suppliers with pre-certified quality systems.
For Market Incumbents: Build regulatory documentation moats by investing in ISO 13485 quality system certification and FDA 510(k) premarket notification capabilities to defend against emerging Asian manufacturers seeking European private-label partnerships. Deepen backward integration into sterilization pouch converting capacity in Baden-Württemberg manufacturing clusters to secure supply continuity. Acquire bioburden validation software specialists to capture recurring service revenue adjacent to physical product sales. For New Entrants and Emerging Players: Mid-market dental clinics in India's Maharashtra and Karnataka states represent the most penetrable entry point, where CDSCO registration barriers filter out smaller competitors but volume growth rewards early positioning. Direct-to-clinic digital procurement platforms in Japan's Kanto region offer white-space opportunity for specialized barrier film suppliers with METI-compliant quality systems. Target orthodontic centers converting from reusable draping to disposable barriers, where margin-rich SKU expansion outpaces commoditized disinfectant competition. For Investors and Strategic Acquirers: Capital is best deployed toward sterilization monitoring software providers with remote bioburden sensing capabilities, as recurring revenue models command premium valuations over transactional consumable suppliers. ISO 13485-certified Asian manufacturers with established NMPA registration in China present acquisition targets for European dental brands seeking outsourced infection control bundling. Watch for EPA FIFRA registration timeline extensions as an inflection signal: prolonged approval cycles will force consolidation among mid-tier disinfectant formulators unable to sustain specialized regulatory affairs staffing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Quality System Certification | Unlocks OEM private-label partnerships with European dental device brands seeking outsourced bundling. |
| Direct-to-Clinic Digital Procurement Platform | Disintermediates legacy Henry Schein distributor networks for standardized consumable categories. |
| Bioburden Validation Software Development | Captures recurring subscription revenue adjacent to physical sterilization pouch and barrier film sales. |
| Backward Integration into Pouch Converting | Secures supply continuity for German dental service organizations amid geographic concentration risk. |
| Hydrogen Peroxide Vapor Sterilizer Launch | Addresses orthodontic and implantology practices requiring rapid instrument turnaround without thermal degradation. |
Research Methodology
Cross-validation between primary interviews with dental clinic purchasing managers, sterilization equipment biomedical engineers, GPO contracts managers, and EPA regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA 510(k) premarket notification databases, EPA FIFRA registration records, EU MDR technical documentation filings, and ISO 17665 thermal parameter standards. Bottom-up demand modeling from individual clinic procurement patterns triangulates with top-down supply-side capacity assessments across German and Swiss manufacturing clusters.
Calibration against historical equipment replacement cycle data and spore-test validation mandate adoption curves shapes the analytical framework across the analysis window. Segmentation dimensions include product type (disinfectants, sterilizers, barrier films, hand sanitizers), application (instrument sterilization, surface disinfection, hand hygiene), end user (dental clinics, orthodontic centers, oral surgery units), and distribution channel (direct sales, online platforms, dental distributors). CAGRs derive from weighted average of clinician population growth, regulatory upgrade mandates, and single-use conversion rates in orthodontic settings.
Practitioners should monitor EPA FIFRA registration timeline volatility and EU REACH chemical restriction amendments for early signals of supply disruption. Cross-checking against hospital-grade infection control equipment procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Antimicrobial Catheters Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
Infection Control Supplies Market
Infection Control
Global Infection Prevention Devices Market
Infection Control
Clinical Hand Hygiene Products Market
Infection Control
Preventable Vaccines Market
Infection Control
Antimicrobial Suture Market
Infection Control
Peptide-Based Infection Therapeutics Market
Infection Control
Australia Hand Sanitizer Market
Infection Control
Intra Abdominal Infection Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Global Biofilms Treatment Market
Infection Control
Europe Ultrasound Probe Disinfection Market