
 Preventable Vaccines Market | 2026-2036
Preventable Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Preventable Vaccines Market Analytics
Combination vaccine bundling is recalibrating procurement economics for national immunization programs. Pfizer Inc. leverages its pneumococcal conjugate franchise to anchor premium positioning across pediatric contracts. GSK plc competes through differentiated access strategies in emerging markets. Sanofi sustains manufacturing scale through diversified antigen production networks spanning multiple continents.
Preventable vaccines comprise biologically active immunological preparations containing attenuated, inactivated, or subunit antigenic components formulated to elicit protective adaptive immunity against specific infectious pathogens, with stability profiles typically requiring cold-chain maintenance between two and eight degrees Celsius. Their primary commercial purpose centers on population-level disease burden reduction through prophylactic administration. Conjugate vaccines command the deepest margin pools due to complex polysaccharide-protein chemistry and limited biosimilar substitution. Pediatric applications generate the highest volume throughput, while intranasal delivery methods represent the fastest-growing configuration as mucosal immunization science matures.
The FDA's Center for Biologics Evaluation and Research enforces lot-release testing standards that shape manufacturing compliance costs and facility investment requirements. The WHO prequalification program governs access to United Nations procurement channels, directly determining market participation for lower-income country tenders. The EMA's evolving guidance on novel adjuvant safety profiling is forcing additional clinical endpoint documentation. Stakeholders must monitor how regulatory divergence between FDA accelerated approval and EMA conditional marketing authorization pathways affects portfolio prioritization and trial design choices.
Market Dynamics
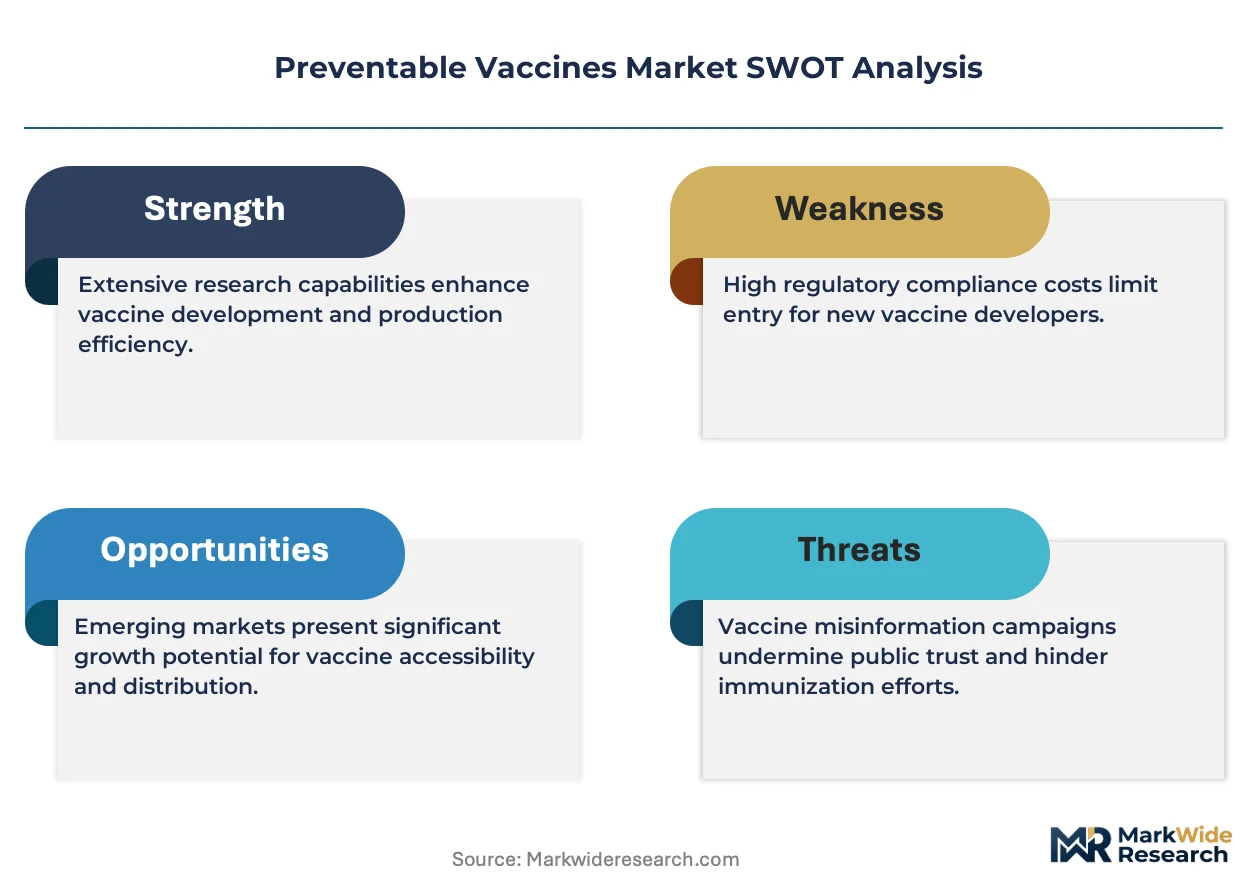
FDA accelerated approval pathways are compressing development timelines while simultaneously intensifying manufacturing compliance costs through enhanced lot-release testing standards, reshaping capital allocation across the preventable vaccines value chain.
Growth Catalysts
- Pediatric schedule expansion:National immunization programs in the United States are broadening coverage breadth through federal CDC procurement channels, anchoring volume demand.
- WHO prequalification access:The WHO prequalification program is unlocking United Nations procurement tenders for lower-income country participation, expanding addressable patient populations.
- Mucosal delivery maturation:Intranasal immunization platforms are advancing protective efficacy against respiratory pathogens, opening new administration modalities beyond intramuscular injection.
Market Restraints
- Cold-chain infrastructure gaps:Stability requirements of two to eight degrees Celsius create distribution bottlenecks in regions with unreliable electricity and refrigeration networks.
- Conjugate chemistry complexity:Polysaccharide-protein conjugation processes limit manufacturing yield and create supply concentration among specialized biologics facilities.
- EMA adjuvant documentation:Evolving European guidance on novel adjuvant safety profiling is forcing additional clinical endpoint studies, extending regulatory timelines.
Strategic Opportunities
- Emerging market access differentiation:Tiered pricing and technology transfer partnerships in India and Brazil are creating volume footholds outside premium-priced Western contracts.
- Combination vaccine bundling:Multi-antigen formulations are recalibrating procurement economics for national programs seeking to reduce injection burden and cold-chain trips.
- Subunit platform expansion:Recombinant protein and virus-like particle technologies are enabling rapid response to emerging infectious threats without live-attenuated handling constraints.
Industry Challenges
- Bioprocess engineering talent scarcity:Specialized expertise in aseptic fill-finish operations and cell culture scale-up is concentrating among a limited pool of experienced practitioners.
- Facility qualification timelines:FDA Center for Biologics Evaluation and Research lot-release protocols and international GMP inspections create multi-year capital deployment cycles before revenue realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preventable Vaccines Market |
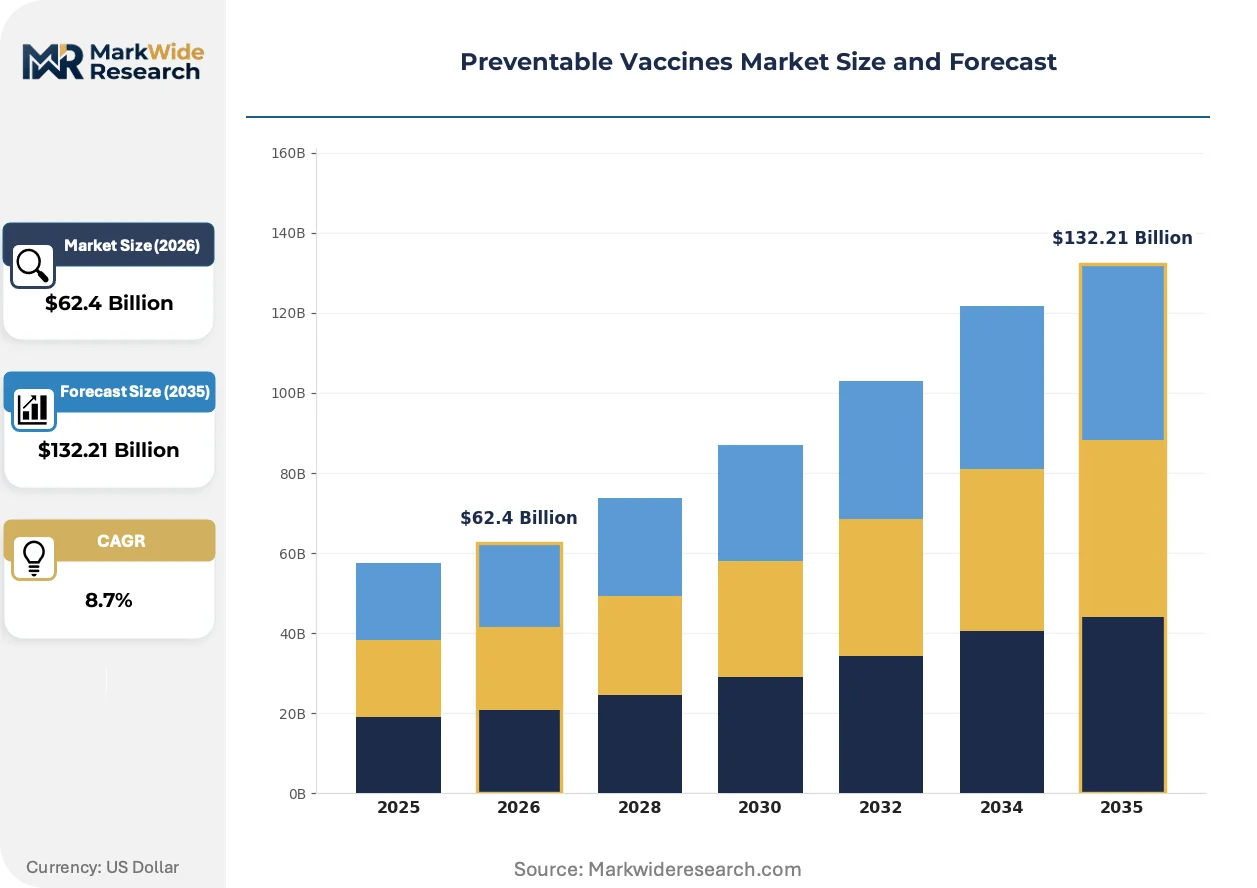
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $132.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, Conjugate Target Age Group: Pediatric, Adolescent, Adult, Elderly Delivery Method: Intramuscular, Subcutaneous, Oral, Intranasal End User: Hospitals, Clinics, Pharmacies, Public Health Organizations |
| Companies Covered | Pfizer Inc., GSK plc, Sanofi, Merck & Co., Inc., Johnson & Johnson Services, Inc., AstraZeneca plc, Moderna, Inc., CSL Limited, Novavax, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preventable Vaccines Market Evolving Landscape
Messenger RNA platforms, novel adjuvant systems, and decentralized manufacturing models are simultaneously disrupting antigen production economics, clinical development paradigms, and distribution architectures across the preventable vaccines sector.
Self-amplifying RNA and circular RNA constructs are rewriting the speed-to-clinic paradigm for pandemic preparedness. The United States Biomedical Advanced Research and Development Authority is pre-positioning manufacturing capacity through multi-year advance purchase commitments. This compression of development timelines is forcing traditional inactivated and live-attenuated platforms to demonstrate differentiated durability or safety profiles to retain procurement relevance.
The European Medicines Agency's conditional marketing authorization pathway is diverging from FDA accelerated approval standards on surrogate endpoint acceptability. Manufacturers pursuing parallel submissions must now design larger safety databases or earlier clinical efficacy readouts. Pediatric indication expansions face the greatest protocol complexity under this regulatory divergence.
National immunization programs are consolidating supplier relationships around full combination portfolio offerings rather than single-antigen tenders. Brazil's Ministry of Health and India's Universal Immunization Programme are leading this procurement rationalization. Incumbents with broad antigen manufacturing networks capture disproportionate contract renewals while single-product specialists face exclusion from multi-year framework agreements.
Preventable Vaccines Market Segmentation
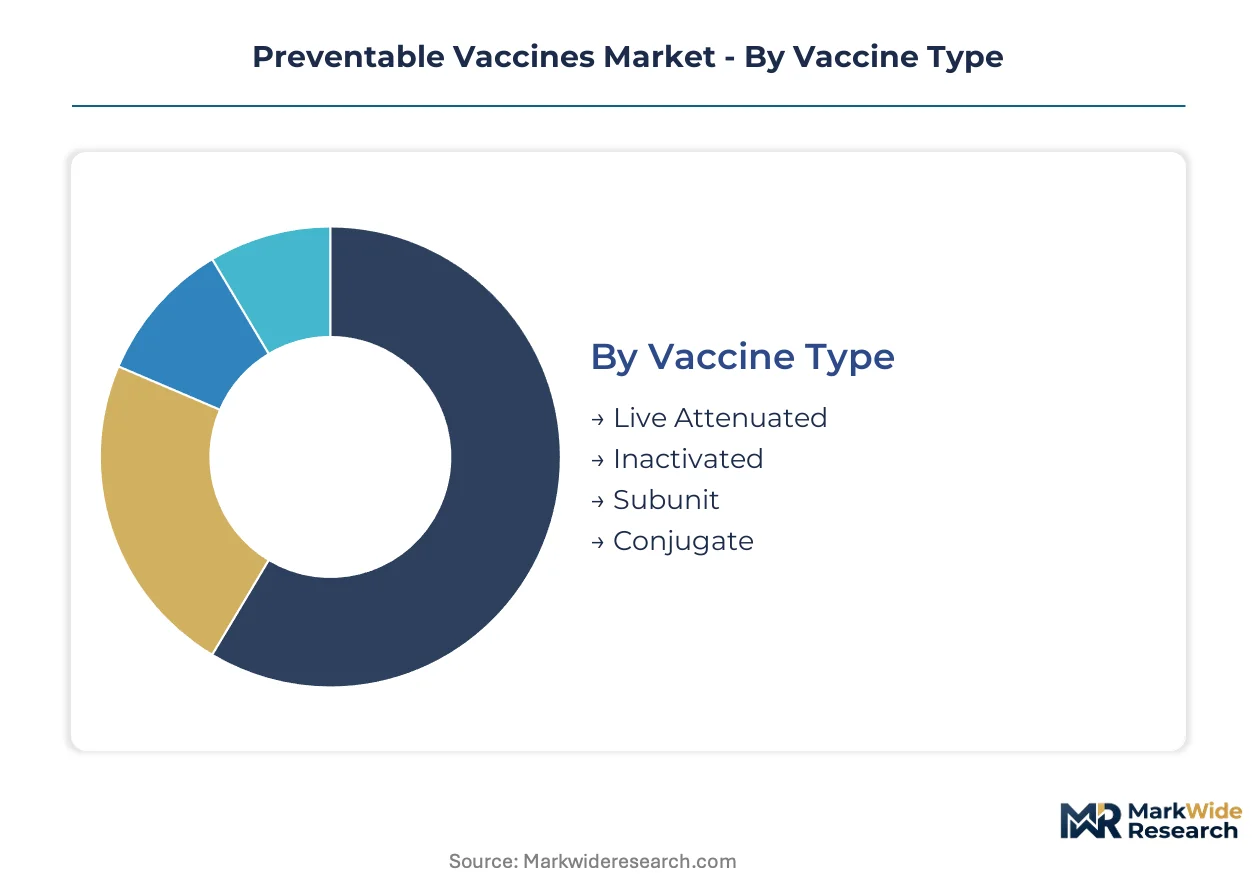
Vaccine procurement decisions hinge on cold-chain feasibility, antigen complexity, and population coverage targets. Manufacturers configure portfolios across four intersecting dimensions to match national immunization program specifications and margin requirements.
Vaccine Type:
Cost tier separates premium conjugate chemistry from commodity inactivated platforms.
- Conjugate:Polysaccharide-protein chemistry creates the deepest margin pools through limited biosimilar substitution. United States CDC procurement anchors demand for pneumococcal and meningococcal formulations, though manufacturing yield constraints concentrate supply among specialized biologics facilities.
- Subunit:Recombinant protein and virus-like particle technologies enable rapid pandemic response without live-attenuated handling constraints. India's Universal Immunization Programme and Brazil's Ministry of Health are expanding subunit procurement for hepatitis and HPV coverage.
- Live Attenuated:Weakened pathogen formulations require stringent cold-chain maintenance between two and eight degrees Celsius. MMR and varicella applications dominate pediatric schedules.
- Inactivated:Killed pathogen platforms offer stability advantages for regions with unreliable refrigeration networks. Polio and influenza applications generate the highest volume throughput in lower-income country tenders.
Conjugate leads on scale; subunit leads on momentum.
Target Age Group:
Application maturity varies sharply across life-stage immunization windows.
- Pediatric:National immunization programs generate the highest volume throughput through birth-cohort targeting. United States federal procurement channels and WHO prequalification pathways concentrate demand for measles, diphtheria-tetanus-pertussis, and pneumococcal series.
- Elderly:Expanding most quickly as aging demographics in Japan and Western Europe drive shingles and pneumococcal booster demand. Reimbursement complexity fragments procurement across Medicare Advantage plans and national health systems.
- Adolescent:HPV and meningococcal catch-up schedules create concentrated procurement windows tied to school-entry requirements.
- Adult:Occupational health mandates and travel medicine sustain steady influenza and hepatitis B demand outside pediatric-focused national programs.
Pediatric dominates contract value; elderly is climbing the fastest.
Delivery Method:
Customer workflow preferences are fragmenting administration modalities beyond traditional injection.
- Intranasal:Mucosal immunization science is maturing fastest for respiratory pathogen protection. United States Biomedical Advanced Research and Development Authority advance purchase commitments are pre-positioning manufacturing capacity for influenza and COVID-19 intranasal candidates.
- Intramuscular:Deltoid and anterolateral thigh administration remains the standard for aluminum-adjuvanted formulations requiring deep tissue deposition.
- Oral:Sabin polio and rotavirus formulations eliminate cold-chain injection requirements, enabling community health worker distribution in sub-Saharan Africa and South Asia.
- Subcutaneous:Fatty tissue deposition suits live-attenuated varicella and MMR combinations with lower reactogenicity profiles.
Intramuscular leads on scale; intranasal leads on momentum.
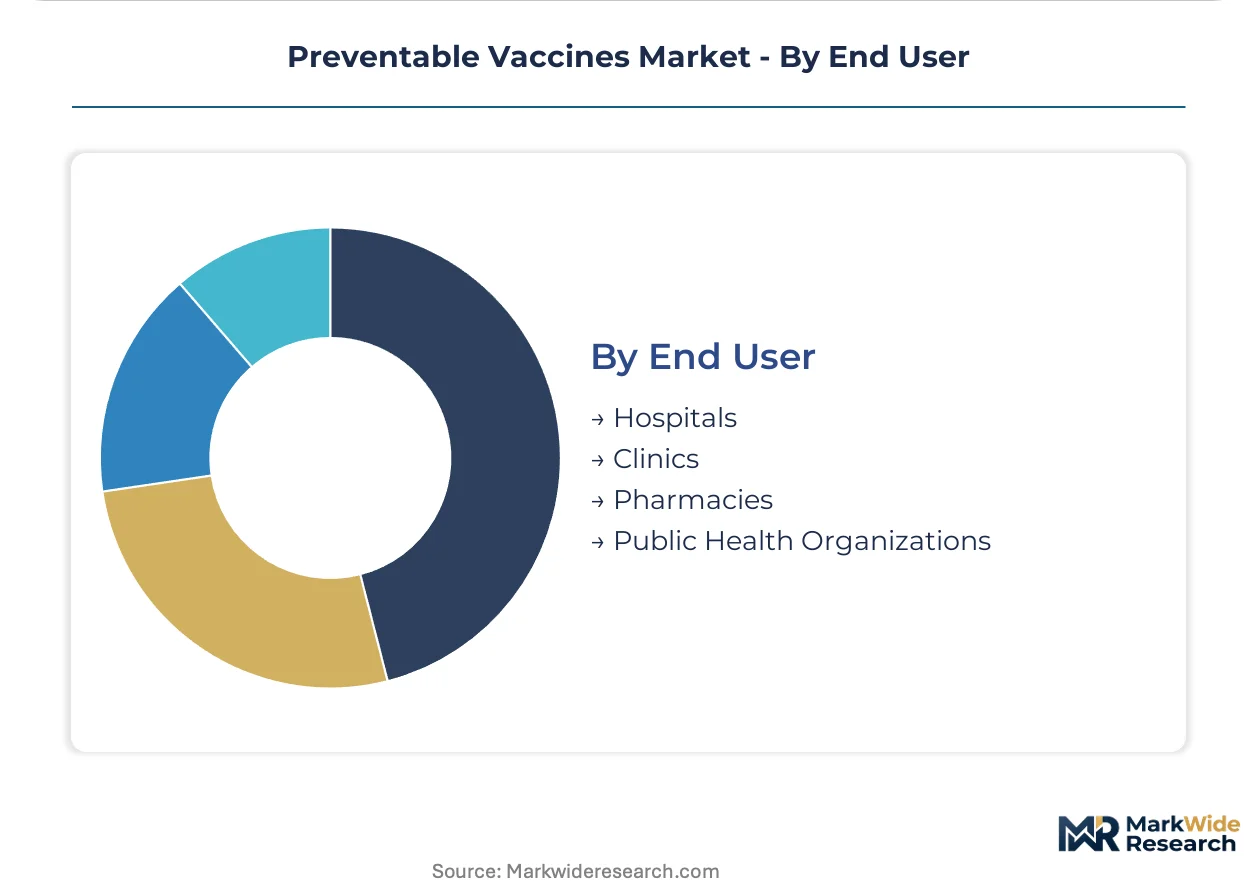
End User:
Supply concentration dictates channel-specific packaging and cold-chain configurations.
- Public Health Organizations:United Nations procurement through WHO prequalification governs access to lower-income country tenders. Multi-dose vial presentations and controlled-temperature chain protocols reduce per-dose logistics costs.
- Hospitals:Integrated delivery networks consolidate purchasing for inpatient and emergency department prophylaxis, favoring single-dose prefilled syringes to reduce waste.
- Clinics:Federally qualified health centers in the United States anchor Medicaid and uninsured population coverage through Vaccines for Children program allocations.
- Pharmacies:Retail clinic expansion in the United States and United Kingdom is shifting influenza and COVID-19 administration from physician offices to pharmacist-delivered settings.
Public health organizations lead on scale; pharmacies lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vaccine industrialization traces its modern origins to French and German bacteriology institutes in the late nineteenth century, with subsequent manufacturing scale concentrating in the United States and Western Europe through Cold War public health infrastructure investments.
United States
Federal CDC procurement channels anchor pediatric pneumococcal and meningococcal demand through the Vaccines for Children program. FDA accelerated approval pathways compress development timelines while intensifying lot-release testing compliance costs. Manufacturing clusters concentrate in Massachusetts and Pennsylvania, where specialized biologics facilities supply domestic and UN procurement channels.
India
The Universal Immunization Programme drives volume demand for hepatitis B and pentavalent combination vaccines across birth-cohort targeting. CDSCO regulatory harmonization with WHO prequalification standards unlocks access to lower-income country tenders. Production gravity centers on Hyderabad and Pune, where technology transfer partnerships with multinational developers expand manufacturing capacity.
Germany
Aging demographics in Western Europe propel shingles and pneumococcal booster demand through statutory health insurance reimbursement. EMA conditional marketing authorization divergence from FDA standards forces additional clinical endpoint documentation for novel adjuvant formulations. Industrial activity clusters in Marburg and Dresden, where diversified antigen production networks span conjugate and subunit platforms.
Brazil
The Ministry of Health consolidates supplier relationships around full combination portfolio offerings rather than single-antigen tenders. ANVISA regulatory alignment with PAHO revolving fund procurement governs access to national immunization program contracts. São Paulo and Rio de Janeiro anchor regional distribution hubs serving Mercosur cold-chain requirements.
Japan
Rapidly aging population demographics drive adult and elderly immunization schedule expansion through municipal health center delivery. PMDA safety profiling requirements for novel adjuvants extend regulatory timelines relative to FDA pathways. Manufacturing concentration in Kansai and Kanto regions supports domestic supply security and selective export to Southeast Asian markets.
Preventable Vaccines Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established biologics manufacturing networks. Market participation concentrates among developers possessing conjugate chemistry expertise and cold-chain distribution capabilities. Three archetypes dominate: multinational vaccine specialists with pediatric franchise anchoring, diversified pharma conglomerates with infectious disease portfolios, and platform-technology innovators with mRNA or subunit capabilities. Competitive moves center on combination vaccine bundling for national program tenders and technology transfer partnerships for emerging market access expansion.
Within the multinational specialist tier, Pfizer Inc., GSK plc, and Sanofi occupy positions defined by manufacturing scale and pediatric contract anchoring. Pfizer exemplifies the pneumococcal conjugate franchise model. GSK represents differentiated access strategies in lower-income markets. Sanofi anchors diversified antigen production across multiple continental facilities. These three entities collectively demonstrate how conjugate chemistry complexity and cold-chain infrastructure requirements create barriers to new entrant participation.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GSK plc |
| Sanofi |
| Merck & Co., Inc. |
| Johnson & Johnson Services, Inc. |
| AstraZeneca plc |
| Moderna, Inc. |
| CSL Limited |
| Novavax, Inc. |
| Others |
Value Network & Pricing Analysis
Specialized aseptic fill-finish technicians in Massachusetts and Pennsylvania command wage premiums that widen spreads between CDC federal contract pricing and emerging market tender rates. Labor-cost differentials across conjugate chemistry expertise tiers stratify procurement economics for national immunization programs.
Pricing Analysis
Three-tier pricing structure across premium conjugate, standard subunit, and economy inactivated levels governs preventable vaccines procurement. Price differentiation rests on WHO prequalification status and cold-chain certification grade, with CDC anchoring premium volumes. Cost compression in economy-tier polio and influenza tenders is intensifying because Indian and Brazilian manufacturers scale subunit platforms. Public health organizations exhibit highest price sensitivity; private hospital networks in Japan and Germany show lowest.
Supply Chain Analysis
Regional distribution centers in São Paulo, Hyderabad, and Rio de Janeiro anchor hub-and-spoke cold-chain networks serving Mercosur and South Asian markets. Manufacturing concentrates in the United States, India, and Germany, with antigen production drawing from specialized polysaccharide-protein conjugation inputs and recombinant cell culture media. Single-source vulnerability in aseptic fill-finish equipment creates bottlenecks. Distribution runs through UN procurement channels and national CDC allocations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preventable vaccines represent a late-cycle quality story as national programs shift procurement criteria toward combination vaccine durability and cold-chain resilience over single-antigen cost minimization.
For Market Incumbents: Deploy technology transfer partnerships to defend position against Indian and Brazilian subunit specialists capturing WHO prequalification pathways. Deepen conjugate chemistry captive supply through Pennsylvania and Massachusetts facility expansion. Consolidate supplier relationships around full combination portfolios to exclude single-product competitors from multi-year framework agreements. For New Entrants and Emerging Players: Direct-to-government digital procurement portals in Brazil and India offer lowest-friction market entry for subunit platform innovators. Target adolescent HPV and elderly shingles catch-up schedules where reimbursement complexity fragments incumbent control. Pursue ANVISA and CDSCO regulatory alignment as the primary go-to-market angle. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with infectious disease portfolios are the most active acquirers in this space, seeking mRNA and intranasal delivery capabilities. Five-to-ten-year viability favors platform-technology innovators over single-antigen specialists. Acquisition target archetype: subunit developers with WHO prequalification progress and emerging market manufacturing partnerships. Monitor FDA accelerated approval pathway divergence from EMA conditional marketing authorization as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Combination Vaccine Portfolio Consolidation | Full-antigen offerings capture multi-year national program contracts from Brazil's Ministry of Health. |
| WHO Prequalification Pathway Investment | UN procurement access unlocks lower-income country tenders across sub-Saharan Africa. |
| Cold-Chain Distribution Network Expansion | Controlled-temperature chain protocols reduce per-dose logistics costs for community health worker deployment. |
| Intranasal Delivery Platform Development | BARDA advance purchase commitments pre-position manufacturing capacity for respiratory pathogen candidates. |
| Technology Transfer Partnership Structuring | Hyderabad and Pune production gravity expands capacity for hepatitis and pentavalent combination supply. |
Research Methodology
Bottom-up national immunization program modeling reconciled against top-down antigen production tracking forms the analytical core of this study. Primary interviews with vaccine development executives, regulatory affairs leads at FDA and EMA, formulary directors at integrated delivery networks, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and WHO prequalification databases. Triangulation across supply-side manufacturing capacity and demand-side procurement volume ensures segmentation integrity.
Historical trendline analysis of pediatric schedule expansion and elderly immunization adoption patterns informed projection parameters across the analysis window. Segmentation dimensions modeled include vaccine type, target age group, delivery method, and end-user channel, with regional regulatory cluster differentiation. CAGRs derive from fitted growth curves calibrated to CDC procurement volumes and UN tender awards. Forecast inputs incorporate cold-chain infrastructure development trajectories and conjugate chemistry yield improvements.
Regulatory divergence between FDA accelerated approval and EMA conditional marketing authorization, adjuvant safety profiling requirement shifts, and pandemic preparedness funding volatility are the dominant revision risks. Forecasts reflect documented assumptions about procurement consolidation timelines and technology transfer partnership execution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Europe Hospital-Acquired Infection Diagnostics Market
Infection Control
Sterilization Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Australia Hand Sanitizer Market
Infection Control
Medical Activated Carbon Dressing Market
Infection Control
Global Hospital Acquired Infection Control Market
Infection Control
Staphylococcal Infection Treatment Market
Infection Control
Sterilization Monitoring Market
Infection Control
South Africa Antibacterial Soap Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
Global Hospital Infection Therapeutics Market
Infection Control
Sterilization Tunnel Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Global Hospital Disinfectant Products and Services Market